
 Europe Hydrogen Peroxide Market | 2026-2036
Europe Hydrogen Peroxide Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hydrogen Peroxide Market Intelligence
Modular packaging configurations for hydrogen peroxide are broadening procurement flexibility for mid-sized chemical processors and textile finishers across Europe. Nouryon leverages its integrated peroxide network spanning the Netherlands and Belgium to sustain supply reliability for pulp mill customers. BASF SE anchors German production capacity with backward integration into anthraquinone process inputs. Solvay S.A. competes through specialized high-purity grades serving semiconductor fabrication lines in France and Italy.
Hydrogen peroxide is an aqueous solution of H₂O₂, typically manufactured through the anthraquinone auto-oxidation process at concentrations ranging from 35% to 70% for industrial use, functioning primarily as a strong oxidizer, bleaching agent, and disinfectant across water treatment, textile processing, and electronics manufacturing. The Standard Grade segment dominates volume throughput across European pulp and paper mills, where cost-per-ton metrics govern procurement decisions. High Purity grades command concentrated margin pools from electronics and pharmaceutical end users in Germany and the Netherlands, where trace metal specifications determine supplier qualification.
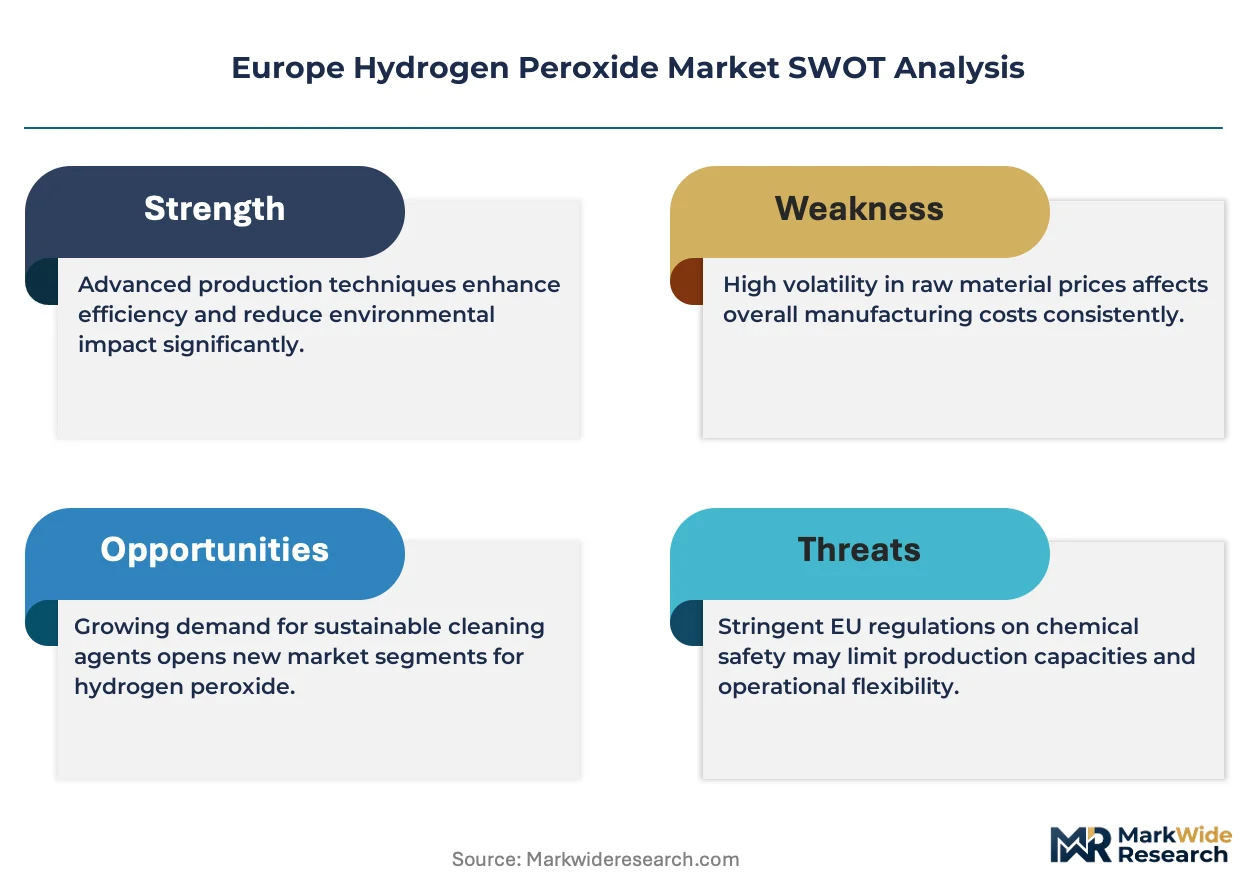
REACH registration requirements and the EU Green Deal's Industrial Emissions Directive shape product formulation standards and discharge compliance costs for hydrogen peroxide manufacturers operating across member states. ECHA classification protocols for concentrated oxidizers influence labeling, transport modalities, and customer handling procedures throughout the supply chain. Stakeholders must monitor evolving EU taxonomy criteria for green hydrogen derivatives and assess how electrolysis-based peroxide production could redraw competitive boundaries between conventional and renewable feedstock routes.
Market Dynamics
EU Green Deal discharge limits and REACH chemical safety protocols are compressing chlorine-based bleaching across European pulp mills, redirecting volume toward peroxide oxidation sequences and tightening supplier qualification criteria.
Growth Catalysts
- Pulp mill chlorine substitution:EU Industrial Emissions Directive mandates favor hydrogen peroxide sequences over halogenated alternatives in Scandinavian and German paper clusters.
- REACH registration tailwinds:ECHA classification protocols for concentrated oxidizers streamline peroxide qualification against unregistered legacy chemistries in water treatment applications.
- Anthraquinone process optimization:Catalytic efficiency gains in auto-oxidation loops are lowering unit production costs for standard-grade material serving textile finishers.
Market Restraints
- Anthraquinone feedstock volatility:Quinone derivative costs fluctuate with aromatics pricing, squeezing margin stability for non-integrated producers.
- High-purity supply concentration:Semiconductor-grade production clusters in the Netherlands and Belgium create geographic chokepoints for electronics customers.
- Electrolysis substitution threat:Green hydrogen-derived peroxide pilot projects in Germany could disrupt conventional process economics before scale.
Strategic Opportunities
- Polish chemical park expansion:Underdeveloped peroxide infrastructure in Central European industrial zones offers first-mover positioning for modular production units.
- Semiconductor grade penetration:Trace metal specification tightening in French and Italian fabrication lines opens premium qualification slots.
- CSRD reporting alignment:Corporate sustainability disclosure requirements favor peroxide-based oxidation for scope 3 emissions accounting in pulp supply chains.
Industry Challenges
- Process safety certification timelines:ECHA transport classification updates delay customer onboarding for concentrated product handlers.
- Legacy chlor-alkali integration:Paper mills with sunk chlorine infrastructure face capex hurdles to retrofit peroxide bleaching sequences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hydrogen Peroxide Market |
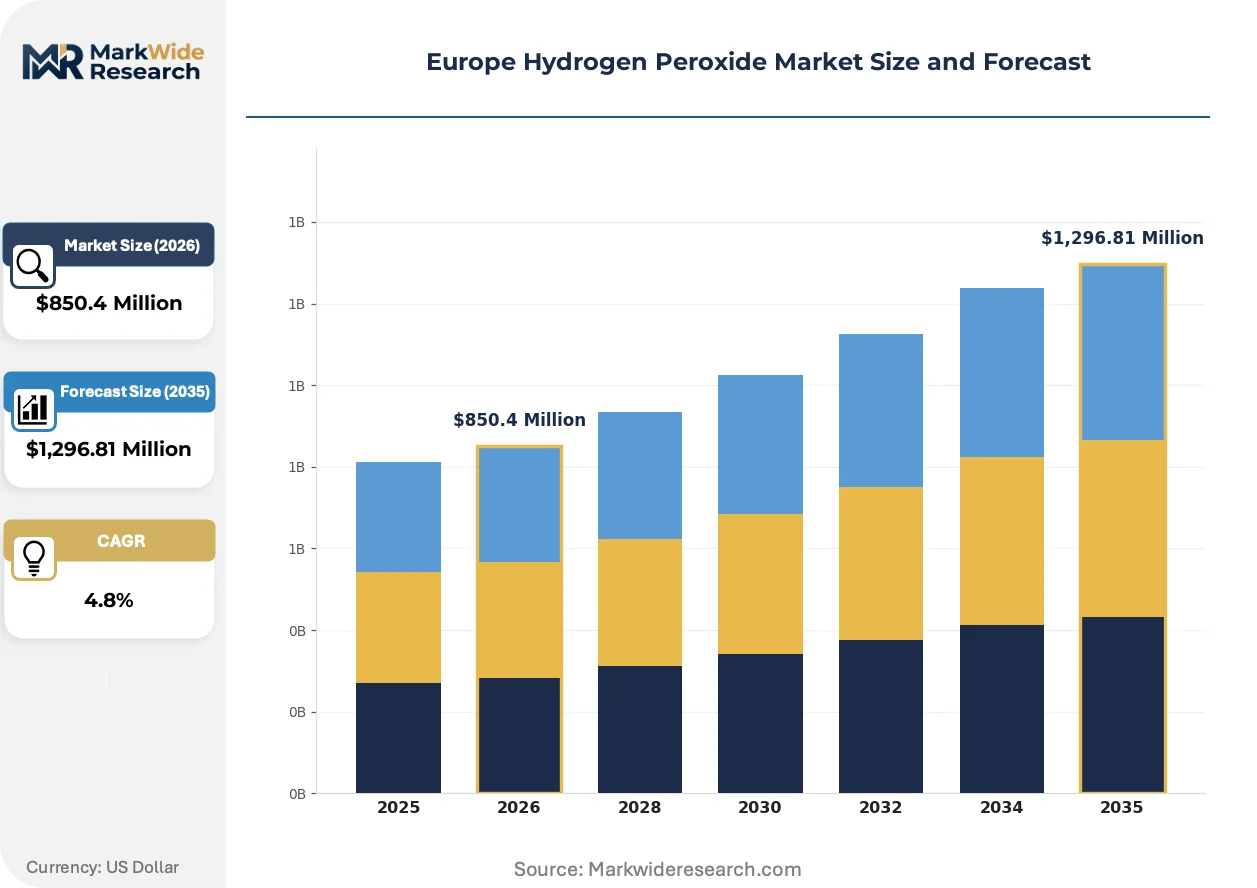
| Market Size in 2026 | $850.4 Million |
| Market Size in 2035 | $1,296.81 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Grade, High Purity, Stabilized, Distilled End Use Industry: Pulp & Paper, Textile, Chemicals, Electronics Application: Disinfectants, Bleaching Agents, Oxidizing Agents, Wastewater Treatment Packaging Type: Drums, Bulk Containers, Bottles, IBCs |
| Companies Covered | Nouryon, BASF SE, Solvay S.A., Airedale Chemical, Grupa Azoty, Evonik Industries AG, Kemira Oyj, Akzo Nobel N.V., Arkema, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hydrogen Peroxide Market Strategic Shifts & Innovations
Process intensification and regulatory disclosure mandates are compressing production footprints while expanding traceability requirements across European peroxide supply chains.
Membrane electrolysis pilot systems for on-site peroxide generation are automating distribution logistics for remote textile processors in Spain and Portugal. Mid-sized finishers are adopting containerized units to bypass bulk transport constraints. The technology is automating inventory management and reducing working capital tied to tanker deliveries.
EU CSRD sustainability reporting rules now require pulp suppliers to document oxidation chemistry in scope 3 disclosures. Paper producers are requalifying bleaching sequences to meet taxonomy-aligned disclosure standards. German and Finnish mills are accelerating peroxide adoption to satisfy auditor traceability requirements.
Spot purchasing through digital chemical exchanges is fragmenting long-term offtake contracts for standard-grade material. Dutch and Belgian traders are capturing volume from processors seeking flexible delivery windows. Textile hubs in northern Italy show the fastest migration toward platform-based procurement.
Europe Hydrogen Peroxide Market Segmentation
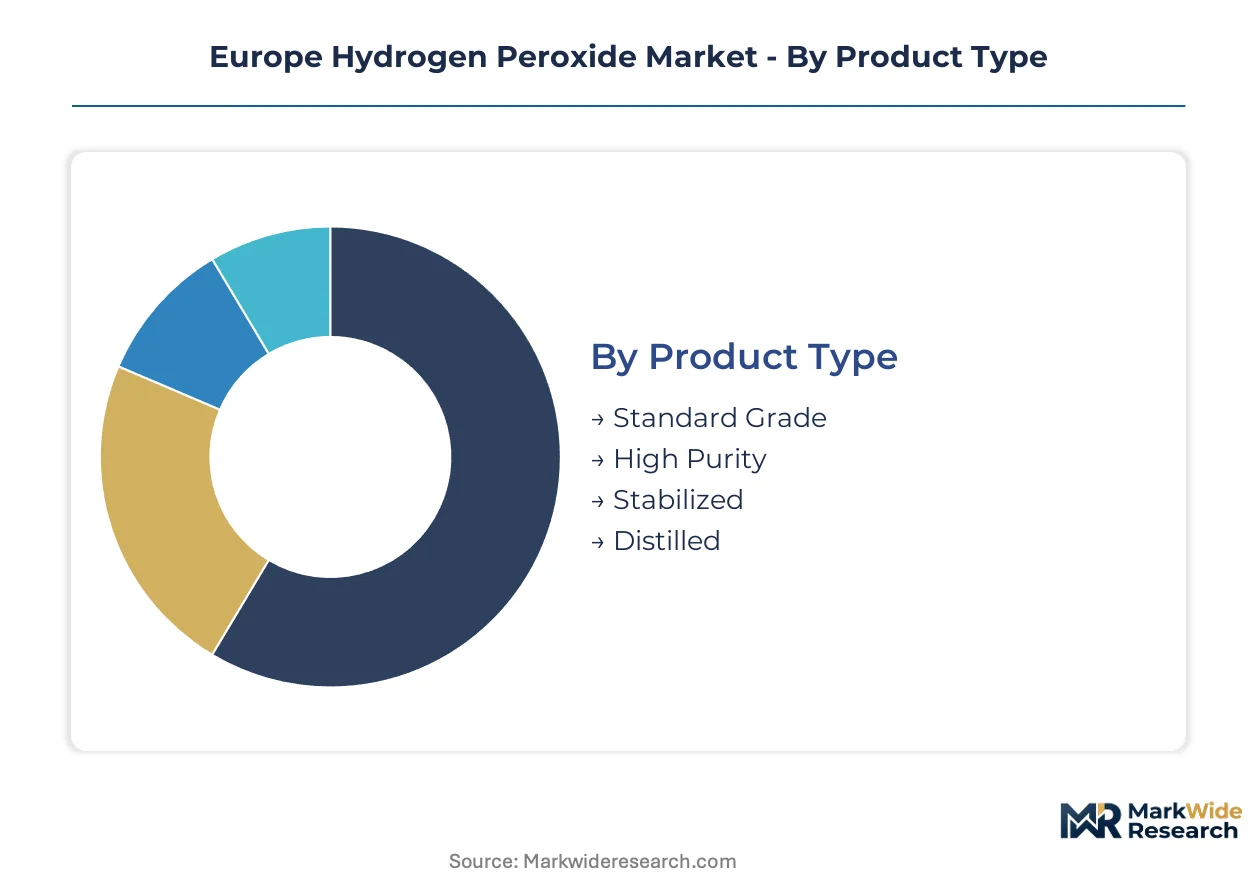
Segmentation in the Europe hydrogen peroxide market reflects divergent purity requirements and supply chain configurations across industrial end uses. Cost-per-ton economics govern volume procurement in pulp bleaching, while trace metal specifications determine supplier qualification for semiconductor fabrication.
Product Type:
Volume throughput concentrates in standard grades serving cost-sensitive paper mills, while premium margins pool in specialized purities for electronics and pharmaceutical customers.
- Standard Grade:Aqueous solutions of 35-70% concentration manufactured through anthraquinone auto-oxidation, optimized for oxidative bleaching sequences. Demand clusters in German and Scandinavian pulp mills where EU Industrial Emissions Directive compliance favors chlorine-free processes.
- High Purity:Sub-ppb trace metal specifications achieved through multi-stage distillation and membrane filtration. French and Italian semiconductor fabrication lines drive qualification requirements, with supply concentrating in Netherlands and Belgium production clusters.
- Stabilized:Formulations incorporating chelating agents to prevent catalytic decomposition during extended storage. Chemical processors in the Benelux region favor stabilized grades for batch oxidation processes.
- Distilled:Ultra-low organic content achieved through fractional distillation, serving pharmaceutical synthesis and specialized electronics cleaning applications in Germany and Switzerland.
Mature deployment sits with Standard Grade. Newer deployment is concentrated in High Purity.
End Use Industry:
Application maturity varies sharply across sectors, with paper bleaching representing established consumption and electronics demanding evolving purity benchmarks.
- Pulp & Paper:Chlorine-free bleaching sequences using alkaline peroxide mechanical pulping. German and Finnish mills anchor regional offtake under EU Green Deal discharge limits.
- Textile:Desizing and bleaching of natural fibers, with northern Italian finishers migrating toward platform-based procurement for flexible delivery.
- Chemicals:Epoxidation and hydroxylation reactions in fine chemical synthesis. Dutch chemical parks integrate peroxide oxidation into specialty intermediate production.
- Electronics:Wafer cleaning and photoresist stripping in semiconductor fabrication. Trace metal tightening in French cleanroom specifications is expanding qualification slots.
Established consumption patterns dominate Pulp & Paper. Steepest expansion trajectory is appearing in Electronics.
Application:
Functional differentiation separates commodity oxidation from specialized disinfection and environmental compliance uses.
- Disinfectants:Antimicrobial formulations for healthcare and food processing sanitation. ECHA classification protocols for concentrated oxidizers shape labeling and transport requirements.
- Bleaching Agents:Lignin removal and brightness enhancement in mechanical pulping. Scandinavian mills report the fastest migration from chlorine-based sequences.
- Oxidizing Agents:Selective epoxidation and sulfoxidation in organic synthesis. Catalytic efficiency gains in anthraquinone loops are lowering unit costs for chemical processors.
- Wastewater Treatment:Advanced oxidation processes for refractory pollutant degradation. CSRD reporting alignment favors peroxide-based methods for scope 3 emissions accounting.
Conventional utilization centers on Bleaching Agents. Emerging utilization is concentrating in Wastewater Treatment.
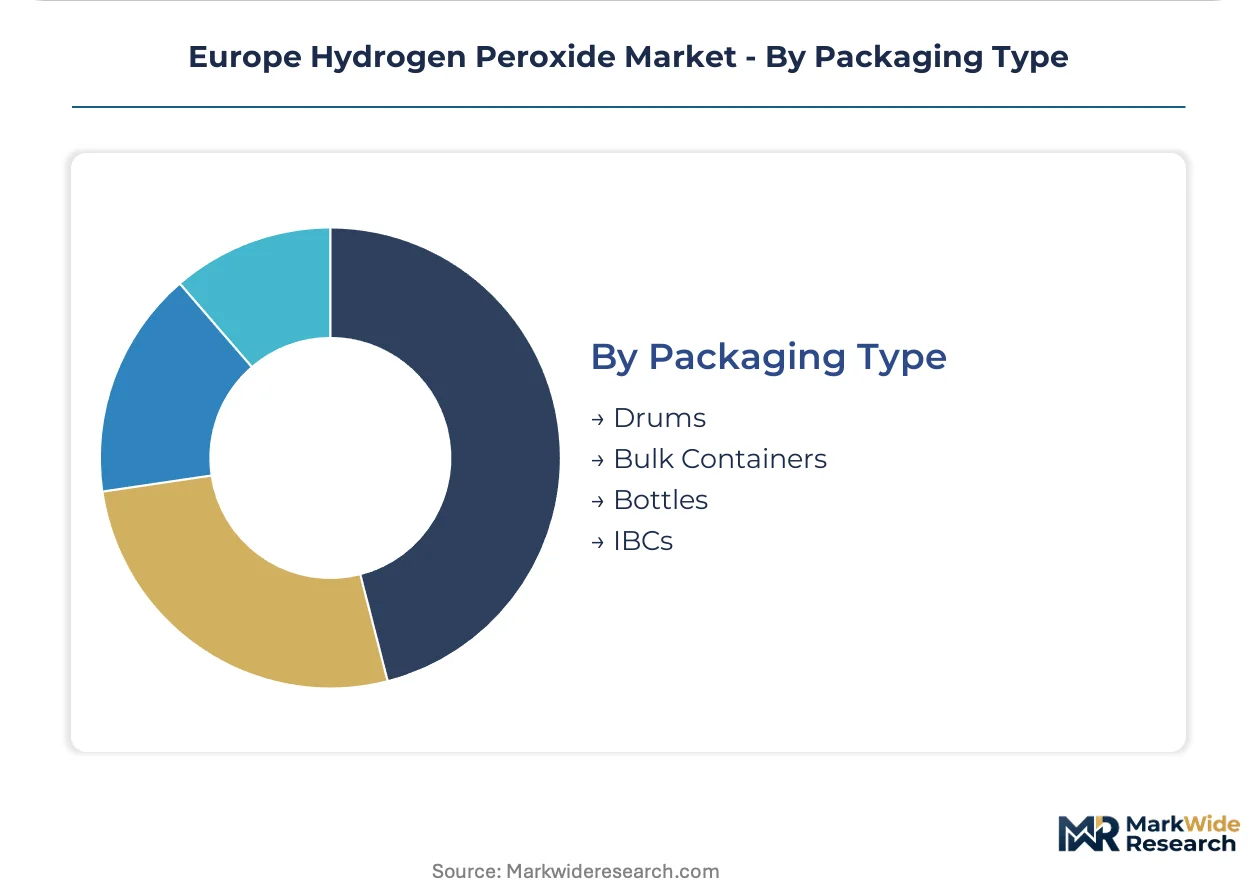
Packaging Type:
Logistics configuration splits between bulk integration for mill-scale consumers and modular formats for distributed chemical processors.
- Drums:200-liter steel or polyethylene containers for mid-volume chemical processors. Polish textile finishers favor drum formats for inventory flexibility.
- Bulk Containers:Tank truck and railcar deliveries for integrated pulp mill consumption. German paper clusters rely on dedicated bulk supply contracts.
- Bottles:Laboratory and small-batch pharmaceutical packaging. Swiss pharmaceutical manufacturers specify amber glass for light-sensitive formulations.
- IBCs:Intermediate bulk containers enabling forklift handling at textile processors. Spanish and Portuguese finishers adopt IBCs to bypass tanker delivery constraints.
Scale deployment sits with Bulk Containers. Distributed deployment is expanding in IBCs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in the Netherlands and Belgium, while consumption clusters in German and Scandinavian pulp corridors. This geographic split shapes logistics configurations and supplier qualification patterns across the region.
Germany
Integrated chemical parks in North Rhine-Westphalia and Lower Saxony anchor anthraquinone-based production for domestic pulp mills. The EU Industrial Emissions Directive tightens discharge limits for paper producers in the Hamburg-Bremen corridor, accelerating chlorine substitution. BASF SE's Ludwigshafen complex supplies backward-integrated feedstock security for standard-grade oxidation chemistry.
Netherlands
Nouryon's Rotterdam-area network serves as a regional supply hub for Benelux textile finishers and water treatment operators. REACH registration protocols streamline peroxide qualification against legacy chemistries in chemical processing applications. The Port of Rotterdam cluster enables bulk container logistics for German and French customers seeking flexible delivery windows.
Belgium
Solvay S.A. concentrates high-purity production for semiconductor fabrication lines in France and Italy. ECHA classification protocols for concentrated oxidizers shape transport modalities and customer handling procedures throughout the supply chain. The Antwerp chemical ring provides distillation infrastructure for ultra-low trace metal specifications serving electronics customers.
Poland
Underdeveloped peroxide infrastructure in Central European industrial zones creates positioning opportunities for modular production units. Grupa Azoty leverages captive anthraquinone inputs from nitrogen fertilizer operations to serve emerging textile processors. The Łódź textile hub reports migration toward platform-based procurement for desizing and bleaching applications.
Finland
Scandinavian pulp mills report the fastest migration from chlorine-based bleaching sequences under EU Green Deal discharge mandates. Kemira Oyj anchors regional supply relationships through integrated logistics serving mechanical pulping operations. The Kemi-Tornio paper cluster qualifies peroxide suppliers against taxonomy-aligned scope 3 disclosure requirements.
Europe Hydrogen Peroxide Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across standard-grade and high-purity segments. The vendor base splits between integrated chemical majors with captive feedstock security and regional distributors capturing spot volume through digital exchanges. Three archetypes dominate: backward-integrated producers controlling anthraquinone inputs, high-purity specialists serving electronics qualification requirements, and modular operators deploying containerized units for remote textile processors. Capacity expansion and strategic partnerships represent the dominant competitive moves as electrolysis pilot projects threaten conventional process economics.
Within the integrated producer tier, Nouryon and BASF SE exemplify backward-integrated structures spanning feedstock through distribution. Solvay S.A. occupies a position in the high-purity specialist archetype, with production clustering in Belgium to serve semiconductor fabrication qualification requirements in neighboring markets. These three anchors illustrate how geographic proximity to end-use clusters and control over process inputs determine competitive positioning across standard and specialty grades.
| Leading Market Players |
|---|
| Nouryon |
| BASF SE |
| Solvay S.A. |
| Airedale Chemical |
| Grupa Azoty |
| Evonik Industries AG |
| Kemira Oyj |
| Akzo Nobel N.V. |
| Arkema |
| Others |
Cost & Logistics Intelligence
EU Green Deal discharge limits and REACH chemical safety protocols gate both qualified supply and premium-tier pricing access, forcing paper mills to requalify suppliers against stricter ECHA classification standards while electronics customers pay trace-metal premiums for semiconductor-grade material. Anthraquinone feedstock volatility and logistics chokepoints in concentrated production zones compound procurement complexity for mid-sized chemical processors.
Pricing Analysis
Margin tightening in standard-grade material reflects anthraquinone derivative cost volatility and spot purchasing fragmentation through Dutch and Belgian digital exchanges. Contract-based long-term offtake dominates German pulp mill procurement, while platform-based spot buying accelerates among northern Italian textile finishers seeking delivery flexibility. Price differentiation hinges on certification grade against ECHA transport classifications and volume scale commitments. Pulp and paper mills exhibit highest price sensitivity due to cost-per-ton procurement metrics, whereas semiconductor fabrication lines in France and Italy absorb premium pricing for sub-ppb trace metal specifications.
Supply Chain Analysis
Freight cost differentials between Rotterdam bulk terminals and Polish textile hubs favor modular IBC configurations over dedicated tanker deliveries for mid-volume processors. Supply concentrates in the Netherlands, Belgium, and Germany, with Nouryon's Rotterdam-area network and BASF SE's Ludwigshafen complex anchoring regional anthraquinone-based production. Raw material dependencies encompass quinone derivatives, hydrogen gas, and specialized palladium catalysts. Single-source vulnerability concentrates in high-purity distillation capacity clustered around Antwerp. Distribution runs through integrated chemical park pipelines for mill-scale consumers and containerized logistics for remote finishers in Spain and Portugal.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as electrolysis-based green hydrogen peroxide pilot projects in Germany threaten to displace conventional anthraquinone process economics, forcing sub-scale producers toward acquisition or exit.
For Market Incumbents: Deploy backward integration into anthraquinone feedstock to secure margin stability against aromatics pricing volatility. Incumbents should expand high-purity distillation capacity in Belgium to capture semiconductor qualification slots as French and Italian cleanroom specifications tighten. Capacity addition in Polish chemical parks offers first-mover positioning before modular competitors establish containerized units. For New Entrants and Emerging Players: Mid-sized textile finishers in Central European industrial zones represent the most penetrable buyer archetype currently underserved by bulk-optimized incumbents. New entrants should target Polish and Spanish processors with containerized membrane electrolysis systems enabling on-site generation and bypassing tanker logistics constraints. Platform-based procurement partnerships with Dutch and Belgian traders provide immediate channel access without legacy infrastructure investment. For Investors and Strategic Acquirers: First commercial-scale electrolysis peroxide output from German pilot facilities is the leading indicator that renewable feedstock economics are approaching competitive parity with conventional routes. Investors should frame long-term viability around five-to-ten-year feedstock transition windows, targeting acquisition of regional distributors with digital exchange capabilities and CSRD-aligned sustainability reporting infrastructure. The inflection signal to monitor is ECHA registration of electrolysis-derived material under REACH protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Anthraquinone Feedstock | BASF SE's Ludwigshafen complex exemplifies captive supply security against quinone derivative volatility. |
| High-Purity Distillation Capacity Expansion | Belgian production clusters serve French and Italian semiconductor fabrication qualification requirements. |
| Modular Containerized Production Deployment | Spanish and Portuguese textile finishers adopt on-site membrane electrolysis to bypass tanker constraints. |
| Digital Exchange Platform Partnership | Dutch and Belgian traders capture spot volume from processors seeking flexible delivery windows. |
| CSRD Reporting Alignment Investment | German and Finnish mills requalify peroxide suppliers to satisfy auditor traceability requirements. |
Research Approach
Multi-period observation of ECHA registration timelines, EU Green Deal implementation trajectories, and pulp mill chlorine substitution rates anchored the trend analysis, supplemented by interviews with plant managers at integrated chemical parks, procurement leads at German paper producers, distribution channel partners in Benelux logistics hubs, and technical R&D directors overseeing anthraquinone process optimization. Secondary validation drew from customs and trade data, Cefic chemical industry reports, SEC 10-K filings of listed chemical conglomerates, and REACH registration databases. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down production capacity assessments across the analysis window.
Input-output matrices modeled hydrogen peroxide demand across grade tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs were derived through regression analysis of historical consumption trajectories and forward projection of regulatory compliance deadlines. Industry-specific forecast inputs encompassed EU Industrial Emissions Directive phase-in schedules and semiconductor fabrication capacity expansion announcements in France and Italy.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electrolysis technology cost curves and green hydrogen subsidy regimes. Forecasts reflect documented assumptions regarding anthraquinone process efficiency gains and ECHA classification stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
United States Hydrogen Peroxide Market
Disinfectants and Preservatives
Alcohol Based Disinfectants Market
Disinfectants and Preservatives
Cosmetic Grade Preservative Market
Disinfectants and Preservatives
Pyrethroids Market
Disinfectants and Preservatives
Fumigant Products Market
Disinfectants and Preservatives
Chlorine Disinfectant Market
Disinfectants and Preservatives
Color Preservatives Market
Disinfectants and Preservatives
Diquat Dibromide Market
Disinfectants and Preservatives
IV Disinfecting Caps Market
Disinfectants and Preservatives
India Air Treatment Products Market
Disinfectants and Preservatives
Surface Disinfectants Market
Disinfectants and Preservatives
Global Sodium Metabisulphite Market
Disinfectants and Preservatives
Low-Temperature Sterilization Market
Disinfectants and Preservatives
Salon Disinfectants Market
Disinfectants and Preservatives
Bleach Gel Market
Disinfectants and Preservatives
UK Hypochlorous Acid Market