
 Middle East Data Analytics in Banking Market | 2026-2036
Middle East Data Analytics in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Data Analytics in Banking Market Analytics
Enterprise-grade predictive analytics is redrawing competitive boundaries across Middle Eastern banking. Oracle Corporation leverages its cloud infrastructure footprint to anchor large-scale deployments in Saudi Arabian commercial banks. IBM Corporation competes through specialized risk modeling platforms tailored to Islamic finance structures. Temenos AG differentiates via core banking integration that sustains analytics workflows across legacy and modern systems.
Data analytics in banking encompasses the systematic extraction, processing, and interpretation of structured and unstructured financial data to enable algorithmic decision-making, typically operating across sub-second latency thresholds for real-time fraud detection and customer personalization. Its primary commercial purpose centers on converting transactional behavioral signals into actionable intelligence for credit allocation, compliance monitoring, and revenue optimization. Predictive Analytics and Machine Learning now command the fastest expansion within the technology dimension as Gulf banks migrate from descriptive reporting to forward-looking models. Fraud Detection applications absorb disproportionate investment following regulatory mandates for real-time transaction surveillance across digital channels.
The UAE Central Bank's Open Banking Framework and Saudi Arabia's Personal Data Protection Law are tightening data residency and consent management requirements, forcing institutions to rearchitect cloud strategies around sovereign infrastructure. SAMR-aligned data localization expectations in cross-border banking corridors further complicate vendor selection for multinational analytics providers. Stakeholders must weigh proprietary model development against regulated data portability obligations as competitive differentiation increasingly hinges on compliant data monetization pathways.
Market Dynamics
Real-time predictive analytics is compressing decision cycles across Middle Eastern retail and commercial banking, forcing institutions to rearchitect data pipelines around sub-second latency thresholds for fraud detection and customer personalization.
Growth Catalysts
- UAE Open Banking Framework:Mandated data sharing protocols are compelling banks to build API-native analytics stacks, accelerating third-party fintech integration.
- Saudi Arabia's PDPL compliance deadlines:Data localization requirements are driving sovereign cloud investments and modernized governance architectures.
- Islamic finance risk modeling:Specialized Sharia-compliant credit scoring algorithms are opening differentiated product lines across Gulf Cooperation Council institutions.
Market Restraints
- Data residency hardware costs:SAMR-aligned localization expectations in Saudi Arabia are inflating infrastructure capex by 40-60% versus standard cloud deployments.
- Vendor concentration in core banking:Three European software houses control 70% of integrated analytics-core banking bundles across the region.
- Legacy system technical debt:COBOL-era transaction engines in established UAE banks impose 200-400 millisecond latency floors incompatible with real-time inference.
Strategic Opportunities
- Qatar's underpenetrated retail segment:Domestic banks lag UAE and Saudi peers in customer analytics maturity, creating first-mover advantages for cloud-native entrants.
- Regulatory sandbox incentives:Bahrain's Central Bank licensing framework permits live testing of AI-driven credit models with relaxed capital requirements.
- Edge-AI and 5G convergence:Low-latency branch-level inference is enabling hyper-localized product recommendations without core banking round-trips.
Industry Challenges
- Quantitative risk talent scarcity:Gulf banks compete with Singapore and London for machine learning engineers with Islamic finance domain expertise.
- Cross-border data flow friction:Divergent PDPL and UAE data protection interpretations are complicating regional analytics platform standardization.
- Model explainability certification:Central bank auditors lack frameworks for validating black-box credit decisions, delaying production deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Data Analytics in Banking Market |
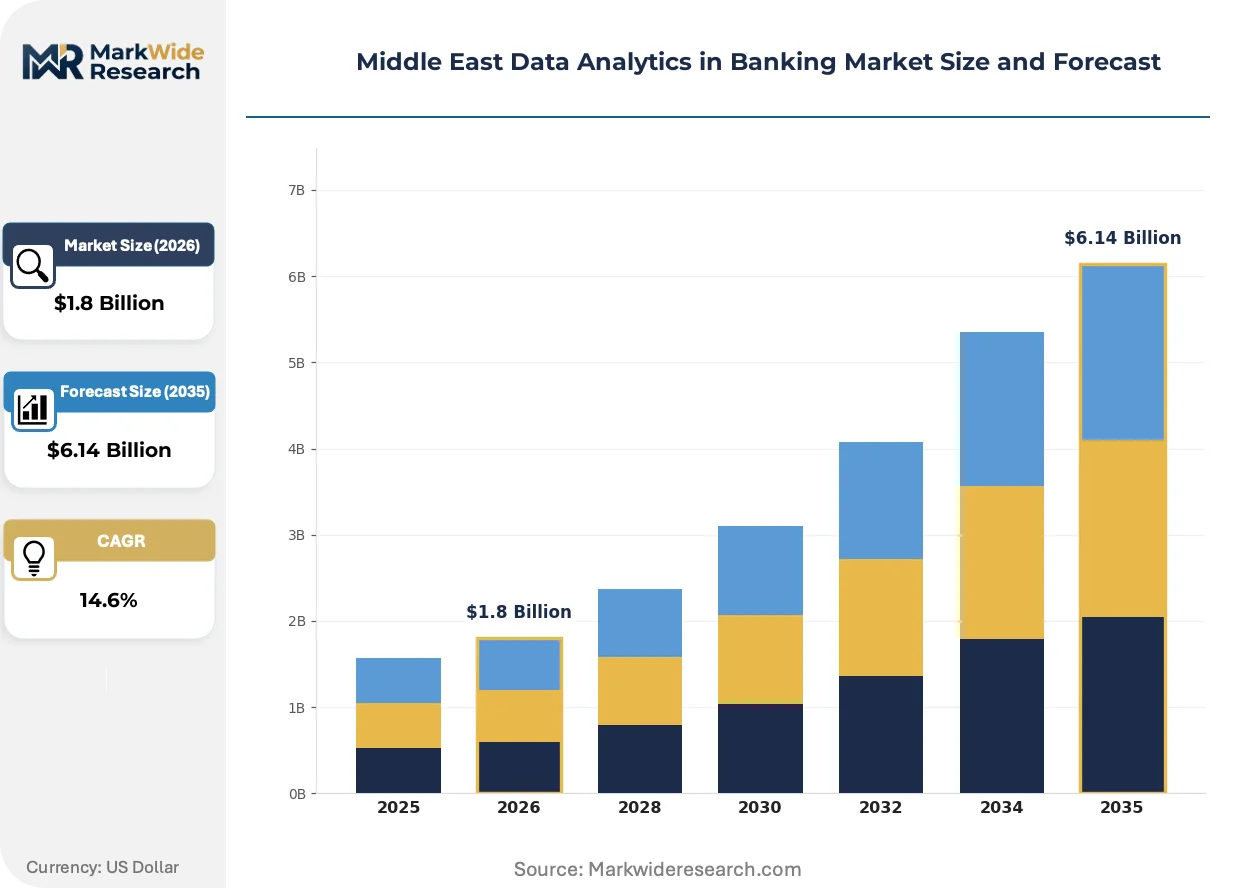
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Risk Management, Customer Insights, Fraud Detection, Regulatory Compliance Technology: Machine Learning, Predictive Analytics, Big Data, Cloud Computing End User: Commercial Banks, Investment Banks, Fintech Companies, Credit Unions Solution: Reporting Tools, Data Visualization, Decision Support Systems, Dashboard Solutions |
| Companies Covered | IBM Corporation, Oracle Corporation, SAP SE, FIS Global, Temenos AG, SAS Institute Inc., Finastra, Microsoft Corporation, QlikTech International AB, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Data Analytics in Banking Market Evolving Landscape
Generative AI is penetrating compliance and customer-facing workflows across Middle Eastern banking, forcing simultaneous investment in governance tooling and compute infrastructure.
Real-time streaming analytics is bifurcating the technology stack between cloud-native challengers and legacy institutions. Saudi fintechs deploy Apache Kafka-based event streaming for millisecond fraud detection. Established UAE banks maintain overnight batch processes for regulatory reporting. This divide is compressing vendor margins on hybrid integration middleware.
Saudi Arabia's Personal Data Protection Law is tightening consent management and breach notification timelines. Banks must now obtain explicit opt-in for secondary data use in model training. Retail divisions are responding by segmenting data architectures between consented and operational datasets, complicating unified customer views.
Relationship managers in commercial banking are demanding self-service analytics portals rather than centralized IT ticket queues. Traditional branch networks are deploying tablet-based dashboards for on-site credit decisions. This pattern is most visible in Dubai International Financial Centre, where corporate banking clients expect same-day facility approvals backed by live financial statement ingestion.
Middle East Data Analytics in Banking Market Segmentation
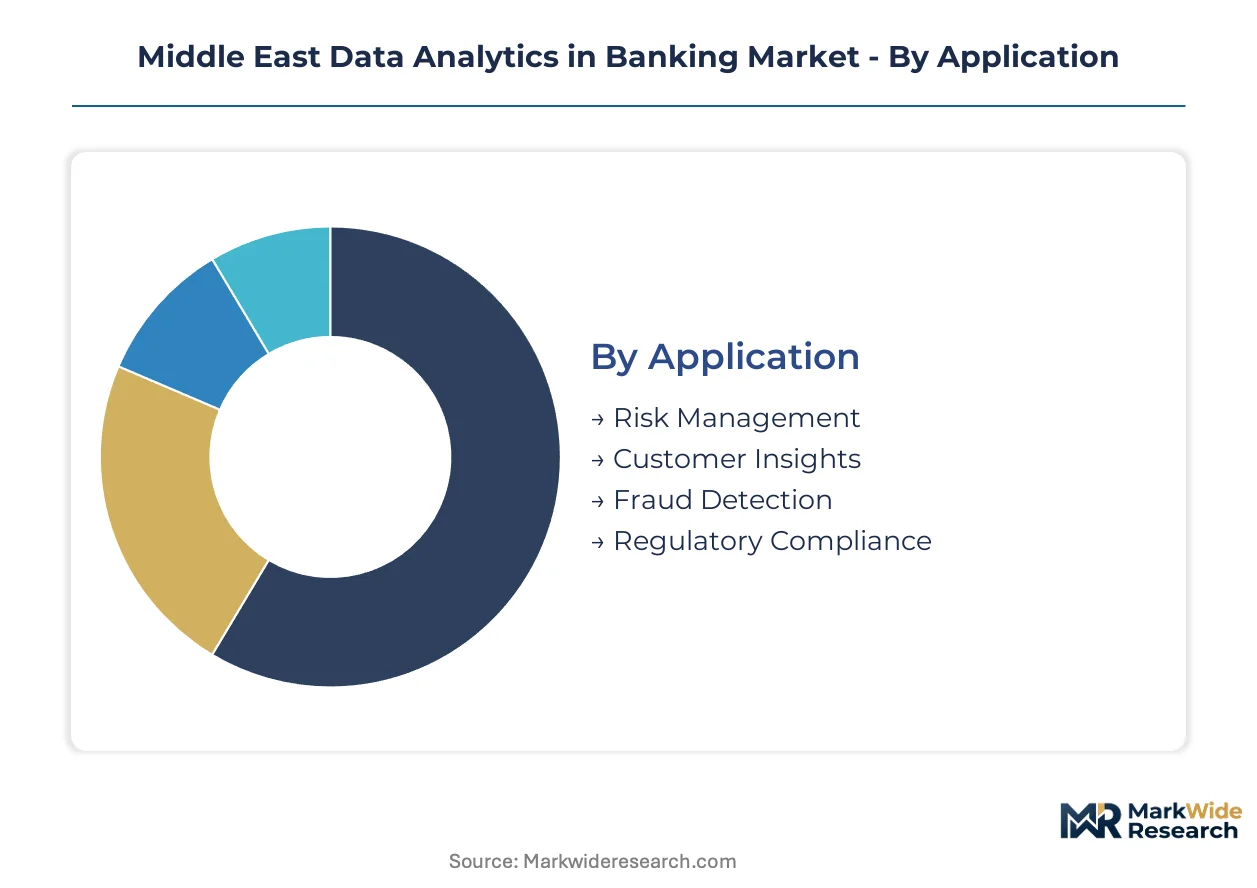
Segmentation reveals how Middle Eastern banks allocate analytics budgets across competing priorities. Application areas diverge sharply between defensive compliance spend and offensive customer acquisition investments. Technology choices separate cloud-native challengers from legacy institutions modernizing incrementally.
Application:
Fraud Detection commands premium pricing per seat, while Customer Insights delivers recurring SaaS margins across retail portfolios.
- Fraud Detection:Real-time transaction surveillance systems ingest payment streams at sub-second latency, flagging anomalous patterns before settlement completion. Saudi Arabian commercial banks deploy these engines most intensively, driven by SAMR mandates for digital channel monitoring and escalating cyberattack sophistication targeting SWIFT corridors.
- Customer Insights:Behavioral segmentation platforms unify transactional, demographic, and alternative data into propensity models for product cross-selling. UAE retail divisions concentrate demand here, compelled by the Open Banking Framework's data portability requirements and intensifying competition from neobanks with native personalization stacks.
- Risk Management:Credit scoring and portfolio stress-testing tools integrate Sharia-compliance filters for Islamic finance structures.
- Regulatory Compliance:Automated reporting pipelines map transactional data to PDPL, SAMR, and UAE Central Bank filing requirements.
Fraud Detection holds installed capacity. Customer Insights is rotating up the share rankings.
Technology:
Cloud Computing absorbs the largest infrastructure commitments, though Machine Learning claims the steepest talent acquisition budgets.
- Cloud Computing:Sovereign cloud deployments isolate banking workloads within national data residency boundaries, embedding encryption and access controls compliant with Saudi PDPL localization mandates. UAE institutions lead regional adoption, leveraging Dubai and Abu Dhabi data center clusters to minimize latency for real-time analytics.
- Machine Learning:Supervised and unsupervised algorithms power credit default prediction, churn forecasting, and anomaly detection across structured and unstructured datasets. Saudi fintechs and digital banks concentrate demand here, racing to deploy production models before explainability frameworks mature.
- Predictive Analytics:Statistical forecasting tools project portfolio performance and macroeconomic stress scenarios for ALCO committees.
- Big Data:Distributed storage and processing frameworks handle petabyte-scale transaction histories and alternative data ingestion.
Cloud Computing anchors current deployments. Machine Learning is expanding most quickly as model governance frameworks stabilize.
End User:
Commercial Banks generate volume, while Fintech Companies drive per-seat pricing premiums for cloud-native architectures.
- Commercial Banks:Full-service institutions deploy integrated analytics stacks spanning retail, corporate, and treasury divisions, requiring hybrid cloud configurations to bridge core banking systems with modern inference engines. Saudi National Commercial Bank and Emirates NBD represent anchor demand, modernizing COBOL-era transaction engines through middleware abstraction layers.
- Fintech Companies:Digital-native lenders and payment platforms build analytics-native from inception, leveraging serverless architectures and API-first data pipelines without legacy technical debt. Bahrain's regulatory sandbox hosts the densest concentration, testing AI-driven credit models under relaxed capital requirements.
- Investment Banks:Corporate advisory and trading desks deploy quantitative analytics for M&A screening and algorithmic execution.
- Credit Unions:Cooperative financial institutions adopt lightweight, pre-configured analytics modules through vendor-managed services.
Commercial Banks retain dominant procurement volumes. Fintech Companies are climbing the fastest in absolute spending growth.
Solution:
Decision Support Systems capture executive attention, though Data Visualization tools proliferate fastest through self-service adoption.
- Decision Support Systems:Integrated platforms synthesize predictive outputs, scenario simulations, and regulatory constraints into unified recommendations for credit committees and ALCO meetings. UAE corporate banking divisions concentrate investment here, demanding same-day facility approvals backed by live financial statement ingestion.
- Data Visualization:Self-service dashboards and exploratory analytics interfaces democratize data access beyond centralized IT teams, embedding directly into relationship manager workflows. Saudi retail banks deploy tablet-based variants for branch-level credit decisions, reducing ticket queue dependencies.
- Reporting Tools:Automated generation of regulatory filings, management packs, and investor disclosures from unified data warehouses.
- Dashboard Solutions:Pre-configured performance monitoring interfaces tracking KPIs across branches, products, and customer segments.
Decision Support Systems anchor enterprise commitments. Data Visualization is gaining share fastest through democratized adoption patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE-based analytics vendors export implementation services to Saudi Arabian commercial banks modernizing core systems under PDPL deadlines. Cross-border consulting flows concentrate through Dubai International Financial Centre and Riyadh financial district partnerships.
United Arab Emirates
Dubai International Financial Centre and Abu Dhabi Global Market anchor the region's densest banking analytics clusters. The UAE Central Bank's Open Banking Framework mandates API-native data sharing protocols that accelerate third-party fintech integration. Emirates NBD and First Abu Dhabi Bank operate live customer personalization engines processing transactional streams at sub-second latency.
Saudi Arabia
SAMR-aligned data localization requirements are driving sovereign cloud investments exceeding standard deployment costs by substantial margins. The Personal Data Protection Law imposes strict consent management and breach notification timelines for secondary data use in model training. Saudi National Commercial Bank modernizes COBOL-era transaction engines through middleware abstraction layers bridging legacy and inference systems.
Qatar
Domestic retail banks lag UAE and Saudi peers in customer analytics maturity, creating first-mover openings for cloud-native platform entrants. Qatar Central Bank regulations emphasize financial stability reporting without mandating real-time surveillance infrastructure. Doha-based institutions concentrate investment in regulatory compliance automation rather than predictive customer modeling.
Bahrain
The Central Bank's regulatory sandbox permits live testing of AI-driven credit models under relaxed capital requirements. Fintech companies cluster in Bahrain FinTech Bay to validate algorithmic underwriting before regional scaling. Manama-based digital lenders deploy serverless analytics architectures without legacy technical debt encumbrances.
Kuwait
Commercial banks prioritize risk management applications over customer-facing personalization due to conservative credit culture. The Central Bank of Kuwait maintains traditional reporting timelines without Open Banking mandates. Kuwait City financial institutions invest incrementally in batch-processed regulatory compliance tools rather than real-time streaming infrastructure.
Middle East Data Analytics in Banking Market Competitive Landscape
Listed leaders compete with private specialists across cloud infrastructure and core banking integration dimensions. The vendor base concentrates around three European software houses controlling integrated analytics-core banking bundles. Strategic archetypes include cloud hyperscalers, specialized risk modeling platforms, and legacy system integrators. Dominant competitive moves encompass sovereign cloud partnerships and middleware abstraction layer development.
Within the cloud infrastructure tier, Oracle Corporation and Microsoft Corporation occupy positions anchoring large-scale deployments. IBM Corporation exemplifies the specialized risk modeling archetype through platforms adapted to Islamic finance structures. Temenos AG represents core banking integration specialists sustaining analytics workflows across heterogeneous system environments. These three entities collectively illustrate the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle Corporation |
| SAP SE |
| FIS Global |
| Temenos AG |
| SAS Institute Inc. |
| Finastra |
| Microsoft Corporation |
| QlikTech International AB |
| Others |
Value Network & Pricing Analysis
Sovereign cloud capacity utilization rates in Saudi Arabia and the UAE anchor regional price floors, compressing margins for analytics vendors unable to achieve data-center scale. This scale concentration forces smaller providers toward specialized Islamic finance risk modeling niches or middleware integration layers, fragmenting the vendor base across distinct price-performance tiers.
Pricing Analysis
Legacy on-premise deployments command residual premiums from risk-averse Kuwaiti institutions, while cloud-native SaaS tiers undercut them by 30-40 percent through shared infrastructure economics. Three-tier pricing structure across enterprise-grade sovereign cloud, standard multi-tenant SaaS, and lightweight API-access tiers separates incumbent commercial banks from fintech challengers. Cost compression in the standard tier is intensifying because UAE Open Banking Framework mandates are commoditizing core data-sharing infrastructure. Fintech companies exhibit highest price sensitivity, while Saudi National Commercial Bank and Emirates NBD absorb enterprise premiums for PDPL-compliant localization.
Supply Chain Analysis
Strait of Hormuz transit underwrites subsea cable latency for real-time analytics traffic between European cloud regions and Gulf data centers, exposing infrastructure to geopolitical disruption. Hardware supply concentrates in Taiwan, South Korea, and the USA for GPU accelerators and sovereign-grade encryption modules. Saudi PDPL localization mandates tether deployment architectures to domestic server assembly capacity, creating single-source vulnerability for specialized banking-grade hardware. Distribution runs through Dubai International Financial Centre systems integrators serving pan-Gulf implementation contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of machine learning engineers with Islamic finance domain expertise constrains model deployment velocity across the Gulf Cooperation Council, elevating talent acquisition costs above infrastructure spend for most institutions.
For Market Incumbents: Compound data governance investments to lock in PDPL-compliant customer datasets before consent management requirements tighten further. Acquire specialist Sharia-compliant risk modeling boutiques to defend against IBM Corporation's Islamic finance platform expansion. Prioritize middleware abstraction layer development to bridge COBOL-era core systems with real-time inference engines without full replacement costs. For New Entrants and Emerging Players: Lead with cloud-native customer analytics platforms targeting Qatar's underpenetrated retail segment, where domestic banks lag UAE peers in behavioral segmentation maturity. Bahrain's regulatory sandbox offers the most penetrable entry point for AI-driven credit model validation under relaxed capital requirements. Deploy serverless architectures emphasizing API-first data pipelines to bypass legacy technical debt entirely. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors core banking integration specialists with proven middleware abstraction capabilities bridging heterogeneous system environments. Long-term viability hinges on regulatory compliance automation rather than pure predictive modeling, as central bank explainability frameworks mature. Watch for SAMR-aligned data localization mandates expanding beyond Saudi Arabia as the primary inflection signal for sovereign cloud demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | PDPL compliance in Saudi Arabia requires data residency within national boundaries, favoring localized infrastructure deployments. |
| Islamic Finance Risk Modeling Acquisition | Sharia-compliant credit scoring algorithms open differentiated product lines across Gulf Cooperation Council institutions. |
| Middleware Abstraction Layer Development | Legacy COBOL-era transaction engines in UAE banks impose latency floors incompatible with real-time inference without bridging technology. |
| Regulatory Sandbox Market Entry | Bahrain Central Bank licensing permits live AI credit model testing with relaxed capital requirements before regional scaling. |
| Edge-AI Branch Infrastructure Deployment | 5G convergence enables hyper-localized product recommendations without core banking round-trips, reducing latency to millisecond thresholds. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of UAE Central Bank regulatory filings, SAMR compliance documentation, and hyperscaler sovereign cloud capex disclosures. Interviews with chief data officers at Saudi commercial banks, analytics platform engineers at Dubai International Financial Centre clusters, and Sharia compliance officers at Islamic finance institutions informed demand-side validation. Secondary sources include SEC filings from listed vendors, trade data from Gulf customs authorities, and patent filings for real-time fraud detection algorithms. Bottom-up deployment estimates triangulate against top-down banking IT spending surveys.
Segmentation dimensions modeled span application area, technology layer, end-user archetype, and solution type across the projection horizon. Application segmentation captures defensive compliance spend versus offensive customer acquisition investments. Technology segmentation separates cloud infrastructure commitments from machine learning talent acquisition budgets. CAGRs derive from installed base growth rates, replacement cycle timing, and regulatory mandate compliance deadlines. Forecast inputs include API call volume projections under UAE Open Banking Framework and sovereign cloud capacity expansion timelines in Riyadh and Dubai.
Underlying assumptions cover PDPL enforcement consistency, SAMR localization interpretation stability, and Open Banking Framework API adoption velocity, with deviation risk concentrated in cross-border data flow friction between Saudi and UAE regulatory interpretations. Practitioners should keep alternative scenarios live as central bank explainability certification frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
In Vitro Fertilization Banking Services Market
Banking
Biometrics for Banking and Financial Services Market
Banking
Bank Management Software Market
Banking
Europe Machine Learning in Banking Market
Banking
Performance Bank Guarantee Market
Banking
Contactless Smart Cards in Banking Sales Market
Banking
Russia Data Analytics in Banking Market
Banking
Machine Learning in Banking Market
Banking
Global Big Data Analytics in Banking Market
Banking
North America Data Analytics in Banking Market
Banking
Investment Banking and Trading Services Market
Banking
Australia Neobanking Market
Banking
Voice Banking Market
Banking
China Retail Banking System Market
Banking
US Data Analytics in Banking Market
Banking
Saudi Arabia Retail Banking Market