
 Queue Manager Market | 2026-2036
Queue Manager Market Size, Share, and Industry Trends Forecast 2026-2036
Queue Manager Market Analytics
The EU AI Act is recalibrating how queue management vendors design algorithmic customer routing and data governance protocols. Q-Matic AB leverages its Nordic manufacturing base to sustain competitive positioning in European public sector deployments. Wavetec FZ-LLC anchors its growth across Middle Eastern banking and healthcare installations. Q-nomy Inc. differentiates through specialized healthcare workflow integration in North American hospital networks.
Queue managers are software-hardware systems that orchestrate customer flow through token generation, digital signage, real-time analytics dashboards, and API-based appointment scheduling, typically processing throughput rates of 50-500 visitors per service point per hour. Their primary commercial purpose is reducing perceived wait times while capturing operational data for workforce optimization. Cloud-based deployment leads in new installations as enterprises prioritize remote accessibility and subscription economics, while on-premises systems retain dominance in highly regulated healthcare environments where data residency requirements constrain off-site processing. The retail application segment occupies the largest revenue pool, though healthcare represents the fastest structural expansion as patient experience mandates harden.
The EU AI Act, GDPR, and HIPAA collectively shape product architecture by mandating explainable routing logic, consent management, and encrypted health data handling. ISO 27001 certification has become a baseline market access requirement for vendors serving European enterprises and American healthcare providers. Stakeholders must monitor how emerging algorithmic accountability rules in the European Union and state-level biometric privacy laws in the United States will constrain facial recognition-based queue analytics.
Market Dynamics
The EU AI Act is forcing queue management vendors to redesign algorithmic routing systems with mandatory explainability layers and consent management frameworks, fundamentally altering product architecture and competitive positioning across European deployments.
Growth Catalysts
- EU AI Act compliance mandates:Automated queue systems in European public services must now incorporate explainable decision logic, creating upgrade cycles across existing installations.
- Healthcare digitization in the United States:HIPAA-compliant patient flow management is accelerating cloud-to-hybrid transitions as hospital networks modernize emergency department throughput.
- API-first architecture:Open integration protocols are enabling queue managers to embed within broader workforce optimization stacks, expanding addressable use cases beyond standalone deployments.
Market Restraints
- Semiconductor supply volatility:Specialized system-on-chip components for edge computing nodes face allocation constraints from concentrated Taiwanese foundry capacity.
- GDPR enforcement escalation:Facial recognition analytics for queue prediction now requires explicit biometric consent, limiting deployment flexibility in European retail environments.
- On-premises infrastructure lock-in:Healthcare data residency requirements in Germany and France block cloud migration for 40% of hospital queue installations.
Strategic Opportunities
- Indian public sector modernization:State-level e-governance initiatives are creating tender pipelines for integrated queue-appointment systems in municipal service centers.
- Convergence of computer vision and edge AI:Real-time occupancy analytics are merging with queue prediction to enable dynamic staffing algorithms in banking halls.
- Subscription pricing penetration:SaaS deployment models are displacing perpetual licenses in mid-market retail chains, reducing customer acquisition friction.
Industry Challenges
- Embedded systems engineering talent scarcity:Firmware development for low-latency token dispensers competes with automotive and consumer electronics for skilled labor pools.
- ISO 27001 certification timelines:European enterprise procurement now mandates six-month security audit cycles, extending sales-to-revenue recognition intervals.
- Legacy ERP integration complexity:Hospital information systems with 1990s-era architectures require custom middleware development for queue data exchange.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Queue Manager Market |
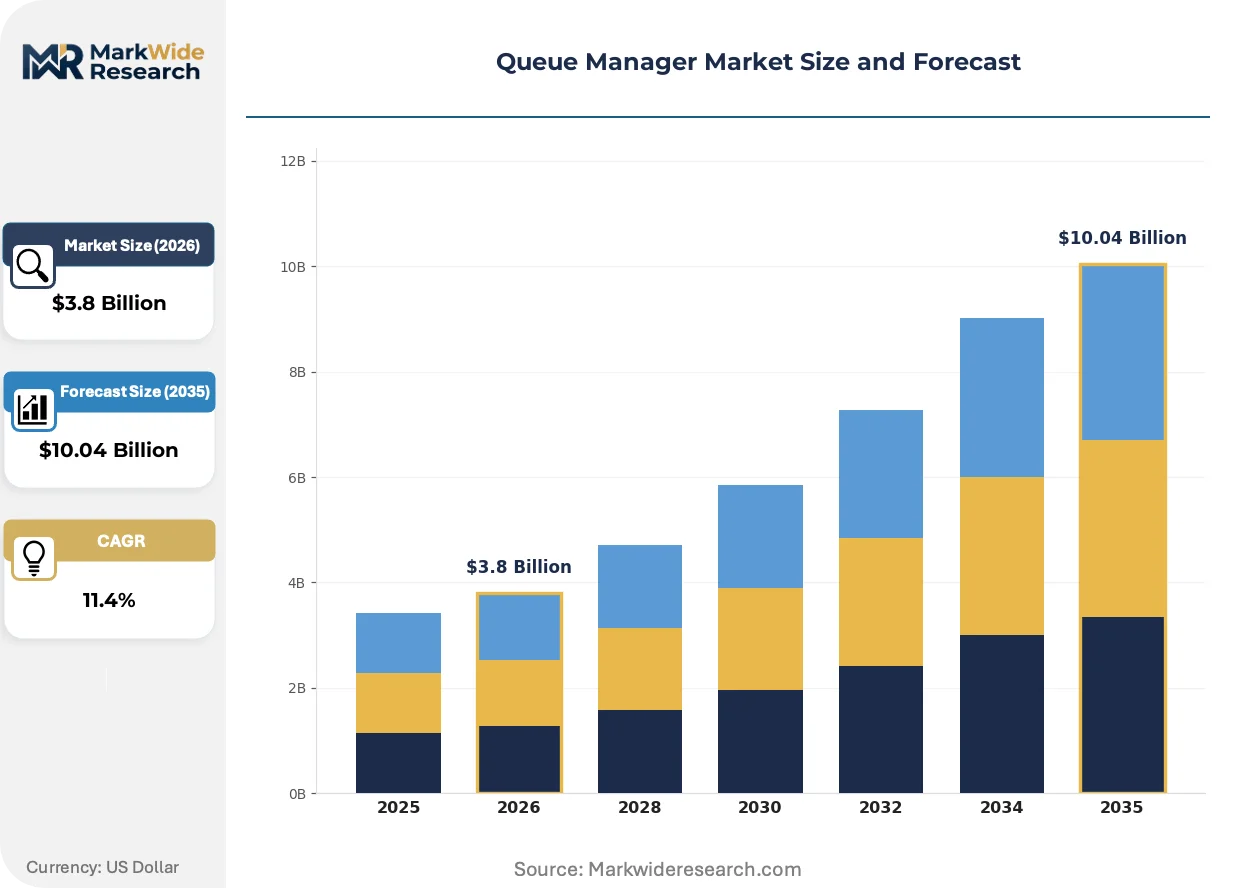
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud-Based, On-Premises, Hybrid, Mobile Application: Retail, Healthcare, Transportation, Entertainment Deployment: Public Cloud, Private Cloud, On-Premise, Multi-Tenant End User: Enterprises, SMBs, Public Sector, Nonprofits |
| Companies Covered | Q-Matic AB, QLess Inc., Aurionpro Solutions Ltd, Advantech Co. Ltd, Wavetec FZ-LLC, Q-nomy Inc., ATT Systems Group, Skiplino Inc., Lavi Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Queue Manager Market Evolving Landscape
Algorithmic accountability requirements and edge computing economics are converging to reshape how queue management systems process, store, and act on visitor flow data across regulated industries.
Computer vision-based queue analytics is expanding into retail banking lobbies and hospital emergency departments as GPU-accelerated edge devices enable sub-100-millisecond inference latency without cloud dependency. Tier-one banks in Singapore and the United States are piloting these systems for real-time branch staffing optimization. The technology is expanding into predictive service point allocation, compressing the gap between arrival pattern detection and workforce response.
The EU AI Act's risk classification framework is recalibrating vendor R&D priorities by mandating human oversight interfaces for high-risk automated decision systems in public sector queue deployments. German municipal authorities now require algorithmic impact assessments before procurement approval. Healthcare networks in France and the Netherlands are responding by bifurcating product lines between fully automated and human-in-the-loop configurations.
Enterprise buyers are unbundling hardware procurement from software subscriptions, treating digital signage and token dispensers as commodity infrastructure while negotiating queue analytics as separate SaaS tiers. This pattern is most visible in United States retail pharmacy chains and United Kingdom government service centers. Vendors must now maintain pricing discipline across disaggregated purchasing committees rather than unified capital expenditure approvals.
Queue Manager Market Segmentation
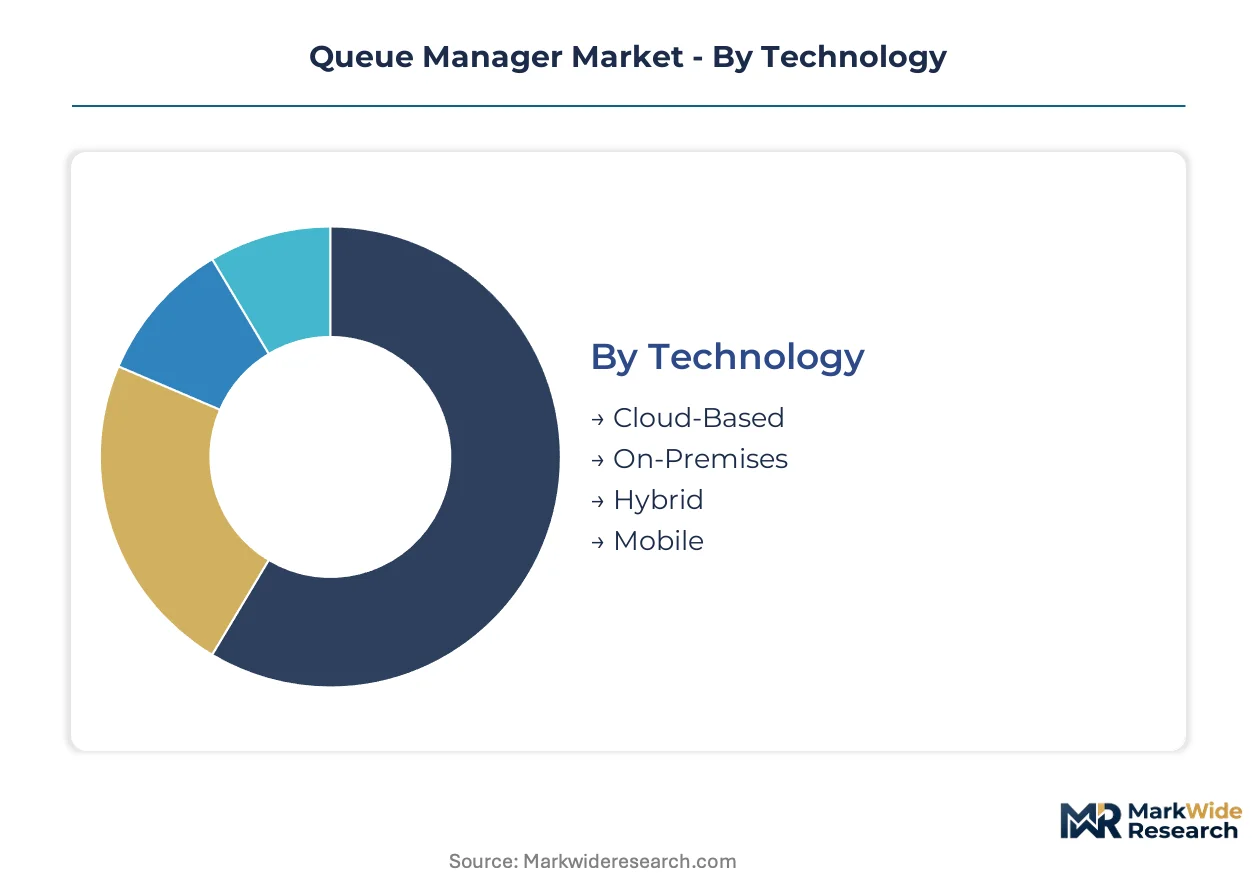
Queue manager segmentation reveals how deployment constraints, regulatory requirements, and customer scale reshape vendor product architecture and go-to-market economics. Understanding these dimensions exposes where margin pools concentrate and which technology transitions are commercially mature versus experimental.
Technology:
Supply concentration in edge computing hardware and hyperscaler infrastructure is forcing tiered vendor strategies across deployment modalities.
- Cloud-Based:SaaS architectures running on AWS, Azure, or Google Cloud enable remote dashboard access and elastic scaling for multi-location retail chains. United States pharmacy networks and United Kingdom government service centers are consolidating procurement around subscription models that unbundle hardware from analytics software.
- On-Premises:Local server installations with encrypted data residency satisfy HIPAA requirements in American hospital emergency departments and GDPR mandates in German municipal service centers. Firmware development for low-latency token dispensers competes with automotive electronics for scarce embedded systems engineering talent.
- Hybrid:Split architectures process sensitive visitor data locally while pushing analytics to cloud tiers, addressing French and German healthcare data sovereignty rules that block full cloud migration for hospital queue installations.
- Mobile:Smartphone-native queue management via progressive web apps or native applications eliminates hardware dependency for SMBs and pop-up retail environments, though limited by digital literacy gaps in aging patient populations.
Cloud-Based deployments absorb the bulk of installed capacity in retail and banking; Hybrid configurations are expanding most quickly as regulated industries navigate data residency compliance.
Application:
End-use differentiation determines whether vendors optimize for throughput velocity, regulatory audit trails, or passenger safety integration.
- Retail:High-frequency customer flow optimization in supermarkets, pharmacies, and banking halls drives demand for real-time occupancy analytics and dynamic staffing algorithms. Singaporean and American tier-one banks are piloting GPU-accelerated edge devices for sub-100-millisecond inference latency.
- Healthcare:HIPAA-compliant patient flow management with explainable routing logic addresses EU AI Act mandates for algorithmic accountability in public sector deployments. French and Dutch hospital networks are bifurcating product lines between fully automated and human-in-the-loop configurations.
- Transportation:Integration with flight information systems and baggage handling protocols requires specialized middleware for airport and rail terminal deployments.
- Entertainment:Venue-specific requirements for group entry management and season ticket priority access create customization demands that strain standardized SaaS margins.
Retail captures the dominant revenue pool; Healthcare is climbing the fastest as patient experience mandates harden and emergency department throughput becomes a operational priority.
Deployment:
Customer IT governance maturity and procurement committee structure determine whether vendors sell unified solutions or disaggregated tiers.
- Public Cloud:Shared infrastructure with standardized SLAs appeals to mid-market retail chains seeking to reduce customer acquisition friction through subscription economics.
- Private Cloud:Dedicated single-tenant environments address data isolation requirements in European banking and American healthcare without full on-premises capital expenditure.
- On-Premise:Physical infrastructure ownership persists where legacy ERP integration complexity or air-gapped security requirements block external connectivity.
- Multi-Tenant:Architecture enabling multiple organizational units to share queue infrastructure while maintaining data separation appeals to municipal service centers and university campus networks.
Public Cloud deployments dominate new installations; Private Cloud is gaining share fastest as enterprises seek middle-ground compliance postures.
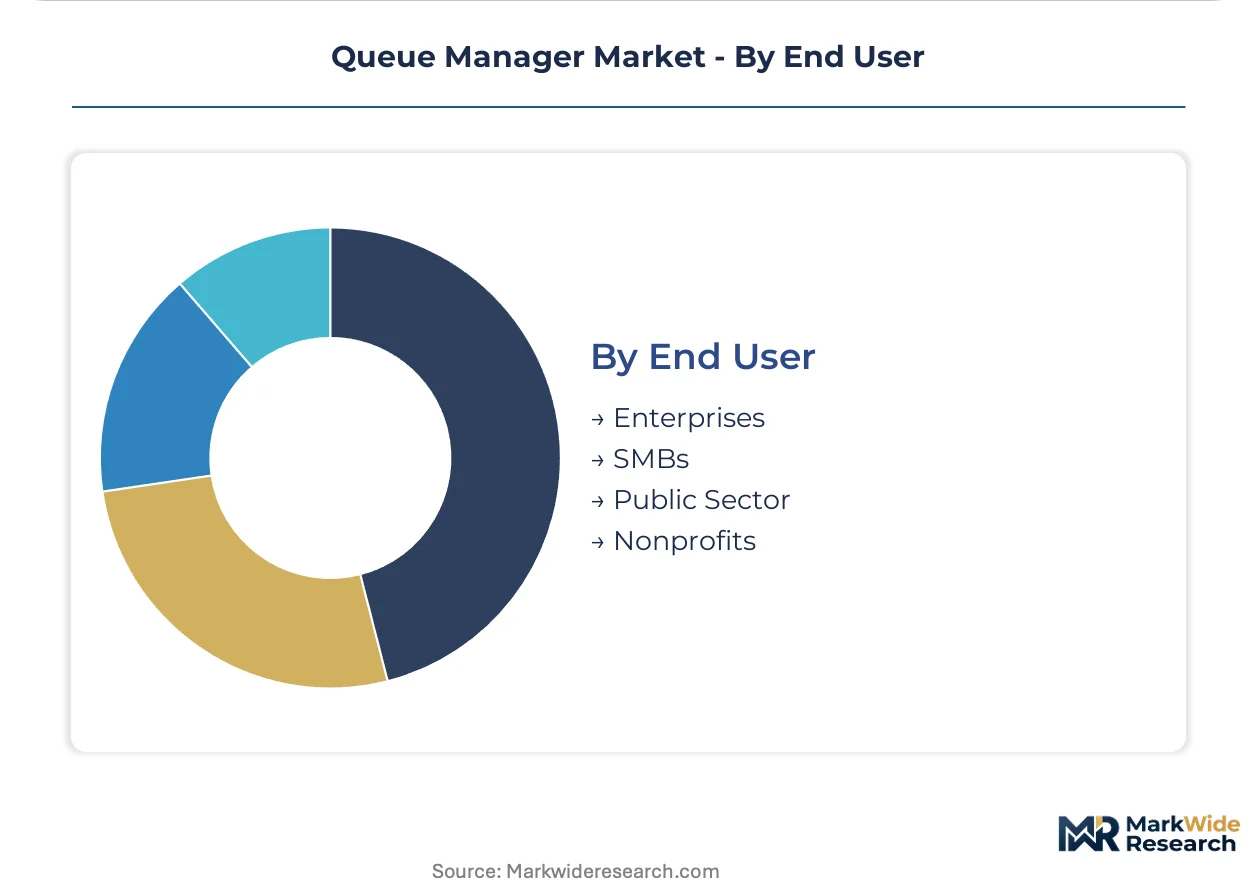
End User:
Scale and procurement sophistication fragment vendor sales motion between enterprise field teams, inside sales, and public sector tender specialists.
- Enterprises:Fortune 500 retail chains and hospital networks negotiate queue analytics as separate SaaS tiers while treating digital signage as commodity infrastructure, requiring pricing discipline across disaggregated purchasing committees.
- SMBs:Small and medium businesses favor mobile-first or tablet-based solutions with minimal IT overhead, though price sensitivity constrains vendor margin expansion.
- Public Sector:Indian state-level e-governance initiatives and European municipal authorities create tender pipelines requiring ISO 27001 certification and algorithmic impact assessments before procurement approval.
- Nonprofits:Budget-constrained community health centers and social service agencies prioritize basic token generation over advanced analytics, limiting addressable revenue per account.
Enterprises command the majority of vendor R&D investment; Public Sector is expanding most quickly as digital service infrastructure modernization accelerates across India, Germany, and the United States.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for queue management hardware concentrates in Nordic and East Asian industrial clusters, while consumption tilts toward North American healthcare networks and European public sector modernization programs.
United States
Hospital emergency departments and retail pharmacy chains drive cloud-to-hybrid transitions for HIPAA-compliant patient flow management. The FDA and state-level biometric privacy laws constrain facial recognition analytics deployment in California and Illinois. Dallas and Atlanta anchor banking sector pilots for GPU-accelerated edge devices in branch staffing optimization.
Germany
Municipal service centers and university hospitals require algorithmic impact assessments under the EU AI Act before procurement approval. The KBA and federal data protection authorities enforce GDPR-compliant data residency for 40% of hospital queue installations blocking full cloud migration. Munich and Hamburg concentrate vendor R&D investment for human-in-the-loop system configurations.
India
State-level e-governance initiatives in Maharashtra and Karnataka create tender pipelines for integrated queue-appointment systems in municipal service centers. The RBI and BIS influence fintech integration standards for banking hall deployments. Bangalore and Hyderabad anchor domestic software development for mobile-first queue management solutions.
France
Hospital networks in Île-de-France and Provence-Alpes-Côte d'Azur bifurcate product lines between fully automated and human-in-the-loop configurations to satisfy EU AI Act risk classifications. The ANSM and CNIL mandate explainable routing logic for public sector queue systems. Lyon concentrates healthcare IT integration specialists serving French and Dutch hospital networks.
Singapore
Tier-one banks pilot computer vision-based queue analytics for real-time branch staffing optimization with sub-100-millisecond inference latency. The Monetary Authority of Singapore influences fintech integration protocols for financial services queue management. The city-state anchors Southeast Asian demand for GPU-accelerated edge devices in retail banking lobbies.
Queue Manager Market Competitive Landscape
The competitive structure tilts toward specialized healthcare workflow integrators and Nordic manufacturing-based public sector vendors. Tier-one vendors differentiate through HIPAA-compliant cloud architectures and EU AI Act-ready explainability layers, while mid-market players compete on subscription pricing for retail and SMB segments. Two strategic archetypes dominate: healthcare-specialized workflow integrators and hardware-anchored public sector vendors. M&A activity concentrates on API-first software acquisitions, and geographic expansion into Indian state-level e-governance tenders represents the second dominant competitive move.
Among Nordic-based public sector specialists, Q-Matic AB exemplifies the hardware-anchored archetype with manufacturing concentration suited to European municipal deployments. Wavetec FZ-LLC occupies a position within Middle Eastern banking and healthcare installation specialists, while Q-nomy Inc. represents the healthcare workflow integration archetype serving North American hospital networks. These three companies illustrate how vendor positioning fragments across regulatory compliance requirements and end-use specialization rather than converging on unified platform strategies.
| Leading Market Players |
|---|
| Q-Matic AB |
| QLess Inc. |
| Aurionpro Solutions Ltd |
| Advantech Co. Ltd |
| Wavetec FZ-LLC |
| Q-nomy Inc. |
| ATT Systems Group |
| Skiplino Inc. |
| Lavi Industries |
| Others |
Value Network & Pricing Analysis
Captive manufacturing of edge computing hardware in Nordic industrial clusters anchors vendor pricing power by insulating tier-one producers from foundry allocation volatility. This integration choice lets Q-Matic AB and comparable specialists defend margin structures while mid-market competitors absorb semiconductor spot-market turbulence.
Pricing Analysis
Price erosion across mid-market SaaS tiers traces to hyperscaler infrastructure commoditization and buyer committee unbundling of hardware from software procurement. Three-tier pricing structure across premium, standard, and economy levels separates HIPAA-compliant healthcare configurations from basic retail token systems. Certification investment for ISO 27001 and EU AI Act readiness drives premium tier pricing. SMB pharmacy chains exhibit acute price sensitivity, while German municipal authorities prioritize audit-trail completeness over cost.
Supply Chain Analysis
Domestic-content mandates in Indian state-level e-governance tenders are reshaping sourcing toward local software development clusters in Bangalore and Hyderabad. Hardware assembly concentrates in Sweden, Taiwan, and China, with system-on-chip components drawing from concentrated Taiwanese foundry capacity. GPU-accelerated inference modules and encrypted token dispensers constitute critical input dependencies. Single-source vulnerability in edge AI chipsets threatens delivery timelines for healthcare installations. Distribution runs through direct enterprise field teams for hospital networks and tender specialists for public sector deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded systems engineering talent scarcity props pricing for firmware-capable vendors, constraining capacity expansion across European and North American healthcare deployments.
For Market Incumbents: Acquire API-first software specialists to fortify integration layers against workforce optimization platform consolidation. Invest in captive edge device manufacturing to reduce Taiwan foundry exposure. ISO 27001 certification acceleration addresses procurement friction in German municipal tenders.
For New Entrants and Emerging Players: Launch via mobile-first progressive web apps targeting Indian municipal service centers and SMB retail chains underserved by hardware-heavy incumbents. White-space concentrates in hybrid deployment architectures for French and German hospital data sovereignty requirements. Channel partnerships with domestic system integrators accelerate tender access.
For Investors and Strategic Acquirers: Exit pathways concentrate in healthcare workflow integration specialists with HIPAA-compliant cloud architectures and established GPO contracts. Long-term viability hinges on EU AI Act compliance infrastructure and explainable routing IP. Watch algorithmic impact assessment mandates as inflection signal for public sector procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of API-First Specialist | Embeds queue analytics within broader workforce optimization stacks serving Fortune 500 retail. |
| EU AI Act Compliance Certification | Unlocks German municipal tender pipelines requiring algorithmic impact assessments. |
| Hybrid Cloud Architecture Launch | Addresses French healthcare data sovereignty blocking full cloud migration. |
| Edge AI Chipset Supply Agreement | Secures GPU-accelerated inference capacity for sub-100-millisecond banking deployments. |
| Mobile-First Platform Expansion | Captures Indian e-governance tenders and SMB segments with minimal hardware overhead. |
Research Methodology
Document review covered regulatory filings from the FDA and EU AI Act implementation guidance, complemented by interviews with hospital biomedical engineers, municipal IT procurement officers, retail pharmacy operations directors, and queue management vendor product strategists. Secondary validation drew from SEC 10-K disclosures, hyperscaler infrastructure capex reports, and healthcare GPO contract databases. Bottom-up installation counts and top-down enterprise IT spending estimates were triangulated.
Segmentation outputs across deployment modality, application vertical, and end-user scale were generated over the projection horizon. CAGRs were derived from elasticity modeling against healthcare digitization budgets and retail footprint expansion. Forecast inputs incorporated EU AI Act compliance upgrade cycles and Indian state-level e-governance tender pipelines.
Semiconductor allocation disruptions, GDPR enforcement escalation on biometric analytics, and hospital ERP integration complexity are the dominant revision risks. Forecasts reflect assumptions around foundry capacity normalization and regulatory timeline adherence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Decision Support System (DSS) Software Market
Software & Services
Royalty Management Software and Services Market
Software & Services
Car-Hailing Software Market
Software & Services
Attendance Tracking Software Market
Software & Services
Asia-Pacific IT Services Market
Software & Services
PCB CAD Software Market
Software & Services
Global Email Management Software Market
Software & Services
Emotion Recognition and Sentiment Analysis Software Market
Software & Services
Saas-Based Expense Management Market
Software & Services
Global Affiliate Software Market
Software & Services
Labeling Software Market
Software & Services
Retail Core Banking Solution Market
Software & Services
Global Retail Execution Software Market
Software & Services
Application Platform As a Service Market
Software & Services
Medical E-Commerce Software Market
Software & Services
3D Animation Software Market