
 Asia-Pacific Data Monetization Market | 2026-2036
Asia-Pacific Data Monetization Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Data Monetization Market Analytics
Revenue-sharing partnerships between cloud infrastructure providers and analytics software vendors are reshaping competitive economics in the Asia-Pacific data monetization landscape. IBM Corporation leverages its hybrid cloud architecture to anchor enterprise data exchange deployments across Australian financial institutions. SAP SE specializes in industry-specific data monetization templates that extend its ERP footprint into aftermarket analytics services. Microsoft Corporation dominates the SaaS deployment layer, competing through embedded Power BI monetization tools that control enterprise subscription flows.
Data monetization encompasses the conversion of raw, processed, or inferred data assets into measurable economic value through direct sales, licensing arrangements, or internal operational optimization, typically requiring structured metadata taxonomies, API-accessible delivery mechanisms, and privacy-preserving computation frameworks such as federated analytics or differential privacy. Its primary commercial purpose is transforming dormant information reservoirs into recurring revenue streams or cost-reduction instruments. Cloud-based deployment now leads solution delivery across the region, though on-premise configurations retain stronghold status among South Korean banking regulators demanding localized data sovereignty. Data brokerage solutions represent the fastest-expanding segment as third-party intermediaries aggregate cross-industry datasets for insurance and retail buyers seeking behavioral prediction inputs.
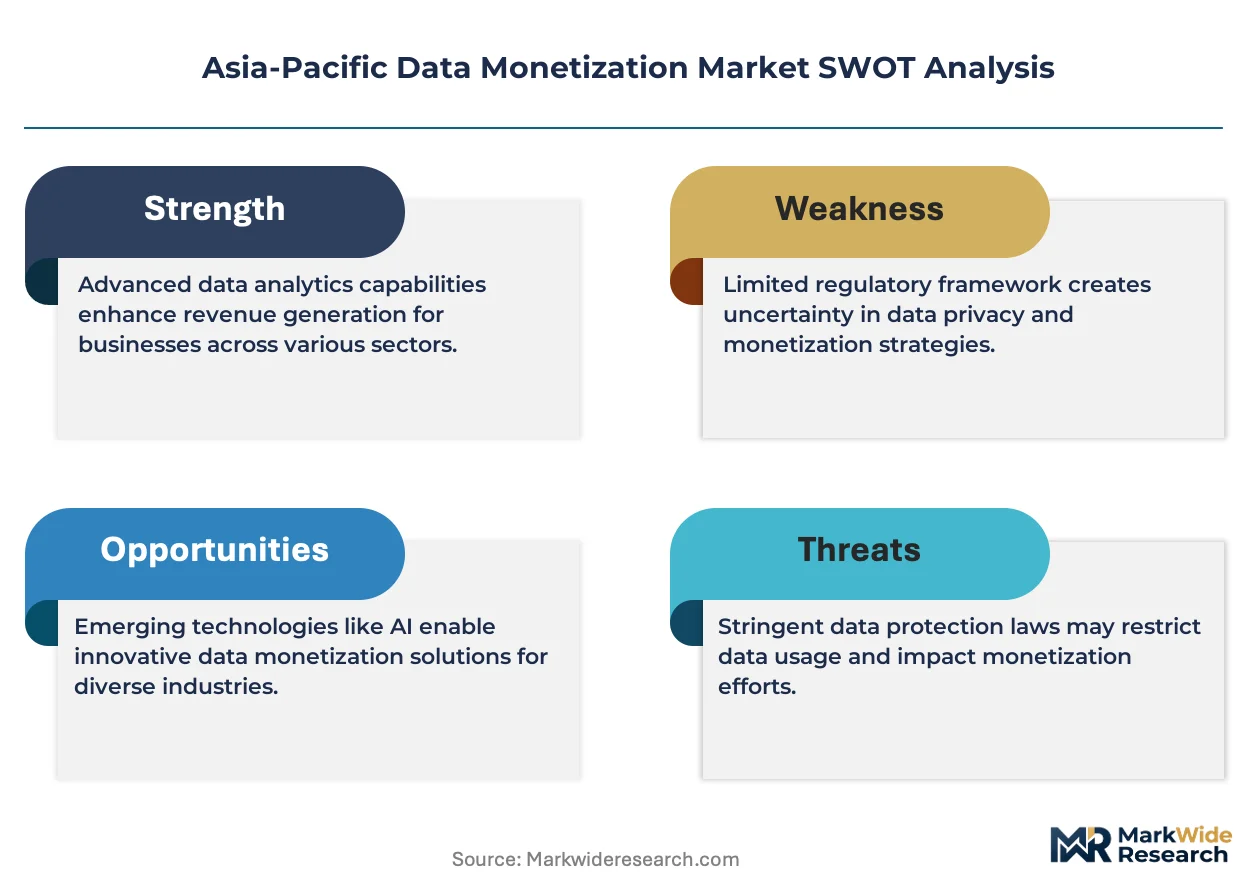
India's Digital Personal Data Protection Act and China's Personal Information Protection Law impose divergent consent and localization obligations that fragment platform architecture requirements across the region. Australia's Privacy Act amendments and Singapore's PDPC guidelines on data portability further complicate cross-border data product standardization. Japan's APPI framework governs anonymization thresholds for monetized health data exports. Stakeholders must monitor regulatory divergence between data localization mandates and emerging interoperability standards to determine whether centralized or federated monetization infrastructure delivers sustainable compliance economics.
Market Dynamics
Telecom operators across Southeast Asia are restructuring subscriber data architectures to capture analytics value through brokerage partnerships, forcing platform vendors to rebuild consent management layers for fragmented regulatory environments.
Growth Catalysts
- Industrial Data Exchanges:China's provincial governments operate state-backed data trading platforms that aggregate manufacturing sensor streams for financial derivatives pricing.
- India's Digital Personal Data Protection Act:Platform operators must restructure consent architectures, creating demand for privacy-preserving computation frameworks and audit-ready data lineage tools.
- API-First Delivery Mechanisms:Real-time data product consumption through standardized interfaces is accelerating cross-border dataset licensing between Australian financial institutions and Singaporean analytics vendors.
Market Restraints
- Localization Mandates:South Korean banking regulators demand on-premise data sovereignty configurations that inflate infrastructure costs versus cloud-native alternatives.
- Anonymization Threshold Uncertainty:Japan's APPI framework governs health data export thresholds with ambiguous technical standards that delay product commercialization timelines.
- Cross-Border Standardization Friction:Divergent consent obligations between India's DPDP Act and China's PIPL fragment platform architecture requirements, raising compliance engineering overhead.
Strategic Opportunities
- Vietnamese Manufacturing Data Pools:Underpenetrated industrial IoT deployments in northern Vietnam offer first-mover aggregation positions for equipment telemetry monetization.
- Federated Analytics Convergence:Differential privacy techniques combined with edge computing architectures enable cross-enterprise dataset collaboration without raw data centralization.
- Singapore's PDPC Portability Guidelines:Data portability mandates create channel innovation opportunities for intermediary platforms that standardize consent-driven data transfer protocols.
Industry Challenges
- Metadata Taxonomy Engineering:Shortage of professionals capable of designing interoperable semantic standards across heterogeneous enterprise data lakes constrains productization velocity.
- Legacy ERP Integration Complexity:SAP and Oracle system environments in established Asian enterprises resist API-native data extraction without expensive middleware redevelopment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Data Monetization Market |
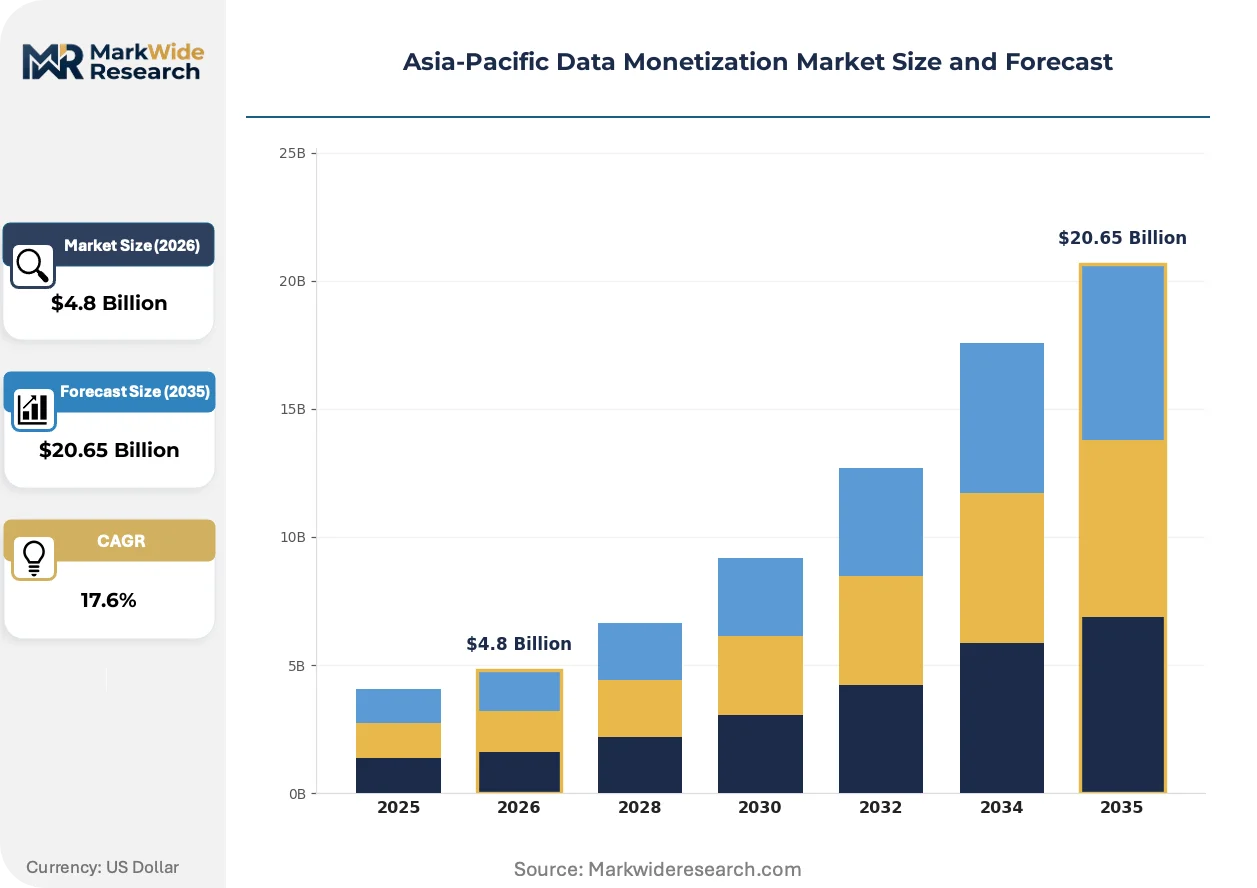
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $20.65 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Data Analytics, Data Brokerage, Advertising Technology, Cloud Services Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Telecommunications, Retail, Finance, Healthcare Technology: Machine Learning, Artificial Intelligence, IoT, Blockchain |
| Companies Covered | Accenture PLC, IBM Corporation, SAP SE, Oracle Corporation, Salesforce, Inc., Google LLC, Infosys Limited, Cisco Systems, Inc., Microsoft Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Data Monetization Market Evolving Landscape
Privacy-preserving computation architectures are displacing centralized data warehousing as the dominant technical foundation for monetization platforms across the region.
Federated analytics infrastructure is migrating from experimental pilot deployments to production-grade enterprise architectures. Australian financial institutions and Singaporean insurance consortia are adopting differential privacy frameworks for cross-institutional risk modeling. This migration from centralized data lakes to distributed computation nodes is compressing time-to-insight for behavioral prediction products while reducing regulatory exposure.
China's Personal Information Protection Law imposes strict consent granularity requirements on platform operators processing consumer behavioral data. Industrial data exchanges in Guangdong and Zhejiang provinces have restructured trading protocols to accommodate individual withdrawal rights and purpose limitation mandates. Manufacturing sector participants are responding by segmenting data products into tiered sensitivity classifications with differentiated licensing terms.
Subscription-based data product procurement is displacing perpetual license arrangements across Asia-Pacific enterprise buyers. Procurement teams in Indonesian retail conglomerates and Thai banking groups now demand consumption-metered pricing tied to query volume or API call frequency. This behavioral shift is most visible in Australia's financial services vertical, where tiered SaaS contracts with embedded analytics tools dominate new vendor selections.
Asia-Pacific Data Monetization Market Segmentation
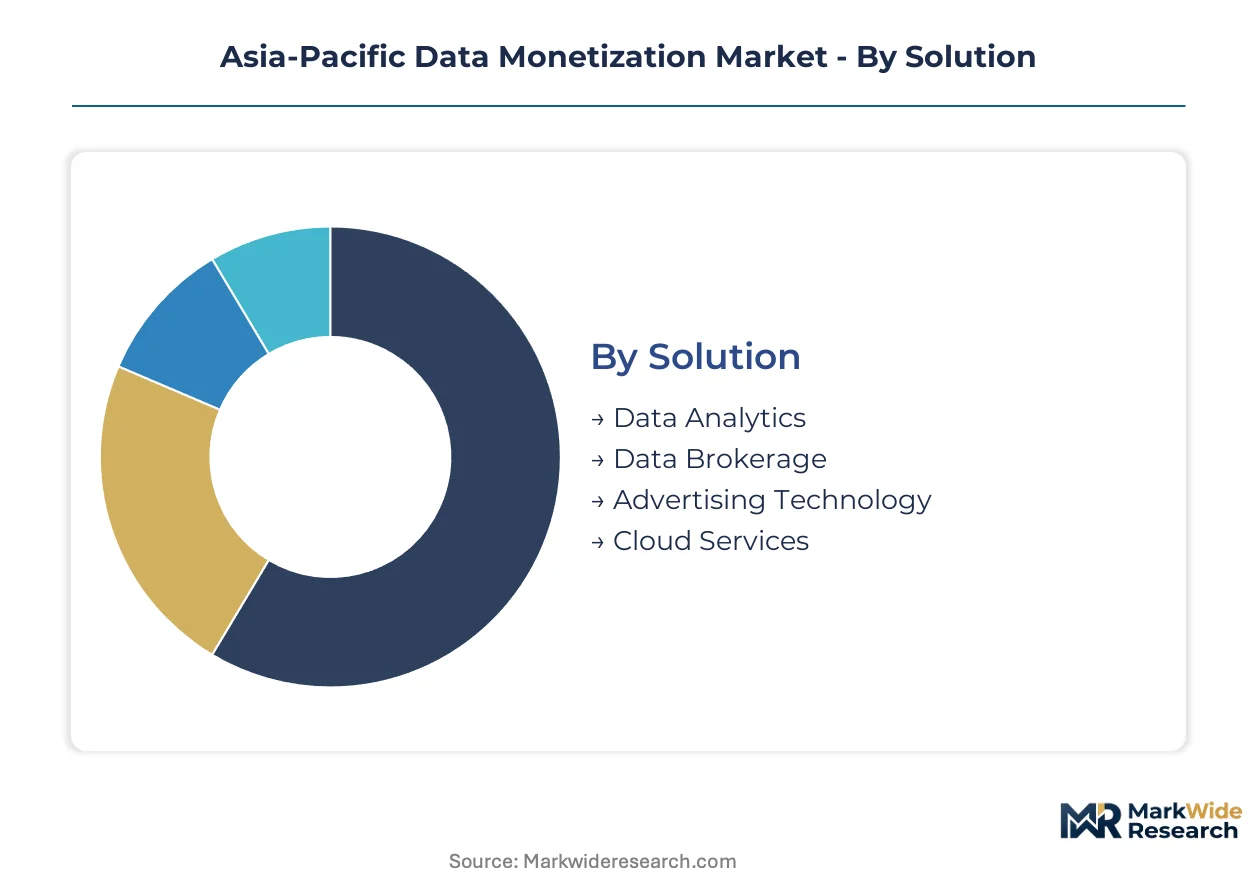
Segmentation in Asia-Pacific data monetization reveals how solution architecture, infrastructure choices, and end-user requirements fragment vendor strategies across regulatory and technological boundaries. Understanding these divisions exposes where compliance costs concentrate and where pricing power accrues.
Solution:
After-sales service intensity varies sharply across solution types, with data brokerage platforms demanding continuous consent management updates while cloud services require less frequent architectural intervention.
- Data Analytics:Platforms processing subscriber behavioral streams and manufacturing sensor outputs require embedded privacy-preserving computation layers. Australian financial institutions and Singaporean insurance consortia drive demand for real-time risk modeling capabilities that compress decision latency.
- Data Brokerage:Third-party intermediaries aggregate cross-industry datasets for behavioral prediction inputs, forcing continuous consent architecture rebuilds as India's DPDP Act and China's PIPL impose divergent withdrawal rights. Southeast Asian telecom operators anchor this segment's expansion through subscriber analytics partnerships.
- Advertising Technology:Consent granularity requirements under China's PIPL restrict behavioral targeting precision.
- Cloud Services:Consumption-metered pricing tied to API call frequency dominates procurement patterns.
By volume, Data Analytics leads. By growth pace, Data Brokerage is ahead.
Deployment:
Cost tier stratification separates sovereign-compliant configurations from elastic cloud-native alternatives, with hybrid architectures commanding premium positioning for regulated verticals.
- Cloud-Based:Elastic infrastructure now leads solution delivery across the region, with subscription-based procurement displacing perpetual licenses. Indonesian retail conglomerates and Thai banking groups demand consumption-metered pricing tied to query volume.
- On-Premise:South Korean banking regulators mandate localized data sovereignty configurations that inflate infrastructure costs versus cloud alternatives. MFDS-aligned healthcare deployments in Seoul and Busan retain this architecture for patient record analytics.
- Hybrid:IBM Corporation anchors enterprise data exchange deployments across Australian financial institutions through this model.
- SaaS:Microsoft Corporation dominates this layer through embedded Power BI monetization tools.
Cloud-Based deployments capture the largest installed base. Hybrid configurations show the steepest expansion trajectory among regulated sectors.
End User:
Application maturity diverges sharply, with telecommunications and finance operating production-grade monetization architectures while healthcare remains constrained by anonymization threshold uncertainty.
- Telecommunications:Southeast Asian operators restructure subscriber data architectures to capture analytics value through brokerage partnerships. TRAI-regulated Indian carriers and Singaporean incumbents lead API-first delivery mechanism adoption.
- Finance:Tiered SaaS contracts with embedded analytics tools dominate new vendor selections in Australian financial services. Cross-border dataset licensing between Australian institutions and Singaporean vendors accelerates through standardized interfaces.
- Retail:Procurement teams in Indonesian conglomerates demand consumption-metered pricing.
- Healthcare:Japan's APPI framework governs anonymization thresholds with ambiguous technical standards that delay product commercialization.
Finance generates the highest revenue per deployment. Telecommunications is climbing the fastest as subscriber data architectures mature.
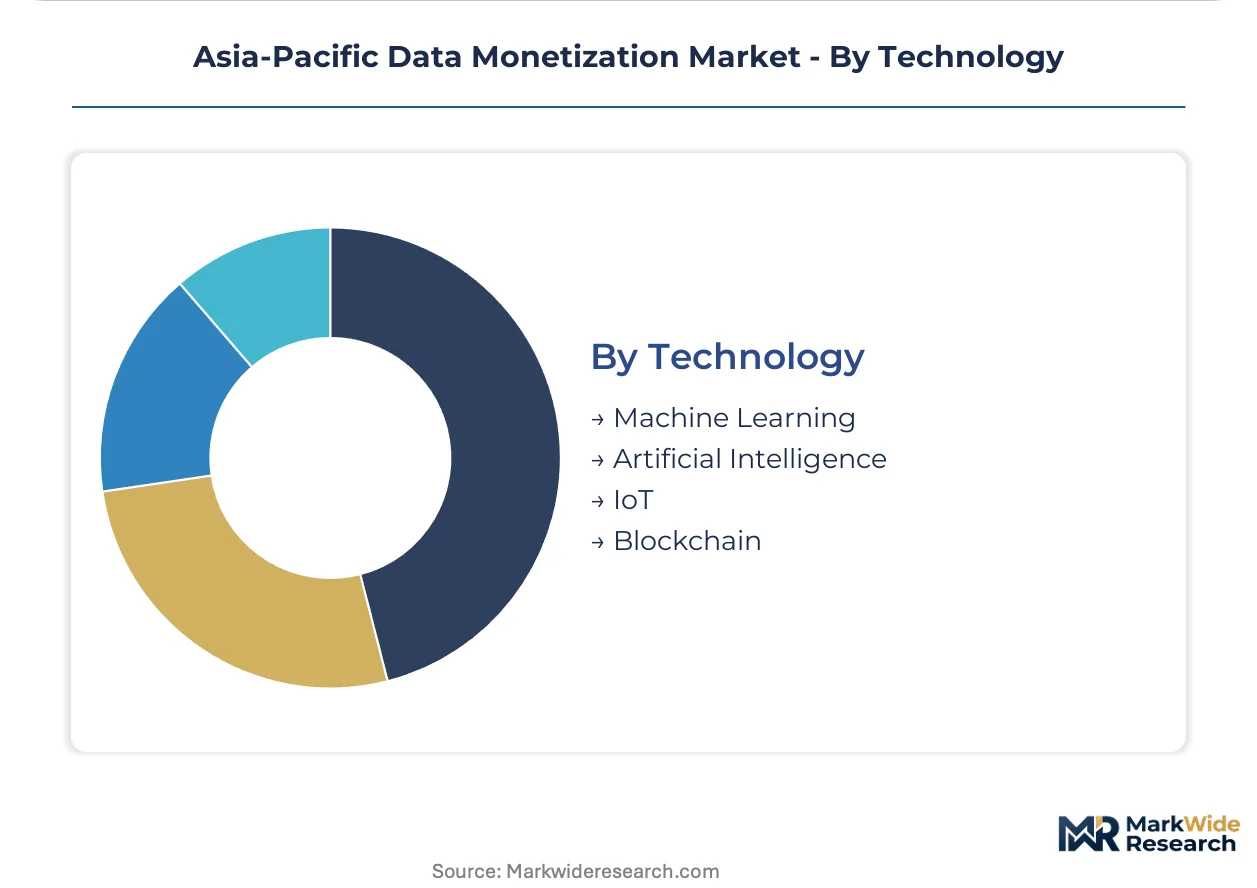
Technology:
Supply concentration favors established platform vendors for Machine Learning and Artificial Intelligence, while IoT and Blockchain remain fragmented with higher integration overhead.
- Machine Learning:Behavioral prediction products across Australian financial institutions and Singaporean insurance consortia rely on differential privacy frameworks for cross-institutional risk modeling. Federated analytics infrastructure migrates from pilot to production-grade architectures.
- Artificial Intelligence:SAP SE specializes in industry-specific templates extending ERP footprints into aftermarket analytics services. Inference engines processing manufacturing sensor streams in Guangdong and Zhejiang industrial exchanges anchor demand.
- IoT:Northern Vietnamese manufacturing data pools offer first-mover aggregation positions for equipment telemetry monetization.
- Blockchain:Provincial data trading platforms experiment with provenance verification for tiered sensitivity classifications.
Machine Learning commands the deepest enterprise penetration. IoT is gaining share fastest among industrial data exchange participants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border data flows within Asia-Pacific generate substantial export value for analytics services while import dependency persists for specialized privacy-preserving computation hardware. The region's regulatory fragmentation creates distinct operational zones that vendors must navigate through localized infrastructure investments.
China
Provincial governments in Guangdong and Zhejiang operate state-backed industrial data exchanges aggregating manufacturing sensor streams for financial derivatives pricing. SAMR and MEE oversight enforces strict consent granularity under PIPL, forcing platform operators to segment data products into tiered sensitivity classifications. Manufacturing clusters in the Pearl River Delta restructure trading protocols to accommodate individual withdrawal rights.
India
TRAI-regulated telecom carriers restructure subscriber data architectures to capture analytics value through brokerage partnerships with retail and insurance buyers. The Digital Personal Data Protection Act mandates consent architecture rebuilds, creating demand for audit-ready data lineage tools and federated analytics frameworks. Bengaluru and Hyderabad host emerging platform vendors serving domestic financial institutions.
Japan
Financial institutions in Tokyo and Osaka adopt differential privacy frameworks for cross-institutional risk modeling, compressing time-to-insight for behavioral prediction products. METI guidance and the APPI framework govern anonymization thresholds for health data exports with ambiguous technical standards that delay commercialization. Healthcare analytics clusters in Kansai retain on-premise configurations for patient record processing.
Australia
Tiered SaaS contracts with embedded analytics tools dominate procurement patterns among Sydney and Melbourne financial services firms. Privacy Act amendments and TGA guidelines complicate cross-border data product standardization with regional counterparts. Revenue-sharing partnerships between cloud infrastructure providers and analytics software vendors reshape competitive economics across Australian banking consortia.
Singapore
PDPC guidelines on data portability create channel innovation opportunities for intermediary platforms standardizing consent-driven data transfer protocols. Insurance consortia adopt federated analytics infrastructure for production-grade cross-enterprise dataset collaboration. The city-state's regulatory clarity attracts regional headquarters for vendors serving Southeast Asian telecom operators restructuring subscriber data architectures.
Asia-Pacific Data Monetization Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper technical positioning. The vendor base clusters around three strategic archetypes: cloud hyperscalers with embedded analytics stacks, ERP incumbents extending into aftermarket data services, and pure-play data brokerages aggregating cross-industry datasets. Dominant competitive moves include M&A activity targeting consent management layer capabilities and strategic partnerships between infrastructure providers and vertical analytics specialists.
Within the platform integrator tier, IBM Corporation and Microsoft Corporation anchor enterprise data exchange deployments across regulated financial institutions. SAP SE exemplifies the ERP extension archetype, occupying a position where industry-specific templates broaden software footprints into monetized analytics services. Accenture PLC represents the systems integration vector, sitting within advisory-led implementation channels that bridge legacy infrastructure and API-native delivery mechanisms. These three entities collectively illustrate how competitive positioning stratifies across deployment architecture, vertical specialization, and service intensity dimensions.
| Leading Market Players |
|---|
| Accenture PLC |
| IBM Corporation |
| SAP SE |
| Oracle Corporation |
| Salesforce, Inc. |
| Google LLC |
| Infosys Limited |
| Cisco Systems, Inc. |
| Microsoft Corporation |
| Others |
Value Network & Pricing Analysis
Guangdong's industrial data exchanges concentrate state-backed manufacturing sensor aggregation capacity, translating upstream platform control into tiered licensing power over financial derivatives pricing downstream. India's DPDP Act compliance engineering costs flow through to subscription premiums, while Vietnamese IoT deployment gaps create pricing asymmetry for first-mover telemetry aggregators.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels within China's provincial data exchanges. Price differentiation rests on consent granularity certification under PIPL and real-time API throughput volume. Cost compression in standard tiers intensifies because South Korean banking regulators mandate on-premise sovereignty configurations that inflate infrastructure overhead. Indonesian retail conglomerates exhibit highest price sensitivity through consumption-metered procurement, while Australian financial institutions demonstrate lowest sensitivity due to embedded SaaS analytics bundling.
Supply Chain Analysis
Foxconn and Wistron hold contract-manufacturing capacity for edge-computing hardware feeding federated analytics deployments across Singapore and Australia. Component sourcing concentrates in Taiwan, South Korea, and Japan for differential privacy chipsets and sensor telemetry modules. Single-source vulnerability runs through TSMC's advanced node production for privacy-preserving computation accelerators. Distribution runs through hyperscaler marketplace integrations and direct enterprise sales channels anchored by IBM and Microsoft field organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across India's DPDP Act, China's PIPL, and Japan's APPI creates structural niche opportunities for compliance-specialized platform vendors. Divergent consent architectures fragment buyer requirements sufficiently to support multiple regional champions rather than consolidated global standards.
For Market Incumbents: Entrench through backward integration into audit-ready data lineage tooling and captive consent management layer development. IBM and Microsoft should expand hybrid cloud sovereignty configurations for South Korean and Australian financial regulators. Threat substitution from open-source federated analytics frameworks demands proprietary differential privacy IP accumulation through targeted R&D allocation. For New Entrants and Emerging Players: Pursue Vietnamese manufacturing data pools in northern industrial zones where equipment telemetry monetization remains underpenetrated. Target Singapore's PDPC portability compliance channel as the most penetrable entry point, leveraging standardized consent-driven transfer protocol gaps left by incumbent platform vendors. Go-to-market execution should anchor on API-first delivery mechanisms with consumption-metered pricing to match Indonesian and Thai procurement patterns. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pure-play data brokerages with consent architecture flexibility across fragmented regulatory zones. Long-term viability hinges on federated analytics infrastructure migration from pilot to production-grade deployment. Acquisition target archetype: regional specialists holding TRAI-aligned subscriber analytics partnerships or SAMR-registered industrial exchange access. Watch for inflection when China's provincial exchanges standardize tiered sensitivity classification protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Consent Architecture Platform Integration | Enables TRAI-regulated carriers to monetize subscriber streams through auditable withdrawal rights. |
| Backward Integration into Edge Hardware | Secures differential privacy chipset supply from Taiwan and South Korean foundry partners. |
| Geographic Expansion into Vietnamese IoT | Captures first-mover equipment telemetry aggregation in northern manufacturing zones. |
| Strategic Partnership with Provincial Exchanges | Unlocks SAMR-registered access to Guangdong and Zhejiang manufacturing sensor derivatives. |
| Acquisition of Federated Analytics Specialist | Accelerates production-grade deployment for Australian financial institution risk modeling. |
Research Methodology
Desk research of regulatory filings from TRAI, SAMR, and PDPC preceded structured interviews with data platform CTOs, privacy engineering leads at telecom operators, and procurement officers at Australian banking consortia. Secondary validation drew from SEC 10-K disclosures of hyperscaler analytics divisions, industrial exchange trading volume reports, and CDSCO-aligned healthcare data governance guidelines. Bottom-up deployment sizing across cloud, on-premise, and hybrid configurations triangulated against top-down market value estimates from subscription revenue aggregation.
Assumptions held regulatory enforcement intensity and cloud infrastructure pricing within observed trajectories across the projection horizon. Segmentation modeling incorporated solution type, deployment architecture, end-user vertical, and technology layer dimensions. CAGRs derived from year-over-year subscription renewal rates and new customer acquisition velocity within Indian telecom and Australian finance verticals. Federated analytics adoption curves and PIPL consent granularity compliance costs served as primary forecast sensitivity inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed exchanges or sudden TRAI regulatory tightening would shift outcomes substantially. Quarterly review of provincial exchange trading protocol updates and DPDP Act enforcement precedent is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Asset Reliability Software Market
Digital Solutions
AI In Packaging Design Market
Digital Solutions
Cheque Scanner Market
Digital Solutions
Virtual Client Computing Market
Digital Solutions
Customer Experience As a Service (Cxaas) Market
Digital Solutions
Global Parking Reservation System Market
Digital Solutions
Passenger Ticket Vending Machine Market
Digital Solutions
Singapore System Integration Market
Digital Solutions
Global Insight As a Service Market
Digital Solutions
Mobile Campaign Management Platform Market
Digital Solutions
US Supply Chain Management Software Market
Digital Solutions
Cloud Service Assurance Market
Digital Solutions
Smart Process Application (SPA) Market
Digital Solutions
Global Continuous Delivery Market
Digital Solutions
Product As a Service Market
Digital Solutions
Load Balancer Market