
 Automation Test Software Market | 2026-2036
Automation Test Software Market Size, Share, and Industry Trends Forecast 2026-2036
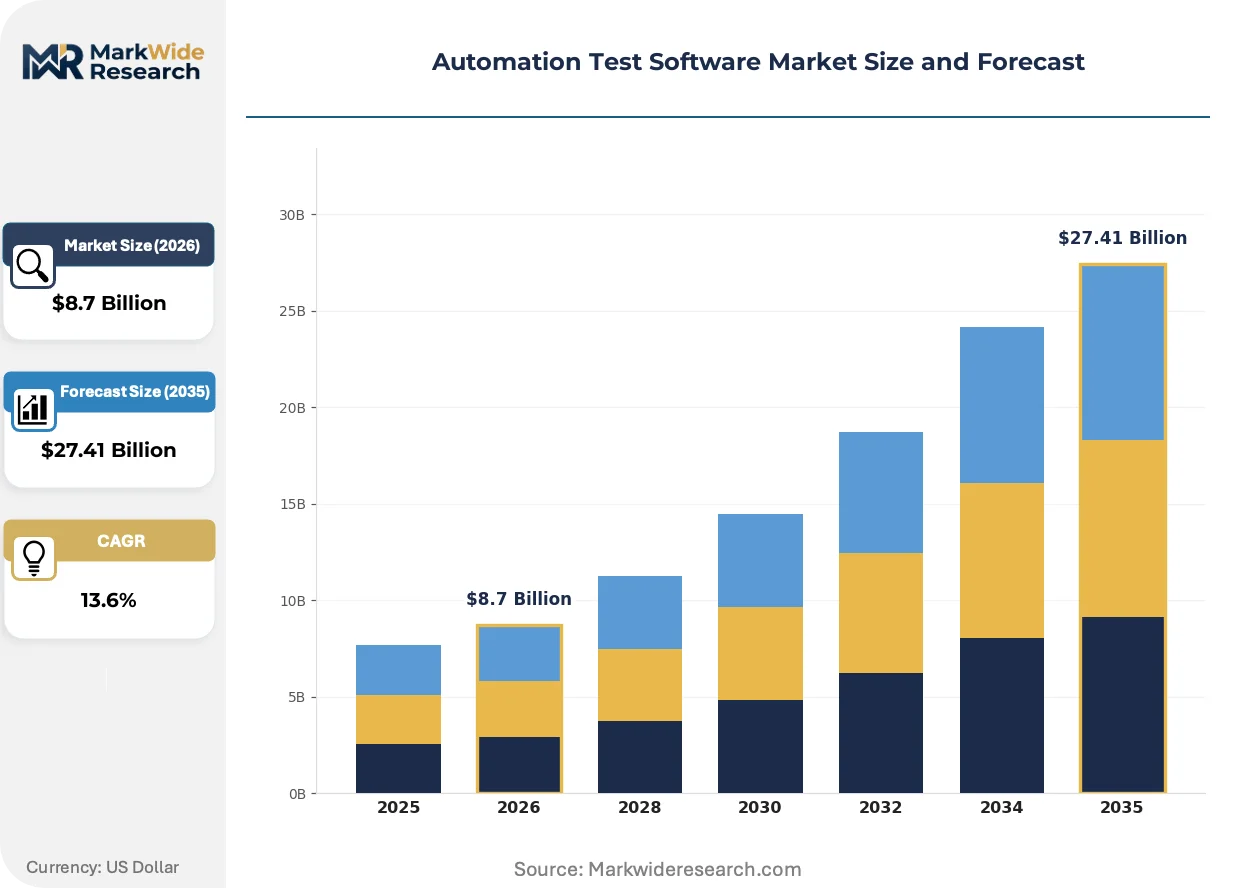
Automation Test Software Market Outlook
EU CSRD disclosure requirements is recalibrating how enterprises validate software supply chains, forcing expanded test coverage across ESG reporting tools. SmartBear Software leverages its API testing heritage to anchor North American enterprise accounts. Cigniti Technologies competes through specialized banking-sector validation frameworks. QualityLogic differentiates via embedded systems testing expertise in automotive-adjacent software.
Automation test software comprises code-driven platforms that execute pre-scripted test cases against applications to detect regressions, performance bottlenecks, and security vulnerabilities without manual intervention. These tools integrate with CI/CD pipelines to validate builds at commit-stage, typically supporting parallel execution across distributed container clusters to compress release cycles. Functional Testing occupies the largest revenue pool as legacy monoliths require exhaustive regression suites during cloud migration. Cloud-Based deployment is expanding fastest where elastic test infrastructure replaces fixed-capacity on-premises labs. SaaS delivery models concentrate margin pools among vendors achieving multi-tenant density at enterprise scale.
FDA 21 CFR Part 11 shapes validation protocols for life-sciences software, mandating audit trails that automation platforms must reproduce under inspection. ETSI cybersecurity standards in Europe and India's CERT-In directives for financial institutions create overlapping compliance burdens that test vendors address through pre-certified template libraries. ISO/IEC 25010 quality frameworks further standardize how organizations benchmark tool selection against maintainability and portability criteria. Stakeholders must weigh whether to consolidate on platforms spanning multiple regulatory regimes or specialize in jurisdiction-specific compliance depth.
Market Dynamics
CI/CD pipeline maturation is compressing test execution windows from hours to minutes, forcing vendors to rebuild architectures around container-native parallelization rather than retrofitting legacy sequential frameworks.
Growth Catalysts
- SEC audit-trail mandates:Financial services firms in the United States are expanding validation budgets to satisfy granular transaction-logging requirements, directly expanding enterprise automation spend.
- API-first development:Microservices proliferation across banking and retail stacks demands continuous contract testing, pulling specialized tooling into standard procurement cycles.
- India:CERT-In directives for financial institutions mandate automated security validation, creating compliance-driven procurement urgency among domestic banks and insurers.
Market Restraints
- Open-source tooling saturation:Selenium and JMeter ecosystems absorb mid-market budgets, compressing commercial vendor pricing power in the sub-$50K annual contract tier.
- Specialized engineering talent scarcity:Test automation architects command 40-60% salary premiums over manual QA roles, inflating implementation costs for complex multi-environment deployments.
- On-premises infrastructure lock-in:German automotive and industrial software vendors face 18-24 month cloud migration cycles, delaying SaaS subscription conversions.
Strategic Opportunities
- Embedded systems validation:Automotive software complexity from ADAS and infotainment stacks creates demand for hardware-in-the-loop test automation currently underserved by generalist platforms.
- EU CSRD alignment:Sustainability reporting tool validation requirements open specialized compliance testing segments as enterprises verify ESG calculation accuracy under audit scrutiny.
- AI-augmented test generation:Machine learning models trained on production traffic patterns are reducing script maintenance overhead, enabling vendors to bundle predictive maintenance into premium tiers.
Industry Challenges
- Fragmented toolchain integration:Enterprises average 12-15 distinct DevOps tools, forcing automation vendors to maintain brittle connector ecosystems that break with each upstream release.
- Cross-browser/device matrix explosion:Mobile OS fragmentation and browser version churn multiply test case counts exponentially, straining execution infrastructure budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automation Test Software Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Functional Testing, Performance Testing, Security Testing, Load Testing Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: IT Companies, Financial Services, Retail, Telecommunications Integration Level: Continuous Integration, Manual Integration, Automated Integration, Third-Party Integration |
| Companies Covered | SmartBear Software, Testlio, ImpactQA, QualityLogic, ThinkSys, Cigniti Technologies, QASource, Abstracta, Wildnet Edge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automation Test Software Market Strategic Shifts
Test execution architectures are pivoting from scheduled batch runs to event-triggered validation, embedding quality gates directly into developer workflows rather than treating testing as a downstream checkpoint.
Self-healing test scripts powered by machine learning are overtaking brittle selector-based automation in enterprise accounts. E-commerce and fintech QA teams at scale deploy these systems to cut maintenance hours by half. The technology is overtaking traditional record-and-playback approaches as the default expectation in RFP evaluations.
ETSI cybersecurity certification requirements for connected devices are mandating automated penetration testing integration into standard release pipelines. European industrial IoT vendors must demonstrate continuous vulnerability scanning to achieve CE marking conformity. Automotive software suppliers in Germany and medical device firms in France are rebuilding validation protocols around these frameworks.
Consumption-based pricing for test execution minutes is displacing traditional seat-license models in mid-market accounts. DevOps teams at SaaS startups prefer granular billing tied to actual CI/CD pipeline usage over fixed annual commitments. This pattern is most visible among Series B-C software companies in Bangalore and Berlin optimizing cash burn against release velocity targets.
Automation Test Software Market Segmentation
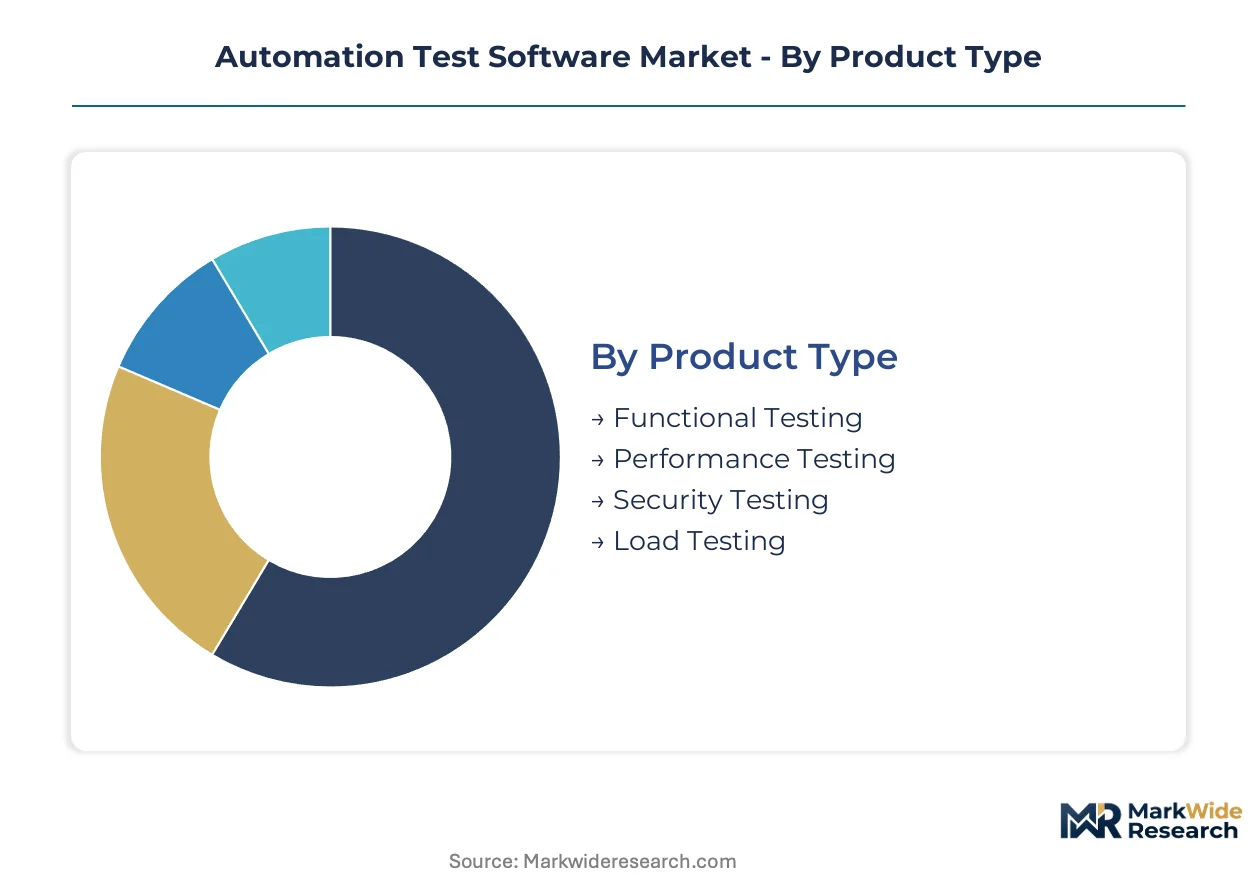
Automation test software segments diverge sharply in infrastructure requirements and compliance burdens. Procurement patterns cluster around deployment flexibility, regulatory exposure, and CI/CD maturity rather than feature checklists alone.
Product Type:
Capital intensity escalates with test environment complexity and data volume throughput. Functional testing demands the largest script libraries and maintenance overhead. Security testing requires specialized hardware for penetration simulation and vulnerability scanning.
- Functional Testing:Validates application behavior against specified requirements through scripted user journey simulation. Financial services firms in the United States consume disproportionate capacity here as SEC audit-trail mandates force exhaustive regression coverage across transaction systems.
- Performance Testing:Measures response times, throughput, and stability under defined load conditions. E-commerce platforms in India deploy these tools most aggressively as CERT-In directives and traffic spikes from festival-season sales create dual pressure points.
- Security Testing:Automated vulnerability scanning and penetration testing against OWASP and NIST frameworks. Banking sector procurement dominates.
- Load Testing:Stress validation for concurrent user simulation and infrastructure elasticity. SaaS vendors prioritize this segment.
Most installed capacity flows through Functional Testing. Expansion is steepest in Security Testing.
Deployment Model:
Revenue concentration tracks enterprise cloud migration velocity and data residency requirements. SaaS delivery captures the highest margin pools where multi-tenant density achieves scale. On-premises deployments retain pricing power in regulated sectors with audit-trail sovereignty demands.
- On-Premises:Dedicated infrastructure within enterprise data centers with full operational control. German automotive software suppliers maintain this model to satisfy KBA traceability requirements and 18-24 month cloud migration cycles.
- Cloud-Based:Elastic test infrastructure provisioned over public cloud with usage-based scaling. DevOps teams at Series B-C SaaS companies in Bangalore and Berlin prefer this for cash burn optimization against release velocity targets.
- Hybrid:Split workloads across on-premises and cloud environments with orchestration layers. Enterprises in transition phases adopt this architecture.
- SaaS:Fully managed multi-tenant platforms with subscription pricing. Mid-market accounts favor consumption-based billing tied to actual CI/CD pipeline usage.
Cloud-Based deployments command the steepest expansion trajectory. SaaS retains the highest margin concentration.
End User:
Procurement authority and budget scale vary dramatically across verticals. Financial services outspend on compliance depth. IT companies prioritize toolchain breadth and API coverage.
- IT Companies:Software vendors and system integrators requiring cross-platform validation frameworks. Microservices proliferation drives API-first testing procurement.
- Financial Services:Banks, insurers, and payment processors with granular audit requirements. SEC mandates in the United States and CERT-In directives in India create overlapping compliance procurement urgency.
- Retail:Omnichannel commerce platforms validating checkout flows and inventory systems. Seasonal load patterns drive cyclical demand spikes.
- Telecommunications:Network equipment and customer-facing application validation. 5G service launches expand test matrices.
Financial Services deploys the deepest test coverage per application. IT Companies expand tool counts fastest.
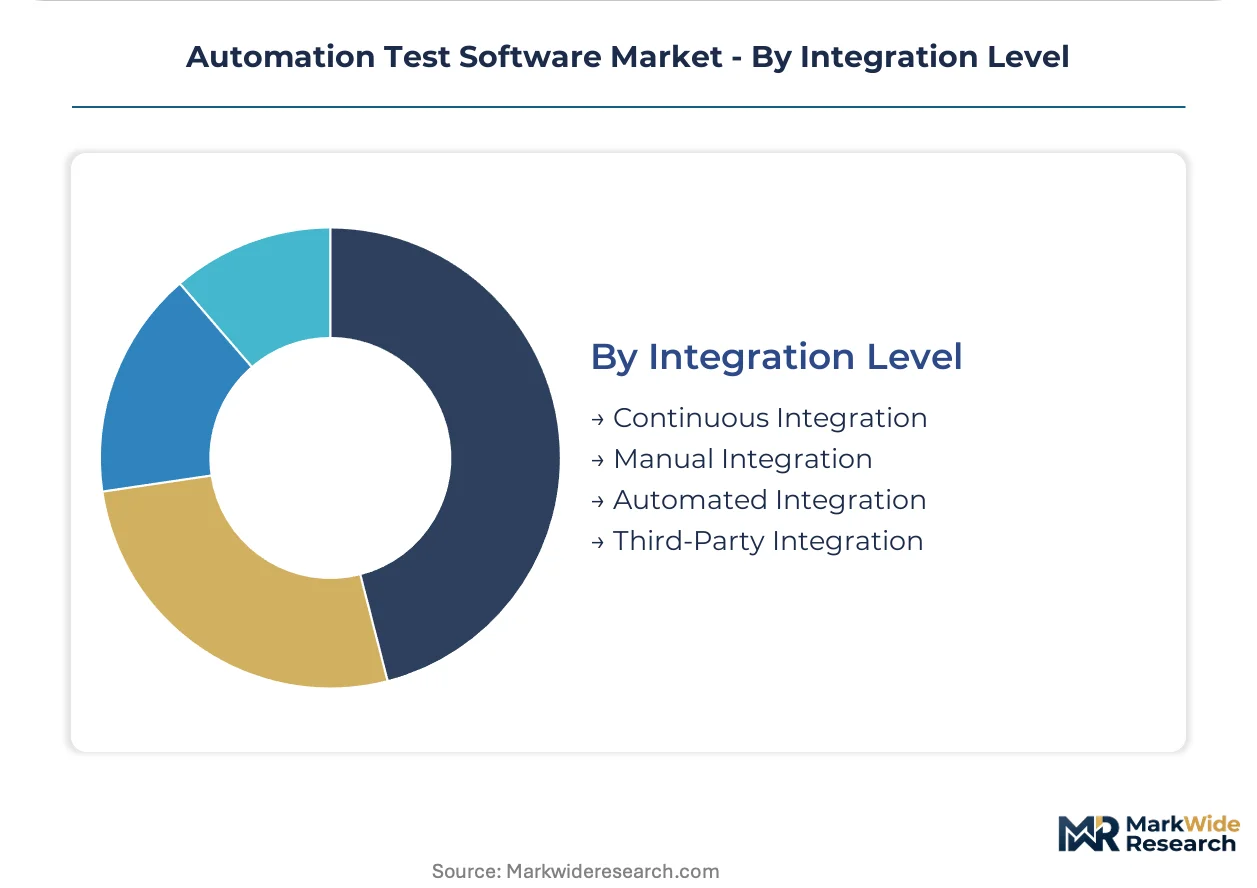
Integration Level:
Technical sophistication and implementation cost scale with pipeline embedding depth. Continuous integration demands the most architecturally complex deployments. Manual integration retains footholds in legacy maintenance contexts.
- Continuous Integration:Automated test execution triggered at every code commit with immediate feedback loops. CI/CD pipeline maturation compresses execution windows from hours to minutes, forcing container-native parallelization.
- Manual Integration:Human-triggered test runs outside automated pipelines. Legacy monolith maintenance and waterfall holdouts retain this model.
- Automated Integration:Scheduled batch execution without full CI/CD embedding. Mid-market teams use this as intermediate maturity step.
- Third-Party Integration:Connector frameworks linking test platforms to external DevOps tools. Fragmented toolchain ecosystems averaging 12-15 distinct tools drive connector maintenance burdens.
Continuous Integration absorbs the majority of new architectural investment. Third-Party Integration faces the steepest connector complexity escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automation test software industry traces its commercial roots to Silicon Valley's quality engineering practices of the 1990s, where early commercial tools emerged from the demands of shrink-wrapped software distribution. From this foundation, development clusters now span four continents with distinct regulatory and procurement characteristics.
United States
Financial services firms in New York and San Francisco deploy the deepest test automation stacks globally, driven by SEC audit-trail mandates requiring granular transaction-logging validation. The FDA's 21 CFR Part 11 framework shapes life-sciences software protocols, mandating reproducible audit trails that automation platforms must satisfy under inspection. Boston's biotech corridor and Austin's SaaS cluster anchor dual demand centers for compliance-heavy and velocity-driven tooling respectively.
Germany
Automotive software suppliers in Stuttgart and Munich maintain 18-24 month cloud migration cycles, delaying SaaS conversions while sustaining premium pricing for on-premises validation suites. The KBA's traceability requirements for vehicle software enforce hardware-in-the-loop testing protocols that generalist platforms struggle to satisfy. Berlin's DevOps startups and Frankfurt's banking infrastructure create divergent procurement patterns within a single national market.
India
CERT-In directives for financial institutions mandate automated security validation, creating compliance-driven procurement urgency among Mumbai's domestic banks and Bangalore's insurers. The RBI's cybersecurity framework overlaps with SEBI's market infrastructure requirements, forcing dual-certification test strategies. Hyderabad's IT services corridor and Pune's manufacturing-software cluster represent contrasting demand profiles—outsourced validation versus embedded systems testing.
United Kingdom
London's fintech density generates API-first testing demand as microservices architectures proliferate across payment and lending stacks. The FCA's operational resilience requirements impose stress-testing mandates that expand automation budgets for critical third-party software. Manchester's emerging tech hub and Cambridge's semiconductor design cluster add specialized validation needs for IoT firmware and chip verification workflows.
Japan
Tokyo's enterprise software vendors prioritize quality gates over release velocity, sustaining demand for exhaustive regression suites in mainframe modernization contexts. METI's cybersecurity guidelines for critical infrastructure create procurement frameworks that favor domestic vendor relationships. Osaka's industrial automation sector and Fukuoka's startup cluster illustrate the tension between legacy system maintenance and cloud-native transformation timelines.
Automation Test Software Market Competitive Environment
Premium-margin players sit above commodity-margin players across compliance certification depth, with tiered pricing separating validated life-sciences tooling from unverified generalist suites. The vendor base clusters around three strategic archetypes: API-testing specialists leveraging microservices proliferation, embedded systems validators serving automotive and medical device verticals, and managed services providers capturing outsourced QA functions from mid-market enterprises. M&A activity concentrates on acquiring compliance template libraries for jurisdiction-specific regulatory regimes, while strategic partnerships with CI/CD platform vendors dominate distribution channel expansion.
Within the specialized validation tier, SmartBear Software and Cigniti Technologies exemplify divergent geographic and sectoral positioning—one anchoring North American enterprise accounts through API heritage, the other competing via banking-sector frameworks in Asian markets. QualityLogic occupies a distinct position in embedded systems testing, reflecting automotive-adjacent software complexity that generalist platforms cannot address. These three entities represent the archetype fragmentation—tool-centric versus service-centric versus vertical-specialist—that structures competitive dynamics across procurement evaluation criteria.
| Leading Market Players |
|---|
| SmartBear Software |
| Testlio |
| ImpactQA |
| QualityLogic |
| ThinkSys |
| Cigniti Technologies |
| QASource |
| Abstracta |
| Wildnet Edge |
| Others |
Value Chain & Pricing Dynamics
Container-native parallelization is compressing test execution economics while redistributing supply power toward hyperscaler-backed infrastructure providers. SaaS delivery models capture margin premiums where multi-tenant density achieves enterprise scale, yet open-source tooling saturation in the sub-$50K contract tier exerts downward pressure on commercial vendor pricing.
Pricing Analysis
Consumption-based billing for test execution minutes is displacing fixed seat-license models across mid-market accounts. Pricing stratifies across premium compliance-certified tiers, standard multi-tenant SaaS, and economy open-source alternatives, with certification depth against FDA 21 CFR Part 11 and ETSI cybersecurity standards commanding substantial premiums. Cost compression in the standard tier is intensifying because Selenium and JMeter ecosystems absorb budget-conscious procurement. DevOps teams at Series B-C SaaS companies exhibit highest price sensitivity, while life-sciences enterprises under FDA inspection show lowest.
Supply Chain Analysis
Cloud compute infrastructure rests on hyperscaler data center networks concentrated in the United States, Germany, and India. Test automation vendors draw from container orchestration platforms, machine learning inference engines, and specialized hardware for hardware-in-the-loop simulation. Single-source vulnerability in GPU availability for AI-augmented test generation creates procurement risk. Distribution runs through CI/CD platform marketplaces and direct enterprise sales channels with implementation service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automation test software procurement functions as a geographic-arbitrage play, with German automotive suppliers paying premium on-premises pricing while Bangalore SaaS startups optimize cash burn through consumption-based cloud models.
For Market Incumbents: Anticipate margin compression from open-source tooling ecosystems by deepening compliance certification moats against FDA and ETSI frameworks. Invest in AI-augmented test generation capabilities to differentiate from Selenium-based alternatives. Vertical integration into hardware-in-the-loop testing addresses automotive embedded systems demand that generalist platforms cannot satisfy. For New Entrants and Emerging Players: Self-healing test scripts powered by machine learning offer a technology-first wedge into e-commerce and fintech QA teams at scale. Embedded systems validation for ADAS and infotainment stacks represents the most penetrable white-space segment. Go-to-market through AWS Marketplace and Azure DevOps extensions captures procurement workflows already embedded in target accounts. For Investors and Strategic Acquirers: Valuations sit cheapest among managed services providers with banking-sector validation frameworks and outsourced QA functions. Long-term viability favors vendors spanning multiple regulatory regimes rather than jurisdiction-specific specialists. Watch CERT-In enforcement intensity in India as inflection indicator for compliance-driven procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Template Library Acquisition | Accelerates FDA 21 CFR Part 11 certification for life-sciences software validation. |
| CI/CD Platform Partnership | Embeds quality gates directly into GitLab and Jenkins developer workflows. |
| AI-Augmented Test Generation Launch | Reduces script maintenance overhead for e-commerce and fintech QA teams. |
| Hardware-in-the-Loop Capability Buildout | Addresses KBA traceability requirements for German automotive software suppliers. |
| Consumption-Based Pricing Introduction | Aligns revenue with actual Bangalore and Berlin startup CI/CD pipeline usage. |
Study Parameters
Coverage spans the United States, Germany, India, and the United Kingdom, with primary inputs from each market. The research combines interviews with CTOs, IT procurement officers, platform engineers, and channel partners with secondary validation against SEC filings, hyperscaler capex disclosures, FDA 510(k) databases, and ETSI certification registries. Bottom-up vendor revenue triangulation against top-down enterprise automation spend estimates ensures cross-verification.
Granularity-level modeling captures deployment mode, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs derive from regression analysis of historical procurement velocity against regulatory mandate timelines. Industry-specific forecast inputs include CERT-In directive implementation schedules and German automotive cloud migration cycle durations.
The model holds under steady regulatory enforcement intensity; deviation in FDA inspection frequency or ETSI cybersecurity certification expansion would shift growth trajectories. Forecasts reflect assumptions about CI/CD pipeline maturation velocity and open-source tooling saturation ceilings. A small set of named triggers—SEC audit-trail mandate expansion, KBA traceability requirement updates, and RBI cybersecurity framework revisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
India Software Services Export Market
Software & Services
Trading Software Market
Software & Services
On-Call Scheduling Software Market
Software & Services
Low Code Development Platform Market
Software & Services
Relational Database Management System Market
Software & Services
Neurodiverse Workforce Productivity Tools Market
Software & Services
Global Digital Experience Management Software Market
Software & Services
Point Cloud Processing Software Market
Software & Services
Global Student Information System Market
Software & Services
Global Ipad POS Software Market
Software & Services
Global Data Integration and Integrity Software Market
Software & Services
Online Paint Editor App Market
Software & Services
North America Automotive Software Market
Software & Services
North America Telecom Expense Management Services Software Market
Software & Services
HR Saas Market
Software & Services
Manufacturing Quoting and Estimating Software Market