
 AI Sales Assistant Software Market | 2026-2036
AI Sales Assistant Software Market Size, Share, and Industry Trends Forecast 2026-2036
AI Sales Assistant Software Market Analysis
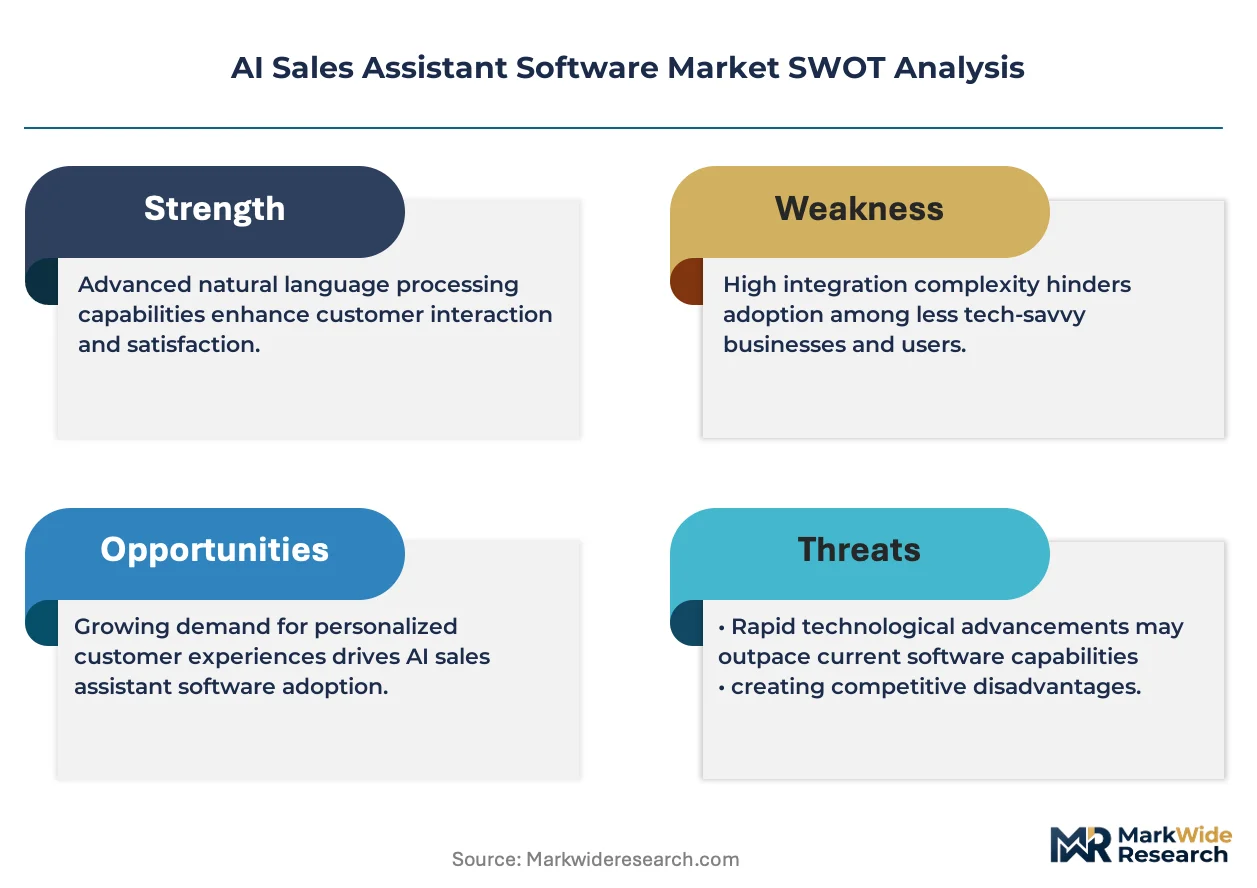
Platform licensing revenue is narrowing as vendors bundle predictive analytics into broader CRM contracts. Gong leverages conversation intelligence to anchor enterprise accounts with multi-year subscriptions. Salesforce Einstein sustains differentiation through native integration within the broader cloud ecosystem. Apollo.io competes on data breadth, combining prospecting automation with intent signals across buyer journeys.
AI sales assistant software encompasses machine learning applications that analyze sales conversations, forecast deal outcomes, and automate routine outreach tasks through natural language processing and predictive modeling. These systems typically process audio transcripts, email threads, and CRM activity logs to generate next-best-action recommendations for revenue teams. Chatbots and predictive analytics tools currently command the deepest margin pools, while automation platforms show the fastest expansion as organizations consolidate point solutions. Cloud-based deployment dominates new adoption, though hybrid models retain traction in regulated industries requiring local data residency controls.
The EU AI Act and GDPR impose transparency obligations on automated decision-making in customer-facing sales tools, compelling vendors to document algorithmic logic and consent flows. The SEC and state-level privacy statutes in California and Virginia add layered compliance costs for vendors serving financial services and healthcare verticals. Stakeholders must monitor evolving algorithmic accountability requirements across multiple jurisdictions to anticipate product architecture investments and go-to-market constraints.
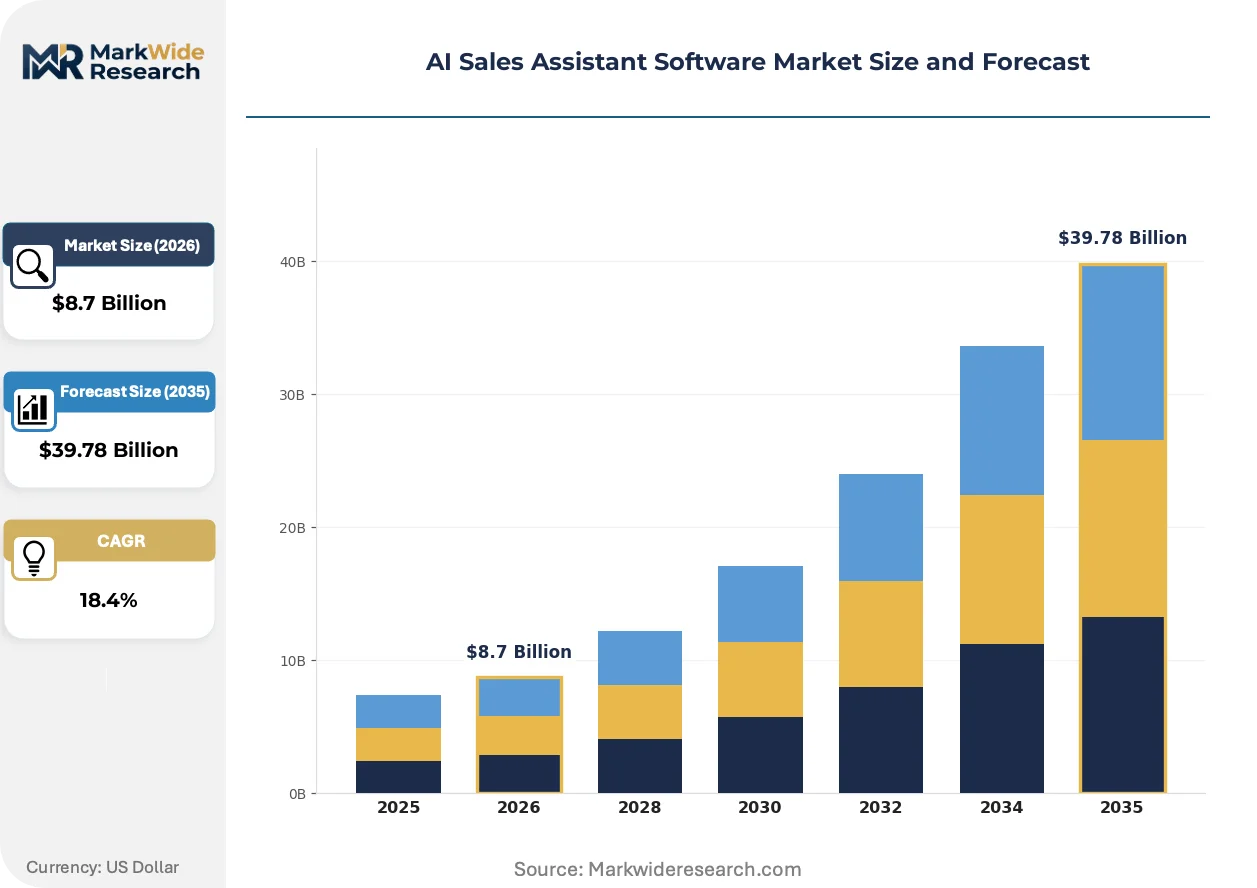
Market Dynamics
Conversational AI is virtualizing the sales stack, collapsing point solutions into unified platforms that process voice, text, and CRM signals through single inference pipelines.
Growth Catalysts
- GDPR Article 22:European mandates for explainable automated decisions compel vendors to build auditable conversation analytics, accelerating procurement of compliant platforms by financial services firms in Germany and France.
- Natural language processing:Transformer architectures now parse multi-turn sales dialogues with contextual memory, enabling real-time coaching prompts that shorten enterprise sales cycles.
- Mid-market SaaS vendors:Cloud-native deployment preferences among United States and United Kingdom software sellers concentrate demand for API-first assistant tools that integrate with existing revenue operations stacks.
Market Restraints
- GPU compute costs:Inference expenses for large language models underlying conversation intelligence compress gross margins, particularly for vendors serving price-sensitive mid-market accounts.
- Data residency requirements:German and Swiss banking regulators mandate local processing of customer interaction data, fragmenting cloud infrastructure and raising operational complexity for unified platform vendors.
- Human-in-the-loop mandates:The EU AI Act's prohibition on fully automated high-risk decisions in B2B credit and insurance sales forces hybrid architecture investments that slow pure automation roadmaps.
Strategic Opportunities
- Japan METI AI governance framework:Early alignment with emerging East Asian algorithmic accountability standards positions vendors for public-sector and automotive sales tool contracts in Tokyo and Osaka industrial corridors.
- Voice synthesis + emotion detection:Converging generative audio and sentiment analysis enables synthetic sales coaching that replicates top performer techniques at scale for distributed teams.
- Embedded finance verticals:Banking-as-a-Service platforms in the United Kingdom and Singapore create demand for AI assistants that navigate complex regulatory disclosure requirements during embedded product sales.
Industry Challenges
- Prompt engineering talent scarcity:Revenue operations teams lack specialists capable of tuning foundation models for domain-specific sales workflows, forcing vendors to absorb implementation costs.
- CRM integration complexity:Legacy Salesforce and Microsoft Dynamics instances with custom object architectures require bespoke connector development, extending deployment timelines and straining professional services capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Sales Assistant Software Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chatbots, Predictive Analytics Tools, Automation Platforms, CRM Integrations End User: SMEs, Large Enterprises, Sales Teams, Customer Support Departments Deployment: Cloud-Based, On-Premises, Hybrid Models, SaaS Solutions Integration Level: Full Integration, Partial Integration, Standalone Systems, API-Based Solutions |
| Companies Covered | Gong, Artisan, Nooks, HubSpot, Salesforce Einstein, Zeliq, Apollo.io, Orum, ZoomInfo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Sales Assistant Software Market Emerging Trajectories
Foundation models are compressing the competitive moat between established conversation intelligence platforms and emerging challengers, forcing differentiation through vertical data depth rather than base model capability.
Multimodal inference engines are virtualizing the traditional separation between call recording, email analysis, and CRM enrichment. These systems ingest audio streams, thread metadata, and calendar signals through unified neural architectures. Enterprise revenue operations teams in the United States and United Kingdom are deploying these tools at departmental scale within six-month procurement cycles. The technology is virtualizing point-solution vendors into feature categories within broader platform contracts.
The EU AI Act's risk-tier classification system imposes documentation burdens on customer-facing automation. Vendors must maintain technical files proving human oversight mechanisms for high-risk sales applications involving credit decisions or insurance underwriting. German automotive and French banking procurement committees now require algorithmic impact assessments as standard RFP components, favoring vendors with pre-built compliance documentation.
Subscription fatigue among software buyers is compressing willingness-to-pay for standalone sales tools. Procurement committees increasingly demand AI capabilities bundled within existing CRM or revenue intelligence contracts rather than separate line items. This pattern is most visible among Series B and C SaaS vendors in San Francisco and London, where finance teams mandate vendor consolidation to reduce administrative overhead and security review burden.
AI Sales Assistant Software Market Segmentation
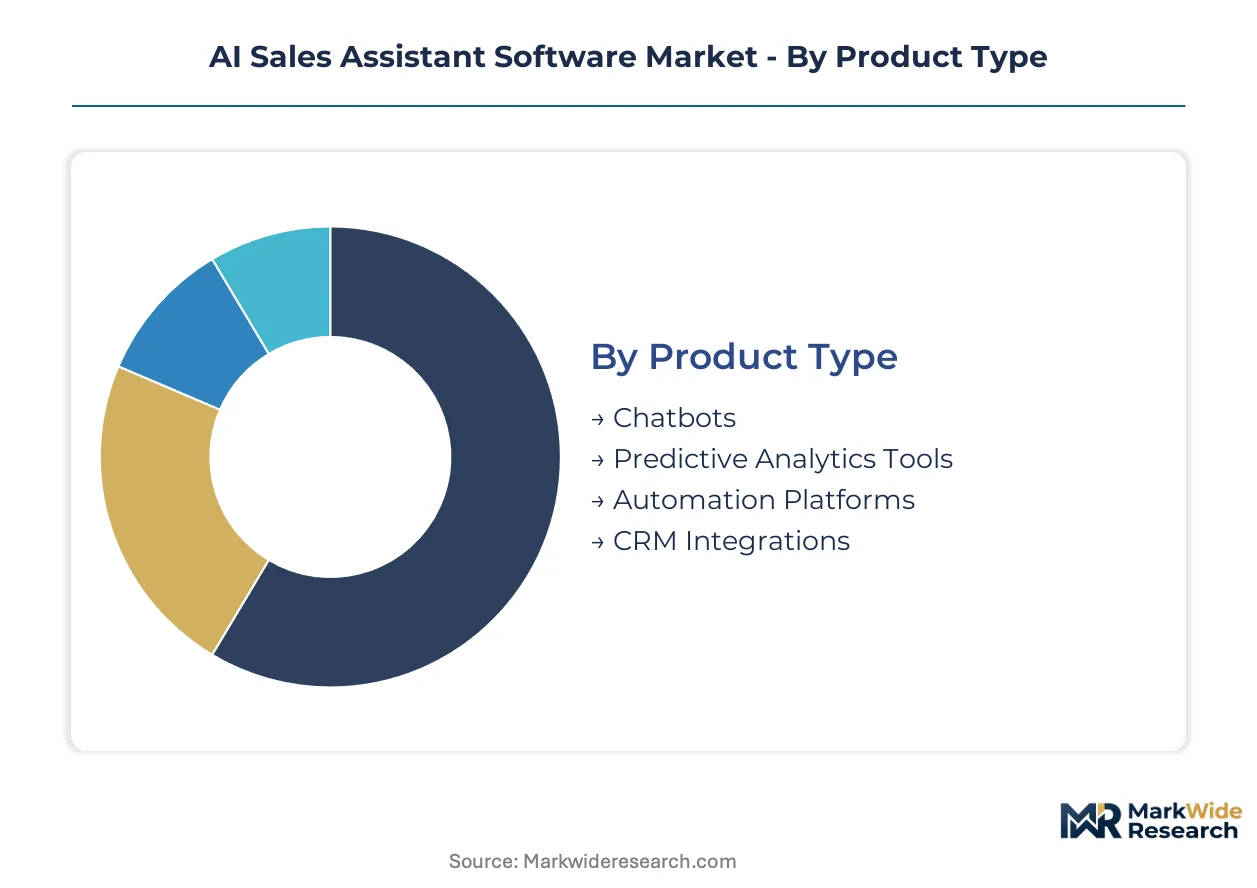
Segmentation in AI sales assistant software reveals how vendor economics fragment across deployment complexity and buyer sophistication. Product architecture choices directly determine margin structure and renewal rates.
Product Type:
Cost tier determines vendor profitability and competitive moat durability in this category.
- Chatbots:Natural language interfaces handle qualification and scheduling through scripted and generative response flows. Demand concentrates in mid-market SaaS vendors across the United States and United Kingdom, driven by subscription fatigue forcing consolidation into bundled CRM contracts.
- Predictive Analytics Tools:Machine learning models score pipeline health and forecast close probabilities from historical CRM data. Financial services firms in Germany and France prioritize these for GDPR Article 22 audit trails.
- Automation Platforms:Workflow engines orchestrate multi-channel outreach sequences.
- CRM Integrations:Embedded modules extending existing customer data infrastructure.
Chatbots hold installed capacity. Automation platforms are rotating up the share rankings.
End User:
Customer type shapes implementation complexity and pricing power for vendors.
- SMEs:Resource-constrained organizations adopting API-first tools with minimal professional services. Cloud-native deployment preferences in the United States and United Kingdom concentrate demand here, constrained by GPU compute costs compressing vendor margins.
- Large Enterprises:Multi-divisional buyers requiring custom object architecture support. German automotive and French banking procurement committees now mandate algorithmic impact assessments, favoring vendors with pre-built EU AI Act documentation.
- Sales Teams:Frontline revenue operators seeking real-time coaching prompts.
- Customer Support Departments:Post-sale retention and expansion workflows.
Large enterprises anchor vendor revenue. SMEs are climbing the fastest as self-serve adoption accelerates.
Deployment:
Volume concentration follows data residency requirements and regulatory jurisdiction.
- Cloud-Based:Fully managed infrastructure with elastic scaling. New adoption dominates in the United States and United Kingdom, driven by six-month departmental procurement cycles among Series B and C SaaS vendors.
- Hybrid Models:Split processing with local inference and cloud training. German and Swiss banking regulators mandate these architectures for customer interaction data, fragmenting infrastructure and raising operational complexity.
- On-Premises:Self-hosted installations in controlled environments.
- SaaS Solutions:Multi-tenant subscription delivery with shared infrastructure.
Cloud-based deployments hold installed capacity. Hybrid models are gaining share fastest in regulated verticals.
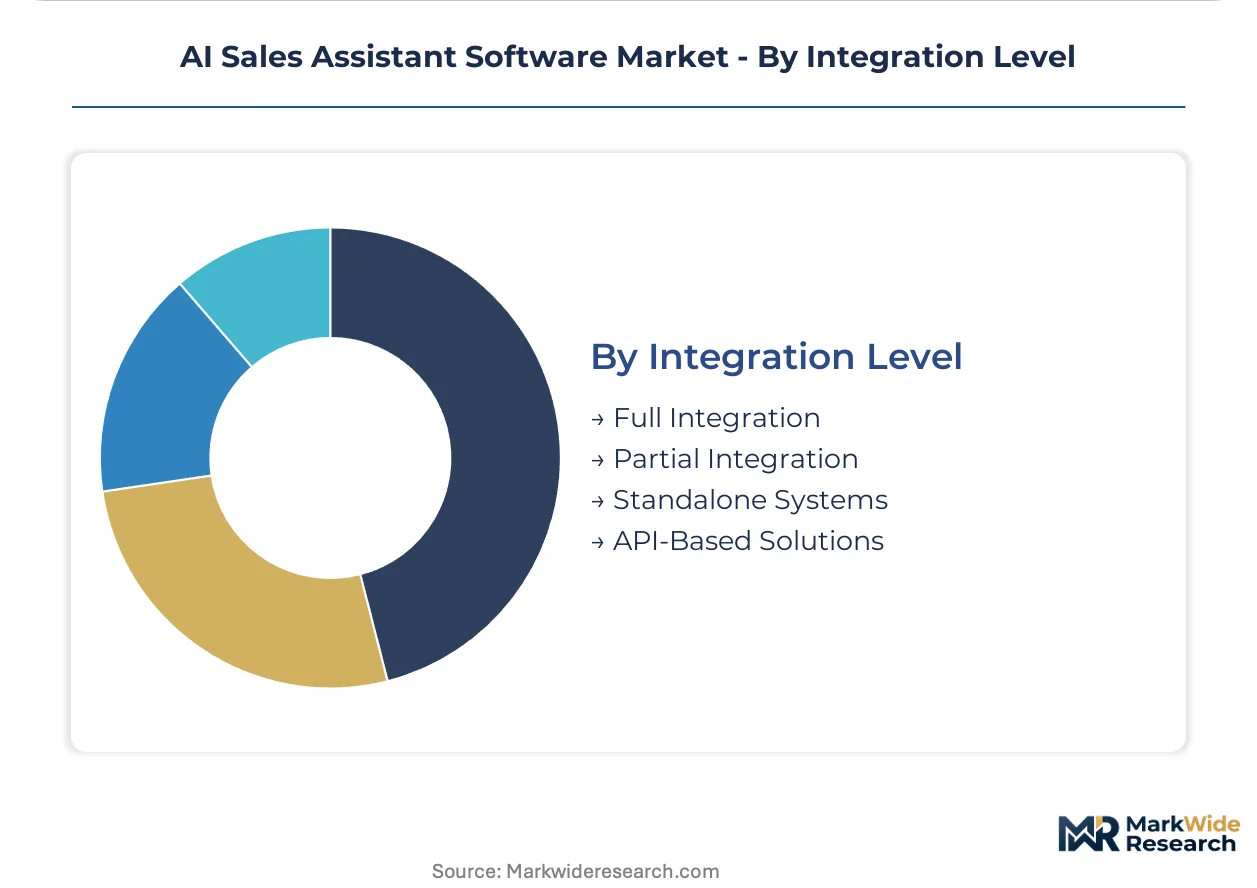
Integration Level:
Application depth determines switching costs and platform stickiness.
- Full Integration:Native embedding within Salesforce, Microsoft Dynamics, or HubSpot with bidirectional sync. Demand concentrates among enterprise revenue operations teams, constrained by legacy custom object architectures requiring bespoke connector development.
- API-Based Solutions:Modular connectivity through REST and GraphQL endpoints. Mid-market buyers in San Francisco and London prefer these for vendor consolidation mandates reducing security review burden.
- Partial Integration:Limited data exchange with select systems.
- Standalone Systems:Independent platforms requiring manual data export.
Full integration holds installed capacity. API-based solutions are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States and United Kingdom demonstrate the highest price elasticity, while German and French financial services firms absorb premium pricing for compliance-ready platforms. Mid-market SaaS vendors in San Francisco and London consolidate vendors aggressively. Enterprise procurement committees in Frankfurt and Paris mandate algorithmic documentation regardless of cost.
United States
Series B and C SaaS vendors in San Francisco and New York Metro drive six-month departmental procurement cycles for cloud-native deployment. The SEC imposes disclosure requirements on AI-driven sales tools serving financial services clients. Austin and Boston clusters concentrate API-first assistant adoption among revenue operations teams seeking minimal professional services overhead.
United Kingdom
Banking-as-a-Service platforms in London generate demand for assistants navigating embedded finance regulatory disclosures. The Financial Conduct Authority scrutinizes automated decision-making in customer-facing sales applications. Manchester and Edinburgh fintech corridors expand procurement of voice synthesis tools for distributed sales coaching.
Germany
Automotive and industrial equipment manufacturers in Stuttgart and Munich prioritize predictive analytics with auditable GDPR Article 22 trails. The KBA and BaFin mandate local data residency for customer interaction processing. Frankfurt banking procurement committees require pre-built EU AI Act algorithmic impact assessments as standard RFP components.
France
Insurance underwriters in Paris and Lyon absorb premium pricing for platforms with human-in-the-loop architectures complying with high-risk automation prohibitions. The CNIL enforces transparency obligations on automated credit decision tools. Sophia Antipolis technology cluster experiments with emotion detection integration for synthetic sales coaching deployment.
Japan
Automotive OEMs in Tokyo and Nagoya industrial corridors evaluate AI governance alignment under the METI framework for public-sector sales tool contracts. The PMDA and JIS standards bodies influence procurement specifications for customer-facing automation. Osaka manufacturing sales teams pilot multimodal inference engines processing voice, text, and CRM signals through unified pipelines.
AI Sales Assistant Software Market Vendor Landscape
Capability concentration sits with specialized conversation intelligence vendors; scale advantage sits with cloud ecosystem incumbents bundling predictive modules into existing CRM contracts. The market structures around three tiers: standalone point-solution specialists, platform-integrated feature providers, and native ecosystem embeds. Strategic moves center on M&A absorption of workflow automation capabilities and vertical data partnerships deepening sector-specific training corpora.
Within the standalone specialist tier, Gong and Apollo.io occupy positions anchored on conversation intelligence and data breadth respectively. Salesforce Einstein exemplifies the native ecosystem embed archetype, leveraging cloud infrastructure integration to reduce procurement friction. These three represent the dominant competitive vectors: conversation analytics depth, prospecting data scale, and platform distribution leverage.
| Leading Market Players |
|---|
| Gong |
| Artisan |
| Nooks |
| HubSpot |
| Salesforce Einstein |
| Zeliq |
| Apollo.io |
| Orum |
| ZoomInfo |
| Others |
Supply Flow & Price Mechanics
San Francisco's concentration of cloud infrastructure providers shapes downstream pricing power for AI sales assistant vendors serving Series B and C SaaS buyers. GPU compute clusters in this region anchor inference cost structures, while procurement committees in London and Frankfurt absorb premium pricing for compliance-ready deployments.
Pricing Analysis
Extended service contracts and professional services tiers drive lifetime value more than initial platform licensing. Three-tier pricing structure across premium, standard, and economy levels segments by integration depth and compliance documentation. Pricing pressure stems from GPU inference costs compressing margins for mid-market vendors. SMEs in the United States and United Kingdom demonstrate highest price sensitivity, while German automotive and French banking buyers accept premium positioning for auditable platforms.
Supply Chain Analysis
Upstream feedstock for AI sales assistant platforms centers on NVIDIA GPU clusters concentrated in the United States, Taiwan semiconductor fabrication for inference accelerators, and Ireland-based data center infrastructure serving European deployments. Foundation model training draws from cloud compute contracts with hyperscalers. Single-source vulnerability in advanced GPU supply creates procurement risk for vendors scaling multimodal inference engines. Distribution runs through direct enterprise sales teams and API-first self-serve channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as subscription fatigue forces vendor consolidation, creating niches for specialized compliance-first platforms and vertical-specific training data providers.
For Market Incumbents: Insulate core enterprise accounts by embedding conversation intelligence deeper into CRM workflows, absorbing workflow automation capabilities through targeted capability acquisitions. Foundation model commoditization threatens differentiation moats anchored on base model performance. Vertical data partnerships in automotive and financial services deepen sector-specific training corpora as a defensive lever. For New Entrants and Emerging Players: Mid-market SaaS vendors in Manchester and Edinburgh fintech corridors represent the most penetrable entry point, underserved by incumbent professional services capacity. API-first deployment with minimal implementation overhead addresses procurement mandates for vendor consolidation. Target voice synthesis and emotion detection integration as a differentiated go-to-market angle for distributed sales coaching. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because platform licensing revenue narrowing forces absorption of point-solution specialists into broader revenue operations contracts. Acquisition target archetype: standalone conversation intelligence vendors with pre-built EU AI Act documentation and German automotive customer concentration. Signal to watch: algorithmic impact assessment requirements spreading beyond banking into insurance and embedded finance verticals.| Strategic Initiative | Industry Significance |
|---|---|
| Vertical Data Partnership | Deepens automotive and financial services training corpora for sector-specific model performance. |
| Compliance Documentation Investment | Pre-builds EU AI Act algorithmic impact assessments for German and French procurement committees. |
| Workflow Automation Acquisition | Absorbs point-solution capabilities before platform licensing revenue narrows further. |
| Hybrid Deployment Architecture | Addresses German and Swiss banking data residency mandates fragmenting cloud infrastructure. |
| Voice Synthesis Integration | Enables synthetic sales coaching replication of top performer techniques at scale. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across revenue operations leaders, CRM integration specialists, compliance officers at financial services firms, and procurement directors at mid-market SaaS vendors. Secondary validation drew from SEC filings of publicly traded software vendors, hyperscaler capex disclosures, EU regulatory documentation repositories, and trade data on cloud infrastructure deployment. Bottom-up sizing of vendor licensing revenue combined with top-down triangulation against CRM software market estimates.
Calibration against historical adoption curves for conversational AI and revenue intelligence platforms anchored the analytical framework. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs were derived from slope analysis of comparable software category maturation patterns, incorporating GPU cost trajectory assumptions and compliance burden expansion across the analysis window.
Practitioners should monitor EU AI Act implementation timelines and GPU supply availability for early signals requiring forecast revision. Cross-checking against hyperscaler earnings call commentary on enterprise AI workload growth is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Data Recovery Software Market
Software & Services
Association Management Software Market
Software & Services
Construction Enterprise Resource Planning (ERP) Software Market
Software & Services
ID Photo Software Market
Software & Services
Predictive Dialer Software Market
Software & Services
Global Driving School Software Market
Software & Services
Asia-Pacific Digital Signage Software Market
Software & Services
Electromagnetic Simulation Software Market
Software & Services
Global Software Resellers Market
Software & Services
Mobile Application Development Platform (MADP) Market
Software & Services
Global Product Management Software Market
Software & Services
Account-Based Advertising Software Market
Software & Services
Balance Sheet Management Software Market
Software & Services
Global Application Management Services Market
Software & Services
Pay-Per-Click (PPC) Software Market
Software & Services
Asia Pacific Human Capital Management Software (HCM) Market