
 Online Whiteboard Software Market | 2026-2036
Online Whiteboard Software Market Size, Share, and Industry Trends Forecast 2026-2036
Online Whiteboard Software Market Analytics
North American cloud infrastructure expansion is reshaping how online whiteboard software reaches enterprise buyers. Miro leverages deep integration partnerships with productivity suites to anchor its position among design-led organizations. Lucidspark sustains competitive pressure through specialized diagramming capabilities that extend its utility beyond basic whiteboarding. Microsoft Whiteboard dominates within existing Office 365 ecosystems, controlling access to the largest installed base of corporate users.
Online whiteboard software delivers real-time collaborative canvases with vector-based rendering, multi-user concurrency support, and API-driven integration architectures, serving primarily to replace physical meeting room infrastructure with persistent digital workspaces. Cloud-based deployment leads the market due to zero-install accessibility and automatic feature updates, while on-premises alternatives retain traction in defense and regulated finance segments where data residency requirements constrain SaaS adoption. The education end-user segment shows structural momentum as institutions standardize on platform-agnostic tools that support both synchronous instruction and asynchronous student projects.
GDPR compliance obligations in Europe, HIPAA considerations for US healthcare deployments, and China's Personal Information Protection Law collectively shape product architecture decisions around data localization and encryption standards. The EU AI Act's emerging transparency requirements for automated decision-support tools will likely extend to AI-powered whiteboard features such as smart clustering and content generation. Stakeholders must monitor evolving cross-border data transfer rulings that could fragment platform availability and force region-specific hosting commitments.
Market Dynamics
Cloud migration mandates under the EU AI Act and comparable digital sovereignty frameworks are forcing platform providers to rearchitect data residency controls, reshaping procurement patterns across financial services and enterprise technology sectors.
Growth Catalysts
- Hybrid work infrastructure mandates:Financial services firms in the United States are expanding persistent digital workspace deployments to replace physical meeting room investments.
- GDPR-driven data localization:European enterprises require region-specific hosting commitments, accelerating demand for compliant SaaS architectures with encryption standards meeting EU requirements.
- API-driven integration architectures:Vector-based rendering engines with multi-user concurrency support are enabling real-time collaboration across distributed product teams.
Market Restraints
- Defense sector data residency requirements:On-premises alternatives retain traction where China's Personal Information Protection Law and comparable national frameworks constrain SaaS adoption.
- HIPAA compliance friction:US healthcare deployments face extended certification timelines for cloud-based whiteboard tools handling protected health information.
- Enterprise switching costs:Deep integration with productivity suites creates vendor lock-in that slows platform migration decisions.
Strategic Opportunities
- Education sector standardization:Institutions are adopting platform-agnostic tools supporting synchronous instruction and asynchronous student projects.
- AI-powered feature expansion:Smart clustering and automated content generation capabilities align with emerging EU AI Act transparency requirements for decision-support tools.
- Cross-border data transfer fragmentation:Evolving rulings on international data flows create openings for region-specific hosting providers.
Industry Challenges
- Legacy system integration complexity:Enterprise buyers require seamless connectivity with existing document management and video conferencing infrastructure.
- Certification timeline compression:Rapidly evolving regulatory frameworks in Europe and Asia-Pacific demand continuous compliance engineering investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Whiteboard Software Market |
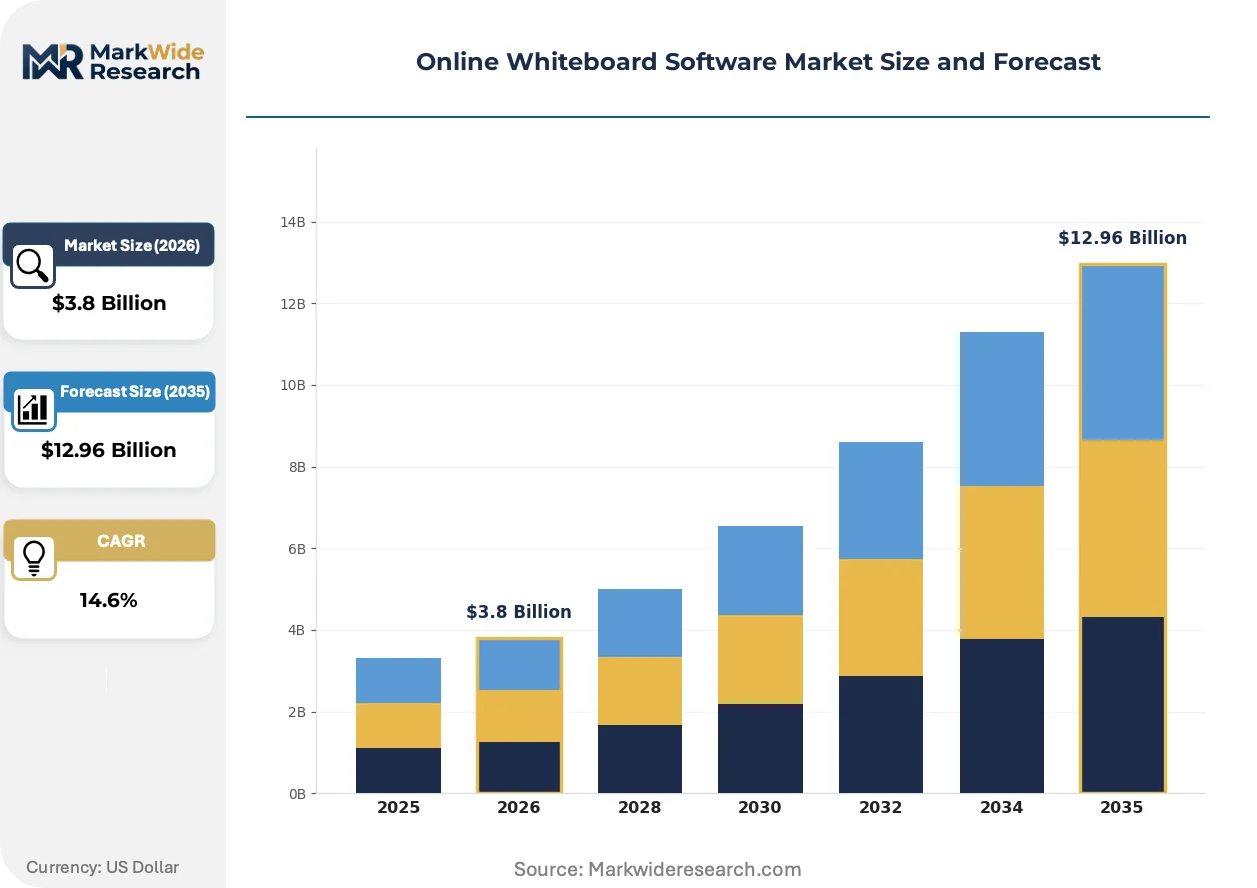
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: Education Institutions, Corporates, Freelancers, Nonprofits Use Case: Brainstorming, Teaching, Project Management, Remote Collaboration Feature: Real-Time Editing, Templates, Integrations, File Sharing |
| Companies Covered | Lucidspark, Creately, Miro, Conceptboard, Canva Whiteboards, FigJam, Mural, Kosmik, Microsoft Whiteboard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Whiteboard Software Market Evolving Landscape
Real-time collaborative canvases are evolving from simple drawing surfaces into intelligent workspace platforms, with artificial intelligence and regulatory compliance emerging as the primary axes of differentiation.
Vector-based rendering engines with infinite canvas architectures are digitizing physical whiteboard workflows for distributed engineering teams. Automotive and aerospace manufacturers are adopting these tools for design review sessions previously conducted in dedicated visualization facilities. The technology is digitizing synchronous collaboration patterns that once required co-located talent.
The EU AI Act's transparency requirements for automated decision-support tools are extending to smart clustering algorithms and generative content features within whiteboard platforms. Product architects must now document training data provenance and inference logic for AI-powered suggestions. European financial services buyers are prioritizing vendors with auditable AI pipelines over functionality-rich alternatives.
Enterprise buyers are consolidating vendor relationships around integrated productivity suites rather than best-of-breed point solutions. Procurement teams favor platforms with pre-built connectors to existing document repositories and identity management systems. This pattern is most visible in United States technology sector deployments where IT standardization mandates reduce vendor sprawl.
Online Whiteboard Software Market Segmentation
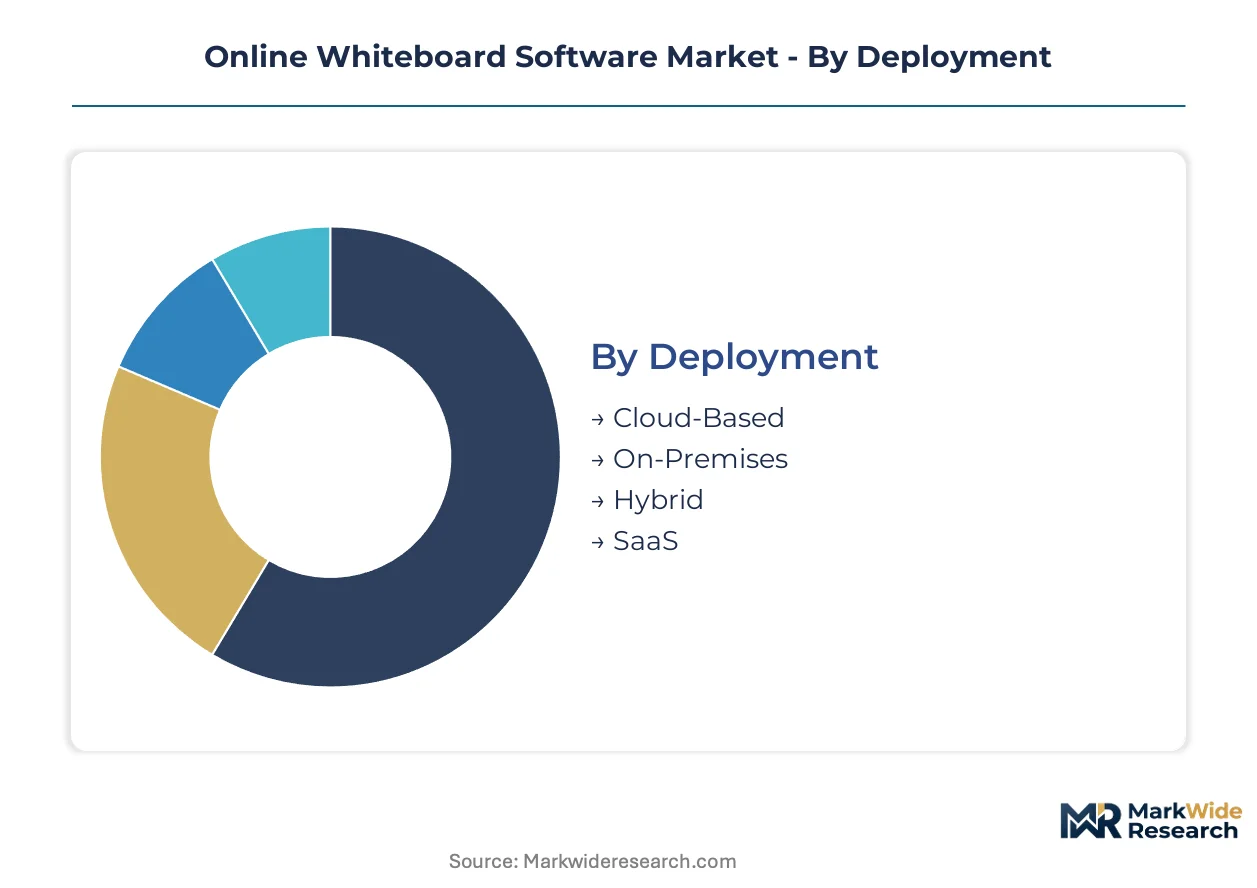
Segmentation in online whiteboard software reveals divergent procurement cycles across deployment modes and end-user categories. Enterprise buyers prioritize compliance-ready architectures with extended evaluation timelines, while education and freelance segments favor rapid-deployment SaaS models with minimal IT overhead.
Deployment:
Cloud-based solutions turn over fastest with monthly subscription renewals, while on-premises deployments cycle through 3-5 year capital planning horizons.
- Cloud-Based:Zero-install accessibility with automatic feature updates eliminates IT provisioning delays. Financial services firms in the United States favor this model for hybrid work infrastructure, though GDPR-driven data localization requirements in Europe are forcing providers to establish EU-specific hosting regions.
- On-Premises:Self-hosted architectures with dedicated server infrastructure meet defense sector data residency mandates. China's Personal Information Protection Law and comparable national frameworks constrain SaaS adoption here, preserving demand for air-gapped deployments in regulated finance and government segments.
- Hybrid:Split architectures allowing sensitive data on-premises while collaboration layers operate in cloud. This configuration addresses HIPAA compliance friction for US healthcare deployments.
- SaaS:Multi-tenant subscription models with API-driven integration architectures dominate procurement for distributed product teams seeking rapid scalability.
Cloud-based deployments dominate installed base. On-premises is where expansion concentrates among regulated sectors.
End User:
Corporate procurement operates on annual enterprise licensing cycles, while education institutions refresh tools on academic calendar timelines and freelancers adopt continuously.
- Education Institutions:Platform-agnostic tools supporting synchronous instruction and asynchronous student projects are standardizing across K-12 and higher education. European universities prioritize GDPR-compliant architectures with auditable data processing records.
- Corporates:Deep integration requirements with productivity suites and identity management systems drive vendor consolidation. Technology sector IT standardization mandates in the United States reduce vendor sprawl through pre-approved platform lists.
- Freelancers:Individual practitioners and small agencies favor low-cost tiers with essential collaboration features, often migrating between tools based on project-specific client requirements.
- Nonprofits:Grant-funded organizations select discounted or donated licenses, with procurement decisions influenced by existing technology partnerships and volunteer technical capacity.
Corporates dominate installed base. Education institutions are climbing the fastest.
Use Case:
Remote collaboration features refresh quarterly with competitive pressure, while project management integrations evolve on annual roadmap cycles tied to partner ecosystem updates.
- Brainstorming:Unstructured ideation sessions with sticky-note clustering and freeform drawing. Design-led organizations in the United States anchor procurement here, prioritizing infinite canvas architectures and real-time cursor tracking.
- Teaching:Structured instructional workflows with student pacing controls and assessment integration. Institutions across Germany and France are deploying these for hybrid classroom models under national digital education initiatives.
- Project Management:Timeline visualization and task dependency mapping extending whiteboard utility into execution tracking. This segment gains traction where teams seek to reduce tool fragmentation.
- Remote Collaboration:Video-integrated sessions replacing physical meeting room infrastructure. Persistent digital workspaces here are displacing dedicated visualization facilities in automotive and aerospace manufacturing.
Remote collaboration dominates installed base. Teaching is gaining share fastest.
Feature:
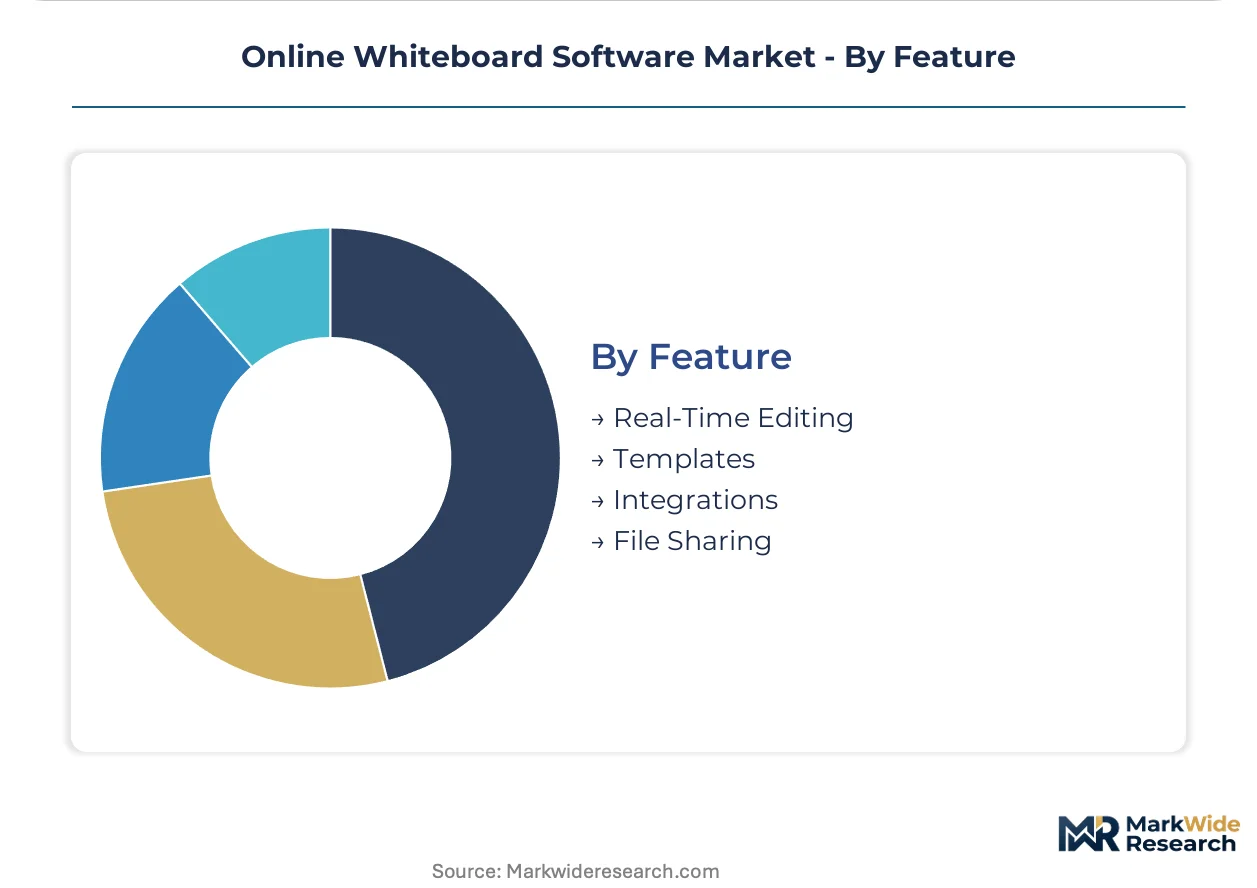
Integration roadmaps refresh on 6-12 month partner cycles, while template libraries expand continuously and real-time editing engines require substantial R&D investment with slower release cadences.
- Real-Time Editing:Vector-based rendering engines with multi-user concurrency support and conflict resolution algorithms. Distributed engineering teams in Japan and South Korea prioritize low-latency synchronization for design review sessions.
- Templates:Pre-built frameworks for agile ceremonies, design sprints, and strategic planning. This feature accelerates adoption among organizations with standardized methodologies.
- Integrations:API connectors to document repositories, video conferencing, and project management platforms. European financial services buyers under EU AI Act transparency requirements prioritize vendors with documented inference logic for AI-powered suggestions.
- File Sharing:Embedded document handling with version control and permission inheritance. This capability reduces context switching for teams managing complex project artifacts.
Real-time editing dominates installed base. Integrations show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure investment concentrates heavily in the United States, where enterprise SaaS procurement drives platform development. European data localization mandates and Asia-Pacific manufacturing digitization create divergent demand patterns across major economies.
United States
Financial services firms in New York and San Francisco are replacing physical meeting rooms with persistent digital workspaces under hybrid work mandates. HIPAA compliance requirements extend certification timelines for healthcare deployments handling protected health information. Austin and Seattle technology clusters anchor venture funding for collaboration startups targeting enterprise buyers.
Germany
Automotive manufacturers in Stuttgart and Munich are digitizing design review sessions previously conducted in dedicated visualization facilities. The EU AI Act's transparency requirements for automated decision-support tools are reshaping vendor selection criteria for AI-powered whiteboard features. Frankfurt's financial services sector prioritizes GDPR-compliant architectures with auditable data processing records.
United Kingdom
London's professional services firms are consolidating vendor relationships around integrated productivity suites to reduce IT complexity. CSRD disclosure obligations are extending to digital collaboration tool procurement decisions for ESG reporting compliance. Cambridge and Manchester education clusters are standardizing on platform-agnostic tools for hybrid classroom models.
Japan
Engineering teams in Tokyo and Osaka prioritize low-latency synchronization for distributed design review sessions. METI's digital transformation incentives are accelerating cloud migration for manufacturing enterprises previously reliant on on-premises infrastructure. Nagoya's automotive supply base is adopting vector-based rendering engines for supplier collaboration networks.
India
Bengaluru and Hyderabad IT services exporters are deploying whiteboard platforms for client delivery teams across multiple time zones. The country's data protection framework is pushing providers toward local hosting commitments for government and banking contracts. Mumbai financial institutions are evaluating compliant SaaS architectures for regulatory reporting workflows.
Online Whiteboard Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower functional scopes. The vendor base spans three distinct tiers: productivity suite incumbents with pre-installed distribution, independent collaboration platforms with design-led positioning, and diagramming specialists extending into whiteboarding adjacencies. Strategic differentiation concentrates on API ecosystem breadth and AI-powered feature pipelines. M&A activity targets workflow automation capabilities; partnership strategies emphasize pre-built connectors to document repositories and identity management systems.
Among independent collaboration platforms, Miro and Mural exemplify the design-led archetype with infinite canvas architectures. Microsoft Whiteboard anchors the productivity suite tier through Office 365 ecosystem integration. Lucidspark occupies a position within the diagramming specialist tier, extending specialized visualization capabilities into broader whiteboarding use cases. These three represent the dominant competitive anchors across strategic positioning vectors.
| Leading Market Players |
|---|
| Lucidspark |
| Creately |
| Miro |
| Conceptboard |
| Canva Whiteboards |
| FigJam |
| Mural |
| Kosmik |
| Microsoft Whiteboard |
| Others |
Value Network & Pricing Analysis
Single-source dependency on hyperscaler cloud infrastructure dictates both pricing tier spreads and supply chain shape in online whiteboard software. GDPR-driven data localization requirements and EU AI Act compliance mandates force providers to establish region-specific hosting commitments, fragmenting procurement patterns and compressing margins for non-compliant architectures.
Pricing Analysis
EU AI Act transparency requirements dictate the pricing tier structure across the European market. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade compliance bundles from mid-market SaaS tiers and individual freelancer licenses. Certification investment for HIPAA and GDPR architectures drives premium tier pricing in United States healthcare and European financial services segments. Cost compression in the freelancer tier intensifies because of low switching costs and abundant substitute platforms. Education institutions exhibit highest price sensitivity due to grant-funded procurement cycles, while defense sector buyers show lowest sensitivity given air-gapped deployment mandates.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk assessment for on-premises hardware components serving defense and regulated finance segments. Cloud infrastructure draws from hyperscaler data centers concentrated in United States, Ireland, and Singapore, with compute and storage resources resting on semiconductor supply from Taiwan and South Korea. Single-source vulnerability in AI training data pipelines creates concentration risk for smart clustering and generative content features. Distribution runs through direct enterprise sales teams for large accounts and self-service digital channels for mid-market and individual subscribers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Online whiteboard software represents a service-attach opportunity where API integration layers and compliance consulting expand faster than core subscription revenue. Recurring revenue from managed data residency and audit documentation services outpaces new license growth in European financial services procurement.
For Market Incumbents: Build switching-cost moats through deep productivity suite integration and identity management system embedding. Defensive consolidation moves should prioritize acquiring workflow automation specialists and regional hosting providers to address EU AI Act data localization mandates. Threat from Microsoft's Office 365 ecosystem integration requires counter-investment in design-led differentiation and infinite canvas performance optimization. Channel control through pre-built connector marketplaces serves as the critical lever for vendor lock-in. For New Entrants and Emerging Players: Build out specialized compliance architectures for HIPAA-constrained United States healthcare deployments and air-gapped defense sector requirements. White-space targets concentrate in hybrid deployment configurations addressing data residency fragmentation. The most penetrable segment lies in mid-sized European financial services firms seeking auditable AI pipelines under EU transparency requirements. Go-to-market execution should anchor on partnership with regional system integrators possessing existing security clearance relationships. For Investors and Strategic Acquirers: EU AI Act implementation timelines reshape the acquisition landscape toward compliance-engineering capabilities and region-specific hosting infrastructure. Long-term viability frames around platform consolidation into integrated productivity suites with AI-powered feature differentiation sustaining independent positioning. Acquisition target archetype centers on diagramming specialists with established enterprise relationships and API ecosystem breadth. Signal to watch involves cross-border data transfer rulings that fragment platform availability and force hosting commitment investments.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep Office 365 embedding captures United States enterprise procurement under IT standardization mandates. |
| Compliance Architecture Investment | EU-specific GDPR hosting regions unlock Frankfurt financial services procurement previously blocked by data residency. |
| AI Feature Pipeline Expansion | Auditable smart clustering algorithms meet EU AI Act transparency requirements for automated decision-support tools. |
| Acquisition of Specialist Firm | Diagramming platform integration extends utility into project management and reduces customer tool fragmentation. |
| Geographic Expansion | India local hosting commitments address RBI data protection requirements for Mumbai banking contracts. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists across financial services, technology, and education sectors; and secondary validation drawing from SEC filings, hyperscaler capex disclosures, App Annie usage data, and EU regulatory documentation. Bottom-up segmentation modeling triangulated against top-down market sizing from cloud infrastructure investment tracking and enterprise SaaS procurement surveys.
Forecast inputs considered deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern across the projection horizon. CAGRs derived from historical growth rate analysis adjusted for regulatory inflection points and technology substitution curves. AI-powered feature penetration rates and compliance-driven procurement delays served as software-specific forecast modifiers.
Practitioners should monitor EU AI Act enforcement actions, cross-border data transfer rulings, and hyperscaler regional expansion announcements for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Cloud-Based Call Center Software Market
Software & Services
Global Home Inspection Software Market
Software & Services
Category Management Software Market
Software & Services
Global Business Software Market
Software & Services
Banking Team Collaboration Software Market
Software & Services
Tenant Billing System Market
Software & Services
Talent Management Software Market
Software & Services
Japan IT Services Market
Software & Services
Global Online Form Builder Software Market
Software & Services
Global Affiliate Software Market
Software & Services
BFSI Software Market
Software & Services
Metal Fabrication Software Market
Software & Services
Federal Government Software Market
Software & Services
Global Cloud Based Collaboration Software Market
Software & Services
Content Marketing Software Market
Software & Services
Global Vendor Management Software Market