
 Reinforcement Learning Market | 2026-2036
Reinforcement Learning Market Size, Share, and Industry Trends Forecast 2026-2036
Reinforcement Learning Market Insights
The gap between research-grade reinforcement learning and production deployment is narrowing as enterprises demand real-time decision systems. Google LLC leverages its TensorFlow ecosystem to anchor cloud-based RL training pipelines for autonomous systems. NVIDIA Corporation sustains hardware-software co-design advantages through GPU-accelerated simulation environments. Microsoft competes by integrating RL modules across Azure AI services for enterprise orchestration.
Reinforcement learning denotes a machine learning paradigm where an agent learns optimal behavioral policies through trial-and-error interaction with an environment, maximizing cumulative reward signals via deep neural network function approximators. Industrial applications span robotic manipulation, dynamic pricing engines, and network traffic optimization where sequential decision-making under uncertainty delivers measurable efficiency gains. Cloud-Based deployment leads structural adoption as hyperscalers absorb computational burdens of policy gradient training. Robotics application segments attract the fastest investment velocity, driven by simulation-to-reality transfer demands in manufacturing and logistics. Financial Services end users concentrate margin pools in algorithmic trading and risk-adjusted portfolio optimization.
The EU AI Act imposes conformity assessment obligations on high-risk autonomous systems, compelling RL vendors to document training data provenance and reward function design. The FDA exercises oversight through premarket review pathways for RL-driven diagnostic and therapeutic devices, while the SEC scrutinizes RL deployment in automated trading for market manipulation risks. NHTSA guidelines for autonomous vehicle validation increasingly reference scenario-based RL testing protocols. Stakeholders must weigh regulatory compliance investments against the latency advantages of opaque deep RL policies in time-critical applications.
Market Dynamics
Simulation-to-reality transfer protocols are compressing the deployment timeline for RL-trained robotic systems, forcing vendors to restructure validation pipelines around synthetic data generation rather than physical prototyping cycles.
Growth Catalysts
- EU AI Act Conformity Pathways:Mandatory documentation requirements for high-risk autonomous systems are creating certified vendor ecosystems that accelerate enterprise procurement confidence.
- GPU Cluster Proliferation:Hyperscaler capital expenditures on distributed training infrastructure are reducing policy gradient computation costs for mid-market robotics developers.
- Defense Contractor Integration:Pentagon procurement programs for autonomous unmanned systems are establishing reference architectures that cascade into commercial logistics and manufacturing applications.
Market Restraints
- Reward Function Design Bottleneck:Sparse human feedback integration remains technically unresolved, limiting deployment in safety-critical medical and automotive environments.
- Silicon Supply Concentration:Advanced GPU and TPU availability depends on Taiwan Semiconductor Manufacturing capacity allocation priorities.
- FDA Premarket Review Friction:RL-driven diagnostic devices face extended validation timelines due to non-deterministic policy behavior under edge-case inputs.
Strategic Opportunities
- India Manufacturing Automation:PLI scheme incentives for electronics and automotive assembly are creating first-mover advantages for RL-based visual servoing vendors.
- Neuromorphic Hardware Convergence:Integration of spiking neural networks with conventional deep RL is enabling sub-watt edge inference for battery-constrained drones.
- Scenario-Based Testing Mandates:NHTSA guidelines for autonomous vehicle validation are institutionalizing synthetic environment procurement as a standard line item.
Industry Challenges
- Sim-to-Real Transfer Talent Scarcity:Domain randomization and domain adaptation expertise remains concentrated within elite research labs and select robotics startups.
- Legacy PLC Integration Complexity:Brownfield manufacturing facilities require protocol translation layers that introduce latency incompatible with real-time RL control loops.
- Opaque Policy Auditing:Deep neural network function approximators resist post-hoc explanation, complicating incident investigation and liability assignment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reinforcement Learning Market |
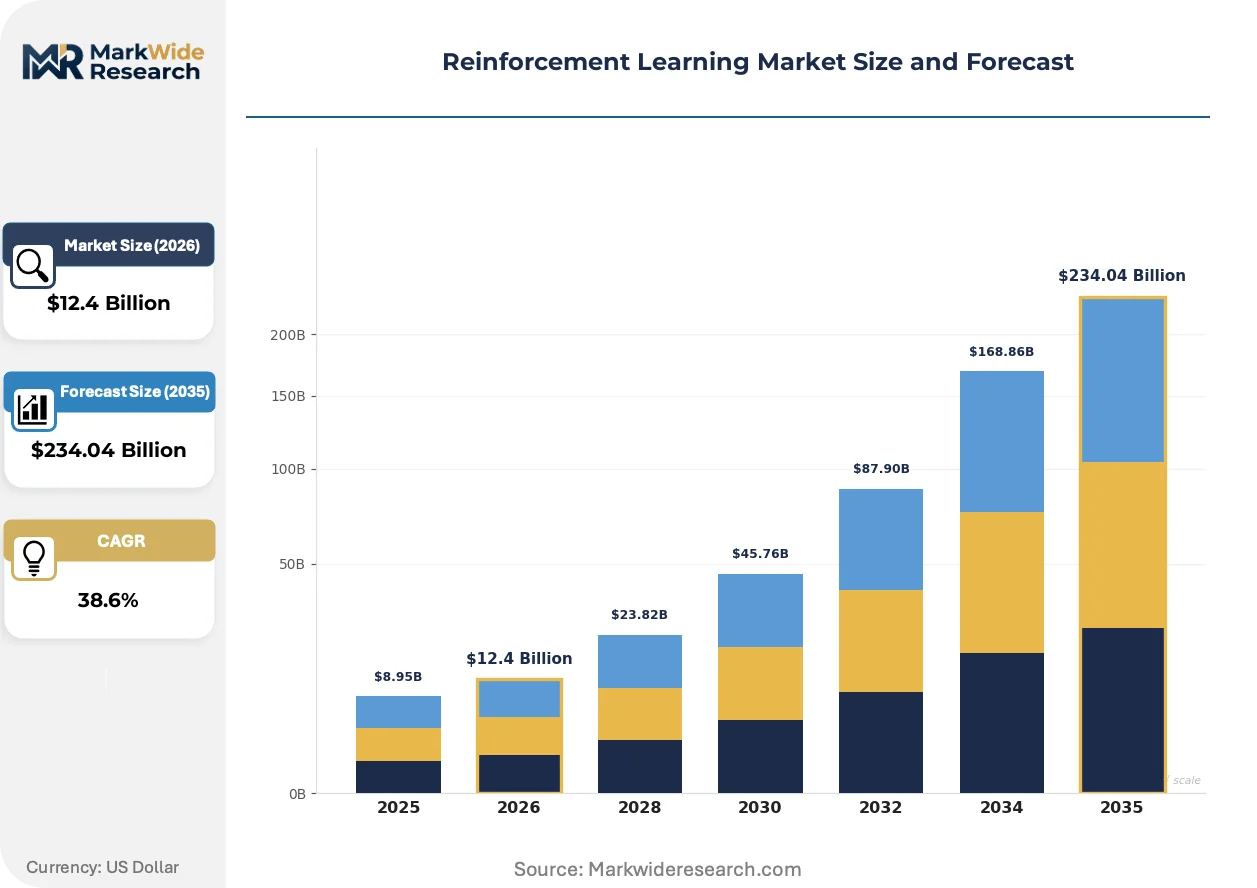
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $234.04 Billion |
| CAGR (2026 – 2036) | 38.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User: Healthcare, Automotive OEMs, Retailers, Financial Services Application: Game Development, Robotics, Virtual Assistants, Supply Chain Optimization Deployment: Cloud-Based, On-Premises, Hybrid Cloud, Edge Computing Solution: Frameworks, Software Tools, APIs, Integrated Systems |
| Companies Covered | Google LLC, Microsoft, Amazon Web Services, Inc., IBM Corporation, NVIDIA Corporation, Intel Corporation, Alibaba Group Holding Ltd., SAP SE, OpenAI Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reinforcement Learning Market Trends and Innovations
Foundation model architectures trained on massive offline datasets are displacing task-specific RL implementations, compressing the engineering effort required for new deployment domains.
Differentiable physics engines are collapsing the cost structure of policy training by enabling gradient computation through simulation steps. Automotive Tier 1 suppliers are adopting NVIDIA Isaac Gym and similar frameworks to train manipulation policies entirely in silicon before hardware commissioning. This compression eliminates months of physical testing and reduces capital requirements for new robotic product lines.
The EU AI Act's risk classification framework is mandating conformity assessment procedures for high-risk autonomous systems. Industrial robotics vendors must now document training data provenance and reward function specifications to access European markets. German automotive manufacturers are responding by establishing internal algorithmic auditing functions that pre-validate RL policies before regulatory submission.
Defense procurement offices are consolidating vendor relationships around integrated platform providers rather than component specialists. This concentration is displacing point-solution robotics vendors who lack end-to-system integration capabilities. The shift is most visible in United States Department of Defense programs, where prime contractors now bundle RL-based navigation with hardware, sensors, and sustainment in single-award contracts.
Reinforcement Learning Market Segmentation
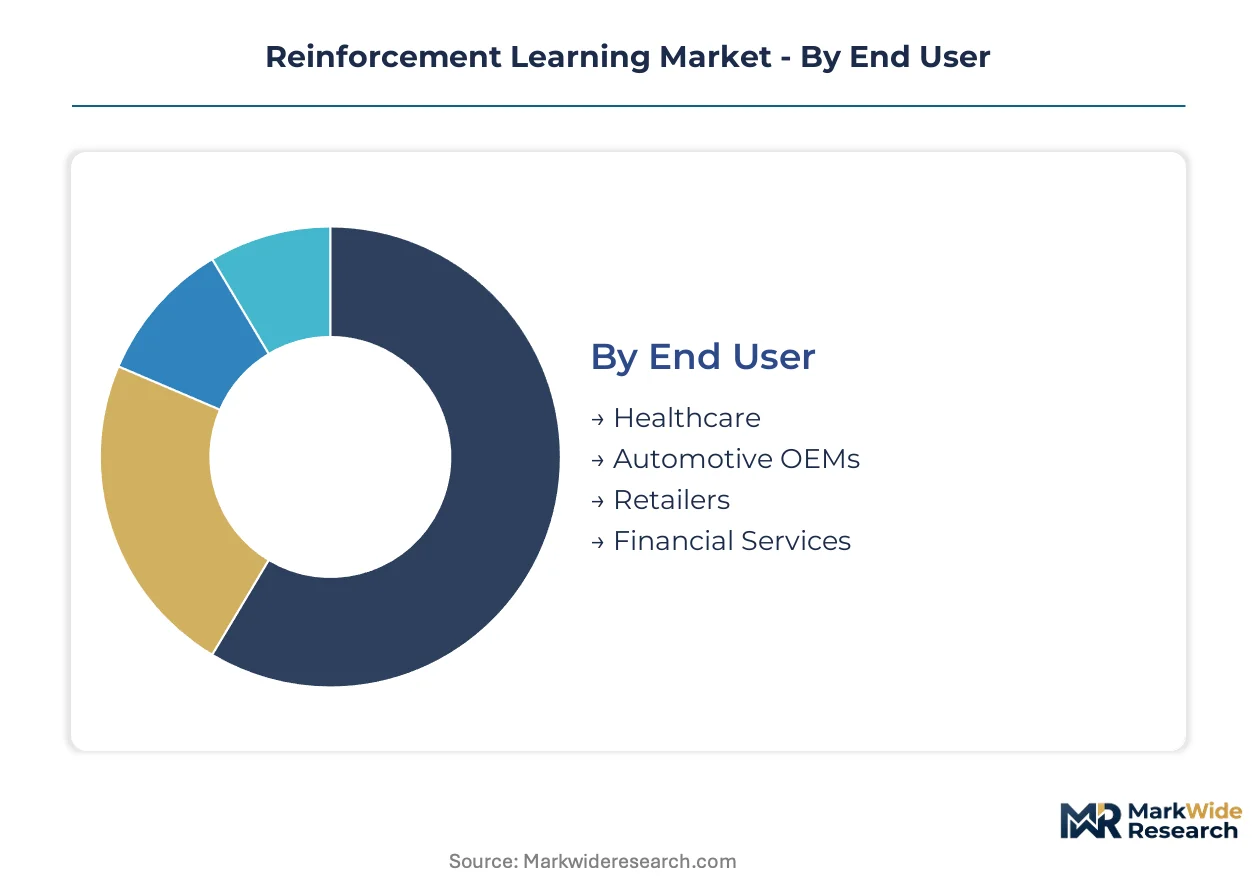
Segmentation in reinforcement learning markets reveals divergent procurement cycles across deployment modes and end-use verticals. Healthcare and automotive applications demand extended validation timelines, while cloud-native financial services deploy policy updates weekly. Understanding these velocity differentials enables vendors to align R&D roadmaps with segment-specific certification requirements.
End User:
Healthcare procurement cycles stretch across multiple quarters due to FDA premarket review pathways, while financial services firms iterate trading algorithms in days. Automotive OEMs occupy the middle ground with NHTSA scenario-based testing mandates.
- Healthcare:RL deployment concentrates in diagnostic imaging and robotic surgery systems where reward function design must satisfy FDA validation protocols. Demand clusters at academic medical centers in Massachusetts and California where pilot programs receive institutional review board clearance.
- Automotive OEMs:Manufacturers integrate RL-based navigation and manipulation controllers into electric vehicle production lines. German and Japanese automakers lead procurement volumes, driven by EU AI Act conformity requirements and domestic safety certification standards.
- Retailers:Dynamic pricing engines and warehouse robotics attract mid-market investment from grocery and apparel chains.
- Financial Services:Algorithmic trading desks and risk optimization platforms dominate RL spending at hedge funds and proprietary trading firms.
Financial Services anchors the volume base while Healthcare gains share at the steepest rate as FDA establishes clearer RL device review frameworks.
Application:
Robotics applications command premium pricing due to sim-to-real transfer complexity, whereas game development leverages established physics engines with lower marginal engineering cost.
- Robotics:Manufacturing and logistics operators deploy visual servoing and grasp planning policies trained in NVIDIA Isaac Gym before hardware commissioning. Japanese automotive parts suppliers and German industrial conglomerates drive procurement concentration.
- Game Development:Non-player character behavior and procedural content generation utilize established RL frameworks with compressed implementation timelines. Demand spreads across independent studios and major publishers in California and Quebec.
- Virtual Assistants:Enterprise customer service platforms integrate dialogue policy optimization for multi-turn interaction management.
- Supply Chain Optimization:Inventory positioning and routing algorithms attract third-party logistics providers and e-commerce fulfillment operators.
Game Development sustains the broadest installed base while Robotics climbs the fastest as simulation-to-reality protocols mature.
Deployment:
Cloud-Based deployment absorbs capital-intensive training burdens for mid-market developers, while Edge Computing demands hardware-software co-design expertise concentrated at defense contractors.
- Cloud-Based:Hyperscaler infrastructure enables distributed policy gradient training without on-premise GPU cluster investment. United States and Western European developers dominate consumption patterns.
- Edge Computing:Battery-constrained drones and autonomous ground vehicles require sub-watt inference on neuromorphic or embedded GPU hardware. Defense procurement programs in the United States and United Kingdom establish reference architectures.
- On-Premises:Financial institutions and healthcare systems with data sovereignty requirements maintain captive training infrastructure.
- Hybrid Cloud:Enterprises split sensitive data processing on-premise while offloading simulation workloads to cloud instances.
Cloud-Based deployment captures the majority of new project starts while Edge Computing expands most quickly in defense and energy inspection applications.
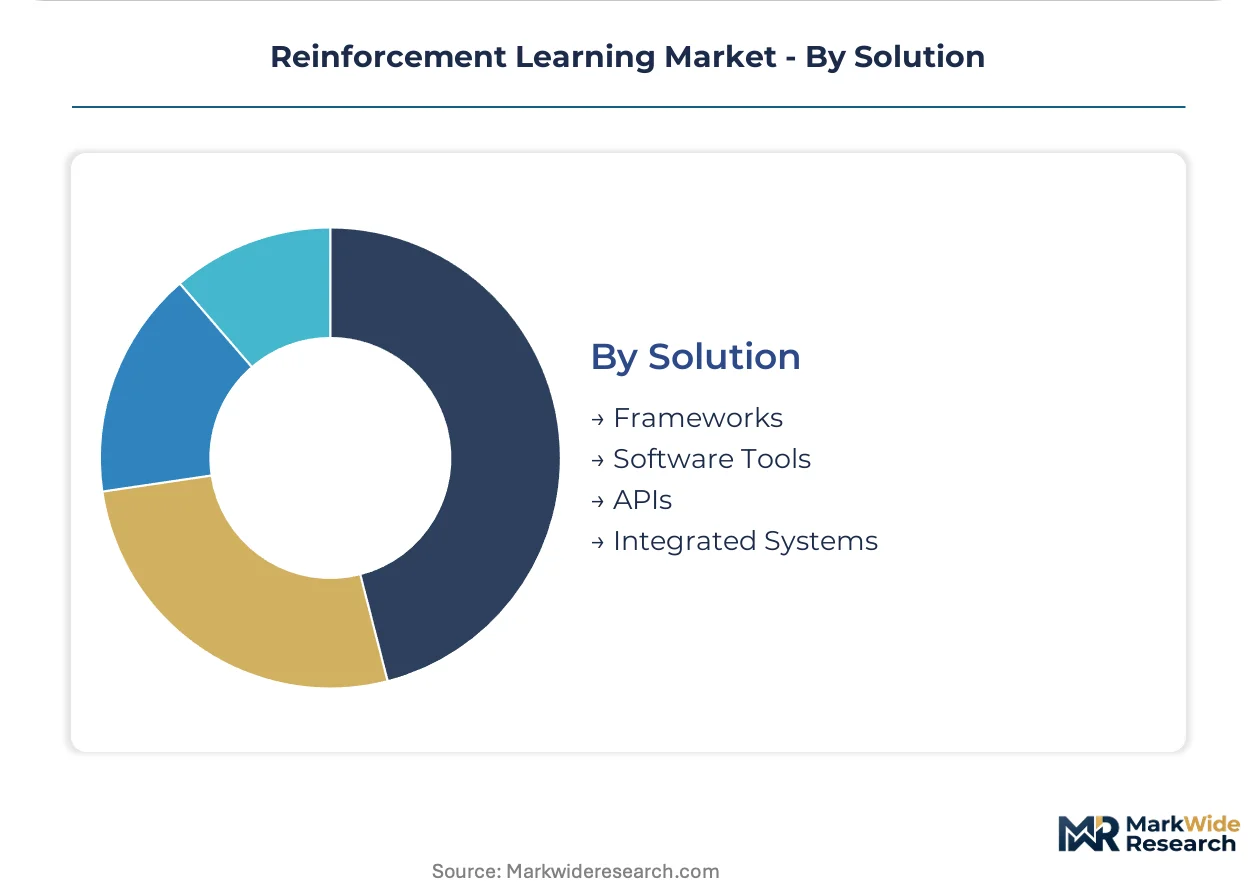
Solution:
Integrated Systems command the highest contract values through bundled hardware-software-sustainment offerings, while APIs enable rapid experimentation with limited capital commitment.
- Integrated Systems:Prime contractors deliver end-to-end autonomous platforms combining RL controllers with sensors and actuators. United States Department of Defense single-award contracts consolidate vendor relationships around these comprehensive offerings.
- Frameworks:TensorFlow RL and Ray RLlib anchor open-source development pipelines at research institutions and venture-backed startups. Academic adoption concentrates at Stanford, Berkeley, and ETH Zurich.
- Software Tools:Visualization and debugging environments support policy development workflows at robotics specialists.
- APIs:Managed RL services from cloud providers lower entry barriers for enterprise experimentation.
Frameworks sustain the widest developer adoption while Integrated Systems capture the steepest expansion trajectory through defense procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese cloud hyperscalers export RL training infrastructure to Southeast Asian manufacturing hubs, while German automotive OEMs import simulation software from United States-based platform vendors. Trade corridors concentrate value capture at the algorithm design layer in North America and the deployment hardware layer in East Asia.
United States
Pentagon procurement programs for autonomous unmanned systems and commercial cloud hyperscaler investments drive domestic demand. The SEC scrutinizes RL deployment in automated trading for market manipulation risks. Defense contractors cluster in Northern Virginia and Greater Boston, where prime contractors bundle RL-based navigation with hardware in single-award contracts.
Germany
Automotive OEMs and industrial conglomerates anchor European demand for manufacturing automation and autonomous vehicle validation. The EU AI Act imposes conformity assessment obligations that compel vendors to document training data provenance. Stuttgart and Munich host algorithmic auditing functions that pre-validate RL policies before regulatory submission.
China
Domestic cloud infrastructure expansion and state-backed robotics manufacturing initiatives absorb policy gradient training capacity. The national dual carbon goals accelerate RL deployment in energy grid optimization. Shenzhen and Shanghai concentrate visual servoing vendors serving electronics assembly lines under the MIIT industrial upgrade framework.
Japan
Automotive parts suppliers and precision machinery manufacturers deploy grasp planning policies trained in synthetic environments. METI safety certification standards for collaborative robots mandate extensive simulation-based validation. Nagoya and Osaka host the densest concentrations of RL-integrated manufacturing cells for automotive component production.
India
Electronics and automotive assembly incentives under the PLI scheme attract first-mover RL vendors for visual servoing applications. The central bank's digital payment infrastructure investments create adjacent demand for fraud detection algorithms. Karnataka and Tamil Nadu concentrate contract manufacturing facilities where RL-based quality inspection systems displace manual sampling protocols.
Reinforcement Learning Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform providers capable of bundling hardware, software, and sustainment. Three archetypes dominate: cloud hyperscalers offering managed RL training pipelines, semiconductor vendors with hardware-software co-design advantages, and defense prime contractors delivering end-to-end autonomous systems. Competitive moves center on strategic partnerships with robotics OEMs and vertical integration into simulation engine development.
Within the cloud-native tier, Google LLC and Microsoft exemplify platform-scale competition anchored in TensorFlow and Azure ecosystems respectively. NVIDIA Corporation occupies a distinct position bridging silicon and simulation software. These three entities represent the dominant architectural choices facing enterprise procurement teams selecting between open-source frameworks, proprietary cloud services, and hardware-integrated stacks.
| Leading Market Players |
|---|
| Google LLC |
| Microsoft |
| Amazon Web Services, Inc. |
| IBM Corporation |
| NVIDIA Corporation |
| Intel Corporation |
| Alibaba Group Holding Ltd. |
| SAP SE |
| OpenAI Inc. |
| Others |
Pricing and Supply Chain Analysis
Taiwan Semiconductor Manufacturing capacity allocation bottlenecks determine both GPU availability premiums and the geographic clustering of RL training infrastructure investments. The EU AI Act's conformity assessment requirements add certification cost layers that widen pricing spreads between documented and undocumented system providers.
Pricing Analysis
Next-generation neuromorphic hardware commands substantial premiums over current GPU-based training clusters and prior-generation CPU-only deployments. Three-tier pricing structure across premium, standard, and economy levels separates defense-grade integrated systems from cloud-managed APIs and open-source frameworks. Cost compression in mid-market robotics software stems from hyperscaler SaaS competition. Hedge funds and proprietary trading firms exhibit the lowest price sensitivity due to direct P&L linkage, while Indian contract manufacturers under PLI scheme constraints drive hardest bargain negotiations.
Supply Chain Analysis
Tariff exposure between United States and China dominates strategic sourcing decisions for advanced GPU and TPU procurement. Taiwan, South Korea, and United States anchor semiconductor fabrication capacity for training accelerators. The supply chain draws from cobalt-intensive memory modules, rare-earth magnet components, and photolithography equipment. Single-source vulnerability concentrates at TSMC's leading-edge node production. Distribution runs through defense prime contractor integrators, cloud hyperscaler marketplaces, and direct OEM relationships with robotics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domain randomization expertise and sim-to-real transfer engineering talent concentrate within fewer than two dozen institutions globally, constraining scalable deployment capacity. This scarcity architecture rewards first-movers who lock in specialist teams and synthetic data generation pipelines.
For Market Incumbents: Harden algorithmic auditing capabilities ahead of EU AI Act enforcement expansion and FDA premarket review pathway maturation. Establish captive simulation environment development to reduce dependency on NVIDIA Isaac Gym licensing. Acquire domain adaptation specialists in Germany and Japan before talent costs escalate further. For New Entrants and Emerging Players: Mid-market warehouse robotics in India and Southeast Asia represent the most penetrable entry point given PLI scheme automation incentives and limited incumbent presence. Battery-constrained drone inspection for energy infrastructure offers adjacent white-space with shorter validation cycles. Lead with open-source framework customization services to bypass capital-intensive hardware development. For Investors and Strategic Acquirers: Simulation-to-reality transfer boutiques with established German automotive OEM relationships command scarcity premiums through the projection horizon. Long-term viability hinges on regulatory documentation capabilities rather than raw algorithmic performance. Watch NHTSA scenario-based testing mandate expansion as inflection indicator for synthetic environment procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Simulation Environment Development | Differentiable physics engines from NVIDIA Isaac Gym collapse training costs for automotive Tier 1 suppliers. |
| Algorithmic Auditing Function Establishment | Internal pre-validation capabilities at German automotive OEMs accelerate EU AI Act conformity pathways. |
| Neuromorphic Hardware Integration | Spiking neural network convergence enables sub-watt edge inference for battery-constrained defense drones. |
| Defense Prime Contractor Partnership | Single-award Pentagon procurement bundles establish reference architectures cascading into commercial logistics. |
| Cloud-Native API Service Launch | Managed RL pipelines from Google and Microsoft lower entry barriers for mid-market robotics developers. |
Research Methodology
Initial hypotheses were tested against primary input from robotics control engineers, cloud infrastructure procurement officers, regulatory affairs specialists at medical device manufacturers, and defense program managers, then refined through secondary validation. Sources included FDA premarket submission databases, EU AI Act implementation guidance, hyperscaler capital expenditure disclosures, and robotics OEM technical specifications. Bottom-up segment sizing and top-down macro constraint checks ensured analytical coherence.
Demand-supply balance framing anchored the forecast architecture across the analysis window. Segmentation dimensions encompassed deployment mode, end-use vertical, application complexity tier, and regional regulatory cluster. CAGRs emerged from policy gradient training cost trajectory modeling and enterprise procurement cycle analysis. Simulation-to-reality protocol maturity curves and GPU cluster availability projections supplied industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in defense budget appropriations, semiconductor capital expenditure cycles, or EU AI Act enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding training cost decline rates and regulatory timeline adherence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
CLV and Churn Prediction AI Market
Artificial Intelligence (AI)
Text-To-Speech (TTS) Market
Artificial Intelligence (AI)
AI Development Service Market
Artificial Intelligence (AI)
AI Content Creation Tool Market
Artificial Intelligence (AI)
Agentic AI Market
Artificial Intelligence (AI)
Latin America Artificial Intelligence Market
Artificial Intelligence (AI)
AI Demand Forecasting Software Market
Artificial Intelligence (AI)
United States Conversational AI Market
Artificial Intelligence (AI)
Adaptive AI Market
Artificial Intelligence (AI)
Smart Home Digital Assistant [Voice] Market
Artificial Intelligence (AI)
Robotic Vision Market
Artificial Intelligence (AI)
Global Cognitive Computing Technology Market
Artificial Intelligence (AI)
US Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Cloud Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence in Logistics Market
Artificial Intelligence (AI)
Global AI in Social Media Market