
 AI Image Recognition Market | 2026-2036
AI Image Recognition Market Size, Share, and Industry Trends Forecast 2026-2036
AI Image Recognition Market Analysis
Subscription-based API access for facial recognition and object detection is hardening into the dominant commercial model for AI image recognition vendors. Scale AI leverages its data-labeling infrastructure to anchor enterprise contracts across autonomous vehicle developers. Clarifai specializes in custom model training services that sustain recurring revenue from defense and retail clients. Paravision dominates government-sector facial recognition procurement through FedRAMP-authorized cloud deployments.
AI image recognition encompasses computational systems that process visual inputs through convolutional neural networks to identify patterns, objects, or individuals with defined accuracy thresholds, serving industrial automation, security screening, and medical diagnostics. Deep learning architectures now lead technology adoption due to superior performance on unstructured visual data, while edge computing deployment is expanding fastest as manufacturers seek millisecond-latency inference without cloud dependency. Healthcare and security end users concentrate margin pools because these sectors require certified, high-reliability systems with long support contracts.
The EU AI Act classifies biometric identification as high-risk, mandating conformity assessments before market entry, while the FDA regulates AI-enabled diagnostic imaging as Software as a Medical Device requiring clinical validation. In the United States, NIST facial recognition standards shape procurement specifications for federal agencies. Stakeholders must monitor evolving compliance thresholds across jurisdictions to determine whether to standardize on cloud-based or hybrid deployment architectures.
Market Dynamics
Edge inference hardware is compressing latency requirements for real-time visual processing, forcing vendors to rearchitect delivery models around on-device deployment rather than cloud-centric processing pipelines.
Growth Catalysts
- FDA Software as a Medical Device pathway:The framework accelerates clinical validation for AI-enabled diagnostic imaging, enabling faster commercialization of radiology screening tools in hospital networks.
- Defense procurement specifications:NIST facial recognition standards mandate accuracy thresholds for federal agency contracts, creating certified demand pools for biometric system vendors.
- Convolutional neural network optimization:Algorithmic efficiency gains reduce compute requirements for inference, expanding deployability to resource-constrained manufacturing environments.
Market Restraints
- GPU supply concentration:Advanced training hardware availability concentrates with Taiwan-based foundry capacity, creating input bottlenecks for model development pipelines.
- EU AI Act conformity costs:High-risk biometric system assessments impose documentation and audit burdens that extend time-to-revenue for European market entry.
- Edge hardware unit economics:Dedicated inference accelerators carry premium pricing relative to general-purpose processors, limiting adoption in cost-sensitive industrial automation segments.
Strategic Opportunities
- Agricultural automation in Brazil:Crop monitoring and livestock identification applications remain underpenetrated, offering first-mover positioning for computer vision providers.
- Synthetic data generation:Physics-based simulation tools converge with generative models to reduce dependency on expensive manual labeling for rare pathology detection.
- India PLI scheme for electronics:Production-linked incentives for semiconductor and component manufacturing create localized supply chain foundations for edge device assembly.
Industry Challenges
- Embedded systems integration:Deployment of vision models onto heterogeneous edge hardware requires specialized firmware engineering talent that remains scarce in industrial regions.
- FedRAMP authorization timelines:Cloud service providers face extended security assessment cycles that delay government contract eligibility and revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Image Recognition Market |
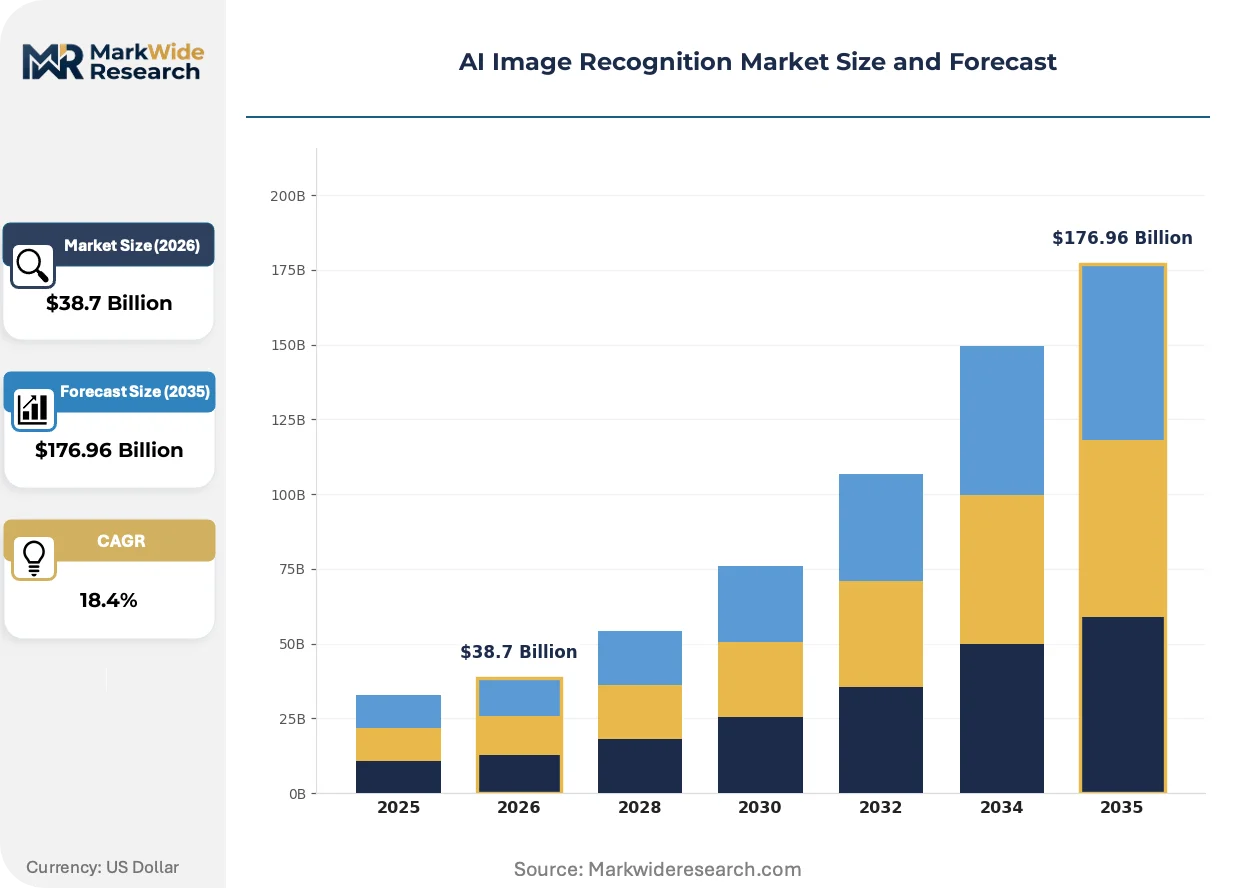
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $176.96 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Convolutional Neural Networks, Deep Learning, Computer Vision, Machine Learning End User: Healthcare, Retail, Automotive, Security Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Application: Facial Recognition, Object Detection, Image Classification, Augmented Reality |
| Companies Covered | Paravision, HyperVerge, Scale AI, Dashmote, Techcyte, Clarifai, Trax, Nexar, Chooch AI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Image Recognition Market Emerging Trajectories
Federated learning architectures are redistributing model training across distributed device networks, altering how visual AI systems accumulate knowledge without centralizing sensitive image data.
Vision transformers are displacing convolutional architectures as the dominant neural network design for image classification and object detection tasks. Medical imaging departments at academic hospital systems are piloting these models for pathology screening workflows. The shift is decentralizing performance leadership away from established computer vision incumbents toward natural language processing specialists cross-applying attention mechanisms.
The EU AI Act mandates fundamental rights impact assessments for biometric identification systems before market deployment. Manufacturers must document risk mitigation measures and maintain post-market monitoring systems throughout product lifecycles. High-risk system vendors are responding by establishing dedicated regulatory affairs functions in Brussels and Dublin to manage conformity certification processes.
Enterprise buyers are unbundling software licenses from hardware procurement for edge vision deployments. Manufacturing facilities increasingly source cameras and accelerators separately from inference runtime subscriptions, compressing traditional bundled system margins. This pattern is most pronounced in Germany automotive supplier networks, where procurement teams negotiate API access independently of edge gateway hardware.
AI Image Recognition Market Segmentation
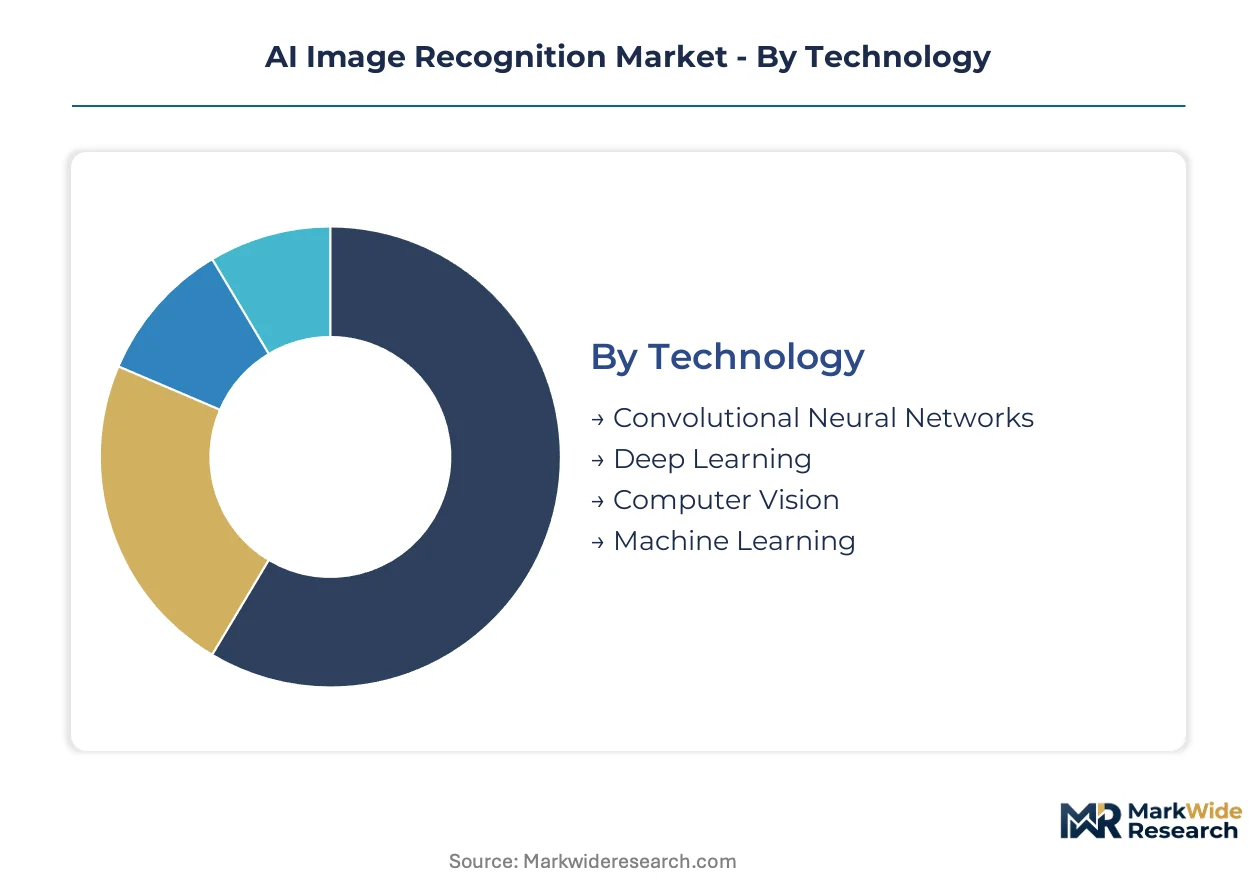
Technology selection determines integration architecture for AI image recognition deployments. Convolutional neural networks and deep learning frameworks impose distinct hardware requirements and latency profiles that shape procurement decisions across end-use verticals.
Technology:
Standalone inference engines demand discrete processing resources, while embedded implementations compress models onto specialized accelerators.
- Convolutional Neural Networks:Layered feature extraction architectures process spatial hierarchies through filter banks and pooling operations. Automotive manufacturers in Germany specify CNN-based perception stacks for autonomous driving validation pipelines, constrained by thermal budgets in vehicle-integrated hardware.
- Deep Learning:Multi-layer neural architectures with backpropagation training enable end-to-end feature learning from raw pixel data. Academic medical centers in the United States deploy deep learning models for pathology screening, driven by FDA Software as a Medical Device pathway acceleration for clinical validation.
- Computer Vision:Rule-based and hybrid algorithms combining classical image processing with learned representations.
- Machine Learning:Traditional statistical learning methods including support vector machines and random forests for constrained-resource deployments.
Volume placements concentrate in Convolutional Neural Networks; the faster expansion belongs to Deep Learning.
End User:
Margin concentration varies sharply by sector certification requirements and contract duration.
- Healthcare:Diagnostic imaging workflows demand FDA-validated algorithms with clinical evidence packages. Hospital networks in the United States prioritize radiology screening tools for lung nodule and retinal pathology detection, constrained by liability frameworks and reimbursement coding alignment.
- Security:Biometric identification systems face EU AI Act high-risk classification with conformity assessment mandates. Federal agencies in the United States specify NIST-compliant facial recognition accuracy thresholds for border control and facility access applications.
- Retail:Inventory management and customer analytics applications.
- Automotive:Advanced driver-assistance systems and autonomous vehicle perception stacks.
Revenue concentration sits with Healthcare; Security shows the steepest expansion trajectory from government procurement acceleration.
Deployment:
Latency requirements and data sovereignty rules partition architecture choices across use cases.
- Cloud-Based:Centralized inference with elastic compute scaling and API access models. Retail chains in the United States deploy cloud-based object detection for warehouse automation, driven by seasonal demand volatility and capital expenditure minimization priorities.
- Edge Computing:On-device inference with millisecond-latency processing without network dependency. Manufacturing facilities in Germany specify edge vision for quality inspection lines, constrained by production continuity requirements and data localization policies.
- On-Premises:Private data center deployments with dedicated infrastructure ownership.
- Hybrid:Distributed processing with cloud training and edge inference orchestration.
Cloud-Based captures current volume leadership; Edge Computing is climbing the fastest from manufacturing automation mandates.
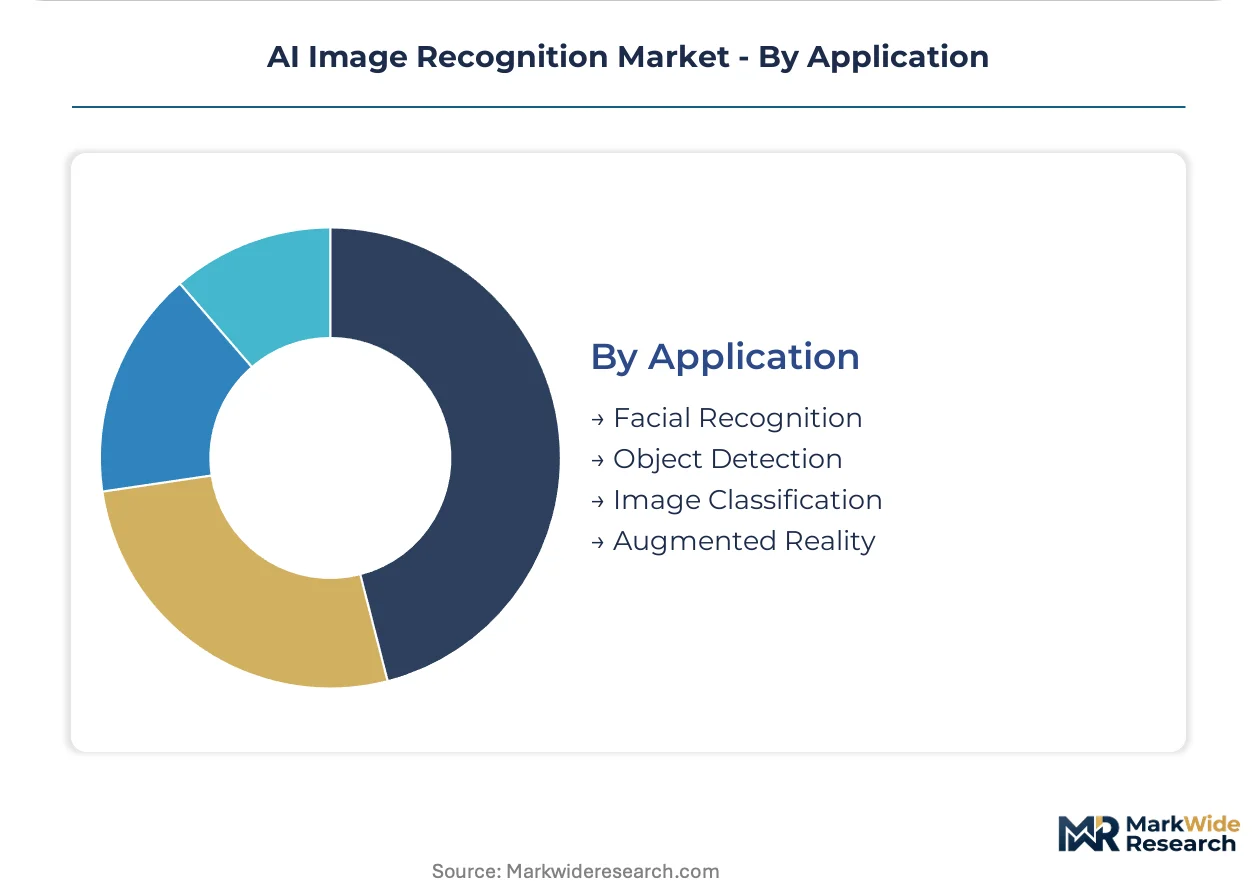
Application:
Functional use cases map to distinct accuracy thresholds and regulatory exposure profiles.
- Facial Recognition:Biometric identity verification through facial geometry analysis and liveness detection. Government agencies in the United States procure FedRAMP-authorized cloud deployments for identity verification services, shaped by NIST accuracy benchmarking and civil liberties oversight frameworks.
- Object Detection:Bounding-box localization and classification of multiple entities within visual scenes. Agricultural automation pilots in Brazil deploy drone-mounted object detection for crop health monitoring and livestock enumeration, enabled by synthetic data generation reducing manual labeling costs.
- Image Classification:Single-label or multi-label categorization of entire image contents.
- Augmented Reality:Real-time visual overlay and spatial anchoring for user interface enhancement.
Facial Recognition dominates procurement value; Object Detection is gaining share fastest from industrial automation penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley anchors the densest concentration of AI image recognition R&D, with San Francisco and San Jose hosting specialized computer vision labs and venture capital networks that seed early-stage model development.
United States
Defense procurement and retail automation drive demand concentration. NIST facial recognition standards mandate accuracy thresholds for federal agency contracts. Boston's academic medical centers pilot FDA-validated diagnostic imaging tools for pathology screening workflows.
China
Smart city surveillance and manufacturing quality inspection absorb significant deployment volumes. MIIT issues algorithmic recommendation management provisions affecting biometric system deployments. Shenzhen's hardware ecosystem supplies edge inference accelerators to domestic automation integrators.
Germany
Automotive perception stack validation and industrial quality inspection dominate procurement priorities. EU AI Act conformity assessments impose documentation burdens on biometric system vendors. Stuttgart's automotive supplier networks negotiate API access independently of edge gateway hardware.
India
Agricultural automation and healthcare diagnostics expansion create emerging demand pools. PLI scheme incentives for electronics manufacturing localize supply chain foundations for edge device assembly. Bengaluru's technology corridor hosts computer vision startups targeting crop monitoring applications.
United Kingdom
Financial services identity verification and retail analytics sustain commercial adoption. Information Commissioner's Office guidance shapes biometric data processing compliance frameworks. London's fintech cluster deploys cloud-based facial recognition for customer onboarding pipelines.
AI Image Recognition Market Vendor Landscape
Capital-heavy infrastructure providers compete with asset-light algorithm developers for margin capture in AI image recognition. The vendor base concentrates around three strategic tiers: cloud-scale API platforms, specialized vertical solution providers, and edge hardware-software integrators. Dominant competitive moves include FedRAMP authorization pursuit for government eligibility and synthetic data generation capability acquisition to reduce manual labeling dependencies.
Within the government-sector tier, Paravision exemplifies the compliance-first archetype through FedRAMP-authorized positioning. Scale AI and Clarifai occupy distinct positions on the infrastructure-versus-customization spectrum, with the former representing data-labeling anchored enterprise contracting and the latter exemplifying recurring revenue from defense and retail model training services.
| Leading Market Players |
|---|
| Paravision |
| HyperVerge |
| Scale AI |
| Dashmote |
| Techcyte |
| Clarifai |
| Trax |
| Nexar |
| Chooch AI |
| Others |
Supply Flow & Price Mechanics
Federal agency procurement pools in the United States anchor pricing power for biometric system vendors, conditioning commercial models on FedRAMP authorization and NIST accuracy certification tiers. This buyer concentration elevates value-based contracting over transactional hardware sales, with subscription API access hardening into the dominant commercial structure.
Pricing Analysis
Outcome-linked pricing tied to detection accuracy thresholds and system uptime commitments anchors enterprise contracts in security and healthcare verticals. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-authorized deployments from uncertified cloud offerings and edge hardware bundles. Pricing pressure stems from GPU supply concentration compressing margins for training-intensive model development. Cost-sensitive industrial automation buyers in manufacturing exhibit highest price sensitivity, while defense procurement shows lowest elasticity due to mission-critical reliability requirements.
Supply Chain Analysis
Dual-sourcing requirements for inference accelerators are becoming standard in automotive and defense procurement specifications, with buyers mandating multi-supplier qualification to mitigate Taiwan foundry concentration. Advanced training hardware draws from Taiwan, South Korea, and United States fabrication capacity, while edge deployment chips source from China and United States assembly networks. Single-source vulnerability in GPU supply creates input bottlenecks for model development pipelines. Distribution runs through cloud service provider marketplaces and direct enterprise sales teams for government contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AI image recognition market operates as a cost-of-compliance story where EU AI Act conformity assessments and FDA Software as a Medical Device pathways erect barrier-to-entry moats for certified players, marginalizing vendors lacking regulatory affairs infrastructure.
For Market Incumbents: Extend FedRAMP authorization coverage into emerging biometric applications and deepen synthetic data generation capabilities to reduce manual labeling dependencies. Vision transformer architectures threaten CNN-based incumbents with performance displacement; counter by acquiring attention-mechanism engineering talent from natural language processing specialists. For New Entrants and Emerging Players: Synthetic data generation tools offer a technology-first wedge into agricultural automation in Brazil, where crop monitoring and livestock identification applications remain underpenetrated. Target API-first commercial models for manufacturing quality inspection in Germany, where procurement teams unbundle software licenses from hardware procurement. Lead with edge deployment expertise to bypass cloud infrastructure capital requirements. For Investors and Strategic Acquirers: The window for entry favors regulatory affairs-enabled specialists with EU AI Act conformity infrastructure and FDA clinical validation track records. Long-term viability hinges on five-to-ten year contract duration in healthcare and security verticals. Watch NIST facial recognition standard revision cycles as inflection indicators for federal procurement specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Pursuit | Enables federal agency contract eligibility and revenue recognition in government biometric procurement. |
| Synthetic Data Generation Acquisition | Reduces dependency on expensive manual labeling for rare pathology detection in medical imaging workflows. |
| Edge Hardware-Software Integration | Captures manufacturing automation demand requiring millisecond-latency inference without cloud dependency. |
| Vision Transformer Architecture Migration | Displaces CNN performance leadership in academic hospital pathology screening pilots. |
| EU Regulatory Affairs Function Establishment | Manages conformity certification processes for high-risk biometric system market entry. |
Methodological Framework
SEC filings, hyperscaler capex disclosures, and FDA Software as a Medical Device submissions formed the secondary backbone, supplemented by EU AI Act conformity assessment documentation and NIST facial recognition standard benchmarking reports. Primary interviews with computer vision engineering leads, federal procurement officers, hospital biomedical informatics directors, and automotive Tier 1 supplier technology strategists validated secondary findings. Bottom-up deployment volume estimates triangulated against top-down technology spending projections across the analysis window.
Historical trendline analysis of convolutional neural network and deep learning adoption curves informed growth trajectory modeling across technology segments. Segmentation dimensions included deployment architecture, end-use vertical certification requirements, and regional regulatory framework clusters. CAGR derivation rested on algorithmic efficiency improvement rates and edge hardware cost decline curves. Forecast inputs incorporated GPU supply capacity expansion timelines and EU AI Act implementation phase-in schedules.
Several conditions sit outside the modeled scope, including geopolitical disruption of Taiwan semiconductor foundry operations and unanticipated FDA pathway revisions for diagnostic imaging algorithms. Forecasts reflect documented assumptions regarding continued defense procurement acceleration and cloud API commercial model consolidation. Deviation in EU AI Act enforcement intensity or NIST standard revision timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global AI in Social Media Market
Artificial Intelligence (AI)
Permission-Aware AI Repository Gateway Market
Artificial Intelligence (AI)
Global AI in Telecommunication Market
Artificial Intelligence (AI)
AI Orchestration Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Social Media Market
Artificial Intelligence (AI)
Explainable AI Market
Artificial Intelligence (AI)
AI Industrial Defect Detection Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Sports Market
Artificial Intelligence (AI)
North America Artificial Intelligence Market
Artificial Intelligence (AI)
Global Artificial Intelligence-Emotion Recognition Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Radiology Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in BFSI Market
Artificial Intelligence (AI)
Global Augmented Intelligence Market
Artificial Intelligence (AI)
Asia-Pacific Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
Aiops Market
Artificial Intelligence (AI)
AI in Retail Market