
 Global Cognitive Operations Market | 2026-2036
Global Cognitive Operations Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cognitive Operations Market Foresight
The shortage of site reliability engineers with AI-operations expertise is collapsing deployment timelines for enterprise cognitive platforms. IBM Corporation leverages its Watson portfolio to anchor hybrid cloud automation across regulated industries. Splunk Inc. competes on real-time data analytics depth, while Dynatrace LLC specializes in full-stack observability with native AI root-cause analysis.
Cognitive operations denotes the integration of artificial intelligence, machine learning, and natural language processing with IT operations to enable self-healing systems, predictive incident management, and autonomous remediation workflows. These systems process telemetry streams exceeding terabytes daily to surface anomalies before service degradation occurs. Automation Platforms and Data Analytics Tools command the largest solution offering share, as enterprises prioritize closed-loop remediation over standalone cognitive assistants. Cloud-Based deployment dominates new implementations, though Hybrid configurations retain strong traction among financial services firms with data residency requirements.
The EU AI Act, GDPR, and ISO/IEC 42001 standards collectively mandate algorithmic transparency and risk classification for automated decision systems, directly shaping vendor product roadmaps and procurement criteria. In the United States, NIST AI Risk Management Framework and SEC disclosure rules for material cybersecurity incidents add compliance layers that favor established platform providers with audit-ready governance tooling. Stakeholders must weigh the pace of generative AI integration against emerging liability frameworks that assign accountability for autonomous system failures.
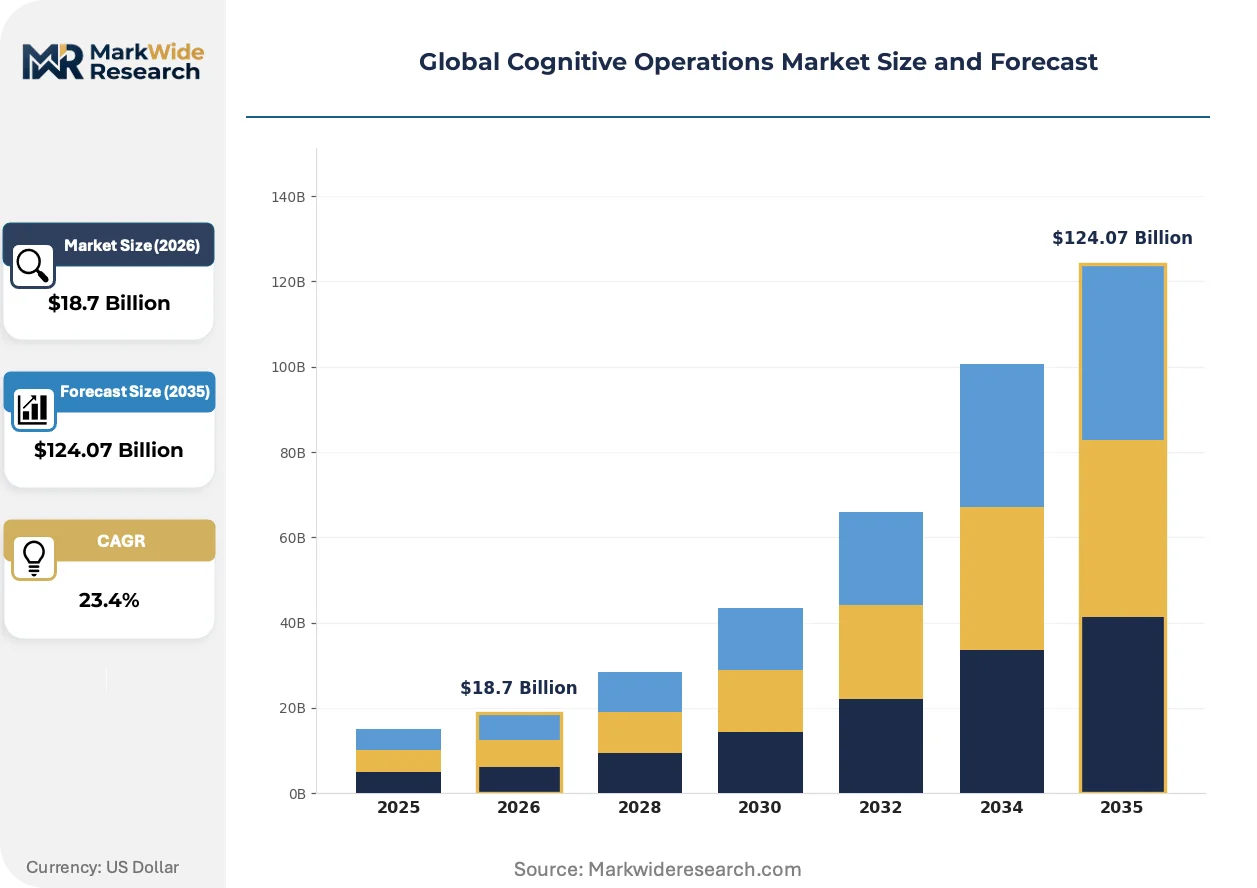
Market Dynamics
The integration of generative AI into IT operations is compressing incident response windows while simultaneously exposing enterprises to algorithmic liability under emerging regulatory frameworks.
Growth Catalysts
- Federal cloud modernization mandates:United States government agencies are accelerating procurement of intelligent operations platforms to meet zero-trust architecture deadlines.
- EU AI Act risk classification:Banking and insurance firms across Europe are deploying automated decision systems with embedded audit trails to satisfy high-risk system requirements.
- Telemetry volume explosion:Edge computing deployments in manufacturing and energy are generating petabyte-scale observability data that exceeds human analytical capacity.
Market Restraints
- GPU supply concentration:Training and inference workloads for cognitive operations depend on semiconductor fabrication concentrated in Taiwan and South Korea.
- ISO/IEC 42001 compliance costs:Certification for AI management systems imposes documentation burdens that disproportionately affect mid-sized platform vendors.
- Data residency fragmentation:Divergent national data localization laws in China, Russia, and India fragment cloud deployment architectures.
Strategic Opportunities
- Underpenetrated industrial IoT:Process manufacturing facilities in Brazil and Mexico lack AI-operations coverage despite high downtime costs.
- Convergence of AIOps and FinOps:Unified platforms combining infrastructure observability with cloud cost optimization address enterprise procurement consolidation trends.
- SEC cybersecurity disclosure rules:Material incident reporting requirements create demand for real-time anomaly detection with forensic audit capabilities.
Industry Challenges
- Site reliability engineering talent scarcity:Hybrid skill requirements spanning Kubernetes, machine learning operations, and domain-specific telemetry interpretation exceed available labor supply.
- Legacy mainframe integration:Financial services cognitive platforms must bridge decades-old COBOL systems with modern API-first observability stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cognitive Operations Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $124.07 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Automation Platforms, Data Analytics Tools, Cognitive Assistants, Process Mining Software, Decision Support Systems Deployment Model: Cloud-Based, On-Premise, Hybrid, Edge Computing, Virtualized Environments Use Case: Customer Service Automation, Fraud Detection, Predictive Maintenance, Risk Management, Compliance Monitoring End User Industry: Banking & Insurance, Telecommunications, Manufacturing, Government Agencies, Logistics & Transportation |
| Companies Covered | Dynatrace LLC, Broadcom Inc., IBM Corporation, New Relic, Inc., VMware, Inc., Splunk Inc., Micro Focus International plc, HCL Technologies, BMC Software, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cognitive Operations Market Shifts & Advancements
Generative AI capabilities are migrating from standalone assistants into embedded reasoning engines within observability platforms, fundamentally altering how IT teams interact with operational data.
Large language model inference is miniaturizing through quantization and edge deployment techniques. Manufacturing plants and telecommunications providers are adopting lightweight models for on-premises anomaly detection. This compression is miniaturizing the hardware footprint required for cognitive operations, enabling deployment in air-gapped environments previously inaccessible to cloud-dependent AI.
REACH chemical restrictions and the EU AI Act's prohibited practices list are converging to constrain training data sourcing. Platform vendors must now document data provenance and toxicity screening for models deployed in European jurisdictions. Automotive and medical device manufacturers face the steepest compliance ramps as both sectors fall under high-risk system classifications.
Enterprise buyers are unbundling professional services from platform licenses. Systems integrators and managed service providers are capturing implementation and tuning revenues that previously accrued to software vendors. This disintermediation is most pronounced in German-speaking markets, where specialized consultancies possess deep relationships with Mittelstand manufacturers undergoing digital transformation.
Global Cognitive Operations Market Segmentation
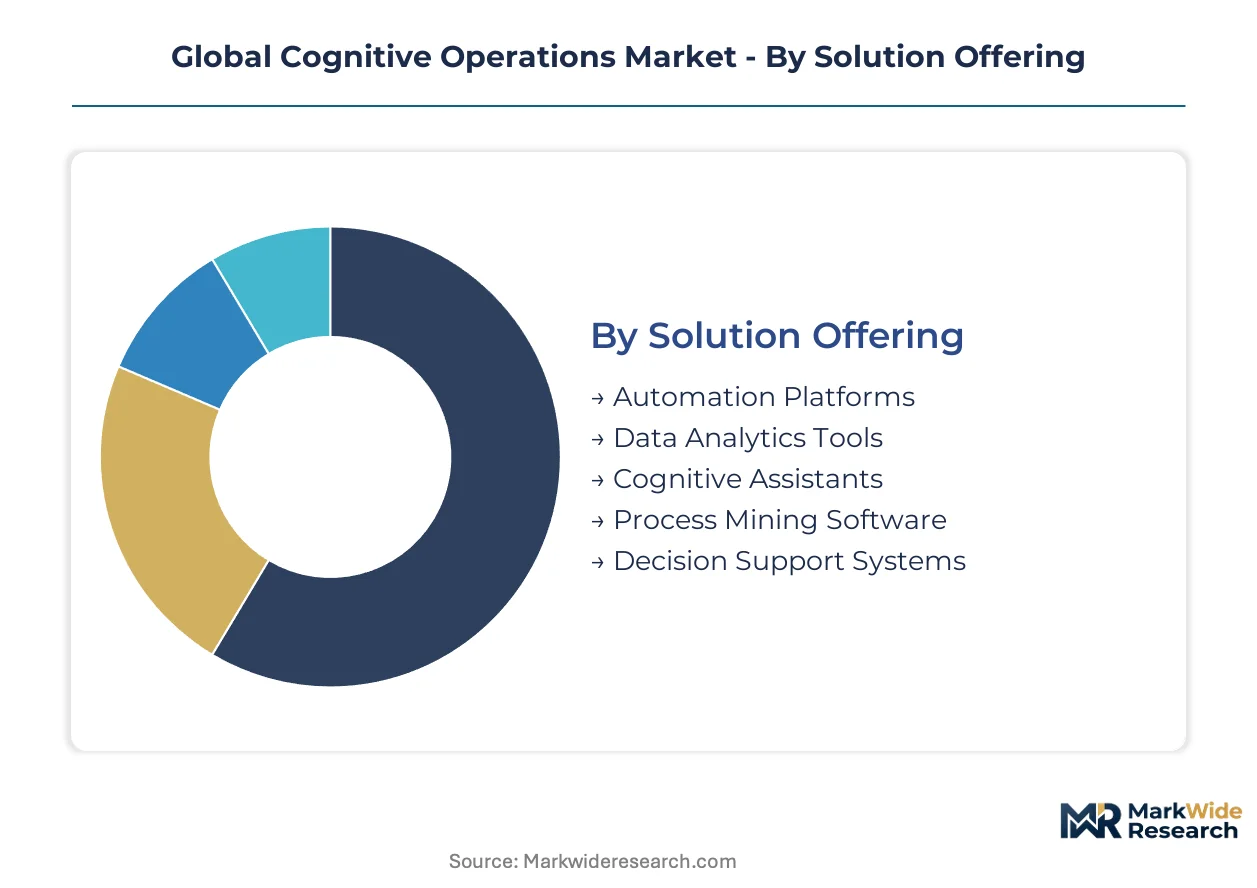
Cognitive operations platforms serve heterogeneous operational environments where deployment constraints, regulatory exposure, and telemetry complexity vary dramatically across buyer profiles. Segmentation reveals where vendor roadmaps diverge and which capability bundles command pricing premiums.
Solution Offering:
Automation Platforms and Data Analytics Tools flow through direct enterprise sales with embedded professional services, while Cognitive Assistants and Process Mining Software increasingly route through systems integrators and cloud marketplaces.
- Automation Platforms:These systems orchestrate self-healing workflows across distributed infrastructure, integrating with IT service management tools to execute remediation without human intervention. United States federal agencies under zero-trust mandates are standardizing procurement around platforms with FedRAMP authorization and native SOAR capabilities.
- Data Analytics Tools:Real-time stream processing engines that apply statistical and machine learning models to terabyte-scale telemetry, surfacing correlation patterns invisible to rule-based monitoring. Banking and insurance firms in the European Union deploy these with embedded audit trails to satisfy EU AI Act high-risk system documentation requirements.
- Cognitive Assistants:Natural language interfaces that translate operational queries into diagnostic actions, reducing mean time to resolution for tier-one support teams.
- Process Mining Software:Discovery tools that reconstruct business process flows from event logs, identifying automation candidates and compliance deviations.
- Decision Support Systems:Recommendation engines that synthesize multiple data sources to guide human operators through complex remediation scenarios.
Automation Platforms dominate installed base. Data Analytics Tools are where expansion concentrates.
Deployment Model:
Cost tier structures separate Cloud-Based deployments with consumption pricing from capital-intensive On-Premise installations requiring dedicated infrastructure teams.
- Cloud-Based:Multi-tenant SaaS architectures with elastic compute scaling and continuous model updates delivered by the vendor. United States commercial enterprises favor this model for speed of deployment, though data egress costs create friction at petabyte observability scales.
- On-Premise:Air-gapped installations in facilities with physical security requirements or latency constraints that preclude external connectivity. Manufacturing plants in Germany and Switzerland deploy these for production line monitoring subject to strict data residency protocols.
- Hybrid:Architectures that retain sensitive telemetry on-premises while routing anonymized patterns to cloud-based training pipelines. Financial services firms in Singapore and the United Kingdom use this configuration to balance model performance with regulatory constraints.
- Edge Computing:Lightweight inference engines deployed on factory floors, cellular towers, and utility substations where bandwidth limitations or millisecond latency requirements exclude centralized processing.
- Virtualized Environments:Containerized deployments on private infrastructure that mimic cloud operational patterns without external dependency.
Cloud-Based configurations capture the majority of new logo acquisitions. Hybrid deployments show the steepest expansion trajectory among regulated industries.
Use Case:
Application maturity varies sharply, with Fraud Detection and Predictive Maintenance commanding specialized hardware investments while Customer Service Automation faces compressed pricing from generative AI commoditization.
- Customer Service Automation:Ticket classification, routing, and resolution recommendation systems that reduce human agent workload. Telecommunications providers in India and Brazil deploy these at scale for subscriber support, though large language model integration is displacing earlier natural language processing architectures.
- Fraud Detection:Real-time transaction scoring systems that identify anomalous patterns indicating financial crime. Banking networks in the United States and European Union require these systems to demonstrate explainability under SEC disclosure rules and EU AI Act transparency mandates.
- Predictive Maintenance:Equipment health monitoring that forecasts failures before operational impact, enabling just-in-time maintenance scheduling.
- Risk Management:Portfolio and operational risk quantification systems that aggregate exposures across business units and external data sources.
- Compliance Monitoring:Continuous control testing and regulatory reporting automation that reduces manual audit preparation effort.
Fraud Detection dominates installed base. Predictive Maintenance is where expansion concentrates.
End User Industry:
Customer concentration and procurement sophistication separate Banking & Insurance with dedicated innovation budgets from Manufacturing with project-based capital allocation cycles.
- Banking & Insurance:Institutions with the highest telemetry complexity and regulatory exposure, deploying full-stack cognitive operations across fraud, compliance, and infrastructure domains. United States money center banks and European universal banks represent the most demanding reference customers for platform vendors.
- Telecommunications:Network operators managing billion-dollar infrastructure footprints with strict service level agreements, requiring predictive capabilities for cell tower and fiber optic maintenance. Operators in South Korea and Japan lead deployment of edge-based anomaly detection for 5G infrastructure.
- Manufacturing:Process and discrete manufacturers seeking to minimize unplanned downtime through equipment health monitoring and quality deviation detection.
- Government Agencies:Civilian and defense organizations with zero-trust cybersecurity mandates and classified data handling requirements that constrain vendor selection.
- Logistics & Transportation:Fleet operators and port authorities optimizing route planning, cargo handling, and predictive maintenance for mobile assets.
Banking & Insurance dominates installed base. Manufacturing is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC disclosure rules for material cybersecurity incidents and NIST AI Risk Management Framework compliance layers favor established platform providers with audit-ready governance tooling in the United States. Federal cloud modernization mandates are accelerating procurement of intelligent operations platforms to meet zero-trust architecture deadlines.
United States
Money center banks and federal agencies drive demand for FedRAMP-authorized platforms with native SOAR capabilities. SEC disclosure rules for material cybersecurity incidents create procurement preference for real-time anomaly detection with forensic audit capabilities. The Washington DC-to-Boston corridor concentrates vendor headquarters and systems integrator partnerships serving regulated industries.
Germany
Mittelstand manufacturers undergoing digital transformation seek closed-loop remediation platforms for production line monitoring. REACH chemical restrictions and EU AI Act prohibited practices constrain training data sourcing for automotive and medical device applications. Industrial clusters in Baden-Württemberg and Bavaria deploy air-gapped installations subject to strict data residency protocols.
Singapore
Financial services firms balance model performance with regulatory constraints through hybrid deployment architectures. The Monetary Authority of Singapore's technology risk management guidelines shape vendor selection criteria for banking networks. The Marina Bay financial district hosts regional headquarters for platforms serving Southeast Asian expansion.
United Kingdom
Universal banks and telecommunications operators require predictive capabilities for infrastructure maintenance with strict service level agreements. FCA operational resilience requirements mandate demonstrable self-healing workflow capabilities. London's Canary Wharf and Thames Valley technology corridor concentrate enterprise procurement decision-making.
Japan
Network operators managing billion-dollar 5G infrastructure footprints deploy edge-based anomaly detection for cell tower maintenance. METI guidelines on AI governance influence platform documentation standards for high-risk system classifications. The Tokyo-Yokohama corridor leads adoption of lightweight inference engines for millisecond-latency applications.
Global Cognitive Operations Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the cognitive operations market. Consolidation pressure favors vendors with hybrid cloud automation portfolios spanning regulated industries. Two archetypes dominate: full-stack observability platforms with native AI root-cause analysis, and data analytics specialists competing on real-time stream processing depth. Competitive moves concentrate on strategic partnerships with systems integrators and geographic expansion through cloud marketplace listings.
Within the integrated platform tier, IBM Corporation and Dynatrace LLC exemplify contrasting positioning strategies. Splunk Inc. occupies a position among analytics-depth specialists competing on terabyte-scale telemetry processing. These three entities represent the spectrum from hybrid cloud automation anchors to real-time data analytics depth providers.
| Leading Market Players |
|---|
| Dynatrace LLC |
| Broadcom Inc. |
| IBM Corporation |
| New Relic, Inc. |
| VMware, Inc. |
| Splunk Inc. |
| Micro Focus International plc |
| HCL Technologies |
| BMC Software, Inc. |
| Others |
Supply & Pricing Matrix
GPU-to-TPU substitution in training infrastructure is simultaneously redrawing procurement geography toward Taiwan and South Korea while compressing price premiums for inference-optimized hardware tiers.
Pricing Analysis
North American deployments command 15-25% premiums over equivalent configurations in Southeast Asian cloud regions. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-authorized platforms from commercial SaaS and open-source alternatives. Cost compression in the economy tier is intensifying because generative AI commoditization is displacing earlier NLP architectures. Mid-sized manufacturing firms in Germany and Brazil exhibit highest price sensitivity; United States federal agencies under zero-trust mandates show lowest sensitivity due to compliance-driven procurement.
Supply Chain Analysis
Inbound logistics costs through the Shanghai-to-Long Beach lane fluctuate with container availability, directly affecting on-premise hardware delivery timelines for air-gapped installations. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States. Cognitive operations platforms draw from GPU clusters, high-bandwidth memory modules, and specialized inference accelerators. Single-source vulnerability in advanced node manufacturing presents structural risk. Distribution runs through direct enterprise sales for automation platforms and cloud marketplaces for cognitive assistants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
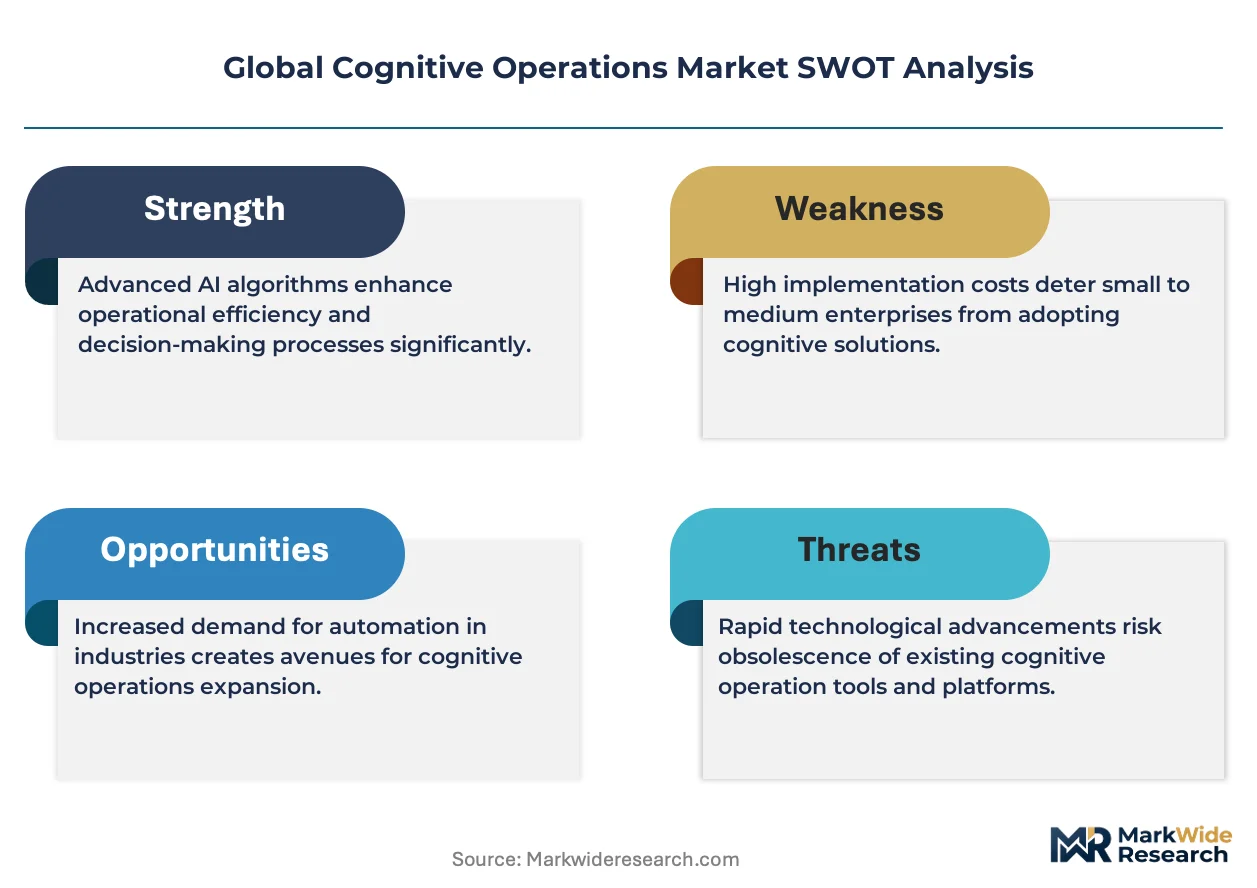
The acute shortage of site reliability engineers with hybrid Kubernetes and MLOps expertise is constraining deployment velocity and creating asymmetric returns for vendors with embedded professional services capabilities.
For Market Incumbents: Compound defensive moats by deepening FedRAMP authorization portfolios and embedding SOAR capabilities into core platforms. Vertical integration into lightweight edge inference hardware counters emerging specialists in manufacturing IoT. Certification investment in ISO/IEC 42001 documentation tooling addresses mid-market vendor displacement from compliance burdens.
For New Entrants and Emerging Players: Lead with unbundled cognitive assistant offerings targeting process manufacturing facilities in Brazil and Mexico where AI-operations coverage remains sparse. Cloud marketplace listings through AWS and Azure Marketplaces reduce customer acquisition friction against established direct sales organizations. Geographic expansion should prioritize German-speaking Mittelstand manufacturers undergoing digital transformation.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors full-stack observability platforms with native AI root-cause analysis over point-solution analytics vendors. Long-term viability favors vendors with hybrid cloud automation portfolios spanning regulated industries. Acquisition targets should demonstrate embedded audit trail capabilities for EU AI Act high-risk system requirements. Watch for inflection when SEC cybersecurity disclosure enforcement accelerates real-time anomaly detection procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies AIOps and FinOps capabilities for procurement consolidation trends in United States enterprises. |
| Acquisition of Specialist Firm | Adds edge inference expertise for manufacturing IoT deployments in German industrial clusters. |
| Strategic Partnership | Systems integrator alliances capture implementation revenues disintermediated from software vendors. |
| Geographic Expansion | Cloud marketplace listings in Singapore address Southeast Asian financial services hybrid deployment demand. |
| Product Launch | Lightweight quantization models enable air-gapped deployments for Japanese telecommunications 5G infrastructure. |
Research Methodology
Desk research of SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory guidance documents preceded structured interviews with platform engineering directors, IT procurement officers at money center banks, federal agency technology leads, and systems integrator partners. Primary fieldwork combined with secondary validation across FDA, NIST, and EMA regulatory databases. Bottom-up deployment estimates triangulated against top-down enterprise IT spending benchmarks.
Variance decomposition across solution offering, deployment model, use case, and end-user industry dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macro technology adoption curves. Forecast inputs incorporated telemetry volume growth assumptions from edge computing deployments and generative AI integration timelines.
The analysis sits within stated boundaries; outcomes outside sustained GPU supply availability, EU AI Act enforcement intensity, or federal zero-trust mandate timelines would require recalibration. Forecasts reflect documented assumptions regarding site reliability engineering labor supply and cloud egress cost trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Cloud Telecommunication AI Market
Artificial Intelligence (AI)
GCC Artificial Intelligence Market
Artificial Intelligence (AI)
Human-Computer Interaction (HCI) Market
Artificial Intelligence (AI)
Generative AI in Coding Market
Artificial Intelligence (AI)
Brain Machine Interface Market
Artificial Intelligence (AI)
Artificial Intelligence Chatbots Market
Artificial Intelligence (AI)
Autonomous Agents Market
Artificial Intelligence (AI)
NLP in Healthcare and Life Sciences Market
Artificial Intelligence (AI)
Asia-Pacific AI Orchestration Market
Artificial Intelligence (AI)
AI Search Engine Market
Artificial Intelligence (AI)
Global Voice Assistant Application Market
Artificial Intelligence (AI)
Artificial Intelligence for IT Operations (Aiops) Market
Artificial Intelligence (AI)
Far-Field Speech and Voice Recognition Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Oil and Gas Market
Artificial Intelligence (AI)
AI Development Service Market
Artificial Intelligence (AI)
Artificial Intelligence Systems Spending Market