
 Healthcare Cloud Computing Software Market | 2026-2036
Healthcare Cloud Computing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Cloud Computing Software Market Insights
Healthcare software distribution through value-added resellers and systems integrators is reconfiguring as direct cloud procurement gains share among provider networks. Amazon Web Services leverages its FedRAMP and HIPAA-compliant infrastructure to anchor large hospital system migrations. Microsoft competes through Azure API for FHIR integration, which positions its platform for interoperability mandates. IBM Corporation specializes in hybrid cloud orchestration for diagnostic labs managing multi-terabyte imaging workloads.
Healthcare cloud computing software encompasses virtualized compute, storage, and application layers delivered over networks to medical organizations, typically operating on shared or dedicated server clusters with encryption standards such as AES-256 for data at rest and TLS 1.3 for data in transit. Its primary purpose is to replace on-premises health IT infrastructure with elastic, remotely managed resources that reduce capital expenditure and accelerate deployment of clinical applications. Software as a Service dominates revenue contribution because electronic health record platforms and revenue cycle management tools command recurring subscription fees with high switching costs. Hybrid Cloud deployment models represent the fastest-expanding structural segment as hospitals balance latency-sensitive workloads on private nodes while bursting analytics to public infrastructure.
FDA guidance on cybersecurity in medical devices and HIPAA Security Rule enforcement by the Office for Civil Rights jointly elevate compliance spending across cloud procurement budgets. The EU AI Act and GDPR cross-border data transfer restrictions add jurisdictional complexity for multi-national health systems operating single cloud estates. Stakeholders must monitor evolving FedRAMP authorization baselines and state-level health data privacy laws to anticipate infrastructure certification requirements that will determine vendor eligibility.
Market Dynamics
Hospital CIOs now face simultaneous pressure from HIPAA Security Rule audits and AI-enabled diagnostic workloads, forcing infrastructure decisions that privilege hybrid architectures over pure public or private cloud deployments.
Growth Catalysts
- FHIR Interoperability Mandates:CMS rules requiring Fast Healthcare Interoperability Resources compliance push providers toward API-native cloud platforms that consolidate fragmented EHR systems.
- Diagnostic Imaging Volume Surge:PET-CT and MRI scan proliferation generates petabyte-scale storage demands that on-premises arrays cannot economically satisfy.
- Cybersecurity Insurance Requirements:Underwriters now mandate AES-256 encryption and SOC 2 Type II certification as prerequisites for coverage, accelerating certified cloud adoption.
Market Restraints
- Cross-Border Data Transfer Friction:GDPR Article 44 restrictions and Schrems II rulings complicate multi-national health system cloud consolidation into single estates.
- Specialized Talent Scarcity:Health informaticists with dual cloud architecture and clinical workflow expertise command compensation premiums that strain mid-market provider budgets.
- Legacy System Technical Debt:Decades-old HL7 v2 interfaces and custom EHR modules resist API abstraction, prolonging migration timelines.
Strategic Opportunities
- Edge Computing Convergence:5G-enabled surgical robotics and real-time patient monitoring create demand for distributed cloud nodes within hospital premises.
- FedRAMP Authorization Expansion:Federal healthcare facilities including VA hospitals represent underpenetrated demand for authorized cloud infrastructure.
- Genomics Pipeline Integration:CRISPR research workflows and population-scale biobanks require elastic compute that on-premises HPC clusters cannot provision.
Industry Challenges
- Multi-Cloud Orchestration Complexity:Health systems operating AWS, Azure, and private nodes simultaneously struggle with unified identity management and cost allocation.
- Incident Response Latency:HIPAA breach notification rules require 60-day disclosure windows, yet forensic analysis across distributed cloud environments often exceeds this threshold.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Cloud Computing Software Market |
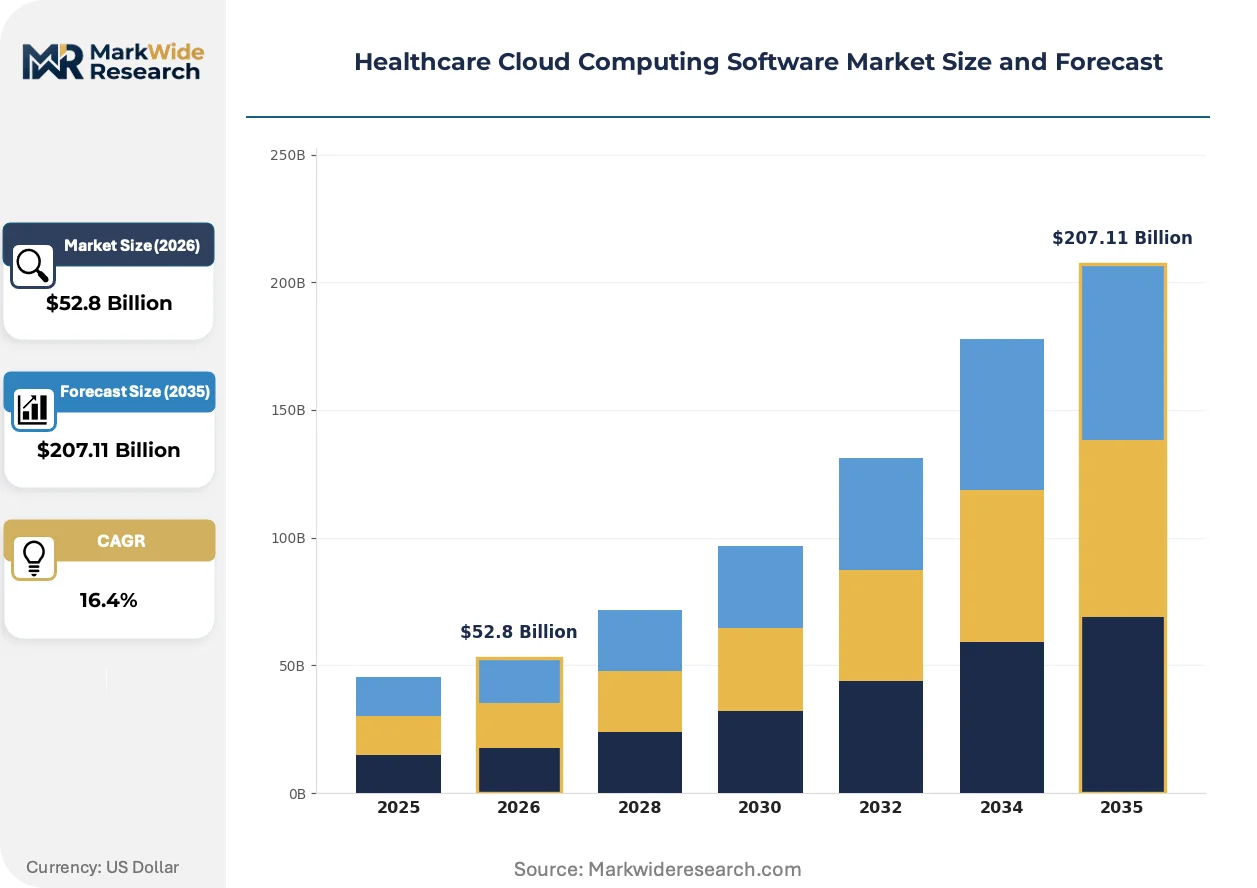
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $207.11 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Managed Services End User: Hospitals, Clinics, Diagnostic Labs, Telehealth Providers Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Application: Data Storage, Patient Management, Billing, Compliance Management |
| Companies Covered | Amazon Web Services, Microsoft, IBM Corporation, Oracle, Google, Athenahealth, CareCloud, Siemens Healthineers, ClearDATA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Cloud Computing Software Market Trends and Innovations
Container orchestration and serverless architectures are compressing deployment cycles for clinical applications, while regulatory pressure on algorithmic transparency reshapes how AI-enabled diagnostics reach production environments.
Serverless computing is collapsing the traditional provisioning gap between infrastructure request and clinical application deployment. Hospital IT departments at academic medical centers now spin up FHIR-enabled microservices in hours rather than months. This compression eliminates capital expenditure approval cycles that previously delayed pilot programs.
EU AI Act risk classification rules for medical device software force manufacturers to maintain algorithmic audit trails and human oversight protocols. Class III AI diagnostic tools must now demonstrate conformity assessment procedures before cloud deployment. German diagnostic imaging vendors are restructuring development pipelines to embed technical documentation requirements from initial architecture design.
Subscription-based procurement for clinical decision support tools is displacing perpetual license models that dominated EHR vendor relationships. IDN procurement committees now prioritize consumption-based pricing that scales with patient volume rather than fixed enterprise agreements. This shift is most pronounced in United States multi-hospital systems consolidating vendor relationships under centralized cloud contracts.
Healthcare Cloud Computing Software Market Segmentation
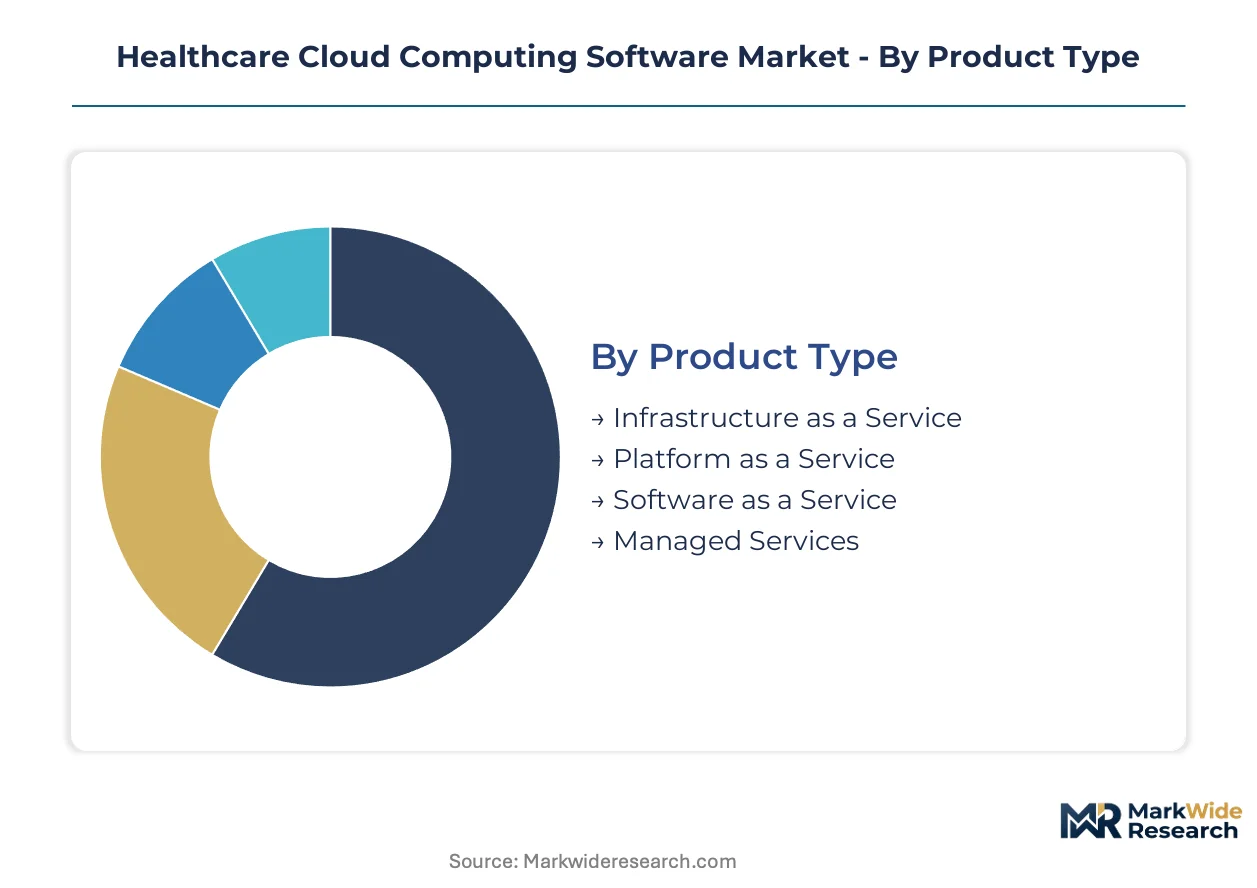
Healthcare cloud computing software segments diverge sharply in service intensity, with managed services requiring continuous clinical workflow optimization while infrastructure layers demand minimal post-deployment support. Understanding these support dynamics helps vendors allocate technical resources and price recurring revenue streams appropriately across the technology stack.
Product Type:
After-sales service intensity varies dramatically across cloud delivery models, with higher-touch segments commanding dedicated customer success teams and 24/7 clinical escalation protocols.
- Software as a Service:Electronic health record platforms and revenue cycle management tools operate on subscription models with embedded clinical workflow support. Hospital networks in the United States concentrate demand here due to HIPAA compliance requirements and the high switching costs of migrating patient data histories. Vendors embed certified health informaticists within account teams to manage FHIR integration and regulatory audit preparation.
- Managed Services:Third-party cloud operations teams assume full infrastructure management responsibility, including patch management, backup verification, and disaster recovery testing. Diagnostic labs with limited internal IT staff drive adoption, particularly for genomic sequencing pipelines requiring elastic compute orchestration beyond their technical capabilities. Service level agreements specify 99.99% uptime with financial penalties for clinical system unavailability.
- Infrastructure as a Service:Raw compute, storage, and networking resources delivered without application-layer management.
- Platform as a Service:Development environments and middleware enabling custom clinical application deployment.
Software as a Service holds the largest share; momentum sits with Managed Services as provider IT staffing constraints deepen.
End User:
Procurement sophistication and compliance burden scale inversely with organizational size, reshaping vendor sales motion and contract structure.
- Hospitals:Large health systems negotiate enterprise-wide cloud contracts consolidating previously fragmented departmental purchasing. Academic medical centers in the United States lead adoption of hybrid architectures, balancing latency-sensitive imaging workloads on private nodes while bursting analytics to public infrastructure. Procurement committees now mandate FedRAMP authorization and SOC 2 Type II certification as table stakes.
- Telehealth Providers:Virtual care platforms emerged as distinct cloud consumers with unique scalability requirements—traffic spikes during public health emergencies demand automatic provisioning without capital commitment. These organizations prioritize consumption-based pricing and API-native architectures enabling rapid feature deployment. HIPAA Business Associate Agreements with explicit breach notification timelines are non-negotiable contract terms.
- Clinics:Small and mid-size practices seeking turnkey solutions with minimal internal technical expertise.
- Diagnostic Labs:High-volume imaging and genomic testing facilities with petabyte-scale storage and compute demands.
Hospitals dominate current procurement volume; telehealth providers are expanding most quickly as virtual care reimbursement stabilizes.
Deployment Model:
Cost tier stratification separates capital-intensive private infrastructure from operational expenditure models, with hybrid configurations capturing mid-market budget flexibility.
- Hybrid Cloud:Combines dedicated private infrastructure for protected health information with public cloud bursting for analytics workloads. Hospital CIOs facing simultaneous HIPAA audit pressure and AI diagnostic deployment timelines gravitate toward this architecture. The model permits gradual migration of legacy HL7 v2 interfaces without wholesale system replacement.
- Multi-Cloud:Deliberate distribution across AWS, Azure, and specialized health cloud providers to avoid vendor lock-in and optimize workload placement. Large integrated delivery networks in the United States adopt this approach, though unified identity management and cost allocation across estates remain operational challenges. Regulatory compliance documentation must reconcile differing security control frameworks.
- Public Cloud:Shared infrastructure with encryption and access controls meeting healthcare regulatory requirements.
- Private Cloud:Single-tenant environments providing maximum data sovereignty and customization control.
Hybrid Cloud commands the dominant position; Multi-Cloud is gaining share fastest among consolidated health systems with sophisticated procurement functions.
Application:
Functional maturity and integration complexity determine implementation timeline and vendor selection criteria across clinical and administrative use cases.
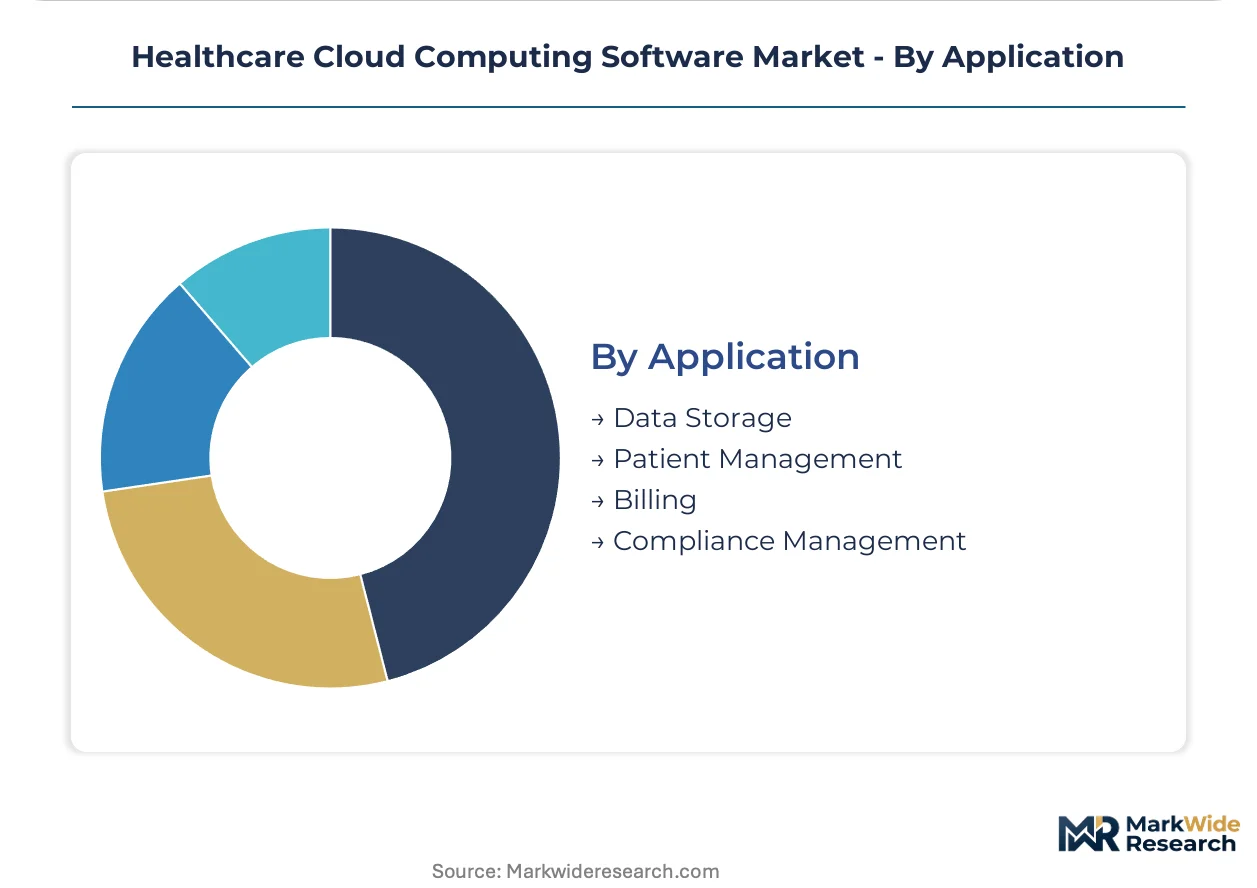
- Patient Management:Cloud-native electronic health record systems and care coordination platforms central to clinical operations. United States provider networks prioritize FHIR-enabled solutions satisfying CMS interoperability mandates. Real-time patient data access across affiliated facilities drives consolidation toward unified cloud estates.
- Compliance Management:Automated security monitoring, audit logging, and regulatory reporting tools addressing HIPAA Security Rule and state privacy law requirements. Cloud platforms now embed continuous compliance verification, with automated evidence collection for Office for Civil Rights investigations. Cybersecurity insurance underwriters increasingly mandate these capabilities as policy conditions.
- Data Storage:Scalable repositories for imaging, genomic, and longitudinal patient records.
- Billing:Revenue cycle management and claims processing systems with payer-specific rule engines.
Patient Management represents the largest application segment; Compliance Management shows the steepest expansion trajectory as regulatory enforcement intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA enforcement of the HIPAA Security Rule anchors demand concentration in the United States, where hospital system consolidation and FedRAMP-authorized procurement create structural advantages for certified cloud vendors. Regulatory divergence across jurisdictions fragments vendor eligibility requirements.
United States
Academic medical centers in Boston and the San Francisco Bay Area deploy hybrid architectures for latency-sensitive imaging workloads. CMS interoperability mandates accelerate FHIR-native platform procurement. The Texas Medical Center cluster drives petabyte-scale genomic data pipeline adoption.
Germany
Diagnostic imaging vendors restructure development pipelines to embed EU AI Act conformity assessments from initial design. The country's national pharmaceutical regulator enforces Class III AI diagnostic documentation requirements. Berlin-Brandenburg health technology clusters concentrate serverless clinical microservices deployment.
United Kingdom
NHS Digital transformation programs consolidate electronic health record estates toward API-native cloud platforms. The Medicines and Healthcare products Regulatory Agency aligns cybersecurity guidance with FDA medical device frameworks. London-based integrated care systems negotiate enterprise-wide cloud contracts.
Japan
Meti industrial policy incentivizes edge computing convergence for surgical robotics and real-time patient monitoring. The Pharmaceuticals and Medical Devices Agency accelerates cloud-enabled diagnostic software approval pathways. The Kanto region anchors hybrid cloud adoption for multi-terabyte imaging workloads.
India
Telehealth providers in Karnataka and Maharashtra prioritize consumption-based pricing for virtual care platform scalability. The Central Drugs Standard Control Organization harmonizes medical device software regulations with international standards. Hyderabad's health technology corridor concentrates FHIR integration development talent.
Healthcare Cloud Computing Software Market Competitive Landscape
Hyperscale cloud providers and health-specialized managed services firms split the market along compliance depth and workflow integration vectors. Vendor concentration remains high at the infrastructure layer while application-level competition fragments across niche clinical domains. Three archetypes dominate: FedRAMP-authorized hyperscalers, hybrid orchestration specialists, and vertical-specific SaaS platforms. Capacity expansion into sovereign cloud regions and strategic partnerships with electronic health record vendors constitute the primary competitive moves.
Within the hyperscale tier, Amazon Web Services and Microsoft exemplify infrastructure-first positioning anchored by federal authorization baselines. IBM Corporation occupies a position representing hybrid orchestration specialization for diagnostic workloads. These three entities collectively illustrate the compliance-certification barrier that structures vendor eligibility for hospital system procurement committees.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| IBM Corporation |
| Oracle |
| Athenahealth |
| CareCloud |
| Siemens Healthineers |
| ClearDATA |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in FedRAMP-authorized infrastructure across United States federal healthcare zones is driving hyperscalers toward premium positioning while mid-market providers absorb cost compression through managed service bundling. Hospital procurement committees now face extended vendor qualification timelines that inflate total cost of ownership even as unit compute prices stabilize.
Pricing Analysis
Geographic price spreads between United States and European cloud procurement have widened as GDPR compliance overhead and EU AI Act documentation requirements inflate European contract values. The dominant pricing structure is subscription-based SaaS with three-tier differentiation across premium FedRAMP-High, standard HIPAA-compliant, and economy-tier business associate agreement levels. Price differentiation hinges on certification grade and after-sales service intensity, with embedded clinical workflow support commanding substantial premiums. Cost compression in the economy tier is intensifying because telehealth providers prioritize consumption-based elasticity over fixed commitments. Small and mid-size clinics exhibit highest price sensitivity, while academic medical centers with consolidated IT budgets show least sensitivity to per-unit increases.
Supply Chain Analysis
Extended payment terms from hyperscale cloud providers to semiconductor foundries are reshaping working capital structures across the infrastructure layer. Geographic supply concentration centers on United States, Ireland, and Singapore for certified healthcare data center capacity, with Taiwan and South Korea anchoring specialized AI accelerator fabrication. Raw material dependencies include high-bandwidth memory modules, custom ASICs, and precision cooling systems. Single-source vulnerability in advanced node semiconductor manufacturing poses structural risk given concentration with TSMC. Distribution runs through direct enterprise sales teams and health-specialized systems integrators, with value-added resellers losing share to API-native procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare cloud computing software exhibits fragmentation opportunity as compliance complexity splinters demand across specialized vendor archetypes. The simultaneous pressure from HIPAA enforcement and AI diagnostic deployment creates niches for hybrid orchestration specialists between hyperscale infrastructure and clinical application layers.
For Market Incumbents: Pre-empt margin erosion from container-native entrants by embedding serverless clinical microservices into existing EHR partnerships. Acquire boutique FHIR integration firms to consolidate interoperability talent pools before CMS mandate deadlines tighten. FedRAMP authorization maintenance represents the critical defensive lever against unauthorized challengers.
For New Entrants and Emerging Players: Build out edge computing nodes for surgical robotics and real-time monitoring within hospital premises, where latency requirements exclude pure public cloud deployment. Target mid-market diagnostic labs with limited internal IT staff as the most penetrable segment, offering managed genomic pipeline orchestration. A go-to-market angle through existing laboratory information system vendors accelerates trust establishment.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed services providers with embedded clinical workflow expertise and multi-year hospital system contracts. Long-term viability across the next decade favors vendors with demonstrated cross-cloud orchestration capabilities rather than single-platform dependencies. Acquisition target archetype: hybrid cloud specialists with existing SOC 2 Type II certification and diagnostic imaging workload experience. The signal to watch as inflection indicator is Office for Civil Rights enforcement action frequency, which accelerates compliance-driven procurement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Expansion | Federal healthcare facilities including VA hospitals represent underpenetrated demand requiring certified infrastructure. |
| FHIR-Native Platform Development | CMS interoperability mandates accelerate API-first procurement from hospital networks consolidating fragmented EHR estates. |
| Hybrid Cloud Partnership | Diagnostic labs with petabyte-scale imaging workloads require orchestration between private nodes and public bursting. |
| Edge Computing Deployment | 5G-enabled surgical robotics and real-time monitoring create distributed cloud node demand within hospital premises. |
| Genomics Pipeline Integration | CRISPR research workflows and population-scale biobanks require elastic compute beyond on-premises HPC cluster capacity. |
Research Methodology
Initial hypotheses were tested against primary input from hospital CIOs, health informaticists, cloud procurement officers, and GPO contracts managers and refined through secondary validation. Primary research combined structured interviews with secondary sources including CMS Medicare data, hospital procurement databases, FedRAMP authorization repositories, and hyperscaler healthcare vertical disclosures. Bottom-up and top-down triangulation reconciled vendor-reported deployment metrics with provider-stated infrastructure spending patterns.
Demand-supply balance modeling anchored forecast construction, with segmentation across deployment model, organization size, clinical application, integration complexity, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical adoption rates and policy mandate timelines. Industry-specific forecast inputs included HIPAA audit frequency projections and FDA cybersecurity guidance evolution across the analysis window.
Practitioners should monitor regulatory enforcement intensity, cross-border data transfer rulings, and AI diagnostic classification determinations for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Bare Metal Cloud Service Market
Cloud Computing
Global Cloud Computing in Healthcare Market
Cloud Computing
China Cloud Computing Market
Cloud Computing
Cloud Data Warehouse Market
Cloud Computing
Latin America Cloud Computing Market
Cloud Computing
Cognitive Cloud Market
Cloud Computing
Hybrid Cloud Market
Cloud Computing
Web Scale IT Market
Cloud Computing
Global Cloud/Mobile Backend AS a Service (Baas) Market
Cloud Computing
Cloud ECS Market
Cloud Computing
Cloud-Managed LAN Market
Cloud Computing
Multi-Cloud Architecture Market
Cloud Computing
Cloud Directory Services Market
Cloud Computing
Commercial Cloud Market
Cloud Computing
France Cloud Computing Market
Cloud Computing
United States Cloud Computing Market