
 Clinical Risk Grouping Solutions Market | 2026-2036
Clinical Risk Grouping Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Risk Grouping Solutions Market Intelligence
The United States is rewriting competitive dynamics in clinical risk grouping as health systems invest heavily in predictive infrastructure. 3M leverages decades of coding classification expertise to anchor enterprise contracts with large payer organizations. Cerner Corporation sustains platform stickiness through deep EHR integration across hospital networks. Optum Inc competes by controlling end-to-end data pipelines from claims to care management workflows.
Clinical Risk Grouping Solutions comprise software platforms that stratify patient populations by morbidity burden using diagnostic codes, pharmacy claims, and social determinants of health data to generate risk scores for resource allocation and reimbursement. These systems employ hierarchical condition category mapping algorithms that process longitudinal patient records to predict future healthcare expenditures and clinical outcomes. Software and analytics segments dominate current revenue as health systems prioritize algorithmic risk scoring over standalone reporting tools. Cloud-based systems and SaaS deployment models are expanding fastest as IT departments seek to reduce on-premises infrastructure overhead while maintaining HIPAA-compliant data governance.
CMS Medicare Advantage risk adjustment audits, HIPAA privacy safeguards, and ONC interoperability certification requirements collectively shape product development roadmaps and vendor qualification criteria in the United States. FDA oversight of clinical decision support software introduces additional validation burdens for vendors embedding predictive algorithms into care workflows. Stakeholders must monitor evolving state-level Medicaid managed care regulations and value-based payment mandates to anticipate procurement cycles and compliance investments.
Market Dynamics
Medicare Advantage risk adjustment audits are intensifying documentation requirements for hierarchical condition categories, forcing health systems to rebuild their clinical data infrastructure around predictive scoring engines rather than retrospective reporting tools.
Growth Catalysts
- CMS Risk Adjustment Model Refinements:Annual updates to the hierarchical condition category methodology create recurring demand for algorithm recalibration services and staff retraining programs across Medicare Advantage plans.
- Value-Based Care Contract Proliferation:Commercial payers and state Medicaid agencies are embedding risk-adjusted quality metrics into reimbursement formulas, requiring providers to deploy population stratification tools for contract performance management.
- Cloud Migration Imperatives:Hospital IT departments are retiring on-premises data warehouses in favor of HIPAA-compliant SaaS architectures that reduce capital expenditure while enabling real-time risk score computation.
Market Restraints
- Specialized Talent Scarcity:Health informaticists with dual expertise in clinical coding and machine learning command premium compensation, constraining vendor expansion and health system internal build-outs.
- Interoperability Fragmentation:Inconsistent implementation of FHIR standards across EHR vendors forces expensive custom integration work for each new health system deployment.
- Regulatory Validation Burden:FDA oversight of clinical decision support software introduces 12-18 month validation timelines for algorithms embedded directly into care workflows, slowing product release cycles.
Strategic Opportunities
- Medicaid Managed Care Expansion:States converting fee-for-service Medicaid to managed care are procuring risk stratification platforms for the first time, creating greenfield demand outside the Medicare Advantage core.
- Social Determinants Integration:Convergence of clinical risk engines with housing instability, food security, and transportation data sources enables predictive models that anticipate utilization spikes before acute episodes.
- Pharmacy Claims Fusion:Vendors controlling both medical and pharmacy data pipelines can construct medication adherence risk scores that differentiate their offerings from diagnosis-only competitors.
Industry Challenges
- Legacy System Entrenchment:Decades-old patient accounting systems in community hospitals resist API-based data extraction, forcing manual abstraction workflows that degrade risk score accuracy and audit defensibility.
- Auditor-Grade Documentation Standards:CMS Medicare Advantage risk adjustment audits now require physician attestation of diagnosis specificity that EHR note templates rarely capture without workflow redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Risk Grouping Solutions Market |
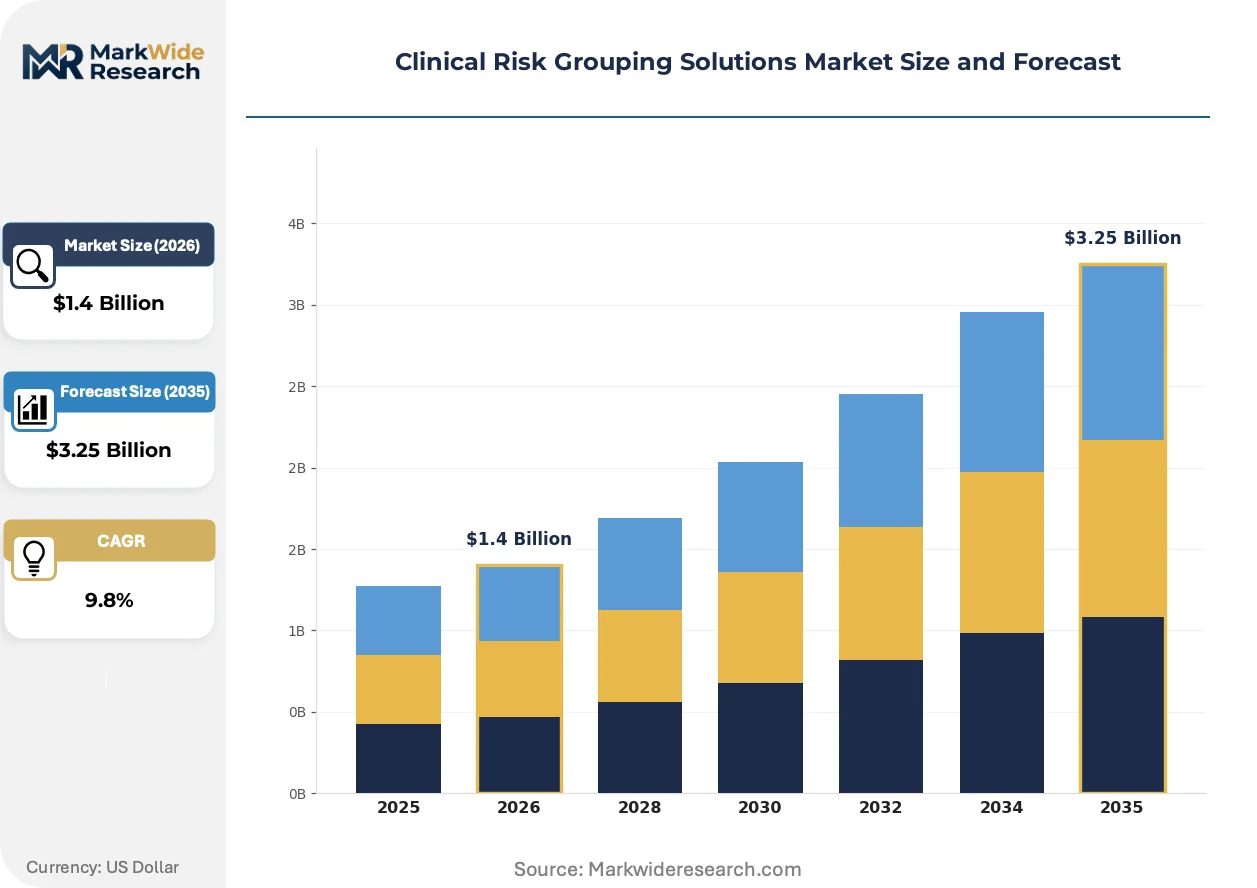
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Analytics, Reporting Tools, Risk Assessment Platforms End User: Healthcare Providers, Insurers, Payers, Clinics Technology: AI-Powered Solutions, Cloud-Based Systems, Data Lakes, Integration Tools Deployment: On-Premises, Cloud Deployment, Hybrid Solutions, SaaS |
| Companies Covered | Lightbeam Health Solutions, HBI Solutions, 3M, Cerner Corporation, Conduent Inc, Optum Inc, Health Catalyst, Reveleer, Nuance Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Risk Grouping Solutions Market Strategic Shifts & Innovations
Algorithmic risk scoring is migrating from retrospective annual calculations to continuous patient monitoring, embedding predictive signals directly into clinical decision workflows at the point of care.
Natural language processing engines are hybridizing structured diagnosis codes with unstructured clinical notes to identify undocumented hierarchical condition categories that traditional abstraction misses. Medicare Advantage plans with advanced deployments report 15-20% improvement in risk score capture rates compared to manual coding workflows. This capability is compressing the competitive advantage window for vendors lacking NLP infrastructure.
CMS continues tightening documentation requirements for hierarchical condition categories through annual risk adjustment model updates and expanded audit sampling methodologies. Health systems must now maintain auditable evidence of face-to-face evaluation for every diagnosis submitted to Medicare Advantage plans. The documentation burden falls heaviest on primary care networks with thin margins and limited coding specialist staffing.
Integrated delivery networks are consolidating vendor relationships around platforms that combine risk stratification with care management workflow tools rather than standalone scoring engines. Procurement teams favor end-to-end contracts that span data ingestion, score computation, and care team alerting over point solutions requiring internal integration. This preference shift is most visible in the Southeast and Midwest where health system consolidation has concentrated buying power among five to ten dominant regional players.
Clinical Risk Grouping Solutions Market Segmentation
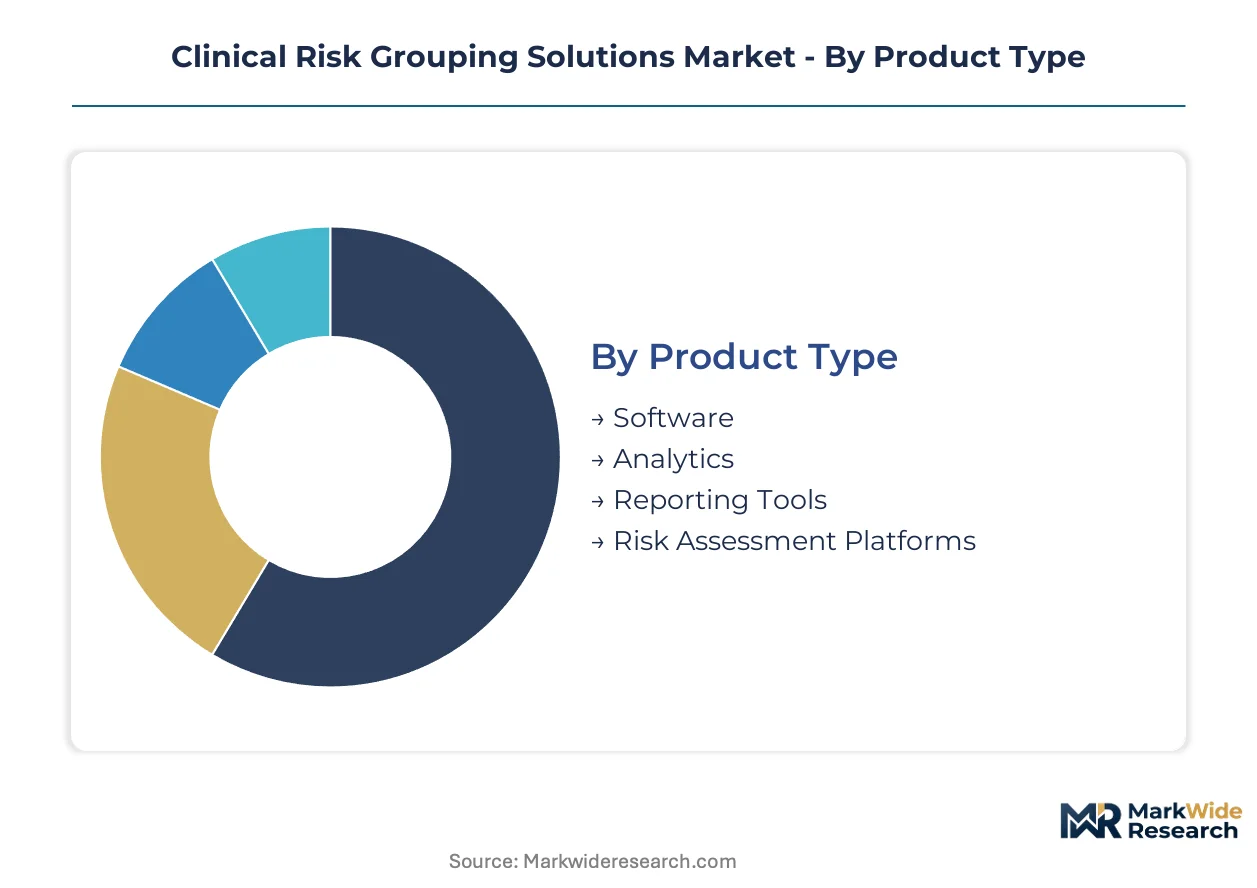
Clinical risk grouping solutions fragment across four distinct dimensions that shape procurement priorities and vendor positioning. Product architecture determines whether health systems purchase standalone tools or integrated platforms. Technology choices separate legacy deployments from AI-native architectures that process unstructured clinical data.
Product Type:
Cost tier separates point solutions from enterprise platforms that bundle multiple functional modules under unified contracts.
- Software:Core risk calculation engines execute hierarchical condition category mapping algorithms against structured claims and diagnosis data. Hospital systems in the United States prioritize software licenses that embed directly into existing EHR workflows rather than standalone applications requiring separate login credentials.
- Analytics:Predictive modeling layers consume longitudinal patient records to forecast utilization patterns and cost trajectories. Insurers concentrate demand here, using analytics outputs to set premium rates and design care management interventions for high-risk members.
- Reporting Tools:Static dashboards and retrospective scorecards for regulatory submission and internal performance review.
- Risk Assessment Platforms:Integrated suites combining scoring, documentation guidance, and audit preparation workflows.
Software holds installed capacity. Analytics is rotating up the share rankings.
End User:
Customer type dictates functional requirements, with providers prioritizing clinical workflow integration while payers emphasize population-level stratification accuracy.
- Healthcare Providers:Integrated delivery networks and hospital systems deploy risk grouping tools to optimize value-based contract performance and capture appropriate reimbursement under CMS risk adjustment models. Documentation support features rank highest in procurement evaluations.
- Insurers:Medicare Advantage plans and commercial carriers use population stratification to allocate care management resources and set reserve requirements.
- Payers:State Medicaid agencies and employer-sponsored plan administrators seeking audit-ready risk score documentation.
- Clinics:Smaller primary care networks with limited coding specialist staffing requiring automated abstraction assistance.
Healthcare Providers anchor current deployments. Payers are expanding procurement fastest as Medicaid managed care conversion accelerates.
Technology:
Maturity divides established data infrastructure from emerging AI architectures that process unstructured clinical notes.
- AI-Powered Solutions:Natural language processing engines extract undocumented hierarchical condition categories from physician notes, improving risk score capture rates substantially. Medicare Advantage plans with advanced deployments report measurable gains over manual coding workflows.
- Cloud-Based Systems:HIPAA-compliant SaaS architectures reduce capital expenditure while enabling real-time score computation. Hospital IT departments favor these for faster deployment timelines and reduced infrastructure overhead.
- Data Lakes:Centralized repositories consolidating medical claims, pharmacy records, and social determinants data for longitudinal analysis.
- Integration Tools:FHIR-based connectors and API middleware bridging risk engines with diverse EHR vendor environments.
Cloud-Based Systems dominate new deployments. AI-Powered Solutions are climbing the fastest as documentation requirements tighten.
Deployment:
Supply concentration clusters around cloud-native delivery models as health systems retire on-premises data warehouses.
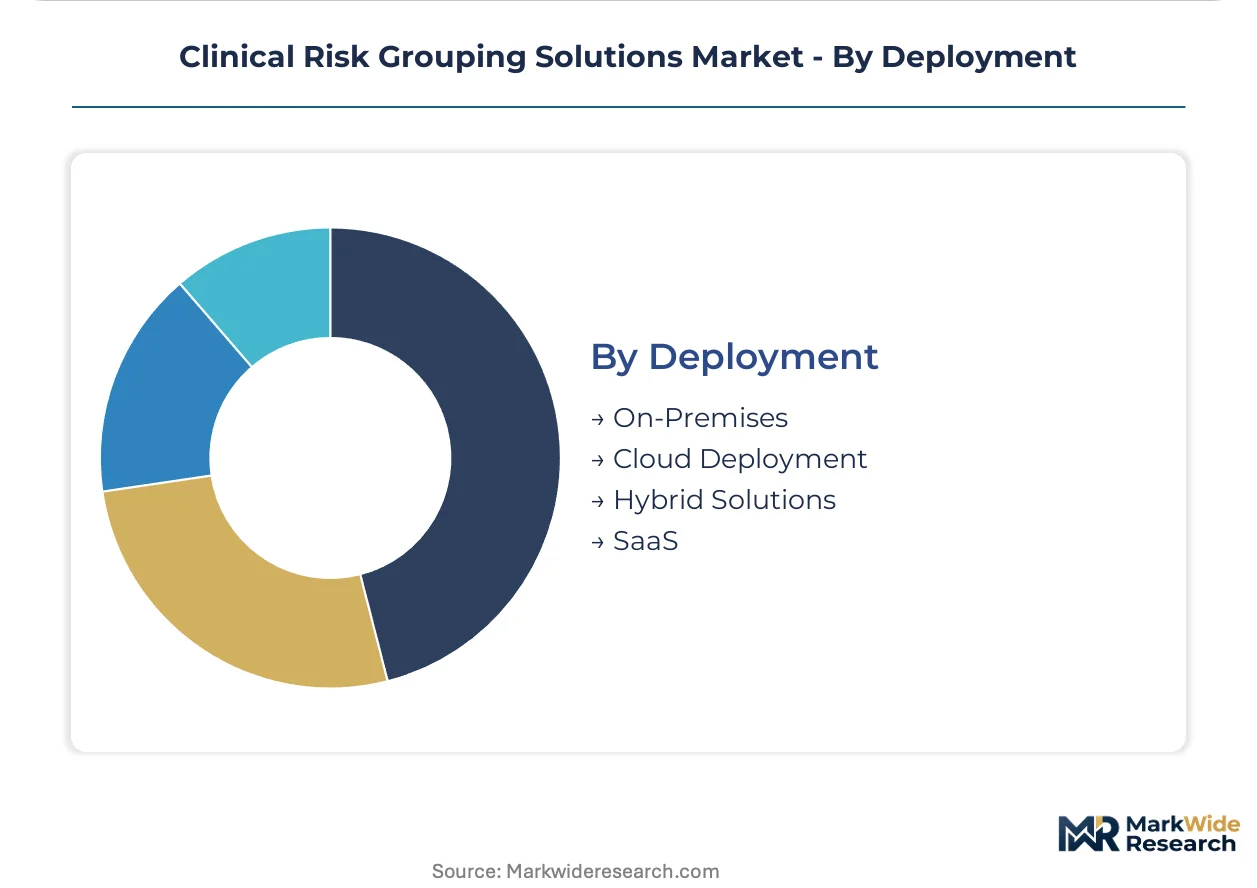
- On-Premises:Legacy installations in security-sensitive environments requiring complete data sovereignty. Community hospitals with decades-old patient accounting systems maintain these deployments despite higher total cost of ownership.
- Cloud Deployment:Fully managed SaaS offerings with automatic algorithm updates and elastic compute scaling. Large integrated delivery networks in the United States favor multi-tenant architectures that reduce per-member infrastructure costs.
- Hybrid Solutions:Split architectures keeping protected health information on-premises while pushing analytics workloads to cloud environments.
- SaaS:Subscription-based access to continuously updated risk models without capital equipment procurement.
Cloud Deployment holds installed capacity. SaaS is rotating up the share rankings as procurement teams prioritize operational expenditure models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor concentration clusters in the United States where CMS risk adjustment complexity drives premium pricing for algorithmic platforms. Health systems across multiple countries now replicate American deployment patterns as value-based payment models spread internationally.
United States
Medicare Advantage expansion and Medicaid managed care conversion generate sustained procurement demand from integrated delivery networks. CMS annual risk adjustment model updates force algorithm recalibration investments. The Southeast and Midwest concentrate buying power among dominant regional health systems consolidating vendor relationships.
Germany
Statutory health insurance funds adopt diagnosis-related group refinements requiring morbidity stratification tools. The EU AI Act imposes validation requirements on clinical decision support algorithms. Berlin and Munich anchor health IT procurement clusters where university hospitals pilot predictive analytics platforms.
United Kingdom
NHS Integrated Care Systems embed risk stratification into population health management frameworks. NHS England commissioning guidelines mandate standardized risk assessment methodologies. London and Greater Manchester concentrate digital health procurement where academic medical centers test AI-powered documentation tools.
Canada
Provincial health authorities implement patient-based funding models requiring accurate case mix measurement. Health Canada oversight of medical device software classification affects vendor market entry strategies. Ontario and Quebec anchor procurement concentration where hospital networks modernize legacy patient accounting infrastructure.
Australia
Activity-based funding reforms drive demand for casemix classification and risk adjustment capabilities. The Therapeutic Goods Administration regulates clinical decision support software as medical devices. New South Wales and Victoria concentrate health system procurement where public hospitals evaluate cloud-native risk scoring platforms.
Clinical Risk Grouping Solutions Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying algorithm modules and data connectors. Market structure tilts toward consolidation as integrated delivery networks favor end-to-end contracts over point solutions. Three archetypes dominate: EHR-embedded platforms, payer-owned analytics divisions, and independent risk-scoring specialists. Competitive dynamics center on strategic partnerships bridging data pipeline gaps and portfolio diversification into adjacent care management workflows.
Within the independent specialist tier, Lightbeam Health Solutions and HBI Solutions exemplify vendors competing through focused risk stratification expertise rather than broad platform scope. 3M anchors the legacy classification segment, leveraging decades of coding infrastructure relationships. These three entities occupy distinct competitive positions: Lightbeam and HBI represent agile specialists targeting mid-market health systems, while 3M exemplifies entrenched incumbents defending enterprise contracts through installed base stickiness and regulatory compliance depth.
| Leading Market Players |
|---|
| Lightbeam Health Solutions |
| HBI Solutions |
| 3M |
| Cerner Corporation |
| Conduent Inc |
| Optum Inc |
| Health Catalyst |
| Reveleer |
| Nuance Communications |
| Others |
Cost & Logistics Intelligence
Overcapacity in cloud infrastructure across North American data centers is compressing SaaS hosting costs and enabling vendors to absorb algorithm recalibration expenses without passing full cost burdens to health systems, reshaping competitive pricing postures across deployment tiers.
Pricing Analysis
CMS Medicare Advantage risk adjustment audits dictate the pricing tier structure across the Clinical Risk Grouping Solutions Market, with vendors stratifying offerings by audit-readiness certification depth. Three-tier pricing structure across premium, standard, and economy levels separates enterprise platforms with NLP-enabled documentation guidance from basic scoring engines and retrospective reporting tools. Cost compression in the standard tier is intensifying because mid-market health systems demand SaaS flexibility without premium workflow integration. Medicaid managed care agencies exhibit highest price sensitivity due to constrained state procurement budgets, while Medicare Advantage plans show lowest sensitivity given direct revenue linkage to risk score accuracy.
Supply Chain Analysis
Upstream feedstock for clinical risk grouping platforms draws from specialized health informatics talent pools concentrated in the United States, India, and Ireland, where clinical coding expertise intersects with machine learning engineering. Core components include NLP model training data, FHIR-compliant API middleware, and HIPAA-certified cloud infrastructure. Single-source vulnerability runs through concentrated EHR vendor partnerships that gate data pipeline access. Distribution runs through direct enterprise sales teams targeting integrated delivery networks and channel partnerships with GPOs serving smaller hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across Medicaid managed care procurement creates specialist niches as states convert fee-for-service programs, generating demand pockets underserved by Medicare-centric platform architectures.
For Market Incumbents: Build regulatory compliance moats through FDA 510(k) pre-submission pathways for clinical decision support algorithms and CMS ONC certification maintenance. Consolidate position by acquiring NLP documentation specialists before they scale independent audit-prep workflows. Threat substitution from EHR-native risk modules demands deeper EHR API control as defensive priority. For New Entrants and Emerging Players: State Medicaid agencies in the Southeast and Midwest represent the most penetrable entry point, where managed care conversion lags Medicare Advantage sophistication and procurement cycles remain uncommitted to incumbent platforms. Target community hospital networks with hybrid deployment models bridging legacy patient accounting systems to cloud-native scoring engines. Go-to-market angle: automated abstraction tools addressing thin-margin primary care coding specialist shortages. For Investors and Strategic Acquirers: Capital is best deployed toward vertical specialists controlling pharmacy-medical data fusion capabilities, where longitudinal medication adherence signals differentiate risk models from diagnosis-only competitors. Long-term viability hinges on platform stickiness through care management workflow integration rather than standalone scoring utility. Watch for inflection when CMS expands social determinants of health data requirements into risk adjustment models.| Strategic Initiative | Industry Significance |
|---|---|
| NLP Documentation Engine Launch | Captures undocumented hierarchical condition categories that manual coding workflows miss, directly improving audit-defensible risk scores. |
| Pharmacy Claims Data Partnership | Enables medication adherence risk scoring that differentiates offerings from diagnosis-only competitors in Medicare Advantage. |
| Medicaid Managed Care Expansion | Accesses greenfield state procurement cycles outside saturated Medicare Advantage core with tailored SaaS pricing. |
| FHIR-Based EHR Integration | Reduces custom implementation costs per health system deployment, accelerating sales velocity in fragmented EHR environments. |
| Social Determinants Data Fusion | Anticipates utilization spikes before acute episodes, aligning with CMS trajectory toward broader risk adjustment inputs. |
Research Approach
A spread of perspectives from health informatics officers, Medicare Advantage plan actuaries, CMS policy specialists, and hospital IT procurement managers converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) databases, CMS Medicare Advantage rate announcement filings, and hospital GPO contract disclosures. Bottom-up sizing of vendor-reported deployments triangulated against top-down spend analysis across Medicare Advantage and Medicaid managed care programs.
Demand-supply balance modeling anchored the analytical framework across the projection horizon, with segmentation dimensions spanning deployment architecture, end-user type, technology maturity, and geographic regulatory cluster. CAGRs derived from algorithmic curve-fitting against historical adoption patterns in comparable health IT categories. Forecast inputs incorporated CMS annual risk adjustment model update schedules and state Medicaid managed care conversion timelines without year-specific pinning.
Macroeconomic conditions sit as an overlay; deviation in federal healthcare reimbursement policy or state Medicaid funding allocations would shift the trajectory materially. Cross-checking against CMS Medicare Advantage rate announcement benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Global Patient Safety and Risk Management Softwares Market
Risk Management and Compliance
Asset Liability Management (ALM) Solution Market
Risk Management and Compliance
United States Strategic Consulting Services Market
Risk Management and Compliance
Global Strategy Consulting Market
Risk Management and Compliance
AI in Fraud Management Market
Risk Management and Compliance
Asia-Pacific Compliance and Traceability Solutions Market
Risk Management and Compliance
Travel Risk Management Services Market
Risk Management and Compliance
Governance, Risk and Compliance Platform Market
Risk Management and Compliance
Cyber Security in BFSI Market
Risk Management and Compliance
BFSI Crisis Management Market
Risk Management and Compliance
Asia-Pacific Operational Risk Management Consulting Services in Manufacturing Market
Risk Management and Compliance
Global Risk Management Software Market
Risk Management and Compliance
Legal Advisory Service Market
Risk Management and Compliance
Operations Advisory Service Market
Risk Management and Compliance
Enterprise Governance, Risk, and Compliance (Egrc) Market
Risk Management and Compliance
Risk Assessment Software Market