
 BFSI Crisis Management Market | 2026-2036
BFSI Crisis Management Market Size, Share, and Industry Trends Forecast 2026-2036
BFSI Crisis Management Market Intelligence
The BFSI crisis management landscape is rebalancing between premium integrated suites and commodity point solutions as buyer procurement criteria diverge sharply. IBM Corporation leverages its hybrid cloud footprint to anchor enterprise-grade resilience orchestration for tier-one banks. MetricStream sustains competitive positioning through specialized governance-risk-compliance modules that dominate regulated insurance verticals.
BFSI crisis management encompasses the systematic identification, response coordination, and operational recovery protocols that financial institutions deploy to maintain continuity during cyber incidents, natural disasters, or systemic market disruptions, typically integrating real-time alerting, scenario modeling, and regulatory reporting workflows. Incident response services command the largest share of current expenditure as ransomware frequency against banking infrastructure escalates. Recovery planning is expanding fastest among credit unions and regional banks that previously underinvested in business continuity architecture.
EU regulators enforce DORA compliance deadlines while the Federal Reserve and OCC mandate operational resilience standards for US systemically important banks, collectively elevating software procurement above discretionary spend thresholds. The SEC's disclosure rules for material cybersecurity incidents add parallel compliance layers for investment firms and asset managers. Stakeholders must monitor how divergent jurisdictional timelines for resilience certification reshape vendor qualification requirements and cross-border service delivery models.
Market Dynamics
The BFSI crisis management market is reconfiguring around regulatory fragmentation as the EU Digital Operational Resilience Act and US Federal Reserve operational resilience standards impose divergent compliance architectures on multinational banking groups. Technology refresh cycles are compressing as institutions race to meet certification deadlines.
Growth Catalysts
- DORA implementation timelines:EU banks must operationalize resilience testing frameworks by January 2025, forcing immediate procurement of integrated incident response platforms and scenario modeling tools.
- Ransomware frequency against payment infrastructure:Real-time gross settlement systems and SWIFT networks face escalating attack sophistication, mandating 24/7 security operations center upgrades.
- Cloud-native architecture migration:Hybrid and multi-cloud deployments require new orchestration layers for crisis coordination across distributed environments.
Market Restraints
- Specialized talent scarcity:Cyber resilience architects and operational risk modelers command premium compensation, constraining mid-tier institution buildouts.
- Legacy system integration friction:Core banking platforms running COBOL-based infrastructure resist API connectivity with modern crisis management suites.
- Vendor concentration in incident response:Three dominant platform providers control critical orchestration middleware, creating single-source dependency risks.
Strategic Opportunities
- Credit union segment underpenetration:Smaller cooperative banks in the United States lack dedicated resilience officers, presenting managed service entry points.
- AI-driven predictive scenario modeling:Machine learning convergence with historical loss databases enables forward-looking stress testing beyond reactive protocols.
- SEC cybersecurity disclosure mandates:Material incident reporting requirements for investment advisors create compliance software demand previously absent in wealth management.
Industry Challenges
- Cross-border regulatory reconciliation:Institutions operating across EU and US jurisdictions face conflicting resilience certification timelines and testing methodologies.
- Tabletop exercise fatigue:Mandatory scenario drills consume executive bandwidth without delivering measurable operational improvements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BFSI Crisis Management Market |
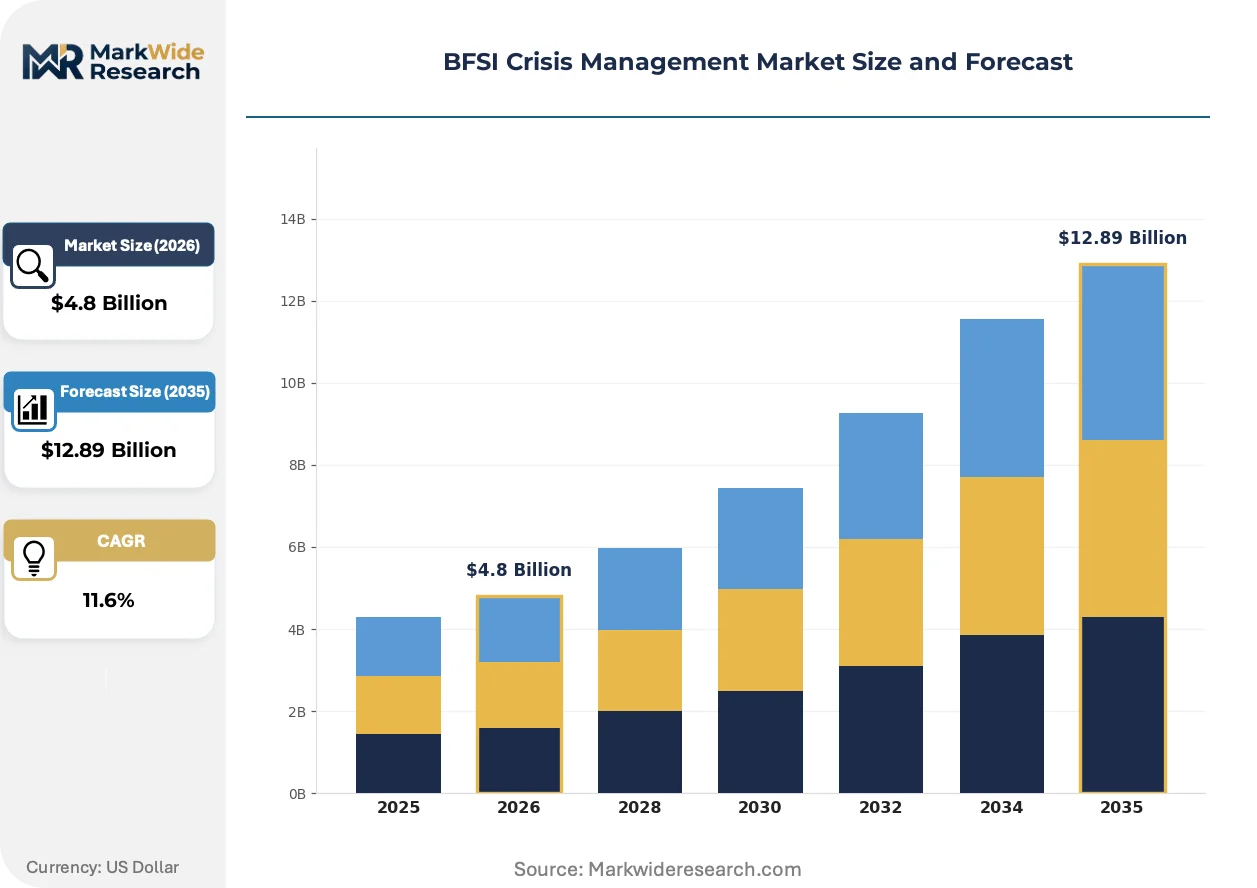
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Risk Assessment, Communication Planning, Incident Response, Recovery Planning Client Type: Banking Institutions, Insurance Providers, Investment Firms, Credit Unions Engagement Type: Consulting, Training, Software Solutions, Compliance Services Industry Vertical: Commercial Banking, Wealth Management, Asset Management, Financial Technology |
| Companies Covered | IBM Corporation, MetricStream, Inc., LogicGate, Inc., 4C Strategies, SAS Institute Inc., Everbridge, NCC Group plc, Noggin, Deloitte Touche Tohmatsu Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BFSI Crisis Management Market Strategic Shifts & Innovations
Automation is penetrating crisis response workflows as institutions seek to compress detection-to-recovery intervals. Three developments are reshaping competitive requirements.
Generative AI is rewriting crisis communication protocols. Large language models now draft regulatory notifications and stakeholder briefings within minutes of incident detection. Tier-one banks in London and New York are deploying these tools for board-level reporting. The technology is compressing the gap between technical response and executive decision-making.
EU regulators finalized DORA technical standards in 2024, mandating threat-led penetration testing for all critical ICT third-party providers. Cloud service providers serving EU banks must now obtain resilience certification from national competent authorities. German and French supervisors are conducting the first wave of compliance audits, with Dutch and Italian regulators following in 2025.
Subscription-based resilience platforms are displacing perpetual license models among regional banks. Credit unions in the United States Midwest and community banks in the United Kingdom are adopting SaaS incident response tools to avoid capital expenditure approval cycles. This shift is visible most acutely in institutions with assets below fifty billion dollars.
BFSI Crisis Management Market Segmentation
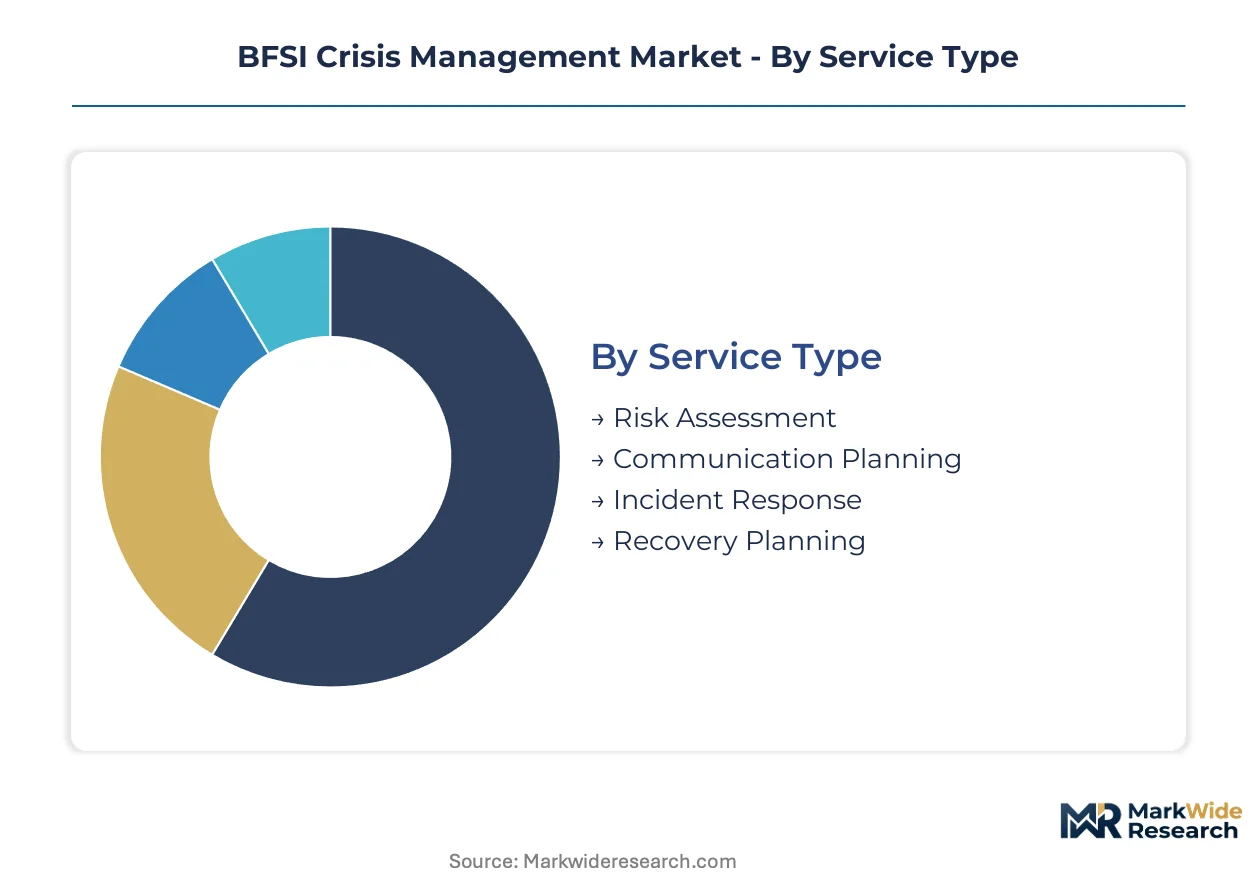
BFSI crisis management procurement diverges sharply by institutional scale and regulatory exposure. Segment boundaries determine whether vendors pursue enterprise license deals or subscription-based managed services.
Service Type:
Capital intensity concentrates in platforms requiring continuous infrastructure investment rather than episodic consulting engagements.
- Incident Response:Real-time orchestration platforms integrate security operations center workflows with automated escalation protocols. Banking institutions in the United States and Germany dominate procurement as ransomware targeting payment infrastructure intensifies.
- Recovery Planning:Business continuity architecture spans data center failover, cloud workload restoration, and branch network reactivation. Credit unions and regional banks previously underinvested in this capability, creating backlog demand.
- Risk Assessment:Stress testing and scenario modeling services evaluate operational resilience against defined threat vectors.
- Communication Planning:Stakeholder notification frameworks coordinate regulatory disclosure and customer outreach during active incidents.
Incident Response absorbs the bulk of installed capacity; Recovery Planning is expanding most quickly.
Client Type:
Procurement sophistication scales with balance sheet size and supervisory scrutiny intensity.
- Banking Institutions:Tier-one banks deploy integrated resilience suites across hybrid cloud environments. United Kingdom and German institutions face overlapping DORA and national competent authority mandates.
- Insurance Providers:Governance-risk-compliance modules dominate purchasing, with specialized focus on Solvency II operational continuity requirements.
- Investment Firms:SEC cybersecurity disclosure rules are driving first-time procurement among asset managers and wealth advisors.
- Credit Unions:Smaller cooperative banks lack dedicated resilience officers, creating managed service entry points in the United States Midwest.
Banking Institutions command the deepest vendor relationships; Credit Unions are gaining share fastest as SaaS platforms penetrate the mid-market.
Engagement Type:
Revenue predictability favors recurring models over project-based delivery.
- Software Solutions:Cloud-native platforms deliver continuous monitoring, automated playbook execution, and regulatory reporting dashboards.
- Consulting:Advisory engagements span resilience strategy, third-party risk assessment, and certification preparation.
- Training:Executive tabletop exercises and technical certification programs address capability gaps.
- Compliance Services:Outsourced DORA and Federal Reserve operational resilience documentation support.
Software Solutions generate the most recurring revenue; Compliance Services are climbing the fastest as certification deadlines approach.
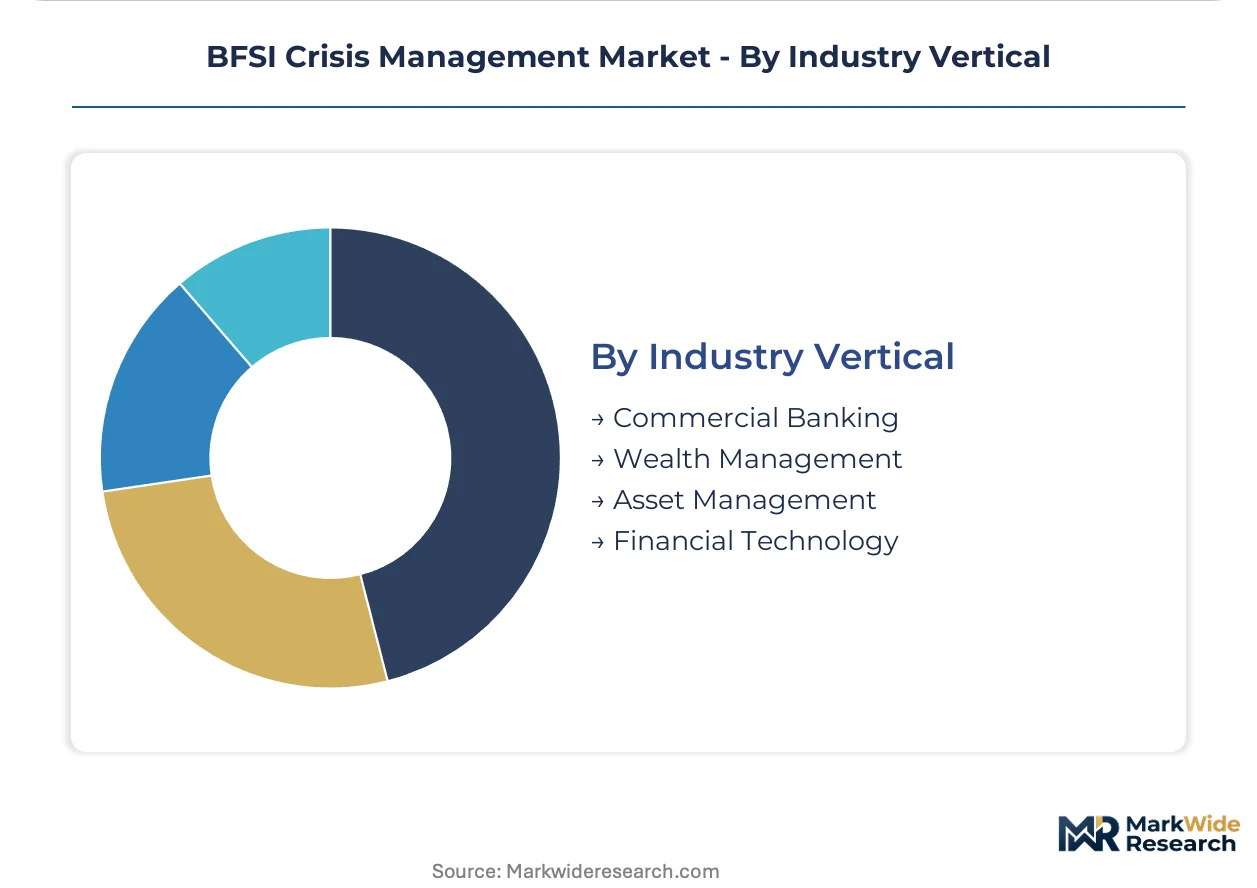
Industry Vertical:
Technology refresh cycles vary by exposure to real-time payment systems and customer-facing digital channels.
- Commercial Banking:Core banking platforms require legacy integration for crisis orchestration, constraining vendor selection.
- Financial Technology:Cloud-native architecture enables faster deployment of resilience automation, though third-party provider concentration creates new vulnerabilities.
- Wealth Management:SEC disclosure mandates are reshaping procurement priorities for registered investment advisors.
- Asset Management:Operational resilience for fund administration and custody operations lags banking sector investment.
Commercial Banking carries the heaviest legacy integration burden; Financial Technology is on the steepest expansion trajectory for cloud-native resilience tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London anchors procurement intensity for BFSI crisis management platforms, with Canary Wharf banking clusters driving enterprise-grade resilience software adoption. The United States, United Kingdom, Germany, Japan, and Singapore concentrate regulatory pressure and technology investment.
United States
Banking institutions in New York and Chicago dominate procurement of incident response platforms as ransomware targeting payment infrastructure escalates. The Federal Reserve and OCC mandate operational resilience standards for systemically important banks. Texas regional banks are accelerating SaaS adoption to bypass capital expenditure approval cycles.
United Kingdom
Tier-one banks in the City of London deploy integrated resilience suites across hybrid cloud environments. The Prudential Regulation Authority enforces operational continuity requirements overlapping with EU DORA mandates. Edinburgh-based insurance groups are expanding governance-risk-compliance module procurement.
Germany
Frankfurt's banking concentration drives demand for scenario modeling tools and threat-led penetration testing services. BaFin conducts the first wave of DORA compliance audits for critical ICT third-party providers. Munich insurance headquarters sustain specialized vendor relationships for Solvency II alignment.
Japan
Tokyo financial institutions invest in cloud-native crisis orchestration as METI guidelines harden operational resilience expectations. The Financial Services Agency mandates business continuity testing for systemically important banks. Osaka regional banks lag in recovery planning investment, creating backlog demand.
Singapore
Wealth management firms in the Marina Bay district adopt SEC-aligned disclosure tools for cross-border regulatory consistency. The Monetary Authority of Singapore operationalizes resilience frameworks for digital payment infrastructure. Fintech clusters in One-North drive fastest cloud-native resilience tool deployment.
BFSI Crisis Management Market Key Industry Players
Premium-margin players sit above commodity-margin players across integration depth and regulatory certification breadth. Three strategic archetypes dominate: enterprise-grade platform orchestrators, specialized governance-risk-compliance module providers, and managed service entrants targeting mid-market institutions. Consolidation pressure intensifies as certification requirements narrow vendor qualification pools. M&A activity concentrates on incident response automation capabilities; strategic partnerships bridge legacy system integration gaps.
Within the enterprise platform tier, IBM Corporation and SAS Institute Inc. represent integrated-suite positioning. MetricStream, Inc. exemplifies specialized governance-risk-compliance anchoring. Among advisory-anchored providers, Deloitte Touche Tohmatsu Limited occupies a position spanning consulting and technology implementation.
| Leading Market Players |
|---|
| IBM Corporation |
| MetricStream, Inc. |
| LogicGate, Inc. |
| 4C Strategies |
| SAS Institute Inc. |
| Everbridge |
| NCC Group plc |
| Noggin |
| Deloitte Touche Tohmatsu Limited |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up incident response specialists dominate the vendor landscape, concentrating pricing power among three platform orchestrators while compressing procurement cycles for mid-tier institutions. This ownership pattern tightens margin discipline across subscription tiers and forces legacy system integrators into defensive bundling strategies.
Pricing Analysis
Value-based pricing anchored to uptime guarantees and mean-time-to-recovery metrics commands premium positioning among tier-one banks. Three-tier pricing structure across enterprise, mid-market, and credit union levels reflects certification breadth and regulatory jurisdiction coverage. Pricing pressure stems from SaaS commoditization in the sub-fifty-billion-asset segment, where procurement officers prioritize operational expenditure flexibility over feature depth. Credit unions exhibit highest price sensitivity; systemically important banks demonstrate lowest, accepting long-term enterprise licenses for integrated resilience orchestration.
Supply Chain Analysis
Domestic-content mandates in EU member states and US federal procurement rules are reshaping third-party risk management sourcing, requiring residency-certified cloud infrastructure for critical ICT providers. Software development concentrates in the United States, Ireland, and India; threat intelligence feeds originate from Israeli and British cybersecurity clusters. The supply chain draws from specialized cloud infrastructure, historical loss databases, and regulatory content libraries. Single-source vulnerability in orchestration middleware creates systemic dependency exposure. Distribution runs through direct enterprise sales teams and hyperscaler marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as DORA certification deadlines and Federal Reserve operational resilience standards force sub-scale vendors out of qualified supplier pools.
For Market Incumbents: Anticipate regulatory qualification narrowing by acquiring specialized scenario modeling capabilities before certification windows close. IBM Corporation and MetricStream should deepen vertical integration into threat intelligence feeds to lock out mid-market challengers. Defensive patent positioning around AI-driven playbook automation will secure renewal pricing power against SaaS entrants.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in credit union managed services offers white-space entry below incumbent minimum contract values. Target United States Midwest cooperative banks with subscription-based resilience officers-as-a-service. Penetrate wealth management compliance services for SEC cybersecurity disclosure mandates, where incumbent platforms lack specialized advisor workflows.
For Investors and Strategic Acquirers: First-wave DORA audit failures among critical ICT third-party providers is the leading indicator that consolidation acceleration will concentrate through 2026. Over a five-to-ten-year horizon, platforms with dual EU-US certification coverage will outlast single-jurisdiction specialists. Monitor BaFin and PRA enforcement actions as early signals of vendor qualification pool contraction.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | DORA and Federal Reserve dual compliance opens tier-one banking procurement pipelines. |
| AI-Driven Playbook Automation | Generative AI compression of detection-to-recovery intervals differentiates platform tiers. |
| Managed Service Expansion | Resilience-officer-as-a-service penetrates credit union price sensitivity barriers. |
| Threat Intelligence Integration | Real-time attack surface monitoring binds customers to orchestration platforms. |
| Geographic Certification Footprint | BaFin, PRA, and OCC coverage qualifies vendors for multinational banking groups. |
Research Approach
Multi-period observation of regulatory filing patterns, procurement announcement velocity, and third-party risk management spend anchored the trend analysis, supplemented by interviews with chief risk officers, resilience program directors, regulatory affairs leads at national competent authorities, and SaaS procurement officers at regional banks. Secondary validation drew from SEC disclosure databases, EBA stress test publications, Federal Reserve supervision letters, and DORA technical standard drafts. Bottom-up vendor revenue triangulation against top-down institutional spend estimates calibrated market sizing.
Segment-weighting across service type, client type, engagement model, and industry vertical determined value distribution throughout the forecast period. CAGRs derived from technology refresh cycle compression rates and regulatory deadline clustering effects. Scenario modeling adoption curves and ransomware incident frequency against payment infrastructure informed growth trajectory assumptions.
Underlying measurement precision varies by segment; incident response platforms carry tighter precision than recovery planning consulting due to disclosed contract values. Forecasts reflect assumptions about certification timeline adherence and threat actor sophistication progression. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Disclosure Management Market
Risk Management and Compliance
Europe BFSI Biometrics Market
Risk Management and Compliance
Risk-Based Monitoring Software Market
Risk Management and Compliance
Digital Risk Management Market
Risk Management and Compliance
Pre Trade Risk Management Solution Market
Risk Management and Compliance
Legal Advisory Service Market
Risk Management and Compliance
Enterprise Governance, Risk, and Compliance (Egrc) Market
Risk Management and Compliance
Vendor Risk Management Market
Risk Management and Compliance
Loan Compliance Management Software Market
Risk Management and Compliance
BFSI Security Market
Risk Management and Compliance
Asia-Pacific BFSI Biometrics Market
Risk Management and Compliance
Clinical Risk Grouping Solutions Market
Risk Management and Compliance
Cyber Security in BFSI Market
Risk Management and Compliance
North America BFSI Biometrics Market
Risk Management and Compliance
Operational Risk Management Consulting Services in Manufacturing Market
Risk Management and Compliance
Employee Benefits Strategy and Consulting Market