
 Asset Liability Management (ALM) Solution Market | 2026-2036
Asset Liability Management (ALM) Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Asset Liability Management (ALM) Solution Market Outlook
Pension fund demand is restructuring the ALM solution landscape as defined-benefit schemes grapple with duration-matching complexities. Finastra International Limited leverages its treasury management heritage to anchor European pension fund contracts. Moody's Corporation sustains competitive differentiation through integrated credit risk analytics within ALM workflows. SAS Institute Inc specializes in stress-testing engines that dominate North American bank procurement cycles.
Asset Liability Management solutions constitute integrated software platforms that model interest rate risk, liquidity gaps, and capital adequacy through stochastic simulation engines and scenario analysis frameworks. These systems enable financial institutions to match asset durations against liability obligations while optimizing net interest margin under regulatory constraints. Cloud-based deployment is expanding fastest among mid-market banks seeking elastic compute for overnight risk runs without on-premises infrastructure overhead. Software solutions command the deepest margin pools due to recurring license structures and embedded regulatory update cycles. Managed services are maturing as a segment where Wolters Kluwer N V and Fiserv Inc compete on compliance outsourcing depth rather than proprietary analytics.
The European Banking Authority's IRRBB guidelines, the US Federal Reserve's CCAR stress-testing regime, and the Basel Committee's NSFR standards collectively shape product roadmaps and procurement urgency across institutional tiers. SAP SE and Oracle Corporation navigate these frameworks by embedding regulatory interpretation layers directly into platform architectures. Stakeholders must monitor how AI-driven scenario generation reshapes vendor differentiation before the next Basel revision cycle.
Market Dynamics
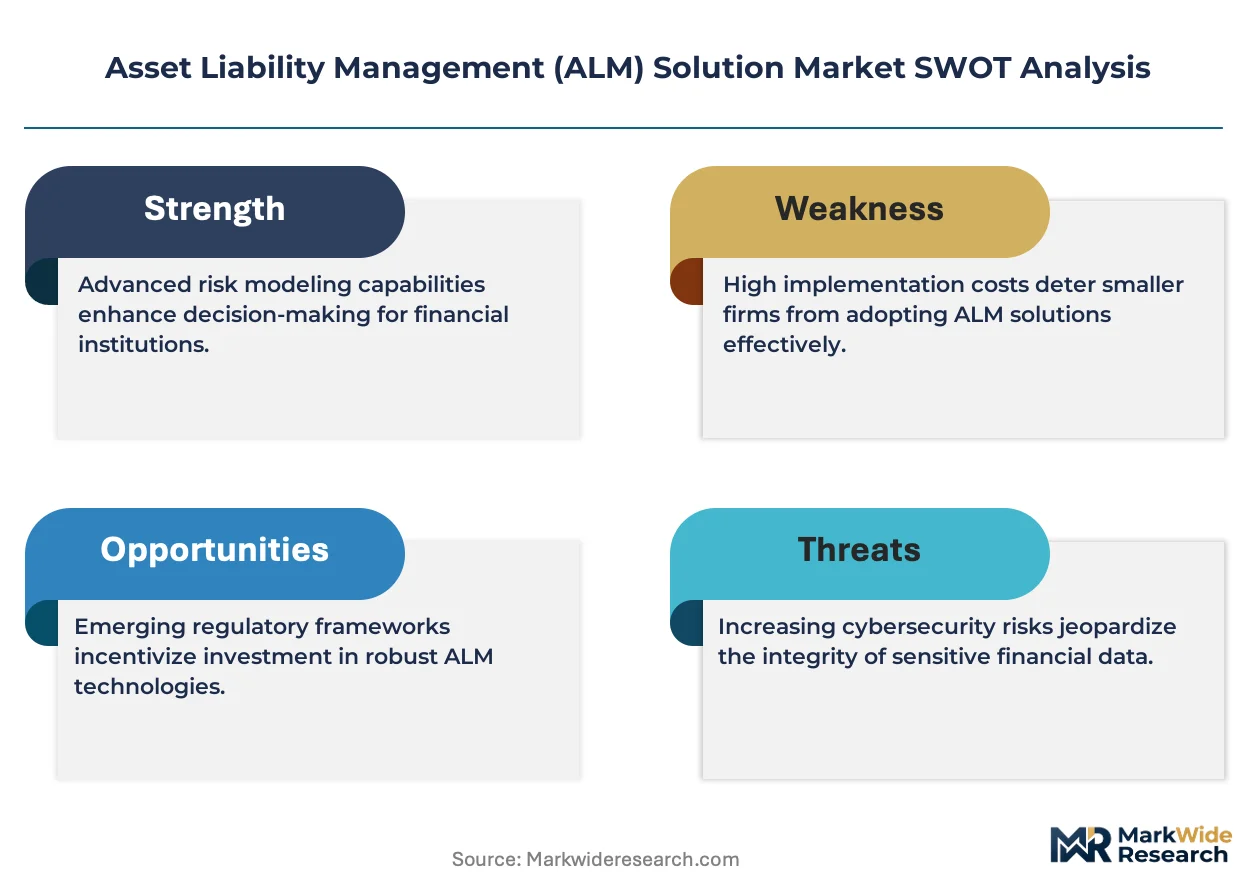
Regulatory convergence across Basel III liquidity standards and IRRBB guidelines is compressing vendor implementation timelines while forcing banks toward real-time risk infrastructure. Financial institutions now face simultaneous compliance deadlines that demand unified data architectures rather than siloed point solutions.
Growth Catalysts
- Basel III NSFR Implementation:Southeast Asian banks accelerate ALM procurement to meet net stable funding ratio deadlines, creating concentrated demand spikes in Singapore, Thailand, and Vietnam.
- Pension Fund Duration-Matching:Defined-benefit schemes across Europe and North America require sophisticated stochastic modeling to hedge longevity risk against fixed-income portfolios.
- Cloud Elasticity:Mid-tier insurers adopt cloud-native deployment to execute overnight Monte Carlo simulations without capital-intensive server farms.
Market Restraints
- Specialized Talent Scarcity:Quantitative risk modelers with both actuarial expertise and software engineering skills command premium compensation, constraining vendor expansion.
- Legacy System Entrenchment:Core banking platforms from the 1990s resist API integration, forcing costly middleware layers that erode ALM project ROI.
- Data Fragmentation:Asset and liability data resides across treasury, accounting, and trading systems without standardized ontologies, complicating unified risk views.
Strategic Opportunities
- AI-Driven Scenario Generation:Machine learning models trained on macroeconomic time series enable predictive stress-testing beyond historical scenario libraries.
- Embedded Regulatory Interpretation:Platforms that automate compliance mapping to EBA IRRBB and Federal Reserve CCAR requirements reduce implementation friction.
- Mid-Market SaaS Penetration:Regional banks in India and Brazil lack dedicated ALM teams, creating demand for managed-service wrappers around cloud analytics.
Industry Challenges
- Model Risk Governance:Validation teams struggle to certify black-box machine learning algorithms for regulatory capital calculations, slowing AI adoption.
- Cross-Functional Coordination:Treasury, risk, and IT departments maintain conflicting priorities during ALM platform selection, extending procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asset Liability Management (ALM) Solution Market |
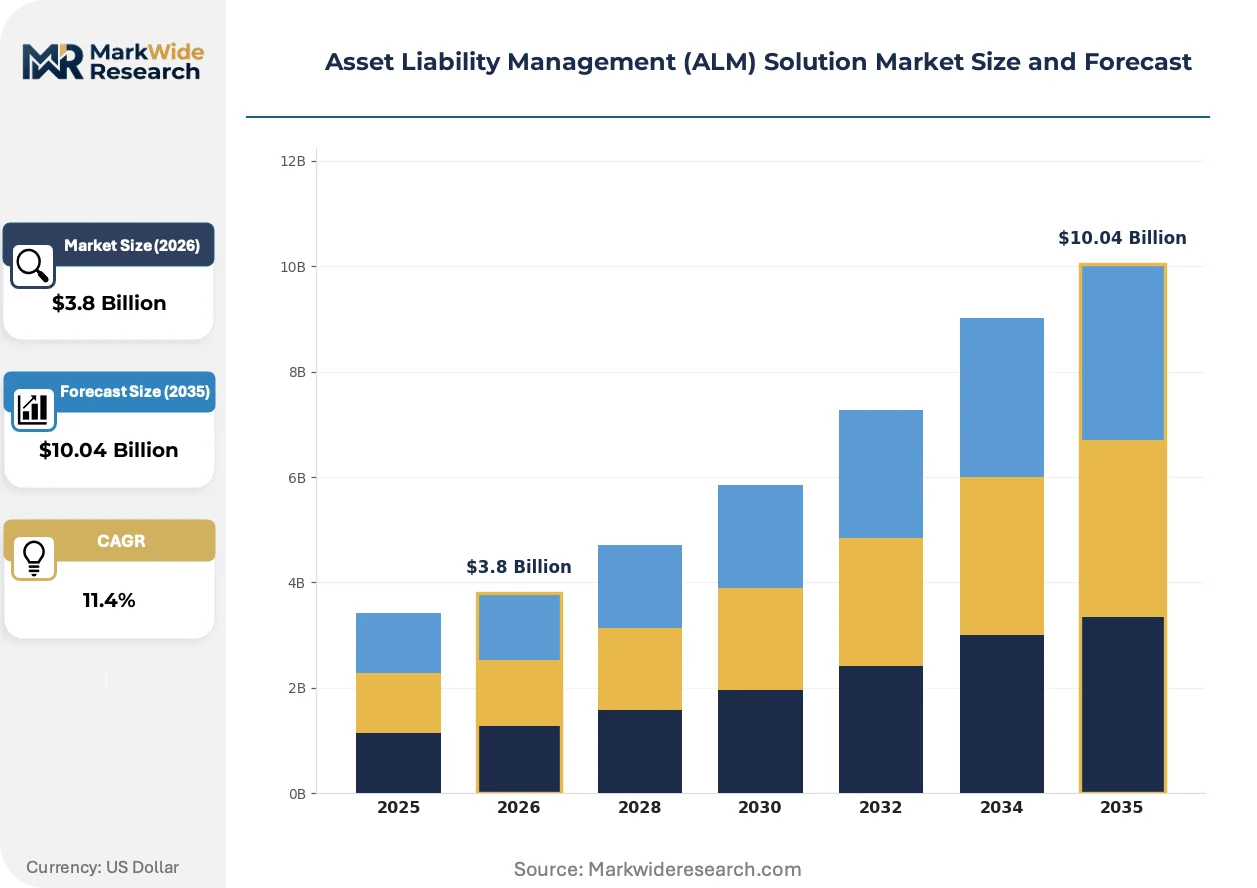
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Software, Consulting, Managed Services, Training Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Banks, Insurance Companies, Pension Funds, Investment Firms Functional Area: Risk Management, Treasury Management, Financial Planning, Reporting |
| Companies Covered | Finastra International Limited, Moody's Corporation, International Business Machines Corporation, Fiserv Inc, Fidelity National Information Services Inc, Oracle Corporation, Wolters Kluwer N V, SAS Institute Inc, SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asset Liability Management (ALM) Solution Market Strategic Shifts
Computational architectures and regulatory automation are restructuring how financial institutions deploy risk analytics. Vendors now compete on integration depth rather than isolated modeling sophistication.
Stochastic simulation engines are modularizing into containerized microservices that banks compose into custom risk workflows. Tier-two institutions in Germany and the Netherlands adopt these components to bypass monolithic platform licensing. This architecture is modularizing vendor competitive advantage from end-to-end suites toward interoperable analytics libraries.
The European Banking Authority's IRRBB guidelines mandate standardized interest rate shock scenarios and automatic outlier identification for capital allocation. Banks must now embed these calculations directly into limit-setting and pricing workflows. French and Italian institutions face the steepest adaptation curves due to decentralized legacy treasury operations.
Buying committees now unbundle implementation services from software licenses, selecting specialized systems integrators for data migration while negotiating direct platform subscriptions. This pattern compresses vendor margins on professional services while elevating pure-play analytics providers. The shift is most pronounced among Scandinavian banks with mature procurement functions and established vendor management offices.
Asset Liability Management (ALM) Solution Market Segmentation
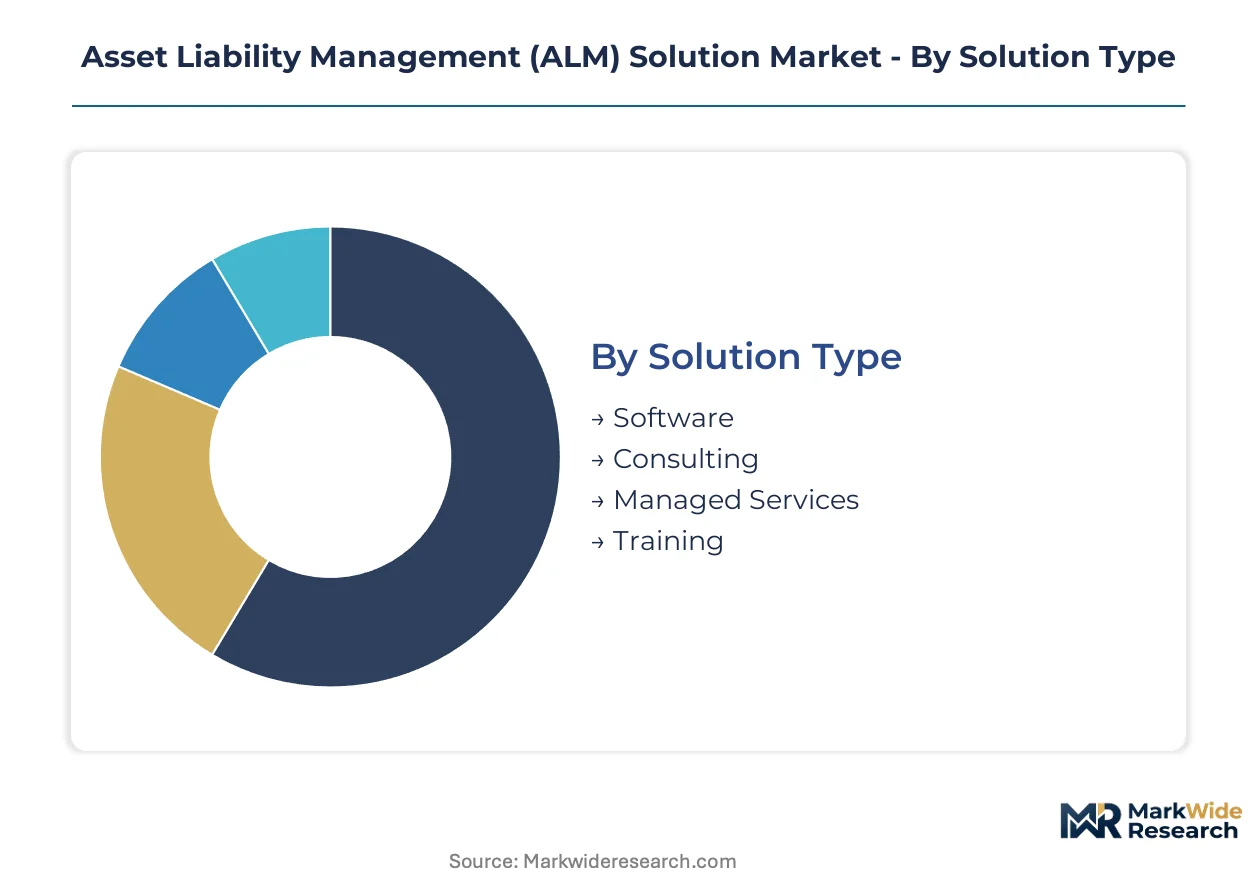
ALM solution procurement patterns diverge sharply by institutional sophistication and regulatory exposure. Segmentation reveals how vendors must architect pricing and delivery models around divergent buyer capabilities rather than uniform feature sets.
Solution Type:
Customization intensity spans from configurable software platforms to fully outsourced operational partnerships, with pricing power concentrating at the integration-heavy end of this spectrum.
- Software:Integrated platforms embed stochastic simulation engines, scenario analysis frameworks, and regulatory update cycles into recurring license structures. Pension funds across Europe and North America drive demand here as they confront duration-matching complexities for defined-benefit obligations.
- Consulting:Advisory engagements address Basel III liquidity coverage ratio implementation, IRRBB gap analysis, and stress-testing framework design. Southeast Asian banks in Singapore, Thailand, and Vietnam currently represent the most active procurement cluster as NSFR deadlines approach.
- Managed Services:Outsourced ALM operations include overnight risk runs, regulatory reporting, and limit monitoring delivered under multi-year service contracts.
- Training:Certification programs and model risk governance education target quantitative teams navigating AI-driven scenario generation and black-box algorithm validation.
Most installed capacity flows through Software. Expansion is steepest in Managed Services.
Deployment Model:
Capital deployment preferences separate institutions with established data centers from those seeking elastic compute without infrastructure ownership.
- On-Premises:Perpetual-license installations behind institutional firewalls serve banks with dedicated risk IT teams and stringent data residency requirements. Tier-one institutions in Germany and France maintain this model to preserve direct control over Monte Carlo simulation clusters.
- Cloud-Based:Elastic compute environments enable overnight risk runs and scenario generation without server farm capital expenditure. Mid-tier insurers across the Netherlands and Belgium adopt this model most aggressively to bypass infrastructure procurement cycles.
- Hybrid:Split architectures keep sensitive liability data on-premises while pushing computational workloads to cloud instances.
- SaaS:Subscription-based platform access eliminates implementation timelines and reduces upfront commitment for regional banks lacking dedicated ALM teams.
Cloud-Based deployments are gaining share fastest among mid-market entrants. Hybrid architectures dominate procurement conversations at tier-one institutions.
End User:
Regulatory complexity and balance sheet structure determine solution sophistication requirements across institutional categories.
- Banks:Universal and commercial banks require comprehensive interest rate risk, liquidity gap, and capital adequacy modeling under Basel III frameworks. Institutions across Singapore, Thailand, and Vietnam are expanding procurement most rapidly to meet net stable funding ratio compliance timelines.
- Insurance Companies:Life and property-casualty carriers apply ALM tools to asset-liability duration matching, solvency capital requirement calculations, and investment portfolio optimization. Mid-tier European insurers are shifting toward cloud-native deployment to execute stochastic projections without capital-intensive infrastructure.
- Pension Funds:Defined-benefit schemes leverage stochastic modeling to hedge longevity risk against fixed-income portfolios.
- Investment Firms:Asset managers and hedge funds deploy ALM analytics for liability-driven investment strategies and multi-asset portfolio construction.
Banks account for the deepest existing installed base. Pension Funds are expanding procurement most quickly as demographic pressures intensify.
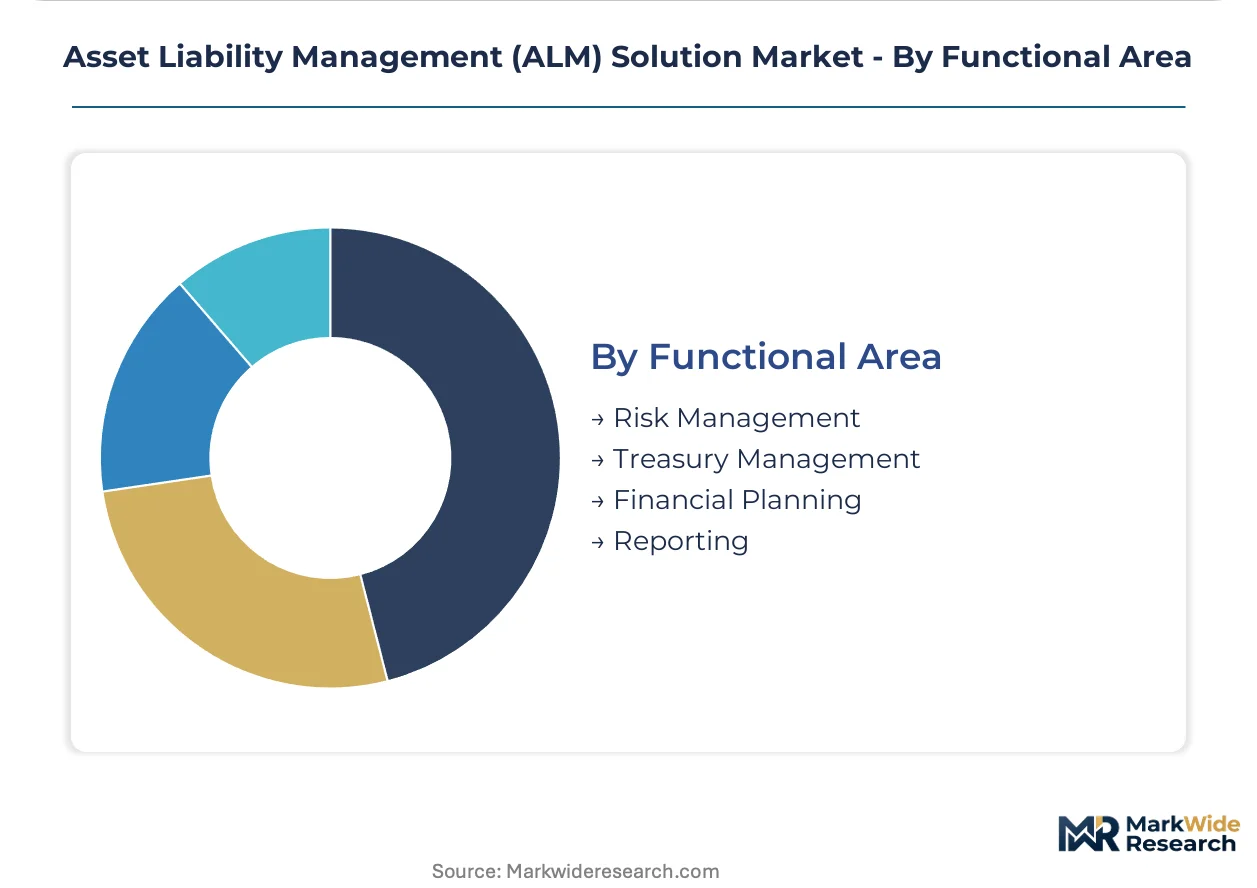
Functional Area:
Workflow integration depth separates point solutions from enterprise-wide risk infrastructure investments.
- Risk Management:Interest rate risk in the banking book calculations, liquidity stress testing, and capital allocation optimization form the core analytical workload. French and Italian institutions face the steepest adaptation curves here due to decentralized legacy treasury operations.
- Treasury Management:Funding desk operations, securities portfolio management, and intraday liquidity positioning require real-time data feeds and limit enforcement. Scandinavian banks with mature procurement functions unbundle implementation services from software licenses in this category.
- Financial Planning:Strategic balance sheet forecasting and net interest margin projection support executive decision-making.
- Reporting:Automated regulatory submission generation for EBA IRRBB, Federal Reserve CCAR, and Basel Committee NSFR standards.
Risk Management absorbs the majority of current platform investment. Reporting functionality is climbing fastest as regulatory automation becomes a competitive differentiator.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial centers in Singapore anchor procurement momentum for ALM solutions as Southeast Asian banks confront Basel III liquidity deadlines. European pension funds and North American stress-testing regimes generate parallel demand clusters across distinct regulatory environments.
Singapore
Net stable funding ratio compliance deadlines and IRRBB guideline implementation drive concentrated procurement from universal banks. The Monetary Authority of Singapore enforces liquidity coverage standards that exceed Basel minima. The Marina Bay financial district houses regional treasury operations for DBS, OCBC, and UOB expanding risk infrastructure.
United States
Comprehensive Capital Analysis and Review stress-testing cycles and regional bank consolidation create sustained platform demand. The Federal Reserve mandates forward-looking scenario analysis that compresses implementation timelines. New York-based money center banks and Chicago regional banking hubs upgrade Monte Carlo simulation capacity.
Germany
Decentralized legacy treasury architectures and European Banking Authority outlier identification rules force infrastructure replacement. BaFin supervises IRRBB compliance across fragmented savings bank networks. Frankfurt's banking quarter and Munich insurance clusters adopt modular microservices to bypass monolithic licensing.
United Kingdom
Defined-benefit pension scheme buyout activity and liability-driven investment strategies intensify duration-matching software demand. The Pensions Regulator mandates funding ratio monitoring that embeds stochastic mortality models. London's City and Edinburgh fund management centers deploy cloud-native ALM for overnight risk runs.
Netherlands
Mid-tier insurers seeking operational elasticity without server farm capital expenditure accelerate cloud deployment adoption. De Nederlandsche Bank supervises solvency capital requirements that demand real-time asset-liability projections. Amsterdam's Zuidas district and Rotterdam insurance operations adopt SaaS delivery models.
Asset Liability Management (ALM) Solution Market Competitive Environment
Strategic partnerships dominate the current landscape as vendors embed regulatory interpretation layers directly into platform architectures. The vendor base separates into three tiers: integrated enterprise suites, specialized analytics engines, and compliance-focused managed service operators. Technology licensing agreements and portfolio diversification into adjacent risk categories represent the primary competitive vectors reshaping positioning.
Within the enterprise software tier, Oracle Corporation and SAP SE exemplify platform consolidation strategies that embed regulatory automation into core architectures. SAS Institute Inc occupies a specialist position representing pure-play analytics providers competing on stress-testing engine sophistication. Moody's Corporation anchors the integrated risk data segment connecting credit analytics to ALM workflows.
| Leading Market Players |
|---|
| Finastra International Limited |
| Moody's Corporation |
| International Business Machines Corporation |
| Fiserv Inc |
| Fidelity National Information Services Inc |
| Oracle Corporation |
| Wolters Kluwer N V |
| SAS Institute Inc |
| SAP SE |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up software specialists anchor supply discipline in the ALM solution market, compressing professional services margins while elevating recurring license pricing power through embedded regulatory update cycles. Their ownership structures prioritize predictable cash flows over implementation-heavy revenue, reshaping how vendors negotiate with banks and insurers.
Pricing Analysis
Direct-to-institution subscription models bypass traditional systems integrator markups, with banks in Singapore and Thailand negotiating platform licenses separately from implementation services. Price differentiation centers on regulatory automation depth—Basel III NSFR-compliant modules command premiums over basic interest rate risk engines—and cloud elasticity tiers that scale compute for overnight Monte Carlo runs. Pricing pressure stems from unbundling trends among Scandinavian banks with mature procurement functions, eroding vendor margins on professional services. Regional banks in India and Brazil exhibit highest price sensitivity due to limited dedicated ALM teams, while tier-one institutions in Germany and France prioritize control over cost.
Supply Chain Analysis
Specialized quantitative talent supply rests on elite academic programs in the United States, United Kingdom, and Switzerland, where actuarial and financial engineering pipelines feed vendor development centers. Cloud infrastructure inputs draw from hyperscaler data center networks across Ireland, Singapore, and Virginia, while regulatory interpretation layers source from former central bank staff in Frankfurt, London, and Washington. Single-source vulnerability concentrates in stochastic simulation engine IP held by a narrow specialist tier. Distribution runs through direct enterprise sales teams supplemented by regional systems integrators for data migration and legacy system bridging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ALM solution market represents a late-cycle quality story as pension funds and insurers shift procurement toward platforms with embedded AI-driven scenario generation and automated regulatory compliance mapping.
For Market Incumbents: Anticipate margin compression in implementation services as buying committees unbundle professional services from software licenses. Defensive moves should center on deepening regulatory interpretation automation for EBA IRRBB and Federal Reserve CCAR requirements, and embedding stress-testing engines directly into client treasury workflows to reduce substitution risk from modular microservices competitors.
For New Entrants and Emerging Players: Cloud-native SaaS delivery routes offer the most penetrable path into mid-tier insurers across the Netherlands and Belgium lacking capital-intensive infrastructure appetite. White-space targets include regional banks in Brazil and India seeking managed-service wrappers around analytics, and tier-two German institutions adopting containerized risk components to bypass monolithic platform licensing. A specialist systems integrator partnership model accelerates credibility without legacy entrenchment.
For Investors and Strategic Acquirers: Private equity firms with fintech portfolio experience are the most active acquirer in this space, drawn to recurring revenue visibility and regulatory-mandated upgrade cycles. Long-term viability hinges on AI model risk governance capabilities as validation teams struggle to certify black-box algorithms for regulatory capital. Acquisition target archetypes include stress-testing engine specialists and compliance-focused managed service operators. The signal to watch is the next Basel revision cycle timing, which would trigger concentrated procurement spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Scenario Generation Development | Machine learning models trained on macroeconomic time series enable predictive stress-testing beyond historical libraries for pension funds. |
| Regulatory Interpretation Layer Embedding | Automated compliance mapping to EBA IRRBB and Federal Reserve CCAR requirements reduces implementation friction for Southeast Asian banks. |
| Cloud-Native Microservices Architecture | Containerized risk components allow tier-two German institutions to compose custom workflows without monolithic platform licensing. |
| Mid-Market SaaS Expansion | Subscription-based platform access eliminates upfront commitment for regional banks in India and Brazil lacking dedicated ALM teams. |
| Managed Services Capability Buildout | Outsourced overnight risk runs and regulatory reporting capture demand from insurers seeking operational elasticity without server farms. |
Study Parameters
Multiple input streams — structured interviews with ALM software procurement officers at banks and insurers, regulatory affairs specialists at European and Asian central banks, and quantitative risk modelers at pension funds — were reconciled against secondary validation from SEC filings, EBA guideline documentation, and Basel Committee technical standards. Bottom-up triangulation across vendor licensing disclosures and top-down reconciliation against institutional IT spending patterns anchored market sizing. Primary fieldwork captured implementation timeline compression and unbundling trends across procurement cycles.
Data-stream reconciliation fed analytical frameworks modeling deployment model transitions, end-user sophistication tiers, and functional area investment priorities across the projection horizon. Segmentation dimensions included solution type intensity, cloud adoption patterns by institutional tier, and regulatory exposure clustering. CAGRs were derived from scenario-weighted procurement velocity assumptions, with stochastic simulation engine demand and pension fund duration-matching complexity serving as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for AI-driven scenario generation would alter the outlook if regulatory validation timelines extend or black-box model governance requirements harden. Forecasts reflect underlying assumptions about Basel III implementation deadlines and cloud infrastructure cost trajectories. A small set of named triggers — next-generation Basel revisions, central bank digital currency integration requirements, and quantum computing disruption of Monte Carlo methods — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
United States Governance, Risk and Compliance Platform Market
Risk Management and Compliance
Europe Sustainable Finance Market
Risk Management and Compliance
Global Management Decision Market
Risk Management and Compliance
Healthcare Safety and Risk Management Solutions Market
Risk Management and Compliance
North America Strategic Consulting Market
Risk Management and Compliance
Fraud Detection and Prevention (FDP) Market
Risk Management and Compliance
Global Risk and Compliance Consulting Services Market
Risk Management and Compliance
Loan Compliance Management Software Market
Risk Management and Compliance
Governance, Risk and Compliance Platform Market
Risk Management and Compliance
Operational Risk Management Consulting Services in Manufacturing Market
Risk Management and Compliance
Global Asset Integrity Management Market
Risk Management and Compliance
UK Anti Money Laundering Solutions Market
Risk Management and Compliance
Risk Assessment Software Market
Risk Management and Compliance
Stress Testing Solutions Market
Risk Management and Compliance
Global Backstop Netting Systems Market
Risk Management and Compliance
Asia-Pacific Sustainable Finance Market