
 Operations Advisory Service Market | 2026-2036
Operations Advisory Service Market Size, Share, and Industry Trends Forecast 2026-2036
Operations Advisory Service Market Outlook
Healthcare provider demand is shifting toward operational advisory as hospital systems confront margin compression and workforce shortages. Deloitte leverages its healthcare practice scale to anchor complex transformation programs across integrated delivery networks. PwC competes through technology implementation capabilities that embed automation into clinical and back-office workflows. McKinsey & Company differentiates via advanced analytics and proprietary operational benchmarks that reshape client cost structures.
Operations advisory service encompasses structured consulting engagements that diagnose, redesign, and implement enterprise operating models across functional boundaries, typically deploying process mapping, lean methodology, and digital tooling to achieve measurable throughput or cost outcomes. The primary industrial purpose centers on closing performance gaps between current-state operations and competitive benchmarks or regulatory requirements. Process improvement and technology implementation command the largest share of engagement value, reflecting sustained enterprise investment in automation and workflow rationalization. Change management represents the fastest-expanding segment as organizations recognize that technical redesigns fail without parallel workforce and cultural transition programs.
ISO 9001 quality management standards and the EU AI Act shape advisory scope by mandating documented process controls and algorithmic accountability in automated decision systems. The SEC climate disclosure rules and OSHA workplace safety frameworks further expand compliance-driven advisory demand across manufacturing and energy clients. Stakeholders must monitor how evolving AI governance requirements alter the skill mix and pricing power of advisory delivery models.
Market Dynamics
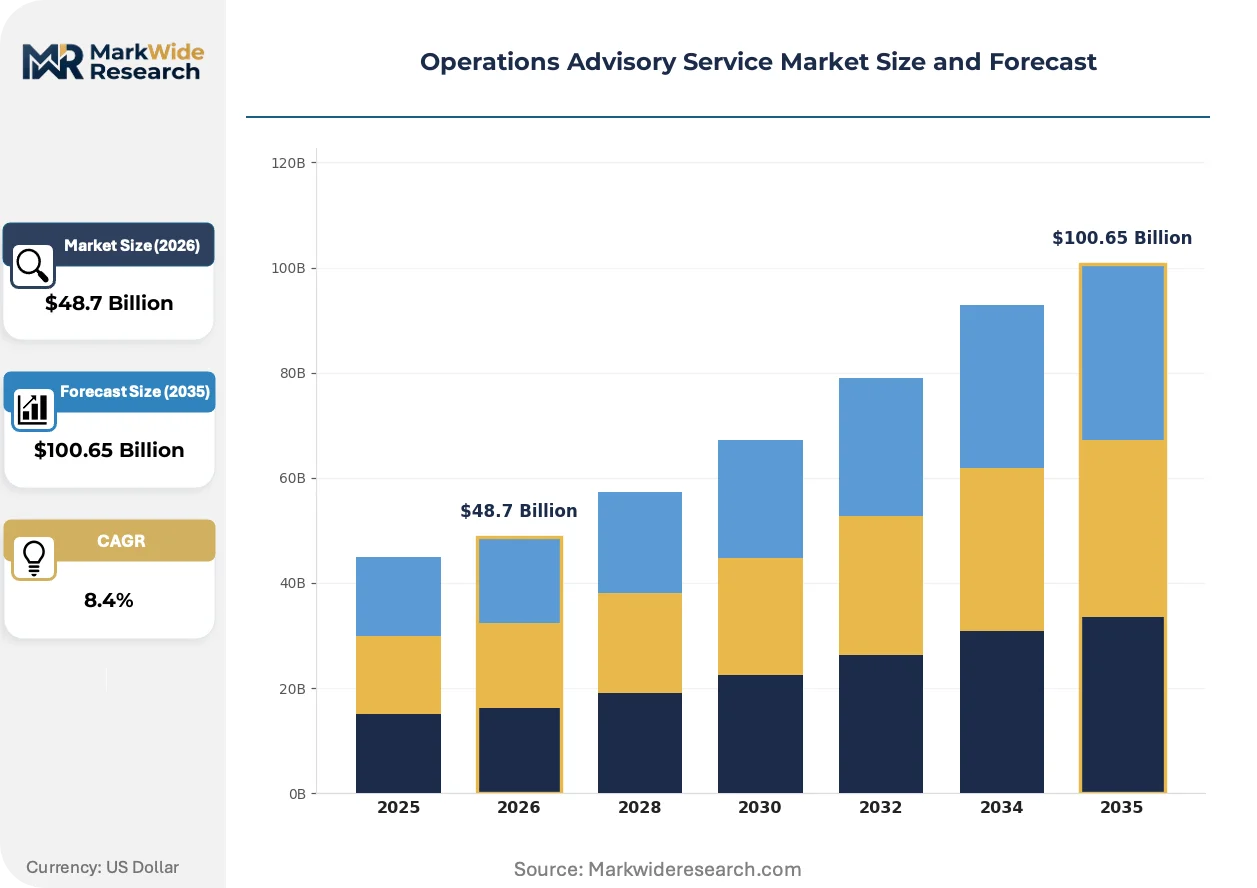
Enterprise restructuring mandates and AI governance requirements are compressing advisory engagement cycles while expanding scope into algorithmic accountability and workforce transition architecture.
Growth Catalysts
- EU AI Act compliance mandates:Automated decision systems in healthcare and finance require documented process controls, expanding advisory demand for algorithmic governance frameworks.
- Hospital margin compression:Integrated delivery networks facing workforce shortages are operationalizing lean methodology across clinical and administrative workflows.
- SEC climate disclosure rules:Manufacturing and energy clients require emissions accounting integration into operating models, driving sustainability-aligned advisory engagements.
Market Restraints
- Talent scarcity in change management:Advisory firms confront pipeline constraints for practitioners capable of orchestrating workforce transitions alongside technical redesigns.
- Procurement cycle elongation:Enterprise buyers extend vendor evaluation periods for transformation programs exceeding twelve months, compressing revenue recognition timelines.
- Substitute internal capabilities:Large corporations build in-house operational excellence centers, displacing mid-tier advisory engagements for standardized process improvement.
Strategic Opportunities
- ISO 9001 certification expansion:Quality management system implementation across mid-market manufacturing in Germany and France creates advisory whitespace.
- OSHA workplace safety integration:Safety framework digitization converges with operational advisory, enabling bundled compliance and productivity offerings.
- Healthcare automation convergence:Robotic process automation and clinical workflow redesign are merging, requiring advisory firms to embed technology implementation capabilities.
Industry Challenges
- Legacy system integration complexity:Enterprise resource planning modernization requires parallel operation of obsolete and redesigned workflows, extending project timelines.
- Certification timeline compression:EU AI Act readiness deadlines force accelerated documentation of algorithmic decision pathways without established precedent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Operations Advisory Service Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Process Improvement, Technology Implementation, Change Management Industry Vertical: Manufacturing, Healthcare, Retail, Telecommunications Client Type: Startups, SMEs, Corporates, Enterprises Engagement Model: Project-based, Retainer, On-demand, Hybrid |
| Companies Covered | Deloitte, PricewaterhouseCoopers (PwC), KPMG International, McKinsey & Company, Ernst & Young Global Limited (EY), Boston Consulting Group (BCG), Bain & Company, Accenture, A.T. Kearney, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Operations Advisory Service Market Strategic Shifts
Advisory delivery models are restructuring around embedded technology implementation and outcome-based contracting, compressing the traditional diagnose-design-deliver sequence into continuous optimization partnerships.
Generative AI is converging with process mining platforms to automate workflow documentation and bottleneck identification. Healthcare systems and financial services firms are deploying these tools within six-month pilot programs. The technology is converging with traditional advisory methodologies to compress diagnostic phases from months to weeks.
The EU AI Act mandates algorithmic impact assessments for high-risk automated systems, requiring advisory firms to build machine-learning audit capabilities. Healthcare providers deploying diagnostic algorithms must document training data provenance and performance drift monitoring. German hospital networks are engaging specialized compliance advisors to retrofit existing AI deployments ahead of enforcement deadlines.
Enterprise buyers are unbundling transformation programs into modular engagements with milestone-based termination rights. Procurement functions at US manufacturing conglomerates are replacing multi-year master service agreements with quarterly statement-of-work structures. This pattern is most pronounced in automotive and industrial equipment sectors where CFOs demand faster returns on advisory spend.
Operations Advisory Service Market Segmentation
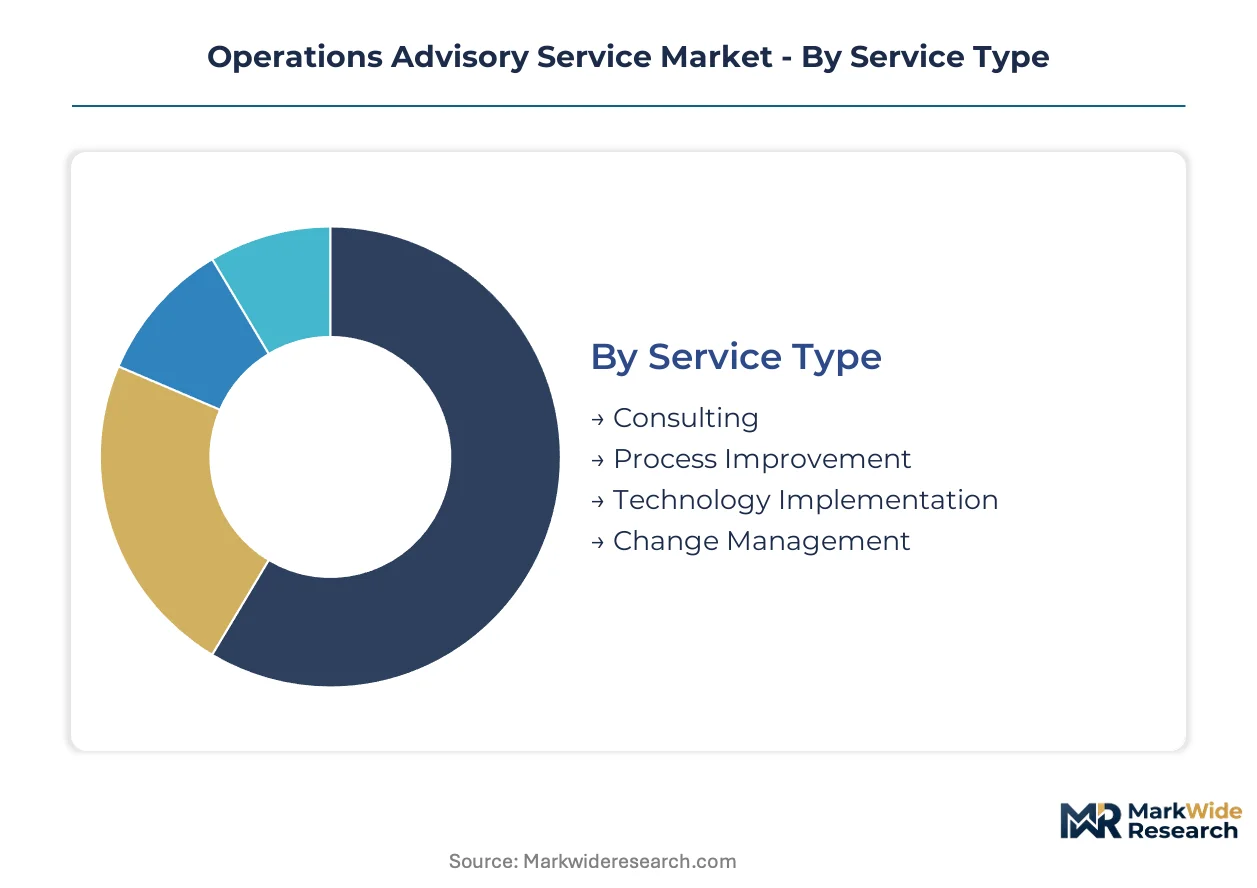
Operations advisory service providers structure their offerings across four distinct dimensions that shape pricing power, delivery methodology, and client relationship architecture. Each segmentation axis reveals divergent margin profiles and capability requirements that determine competitive positioning.
Service Type:
Advisory buyers differentiate primarily by the depth of transformation they require versus their internal execution capacity.
- Consulting:Strategic advisory engagements diagnose operating model gaps and define transformation roadmaps without implementation responsibility. Healthcare systems in the United States deploy these engagements to benchmark clinical workflows against integrated delivery network leaders.
- Process Improvement:Lean methodology and Six Sigma deployments target measurable throughput gains in manufacturing and administrative functions. German automotive suppliers engage these services to align production flows with ISO 9001 quality management requirements.
- Technology Implementation:System integration and automation deployment embed digital tooling into redesigned workflows. This segment captures advisory spend from financial services firms modernizing core banking platforms.
- Change Management:Workforce transition architecture and cultural alignment programs run parallel to technical redesigns. EU AI Act compliance deadlines are accelerating advisory demand for algorithmic governance change programs.
Volume sits with Consulting; growth tilts toward Change Management.
Industry Vertical:
Vertical specialization determines pricing premiums based on regulatory complexity and operational risk exposure.
- Healthcare:Clinical workflow optimization and revenue cycle management advisory address margin compression in hospital systems. Workforce shortages are forcing integrated delivery networks to operationalize lean methodology across patient care pathways.
- Manufacturing:Supply chain resilience and emissions accounting integration dominate advisory scope. SEC climate disclosure rules are driving sustainability-aligned operating model redesigns among industrial conglomerates.
- Retail:Omnichannel fulfillment and inventory optimization engagements target working capital efficiency. These programs deploy process mining to identify bottleneck reduction opportunities.
- Telecommunications:Network operations center transformation and customer service automation reshape cost structures. Advisory firms embed robotic process automation into legacy billing system environments.
Healthcare commands the largest engagement value; manufacturing shows the steepest expansion trajectory.
Client Type:
Organizational maturity and governance sophistication dictate engagement structure and risk allocation.
- Startups:Rapid scaling advisory addresses operating model design before process ossification. Venture-backed technology firms engage fractional advisory to build financial planning infrastructure.
- SMEs:Mid-market manufacturers in France and Germany pursue ISO 9001 certification to unlock supply chain tier-one status. These engagements bundle quality system implementation with operational benchmarking.
- Corporates:Division-level transformation programs target specific functional cost reduction. Procurement functions extend vendor evaluation periods for programs exceeding twelve months.
- Enterprises:Multi-year operating model redesigns span business units and geographies. Restructuring mandates compress advisory engagement cycles while expanding scope into workforce transition architecture.
Enterprises generate the highest revenue per engagement; SMEs represent the fastest-climbing client tier.
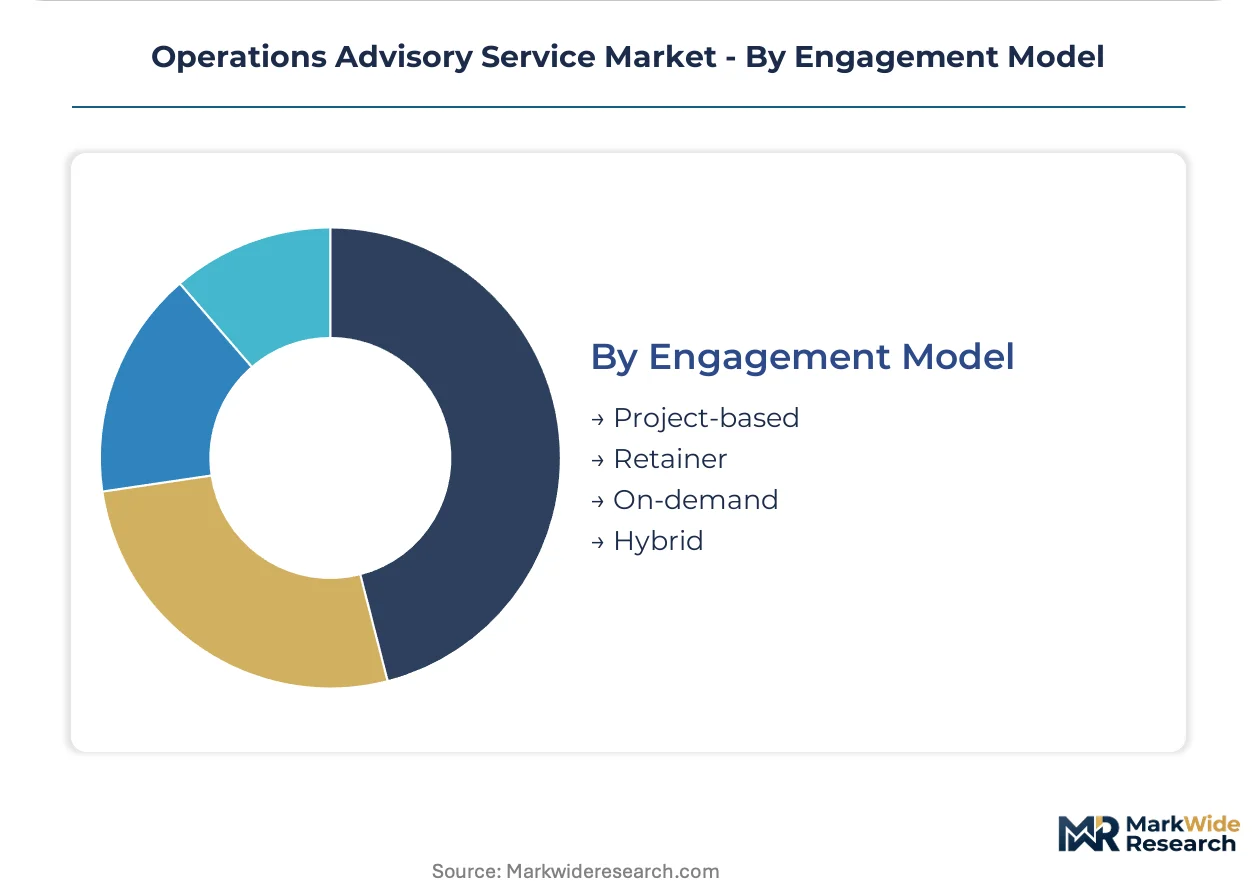
Engagement Model:
Commercial structure reflects client risk appetite and the predictability of transformation outcomes.
- Project-based:Fixed-scope engagements with defined deliverables and milestone payments. US manufacturing conglomerates are unbundling transformation programs into modular project structures with termination rights.
- Retainer:Continuous advisory relationships embedding teams within client organizations. These arrangements support EU AI Act compliance monitoring for healthcare providers deploying diagnostic algorithms.
- On-demand:Ad hoc advisory access for urgent operational decisions or crisis response. This model serves startup clients navigating rapid scaling challenges without dedicated internal operations leadership.
- Hybrid:Blended structures combining project phases with ongoing optimization partnerships. Outcome-based contracting components tie fees to measurable cost or throughput improvements.
Project-based structures retain the highest volume share; hybrid models are gaining share fastest as procurement functions demand faster returns on advisory spend.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advisory service production concentrates in established professional services hubs, while consumption patterns reflect enterprise restructuring intensity and regulatory compliance deadlines across major economies.
United States
Hospital systems and manufacturing conglomerates drive demand for operational transformation and AI governance advisory. SEC climate disclosure rules and OSHA workplace safety frameworks expand compliance-driven engagement scope. The Northeast corridor anchors large-scale advisory delivery, with Boston and New York serving as primary hubs for healthcare and financial services transformation programs.
Germany
Automotive suppliers and mid-market manufacturers pursue ISO 9001 certification and supply chain resilience redesign. The EU AI Act mandates algorithmic impact assessments for industrial automation systems. Bavaria and Baden-Württemberg concentrate advisory activity, with Munich and Stuttgart hosting specialized compliance and operational excellence practices.
United Kingdom
Financial services firms and healthcare networks invest in technology implementation and change management advisory. FCA operational resilience requirements and NHS transformation mandates shape engagement scope. London dominates advisory delivery, while regional health systems in the Midlands and North England drive distributed demand for clinical workflow optimization.
France
Industrial conglomerates and hospital networks engage operational advisory for emissions accounting and lean methodology deployment. ANSM and CNIL oversight of healthcare AI systems creates specialized compliance demand. The Île-de-France region anchors advisory capacity, with Lyon and Toulouse emerging as secondary centers for manufacturing and aerospace operational transformation.
India
Domestic conglomerates and multinational shared service centers drive demand for process improvement and digital transformation advisory. RBI operational guidelines and SEBI disclosure requirements expand financial services advisory scope. Mumbai and Bangalore concentrate advisory delivery, with Hyderabad and Pune emerging as hubs for technology-enabled operational redesign.
Operations Advisory Service Market Competitive Environment
Top-tier vendors anchor complex multi-year transformation programs, while mid-tier specialists compete on vertical expertise and implementation speed. The market structure reflects a tiered hierarchy where scale, brand recognition, and proprietary methodology determine pricing power. Strategic archetypes include full-service global networks, technology-enabled implementers, and boutique strategy specialists. Competitive moves center on capability acquisitions and outcome-based contracting structures that align fees with measurable client results.
Within the full-service advisory tier, Deloitte, PricewaterhouseCoopers (PwC), and McKinsey & Company occupy positions that exemplify divergent competitive positioning. Deloitte represents the scale-driven implementation archetype with integrated healthcare and technology practices. PwC sits within the technology-convergence segment where automation deployment capabilities anchor client relationships. McKinsey & Company exemplifies the strategy-specialist archetype that commands premium pricing through proprietary benchmarks and advanced analytics offerings.
| Leading Market Players |
|---|
| Deloitte |
| PricewaterhouseCoopers (PwC) |
| KPMG International |
| McKinsey & Company |
| Ernst & Young Global Limited (EY) |
| Boston Consulting Group (BCG) |
| Bain & Company |
| Accenture |
| A.T. Kearney |
| Others |
Value Chain & Pricing Dynamics
Enterprise procurement functions at US manufacturing conglomerates and German automotive suppliers concentrate buying power, forcing advisory firms toward outcome-based contracting and modular engagement structures that tie fees to measurable throughput improvements.
Pricing Analysis
Cost-down pressure on mid-tier advisory engagements accelerates because large corporations build in-house operational excellence centers, displacing standardized process improvement work. Pricing stratifies across premium strategy boutiques, integrated implementation networks, and commoditized lean methodology providers. Certification level—ISO 9001 quality management or EU AI Act compliance readiness—commands substantial premiums. Healthcare systems show highest price sensitivity due to margin compression, while financial services firms accept premium rates for algorithmic governance advisory.
Supply Chain Analysis
Talent supply rests on specialized practitioner pipelines concentrated in the United States, United Kingdom, and Germany, with India emerging as a technology-enabled delivery hub. Advisory delivery draws from experienced healthcare operations directors, manufacturing Six Sigma black belts, and machine-learning audit specialists. Single-source vulnerability concentrates in change management practitioners capable of orchestrating workforce transitions. Distribution runs through direct enterprise sales relationships, with procurement functions increasingly unbundling multi-year programs into quarterly statement-of-work structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around firms that can embed technology implementation capabilities, with procurement cycle elongation and outcome-based contracting pressures forcing weaker players toward specialized niches or exit.
For Market Incumbents: Deploy proprietary operational benchmarks and advanced analytics platforms to defend against technology-enabled implementers. Build machine-learning audit capabilities ahead of EU AI Act enforcement deadlines. Acquire boutique change management specialists to address talent scarcity in workforce transition architecture. For New Entrants and Emerging Players: Digital-channel routes through embedded technology partnerships offer lower-friction entry than direct enterprise sales. Target mid-market manufacturers in France and Germany pursuing ISO 9001 certification, where advisory whitespace exists. Lead with process mining and generative AI diagnostic tools to compress engagement cycles. For Investors and Strategic Acquirers: The window for entry favors technology-convergence specialists with healthcare or financial services vertical depth. Long-term viability hinges on advisory firms' ability to transition from project-based to continuous optimization partnerships. Watch for accelerated EU AI Act readiness deadlines as inflection indicators for compliance-advisory demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Capability Acquisition | Machine-learning audit specialists address EU AI Act algorithmic impact assessment mandates. |
| Outcome-Based Contracting | Ties advisory fees to measurable cost or throughput improvements demanded by CFOs. |
| Technology Partnership | Process mining and generative AI convergence compresses diagnostic phases from months to weeks. |
| Vertical Specialization | Healthcare automation advisory merges robotic process automation with clinical workflow redesign. |
| Geographic Expansion | Mid-market manufacturing in Germany and France creates ISO 9001 certification advisory whitespace. |
Study Parameters
Multi-period observation of advisory engagement structures, pricing model evolution, and regulatory compliance deadlines anchored the trend analysis, supplemented by interviews with healthcare operations executives, manufacturing plant managers, financial services technology officers, procurement leads at industrial conglomerates, and regulatory affairs specialists at advisory firms. Secondary validation drew from SEC climate disclosure filings, EU AI Act implementation guidance, ISO management system standards documentation, hospital procurement databases, and automotive supplier quality certification records. Bottom-up segmentation modeling triangulated against top-down market sizing.
Input-output matrices mapped service type, industry vertical, client maturity tier, and engagement model dimensions across the projection horizon. CAGRs derived from regression analysis of historical advisory spend patterns against enterprise restructuring intensity and regulatory compliance deadline clustering. Forecast inputs included healthcare margin compression trajectories, EU AI Act enforcement timeline assumptions, and technology implementation capability diffusion rates.
The model holds under stable regulatory enforcement schedules and sustained enterprise restructuring activity; deviation in EU AI Act deadline acceleration or rapid in-house capability buildout by large corporates would shift advisory demand composition. A small set of triggers—algorithmic governance mandate expansion, hospital system consolidation waves, and procurement function centralization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
China Enterprise Risk Management Market
Risk Management and Compliance
Cyber Security in BFSI Market
Risk Management and Compliance
Asia-Pacific Compliance and Traceability Solutions Market
Risk Management and Compliance
North America Strategic Consulting Market
Risk Management and Compliance
Global Compliance Management Software Market
Risk Management and Compliance
AI in Fraud Management Market
Risk Management and Compliance
Crypto Compliance Software Market
Risk Management and Compliance
Global Financial Crime and Fraud Management Solutions Market
Risk Management and Compliance
Operational Risk Management Consulting Services in Manufacturing Market
Risk Management and Compliance
Oil and Gas Risk Management Market
Risk Management and Compliance
Vendor Risk Management Market
Risk Management and Compliance
Anti-Money Laundering (AML) Market
Risk Management and Compliance
Global Asset Integrity Management Market
Risk Management and Compliance
Enterprise Governance, Risk, and Compliance (Egrc) Market
Risk Management and Compliance
Trade Surveillance Market
Risk Management and Compliance
Revenue Assurance Market