
 United States Strategic Consulting Services Market | 2026-2036
United States Strategic Consulting Services Market Size, Share, and Industry Trends Forecast 2026-2036
United States Strategic Consulting Services Market Analytics
MBA-level talent pipelines is rotating toward data science and artificial intelligence specializations, tightening supply of traditional generalist strategists. McKinsey & Company leverages its advanced analytics division to capture technology transformation engagements. Boston Consulting Group sustains dominance in private equity due diligence through proprietary benchmarking databases. Bain & Company anchors its growth in pricing and revenue management verticals with dedicated practitioner teams.
Strategic consulting services encompass structured advisory engagements where organizations receive external expertise on corporate strategy, operational improvement, market entry, and organizational design, typically delivered through partner-led teams working intensively with C-suite executives over defined periods. Management consulting commands the largest revenue pool among service types, while IT consulting registers the fastest expansion as clients modernize legacy systems and cybersecurity postures. Project-based engagements generate premium pricing relative to retainer structures, particularly in technology and healthcare verticals where scope complexity demands specialized staffing.
The Federal Acquisition Regulation framework governs consulting contracts with government agencies, while SEC disclosure requirements shape the risk and compliance advisory subsegment serving publicly traded clients. OSHA workplace safety mandates and evolving FTC merger review standards further expand the regulatory advisory workload for consulting firms. Stakeholders must monitor how generative AI tools reshape the economics of knowledge work and whether clients begin unbundling strategy from implementation.
Market Dynamics
Cloud-based analytics platforms are displacing traditional spreadsheet-driven planning workflows across client organizations, forcing consulting firms to restructure service delivery models and talent requirements around real-time data infrastructure rather than static advisory outputs.
Growth Catalysts
- Biden Administration Infrastructure Mandates:Federal agencies in Washington D.C. are expanding procurement of strategic advisory services to support industrial policy implementation and capital allocation frameworks.
- Venture-Backed Scaling Requirements:California's technology corridor generates concentrated demand for continuous strategy support as portfolio companies navigate rapid operational expansion and market entry decisions.
- SEC Disclosure Expansion:Publicly traded clients require enhanced risk and compliance advisory to meet evolving securities reporting standards and governance transparency requirements.
Market Restraints
- MBA Talent Pipeline Constriction:Traditional generalist strategist supply tightens as top graduates rotate toward data science and artificial intelligence specializations, raising recruitment costs for partner-track positions.
- Cloud Infrastructure Dependency:Firms face vendor concentration risk in analytics platform partnerships, with Microsoft Azure and Amazon Web Services controlling critical service delivery infrastructure.
- Federal Acquisition Regulation Friction:FAR compliance requirements extend contract award timelines and limit pricing flexibility for government advisory engagements.
Strategic Opportunities
- Generative AI Service Unbundling:Clients are beginning to separate strategy formulation from implementation execution, creating white space for specialized firms in each phase.
- FTC Merger Review Expansion:Heightened antitrust scrutiny under revised standards expands regulatory advisory workload for transactions requiring pre-clearance strategic planning.
- Pricing and Revenue Management Verticalization:Dedicated practitioner teams in specialized functions command premium positioning as clients seek deep expertise over generalist coverage.
Industry Challenges
- Generative AI Knowledge Work Economics:Firms must retrain delivery teams and reprice engagements as automated research and synthesis tools compress traditional hourly billing models.
- OSHA Workplace Safety Compliance Integration:Advisory projects increasingly require embedded safety mandate expertise, complicating staffing for cross-functional client teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Strategic Consulting Services Market |
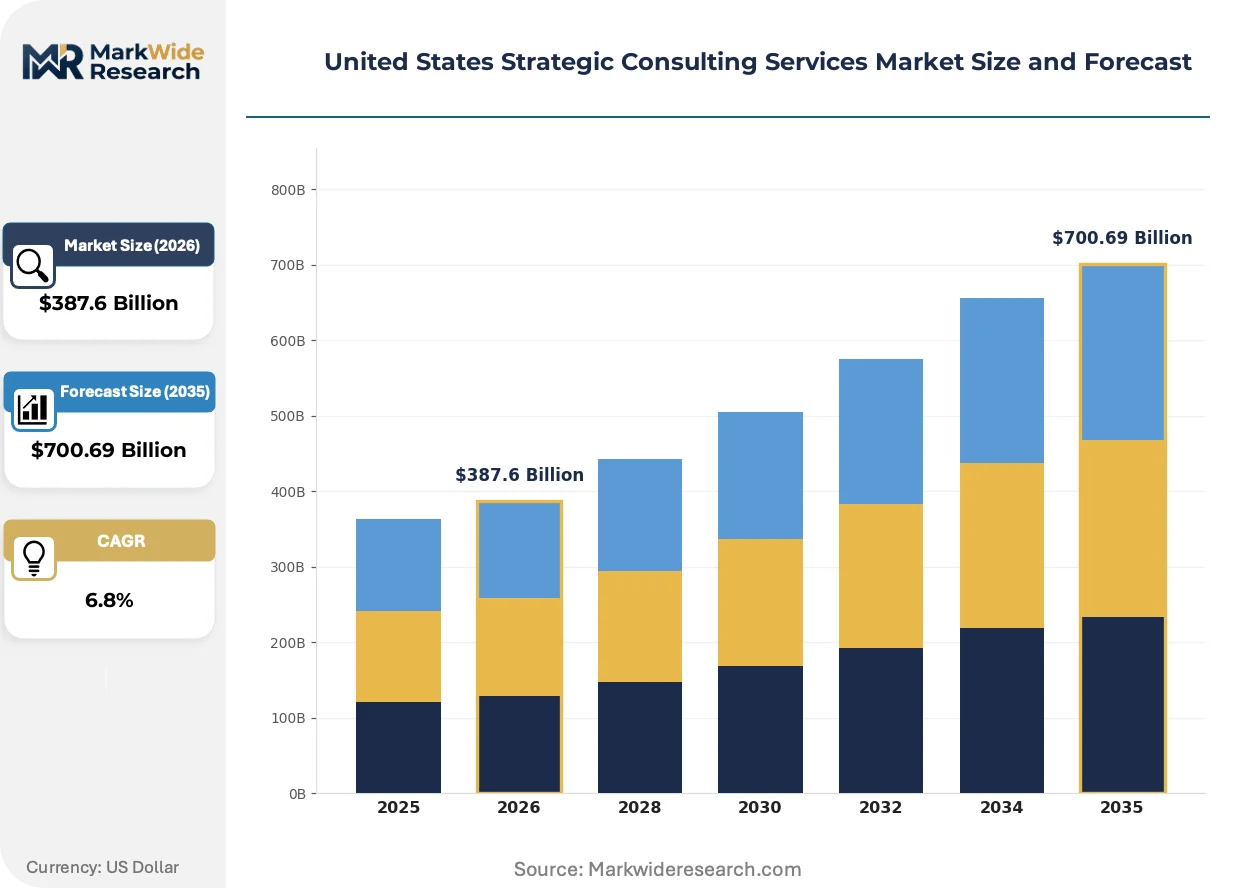
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Financial Advisory, Management Consulting, IT Consulting, Human Resources Client Type: Corporations, Nonprofits, Government Agencies, Startups Engagement Model: Retainer, Project-Based, Time & Materials, Fixed Fee Industry Vertical: Healthcare, Manufacturing, Technology, Telecommunications |
| Companies Covered | McKinsey & Company, Boston Consulting Group, Bain & Company, Deloitte Consulting, Accenture Strategy, PwC Advisory Services, Ernst & Young Advisory, KPMG Advisory, Oliver Wyman, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Strategic Consulting Services Market Evolving Landscape
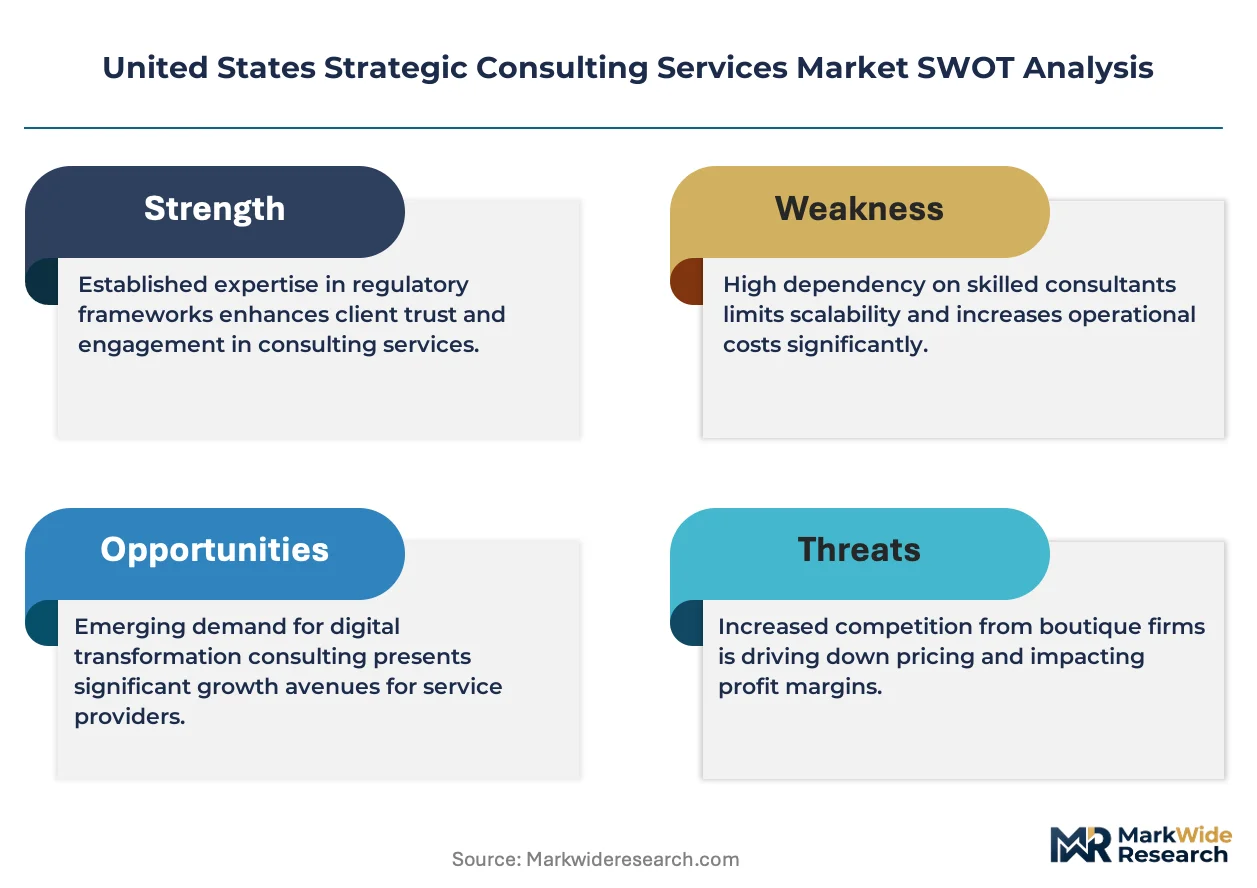
Advisory delivery models are fragmenting as technology-enabled self-service tools and specialized boutique competitors erode the traditional generalist monopoly on C-suite strategy access.
Generative AI research assistants are displacing junior analyst labor pools in due diligence and market sizing workstreams. Private equity firms now deploy these tools for preliminary target screening before engaging senior consultants. The compression of entry-level advisory roles is forcing established firms to restructure pyramid staffing models toward thinner, senior-heavy teams.
OSHA workplace safety mandates and evolving FTC merger review standards expand regulatory advisory workload for consulting practices serving industrials and transaction-heavy clients. The Federal Acquisition Regulation framework simultaneously governs government contracts, creating dual compliance tracks for firms with public sector portfolios. Healthcare and manufacturing verticals face the steepest compliance cost escalations.
Retainer structures are losing ground to project-based pricing in technology and healthcare verticals where scope complexity demands specialized staffing. Clients in California's venture ecosystem increasingly purchase discrete strategy sprints rather than continuous advisory relationships. The shift pressures firms to develop modular service productization and transparent outcome metrics.
United States Strategic Consulting Services Market Segmentation
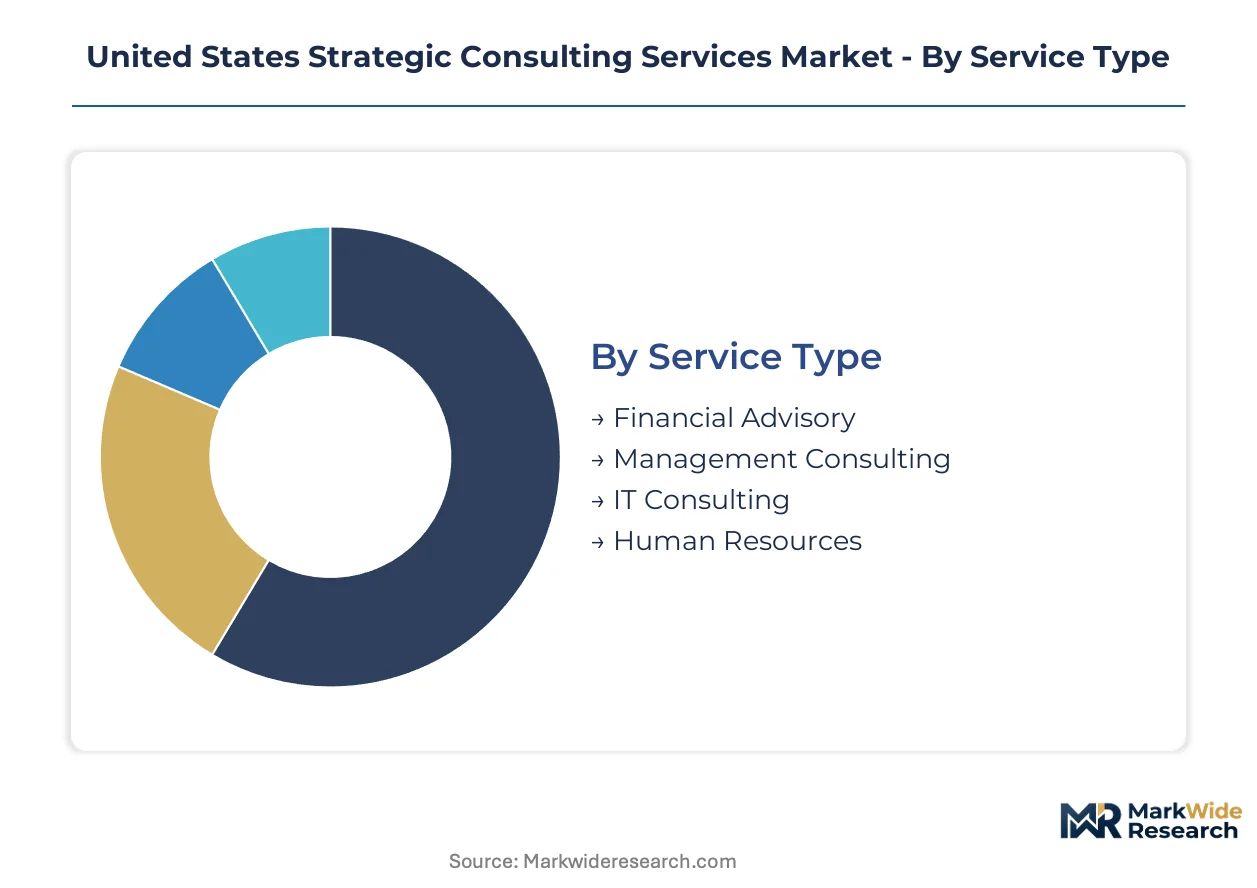
Segmentation in strategic consulting services reveals distinct procurement patterns across client types and engagement structures. Service delivery economics vary substantially between retainer relationships and discrete project mandates.
Service Type:
Management consulting flows through partner-led advisory channels with C-suite access, while IT consulting routes increasingly through technology vendor partnerships and cloud platform ecosystems.
- Management Consulting:Encompasses corporate strategy, operational improvement, and organizational design delivered through intensive partner-led engagements. Demand concentrates among Fortune 500 corporations in New York and Chicago, where board-level mandates for transformation programs sustain premium pricing.
- IT Consulting:Covers legacy system modernization, cybersecurity posture enhancement, and cloud infrastructure migration. California technology firms and federal agencies in Washington D.C. drive procurement as cloud-based analytics platforms displace spreadsheet-driven workflows.
- Financial Advisory:Transaction support, valuation, and capital structure optimization for M&A and restructuring events.
- Human Resources:Talent strategy, compensation design, and workforce transformation advisory.
Management consulting dominates installed base. IT consulting is where expansion concentrates.
Client Type:
Cost tier stratification separates enterprise retainers from startup project sprints, with government procurement operating under distinct Federal Acquisition Regulation compliance requirements.
- Corporations:Large enterprises with continuous strategy needs and multi-year advisory relationships. Manufacturing and healthcare verticals in the Midwest and Northeast sustain the deepest retainer commitments.
- Government Agencies:Federal, state, and municipal entities procuring under FAR and state procurement codes. Washington D.C. metropolitan area agencies are expanding advisory procurement for infrastructure and industrial policy implementation.
- Startups:Venture-backed firms requiring discrete strategy sprints for scaling decisions.
- Nonprofits:Mission-driven organizations with constrained budgets and board-governed project scopes.
Corporations anchor revenue stability. Government agencies represent the steepest expansion trajectory.
Engagement Model:
Volume concentration shifts toward project-based structures in technology and healthcare, while time-and-materials persists in complex regulatory advisory.
- Project-Based:Discrete scope engagements with defined deliverables and outcome metrics. Technology and healthcare verticals command premium pricing as scope complexity demands specialized staffing.
- Retainer:Continuous advisory relationships with predictable monthly fees. Generalist strategy firms defend position through longstanding C-suite access.
- Fixed Fee:Pre-negotiated total cost for well-defined transformation or implementation programs.
- Time & Materials:Hourly billing with cost-plus structures for open-ended regulatory and compliance advisory.
Retainer structures dominate partner-track economics. Project-based engagements are gaining share fastest.
Industry Vertical:
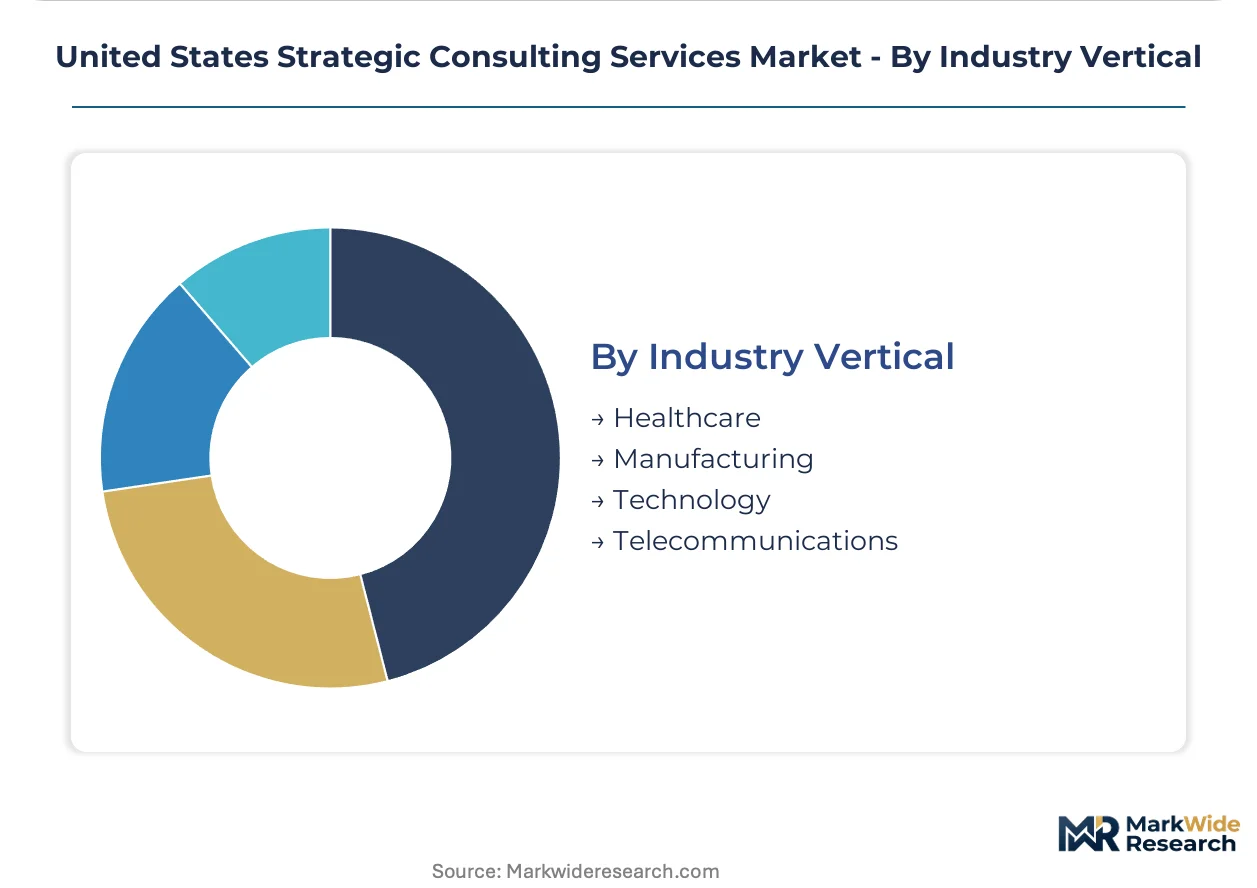
Application intensity varies by regulatory burden and technology disruption exposure, with healthcare and manufacturing facing the steepest compliance cost escalations.
- Healthcare:Strategy support for value-based care transition, M&A integration, and HIPAA compliance. Provider systems and pharmaceutical manufacturers in Boston and Research Triangle Park drive concentrated demand.
- Technology:Scaling strategy, market entry, and pricing optimization for software and platform companies. California's venture corridor generates continuous procurement from portfolio companies navigating rapid expansion.
- Manufacturing:Operational improvement, supply chain restructuring, and OSHA workplace safety mandate integration.
- Telecommunications:5G deployment strategy, regulatory navigation, and infrastructure monetization advisory.
Healthcare dominates regulatory advisory workload. Technology is where pricing and revenue management specialization commands premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC disclosure requirements anchor the United States market, where federal procurement under FAR frameworks and venture capital concentration in coastal corridors generate distinct regional demand patterns across sub-national markets.
California
Venture-backed technology firms in San Francisco and Silicon Valley drive continuous procurement for scaling strategy and pricing optimization advisory. The state's labor regulations and privacy mandates under CCPA shape compliance-heavy engagement scopes. Los Angeles and San Diego anchor secondary demand from aerospace and biotech clusters seeking operational improvement support.
New York Metro
Fortune 500 financial services and media conglomerates sustain deep retainer relationships for corporate strategy and M&A advisory. SEC enforcement actions and NYDFS cybersecurity requirements expand risk and compliance workloads. Manhattan's concentration of private equity headquarters generates due diligence demand that flows through specialized practitioner teams.
Washington D.C. Metropolitan Area
Federal agencies under Biden administration infrastructure mandates expand procurement for industrial policy implementation and capital allocation frameworks. FAR compliance requirements extend contract timelines but create stable multi-year revenue streams. Northern Virginia's defense contractor ecosystem demands embedded strategy support for federal technology modernization programs.
Texas
Energy sector restructuring and healthcare system consolidation in Houston and Dallas generate project-based demand for operational improvement and M&A integration. OSHA workplace safety mandates in refining and petrochemical operations complicate cross-functional staffing requirements. Austin's emerging technology corridor attracts discrete strategy sprints from scaling software firms.
Greater Boston
Pharmaceutical manufacturers and provider systems drive regulatory advisory intensity for HIPAA compliance and value-based care transition. Massachusetts biotech clusters require specialized pricing and revenue management expertise for novel therapeutic launches. Harvard and MIT talent pipelines feed data science specializations that tighten traditional generalist strategist supply.
United States Strategic Consulting Services Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the United States strategic consulting services market. The upper tier commands C-suite access through partner-led advisory channels with multi-decade institutional relationships. Below this, boutique specialists carve position in pricing optimization, regulatory compliance, and technology implementation verticals. Competitive moves concentrate on talent acquisition from data science programs and modular service productization to capture project-based demand.
Within the integrated leader tier, McKinsey & Company and Boston Consulting Group exemplify archetypes built on proprietary knowledge infrastructure and partner-track talent density. Bain & Company occupies a position emphasizing pricing and revenue management verticalization with dedicated practitioner teams. These structures represent the dominant competitive model against which specialists and mid-tier firms define differentiation strategies.
| Leading Market Players |
|---|
| McKinsey & Company |
| Boston Consulting Group |
| Bain & Company |
| Deloitte Consulting |
| Accenture Strategy |
| PwC Advisory Services |
| Ernst & Young Advisory |
| KPMG Advisory |
| Oliver Wyman |
| Others |
Value Network & Pricing Analysis
Project-based engagements with defined deliverables lock in both partner-level staffing access and outcome-based fee visibility for technology and healthcare clients navigating complex regulatory mandates. This contract structure concentrates pricing power with firms maintaining dedicated practitioner teams in specialized verticals.
Pricing Analysis
Manhattan commands premium positioning for financial services advisory, while California's venture corridor accepts compressed margins for discrete strategy sprints. Project-based pricing dominates technology and healthcare verticals where scope complexity demands specialized staffing. Brand premium and certification depth separate McKinsey and Boston Consulting Group from mid-tier competitors. Pricing pressure stems from generative AI tools compressing traditional hourly billing models for junior analyst workstreams. Startups exhibit highest price sensitivity; Fortune 500 retainers show lowest.
Supply Chain Analysis
Port congestion at Los Angeles and Long Beach elevates inbound costs for technology hardware supporting cloud analytics platforms deployed across client sites. Talent supply concentrates in the United States, United Kingdom, and India, with MBA pipelines tightening as graduates rotate toward data science specializations. Cloud infrastructure dependencies rest on Microsoft Azure and Amazon Web Services for critical service delivery. Single-source vulnerability in analytics platform partnerships threatens operational continuity. Distribution runs through partner-led advisory channels with C-suite access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Federal infrastructure mandates under the Biden administration create an early-cycle expansion story, with procurement velocity accelerating as agencies industrialize capital allocation frameworks.
For Market Incumbents: Secure data science talent pipelines through direct university partnerships before MBA rotation tightens generalist strategist supply further. Deepen proprietary benchmarking databases to defend private equity due diligence market share against automated screening tools. Cloud infrastructure partnerships with diversified vendor bases reduce concentration risk.
For New Entrants and Emerging Players: Anchor in pricing and revenue management verticals where dedicated practitioner teams command premium positioning unavailable to generalist competitors. California's technology corridor offers the most penetrable geography for discrete strategy sprints replacing traditional retainer relationships. Modular service productization with transparent outcome metrics accelerates client acquisition.
For Investors and Strategic Acquirers: Boutique specialists with regulatory compliance depth in FTC merger review or OSHA workplace safety integration represent attractive acquisition targets. Long-term viability hinges on generative AI integration capabilities that restructure pyramid staffing models toward senior-heavy teams. Watch for client unbundling of strategy from implementation as an inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Service Integration | Restructures delivery economics by compressing junior analyst roles in due diligence workstreams. |
| Specialist Practitioner Team Buildout | Captures premium positioning in pricing optimization and regulatory compliance verticals. |
| Cloud Platform Partnership Diversification | Reduces vendor concentration risk in Microsoft Azure and Amazon Web Services dependencies. |
| Federal Contract Capability Investment | Unlocks FAR-compliant procurement channels for Biden administration infrastructure mandates. |
| Modular Service Productization | Aligns offering structure with California venture ecosystem demand for discrete strategy sprints. |
Research Methodology
A spread of perspectives from consulting partners, federal procurement officers, venture capital operating partners, and technology firm CFOs converged on the working assumptions shaping demand trajectories. Primary interviews with these stakeholders combined with secondary validation against SEC filings, Federal Acquisition Regulation contract databases, and hyperscaler capex disclosures. Bottom-up engagement volume estimates triangulated with top-down market sizing across service type and client type dimensions.
Segmentation dimensions modeled include service delivery model, client organization size, industry vertical, and geographic procurement cluster throughout the forecast period. CAGRs derive from regression analysis of historical contract award patterns and projected federal spending authorizations. Cloud infrastructure penetration rates and MBA pipeline specialization shifts serve as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained federal procurement expansion and stable venture capital deployment; material deviation would warrant model refresh. Specific risk factors include generative AI adoption velocity exceeding projected timelines and FAR compliance timeline extensions. Recalibration cycles align with material shifts in federal budget appropriations and technology platform economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Operational Risk Management Consulting Services in Manufacturing Market
Risk Management and Compliance
Europe BFSI Biometrics Market
Risk Management and Compliance
North America Strategic Consulting Market
Risk Management and Compliance
Risk Management Market
Risk Management and Compliance
Asia-Pacific BFSI Biometrics Market
Risk Management and Compliance
United States Governance, Risk and Compliance Platform Market
Risk Management and Compliance
Trade Surveillance Market
Risk Management and Compliance
Fraud Detection and Prevention (FDP) Market
Risk Management and Compliance
Compliance As a Service Market
Risk Management and Compliance
Financial Risk Management Software Market
Risk Management and Compliance
Sustainable Finance Market
Risk Management and Compliance
Pre Trade Risk Management Solution Market
Risk Management and Compliance
Global Risk Management Software Market
Risk Management and Compliance
Asia-Pacific Compliance and Traceability Solutions Market
Risk Management and Compliance
China Enterprise Risk Management Market
Risk Management and Compliance
Third Party Risk Management Market