
 Europe Metal Cleaning Chemicals Market | 2026-2036
Europe Metal Cleaning Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Metal Cleaning Chemicals Market Foresight
Aftermarket service revenue from chemical management and bath-life extension programs is rewriting profitability structures across the value chain. BASF SE leverages its integrated surfactant manufacturing network to sustain margin capture in alkaline cleaner formulations. Dow anchors its position through proprietary solvent blends that compete on flash-point performance and worker safety profiles. Evonik Industries differentiates via specialty amine oxide surfactants that extend bath life in high-throughput automotive pretreatment lines.
Europe metal cleaning chemicals comprise formulated blends of solvents, alkaline builders, acids, and surfactants designed to remove oils, oxides, and particulate contaminants from ferrous and non-ferrous substrates, typically operating at temperatures between 40°C and 80°C depending on substrate sensitivity and soil loading. These formulations serve critical functions in preparing metal surfaces for coating, bonding, welding, and final assembly across precision manufacturing sectors. Alkaline cleaners command the largest product-type position due to their versatility across steel and aluminum substrates, while solvent-based systems face structural decline under REACH Annex XVII restrictions on chlorinated and fluorinated chemistries. The aerospace application segment generates premium pricing through NADCAP-compliant precision cleaning requirements, whereas electronics surface preparation represents the fastest-growing demand vector as semiconductor packaging reshoring accelerates across the Netherlands and Ireland.
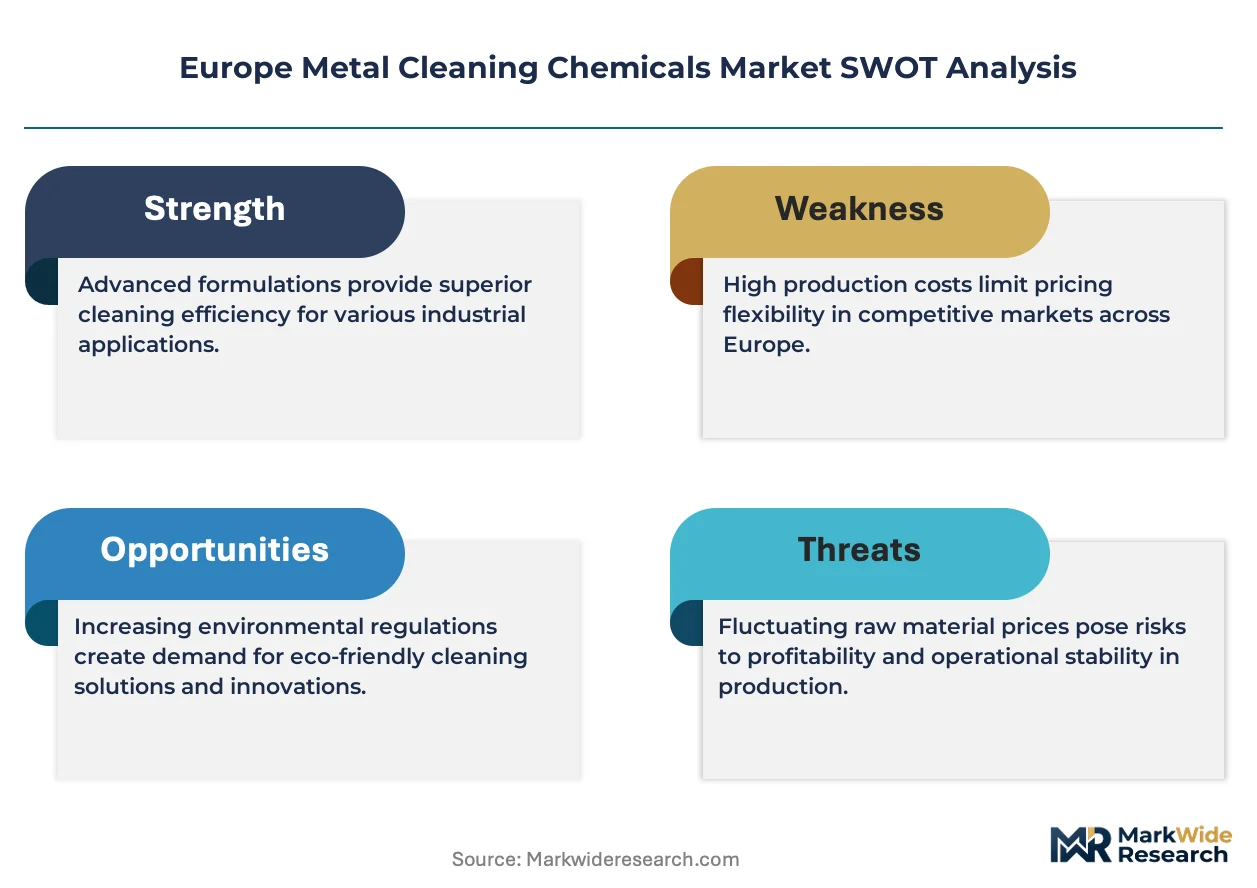
REACH registration requirements and the EU F-Gas Regulation constrain formulation choices for metal cleaning chemicals, forcing suppliers to document substance hazards and phase down high-GWP blowing agents in aerosol delivery systems. ECHA's SVHC candidate list expansion directly shapes R&D priorities, with substance restrictions triggering portfolio redesigns every 24-36 months. Germany's KBA and France's ANSM enforce sector-specific purity standards that elevate compliance costs for pan-European suppliers. Stakeholders must monitor the EU Chemicals Strategy for Sustainability's hazard-class expansion, as the proposed generic risk approach would reclassify numerous established cleaning actives and compress formulation flexibility before the forecast horizon closes.
Market Dynamics
REACH Annex XVII restrictions on chlorinated solvents and the EU F-Gas Regulation are forcing immediate portfolio redesigns, compressing formulation flexibility while simultaneously opening premium positioning for compliant alternatives across German and French automotive pretreatment lines.
Growth Catalysts
- EV Powertrain Manufacturing Scale:Germany's automotive belt is expanding surface treatment capacity for electric motor housings and battery tray assemblies, pulling alkaline cleaner volumes into new substrate preparation workflows.
- REACH-Driven Reformulation Mandates:ECHA's SVHC candidate list expansion triggers mandatory substance substitutions every 24-36 months, creating recurring demand for bio-based surfactant validation and low-VOC certification.
- Semiconductor Packaging Reshoring:The Netherlands and Ireland are attracting advanced packaging fabs that require NADCAP-equivalent precision cleaning for wire bonding and flip-chip assembly preparation.
Market Restraints
- Feedstock Volatility in Ethylene Oxide Derivatives:Specialty amine oxide surfactant costs fluctuate with European naphtha cracking margins, squeezing formulation economics for bath-life extension products.
- Supplier Concentration in Fluorosurfactants:Three producers control per- and polyfluoroalkyl substance alternatives suitable for aerospace precision cleaning, creating supply security risks for NADCAP-compliant operations.
- Technical Ceiling in Aqueous Systems:Water-based cleaners face hard limits removing heavy hydrocarbon soils from cast aluminum engine blocks without elevated temperature or mechanical agitation that damages sensitive substrates.
Strategic Opportunities
- Poland's Emerging Fabrication Cluster:Lower Silesia's automotive supplier parks lack established chemical management programs, creating first-mover advantage for bath-life extension service contracts.
- CSRD-Aligned Carbon Accounting:The EU Corporate Sustainability Reporting Directive mandates Scope 3 chemical footprint disclosure, positioning bio-based cleaners for procurement preference in ESG-screened supply chains.
- Closed-Loop Solvent Recovery:Vacuum distillation systems integrated with vapor degreasing equipment enable on-site solvent regeneration, converting chemical suppliers into circular service providers.
Industry Challenges
- Formulation Chemist Scarcity:REACH dossier preparation requires toxicological assessment expertise that European universities produce insufficiently, extending new product development timelines.
- Legacy Equipment Retrofit Costs:Converting vapor degreasing lines from trichloroethylene to modified alcohol systems demands capital expenditure that mid-tier job shops defer, prolonging non-compliant operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Metal Cleaning Chemicals Market |
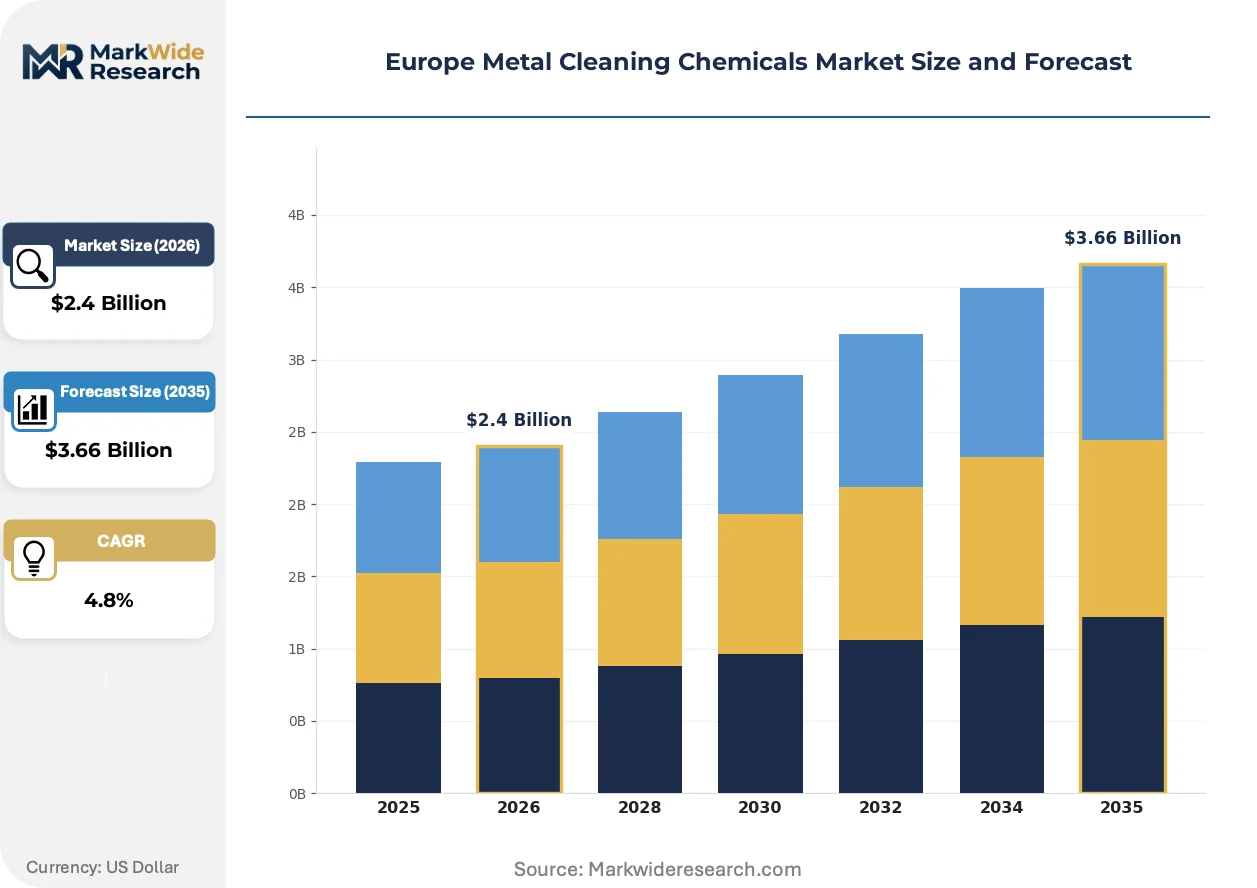
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvents, Alkaline Cleaners, Acids, Surfactants Application: Aerospace, Automotive, Electronics, Industrial Machinery End User: Manufacturers, Maintenance Services, Metal Fabricators, OEMs Packaging Type: Drums, Bottles, Containers, Totes |
| Companies Covered | Dow, Clariant, BASF SE, Stepan Company, Quaker Chemical Corporation, Evonik Industries, Nouryon, Eastman Chemical Company, 3M, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Metal Cleaning Chemicals Market Shifts & Advancements
Formulation chemistry is pivoting toward bio-derived feedstocks and process-integrated service models, with regulatory pressure acting as the primary accelerant rather than end-user preference alone.
Alkaline cleaner technology is migrating from sodium hydroxide-silicate builders toward glucoponide-based surfactant systems that maintain oil-emulsifying performance at reduced temperatures. Tier-1 automotive suppliers in Stuttgart and Wolfsburg are piloting these formulations at 50°C rather than 70°C to cut energy intensity. This migration from conventional caustic chemistry is compressing the addressable market for traditional silicate suppliers while expanding margins for specialty surfactant producers.
The EU Chemicals Strategy for Sustainability's proposed generic risk approach would reclassify numerous established cleaning actives as substances of very high concern based on hazard class alone. Industrial consequence includes mandatory substitution timelines that preempt risk-based exposure assessments. Metal fabrication clusters in the Ruhr region are most affected, with trade associations lobbying for derogations while accelerating alternative screening.
Automotive OEMs are consolidating chemical procurement through single-source pretreatment program contracts that bundle cleaners, conversion coatings, and technical service. Tier-2 and Tier-3 suppliers in France's Auvergne-Rhône-Alpes region face compliance cost burdens as they adapt to customer-mandated chemical management systems. This concentration is most visible in Germany, where KBA type-approval requirements for surface treatment lines elevate documentation standards across the supplier pyramid.
Europe Metal Cleaning Chemicals Market Segmentation
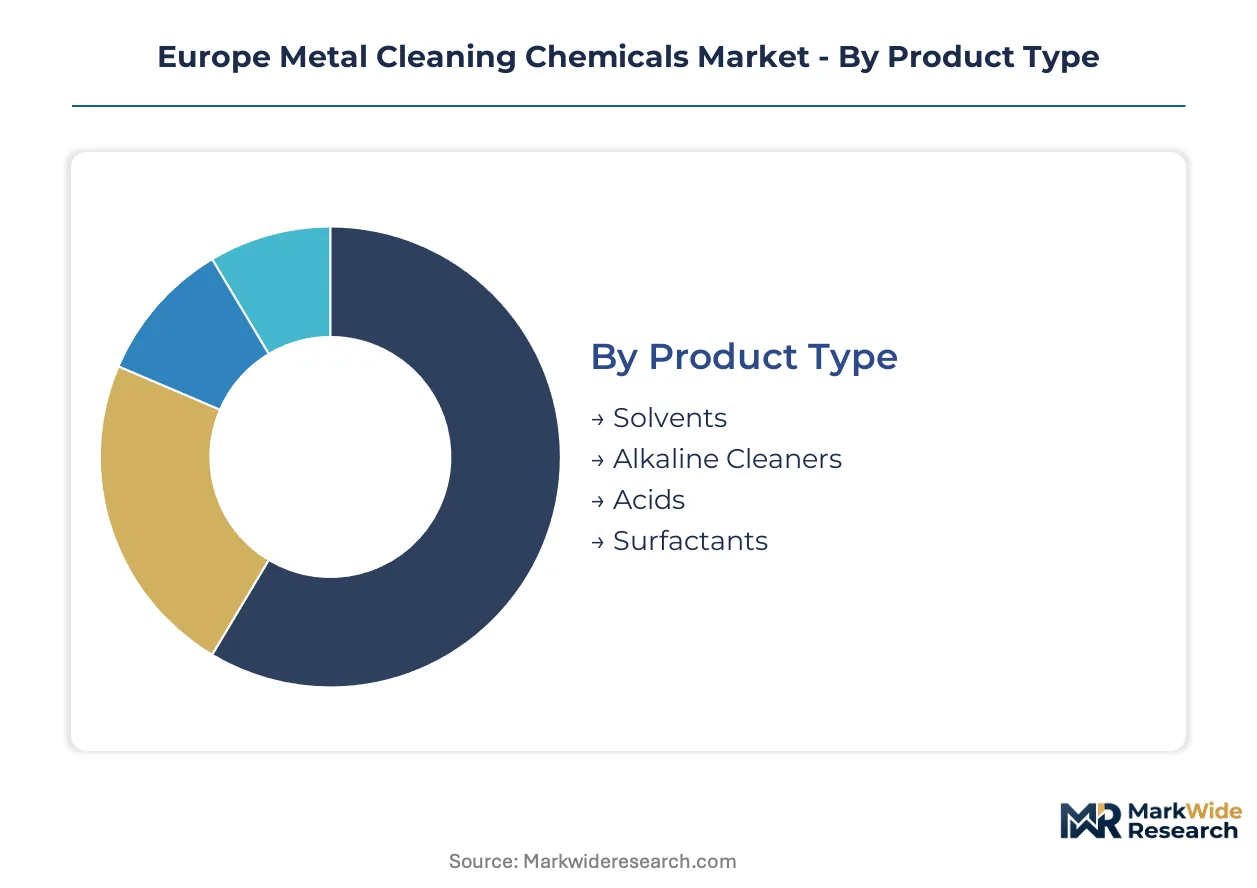
Segmentation in the Europe metal cleaning chemicals market reveals distinct performance profiles across formulation chemistry, end-use intensity, and supply chain configuration. Each dimension carries different regulatory exposure and margin structures that reshape supplier priorities across the forecast window.
Product Type:
Cost tier differentiation separates commodity bulk formulations from specialty surfactant systems commanding premium positioning in precision applications.
- Alkaline Cleaners:Sodium hydroxide-silicate and glucoponide-based formulations emulsify oils from ferrous and aluminum substrates at 40-80°C operating windows. Demand concentrates in Germany's automotive belt where Stuttgart and Wolfsburg facilities are piloting reduced-temperature systems to cut energy intensity under EU Green Deal mandates.
- Solvents:Modified alcohol and hydrocarbon blends target heavy hydrocarbon soil removal where aqueous systems face technical ceilings. REACH Annex XVII restrictions on chlorinated chemistries are compressing addressable volume while elevating pricing power for compliant alternatives in French aerospace clusters.
- Acids:Phosphoric and citric acid formulations remove oxides and scale from metal surfaces prior to coating or bonding operations.
- Surfactants:Amine oxide and bio-derived specialty systems extend bath life and enable low-temperature operation in high-throughput pretreatment lines.
Alkaline cleaners hold installed capacity. Solvent alternatives are rotating up the share rankings as regulatory substitution timelines accelerate.
Application:
End-use maturity varies sharply across sectors, with certification requirements and substrate sensitivity driving formulation specification divergence.
- Automotive:Surface treatment lines for steel and aluminum body-in-white, powertrain, and EV battery tray assemblies consume the largest chemical volumes. Germany's expanding EV manufacturing footprint is pulling alkaline cleaner demand into new substrate preparation workflows for electric motor housings.
- Aerospace:NADCAP-compliant precision cleaning for turbine blades, landing gear, and structural components commands premium pricing through stringent purity standards. The segment faces supply security risks as three producers control PFAS alternatives suitable for high-performance specifications.
- Electronics:Wire bonding and flip-chip assembly preparation for semiconductor packaging is expanding most quickly as reshoring accelerates across Dutch and Irish fabrication facilities.
- Industrial Machinery:General metal fabrication and maintenance cleaning applications operate at lower specification tiers with greater price sensitivity.
Automotive holds installed capacity. Electronics is rotating up the share rankings.
End User:
Customer type determines procurement sophistication, with OEM consolidation programs reshaping access for mid-tier chemical suppliers.
- OEMs:Automotive and aerospace original equipment manufacturers consolidate chemical procurement through single-source pretreatment program contracts bundling cleaners, conversion coatings, and technical service. KBA type-approval requirements in Germany elevate documentation standards across their supplier pyramids.
- Metal Fabricators:Job shops and contract manufacturers in France's Auvergne-Rhône-Alpes region face compliance cost burdens as they adapt to customer-mandated chemical management systems.
- Manufacturers:Tier-1 and Tier-2 component producers operating captive surface treatment lines.
- Maintenance Services:Aftermarket operators providing bath-life extension programs and chemical management services.
OEMs hold installed capacity. Metal fabricators are rotating up the share rankings as Poland's emerging clusters mature.
Packaging Type:
Volume scale and handling infrastructure shape packaging selection across customer segments and geographic density.
- Drums:Standard 200-liter steel and plastic drums serve mid-volume manufacturing operations across Europe's industrial belt with established logistics networks.
- Totes:Intermediate bulk containers reduce handling costs for high-volume automotive pretreatment lines in Germany and France.
- Containers:Specialized vessels for corrosive or temperature-sensitive chemistries.
- Bottles:Small-format packaging for laboratory, pilot-scale, and maintenance service applications.
Drums hold installed capacity. Totes are rotating up the share rankings as OEM consolidation concentrates volume procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across European metal cleaning chemical buyers. Automotive OEMs in Germany absorb premium formulations without volume contraction, while Polish job shops demand commodity pricing on standard alkaline cleaners. France's aerospace sector occupies the middle ground, accepting elevated costs for NADCAP compliance but resisting speculative green premiums.
Germany
EV powertrain manufacturing at Stuttgart and Wolfsburg facilities is pulling alkaline cleaner demand into electric motor housing and battery tray preparation workflows. KBA type-approval requirements for surface treatment lines elevate documentation burdens across the supplier pyramid. The Ruhr metal fabrication cluster faces immediate pressure from ECHA's SVHC candidate list expansion, forcing 24-36 month substitution cycles on established chemistries.
France
Aerospace precision cleaning for turbine blades and landing gear commands premium positioning through NADCAP-compliant specifications. ANSM enforces sector-specific purity standards that elevate compliance costs for pan-European suppliers. The Auvergne-Rhône-Alpes automotive supplier belt is adapting to customer-mandated chemical management systems as OEM consolidation accelerates.
Netherlands
Semiconductor packaging reshoring is attracting advanced fabrication facilities requiring NADCAP-equivalent precision cleaning for wire bonding preparation. The EU Green Deal's decarbonization mandates are accelerating reformulations toward bio-based surfactants in Eindhoven-region electronics clusters. Rotterdam's chemical logistics hub enables just-in-time delivery for high-throughput pretreatment lines serving export markets.
Poland
Lower Silesia's emerging automotive supplier parks lack established chemical management programs, creating first-mover advantage for service providers offering bath-life extension contracts. REACH registration requirements extend compliance timelines for new market entrants relative to established Western European suppliers. Warsaw-based distributors are consolidating procurement for mid-tier fabricators seeking volume discounts on standard formulations.
United Kingdom
Post-Brexit regulatory divergence from REACH is creating dual-registration burdens for suppliers serving both UK and EU markets. Midlands-based automotive component manufacturers are maintaining alkaline cleaner specifications aligned with German OEM requirements to preserve export access. Scotland's electronics assembly sector is expanding precision cleaning capacity for defense and aerospace subcontracting.
Europe Metal Cleaning Chemicals Market Competitive Landscape
Capability concentration sits with specialty surfactant developers; scale advantage sits with integrated petrochemical networks. The market structures around three tiers: multinational chemical conglomerates with backward integration into feedstocks, mid-cap formulators with regional distribution density, and niche specialists in aerospace or electronics certification tiers. Competitive moves center on portfolio redesigns to meet REACH Annex XVII substitution timelines and service model expansion into chemical management programs.
Among diversified chemical conglomerates, BASF SE and Dow occupy positions defined by integrated manufacturing networks and proprietary solvent technology respectively. Evonik Industries sits within the specialty surfactant tier, differentiated through amine oxide chemistry for bath-life extension. These three represent distinct competitive archetypes: feedstock-integrated scale, formulation IP ownership, and application-specific performance optimization.
| Leading Market Players |
|---|
| Dow |
| Clariant |
| BASF SE |
| Stepan Company |
| Quaker Chemical Corporation |
| Evonik Industries |
| Nouryon |
| Eastman Chemical Company |
| 3M |
| Others |
Supply & Pricing Matrix
REACH Annex XVII substitution timelines compress formulation flexibility while simultaneously fragmenting supplier pricing power across compliant and non-compliant tiers. This regulatory chokepoint forces German automotive OEMs to absorb premium pricing for validated low-VOC alternatives while Polish fabricators face extended procurement timelines that compress their operating margins.
Pricing Analysis
Chemical management service contracts now drive lifetime value capture beyond unit formulation sales. Three-tier pricing structure across NADCAP-certified specialty, REACH-compliant standard, and commodity bulk alkaline cleaners separates aerospace precision applications from automotive pretreatment and general fabrication. Cost compression in commodity bulk tiers intensifies as Warsaw-based distributors consolidate procurement for Polish job shops. Automotive OEMs in Stuttgart and Wolfsburg demonstrate lowest price sensitivity, accepting elevated documentation burdens and premium formulations to maintain KBA type-approval compliance.
Supply Chain Analysis
Ethylene oxide derivative feedstocks draw from Belgian and Dutch petrochemical complexes, with specialty amine oxides sourcing from German integrated surfactant networks. Naphtha cracking margins, glucoponide bio-feedstock availability, and fluorosurfactant precursor chemicals constitute critical input dependencies. Single-source vulnerability concentrates in PFAS alternatives suitable for aerospace specifications, where three producers control compliant supply. Distribution runs through Rotterdam's chemical logistics hub for just-in-time delivery to high-throughput automotive pretreatment lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates structural barriers that compound over successive SVHC substitution cycles.
For Market Incumbents: Build certification moats through NADCAP-equivalent validation investments that emerging competitors cannot replicate within standard OEM qualification windows. Deepen backward integration into glucoponide surfactant feedstocks to capture margin compression points as bio-based chemistry mandates accelerate. Anchor channel control through exclusive chemical management service contracts at expanding EV powertrain facilities in Germany.
For New Entrants and Emerging Players: Pursue bath-life extension service contracts in Poland's Lower Silesia automotive supplier parks where established Western European suppliers lack localized technical presence. Target semiconductor packaging reshoring clusters in the Netherlands and Ireland with NADCAP-equivalent precision cleaning formulations. Lead with circular solvent recovery integration rather than commodity formulation pricing.
For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors specialty surfactant developers with validated REACH dossiers over commodity alkaline producers. Long-term viability centers on acquisition targets possessing ECHA pre-registered substance portfolios and existing automotive OEM technical service relationships. Monitor ECHA SVHC candidate list expansion velocity as the primary inflection signal for portfolio redesign demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Surfactant Feedstocks | Captures margin compression points as EU Green Deal mandates accelerate glucoponide chemistry migration. |
| REACH Dossier Pre-Registration Acceleration | Compresses competitor entry timelines as ECHA's 24-36 month substitution cycles intensify. |
| Circular Solvent Recovery Service Deployment | Converts transactional chemical sales into recurring revenue streams at Polish fabrication clusters. |
| NADCAP-Equivalent Certification Investment | Unlocks aerospace premium pricing tiers as PFAS alternative supply concentrates among validated producers. |
| EV Powertrain Pretreatment Line Partnerships | Secures volume anchors at Stuttgart and Wolfsburg facilities expanding surface treatment capacity. |
Research Methodology
Operator-level perspectives from plant managers at German automotive pretreatment facilities, procurement leads at French aerospace subcontractors, distribution channel partners in Rotterdam's chemical logistics hub, and technical R&D directors at specialty surfactant developers anchored the qualitative base. Secondary validation drew from ECHA REACH registration databases, Cefic industry reports, customs trade data for ethylene oxide derivatives, and SEC filings from diversified chemical conglomerates. Bottom-up volume modeling across alkaline cleaner, solvent, acid, and surfactant product tiers triangulated against top-down value estimates derived from OEM procurement consolidation patterns.
Scenario-bracketing around regulatory acceleration and feedstock volatility cases framed the projection horizon. Segmentation dimensions modeled include formulation chemistry grade, end-use industry intensity, packaging format scale, and regional production hub concentration. CAGRs were derived from install-base growth in EV powertrain manufacturing and semiconductor packaging reshoring, cross-referenced against REACH-driven reformulation cycle frequency. Industry-specific inputs incorporated KBA type-approval documentation burden estimates and ECHA SVHC candidate list expansion trajectories.
Sensitivities concentrate around ECHA regulatory acceleration, ethylene oxide feedstock margin volatility, and PFAS alternative supply disruption scenarios. Forecasts reflect documented assumptions regarding substitution timeline adherence and OEM consolidation velocity. Cross-checking against Cefic production statistics and national automotive registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Drain Opener Chemicals Market
Cleaning Chemicals
US Institutional Cleaning Ingredients Market
Cleaning Chemicals
Eco-Label Certified Cleaning Chemicals for Professional Users Market
Cleaning Chemicals
Liquid Detergent Market
Cleaning Chemicals
Coating Removal System Market
Cleaning Chemicals
Brazil Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Dust and Emission Control Chemicals for Ore Handling Market
Cleaning Chemicals
Kitchen Vent Hood and Duct Cleaning Chemicals Market
Cleaning Chemicals
Fabric Softener Market
Cleaning Chemicals
Water-Saving Cleaning Chemical Systems for Professional Use Market
Cleaning Chemicals
Floor Wax Market
Cleaning Chemicals
Latin America Detergent Market
Cleaning Chemicals
Mastic Remover Market
Cleaning Chemicals
Soap and Detergent Market
Cleaning Chemicals
Descaler Market
Cleaning Chemicals
Pipeline Chemical Cleaners Market