
 Non Destructive Testers (NDT) Equipment Market | 2026-2036
Non Destructive Testers (NDT) Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Non Destructive Testers (NDT) Equipment Market Analytics
The EU Green Deal's industrial emissions benchmarking is recalibrating how European manufacturers justify capital expenditure on inspection infrastructure. Baker Hughes Company leverages its energy-sector installed base to anchor recurring service revenue alongside hardware placements. MISTRAS Group specializes in integrated asset protection programs that bundle equipment with predictive analytics, differentiating its offer from pure device vendors. SGS Société Générale de Surveillance SA extends its third-party certification authority into NDT equipment validation, creating channel control over buyer trust architectures.
Non Destructive Testers (NDT) Equipment encompasses instrumentation that evaluates material properties, detects flaws, and assesses structural integrity without compromising the test subject, typically employing frequency ranges from 0.5 MHz to 25 MHz in ultrasonic configurations and X-ray or gamma-ray sources between 10 keV and 15 MeV for radiographic methods. Ultrasonic Testing dominates current procurement volumes across aerospace and energy applications where subsurface crack detection in titanium alloys and welded pressure vessels demands precision. Digital technology architectures are displacing analog systems fastest, driven by real-time data logging requirements and AI-assisted defect classification that reduces inspector interpretation variance.
The American Society of Mechanical Engineers (ASME) Boiler and Pressure Vessel Code, the European Committee for Standardization's EN ISO 17640 framework, and the U.S. Pipeline and Hazardous Materials Safety Administration (PHMSA) integrity management rules collectively mandate inspection frequencies and acceptable flaw thresholds that directly determine equipment replacement cycles and capability upgrades. ASTM International's evolving E317 and E1065 standards for ultrasonic transducer characterization further constrain which device designs qualify for regulated inspections. Stakeholders must weigh the capital cost of phased array and computed radiography platforms against the operational risk of failing audits under tightening third-party accreditation protocols.
Market Dynamics
Digital radiography systems are compressing inspection cycle times from hours to minutes across aerospace MRO networks, forcing analog equipment obsolescence before physical wear. This technological displacement is redrawing competitive boundaries between hardware vendors and software-integrated solution providers.
Growth Catalysts
- PHMSA Integrity Management:Pipeline operators in the United States must replace film-based radiography with digital alternatives under tightened 2024 enforcement guidance, accelerating capital deployment.
- Titanium alloy inspection:Commercial aviation's shift toward single-aisle aircraft with extensive Ti-6Al-4V structures demands phased array ultrasonic systems capable of detecting micro-cracks in forged landing gear components.
- Germany's centralized procurement:Automotive OEMs in Baden-Württemberg coordinate NDT equipment standards through VDI/VDE technical committees, creating pooled demand for automated inspection cells.
Market Restraints
- Scintillator crystal supply:Digital radiography panels depend on cesium iodide and gadolinium oxysulfide inputs concentrated among Japanese and Chinese specialty chemical producers, exposing buyers to price volatility.
- Certification backlog:ASME Section V qualification of automated ultrasonic systems requires 18-24 month validation cycles, freezing procurement decisions for mid-tier inspection service providers.
- Computed tomography substitution:Industrial CT systems are capturing dimensional inspection applications previously served by ultrasonic thickness gauges in additive manufacturing quality control.
Strategic Opportunities
- India's infrastructure buildout:National highway and LNG terminal construction under the PM Gati Shakti initiative is generating first-time NDT equipment demand from regional inspection contractors lacking legacy analog assets.
- EU Green Deal benchmarking:Industrial emissions verification protocols are mandating continuous structural monitoring of carbon capture storage vessels, opening recurring revenue streams for sensor-integrated NDT platforms.
- AI-assisted defect classification:Machine learning algorithms trained on radiographic image databases are converging with portable inspection hardware, enabling technician-delegated screening in remote field locations.
Industry Challenges
- Phased array operator certification:ASNT Level II technicians with ultrasonic flaw detection credentials require 200+ additional training hours for complex weld geometries, constraining deployment velocity.
- Legacy system integration:Analog radiography darkrooms and film processors embedded in established aerospace supply chains resist digital retrofit without production line reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non Destructive Testers (NDT) Equipment Market |
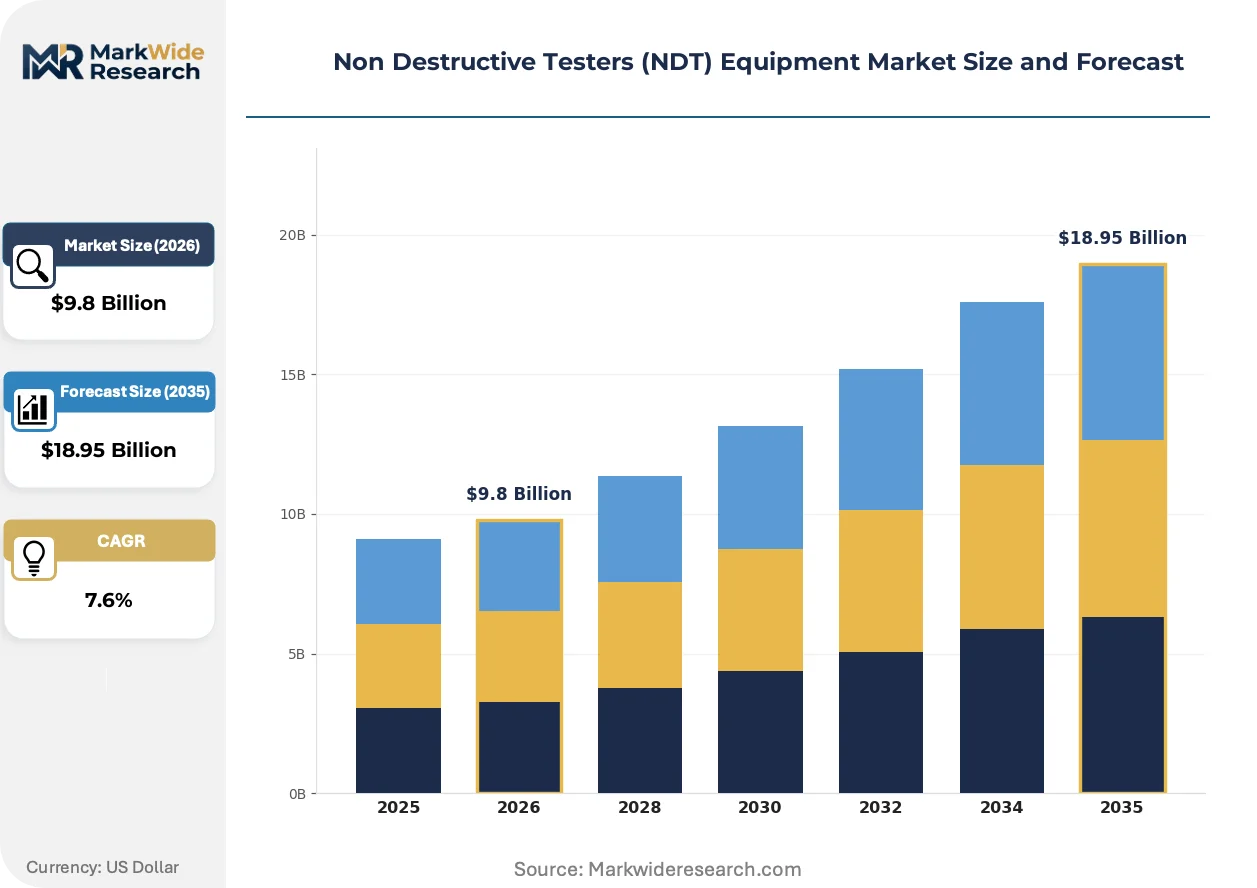
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $18.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Testing, Radiographic Testing, Magnetic Particle Testing, Eddy Current Testing Technology: Digital, Analog, Infrared, Acoustic Application: Aerospace, Automotive, Construction, Manufacturing End User: Oil & Gas, Energy, Defense, Transportation |
| Companies Covered | Evident Corporation, MISTRAS Group, Olympus Corporation, Baker Hughes Company, Bureau Veritas, Applus+, SGS Société Générale de Surveillance SA, Zetec Inc., Sonatest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non Destructive Testers (NDT) Equipment Market Evolving Landscape
Real-time data architectures are collapsing the distinction between inspection hardware and enterprise asset management software. This fusion is reordering how vendors monetize equipment placements and how buyers evaluate total cost of ownership.
Phased array ultrasonic testing is converging with robotics for automated weld inspection in pipeline construction. Offshore energy contractors in the North Sea are deploying crawler-mounted systems for subsea riser examination. This convergence is compressing the addressable market for manual ultrasonic equipment while expanding serviceable contract values for integrated platform providers.
The EU AI Act's risk classification framework is imposing documentation requirements on automated defect recognition algorithms used in safety-critical infrastructure assessment. Manufacturers of radiographic interpretation software must now maintain algorithmic audit trails for notified body review. German TÜV and DEKRA certification bodies are developing specialized accreditation streams for AI-enabled NDT systems, creating compliance differentiation among European suppliers.
Inspection service providers are unbundling equipment ownership from analytical labor, preferring lease-to-operate arrangements over capital purchase. This preference is restructuring vendor revenue models toward per-inspection pricing in North American oil and gas corridors. Baker Hughes and similar energy-sector incumbents are responding with managed service contracts that embed hardware refresh cycles within multi-year operational agreements.
Non Destructive Testers (NDT) Equipment Market Segmentation
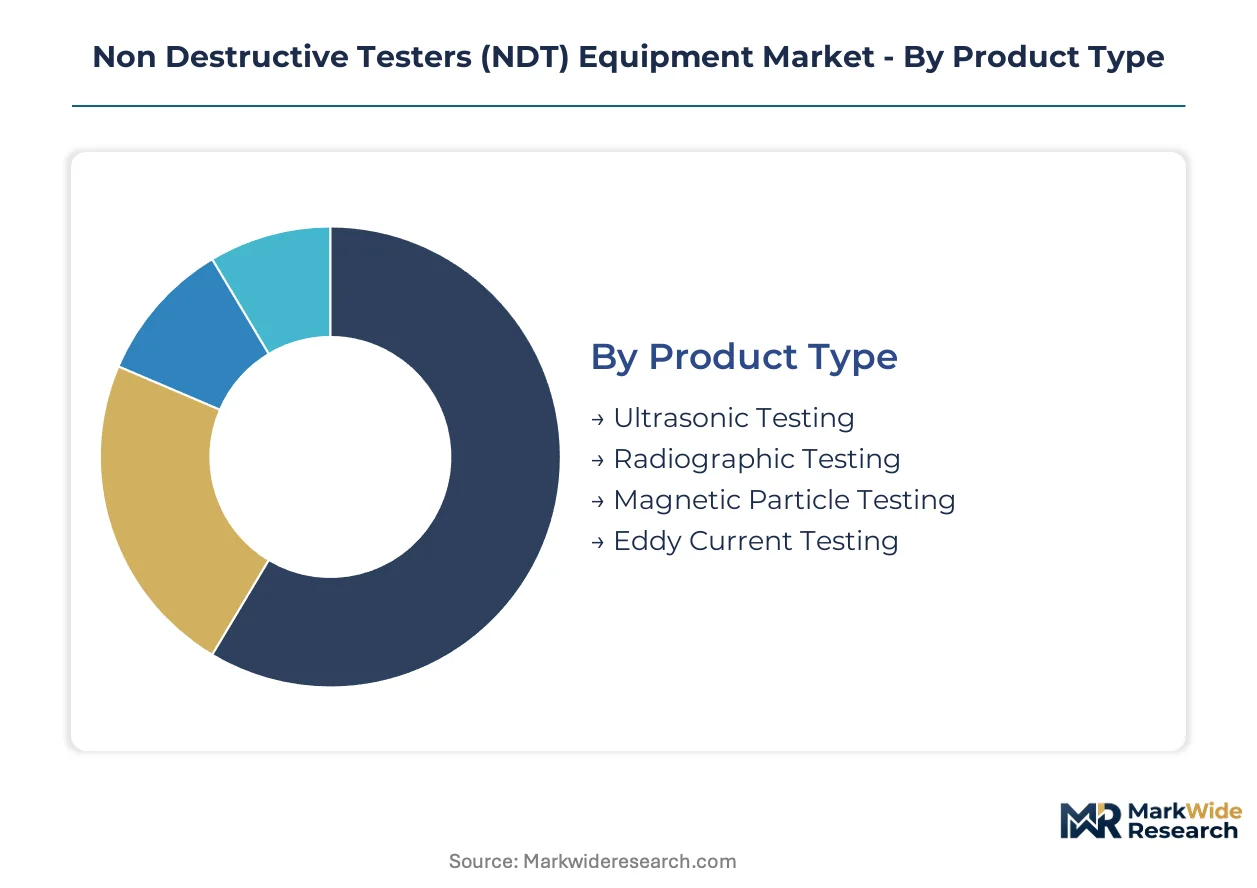
NDT equipment procurement patterns diverge sharply across product architectures and customer operational models. Understanding these fault lines reveals where hardware vendors must build service capabilities versus where pure device sales still dominate.
Product Type:
Supply concentration for core transducers and radiation sources varies dramatically across modalities, reshaping vendor margin structures.
- Ultrasonic Testing:Phased array systems emit pulsed sound waves between 0.5 MHz and 25 MHz through piezoelectric transducers to map subsurface discontinuities. Aerospace MRO facilities in Germany's industrial corridor are consolidating procurement for automated weld inspection cells, driven by Ti-6Al-4V landing gear certification mandates from EASA.
- Radiographic Testing:X-ray and gamma-ray systems between 10 keV and 15 MeV penetrate dense alloys to reveal internal voids and inclusions. Pipeline operators across the Permian Basin are replacing film-based units with digital flat-panel detectors under PHMSA's tightened integrity management enforcement.
- Magnetic Particle Testing:Electromagnetic yokes and prods detect surface-breaking cracks in ferromagnetic components through iron particle aggregation.
- Eddy Current Testing:Alternating current coils induce electromagnetic fields to identify conductivity variations in heat exchanger tubing and aircraft skin fasteners.
Today's leader: Ultrasonic Testing. Tomorrow's challenger: Radiographic Testing.
Technology:
Cost tier separation between digital architectures and legacy analog systems is widening faster than hardware depreciation schedules.
- Digital:Solid-state detectors and FPGA-based signal processors enable real-time data logging and AI-assisted defect classification. Offshore contractors in the North Sea are deploying digital ultrasonic platforms with embedded predictive analytics for subsea riser monitoring.
- Analog:Vacuum tube amplifiers and cathode ray tube displays persist in budget-constrained inspection shops. India's regional highway contractors under PM Gati Shakti are acquiring analog radiography units as first-time infrastructure buildout equipment.
- Infrared:Thermal imaging arrays detect heat signatures from friction-induced defects and electrical resistance variations.
- Acoustic:Passive listening systems capture stress wave emissions from crack propagation in pressure vessel walls.
Digital platforms command premium pricing. Analog retains residual volume in emerging market entry segments.
Application:
Customer type differentiation separates capital-intensive scheduled inspection programs from reactive maintenance deployments.
- Aerospace:Precision requirements for turbine blade and airframe certification drive demand for multi-modal inspection stations. Commercial aviation's single-aisle production surge is concentrating procurement for automated ultrasonic cells capable of micro-crack detection in forged titanium structures.
- Automotive:High-volume production lines require rapid cycle-time testing for spot welds and cast components. Baden-Württemberg OEMs coordinate NDT standards through VDI/VDE technical committees, creating pooled demand for integrated inspection cells.
- Construction:Structural steel and concrete integrity assessment for bridges and high-rise frameworks.
- Manufacturing:General fabrication quality control across metalworking and polymer processing operations.
Aerospace anchors premium system revenue. Automotive scales unit volume through standardization.
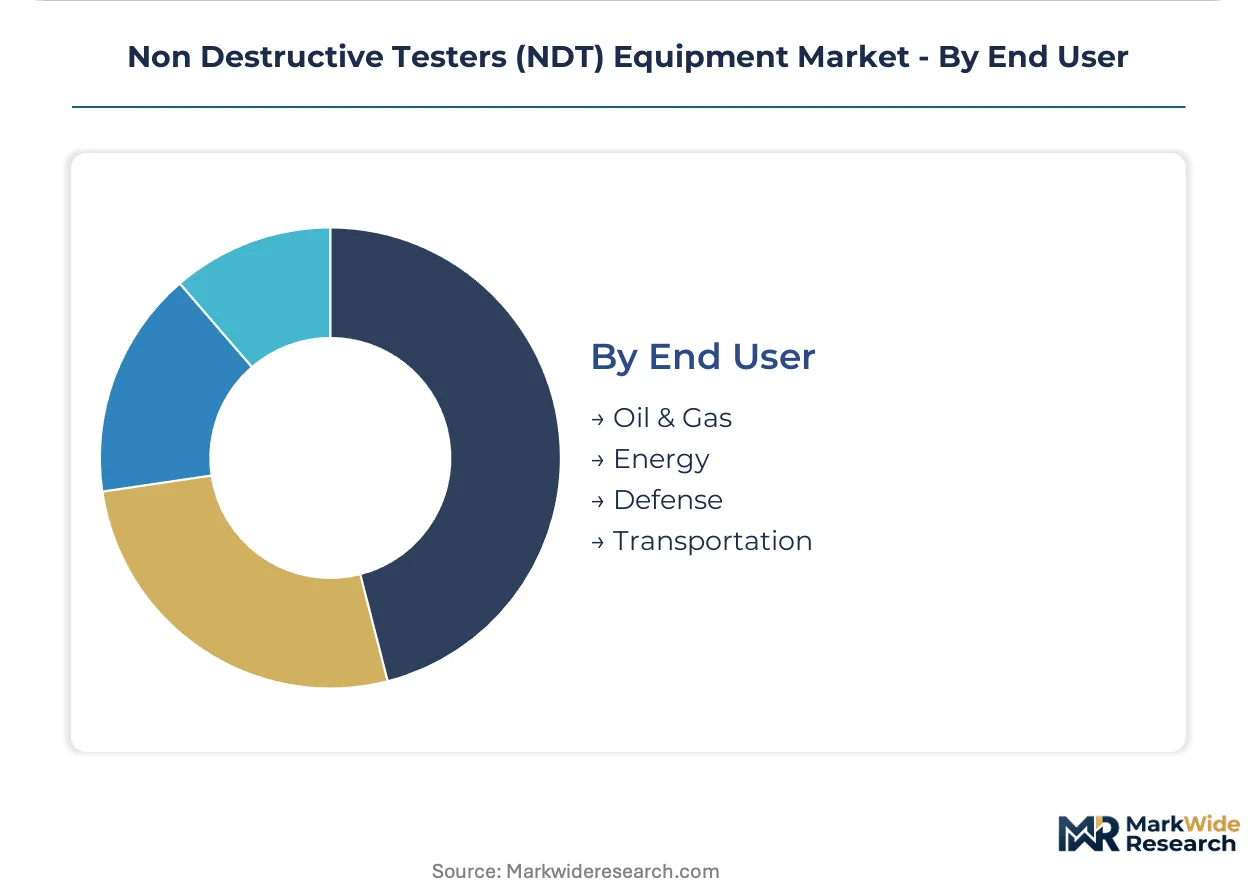
End User:
Volume concentration in energy infrastructure creates procurement gravity that pulls adjacent segments toward similar technical specifications.
- Oil & Gas:Pipeline integrity management and refinery pressure vessel surveillance dominate equipment deployment. PHMSA's 2024 enforcement guidance is mandating digital radiography conversion across U.S. interstate transmission networks.
- Energy:Power generation asset protection spans nuclear steam generators and wind turbine blade composite inspection. EU Green Deal emissions benchmarking is mandating continuous structural monitoring for carbon capture storage vessels.
- Defense:Military airframe and naval vessel certification requirements with classified inspection protocols.
- Transportation:Rail wheel and axle testing alongside maritime hull survey operations.
Oil & Gas drives replacement cycles. Energy is expanding fastest through decarbonization infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The NDT equipment industry traces its commercial origins to post-war Germany's industrial reconstruction, where radiographic inspection methods were standardized for pressure vessel certification before spreading to North American pipeline networks and Asian manufacturing hubs.
United States
Pipeline integrity mandates from PHMSA and API standards are accelerating digital radiography replacement cycles across interstate transmission networks. The 2024 enforcement guidance explicitly mandates film-to-digital conversion for corrosion monitoring. Houston's energy corridor hosts concentrated procurement activity from inspection service contractors serving Permian Basin operators.
Germany
Automotive OEMs and energy infrastructure operators coordinate NDT procurement through centralized VDI/VDE technical committees in Baden-Württemberg. EU Green Deal industrial emissions benchmarking is recalibrating capital expenditure justification for continuous structural monitoring systems. Munich's industrial cluster anchors automated inspection cell development for Ti-6Al-4V aerospace components.
China
National infrastructure buildout under dual carbon goals is generating demand for pressure vessel inspection across LNG terminal construction. GB standards for ultrasonic testing are converging with international frameworks to qualify equipment for export manufacturing. Shanghai's Yangtze River Delta concentration hosts domestic equipment manufacturers scaling phased array production.
India
PM Gati Shakti national highway and LNG terminal construction is creating first-time NDT equipment demand from regional inspection contractors. BIS certification requirements for imported testing equipment are shaping procurement patterns among emerging service providers. Gujarat's industrial corridor concentrates petrochemical inspection activity requiring radiographic and ultrasonic modalities.
Japan
METI industrial standards for non-destructive evaluation maintain stringent qualification protocols for automated ultrasonic systems in nuclear power generation. JIS certification requirements constrain equipment import eligibility for domestic inspection service providers. Nagoya's Chubu region anchors aerospace supply chain integration of phased array inspection for forged landing gear components.
Non Destructive Testers (NDT) Equipment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the NDT equipment landscape, with integrated energy service companies maintaining distinct advantages in recurring revenue capture. The vendor structure separates into three tiers: diversified industrial conglomerates with energy-sector installed bases, specialized inspection service providers bundling equipment with analytics, and pure-play hardware manufacturers competing on technical specifications. Dominant competitive moves include backward integration into sensor component supply and strategic partnerships linking hardware placements with predictive maintenance software platforms.
Within the diversified industrial tier, Baker Hughes Company exemplifies the energy-sector incumbent model leveraging installed base relationships for managed service contracts. MISTRAS Group occupies a position among integrated asset protection specialists bundling equipment deployment with predictive analytics capabilities. SGS Société Générale de Surveillance SA represents the third-party certification authority archetype extending validation services into equipment trust architectures. Olympus Corporation and Zetec Inc. sit within the pure-play hardware manufacturer segment competing on transducer precision and signal processing architectures.
| Leading Market Players |
|---|
| Evident Corporation |
| MISTRAS Group |
| Olympus Corporation |
| Baker Hughes Company |
| Bureau Veritas |
| Applus+ |
| SGS Société Générale de Surveillance SA |
| Zetec Inc. |
| Sonatest |
| Others |
Value Network & Pricing Analysis
Cesium iodide and gadolinium oxysulfide crystal costs cascade from Japanese and Chinese specialty chemical producers through digital radiography panel assembly, stratifying equipment pricing across certification-grade tiers from aerospace-qualified units to emerging-market analog alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ASME-certified phased array systems from industrial-grade ultrasonic units and entry-level analog radiography kits. Price differentiation hinges on transducer precision grade and third-party accreditation tier, with PHMSA-mandated digital conversion intensifying cost compression in the mid-market segment. Regional inspection contractors in India exhibit highest price sensitivity, while German automotive OEMs prioritize standardization over unit economics.
Supply Chain Analysis
Refurbishment flows for analog film processors and darkroom equipment create secondary supply channels as North American pipeline operators retire legacy radiography assets. Component sourcing concentrates in Japan for scintillator crystals, China for flat-panel detector substrates, and Germany for precision transducer ceramics. Single-source vulnerability persists for cesium iodide inputs from Japanese chemical producers. Distribution runs through authorized service networks embedding calibration and certification services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in NDT equipment rests on software-integrated platform shifts that capture recurring service revenue alongside hardware placements, compressing pure-device vendor economics.
For Market Incumbents: Extend predictive analytics bundling into existing energy-sector installed bases before industrial CT systems capture dimensional inspection share from ultrasonic thickness gauges. Deepen backward integration into piezoelectric transducer supply to defend margin position against specialty chemical price volatility. Prioritize ASME Section V pre-certification investments to shorten validation cycles freezing mid-tier competitor procurement decisions. For New Entrants and Emerging Players: Begin with AI-assisted defect classification software layered on portable hardware for remote field deployment, targeting India's PM Gati Shakti infrastructure contractors lacking legacy analog asset burdens. Focus initial penetration on lease-to-operate arrangements preferred by North American oil and gas inspection service providers. Develop TÜV/DEKRA certification pathways early for EU AI Act compliance differentiation. For Investors and Strategic Acquirers: Consolidation pressure builds where pure-play hardware manufacturers face software-integrated solution provider displacement and analog-to-digital replacement cycle exhaustion. Long-term viability favors asset-light designers with predictive maintenance platform traction over capital-heavy producers dependent on unit volume. Watch ASNT Level II technician certification bottlenecks as inflection indicator for automated system deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Transducer Supply | Captive piezoelectric ceramic production insulates margins from Japanese and Chinese specialty chemical volatility. |
| AI-Assisted Defect Classification Development | Machine learning algorithms reduce inspector interpretation variance while creating EU AI Act compliance differentiation. |
| Lease-to-Operate Service Model Launch | Per-inspection pricing captures recurring revenue from inspection service providers unbundling equipment ownership. |
| ASME Pre-Certification Investment | Accelerated Section V validation cycles unlock frozen procurement decisions among mid-tier service providers. |
| Industrial CT Partnership Formation | Additive manufacturing quality control positioning counters dimensional inspection substitution threat from ultrasonic gauges. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with NDT equipment procurement managers, inspection service operations directors, aerospace quality certification leads, and energy-sector asset protection specialists with secondary validation from ASME code documentation, PHMSA enforcement guidance, EASA airworthiness directives, and EU Green Deal industrial emissions protocols.
Historical trendline analysis of equipment replacement cycles and technology displacement patterns anchors the projection framework across product type, technology architecture, application vertical, and end-user industry segments. CAGRs derive from regression-adjusted shipment trajectories incorporating titanium alloy inspection demand from commercial aviation production schedules and pipeline integrity mandate compliance timelines.
Several conditions sit outside the modeled scope, including geopolitical trade restrictions on scintillator crystal exports and unannounced regulatory revisions to radiographic qualification protocols. Forecasts reflect base-case assumptions regarding certification backlog resolution and technician training pipeline expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Global NVH Testing Market
Test and Measurement
Chiplet Integration and Die-to-Die Interconnect Test Solutions Market
Test and Measurement
Pump Testers Market
Test and Measurement
Hardness Testing Machine Market
Test and Measurement
Latin America Measurement and Test Equipment Market
Test and Measurement
Circuit Tracer Market
Test and Measurement
Automated Test Equipment Market
Test and Measurement
Battery Testing Equipment Market
Test and Measurement
Ground Resistance Testers Market
Test and Measurement
AI-Enabled Semiconductor Defect Classification and Review Systems Market
Test and Measurement
Paperless Recorders Market
Test and Measurement
Global Leak Test Equipment Market
Test and Measurement
Smart Contact Lens Optical and Telemetry Test Equipment Market
Test and Measurement
Wi-Fi Test Equipment Market
Test and Measurement
Density Meter Market
Test and Measurement
Surface Vision and Inspection Equipment Market