
 China Washing Machine Market | 2026-2036
China Washing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
China Washing Machine Market Outlook
Consumer leasing and installment-based appliance financing is rewriting competitive access across China's washing machine sector, enabling mid-tier buyers to shift from semi-automatic to fully automatic models without upfront capital strain. Haier leverages its captive ecosystem of smart home platforms to bundle financing with IoT-enabled service contracts. Midea Group sustains manufacturing scale through backward integration into compressor and motor production in its Guangdong and Hubei facilities. TCL Corporation anchors its position through vertical control over display and semiconductor components that feed smart washing interfaces.
A washing machine is an electromechanical appliance engineered to clean textiles through programmed cycles of agitation, rinsing, and spin-drying, with drum capacities typically ranging from five to twelve kilograms and rotational speeds between 800 and 1600 revolutions per minute; its primary purpose is to automate garment and linen cleaning for residential, commercial, and industrial end users. Front load configurations command premium positioning due to superior water efficiency and gentler fabric handling, while fully automatic systems are displacing semi-automatic units in tier-two and tier-three Chinese cities where piped water infrastructure has matured. Smart technology segments are drawing R&D investment toward AI-driven load sensing and remote diagnostic capabilities, though conventional platforms still dominate volume in price-sensitive rural prefectures.
MIIT energy-efficiency labeling requirements and GB standards on water consumption are mandating inverter motor adoption and low-water wash cycles, directly influencing product design priorities for domestic OEMs. SAMR market surveillance protocols enforce compliance testing that raises barriers for uncertified imports and subscale local assemblers. China's dual carbon goals from MEE are accelerating refrigerant and wastewater discharge regulations that extend to washing machine production facilities. Stakeholders must monitor how tightening efficiency tiers reshape margin structures and whether smart connectivity mandates emerge as the next compliance frontier.
Market Dynamics
MIIT energy-efficiency labeling and GB water consumption standards are compressing design cycles for domestic OEMs, forcing inverter motor adoption and low-water wash architectures ahead of typical refresh timelines.
Growth Catalysts
- Urban residential procurement programs:Municipal housing authorities in Shanghai and Beijing are bundling fully automatic washing machines into new development specifications, accelerating replacement of semi-automatic units in high-rise complexes.
- GB standards tightening:Performance thresholds for water efficiency and energy consumption are mandating technology upgrades that create compliance-driven refresh demand across installed bases.
- IoT platform convergence:Smart home ecosystems are integrating washing machines into unified control interfaces, generating attach-rate expansion for connected models through cross-device bundling incentives.
Market Restraints
- Copper and steel input volatility:Drum assemblies and motor windings depend on commodity metals with price swings that compress margin predictability for volume manufacturers.
- Yangtze River Delta supply concentration:OEM clusters serving both domestic and export channels create geographic vulnerability to regional logistics disruptions or energy rationing protocols.
- Semi-automatic substitution persistence:Price-sensitive rural prefectures continue prioritizing lower-capital units despite infrastructure maturation, slowing premium model penetration in tier-three and tier-four cities.
Strategic Opportunities
- Sichuan and Chongqing corridor expansion:Western inland provinces with accelerating urbanization rates remain underpenetrated relative to coastal markets, offering first-mover positioning for distribution network buildout.
- AI-driven predictive maintenance:Convergence of machine learning algorithms with vibration sensors and motor current signature analysis enables subscription-based service revenue models detached from hardware margins.
- Dual carbon goal incentives:MEE wastewater discharge regulations and carbon intensity targets are creating preferential financing channels for manufacturers certifying production facilities under green bond frameworks.
Industry Challenges
- Inverter motor engineering talent scarcity:Specialized electromagnetic design and variable-frequency drive firmware development capabilities concentrate among limited supplier engineering teams, constraining rapid product iteration.
- SAMR compliance timeline compression:Accelerated market surveillance testing protocols are extending certification cycles for new model introductions, delaying revenue recognition against competitor launches.
- Legacy semi-automatic service infrastructure:Existing repair networks and spare parts distribution optimized for mechanical systems face retooling costs to support electronic control module diagnostics and replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Washing Machine Market |
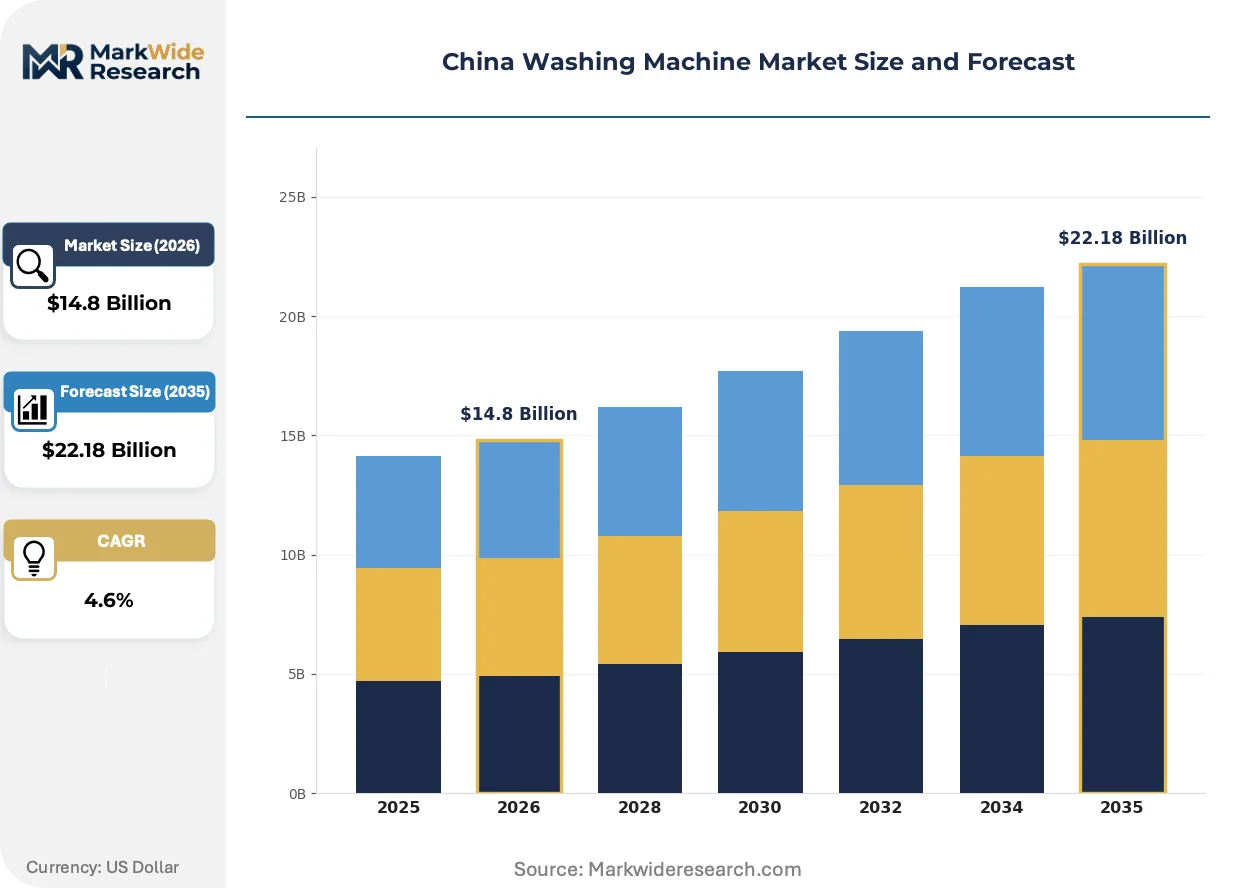
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Load, Top Load, Semi-Automatic, Fully Automatic End User: Residential, Commercial, Industrial, Hospitality Technology: Smart, Conventional, Eco-Friendly, Energy Efficient Distribution Channel: Online, Offline, Direct Sales, Retail |
| Companies Covered | LG Electronics, TCL Corporation, Haier, Shandong Xiaoya Group, Hisense, Midea Group, Xiaomi, Guangdong Welly, Siemens, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Washing Machine Market Strategic Shifts
Smart connectivity architectures and AI-enabled load optimization are redefining product differentiation beyond mechanical specifications, while regulatory pressure on resource efficiency accelerates hardware redesign cycles.
Direct-drive inverter motor systems are eliminating belt-and-pulley mechanical linkages in favor of integrated rotor-stator configurations that reduce energy loss and vibration. Tier-one and tier-two city buyers are specifying these platforms in new construction and replacement cycles at accelerating rates. This technology is digitizing motor control algorithms, enabling real-time torque adjustment based on fabric load sensors and enabling remote diagnostic telemetry that compresses service response times.
MIIT's tightening efficiency labeling tiers are mandating step-function improvements in water and electricity consumption per wash cycle. Domestic manufacturers must redesign drum geometries and spray patterns to meet thresholds that disqualify legacy platforms from subsidy eligibility. Front-load configurations with heat-pump drying integration are capturing disproportionate design investment as these platforms score highest on GB standard compliance matrices.
Installment-based appliance financing is displacing upfront cash purchases among mid-tier buyers in tier-two and tier-three cities. E-commerce platforms and captive finance arms of major OEMs are embedding credit decisioning into purchase workflows, unbundling the transaction from traditional retail banking relationships. This behavioral shift concentrates in the Yangtze River Delta manufacturing corridor where wage growth and credit bureau coverage have matured sufficiently to support scaled underwriting.
China Washing Machine Market Segmentation
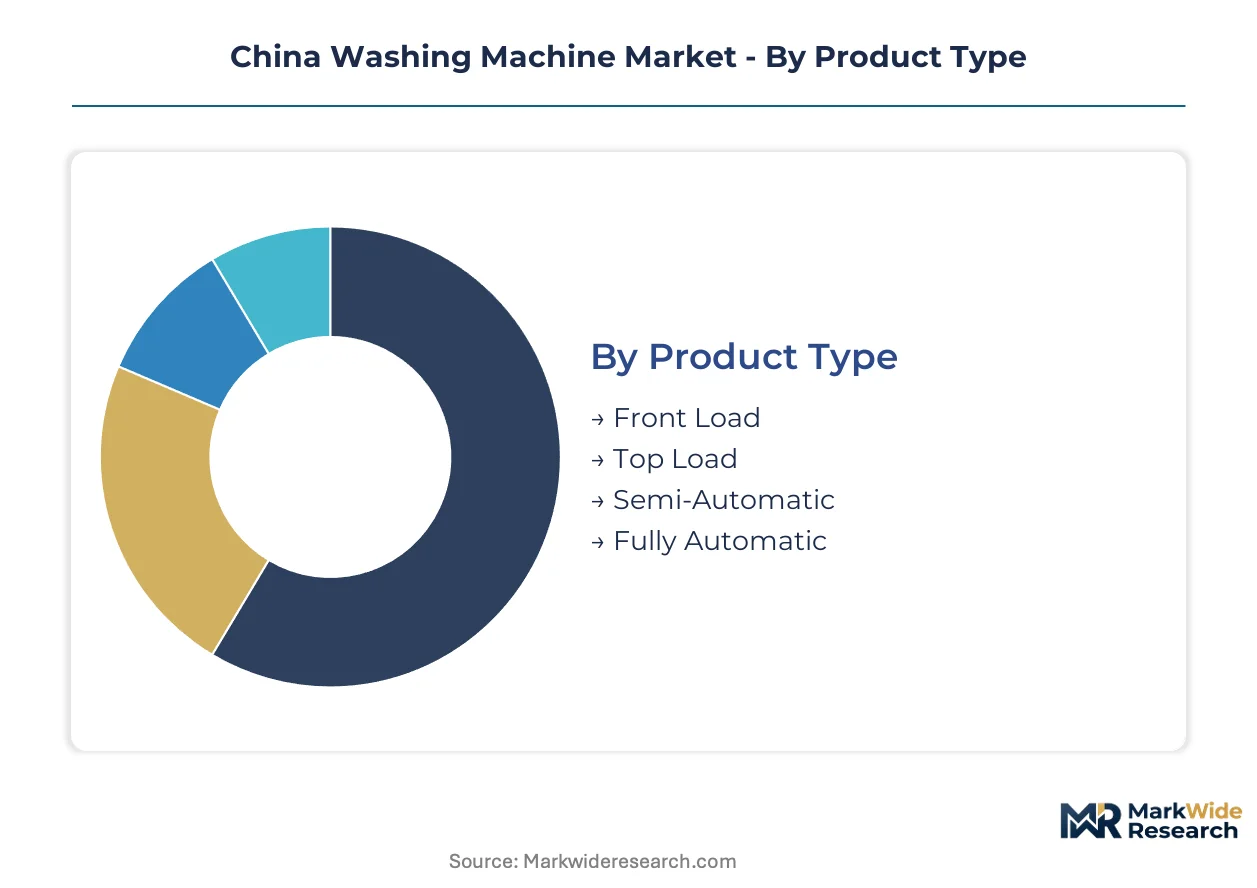
Segmentation clarity determines procurement strategy for municipal housing authorities and OEM product planners navigating MIIT efficiency tiers. Distinct performance requirements across installation environments create divergent margin profiles and service contract structures.
Product Type:
After-sales-service intensity varies sharply by mechanical complexity, with inverter-driven platforms demanding specialized technician networks that semi-automatic units bypass entirely.
- Fully Automatic:Integrated electronic control modules manage water levels, cycle timing, and spin speeds without manual intervention. Demand concentrates in Shanghai and Beijing high-rise complexes where municipal procurement specifications mandate hands-free operation. MIIT efficiency labeling thresholds favor these platforms for subsidy eligibility.
- Front Load:Horizontal drum orientation enables heat-pump drying integration and superior water extraction at 1200-1600 RPM. Yangtze River Delta manufacturing corridors are retooling assembly lines toward these configurations as GB standard compliance tightens.
- Top Load:Vertical axis designs with agitator or impeller mechanisms dominate replacement cycles in legacy residential stock. These units retain mechanical simplicity that reduces field service training requirements.
- Semi-Automatic:Twin-tub configurations requiring manual water filling and transfer between wash and spin cycles. Rural prefectures in western provinces sustain demand through lower capital thresholds and repairability.
By volume, top load units lead. By growth pace, fully automatic configurations are expanding most quickly.
End User:
Cost tier stratification separates capital-intensive commercial installations from price-sensitive residential procurement, with hospitality segments occupying a hybrid position on equipment financing terms.
- Residential:Individual household acquisition through retail channels or developer bundling in new construction. Tier-two and tier-three cities are displacing semi-automatic units as piped water infrastructure matures.
- Commercial:Laundromat operators and multi-unit housing facilities specifying industrial-capacity equipment with coin or card payment integration. These buyers prioritize mean-time-between-failures metrics over upfront capital.
- Hospitality:Hotels and serviced apartments requiring NSF-certified sanitation cycles and accelerated throughput. Procurement runs through specialized facility management contractors rather than consumer retail.
- Industrial:Textile processors and institutional laundries with continuous-batch processing requirements. These installations specify stainless steel construction and programmable chemical injection systems.
Residential segments dominate absolute unit shipments. Hospitality applications are gaining share fastest on post-pandemic sanitation protocol upgrades.
Technology:
Volume concentration in conventional platforms contrasts with margin accretion in connected and certified-efficient variants, creating a dual-track competitive structure.
- Energy Efficient:Inverter motor systems with variable-frequency drives achieving MIIT Grade 1 or 2 efficiency labels. These platforms qualify for municipal subsidy programs and green bond financing.
- Smart:IoT-enabled units with Wi-Fi connectivity, remote diagnostic telemetry, and AI-driven load sensing. Haier and Midea are bundling these with captive smart home ecosystem subscriptions.
- Eco-Friendly:Reduced water consumption architectures meeting GB standard thresholds through spray pattern optimization and drum geometry redesign. These specifications are becoming mandatory for new model certification.
- Conventional:Electromechanical control systems without connectivity or variable-speed capability. These platforms retain dominance in rural distribution channels where price elasticity remains acute.
Conventional technology still leads on volume. Smart platforms show the steepest expansion trajectory on ecosystem bundling incentives.
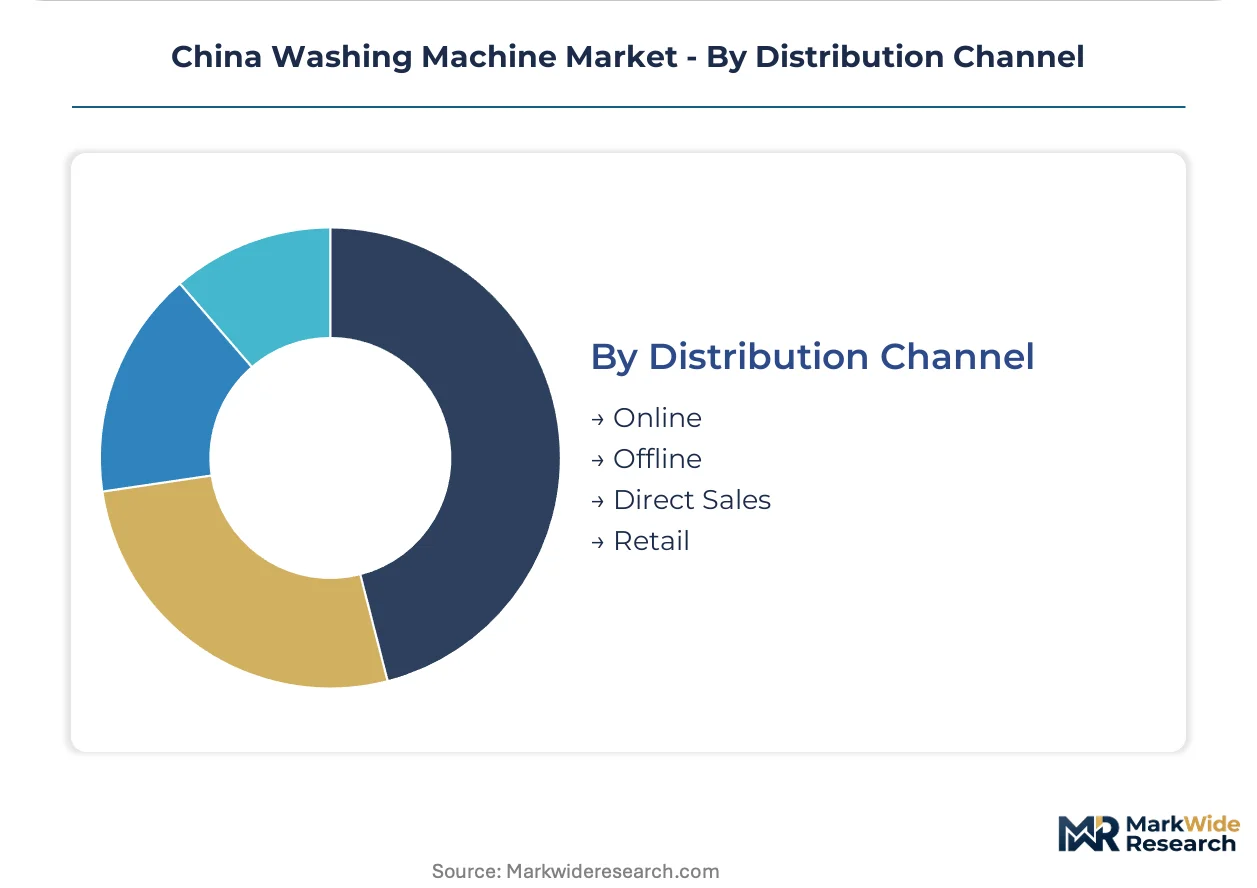
Distribution Channel:
Customer type fragmentation separates installment-financed e-commerce buyers from cash-purchasing retail customers, with direct sales capturing institutional procurement.
- Online:E-commerce platforms with embedded credit decisioning for installment purchases. JD.com and Tmall are capturing mid-tier buyer migration from physical retail through 0% financing promotions.
- Offline:Branded experience stores and appliance hypermarkets where tactile evaluation precedes purchase. These channels retain importance for first-time buyers in lower-tier cities.
- Direct Sales:OEM captive salesforces targeting municipal housing authorities and hospitality procurement departments. These relationships secure multi-year service contracts alongside hardware.
- Retail:Third-party electronics and home goods retailers with floor space allocation negotiated annually. Margin pressure from platform fees is compressing these channels' viability for premium models.
Online channels lead on volume growth. Direct sales are climbing the fastest on municipal procurement program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's washing machine production exceeds domestic absorption, with coastal manufacturing clusters feeding export channels into Southeast Asia and the Middle East while inland provinces absorb overflow capacity. Import dependence concentrates in precision inverter motors and sensor modules where domestic substitution lags. Regional demand fragmentation reflects urban-rural infrastructure divides and varying MIIT subsidy eligibility across provincial boundaries.
Yangtze River Delta
Shanghai and Jiangsu province anchor the highest-value procurement, with municipal housing authorities mandating fully automatic units in new residential complexes. MIIT Grade 1 efficiency labeling qualifies these buyers for provincial green appliance subsidies. The Suzhou-Wuxi manufacturing corridor hosts OEM assembly clusters serving both domestic retail and export markets.
Pearl River Delta
Guangdong province generates concentrated demand through Shenzhen and Guangzhou's high-rise residential expansion. GB water consumption standards enforce heat-pump dryer integration in premium new construction. Midea Group's captive compressor facilities in Foshan anchor backward integration into core components.
Beijing-Tianjin-Hebei
The northern capital region enforces the strictest dual carbon compliance timelines under MEE wastewater discharge protocols. SAMR market surveillance testing concentrates certification laboratories here, accelerating compliance timelines for national model launches. Tianjin port facilities handle inbound component logistics for inverter motor supply chains.
Sichuan-Chongqing
Western inland urbanization is driving first-time appliance penetration in tier-three cities where piped water infrastructure has matured. Provincial finance bureaus are piloting installment-based appliance subsidies to displace semi-automatic legacy stock. Chongqing's automotive supplier base is retooling motor winding capabilities toward washing machine inverter production.
Shandong Peninsula
Qingdao and Yantai host Haier's ecosystem headquarters and smart home platform development. Regional procurement runs through direct sales channels targeting municipal housing authorities rather than retail. The peninsula's port infrastructure supports component import for domestic OEMs lacking captive motor production.
China Washing Machine Market Competitive Environment
On the supply side, the industry is consolidating around ecosystem-integrated conglomerates with captive financing arms, while component specialists and contract assemblers occupy fragmented tiers below. Three archetypes dominate: vertically integrated home appliance conglomerates with smart home platforms, display and semiconductor specialists leveraging component control, and regional contract manufacturers serving price-sensitive distribution. Competitive dynamics center on backward integration into motors and compressors, and strategic partnerships with e-commerce platforms for embedded credit decisioning.
Within the ecosystem-integrated tier, Haier and Midea Group exemplify platform-centric positioning through captive smart home architectures and in-house component production. TCL Corporation occupies a position anchored by vertical control over display and semiconductor supply chains that feed connected appliance interfaces. These three represent divergent paths to margin defense: ecosystem subscription revenue, manufacturing scale, and component technology leverage.
| Leading Market Players |
|---|
| LG Electronics |
| TCL Corporation |
| Haier |
| Shandong Xiaoya Group |
| Hisense |
| Midea Group |
| Xiaomi |
| Guangdong Welly |
| Siemens |
| Others |
Value Chain & Pricing Dynamics
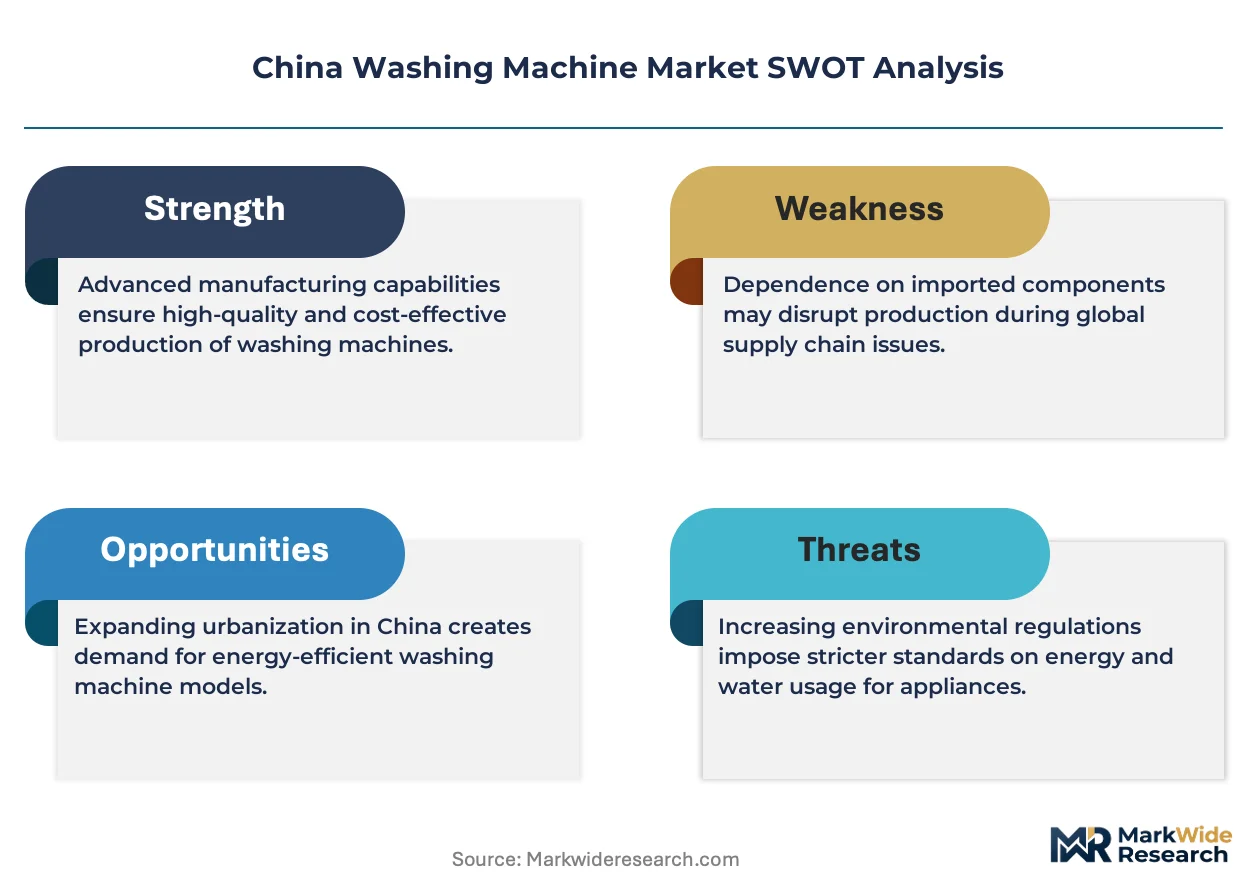
Overcapacity in the Yangtze River Delta assembly corridor compresses supplier margins while concentrating pricing power among OEMs with captive motor production. MIIT efficiency labeling mandates force component upgrades that feed through as tiered product positioning, separating subsidy-eligible platforms from legacy mechanical systems.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on MIIT Grade 1 certification status and inverter motor integration depth. Cost compression in economy-tier units is intensifying because copper and steel input volatility squeezes contract manufacturers lacking backward integration. Rural prefectures exhibit acute price sensitivity, while municipal housing authorities in Shanghai and Beijing prioritize specification compliance over capital outlay.
Supply Chain Analysis
Export-control restrictions on precision inverter motor technology limit component flows from Japan and South Korea into domestic assembly lines. Manufacturing gravity centers on China, with critical dependencies on Malaysian semiconductor packaging and Australian copper concentrate. Single-source vulnerability concentrates in variable-frequency drive firmware suppliers. Distribution runs through JD.com and Tmall platforms with embedded credit decisioning, bypassing traditional retail banking relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China washing machine market is exiting a cyclical trough as municipal procurement programs and GB standard compliance cycles trigger replacement demand. Inventory destocking in the Yangtze River Delta manufacturing corridor signals upstream restocking ahead.
For Market Incumbents: Insulate margin structures by deepening backward integration into compressor and motor winding capabilities at Guangdong and Hubei facilities. SAMR compliance timeline compression threatens new model launch cadence; preemptive certification investment with Beijing-Tianjin-Hebei testing laboratories accelerates revenue recognition against competitor delays. For New Entrants and Emerging Players: Western inland provinces with accelerating urbanization rates offer first-mover positioning for distribution network buildout. Sichuan and Chongqing corridor penetration targets price-sensitive buyers migrating from semi-automatic units as piped water infrastructure matures. Partner with provincial finance bureaus piloting installment-based appliance subsidies to displace legacy mechanical stock. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across smart connectivity platform development as AI-driven load sensing commoditizes. Long-term viability favors acquisition targets with captive smart home ecosystem subscriptions rather than hardware-only manufacturers. Monitor MIIT mandates on connectivity requirements as the inflection signal for platform-centric consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Motor Captive Production | Backward integration into Guangdong and Hubei facilities defends margin compression from commodity volatility. |
| Smart Home Platform Integration | Haier's ecosystem bundling generates recurring service revenue detached from hardware replacement cycles. |
| Sichuan-Chongqing Distribution Buildout | First-mover positioning in underpenetrated western provinces captures urbanization-driven appliance penetration. |
| MIIT Grade 1 Certification Investment | Provincial green appliance subsidies flow exclusively to efficiency-labeled platforms in Shanghai and Beijing. |
| AI Predictive Maintenance Subscription | Machine learning convergence with vibration sensors enables service revenue models beyond unit sales. |
Study Parameters
Desk research of MIIT regulatory filings, GB standard documentation, and municipal procurement specifications preceded structured interviews with OEM product planners, component supplier engineering directors, and e-commerce platform category managers. Secondary validation drew from SAMR market surveillance protocols, Yangtze River Delta customs trade data, and provincial housing authority development specifications. Bottom-up shipment estimates triangulated against top-down absorption forecasts across the projection horizon.
Assumptions held fixed include MIIT efficiency labeling tier thresholds and GB water consumption standard enforcement timelines; variables tested include copper price volatility bands and rural infrastructure maturation rates. Segmentation dimensions modeled encompass product type, end user, technology tier, and distribution channel. CAGRs derived from installed base replacement cycles and new construction appliance bundling ratios. Forecast inputs incorporated inverter motor adoption curves and smart connectivity attach rates.
Macroeconomic conditions sit as an overlay; deviation in residential construction permit issuance or provincial subsidy fund allocation would shift the trajectory. Forecasts reflect these assumptions without claiming predictive certainty. Material shifts in SAMR testing protocol acceleration or dual carbon goal enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
United Kingdom Handheld Vacuum Cleaners Market
Appliances
Washing Appliances Market
Appliances
India Washing Machine Market
Appliances
North America Compact Dishwasher Market
Appliances
Germany Compact Dishwasher Market
Appliances
Egypt Microwave Ovens Market
Appliances
Oman Microwave Ovens Market
Appliances
Asia-Pacific Tumble Dryers Market
Appliances
Laundry Dryer Market
Appliances
UAE Dishwasher Market
Appliances
Hairdryer Market
Appliances
Triple Barrel Waver Market
Appliances
Global Vended Laundry Equipment Market
Appliances
Automatic Dishwasher Market
Appliances
Middle East Portable Washing Machines Market
Appliances
Colombia Appliances and Electronics Market