
 Middle East Portable Washing Machines Market | 2026-2036
Middle East Portable Washing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Portable Washing Machines Market Insights
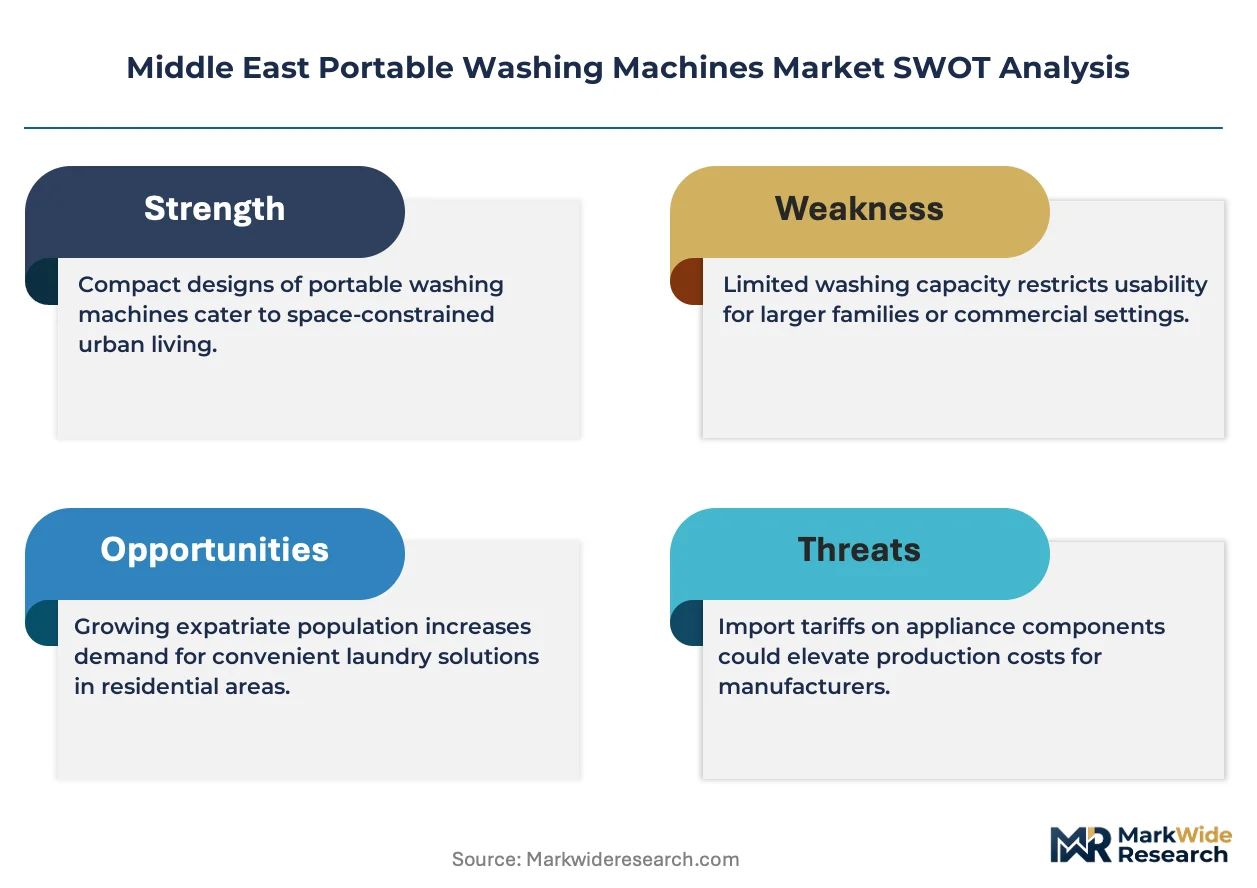
Gulf-based appliance manufacturing clusters is recalibrating output toward compact, energy-efficient formats suited to shrinking residential footprints. SuperGeneral leverages its regional assembly footprint to serve price-sensitive segments across the Levant and North Africa. LG Electronics Inc. anchors premium positioning through inverter-motor technology and extended warranty programs. Samsung competes aggressively on smart-home integration, offering Wi-Fi-enabled diagnostics that appeal to tech-forward buyers in the UAE and Qatar.
Middle East portable washing machines denote self-contained laundry units typically rated below 7 kg capacity, designed for installation without dedicated plumbing infrastructure and operable on standard electrical outlets. These machines employ either pulsator or tumble-drum mechanisms, with water consumption ranging from 15 to 45 liters per cycle depending on load configuration and efficiency class. Compact and washer-dryer combo variants command the fastest expansion trajectory as apartment dwellers and seasonal residents prioritize space optimization over full-size alternatives. The 3-4 kg capacity band dominates unit shipments due to its alignment with single-person and small-family households prevalent across Gulf urban centers.
SASO's water-efficiency labeling requirements and the UAE's Emirates Authority for Standardization and Metrology (ESMA) energy-performance standards are tightening compliance thresholds for imported appliances, effectively filtering out low-tier manufacturers. Saudi Arabia's Saudi Energy Efficiency Center mandates minimum efficiency ratings that directly influence product mix decisions by distributors serving the Kingdom. Stakeholders must monitor evolving Gulf standard harmonization and the pace of smart-grid integration mandates to anticipate which feature sets will secure shelf space in the region's consolidating retail channels.
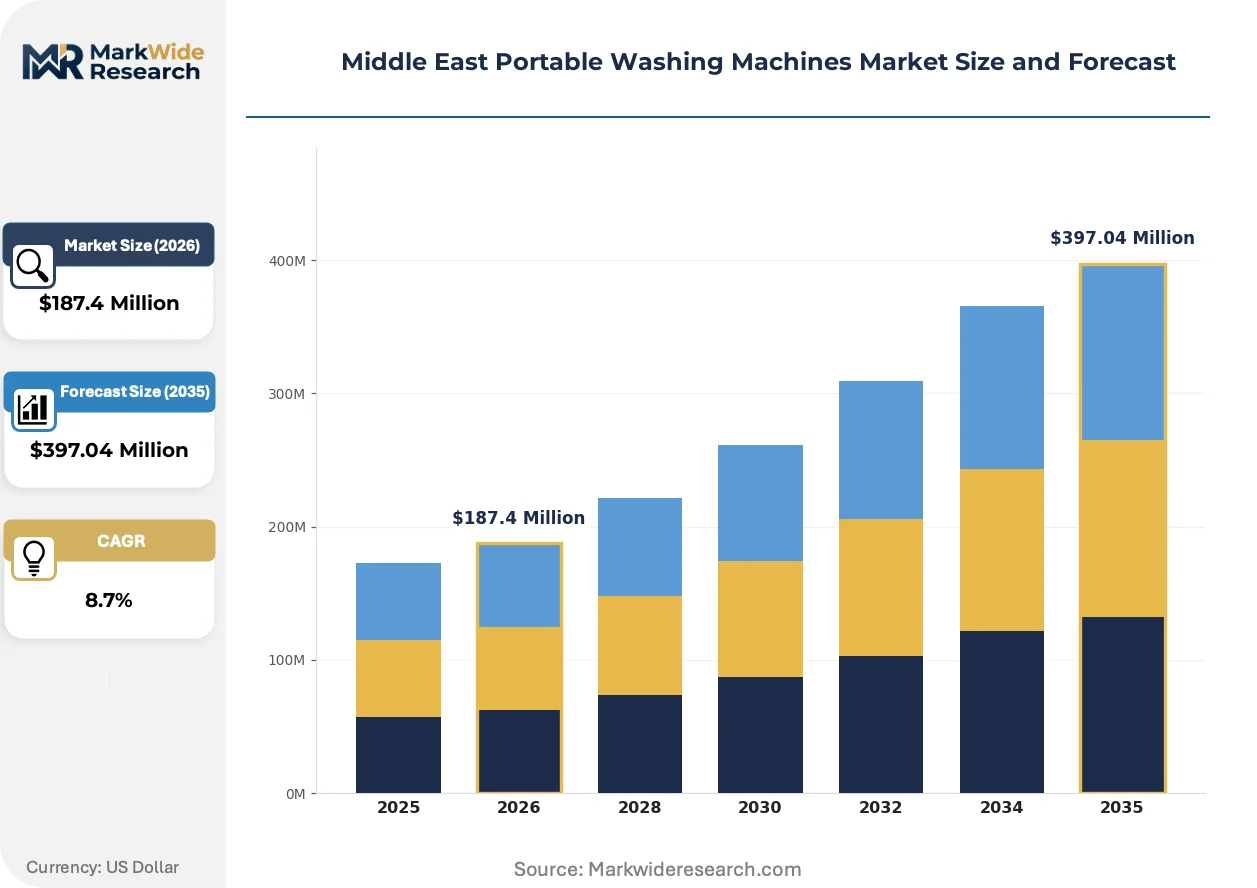
Market Dynamics
Water-efficiency mandates from Saudi Standards, Metrology and Quality Organization (SASO) and the UAE's Emirates Authority for Standardization and Metrology (ESMA) are compressing product development cycles while filtering import eligibility, forcing manufacturers to redesign thermal and hydraulic systems for Gulf-specific operating conditions.
Growth Catalysts
- SASO Water-Efficiency Labeling:Mandatory efficiency tiers for washing machines are accelerating replacement demand in Saudi Arabia as older stock becomes non-compliant, creating pull-through for certified compact models.
- High-Density Residential Construction:Apartment towers in Dubai's Business Bay and Riyadh's King Abdullah Financial District are specifying space-constrained appliances, embedding portable units into developer procurement templates.
- Inverter-Motor Technology:Brushless DC motor adoption is reducing per-cycle electricity draw by 30-40% versus conventional designs, aligning with ESMA energy-performance thresholds and utility rebate eligibility.
Market Restraints
- Steel and Copper Input Volatility:Drum assemblies and motor windings depend on commodity metals whose price swings compress assembler margins and destabilize distributor pricing agreements.
- Single-Source Compressor Supply:Gulf-based manufacturers rely on Chinese refrigeration component suppliers for washer-dryer combos, creating vulnerability to shipping disruptions and tariff adjustments.
- Water-Quality Variability:Hard water conditions in Qatar and Bahrain accelerate heating-element calcification, shortening product lifespans and elevating warranty claim rates versus temperate-climate benchmarks.
Strategic Opportunities
- Levant Secondary Cities:Amman and Beirut exhibit underpenetrated portable-appliance channels relative to Gulf capitals, with independent retailers commanding shelf-space allocation flexibility.
- Solar-Compatible DC Operation:Off-grid installations in Saudi Arabia's remote worker housing and UAE desert tourism camps are creating demand for low-voltage washing units compatible with photovoltaic arrays.
- Smart-Grid Integration Mandates:Dubai Electricity and Water Authority's demand-response programs incentivize Wi-Fi-enabled appliances that accept remote cycle-delay commands during peak-load periods.
Industry Challenges
- Certification Timeline Compression:ESMA and SASO are shortening approval windows for new efficiency classes, forcing manufacturers to parallel-track testing across multiple notified bodies.
- Retrofit Installation Complexity:Older apartment stock in Jeddah's historic districts lacks grounded electrical infrastructure, requiring electrician dispatch and elevating total cost of ownership.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Portable Washing Machines Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Top-Load, Front-Load, Compact, Washer-Dryer Combo End User: Households, Hotels, Laundromats, RV Owners Capacity: 1-2 kg, 3-4 kg, 5-6 kg, 7-8 kg Distribution Channel: Online, Retail Stores, Wholesalers, Distributors |
| Companies Covered | SuperGeneral, Panasonic Corporation, LG Electronics Inc., Danby, Haier, Nikai, Samsung, IFB Appliances, Siemens AG, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Portable Washing Machines Market Trends and Innovations
Product engineering in the Middle East portable washing machines market is pivoting toward dual-axis optimization: water-thermal efficiency for regulatory compliance and connectivity architecture for smart-city integration. Material selection and control-system design are converging on Gulf-specific operating envelopes.
Inverter-driven heat-pump drying is absorbing the thermal load previously handled by resistive heating elements in washer-dryer combos. Saudi-based property developers are specifying these units for new-build serviced apartments, prioritizing ESMA A++ ratings for marketing differentiation. The technology is absorbing margin pressure from electricity tariff escalation while extending garment-fabric longevity through lower peak temperatures.
SASO's 2024 update to water-efficiency labeling requirements is mandating liters-per-kilogram disclosure and minimum performance floors for imported appliances. This regulatory tightening is disqualifying legacy OEMs lacking Gulf-certified test data, consolidating shelf access for pre-qualified suppliers. Compact 3-4 kg capacity models face the steepest compliance burden due to higher per-unit water ratios.
Developer-direct procurement is displacing traditional electronics-retail channels for volume placements in multi-unit residential projects. Emaar and Damac in Dubai are negotiating master supply agreements with manufacturers for fitted-appliance packages, bypassing distributor markups. This channel shift is most visible in the UAE's build-to-rent segment, where standardized unit fit-outs prioritize warranty consolidation and single-point service accountability.
Middle East Portable Washing Machines Market Segmentation
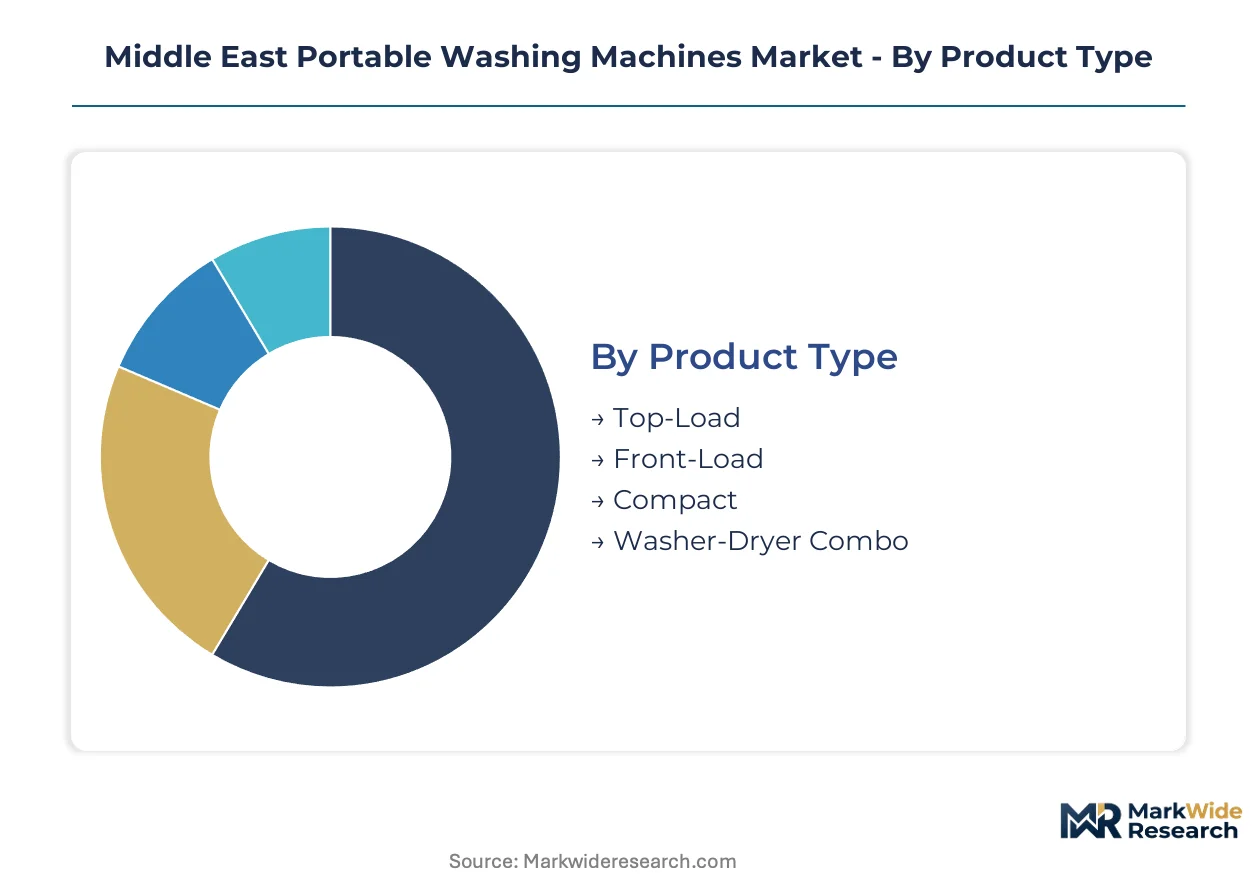
Portable washing machine purchasing in the Middle East hinges on space constraints, water access limitations, and regulatory compliance thresholds. Buyers trade off load capacity against installation flexibility, with SASO efficiency tiers filtering eligible options. Channel selection reflects urgency, price sensitivity, and after-service availability across Gulf urban corridors.
Product Type:
Buyers prioritize footprint dimensions and plumbing independence when selecting format architecture for constrained residential environments.
- Top-Load:Pulsator-driven vertical drums accommodate irregular loading patterns and tolerate higher sediment content in municipal water supplies. Demand clusters in Saudi Arabia's secondary cities where price elasticity exceeds space sensitivity.
- Front-Load:Horizontal tumble mechanisms extract more water per cycle, reducing drying burden in humid coastal climates. Riyadh's King Abdullah Financial District serviced apartments specify these units for ESMA A-rated efficiency credentials.
- Compact:Sub-50 cm width formats target studio apartments and worker housing with nonexistent laundry infrastructure. Dubai's Business Bay build-to-rent towers embed these into developer procurement templates.
- Washer-Dryer Combo:Condensation or heat-pump drying eliminates external venting requirements. Qatar's high-rise stock favors these for balcony-free floor plans, though hard-water calcification elevates maintenance costs.
Volume sits with Compact units; growth tilts toward Washer-Dryer Combo formats.
End User:
Usage intensity and cycle frequency separate commercial operators from residential purchasers, with warranty terms and service response times driving vendor selection.
- Households:Single-person and small-family units in Jeddah's Al-Hamra district and Dubai's Jumeirah Lakes Towers dominate unit shipments. SASO water-efficiency rebates accelerate replacement of pre-2023 stock.
- Hotels:Boutique properties in Beirut's Gemmayzeh and Amman's Rainbow Street deploy portable units for guest laundry services where full commercial installations prove uneconomical. Cycle durability requirements exceed residential benchmarks.
- Laundromats:Coin-operated and card-payment portable clusters serve labor camp peripheries in Saudi Arabia's Eastern Province. Volume purchasing concentrates through Damman-based distributors.
- RV Owners:Saudi desert tourism operators and UAE caravan parks demand 12V DC-compatible units for off-grid photovoltaic installations. Load capacity constraints limit segment expansion.
Households absorb shipment volume; Hotels are expanding most quickly.
Capacity:
Load size selection correlates directly with household composition and available floor space in high-density Gulf developments.
- 1-2 kg:Single-drum mini washers target dormitory residents and temporary worker housing. Bahrain's labor accommodation regulations mandate individual laundry access, sustaining niche demand.
- 3-4 kg:Dual-person household optimization with per-cycle water consumption below 30 liters. This band aligns with SASO's most stringent efficiency tier thresholds and dominates Riyadh-Jeddah corridor sales.
- 5-6 kg:Small-family configurations balance load flexibility against portability trade-offs. Sharjah's mid-income apartment stock shows rising specification rates.
- 7-8 kg:Upper capacity limit for portable classification, approaching semi-permanent installation requirements. Demand concentrates in UAE villa subdivisions where space constraints are less acute.
3-4 kg claims volume leadership; 5-6 kg is gaining share fastest.
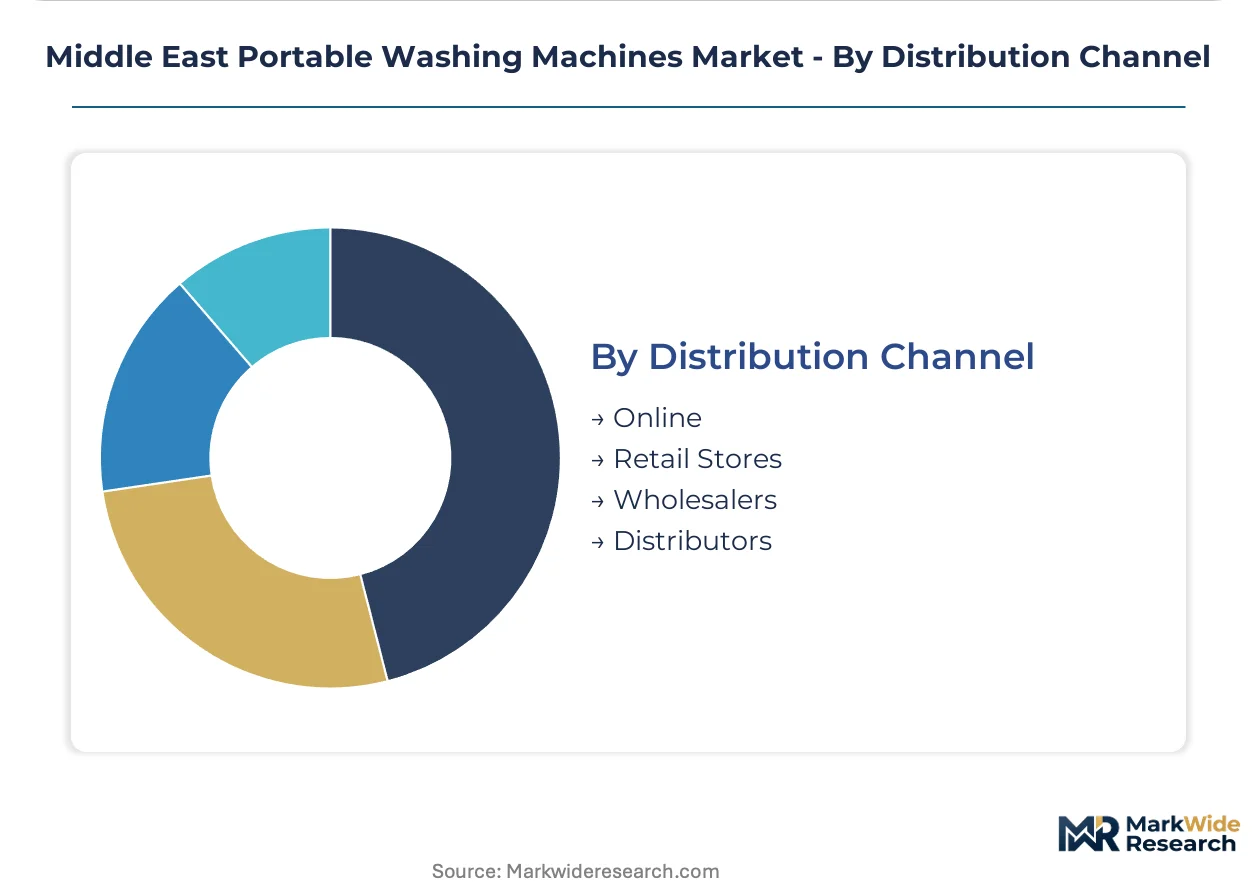
Distribution Channel:
Channel selection reflects buyer urgency, technical consultation needs, and price transparency requirements across Gulf retail ecosystems.
- Online:Marketplace platforms and direct-to-consumer sites capture comparison-shopping behavior among tech-forward UAE and Qatar demographics. ESMA certification badges filter search results.
- Retail Stores:Electronics hypermarkets in Dubai's Deira and Riyadh's Olaya district provide physical verification of dimensions and noise levels. Staff training on SASO labeling varies by banner.
- Wholesalers:Volume aggregation for property developer procurement and hospitality fleet replacement. Dubai's Al Aweer wholesale cluster handles regional re-export to Levant markets.
- Distributors:Authorized networks manage warranty registration and service dispatch. Saudi Arabia's distributor consolidation is reducing parallel import channels.
Retail Stores maintain volume dominance; Online channels show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper and steel supply chains from Jebel Ali anchor Gulf manufacturing networks. Regional procurement templates now embed SASO-certified efficiency tiers into developer specifications. Water-scarcity regulations are compressing product development cycles across Arabian Peninsula markets.
Saudi Arabia
Riyadh's King Abdullah Financial District and Jeddah's Al-Hamra corridor drive specification demand for compact 3-4 kg units. SASO's water-efficiency labeling mandates minimum performance floors that filter import eligibility. The Eastern Province's Dammam-based distributors aggregate volume for labor camp and hospitality fleet procurement.
United Arab Emirates
Dubai's Business Bay build-to-rent towers and Abu Dhabi's Al Reem Island embed portable units into standardized fit-outs. ESMA energy-performance standards tighten compliance thresholds for inverter-motor technology adoption. Sharjah's mid-income apartment stock shows rising specification rates for 5-6 kg capacity bands.
Qatar
High-rise residential towers in Doha's West Bay and Lusail City favor washer-dryer combos for balcony-free floor plans. Hard water conditions accelerate heating-element calcification, elevating warranty service requirements. The country's national standardization body enforces efficiency disclosure parallel to Gulf harmonization efforts.
Kuwait
Salmiya and Hawalli districts concentrate demand from single-person households in aging apartment stock. Electricity tariff escalation drives interest in heat-pump drying technology. Independent retailers in Kuwait City maintain shelf-space flexibility for emerging compact formats.
Bahrain
Manama's diplomatic quarter and Riffa's villa compounds split demand between compact and mid-capacity segments. Labor accommodation regulations mandate individual laundry access, sustaining niche 1-2 kg mini washer demand. The country's water utility promotes rebate programs for ESMA-equivalent efficiency tiers.
Middle East Portable Washing Machines Market Competitive Landscape
Global majors compete with regional champions across certification velocity and distribution reach. The vendor base clusters into three tiers: premium technology licensors, regional assembly specialists, and price-optimized volume suppliers. Strategic archetypes include Gulf-certified efficiency leaders, Levant-focused re-export aggregators, and smart-home integration specialists. Competitive moves concentrate on master supply agreements with property developers and parallel-track certification across multiple notified bodies.
Within the regional assembly tier, SuperGeneral leverages its Gulf footprint to serve price-sensitive segments across the Levant and North Africa. LG Electronics Inc. anchors premium positioning through inverter-motor technology representation. Samsung occupies a position emphasizing smart-home integration vectors for tech-forward buyers in the UAE and Qatar.
| Leading Market Players |
|---|
| SuperGeneral |
| Panasonic Corporation |
| LG Electronics Inc. |
| Danby |
| Haier |
| Nikai |
| Samsung |
| IFB Appliances |
| Siemens AG |
| Others |
Pricing and Supply Chain Analysis
Chinese motor-winding specialists concentrated in Guangdong and Zhejiang provinces feed component cost differentials that separate Gulf-assembled economy tiers from premium inverter-motor imports. Labor-cost spreads between these manufacturing clusters and regional Dubai assembly operations compress margin structures for mid-market distributors serving Saudi Arabia's price-sensitive Eastern Province.
Pricing Analysis
Warranty bundling separates premium positioning from unbundled service tiers across distributor networks. Three-tier pricing structure across premium, standard, and economy levels tracks SASO certification grade and inverter-motor inclusion. Cost compression in economy tiers intensifies because Chinese component suppliers face steel and copper volatility. Labor camp procurement managers in Dammam exhibit highest price sensitivity; Dubai developer-direct buyers prioritize warranty consolidation over unit cost.
Supply Chain Analysis
Certification gating through SASO and ESMA notified bodies filters eligible suppliers before volume allocation decisions. Manufacturing concentrates in China, South Korea, and Vietnam for drum assemblies, motor components, and control systems. Raw material dependencies center on steel for drums, copper for windings, and semiconductor chips for inverter drives. Single-source compressor supply from Chinese refrigeration specialists creates vulnerability to shipping disruptions. Distribution runs through Jebel Ali wholesale clusters for Levant re-export and direct developer procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as SASO efficiency mandates and certification timeline compression force sub-scale assemblers out of import eligibility.
For Market Incumbents: Anticipate margin pressure from developer-direct procurement bypassing distributor markups by securing master supply agreements with Emaar and Damac for standardized fit-outs. Invest in parallel-track certification across multiple notified bodies to compress approval windows for new efficiency classes. Backward integration into Gulf-based assembly reduces exposure to Chinese component tariff volatility.
For New Entrants and Emerging Players: Launch via independent retailer networks in Amman and Beirut where shelf-space allocation flexibility exceeds Gulf hypermarket concentration. Target underpenetrated Levant secondary cities with compact 3-4 kg units priced below LG and Samsung premium positioning. Emphasize solar-compatible DC operation for Saudi remote worker housing and UAE desert tourism camps.
For Investors and Strategic Acquirers: The window for entry favors regional assembly specialists with existing Gulf certification footprints and distributor relationships. Long-term viability hinges on consolidation of parallel import channels as Saudi distributor networks contract. Watch for Dubai Electricity and Water Authority demand-response program expansion as inflection indicator for smart-grid integration premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Master Supply Agreement with Property Developers | Bypasses distributor markups and secures volume through Emaar and Damac procurement templates. |
| Parallel-Track Certification Investment | Compresses SASO and ESMA approval timelines to outpace competitor product launches. |
| Inverter-Motor Technology Adoption | Aligns with ESMA A++ thresholds and utility rebate eligibility for premium positioning. |
| Levant Distribution Network Expansion | Captures underpenetrated Amman and Beirut channels with flexible independent retailers. |
| Solar-Compatible Product Development | Addresses off-grid demand in Saudi remote housing and UAE desert tourism segments. |
Research Methodology
Trade databases, customs records, and Gulf standardization body filings formed the secondary backbone for volume and trade flow calibration. Primary interviews with appliance manufacturing executives, regional distributor principals, property developer procurement managers, and SASO certification consultants triangulated against secondary validation. Bottom-up shipment aggregation and top-down market sizing converged on segment-level estimates.
Historical trendline analysis across capacity band shipments and efficiency class adoption informed projection modeling. Segmentation dimensions included product format, end-user category, load capacity tier, and distribution channel structure. CAGRs were derived from regression analysis of certified unit placement rates and replacement cycle compression. Water-efficiency mandate compliance costs and inverter-motor adoption curves served as industry-specific forecast inputs.
Regulatory timeline acceleration, commodity metal price spikes, and developer procurement channel shifts are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on certification harmonization pace and smart-grid integration mandate timing. A model refresh is warranted upon material change in SASO efficiency tier enforcement or Gulf standard harmonization trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Egypt Dishwashers Market
Appliances
North America Microwave Oven Market
Appliances
Small Appliances Market
Appliances
Cooker Hoods Market
Appliances
Household Vacuum Cleaners Market
Appliances
Refrigerated Cabinet Market
Appliances
United States Multi-Functional Oven Market
Appliances
United States Electric Kettle Market
Appliances
Colombia Laundry Appliances Market
Appliances
Electric Fan Market
Appliances
Israel Laundry Appliances Market
Appliances
Refrigerator Door Seal Market
Appliances
Dishwasher Market
Appliances
Household Beauty Appliances Market
Appliances
Europe Microwave Oven Market
Appliances
Shared Shoe Washing Machine Market