
 Facial Serum Market | 2026-2036
Facial Serum Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Serum Market Analysis
Plant-derived squalane is consolidating its position as the preferred lipid replacement for shark-derived and synthetic alternatives across premium facial serum formulations. COSMAX leverages integrated R&D and manufacturing scale to anchor supply relationships with multinational beauty brands. Trilogy Labs specializes in small-batch custom formulations for emerging direct-to-consumer labels. Guangzhou Rysun Biotechnology Co., Ltd. competes on botanical extraction capabilities and cost-efficient peptide synthesis.
Facial serum denotes a concentrated, low-viscosity topical formulation delivering active ingredients through epidermal penetration, typically containing 5-30% functional actives in a water-based or emulsion vehicle designed for targeted skin concerns. Hyaluronic acid serums dominate volume due to proven hydration efficacy and broad dermatological endorsement, while peptide-based formulations represent the fastest-expanding ingredient segment as consumers prioritize collagen-stimulating claims. Anti-aging serums command the largest value share, though brightening variants show accelerated momentum in Asia-Pacific markets where melanin-inhibition claims drive premium positioning.
FDA oversight of cosmetic labeling and the EU Cosmetics Regulation enforce ingredient disclosure thresholds and prohibit unsubstantiated therapeutic claims, compelling reformulation investments and clinical validation spending. REACH compliance and MoCRA implementation in the United States further tighten safety assessment requirements for preservative systems and fragrance allergens. Stakeholders must monitor evolving green chemistry mandates and biodegradability standards as sustainability criteria increasingly determine retailer access and consumer preference formation.
Market Dynamics
Clean beauty mandates from the EU Cosmetics Regulation and FDA ingredient transparency requirements are forcing reformulation investments across the facial serum value chain, compressing margins for legacy preservative systems while opening premium positioning for compliant botanical alternatives.
Growth Catalysts
- EU Green Deal chemical strategy:The EU's sustainable chemistry framework accelerates biodegradability requirements, pushing brands toward plant-derived squalane and fermented actives that command premium shelf placement.
- Gen Z preventive skincare adoption:Younger demographics in the United States and South Korea integrate serums into daily routines earlier than prior generations, expanding addressable demand beyond corrective anti-aging applications.
- Peptide synthesis automation:Advances in solid-phase peptide manufacturing reduce unit costs for collagen-stimulating actives, enabling mid-market brands to compete on previously premium-only claims.
Market Restraints
- Hyaluronic acid feedstock volatility:Fermentation-derived sodium hyaluronate supply concentrates among Chinese biotech clusters, exposing formulators to input cost swings and geographic concentration risk.
- Clinical validation burden:MoCRA implementation in the United States demands substantiated safety data for preservative systems, extending new product development timelines and raising compliance costs for smaller manufacturers.
- Water-based formulation limitations:Traditional aqueous serums face stability constraints for certain oil-soluble vitamins, limiting delivery efficacy compared to emerging emulsion technologies.
Strategic Opportunities
- Men's grooming underpenetration:Male-specific serum lines remain nascent in China and India, presenting first-mover advantage for brands willing to abandon unisex positioning.
- Direct-to-consumer microbiome testing:At-home skin analysis kits paired with personalized serum subscriptions create recurring revenue models and reduce retailer dependency.
- Refillable packaging mandates:France's AGEC law and similar extended producer responsibility frameworks in Germany reward brands with circular supply chains through preferential retail access.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in encapsulation technologies and preservative-free stability systems commands premium compensation, constraining R&D expansion for mid-tier manufacturers.
- Cross-border registration complexity:Divergent fragrance allergen disclosure thresholds between the EU, United States, and South Korea force territory-specific SKUs, fragmenting production scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Serum Market |
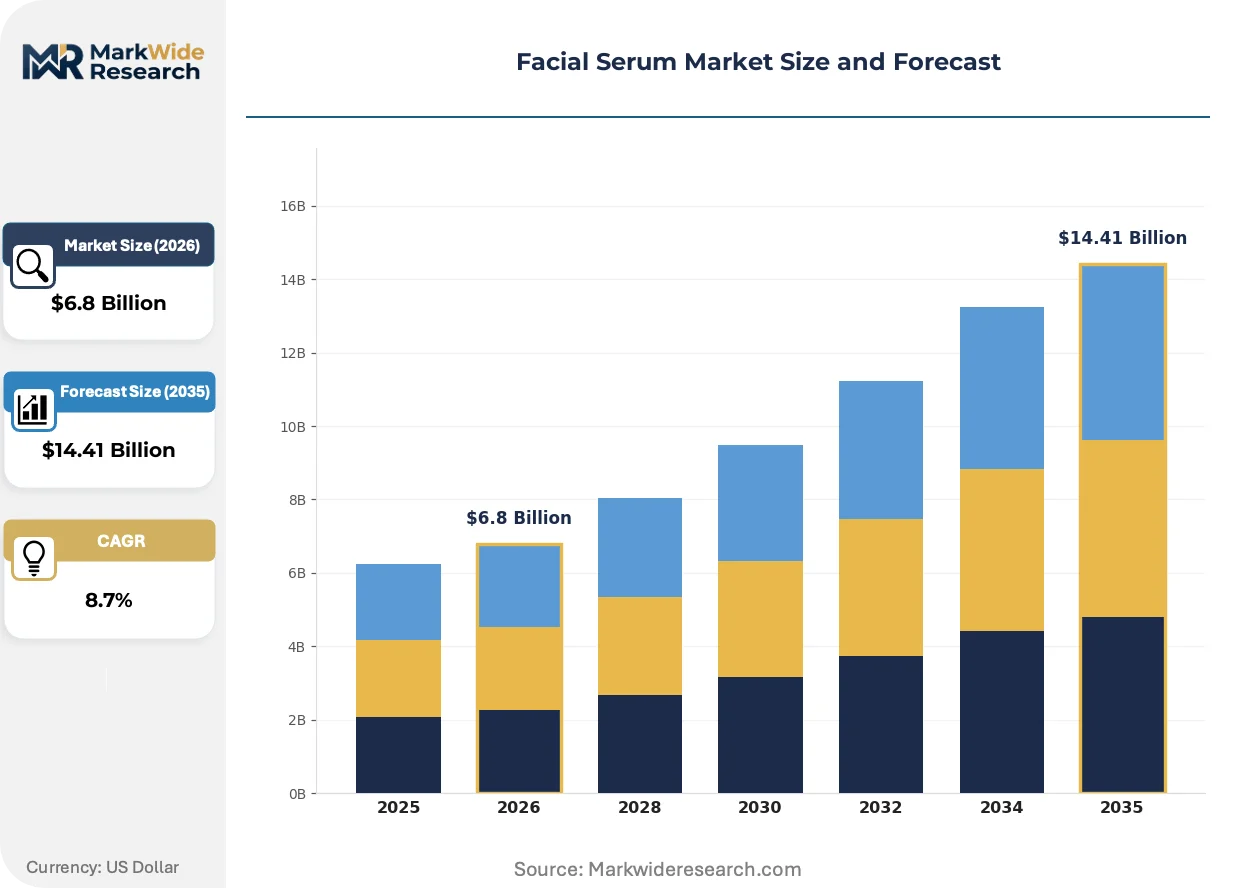
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizing, Anti-Aging, Brightening, Nourishing Ingredient Type: Botanical, Hyaluronic Acid, Vitamin C, Peptides Packaging Type: Dropper Bottle, Pump Bottle, Sachet, Jar Target Skin Type: Dry, Oily, Combination, Sensitive |
| Companies Covered | Vitelle Labs, Guangzhou Rysun Biotechnology Co., Ltd., COSMAX, ONOXA, Trilogy Labs, Pravada, Metro Private Label, RainShadow Labs, Nutrix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Serum Market Emerging Trajectories
Biotechnology-derived actives and personalized delivery systems are compressing the innovation cycle in facial serum development, shortening the gap between laboratory breakthrough and commercial formulation.
Encapsulation technology using lipid nanoparticles and cyclodextrin complexes is decentralizing active ingredient delivery from mass-market monoliths toward niche and bespoke formulators. Independent labs in South Korea and the United States now access previously proprietary stabilization methods through equipment leasing and contract manufacturing partnerships. This diffusion erodes the historical advantage of integrated multinational R&D departments.
REACH compliance deadlines for fragrance allergen labeling are compelling European brands to reformulate entire product lines ahead of 2026 enforcement windows. The regulation's cumulative allergen disclosure requirements particularly impact prestige serums with complex botanical extracts. Manufacturers respond by simplifying ingredient decks and investing in synthetic biology alternatives to traditional essential oil fragrances.
Subscription-based replenishment models displace traditional retail purchasing for core serum categories in urban United States markets. Direct-to-consumer brands capture recurring revenue through algorithmic skin assessment tools that adjust formulations quarterly. This behavioral shift concentrates customer lifetime value with data-integrated challengers rather than legacy department store dependencies.
Facial Serum Market Segmentation
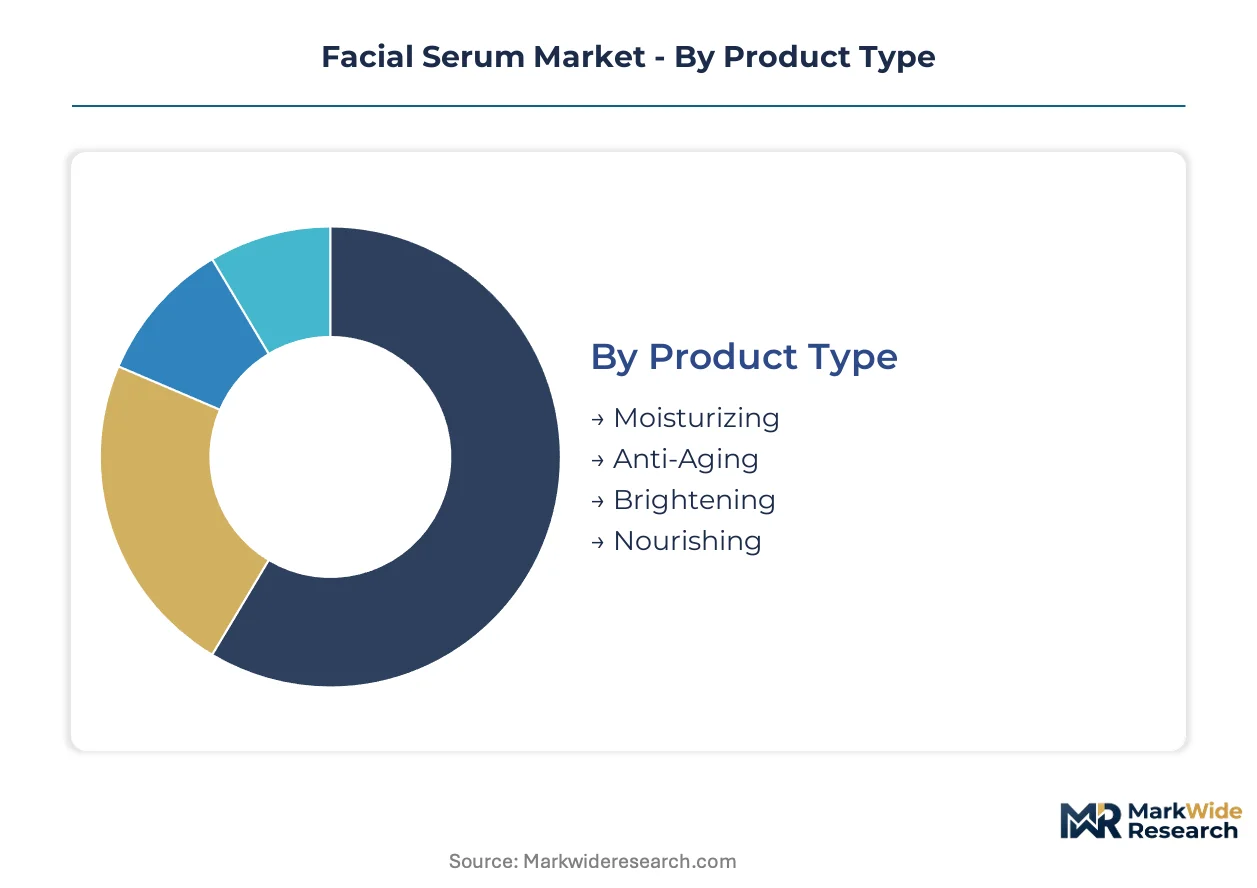
Facial serum segmentation reveals how formulation science, delivery mechanisms, and dermatological targeting combine to create distinct commercial battlegrounds. Manufacturers compete across these dimensions simultaneously, forcing portfolio decisions about which combinations to own versus license.
Product Type:
Standalone serum categories function as entry points for new users, while hybrid formulations embed multiple benefits to reduce routine complexity and capture premium pricing.
- Moisturizing:Hyaluronic acid and glycerin-based formulations dominate daily use frequency across all age demographics. Demand concentrates in United States drugstore channels where dermatologist endorsements drive trial among first-time serum users facing barrier function concerns.
- Anti-Aging:Retinol, peptide, and growth factor combinations target collagen degradation with the highest per-unit pricing in professional and prestige retail. South Korea's aesthetic clinic distribution networks anchor volume for prescription-strength variants requiring post-procedure recovery positioning.
- Brightening:Niacinamide and arbutin formulations addressing hyperpigmentation show concentrated demand in Asia-Pacific urban centers.
- Nourishing:Ceramide and plant oil blends serve compromised barrier repair needs in cold-climate markets.
Moisturizing serums lead volumes today; brightening variants are gaining share fastest.
Ingredient Type:
Cost tier stratification separates commodity fermentation outputs from precision biotechnology, with margin structures diverging sharply between synthetic chemistry and botanical extraction supply chains.
- Botanical:Plant-derived actives from adaptogenic roots and fermented extracts command clean beauty premiums but face batch-to-batch consistency challenges. European Union REACH compliance costs particularly burden small-batch botanical suppliers dependent on wild-harvested feedstocks.
- Hyaluronic Acid:Fermentation-derived sodium hyaluronate in multiple molecular weights enables layered hydration claims with proven clinical validation. Chinese biotech clusters in Shandong and Jiangsu provinces control upstream fermentation capacity, exposing formulators to geographic concentration risk.
- Vitamin C:L-ascorbic acid and stable derivatives compete on oxidation stability timelines.
- Peptides:Solid-phase synthesis advances reduce unit costs for collagen-stimulating signal peptides.
Hyaluronic acid leads volumes today; peptides are expanding most quickly.
Packaging Type:
Application mechanics determine preservation requirements, dosing precision, and sustainability profile—factors that reshape manufacturing location decisions and extended producer responsibility compliance costs.
- Dropper Bottle:Glass pipette systems with rubber bulbs remain the prestige standard despite contamination risks from repeated air exposure. French AGEC law circularity requirements now penalize non-recyclable dropper assemblies, accelerating shifts to mono-material alternatives.
- Pump Bottle:Airless dispensing systems protect oxidation-sensitive actives like vitamin C and retinol through product end-of-life. South Korean contract manufacturers lead airless pump innovation, integrating UV-blocking opaque materials directly into molding processes.
- Sachet:Single-use foil pouches dominate travel retail and sampling economics.
- Jar:Wide-mouth containers persist for thick, emulsion-based serum formats.
Dropper bottles lead volumes today; pump bottles are climbing the fastest.
Target Skin Type:
Customer type segmentation separates mass-market inclusive positioning from clinically validated dermatological solutions, with regulatory substantiation burdens favoring larger manufacturers.
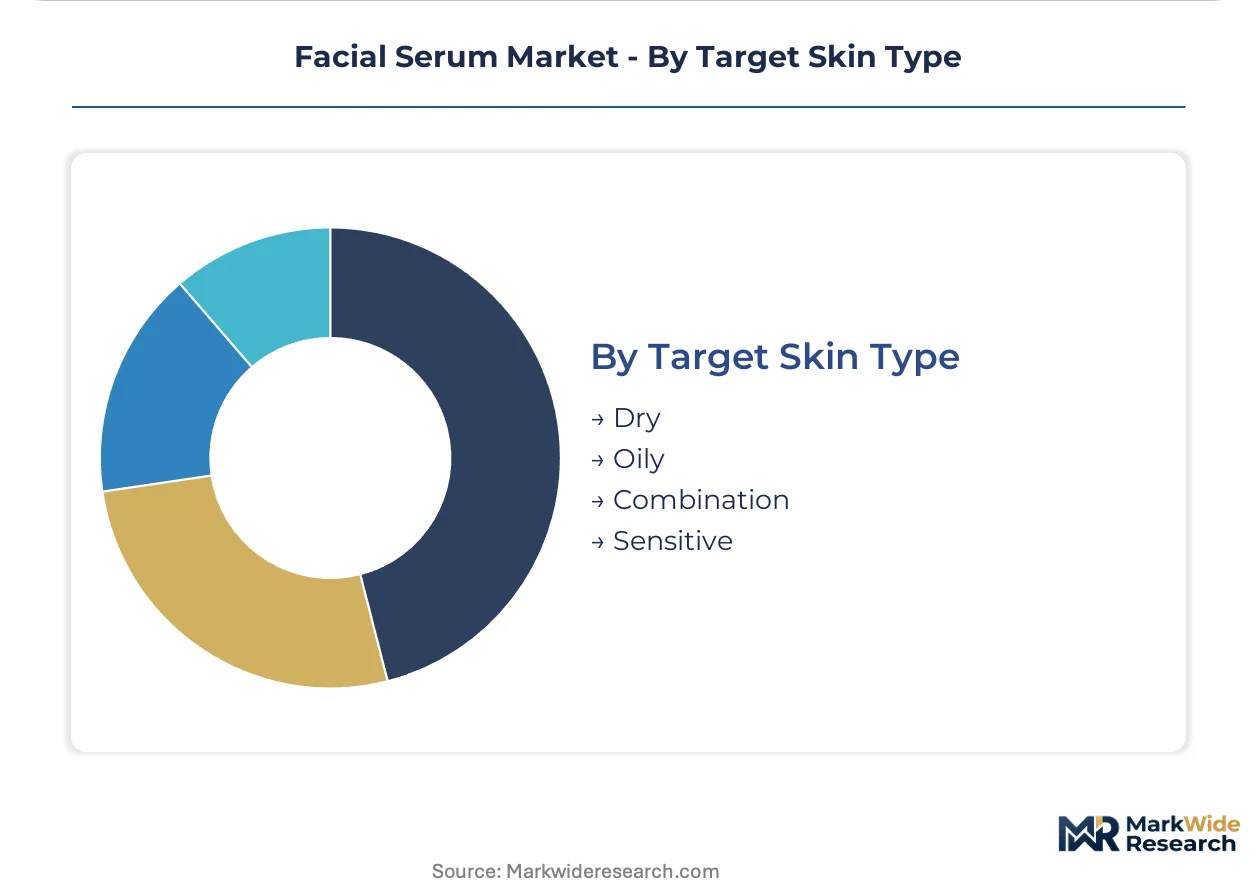
- Dry:Barrier-repair formulations with ceramide and squalane concentrates address transepidermal water loss in mature demographics. United States Medicare-adjacent dermatology practices increasingly prescribe medical-grade dry skin serums as first-line interventions before topical corticosteroids.
- Oily:Niacinamide and zinc PCA combinations target sebum regulation without stripping moisture. Demand concentrates among male consumers in India and Southeast Asia where unmet grooming needs persist.
- Combination:Zone-specific actives balance T-zone oil control with cheek hydration.
- Sensitive:Minimal ingredient decks with excluded fragrance allergens serve reactive skin populations.
Anti-aging serums targeting dry skin lead volumes today; sensitive skin formulations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong and Jiangsu provinces anchor upstream fermentation capacity for sodium hyaluronate, concentrating global supply for hyaluronic acid serums. United States, China, and South Korea concentrate demand, while European Union regulations reshape formulation standards across export markets.
United States
Gen Z preventive skincare adoption expands addressable demand beyond corrective anti-aging applications. FDA MoCRA implementation demands substantiated safety data for preservative systems, extending new product development timelines. Greater Los Angeles and New York Metro host direct-to-consumer brands leveraging algorithmic skin assessment tools for personalized serum subscriptions.
China
Biotech clusters in Shandong and Jiangsu provinces control upstream fermentation capacity for sodium hyaluronate. NMPA and SAMR enforce ingredient disclosure and safety assessment requirements for preservative systems and fragrance allergens. Guangzhou anchors botanical extraction capabilities and cost-efficient peptide synthesis for domestic and export markets.
South Korea
Aesthetic clinic distribution networks anchor volume for prescription-strength variants requiring post-procedure recovery positioning. MFDS regulates cosmetic labeling and prohibits unsubstantiated therapeutic claims, compelling clinical validation spending. Seoul Capital Area contract manufacturers lead airless pump innovation, integrating UV-blocking opaque materials directly into molding processes.
Germany
REACH compliance deadlines for fragrance allergen labeling compel reformulation of entire product lines ahead of enforcement windows. EU Green Deal chemical strategy accelerates biodegradability requirements, pushing brands toward plant-derived squalane. Bavaria and North Rhine-Westphalia concentrate R&D investment in synthetic biology alternatives to traditional essential oil fragrances.
France
Prestige serums with complex botanical extracts face cumulative allergen disclosure requirements under REACH. AGEC law circularity requirements penalize non-recyclable dropper assemblies, accelerating shifts to mono-material alternatives. Île-de-France houses headquarters of multinational beauty brands investing in refillable packaging mandates and extended producer responsibility frameworks.
Facial Serum Market Vendor Landscape
Global majors compete with regional champions across manufacturing scale and formulation specialization, creating a tiered structure where integrated R&D departments face erosion from diffused stabilization technologies. Market structure separates multinational beauty conglomerates with captive supply chains from independent contract manufacturers and emerging direct-to-consumer labels. Three archetypes dominate: integrated R&D-manufacturing hybrids, small-batch custom formulators, and biotechnology-focused ingredient suppliers. Competitive moves concentrate on M&A for fermentation capacity and strategic partnerships for microbiome testing platforms.
Within the integrated manufacturing tier, COSMAX exemplifies scale-driven supply relationships with multinational beauty brands. Guangzhou Rysun Biotechnology Co., Ltd. occupies a position among botanical extraction specialists competing on cost-efficient peptide synthesis. Trilogy Labs sits within the small-batch custom formulation segment serving emerging direct-to-consumer labels. These three anchors illustrate how manufacturing scale, geographic feedstock access, and formulation agility define competitive positioning across serum value chain segments.
| Leading Market Players |
|---|
| Vitelle Labs |
| Guangzhou Rysun Biotechnology Co., Ltd. |
| COSMAX |
| ONOXA |
| Trilogy Labs |
| Pravada |
| Metro Private Label |
| RainShadow Labs |
| Nutrix |
| Others |
Supply Flow & Price Mechanics
Fermentation-derived sodium hyaluronate manufacturing automation simultaneously compresses unit production costs and concentrates upstream capacity within Chinese biotech clusters, reshaping margin structures across hyaluronic acid serum tiers while amplifying geographic dependency risks for multinational formulators.
Pricing Analysis
Input-cost pass-through from fermentation capacity constraints drives divergence between mass-market and premium serum tiers. Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade peptide formulations from commodity hyaluronic acid variants, with price differentiation resting on dermatological endorsement density and preservative-free certification status. Pricing pressure stems from Chinese feedstock volatility and REACH compliance investments, squeezing mid-tier manufacturers most acutely while luxury positioning absorbs cost inflation through brand equity buffers.
Supply Chain Analysis
France's AGEC law and Germany's extended producer responsibility frameworks are forcing packaging localization and circularity investments that favor European contract manufacturers. Shandong and Jiangsu provinces in China anchor sodium hyaluronate fermentation, while South Korea dominates airless pump innovation and the United States concentrates direct-to-consumer fulfillment infrastructure. Raw material dependencies include fermentation-derived hyaluronic acid, solid-phase synthesized peptides, and plant-derived squalane alternatives. Single-source vulnerability in Chinese biotech clusters exposes formulators to input disruption. Distribution runs through aesthetic clinic networks in Seoul, prestige retail in Paris and New York, and algorithmic subscription platforms in Los Angeles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Facial serum manufacturing presents a geographic-arbitrage opportunity between South Korean formulation expertise and Chinese upstream fermentation scale, with regulatory compliance costs in the European Union creating margin compression that agile contract manufacturers can exploit through selective facility placement.
For Market Incumbents: Extend captive R&D partnerships with Chinese fermentation specialists to lock in sodium hyaluronate supply before capacity constraints tighten further. Consolidate airless pump sourcing relationships with Seoul-based contract manufacturers to secure oxidation-sensitive active protection. Defensive moves must address direct-to-consumer algorithmic personalization platforms that threaten department store distribution economics. For New Entrants and Emerging Players: Enter via men's grooming serum lines in India and Southeast Asia, where unmet sebum-regulation demand persists beneath unisex category saturation. Target at-home microbiome testing paired with subscription replenishment models to capture recurring revenue and reduce retailer dependency. Go-to-market execution should leverage social commerce channels rather than traditional prestige retail gatekeepers. For Investors and Strategic Acquirers: Valuations sit cheapest among small-batch botanical extraction specialists burdened by REACH wild-harvesting compliance costs but possessing transferable clean beauty credentials. Long-term viability favors acquisition targets with demonstrated encapsulation technology expertise and preservative-free stability systems. Watch peptide synthesis automation cost curves as the inflection signal for mid-market brand competitive viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | COSMAX and Guangzhou Rysun anchor supply security through captive sodium hyaluronate production in Shandong clusters. |
| Microbiome Testing Platform Partnership | Direct-to-consumer brands in Los Angeles reduce retailer dependency through algorithmic skin assessment recurring revenue models. |
| Refillable Packaging Mandate Compliance | French AGEC law rewards circular supply chains with preferential Sephora and Douglas shelf placement access. |
| Peptide Synthesis Automation Investment | Solid-phase manufacturing cost compression enables mid-market brands to compete on previously premium-only collagen-stimulating claims. |
| Men's Grooming Line Extension | Niacinamide and zinc PCA formulations target underpenetrated male segments in India and Southeast Asia beyond unisex positioning. |
Methodological Framework
Bottom-up serum category modeling reconciled against top-down fermentation capacity tracking forms the analytical core of this study. Primary interviews with formulation chemists, brand managers at direct-to-consumer labels, contract manufacturing procurement leads, and aesthetic clinic distribution heads combined with secondary validation from FDA MoCRA filings, NMPA ingredient disclosure databases, EU Cosmetics Regulation enforcement notices, and Shandong provincial industrial output statistics. Triangulation between demand-side adoption patterns and supply-side biotech cluster expansion ensures cross-verified volume and value estimates.
Input-output matrices map hyaluronic acid feedstock availability through peptide synthesis automation cost curves to finished serum pricing tiers across the projection horizon. Segmentation dimensions include product type, ingredient class, packaging format, and target skin concern, with regional regulatory clusters modeled separately for United States MoCRA, EU REACH, and China NMPA compliance pathways. CAGRs derive from fitted adoption curves for preventive skincare among Gen Z demographics and penetration rates for subscription replenishment models.
The model holds under stable fermentation feedstock pricing and gradual regulatory harmonization; deviation in Chinese biotech cluster output or accelerated EU biodegradability mandates would shift volume and value trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Body Blurring Cosmetics Market
Cosmetics & Skincare
Mushroom Beauty Products Market
Cosmetics & Skincare
Face Wash Market
Cosmetics & Skincare
BB Cream Market
Cosmetics & Skincare
Russia Lip Care Products Market
Cosmetics & Skincare
Organic Makeup Remover Market
Cosmetics & Skincare
Medicated Shampoo Market
Cosmetics & Skincare
Camellia Skincare and Cosmetics Market
Cosmetics & Skincare
Lipstick Market
Cosmetics & Skincare
Hand Cream Market
Cosmetics & Skincare
Makeup Remover Product Market
Cosmetics & Skincare
Herbal Soap Market
Cosmetics & Skincare
Cosmetics OEM and ODM Services Market
Cosmetics & Skincare
Temporary Tattoo Market
Cosmetics & Skincare
Makeup Remover Pen Market
Cosmetics & Skincare
Color Cosmetics OEM and ODM Market