
 Face Compact Market | 2026-2036
Face Compact Market Size, Share, and Industry Trends Forecast 2026-2036
Face Compact Market Foresight
The EU Green Deal is shifting formulation requirements for face compacts across European supply chains, forcing brands to eliminate certain synthetic binders and petroleum-derived waxes. L'Oreal anchors its competitive position through backward integration into botanical ingredient sourcing networks. Chanel differentiates via controlled distribution through owned retail channels in Paris, Tokyo, and Seoul.
A face compact is a pressed or molded cosmetic product containing pigments, binders, and fillers in a portable case, typically delivering coverage, oil absorption, or luminosity through a foam or brush applicator. Pressed powder compacts sustain the largest volume position due to manufacturing scalability and extended shelf stability, while refillable packaging formats are capturing margin pools as sustainability premiums expand. Cream compact formulations lead growth among professional customer segments, where blendability and buildable coverage command higher price positioning.
FDA oversight of cosmetic color additives and the EU REACH framework governing chemical substance registration collectively shape ingredient permissibility and market access timelines for face compact manufacturers. BIS certification requirements in India add another compliance layer for brands seeking entry into that market. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs that erode portfolio economics.
Market Dynamics
Professional makeup artists in film and television production are compressing product refresh timelines while EU Green Deal chemical restrictions force simultaneous reformulation across supply chains, creating dual pressure on R&D bandwidth.
Growth Catalysts
- K-Beauty Innovation Cycles:South Korean beauty brands compress new product introduction timelines to under six months, forcing competitors to accelerate development pipelines to maintain shelf relevance.
- EU Green Deal Implementation:Chemical restrictions under this framework eliminate petroleum-derived waxes and certain synthetic binders, opening formulation space for botanical alternatives and premium positioning.
- Film and Television Production:Professional makeup artists on set demand cream compact formulations with superior blendability, pulling manufacturers toward higher-margin professional-grade product lines.
Market Restraints
- Petroleum-Derived Input Volatility:Paraffin and microcrystalline wax prices fluctuate with crude oil markets, squeezing margins on legacy formulations that have not yet transitioned to botanical substitutes.
- Supply Concentration in East Asia:Mica processing and compact case manufacturing cluster in specific Chinese provinces, creating single-source vulnerability for pigment supply and packaging components.
- REACH Registration Burden:The EU framework imposes costly substance-by-substance compliance documentation, extending market access timelines for smaller ingredient suppliers and limiting formulation flexibility.
Strategic Opportunities
- Refillable Packaging Mandates:Extended producer responsibility laws in France and Germany create regulatory tailwinds for brands investing in durable compact cases with replaceable powder inserts.
- Professional Salon Channel Expansion:Direct-to-artist distribution bypasses traditional retail markup structures, capturing margin pools previously allocated to department store concessions.
- Biotechnology-Enabled Binders:Fermentation-derived film-forming agents converge with clean beauty positioning, enabling water-resistant cream formulations without perfluorinated compounds.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in natural emulsifier stabilization and pressed powder rheology concentrates among senior professionals approaching retirement, constraining innovation velocity.
- Dual Certification Timelines:Simultaneous FDA color additive petitions and EU REACH dossier preparation extend product launch windows, freezing capital in pre-revenue development phases.
- Legacy Equipment Retooling:Existing press lines designed for talc-based powders require substantial modification to handle corn starch and rice powder alternatives without density variation defects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Face Compact Market |
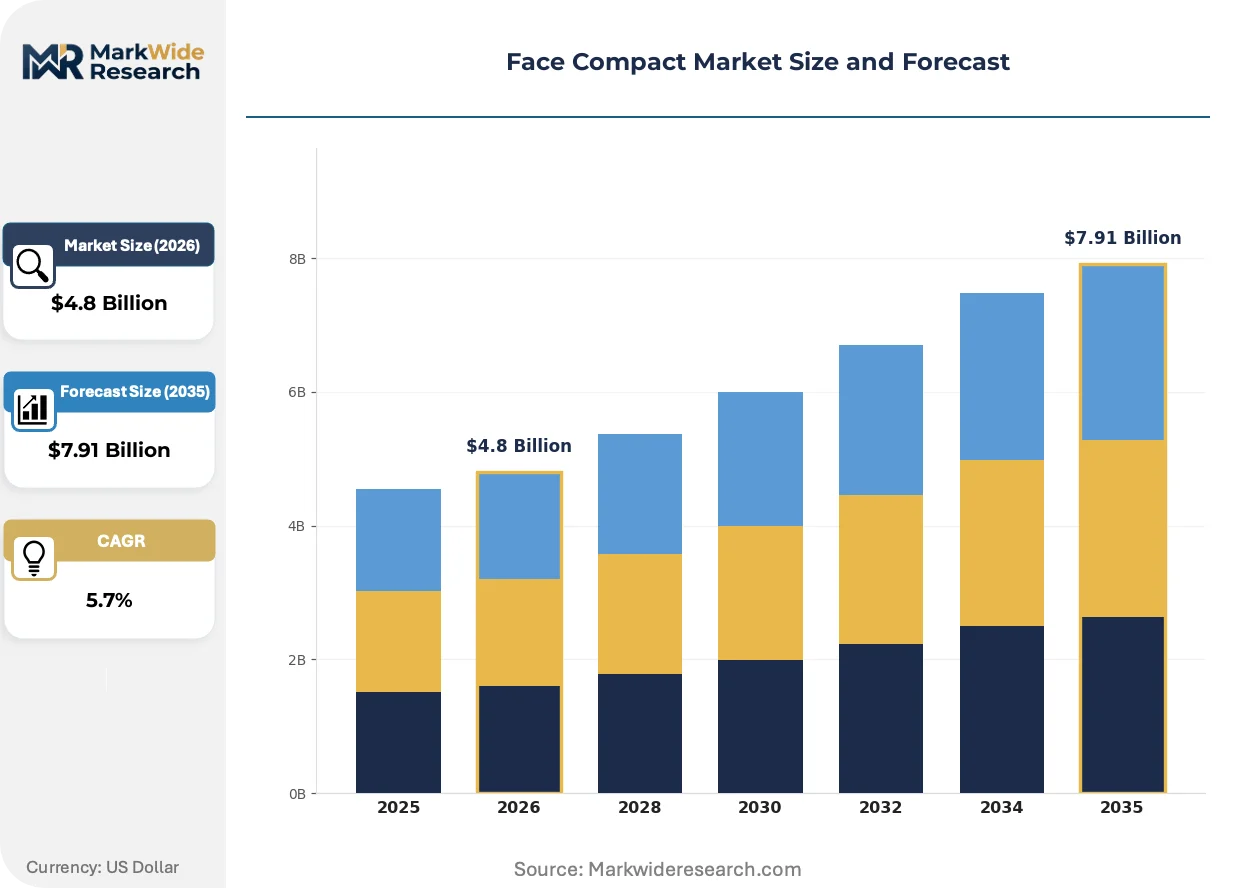
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressed Powder, Cream Compact, Loose Powder, Highlighting Powder Customer Type: Individuals, Professionals, Beauty Enthusiasts, Retailers Formulation: Matte Finish, Shimmer Finish, Satin Finish, Oil-free Packaging Type: Single-unit, Multi-pack, Refillable, Travel Size |
| Companies Covered | Shiseido, Chanel, L'Oreal, MAC Cosmetics, Dior, The Estee Lauder Companies, Unilever, Maybelline New York, Procter & Gamble, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Face Compact Market Shifts & Advancements
Active ingredient delivery systems and sustainable packaging architectures are reshaping competitive positioning in face compacts, with professional-grade performance claims increasingly validated by on-set durability testing rather than laboratory metrics alone.
Silicone-free elastomer powders are unifying the texture profiles previously split between synthetic slip and natural origin claims. Professional makeup artists in high-definition television production adopt these materials fastest, accepting 15-20% price premiums for pore-blurring performance without cyclical siloxane regulatory exposure. This technology is unifying the previously separate clean beauty and professional performance segments into a single premium tier.
EU REACH authorization requirements for titanium dioxide nanoparticles are forcing reformulation of SPF-enhanced compacts toward non-nano alternatives or mineral-free UV filters. Manufacturers serving the European market must either redesign pigment dispersion systems or withdraw sun protection claims entirely. Brands with backward integration into botanical sourcing networks, such as those controlling marigold-derived lutein supplies, pivot toward antioxidant positioning to replace forfeited SPF marketing.
Direct-to-artist subscription models displace traditional wholesale distribution for professional-grade compacts. Makeup department heads on streaming production sets now receive quarterly curated assortments bypassing beauty supply intermediaries, compressing feedback loops between formulation performance and product iteration. This channel shift concentrates most visibly in Los Angeles and Seoul production clusters where crew density supports dedicated logistics infrastructure.
Face Compact Market Segmentation
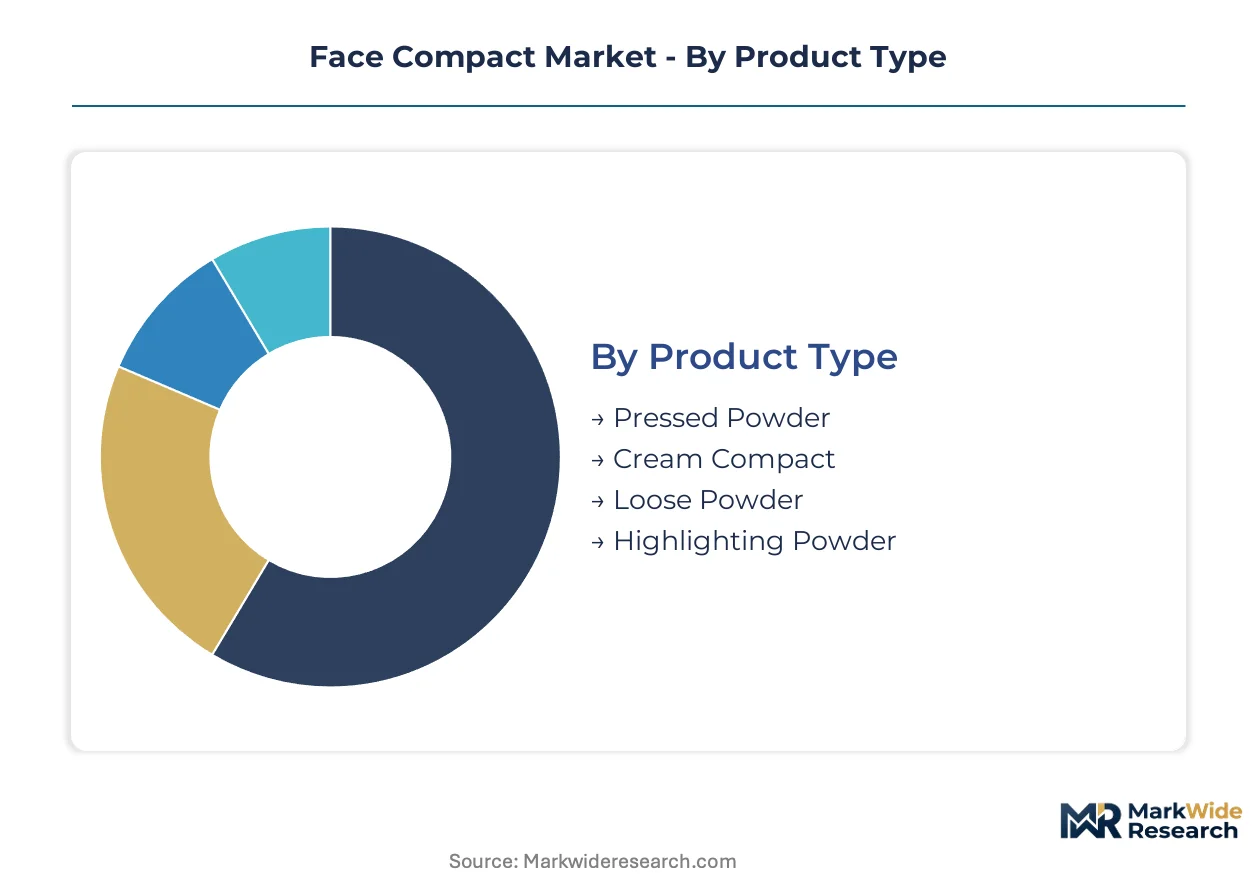
Face compact manufacturers navigate divergent performance demands across professional and consumer channels, with formulation chemistry and packaging architecture determining margin capture. Segmentation reveals where R&D investment concentrates and which product architectures command sustainability premiums.
Product Type:
Pressed powder formats anchor volume shipments while cream compacts extract premium pricing through professional channel penetration.
- Pressed Powder:Compressed pigments with talc, silica, or corn starch binders deliver extended shelf stability and manufacturing scalability. Demand concentrates in mass-market retail across India and Brazil, where humidity resistance and price accessibility drive procurement decisions.
- Cream Compact:Emulsion-based formulations with wax and oil phases enable buildable coverage superior for high-definition camera work. Film and television makeup departments in Los Angeles and Seoul pull manufacturers toward professional-grade SKUs with 40-60% gross margins.
- Loose Powder:Finely milled mineral particles without press binders serve setting and baking techniques in theatrical applications.
- Highlighting Powder:Light-reflecting mica and pearl pigments target social media-driven beauty enthusiasts seeking luminosity effects.
Today's leader: Pressed Powder. Tomorrow's challenger: Cream Compact.
Customer Type:
Professional segments compress product refresh cycles while individual consumers sustain volume through replenishment purchasing.
- Individuals:End-users purchasing for personal use through retail and e-commerce channels, prioritizing shade match convenience and portability.
- Professionals:Licensed makeup artists and salon operators demanding batch consistency, sanitation protocols, and direct technical support from manufacturers.
- Beauty Enthusiasts:Social media-influenced consumers with above-average category knowledge, willing to cross-shop prestige and masstige tiers for specific ingredient claims.
- Retailers:Department store and specialty beauty buyers curating assortments based on margin structure, promotional calendar alignment, and exclusive distribution rights.
Professional demand is climbing the fastest, though individual volume sustains manufacturing base loads.
Formulation:
Finish preferences split between photography-optimized matte and social media-favored luminosity, with oil-free architectures gaining regulatory tailwinds.
- Matte Finish:High oil-absorption silica and talc content reduces shine under production lighting. Studio makeup artists in London and Mumbai specify matte compacts for talent facing 4K cameras, where reflectance control prevents post-production correction costs.
- Satin Finish:Balanced light diffusion with microfine pearl particles bridges professional and consumer applications. South Korean brands lead formulation innovation here, compressing development cycles that force Western competitors to accelerate pipelines.
- Shimmer Finish:Elevated mica loadings create deliberate light reflection for evening and editorial use.
- Oil-free:Elimination of comedogenic ingredients responds to dermatologist recommendations and acne-prone skin positioning.
Satin Finish commands the broadest cross-segment appeal; Oil-free is gaining share fastest among younger demographics.
Packaging Type:
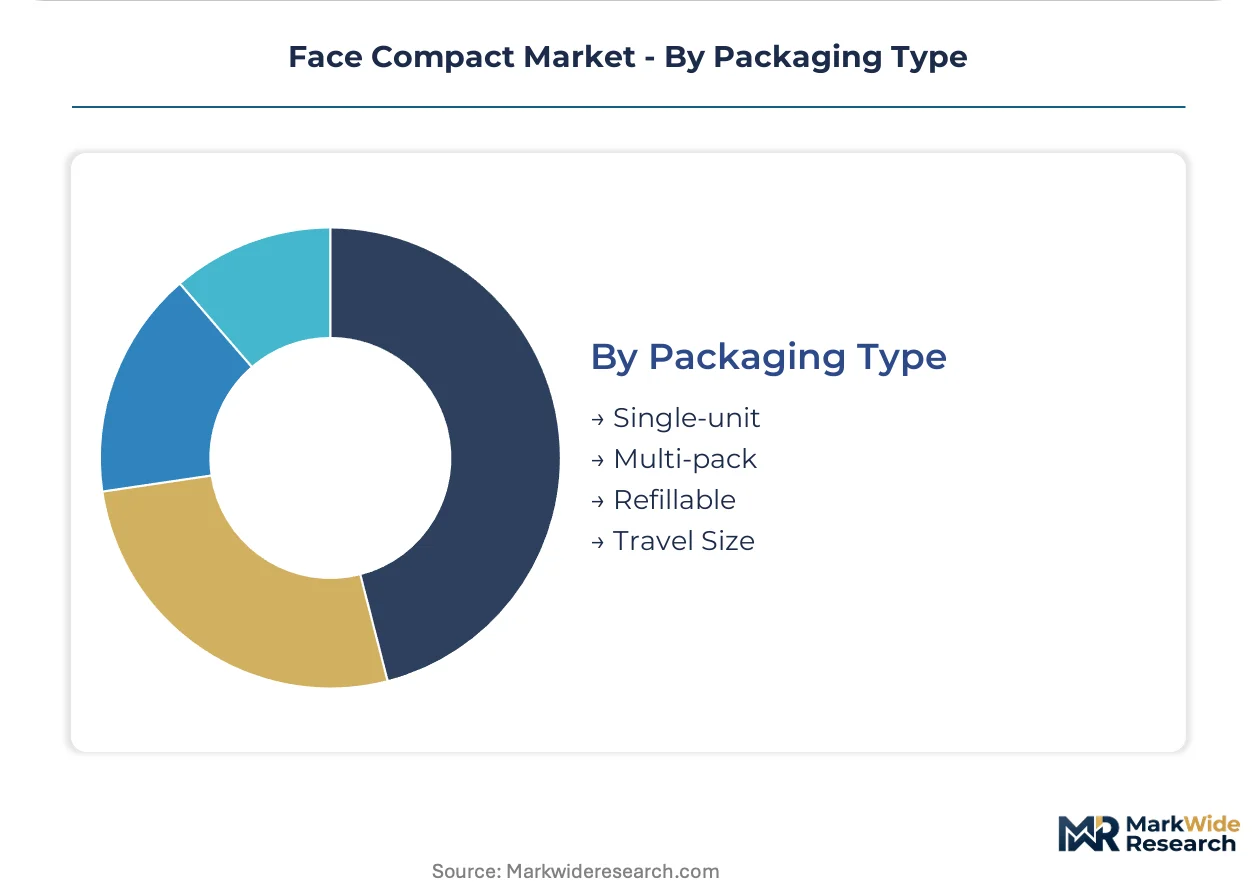
Single-unit formats dominate current shipments while refillable architectures capture regulatory-driven sustainability premiums.
- Refillable:Durable metal or high-grade plastic cases with replaceable powder inserts align with France and Germany's extended producer responsibility mandates. L'Oreal and Chanel have invested in proprietary case ecosystems that lock consumers into branded refill ecosystems, defending margin pools against private label substitution.
- Travel Size:Sub-10 gram formats serve airline retail and trial sampling, with TSA-compliant dimensions driving specification requirements for US airport duty-free channels.
- Single-unit:Standard disposable cases represent the baseline cost structure for mass-market entry.
- Multi-pack:Bundled shade assortments or companion product combinations target gift purchasing occasions and subscription box economics.
Single-unit maintains volume leadership; Refillable shows the steepest expansion trajectory as EU packaging mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Face compact manufacturing originated in European perfumeries and Japanese pharmaceutical laboratories during the early twentieth century, establishing formulation expertise that persists in contemporary supply chains. Regional demand patterns now diverge between professional studio clusters and mass-market retail corridors.
United States
Film and television production in Los Angeles drives professional-grade cream compact procurement, with makeup department heads specifying high-definition-optimized formulations. FDA oversight of cosmetic color additives shapes ingredient permissibility timelines. The Pacific Northwest hosts biotechnology startups developing fermentation-derived film-forming agents for water-resistant applications.
South Korea
K-beauty brands compress product introduction cycles below six months, forcing Western competitors to accelerate development pipelines. MFDS cosmetic safety regulations govern new ingredient approvals and SPF claim substantiation. Seoul's Gangnam district concentrates flagship retail innovation where refillable compact cases with integrated mirrors debut before wider distribution.
France
Prestige heritage houses anchor botanical sourcing networks for marigold-derived lutein and other antioxidant ingredients. Extended producer responsibility laws mandate refillable packaging architectures, with ANSM monitoring cosmetic product safety claims. Parisian ateliers control distribution through owned retail channels that bypass traditional wholesale markup structures.
Japan
Pharmaceutical-grade manufacturing standards from Shiseido's origins influence contemporary pressed powder stability requirements. METI guidelines on sustainable packaging accelerate adoption of durable compact cases with replaceable inserts. Tokyo's Shibuya and Ginza districts serve as test markets for satin-finish formulations bridging professional and consumer applications.
Germany
REACH registration requirements impose substance-by-substance compliance documentation that extends market access timelines for smaller ingredient suppliers. KBA-adjacent chemical safety protocols inform industrial cosmetic manufacturing standards. Hamburg's port logistics cluster facilitates mica pigment importation from processing facilities in neighboring jurisdictions.
Face Compact Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation sophistication and distribution architecture, creating a tiered competitive structure. The vendor base spans multinational conglomerates with captive R&D infrastructure and regional specialists with flexible sourcing relationships. Three archetypes dominate: heritage houses with controlled retail networks, conglomerate beauty divisions with backward integration into botanical supply chains, and professional-grade specialists with direct-to-artist distribution. Consolidation pressure manifests through strategic partnerships for biotechnology-enabled binders and geographic expansion into production clusters in Los Angeles and Seoul.
Within the heritage house tier, Chanel and Dior exemplify positioning through owned retail channel control in Paris, Tokyo, and Seoul. Among conglomerate beauty divisions, L'Oreal anchors competitive posture through upstream control over botanical ingredient sourcing networks. Shiseido occupies a distinctive position bridging pharmaceutical-grade manufacturing heritage with contemporary K-beauty innovation velocity. These three entities represent divergent strategic paths: retail real estate capture, supply chain verticality, and cross-regional format adaptation.
| Leading Market Players |
|---|
| Shiseido |
| Chanel |
| L'Oreal |
| MAC Cosmetics |
| Dior |
| The Estee Lauder Companies |
| Unilever |
| Maybelline New York |
| Procter & Gamble |
| Others |
Supply & Pricing Matrix
Formulation chemist expertise concentrated in Provence and Osaka drives labor-cost differentials that widen pricing-tier spreads between heritage houses and commodity manufacturers. Professional-grade cream compacts command 40-60% gross margins where blendability specifications justify premium positioning, while mass-market pressed powders compete on corn starch and talc input costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the face compact market by formulation sophistication and channel architecture. Price differentiation rests on botanical certification tiers and backward integration into marigold-derived lutein supply networks. Cost compression in the economy tier is intensifying because petroleum-derived wax volatility squeezes legacy formulation margins. Individual consumers in humid climates exhibit highest price sensitivity, whereas film production makeup departments accept 15-20% premiums for silicone-free elastomer performance.
Supply Chain Analysis
Direct-to-artist subscription channels handle professional buyer demand while bypassing traditional wholesale markup structures. Mica processing concentrates in Jiangxi and Hunan provinces, with compact case manufacturing clustering in Guangdong and Zhejiang. Raw material dependencies include titanium dioxide nanoparticles, fermentation-derived film-forming agents, and botanical wax substitutes. Single-source vulnerability in East Asian pigment processing creates supply chain risk. Distribution runs through owned retail flagships in Paris, Tokyo, and Seoul for heritage houses, while mass-market brands rely on department store concessions and e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The face compact market functions as a geographic-arbitrage play where EU REACH registration burdens in Germany extend market access timelines, while South Korea's MFDS pathways enable faster product introduction cycles that compress competitor response windows.
For Market Incumbents: To counter K-beauty innovation velocity, heritage houses must compress development pipelines through direct-to-artist feedback loops in Los Angeles and Seoul production clusters. Backward integration into botanical ingredient sourcing networks defends margin pools against private label substitution under France's extended producer responsibility mandates. For New Entrants and Emerging Players: Social commerce live-streaming platforms offer the most penetrable route for masstige positioning among beauty enthusiasts seeking ingredient transparency. Target refillable packaging architectures in Germany and France where regulatory tailwinds create first-mover advantages before mandates tighten across the analysis window. For Investors and Strategic Acquirers: Biotechnology conglomerates with fermentation capabilities are the most active acquirer in this space, seeking clean beauty positioning through microbial film-forming agents. Acquisition targets include professional-grade specialists with direct-to-artist distribution infrastructure. Watch for EU authorization timelines for titanium dioxide nanoparticles as inflection indicator for SPF-enhanced compact withdrawal rates.| Strategic Initiative | Industry Significance |
|---|---|
| Refillable Packaging Ecosystem Development | L'Oreal and Chanel proprietary case systems lock consumers into branded refill architectures under French extended producer responsibility laws. |
| Direct-to-Artist Distribution Buildout | Quarterly curated assortments bypass beauty supply intermediaries, compressing feedback loops between Seoul production sets and formulation iteration. |
| Biotechnology Binder Integration | Fermentation-derived film-forming agents enable water-resistant cream formulations without perfluorinated compound regulatory exposure. |
| Botanical Sourcing Network Expansion | Upstream control over marigold-derived lutein supplies supports antioxidant positioning as SPF claims face EU REACH nanoparticle restrictions. |
| Professional Channel Certification Investment | Sanitation protocols and batch consistency specifications defend margin pools in film and television production procurement decisions. |
Research Methodology
Direct dialogue with formulation chemists, professional makeup artists on Los Angeles and Seoul production sets, beauty supply distributors, and regulatory affairs specialists at ANSM and MFDS grounds qualitative findings in operational reality. Secondary validation draws from FDA color additive petitions, EU REACH dossier filings, MFDS cosmetic safety registrations, and customs records of mica and titanium dioxide import flows. Bottom-up SKU-level shipment data triangulates against top-down category value estimates across the analysis window.
Bottom-up modeling aggregates individual product line volumes by formulation type, packaging architecture, and customer channel, while top-down approaches benchmark against aggregate prestige and masstige category spend. Segmentation dimensions include product type (pressed powder, cream compact, loose powder, highlighting powder), customer archetype (individual, professional, beauty enthusiast), finish specification (matte, satin, shimmer, oil-free), and packaging format (refillable, single-unit, travel size, multi-pack). CAGRs derive from trend extrapolation of K-beauty innovation cycle compression and EU Green Deal implementation trajectories, with professional channel penetration rates and refillable packaging adoption curves as key forecast inputs.
Regulatory divergence between FDA and EU REACH frameworks, raw material price volatility in petroleum-derived wax markets, and formulation chemist retirement waves are the dominant revision risks to projection assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Essential Oil Soap Market
Cosmetics & Skincare
Sweden Cosmetics Products Market
Cosmetics & Skincare
Camellia Skincare and Cosmetics Market
Cosmetics & Skincare
Beauty Facial Mask Market
Cosmetics & Skincare
Organic Bar Soap Market
Cosmetics & Skincare
Nail Polish Market
Cosmetics & Skincare
Retinol Eye Cream Market
Cosmetics & Skincare
Medicated Shampoo Market
Cosmetics & Skincare
Eyeliner Industry Status and Prospects Professional Market
Cosmetics & Skincare
Lip Oil Market
Cosmetics & Skincare
North America Face Compact Market
Cosmetics & Skincare
Italy Lip Care Products Market
Cosmetics & Skincare
GCC Bath Soap Market
Cosmetics & Skincare
Loose Setting Powder Market
Cosmetics & Skincare
Cosmetics ODM Market
Cosmetics & Skincare
Lip Scrub Market