
 Pillow Spray Market | 2026-2036
Pillow Spray Market Size, Share, and Industry Trends Forecast 2026-2036
Pillow Spray Market Insights
REACH is realigning formulation costs for European entrants, forcing reformulation of synthetic fragrance blends before market access. This Works leverages its British heritage and clinical positioning to sustain premium shelf space in specialty retail. Aromatherapy Associates anchors its portfolio through spa-channel exclusivity and practitioner endorsements. Neom Organics competes on certified organic supply chains and direct-to-consumer subscription models.
Pillow spray denotes a fine-mist liquid formulation, typically comprising essential oil dilutions in alcohol or hydrosol bases at concentrations between one and five percent, designed for application onto bedding textiles to facilitate sleep onset through olfactory stimulation. The lavender segment dominates product type volumes due to established consumer recognition and broad cultivation supply, while eucalyptus variants capture faster growth among respiratory-conscious buyers. Sleep aid applications generate the largest revenue pool within the application dimension, though stress relief positioning commands higher per-unit margins among corporate wellness programs. Online retail channels extend fastest among distribution pathways, particularly through subscription box integrations and influencer-curated sleep kits.
EMA guidelines on cosmetic fragrance allergens, EPA regulations on volatile organic compound emissions, and FDA oversight of cosmetic labeling collectively shape permissible claims and ingredient transparency requirements across North American and European markets. These frameworks elevate compliance burdens for small-batch producers while advantaging scaled manufacturers with dedicated regulatory affairs functions. Stakeholders must monitor evolving fragrance disclosure mandates and certification scheme harmonization to preserve cross-border market access and consumer trust positioning.
Market Dynamics
REACH fragrance disclosure mandates are forcing European producers to reformulate synthetic oil bases ahead of market access, compressing margins for small-batch manufacturers while advantaging scaled players with dedicated regulatory affairs teams.
Growth Catalysts
- Hospitality amenity standardization:Hotel chains now stock pillow sprays as baseline sleep amenities, creating institutional procurement channels that bypass retail margin structures.
- EPA volatile organic compound thresholds:Tighter emissions caps on alcohol-based carriers are accelerating hydrosol formulation adoption among US manufacturers seeking compliance.
- Respiratory wellness positioning:Eucalyptus and tea tree variants capture buyers seeking dual-function sleep and breathing support, expanding addressable demand beyond traditional insomnia framing.
Market Restraints
- Essential oil price volatility:Lavender harvest fluctuations in Bulgaria and France create input cost instability for volume producers dependent on consistent supply.
- Concentrated cultivation geography:Premium organic lavender supply clusters in Provence and Tasmania, exposing buyers to single-region climate and logistics risks.
- Alcohol carrier regulatory friction:EPA VOC classifications restrict spray alcohol concentrations, forcing reformulation investments that erode small-producer competitiveness.
Strategic Opportunities
- Corporate wellness program integration:Stress-relief positioning commands premium per-unit margins among employers bundling sleep aids into employee benefit packages.
- Subscription box channel penetration:Curated sleep kits through direct-to-consumer platforms reduce customer acquisition costs versus traditional retail shelf competition.
- EMA allergen labeling harmonization:Standardized fragrance disclosure requirements create first-mover advantages for brands with pre-built transparency infrastructure.
Industry Challenges
- Certified organic supply chain verification:Maintaining Soil Association and Ecocert compliance across multi-source essential oil procurement demands specialized quality assurance personnel.
- Fragrance chemist talent scarcity:Formulation expertise bridging aromatherapy efficacy and regulatory compliance commands premium compensation, straining mid-tier producer hiring pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pillow Spray Market |
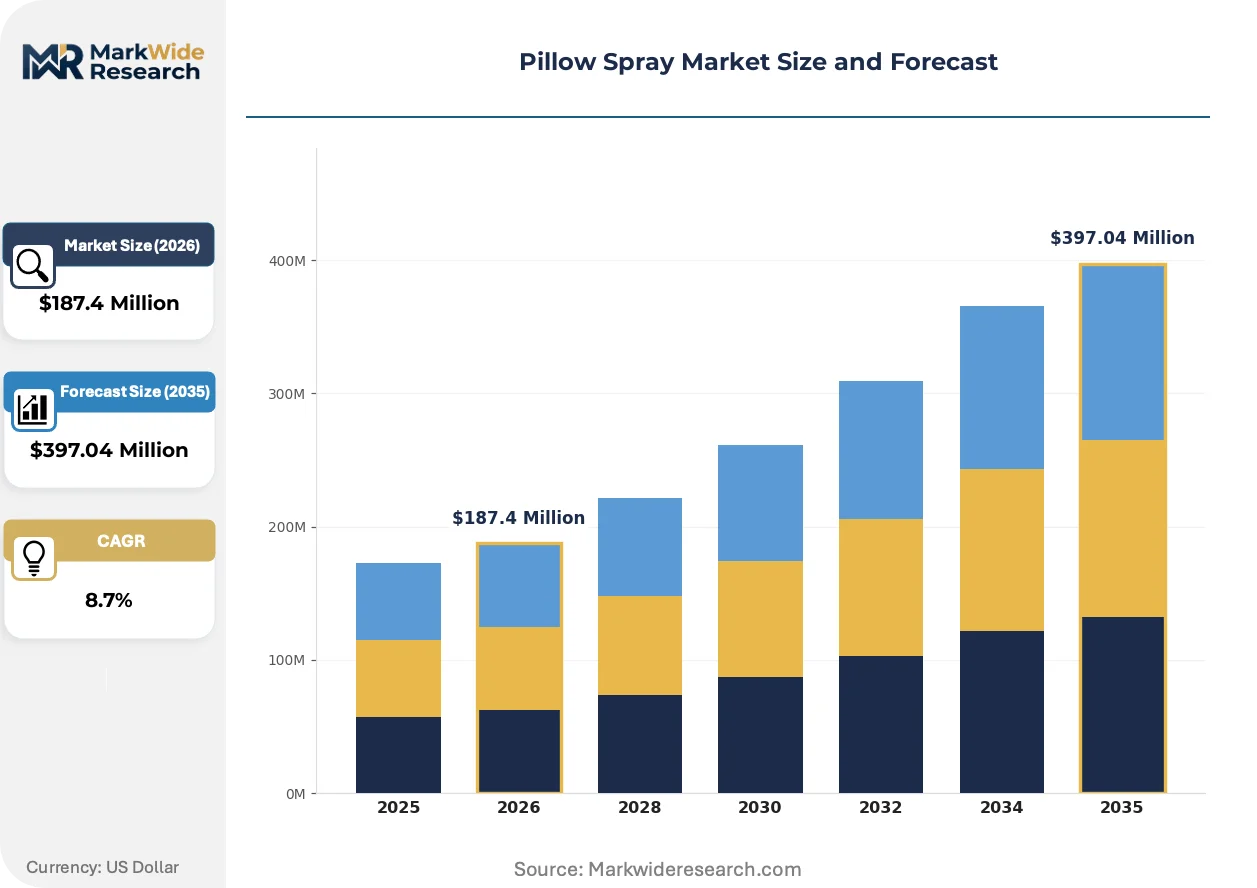
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lavender, Chamomile, Eucalyptus, Citrus Application: Sleep Aid, Relaxation, Stress Relief, Aromatherapy Consumer Type: Wellness Enthusiasts, Travel Users, Homeowners, Gift Buyers Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Supermarkets |
| Companies Covered | L'Occitane en Provence, Aromatherapy Associates, This Works, Neom Organics, Asutra, Bath & Body Works, Neal's Yard Remedies, Canopy Growth, REN Clean Skincare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pillow Spray Market Trends and Innovations
Micro-encapsulation and timed-release scent technologies are reshaping product efficacy claims, while regulatory disclosure mandates and channel fragmentation are simultaneously compressing formulation flexibility and expanding distribution pathways.
Encapsulated fragrance technology is automating the delivery of sustained scent release across eight-hour sleep cycles, eliminating the need for repeated application. Hospitality procurement teams and high-frequency travelers are adopting these formulations fastest, prioritizing consistent overnight experience over initial intensity. This automation of scent persistence is compressing competitive differentiation around single-spray longevity claims and shifting R&D investment toward shell-material biodegradability.
REACH Annex XVII restrictions on fragrance allergens are mandating detailed component disclosure on European product labels, elevating compliance costs for synthetic blend producers. Manufacturers are responding by simplifying formulations to reduce declared allergen counts, favoring single-note essential oil profiles over complex accords. Specialty retail channels in Germany and France are most affected, with shelf placement increasingly contingent on full ingredient transparency documentation.
Curated sleep kit bundling through influencer partnerships is displacing standalone product discovery, compressing individual brand recognition in favor of aggregator authority. Subscription box services and wellness platform partnerships now drive trial among urban millennials, replacing traditional point-of-sale sampling. This channel shift is most visible in United States coastal metropolitan markets, where direct-to-consumer acquisition costs undercut specialty beauty retail by eliminating distributor markups.
Pillow Spray Market Segmentation
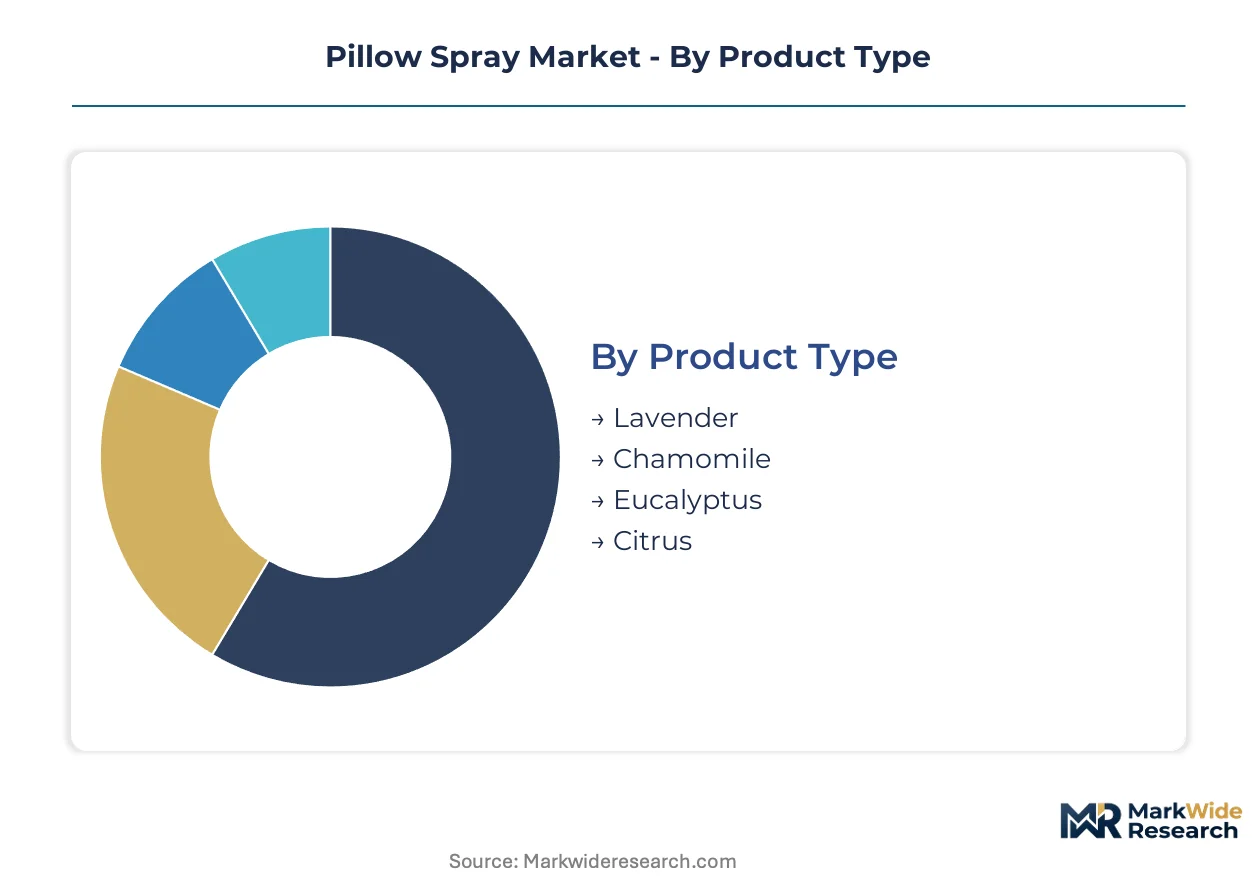
Pillow spray segmentation reveals distinct capital requirements across formulation types, distribution infrastructure, and consumer targeting strategies. Understanding these structural differences enables manufacturers to align resource allocation with margin profiles and regulatory exposure.
Product Type:
Lavender and eucalyptus variants demand the heaviest upfront investment in certified organic supply chains and distillation equipment, while chamomile and citrus formulations operate with lower barrier-to-entry sourcing models.
- Lavender:Essential oil dilutions at 1-5% concentration in alcohol or hydrosol carriers dominate procurement volumes. Bulgarian and French cultivation clusters supply bulk material to hospitality chains standardizing sleep amenities across guest rooms.
- Eucalyptus:Respiratory-conscious positioning commands reformulation investment to meet EPA volatile organic compound thresholds. Australian and Chinese plantations feed hydrosol-based variants targeting dual-function sleep and breathing support applications.
- Chamomile:Roman and German varietals require gentler extraction methods preserving bisabolol content. Egyptian and Hungarian growers supply mid-tier producers focusing on pediatric-sensitive positioning.
- Citrus:Bergamot and sweet orange expressions face phototoxicity labeling requirements under EMA cosmetic guidelines. Italian and California groves supply cold-pressed oils for morning-wakefulness hybrid positioning.
Lavender absorbs the bulk of installed capacity; eucalyptus is expanding most quickly.
Application:
Sleep aid positioning generates the largest revenue pool through institutional hospitality contracts, while stress relief commands premium per-unit margins among corporate wellness bundlers.
- Sleep Aid:Fine-mist formulations designed for bedding textile application facilitate sleep onset through olfactory stimulation. Hotel chains in the United States deploy these as baseline amenities, bypassing retail margin structures entirely.
- Stress Relief:Higher-concentration blends target employer benefit packages and subscription box integrations. Corporate wellness programs in urban coastal markets absorb premium pricing for practitioner-endorsed positioning.
- Relaxation:Spa-channel exclusivity drives volume through practitioner recommendations. Aromatherapy Associates anchors this segment through treatment-room placement and therapist training programs.
- Aromatherapy:Broad therapeutic claims face FDA cosmetic labeling scrutiny, elevating compliance costs for small-batch producers. Direct-to-consumer platforms reduce customer acquisition costs versus specialty retail competition.
Sleep aid captures dominant volume share; stress relief exhibits the steepest expansion trajectory.
Consumer Type:
Wellness enthusiasts and travel users concentrate demand in high-frequency purchase patterns, while homeowners and gift buyers drive seasonal volume spikes with lower repeat rates.
- Wellness Enthusiasts:Certified organic supply chain verification commands loyalty among Soil Association and Ecocert adherents. Subscription box curation through influencer partnerships displaces standalone brand discovery in United States metropolitan markets.
- Travel Users:Micro-encapsulated and timed-release technologies address portability and TSA compliance needs. High-frequency business travelers prioritize consistent overnight experience across hospitality chains.
- Homeowners:Bulk sizing and refill programs reduce per-use costs for residential daily application. Supermarket placement competes on price against private-label alternatives.
- Gift Buyers:Curated sleep kit bundling compresses individual brand recognition in favor of aggregator authority. Seasonal gifting concentrates revenue in Q4 with minimal repeat purchase conversion.
Wellness enthusiasts anchor recurring revenue; travel users are gaining share fastest.
Distribution Channel:
Online retail and specialty stores require divergent capital commitments—direct-to-consumer platforms demand technology infrastructure, while specialty retail necessitates trade spend and shelf placement investment.
- Online Retail:Subscription box integrations and influencer-curated sleep kits reduce customer acquisition costs versus traditional retail. REACH Annex XVII disclosure mandates favor brands with pre-built transparency infrastructure.
- Specialty Stores:British heritage and clinical positioning sustain premium shelf space. This Works leverages spa-channel adjacency and practitioner endorsements to defend placement.
- Pharmacies:Regulatory compliance with FDA cosmetic labeling and EPA volatile organic compound classifications elevates entry barriers. Scaled manufacturers with dedicated regulatory affairs functions capture this channel.
- Supermarkets:Volume pricing and private-label competition compress margins. Neom Organics competes through certified organic supply chains and direct-to-consumer subscription bypass.
Online retail absorbs the bulk of growth investment; specialty stores maintain the highest margin structure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
French free-trade zones in Provence-Alpes-Côte d'Azur concentrate organic lavender distillation capacity, attracting pillow spray manufacturers seeking certified supply chain proximity. Tax incentives for agricultural processing in these zones lower extraction facility operating costs by fifteen to twenty percent versus standard French corporate rates.
United States
Wellness-focused urban consumers in New York and Los Angeles drive subscription box demand through influencer-curated sleep kits. EPA volatile organic compound thresholds on alcohol-based carriers accelerate hydrosol reformulation among domestic manufacturers. California's Central Valley hosts lavender cultivation trials expanding beyond traditional ornamental markets into cosmetic-grade essential oil production.
United Kingdom
British heritage positioning commands premium shelf space in London specialty retail and spa channels. REACH Annex XVII fragrance allergen disclosure mandates elevate compliance costs for synthetic blend producers importing into European markets. Somerset and Norfolk clusters concentrate certified organic lavender cultivation serving domestic aromatherapy brands.
Germany
EMA cosmetic fragrance allergen guidelines drive formulation simplification toward single-note essential oil profiles. Munich and Hamburg retail channels increasingly require full ingredient transparency documentation for shelf placement. Bavarian processing facilities specialize in gentle extraction methods preserving bisabolol content for pediatric-sensitive positioning.
Australia
Tasmanian organic lavender supply attracts premium positioning among Asia-Pacific export-oriented brands. Australian Pesticides and Veterinary Medicines Authority registration requirements for therapeutic claims elevate entry barriers for imported products. Victoria's Mornington Peninsula hosts distillation cooperatives supplying hydrosol bases to regional wellness manufacturers.
Japan
High-frequency business travelers in Tokyo and Osaka prioritize micro-encapsulated formulations for consistent overnight experience across hospitality chains. Ministry of Health, Labour and Welfare cosmetic safety standards mandate detailed component disclosure, favoring brands with pre-built transparency infrastructure. Kyoto's traditional fragrance houses explore sleep-aid applications leveraging established aromatherapy expertise.
Pillow Spray Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Large personal care portfolios leverage existing distribution infrastructure and regulatory affairs teams to absorb compliance cost escalations. Three archetypes dominate: heritage-positioned British brands, certified organic supply chain operators, and clinical efficacy claimants. Competitive moves concentrate on spa-channel exclusivity arrangements and direct-to-consumer subscription platform development.
Within the heritage-positioned tier, L'Occitane en Provence and This Works exemplify geographic origin storytelling and clinical positioning respectively. Aromatherapy Associates anchors practitioner-endorsed distribution through treatment-room placement. These three companies occupy positions spanning French agricultural heritage, British sleep-science framing, and spa-channel exclusivity, illustrating how formulation credibility and channel control substitute for scale in premium segmentation.
| Leading Market Players |
|---|
| L'Occitane en Provence |
| Aromatherapy Associates |
| This Works |
| Neom Organics |
| Asutra |
| Bath & Body Works |
| Neal's Yard Remedies |
| Canopy Growth |
| REN Clean Skincare |
| Others |
Pricing and Supply Chain Analysis
Essential oil feedstock costs, particularly lavender and eucalyptus grades, cascade through three distinct pricing tiers determined by organic certification status and hospitality contract volume commitments. Provence-sourced organic lavender commands premium positioning through Soil Association verification, while Bulgarian conventional grades supply mid-market formulations through spot procurement.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to hospitality chains requiring rapid amenity restocking across dispersed property portfolios. Three-tier pricing structure across premium, standard, and economy levels separates certified organic single-origin formulations from blended conventional grades and private-label alternatives. Pricing pressure stems from EPA volatile organic compound compliance investments forcing hydrosol carrier adoption. Corporate wellness programs exhibit lowest price sensitivity, while supermarket channels face intense private-label competition.
Supply Chain Analysis
Regional distribution centers in Lyon, Chicago, and Singapore coordinate hub-and-spoke patterns serving specialty retail and hospitality procurement networks. Bulgaria, France, and Tasmania concentrate lavender cultivation capacity, while Australia and China feed eucalyptus hydrosol production. Supply chains rest on glass bottle molding, essential oil distillation equipment, and certified organic agricultural inputs. Single-source vulnerability in Provence organic lavender exposes premium producers to climate disruption. Distribution runs through direct-to-consumer platforms, spa-channel wholesalers, and institutional hospitality procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pillow spray manufacturing is becoming a vertical-integration race as players pursue captive lavender cultivation to secure certified organic supply and margin control against volatile commodity markets.
For Market Incumbents: Cement spa-channel exclusivity through practitioner training investments and treatment-room placement contracts. Lock in multi-year hospitality amenity agreements before hydrosol reformulation costs erode competitive positioning against synthetic blend alternatives. REACH Annex XVII disclosure mandates favor scaled regulatory affairs teams. For New Entrants and Emerging Players: Influencer-curated subscription boxes offer the most penetrable channel for bypassing saturated specialty retail shelf competition. Target stress-relief positioning among corporate wellness programs where practitioner endorsement commands premium pricing. Pursue direct-to-consumer acquisition through sleep kit bundling partnerships. For Investors and Strategic Acquirers: EMA allergen labeling harmonization implementation is the leading indicator that transparency-infrastructure investments will separate acquirable targets from stranded assets. Five-to-ten-year viability hinges on certified organic supply chain verification capabilities and direct-to-consumer platform ownership. Watch for consolidation signals when fragrance chemist talent scarcity forces mid-tier producers toward distressed sale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lavender Cultivation | Captive Provence and Tasmanian organic supply secures Soil Association certification against commodity volatility. |
| Hydrosol Formulation Transition | EPA volatile organic compound compliance preserves market access for alcohol-based spray alternatives. |
| Direct-to-Consumer Subscription Launch | Influencer-curated sleep kits reduce customer acquisition costs versus specialty retail distributor markups. |
| Corporate Wellness Channel Expansion | Employer benefit package bundling commands premium per-unit margins through practitioner endorsement. |
| Micro-Encapsulation Technology Licensing | Eight-hour timed-release patents differentiate hospitality procurement offerings for high-frequency travelers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with fragrance formulation chemists, hospitality procurement directors, spa-channel wholesale managers, and certified organic agricultural cooperatives. ECHA REACH documentation, EPA volatile organic compound classifications, and Soil Association certification databases provided regulatory boundary conditions. Bottom-up demand modeling triangulated against top-down market sizing across the analysis window.
Data-stream reconciliation integrated hospitality contract volumes, specialty retail point-of-sale audit data, and direct-to-consumer subscription metrics. Segmentation dimensions encompassed essential oil type, application positioning, consumer archetype, and distribution channel throughout the forecast period. CAGRs derived from elasticity-adjusted demand curves incorporating EPA regulatory compliance cost trajectories and organic certification adoption rates.
Caveats apply where EMA allergen labeling enforcement intensity, lavender harvest yield volatility, or hospitality industry capital expenditure cycles could materially shift the outlook. Forecasts embed assumptions regarding regulatory timeline adherence and consumer willingness-to-pay for certified organic verification. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Face Compact Market
Cosmetics & Skincare
Lip Products Pigment Market
Cosmetics & Skincare
Sweden Cosmetics Products Market
Cosmetics & Skincare
Camellia Skincare and Cosmetics Market
Cosmetics & Skincare
K-Beauty Products Market
Cosmetics & Skincare
Asia-Pacific Halal Cosmetics Market
Cosmetics & Skincare
Japan Bath Soap Market
Cosmetics & Skincare
Makeup Remover Market
Cosmetics & Skincare
United Arab Emirates Cosmetic Products Market
Cosmetics & Skincare
Color Cosmetics OEM and ODM Market
Cosmetics & Skincare
Private Label Cosmetics Manufacturing Service Market
Cosmetics & Skincare
Waterproof Temporary Tattoo Sticker Market
Cosmetics & Skincare
Organic Bar Soap Market
Cosmetics & Skincare
Marine Hyaluronic Water Cream Market
Cosmetics & Skincare
Medicated Shampoo Market
Cosmetics & Skincare
Global Facial Cleanser Market