
 Qatar Cosmetic Products Market | 2026-2036
Qatar Cosmetic Products Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Cosmetic Products Market Analytics
Buyer concentration in Qatar is pivoting toward luxury hotel spas and premium salon chains that now command bulk procurement contracts once fragmented across independent retailers. L'Oréal SA leverages its professional division to anchor supply relationships with Doha's five-star hospitality groups. Beiersdorf AG competes through Nivea's accessible dermatological positioning in pharmacy channels. Shiseido Co Ltd differentiates via Japanese formulation credibility among Gulf consumers seeking non-European alternatives.
Cosmetic products encompass chemically formulated preparations applied to human skin, hair, or nails for cleansing, beautifying, or protective functions, typically containing emulsifiers, active ingredients, and preservation systems stabilized within defined pH ranges. These products serve commercial purposes ranging from daily personal hygiene to professional aesthetic services in salon and clinical settings. Skincare dominates value generation due to Gulf climate-driven concerns around hydration and sun protection, while fragrance captures disproportionate margin pools linked to gifting customs and Ramadan consumption peaks. Online retail represents the fastest-growing distribution channel as Qatari consumers under age thirty-five shift mobile-first purchasing behaviors.
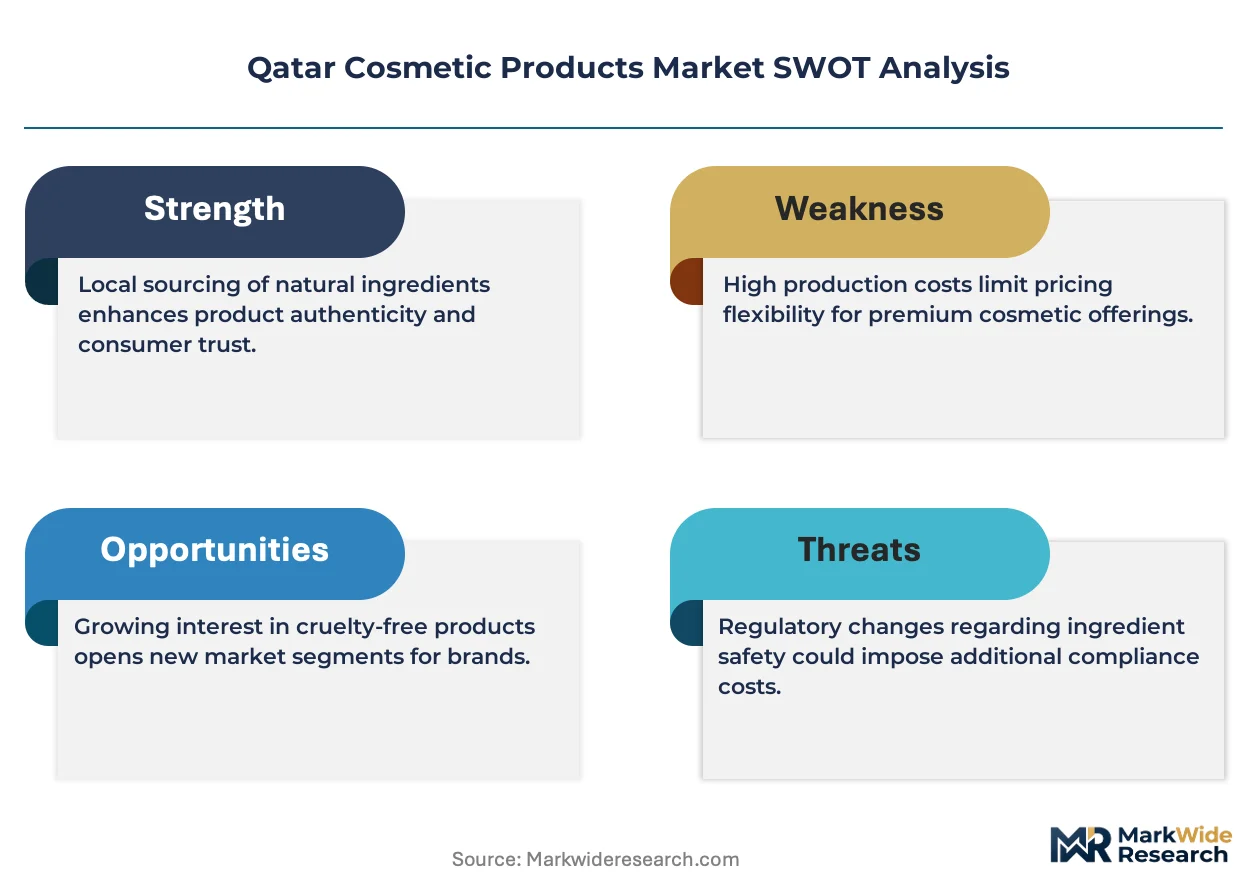
Qatar's Ministry of Public Health enforces cosmetic product registration under its national health authority framework, requiring safety assessments and Arabic labeling that filter non-compliant imports from Gulf Cooperation Council markets. The country's adherence to GCC Standardization Organization (GSO) cosmetic regulations harmonizes ingredient restrictions with Saudi Arabia and the UAE, reducing multi-market compliance burdens for entrants. Stakeholders must monitor MOHAP's evolving stance on clean beauty claims and halal certification alignment, as these criteria increasingly determine shelf access in Qatar's consolidated retail landscape.
Market Dynamics
Qatar's cosmetic products sector is compressing around professional-grade supply chains as luxury hospitality venues consolidate procurement power and MOHAP tightens registration protocols that filter non-compliant imports.
Growth Catalysts
- MOHAP Registration Mandates:The Ministry of Public Health's intensified safety assessment requirements for imported cosmetics are accelerating reformulation investments among brands seeking shelf access in Doha's consolidated retail landscape.
- Luxury Hospitality Expansion:Five-star hotel spas and premium salon chains in West Bay and Pearl-Qatar districts are aggregating bulk procurement contracts previously fragmented across independent retailers.
- Climate-Driven Skincare Demand:Gulf-specific hydration and sun protection concerns are pulling premium dermatological formulations into daily use among affluent residents and expatriate professionals.
Market Restraints
- Ingredient Disclosure Burden:MOHAP's tightening Arabic labeling and safety documentation requirements impose compliance costs that disadvantage smaller import brands lacking Gulf market infrastructure.
- Supply Concentration in Doha:Distribution and retail gravity centers on West Bay and Pearl-Qatar districts, creating geographic dependency that limits penetration into secondary Qatari markets.
- Reformulation Cycle Compression:Accelerating regulatory alignment with GCC Standardization Organization ingredient restrictions forces repeated product adaptation, eroding margin stability for established portfolios.
Strategic Opportunities
- Online Retail Channel Development:Mobile-first purchasing behaviors among Qatari consumers under age thirty-five are opening direct-to-consumer pathways that bypass traditional pharmacy and department store gatekeepers.
- Halal Certification Alignment:Evolving MOHAP stance on clean beauty claims and Islamic compliance standards creates positioning space for brands that integrate religious certification with premium formulation credibility.
- Ramadan Gifting Concentration:Seasonal fragrance consumption peaks tied to Islamic calendar observances offer concentrated margin capture for brands with calibrated inventory and promotional timing.
Industry Challenges
- Skilled Formulation Talent Scarcity:Local expertise in GCC-adapted cosmetic chemistry remains concentrated among expatriate professionals, complicating in-house product development for market entrants.
- MOHAP Approval Timeline Variability:Registration processing durations for imported cosmetics create inventory planning uncertainty that strains working capital for distributors managing multiple brand portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Cosmetic Products Market |
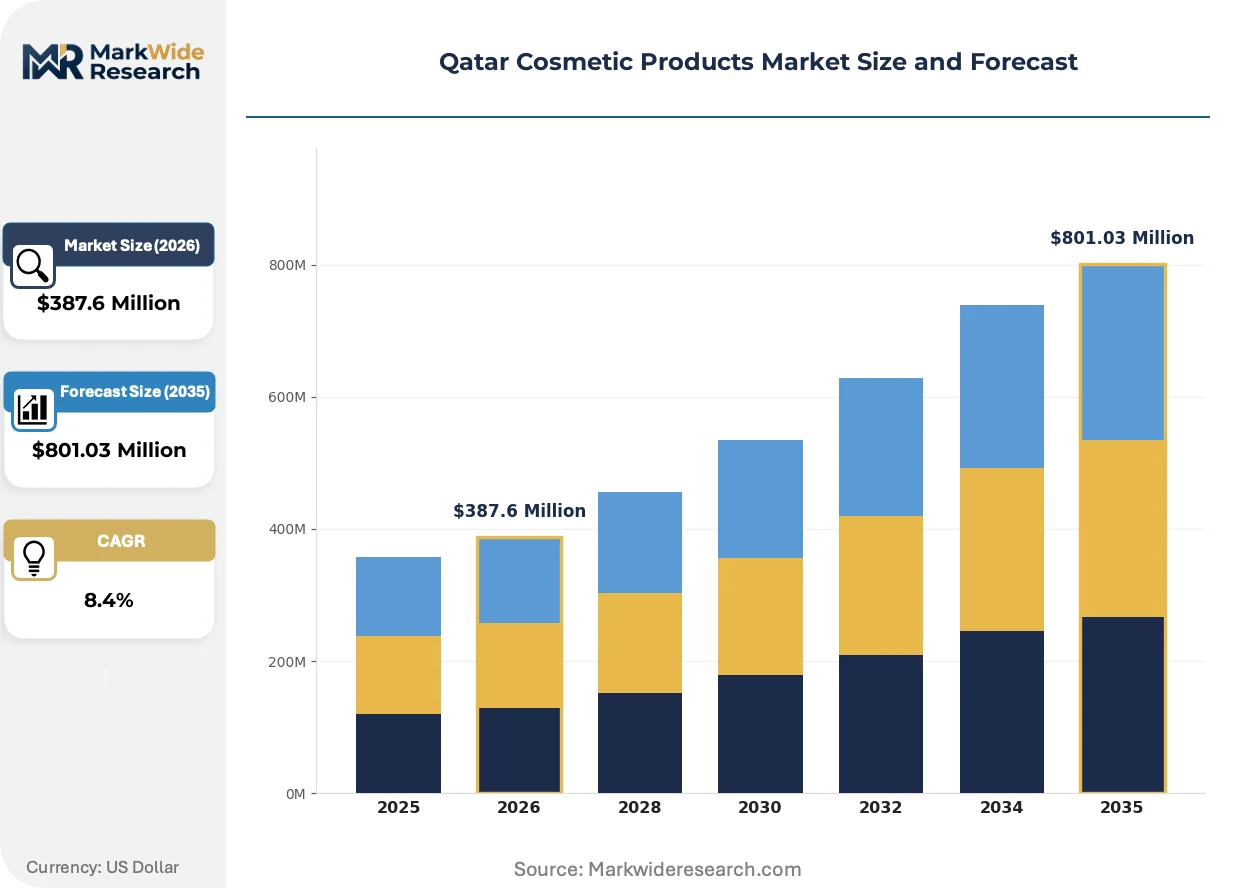
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $801.03 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
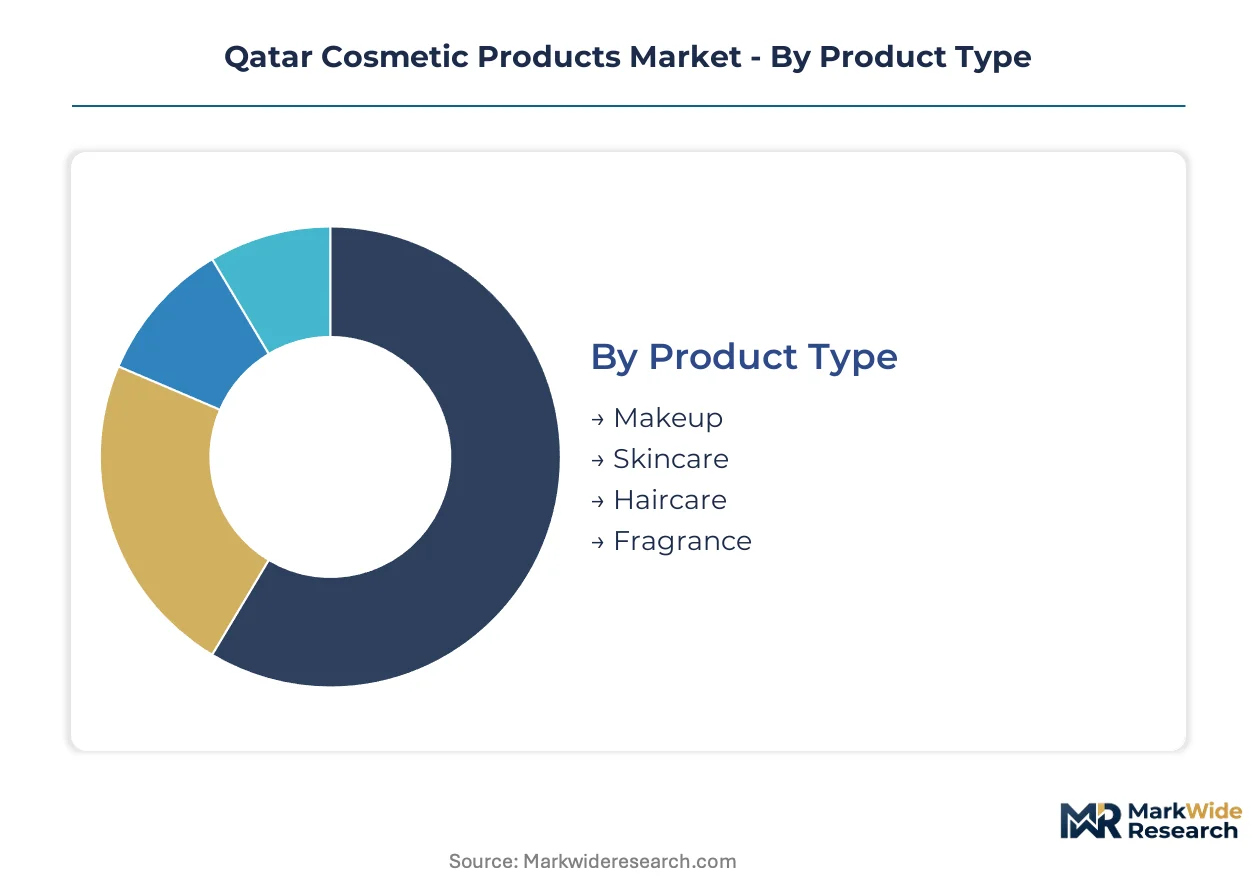
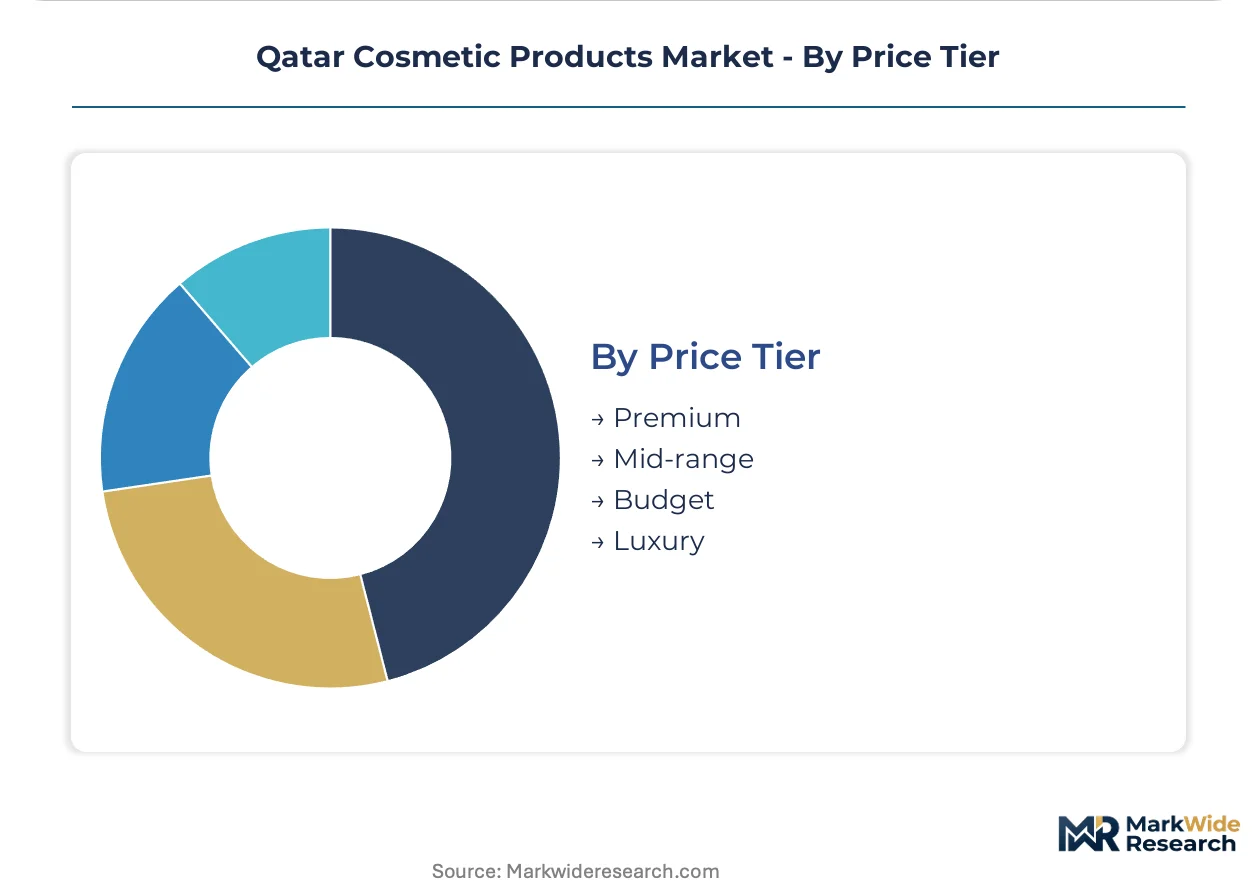
| Segmentation | Product Type: Makeup, Skincare, Haircare, Fragrance Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Pharmacies Customer Type: Women, Men, Teenagers, Professionals Price Tier: Premium, Mid-range, Budget, Luxury |
| Companies Covered | Coty Inc., Procter & Gamble Company, L'Oréal SA, Beiersdorf AG, Unilever PLC, The Estée Lauder Companies, LVMH Moët Hennessy Louis Vuitton, Oriflame Holdings AG, Shiseido Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Cosmetic Products Market Evolving Landscape
Active ingredient transparency and channel digitization are restructuring how cosmetic products reach Qatari consumers, with professional-grade formulations migrating from clinical settings into daily retail.
Encapsulated delivery systems for hyaluronic acid and vitamin C are integrating into premium skincare lines targeting Gulf climate stressors. Doha's luxury hotel spas are adopting these technologies at accelerated pace for in-treatment protocols. This convergence is integrating professional efficacy claims into consumer-facing product positioning.
MOHAP's alignment with GCC Standardization Organization cosmetic regulations is harmonizing ingredient restrictions across Qatar, Saudi Arabia, and the UAE. This regulatory convergence reduces multi-market compliance burdens for entrants but compresses formulation flexibility. Professional-grade brands are responding by developing GCC-specific SKUs that preempt cross-border regulatory friction.
Mobile commerce penetration among Qatari consumers under thirty-five is fragmenting traditional pharmacy and department store dominance. Direct-to-consumer platforms and social commerce integrations are capturing fragrance and skincare transactions previously routed through physical retail. This channel rotation is most visible in Pearl-Qatar and West Bay districts where affluent digital-native consumers cluster.
Qatar Cosmetic Products Market Segmentation
Qatar's cosmetic market stratification reflects the purchasing power concentration in Doha's affluent districts and the regulatory filtering imposed by MOHAP registration protocols. Segment boundaries are hardening around professional-grade supply chains and digital-native consumption patterns.
Product Type:
Capital requirements vary sharply across formulation categories, with professional-grade skincare demanding the most substantial R&D and safety assessment investments.
- Skincare:Emulsion-based formulations with active ingredients like hyaluronic acid and vitamin C require extensive stability testing under Gulf climate conditions. Demand concentrates in West Bay and Pearl-Qatar districts where expatriate professionals and affluent residents prioritize dermatological efficacy for hydration and sun protection concerns.
- Fragrance:Concentrated perfume oils and alcohol-based preparations command the highest margin pools in Qatar's market, tied to Ramadan gifting customs and hospitality venue procurement. Five-star hotel spas in Doha aggregate bulk contracts for signature scent programs, displacing fragmented independent retailer purchases.
- Makeup:Color cosmetics with GCC-adapted formulations for heat resistance.
- Haircare:Salon-grade treatments and daily maintenance products for professional and consumer channels.
Skincare absorbs the bulk of installed formulation capacity; fragrance is expanding most quickly through hospitality channel consolidation.
Distribution Channel:
Channel economics diverge around inventory velocity and compliance burden, with online platforms offering the lowest regulatory friction for new market entrants.
- Online Retail:Mobile-first platforms and social commerce integrations capture transactions from Qatari consumers under thirty-five, bypassing traditional pharmacy and department store gatekeepers. Pearl-Qatar and West Bay districts show the highest digital penetration among affluent digital-native consumers.
- Pharmacies:Dermatological positioning and accessible price points anchor volume in this channel, with Nivea and similar brands leveraging pharmacy credibility. MOHAP registration requirements filter non-compliant imports, concentrating shelf access among established players with Gulf market infrastructure.
- Specialty Stores:Premium beauty retailers with trained consultants and tester programs.
- Supermarkets:Mass-market personal care products with high inventory turnover.
Pharmacies dominate current transaction volume; online retail claims the steepest expansion trajectory among Qatari consumers under thirty-five.
Customer Type:
Purchasing behavior splits along professional necessity versus discretionary gifting motivations, with distinct product specifications for each cohort.
- Women:Core volume drivers across all product categories with concentrated spending in premium skincare and fragrance.
- Professionals:Salon operators and hospitality procurement managers command bulk contracts for professional-grade formulations, consolidating demand previously fragmented across independent retailers. L'Oréal's professional division anchors supply relationships with Doha's five-star hospitality groups.
- Men:Grooming products with simplified regimens and masculine-positioned fragrance.
- Teenagers:Entry-level color cosmetics and social-media-influenced purchasing.
Women account for the majority of current spending; professionals are gaining share fastest through hospitality procurement consolidation.
Price Tier:
Margin structures align with certification burden and ingredient transparency requirements, with luxury tiers absorbing the highest compliance costs.
- Luxury:Exclusive formulations with proprietary delivery systems and limited distribution. Japanese brands like Shiseido leverage non-European formulation credibility among Gulf consumers seeking alternatives to L'Oréal and Beiersdorf portfolios.
- Premium:Professional-grade products with clinical efficacy claims and halal certification alignment. MOHAP's evolving stance on clean beauty claims creates positioning space for brands integrating religious certification with formulation credibility.
- Mid-range:Accessible quality with pharmacy channel presence.
- Budget:Mass-market personal care with minimal margin and high volume turnover.
Luxury tiers capture the highest margins per unit; premium segments are climbing the fastest as MOHAP registration protocols filter out non-compliant budget alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability along Qatar's northeastern coast anchors cosmetic formulation capacity, with Doha's industrial zones supporting emulsifier and active ingredient processing for Gulf markets.
Saudi Arabia
Fragrance oil distillation and oud-based perfume manufacturing drive demand in Riyadh and Jeddah. The Saudi Food and Drug Authority enforces cosmetic registration protocols that align with GCC Standardization Organization standards. The Eastern Province's Jubail industrial cluster hosts petrochemical facilities supplying cosmetic-grade ethanol and emollients to regional formulators.
United Arab Emirates
Dubai's duty-free retail corridors and Abu Dhabi's luxury hospitality sector concentrate fragrance and skincare procurement. The UAE Ministry of Health and Prevention operates a parallel registration system that cross-recognizes GCC-compliant safety documentation. Jebel Ali free zone warehouses serve as transshipment nodes for Qatar-bound cosmetic imports.
Kuwait
High per-capita income and Ramadan gifting customs sustain premium fragrance consumption in Kuwait City. The national pharmaceutical regulator requires Arabic labeling and safety assessments for all cosmetic imports. The Shuwaikh industrial area contains regional distribution centers serving northern Gulf markets with consolidated logistics.
Bahrain
Professional salon services and bridal beauty preparation sustain mid-range color cosmetics demand in Manama. The national health regulator maintains cosmetic product registration requirements harmonized with GCC standards. The Sitra industrial zone hosts light manufacturing and repackaging operations for Bahrain-Qatar trade corridors.
Qatar Cosmetic Products Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue halal-certified formulations and direct-to-consumer digital channels. The vendor base stratifies around three archetypes: multinational conglomerates with professional-grade divisions, regional distributors with MOHAP registration expertise, and niche players leveraging non-European formulation credibility. Dominant competitive moves include portfolio diversification into climate-adapted skincare and strategic partnerships with Doha hospitality procurement managers.
Within the multinational tier, L'Oréal SA and Beiersdorf AG exemplify divergent positioning strategies, with the former anchoring professional supply relationships and the latter occupying accessible dermatological channels. Shiseido Co Ltd represents the non-European alternative archetype, leveraging Japanese formulation credibility among Gulf consumers seeking differentiated sourcing. These three entities collectively illustrate how geographic origin and channel specialization structure competitive access to Qatar's consolidated retail landscape.
| Leading Market Players |
|---|
| Coty Inc. |
| Procter & Gamble Company |
| L'Oréal SA |
| Beiersdorf AG |
| Unilever PLC |
| The Estée Lauder Companies |
| LVMH Moët Hennessy Louis Vuitton |
| Oriflame Holdings AG |
| Shiseido Co Ltd |
| Others |
Value Network & Pricing Analysis
Petrochemical feedstock costs from Qatar's northeastern industrial zones cascade through emulsifier and active ingredient processing before stratifying across luxury, premium, and mass-market cosmetic tiers in Doha's retail landscape. The concentration of formulation capacity near Ras Laffan anchors input pricing power for domestic producers while import-dependent brands absorb GCC-wide logistics premiums.
Pricing Analysis
Service bundling separates professional-grade supply contracts from unbundled retail transactions, with hospitality procurement managers negotiating inclusive training and inventory management alongside bulk formulation purchases. Three-tier pricing structure across luxury, premium, and economy levels reflects halal certification investment and MOHAP registration compliance burden. Price differentiation hinges on clinical efficacy claims and Arabic labeling completion status. Margins are tightening in the mid-range tier due to reformulation cycle compression for GCC ingredient alignment. Budget-conscious independent retailers exhibit highest price sensitivity; five-star hotel spas demonstrate lowest sensitivity given procurement consolidation advantages.
Supply Chain Analysis
Encapsulated active ingredient supply rests on Japanese and South Korean specialty chemical producers for hyaluronic acid and vitamin C delivery systems. European fragrance houses and UAE-based oud distillers feed concentrated perfume oil inputs. Single-source vulnerability concentrates in Japanese biotech-derived actives. Distribution runs through Jebel Ali free zone transshipment nodes before MOHAP registration clearance at Doha port facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive emulsifier production and direct-to-consumer digital infrastructure is accelerating as players seek margin defense against reformulation cost inflation and channel disintermediation.
For Market Incumbents: Deepen professional division relationships with Pearl-Qatar and West Bay hospitality procurement managers to lock in multi-year supply contracts before digital-native competitors establish direct channels. Anchor backward integration into GCC-adapted formulation R&D to reduce dependency on expatriate chemistry talent. Defend against halal-certified niche entrants by accelerating MOHAP clean beauty claim alignment. For New Entrants and Emerging Players: Launch via mobile-first social commerce platforms targeting Qatari consumers under thirty-five in West Bay and Pearl-Qatar districts, bypassing pharmacy and department store gatekeepers. Penetrate the Ramadan gifting fragrance segment through calibrated inventory timing and Islamic calendar promotional alignment. Exploit regulatory friction burdening smaller import brands by front-loading MOHAP registration investment. For Investors and Strategic Acquirers: Accelerating hospitality procurement consolidation is the leading indicator that professional-grade supply relationships will command scarcity premiums in the medium-term outlook. Target acquisition profiles center on regional distributors with established MOHAP registration expertise and existing five-star hotel spa contracts. Watch for MOHAP approval timeline standardization as the signal that working capital efficiency gains are unlocking for multi-brand portfolio managers.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Investment | MOHAP's evolving clean beauty stance makes Islamic compliance a shelf-access prerequisite in Doha's consolidated retail landscape. |
| Direct-to-Consumer Platform Launch | Mobile-first purchasing behaviors among Qatari consumers under thirty-five fragment traditional pharmacy and department store dominance. |
| Professional Division Capacity Expansion | Luxury hospitality venues in West Bay and Pearl-Qatar are aggregating bulk procurement contracts previously fragmented across independents. |
| GCC-Adapted Formulation R&D | Climate-specific hydration and sun protection claims require stability testing investments that filter non-compliant import competitors. |
| Hospitality Supply Partnership | Five-star hotel spas anchor professional-grade volume with signature scent programs and in-treatment protocol integration. |
Research Methodology
Multi-period observation of MOHAP registration processing durations, hospitality procurement contract structures, and mobile commerce penetration rates anchored the trend analysis, supplemented by interviews with cosmetic brand managers, pharmacy category buyers, hospitality procurement directors, and GCC regulatory affairs specialists. Primary fieldwork combined with secondary validation from Qatar customs records, GCC Standardization Organization cosmetic regulation updates, and regional retail audit databases. Bottom-up segment sizing triangulated against top-down market value estimates.
Segment-weighting across product type, distribution channel, customer archetype, and price tier dimensions structured the analytical framework across the projection horizon. Skincare and fragrance category trajectories were modeled separately given divergent margin dynamics and regulatory exposure. CAGRs were derived from trend extrapolation of hospitality procurement consolidation rates and digital channel share expansion. Climate-adapted formulation adoption curves and halal certification completion timelines served as industry-specific forecast inputs.
MOHAP regulatory stance shifts, GCC ingredient restriction amendments, and hospitality sector investment cycles are the dominant revision risks to the forecast framework. Forecasts reflect documented assumptions regarding registration timeline stability and digital commerce penetration sustainability. A concentrated set of regulatory and channel-evolution triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Lip Scrub Market
Cosmetics & Skincare
Malaysia Skin Care Products Market
Cosmetics & Skincare
Lip Oil Market
Cosmetics & Skincare
North America Bath Soap Market
Cosmetics & Skincare
Halal Cosmetics Market
Cosmetics & Skincare
Makeup Remover Market
Cosmetics & Skincare
Cosmetics ODM Market
Cosmetics & Skincare
Cosmetics Private Label and Contract Manufacturing Market
Cosmetics & Skincare
Lip Products Pigment Market
Cosmetics & Skincare
Cosmetic Mirror Market
Cosmetics & Skincare
Glow in the Dark Cosmetics Market
Cosmetics & Skincare
Matte Lipstick Market
Cosmetics & Skincare
France Lip Care Products Market
Cosmetics & Skincare
Chile Cosmetics Products Market
Cosmetics & Skincare
Vietnam Skin Care Products Market
Cosmetics & Skincare
Loose Setting Powder Market