
 Middle East Catalog Market | 2026-2036
Middle East Catalog Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Catalog Market Insights
Market Context
Aftermarket service revenue attached to catalog platforms is reconfiguring how retailers monetize customer relationships beyond initial transactions. noon leverages its fulfillment network to sustain last-mile delivery advantages across Saudi Arabia and Egypt. Amazon.ae anchors its catalog operations with Prime-integrated logistics, while Majid Al Futtaim competes through mall-to-digital hybrid experiences that bridge physical and online browsing.
Technical Definition and Segment Structure
A catalog in this context constitutes a structured product database rendered through print, web, or mobile interfaces, typically incorporating SKU metadata, pricing tiers, and inventory availability signals to facilitate B2B or B2C procurement decisions. Digital catalogs now dominate volume, though printed variants retain traction in B2B industrial supply and luxury real estate verticals where tactile presentation influences purchasing authority. Fashion and retail verticals lead industry segmentation, with mobile apps representing the fastest-growing distribution channel as smartphone penetration exceeds fixed broadband in several Gulf states. Interactive catalogs, embedding AR visualization and real-time inventory APIs, capture expanding margin pools as merchants prioritize engagement metrics over static impressions.
Regulatory Environment
Saudi Arabia's e-commerce regulations, the UAE's data protection framework, and Egypt's consumer protection standards collectively shape catalog platform compliance burdens across the region. These frameworks mandate disclosure of seller identity, return policies, and pricing transparency, which elevates operational costs for cross-border catalog operators while creating barriers for informal marketplace entrants. Stakeholders must monitor evolving VAT harmonization across GCC states and assess whether centralized catalog infrastructure or country-specific platform variants better balance compliance efficiency against customer experience localization.
Market Dynamics
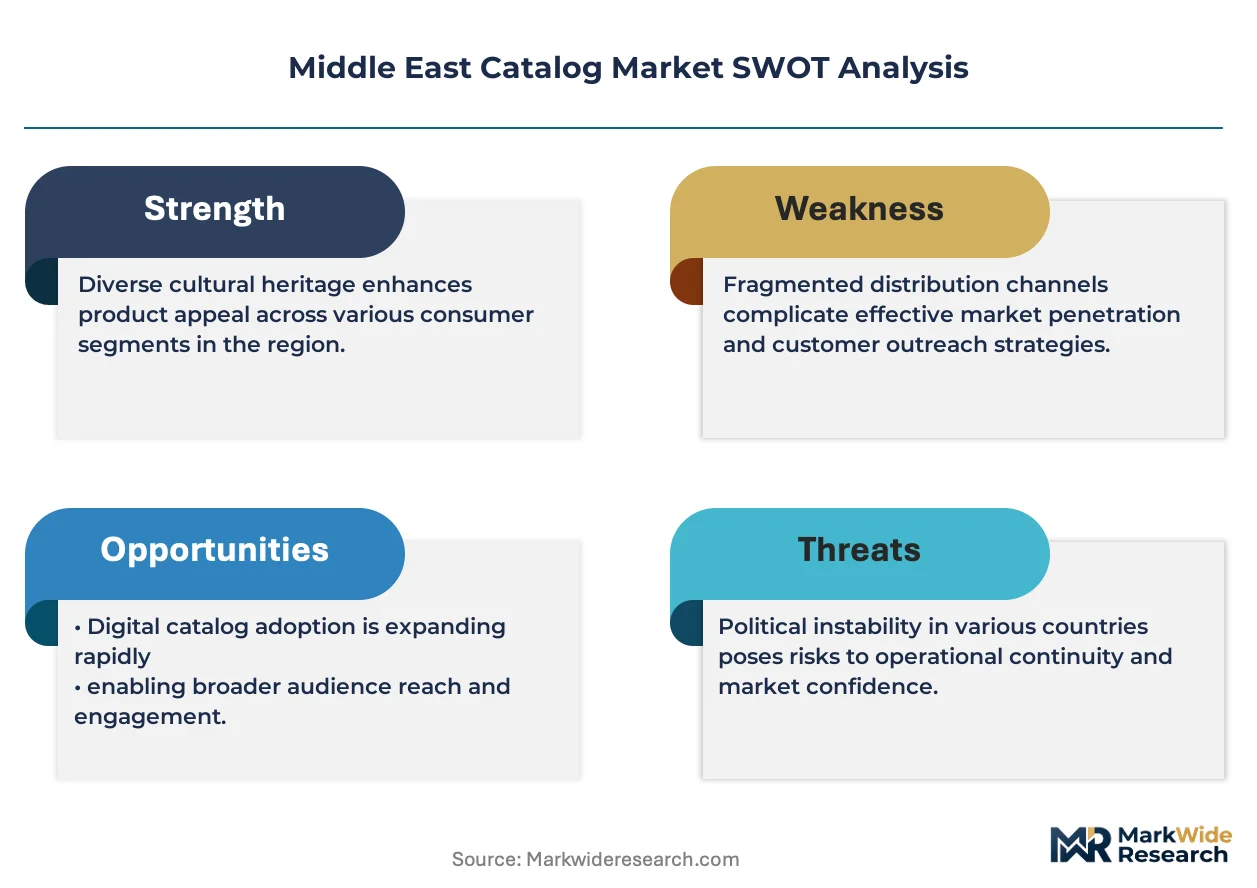
Catalog platform economics across the Middle East are being restructured by Saudi Arabia's data localization mandates, which force operators to deploy country-specific infrastructure rather than centralized regional hubs.
Growth Catalysts
- SFDA e-commerce disclosure rules:Saudi Arabia's mandate for seller identity transparency and return policy standardization is formalizing previously informal marketplace transactions, expanding addressable transaction volume for compliant catalog operators.
- Smartphone-first catalog consumption:Mobile app distribution channels are capturing the fastest-growing segment as Gulf smartphone penetration exceeds fixed broadband availability, particularly among younger demographics in the UAE and Qatar.
- Dubai logistics clustering:Jebel Ali's free zone infrastructure enables same-day catalog fulfillment across the GCC, reducing working capital requirements for inventory-heavy retail verticals.
Market Restraints
- Cross-border VAT fragmentation:GCC states maintain divergent VAT implementation timelines and exemption categories, forcing catalog operators to maintain separate pricing engines and tax calculation logic for each market.
- Data center infrastructure scarcity:Saudi Arabia's data localization requirements confront limited in-country cloud capacity, elevating capital intensity for platform operators seeking compliance.
- Printed catalog substitution pressure:Industrial B2B procurement committees in construction and oilfield services retain preference for tactile presentation formats, slowing full digital migration in high-value verticals.
Strategic Opportunities
- Egypt consumer protection alignment:Cairo's evolving e-commerce standards create first-mover advantage for catalog platforms that preemptively implement disclosure and dispute-resolution infrastructure ahead of formal enforcement.
- AR-integrated product visualization:Furniture and automotive parts verticals are deploying augmented reality overlays that reduce return rates and compress purchase decision cycles.
- Mall-to-digital hybrid experiences:UAE retail operators are converting physical foot traffic into catalog-registered users through in-store QR activation and click-and-collect fulfillment integration.
Industry Challenges
- API integration complexity:Legacy ERP systems in Saudi industrial supply chains require custom middleware development to synchronize real-time inventory signals with digital catalog frontends.
- Multilingual content operations:Catalog platforms must maintain parallel Arabic-English product metadata workflows, elevating editorial costs and slowing SKU onboarding velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Catalog Market |
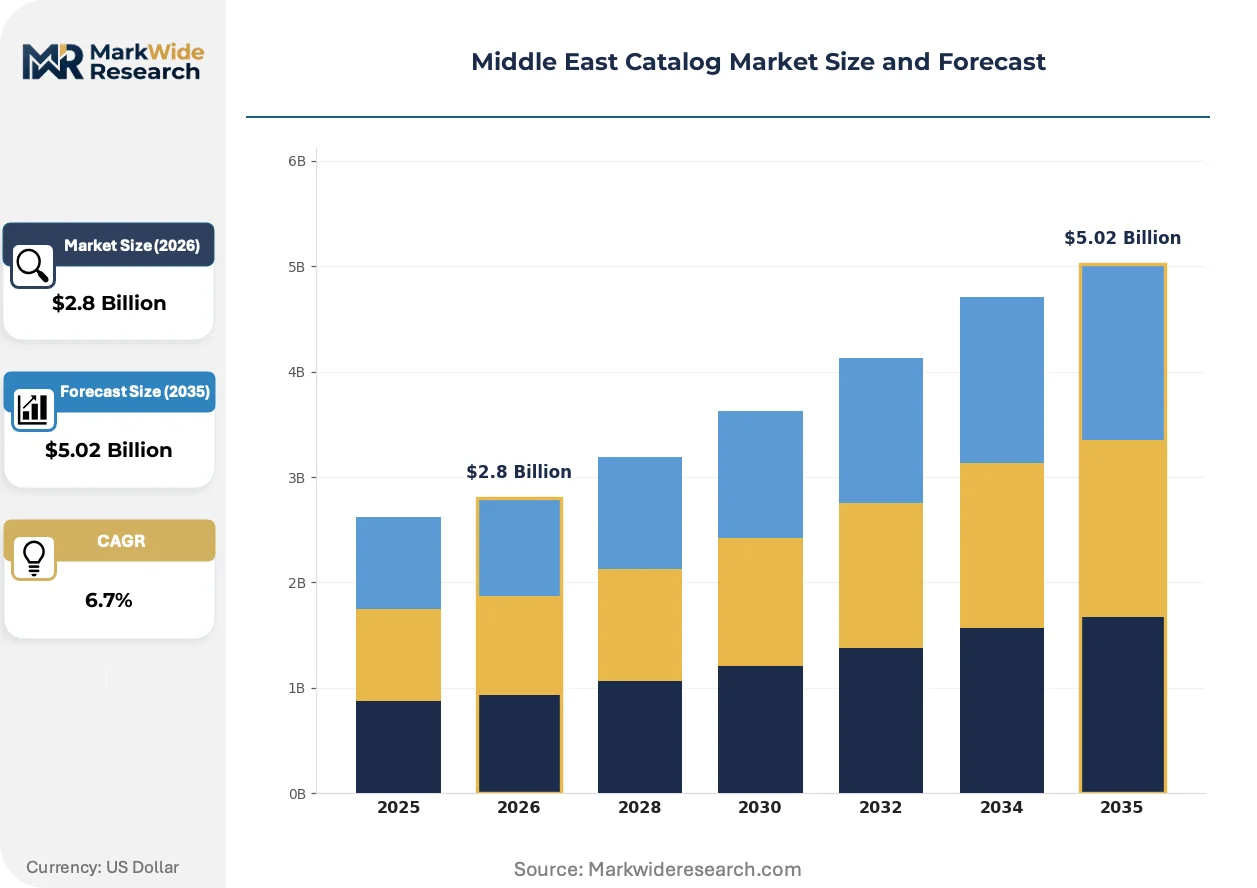
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Printed Catalogs, Digital Catalogs, Mobile Catalogs, Interactive Catalogs Industry Vertical: Retail, Automotive, Real Estate, Fashion Distribution Channel: Online, In-Store, Direct Mail, Mobile Apps Customer Type: Consumers, Businesses, Government, Non-Profit |
| Companies Covered | noon, Amazon.ae, Souq, Namshi General Trading LLC, Majid Al Futtaim, LuLu Group International, Carrefour, Trendyol, Jumia Technologies AG, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Catalog Market Trends and Innovations
Interactive catalog formats embedding real-time inventory APIs and immersive visualization tools are compressing the traditional browse-to-purchase funnel across Middle East retail verticals.
Headless commerce architecture is rendering obsolete monolithic catalog platforms that couple frontend presentation layers with backend transaction processing. UAE-based fashion retailers are adopting API-first infrastructure to enable simultaneous deployment across mobile apps, social commerce channels, and in-store kiosks. This decoupling is rendering obsolete the previous generation of platform vendors that required months-long implementation cycles for each new touchpoint.
MOHAP's UAE data protection framework is mandating explicit consent mechanisms for customer data processing in catalog platforms, with particular scrutiny on cross-border data transfers to non-GCC jurisdictions. Retail operators are responding by localizing customer databases and implementing granular permission management systems. Luxury verticals with high customer lifetime value are investing most heavily in compliance infrastructure given their exposure to reputational risk.
Corporate procurement committees in Saudi construction and oilfield services are unbundling catalog purchasing from integrated supplier relationships, instead demanding standalone platform access with transparent pricing and independent fulfillment verification. This pattern is displacing traditional distributor-captive purchasing arrangements. The shift is most visible in Riyadh and Dammam industrial zones where project owners now mandate direct platform access for materials procurement.
Middle East Catalog Market Segmentation
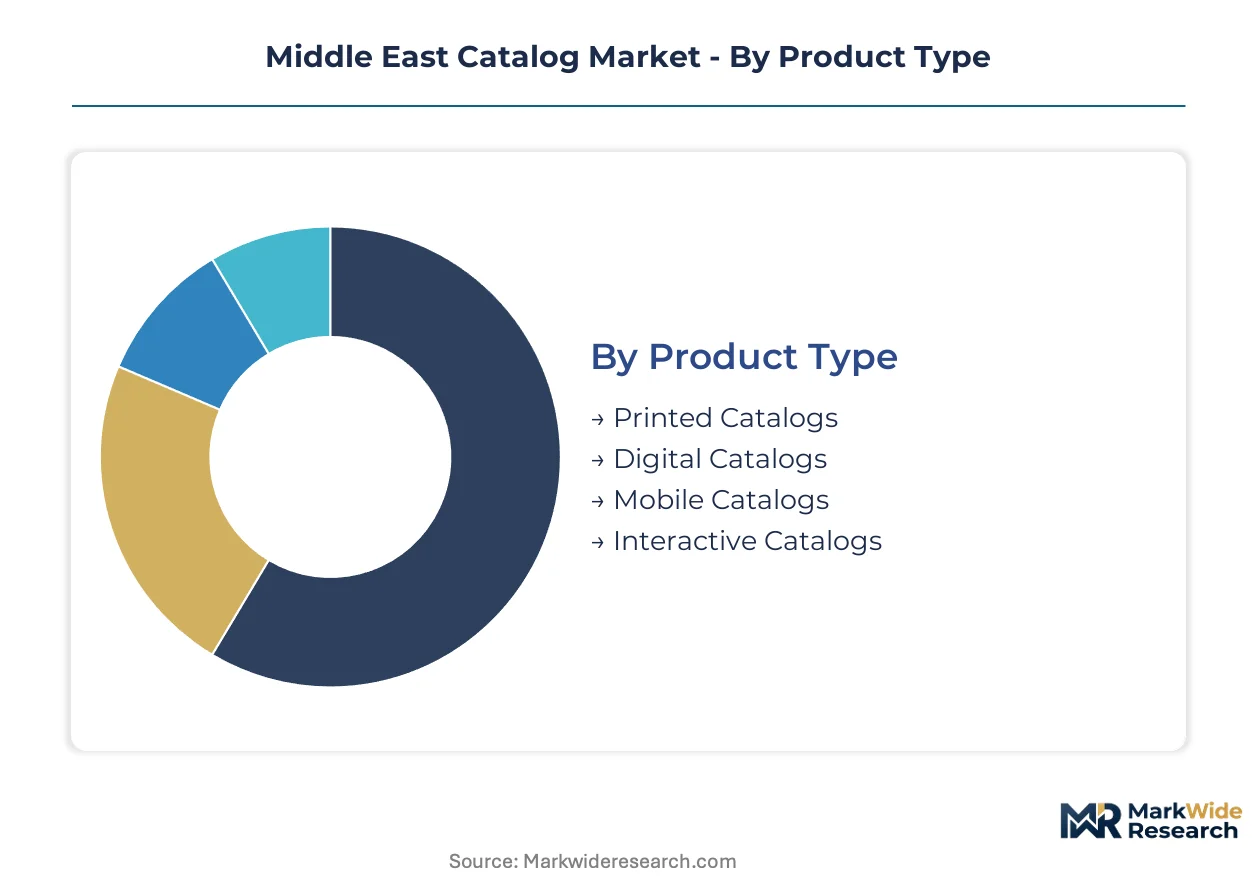
Catalog platform operators across the Middle East must align infrastructure investments with divergent consumption patterns. Product refresh cycles, procurement authority structures, and channel loyalty vary dramatically across segment boundaries, forcing modular platform architecture rather than uniform deployment.
Product Type:
Digital formats turn inventory fastest, while print retains extended replacement cycles in relationship-heavy B2B contexts.
- Printed Catalogs:Heavy-stock production with tactile finishing dominates Saudi construction and oilfield procurement committees where physical presentation signals vendor credibility. Riyadh industrial zones sustain demand despite digital pressure, though run lengths compress with each contract renewal.
- Digital Catalogs:Web-rendered databases with real-time inventory APIs constitute the revenue foundation for UAE fashion and electronics retailers. Dubai's logistics clustering enables same-day fulfillment promises that static print cannot match.
- Mobile Catalogs:Smartphone-optimized interfaces with progressive web app architecture capture Gulf youth demographics where fixed broadband penetration lags smartphone ownership.
- Interactive Catalogs:AR-embedded visualization tools reduce return rates in furniture and automotive parts verticals, though implementation costs limit adoption to premium-tier merchants.
Digital catalogs dominate installed base. Interactive formats are where expansion concentrates.
Industry Vertical:
Customer acquisition costs stratify sharply, with fashion merchants cycling campaigns quarterly while real estate catalogs persist across multi-year development cycles.
- Retail:SKU-intensive databases with dynamic pricing engines serve hypermarket and specialty store operators across GCC markets. UAE mall operators deploy hybrid digital-physical catalog experiences to convert foot traffic into registered platform users.
- Automotive:Parts compatibility matrices with VIN-level lookup functionality address Saudi Arabia's aftermarket service demand, particularly in Riyadh and Jeddah independent repair networks.
- Real Estate:High-production-value print and digital hybrids target institutional investors and high-net-worth individuals in Dubai's luxury development sector, with tactile presentation retaining influence in final selection committees.
- Fashion:Rapid inventory turnover with trend-responsive photography workflows defines this vertical, where UAE-based retailers adopt headless commerce architecture to deploy simultaneously across mobile apps and social commerce channels.
Retail commands transaction volume. Fashion is climbing the fastest.
Distribution Channel:
Fulfillment integration depth determines channel economics, with mobile apps capturing highest engagement frequency and direct mail retaining cost advantages in rural addressable markets.
- Online:Browser-based catalog access with guest checkout and account-persistent wishlists serves price-comparison shoppers across Saudi Arabia and UAE urban centers.
- In-Store:QR-activated digital catalogs with click-and-collect integration bridge physical browsing and inventory availability, particularly effective in Dubai mall environments.
- Direct Mail:Postal distribution to residential and commercial addresses persists in Egyptian and Saudi markets with lower smartphone penetration, though address database quality constrains targeting precision.
- Mobile Apps:Native application distribution with push notification personalization achieves highest session frequency among Qatari and Emirati consumers, where smartphone-first behavior dominates.
Online channels anchor revenue. Mobile apps are gaining share fastest.
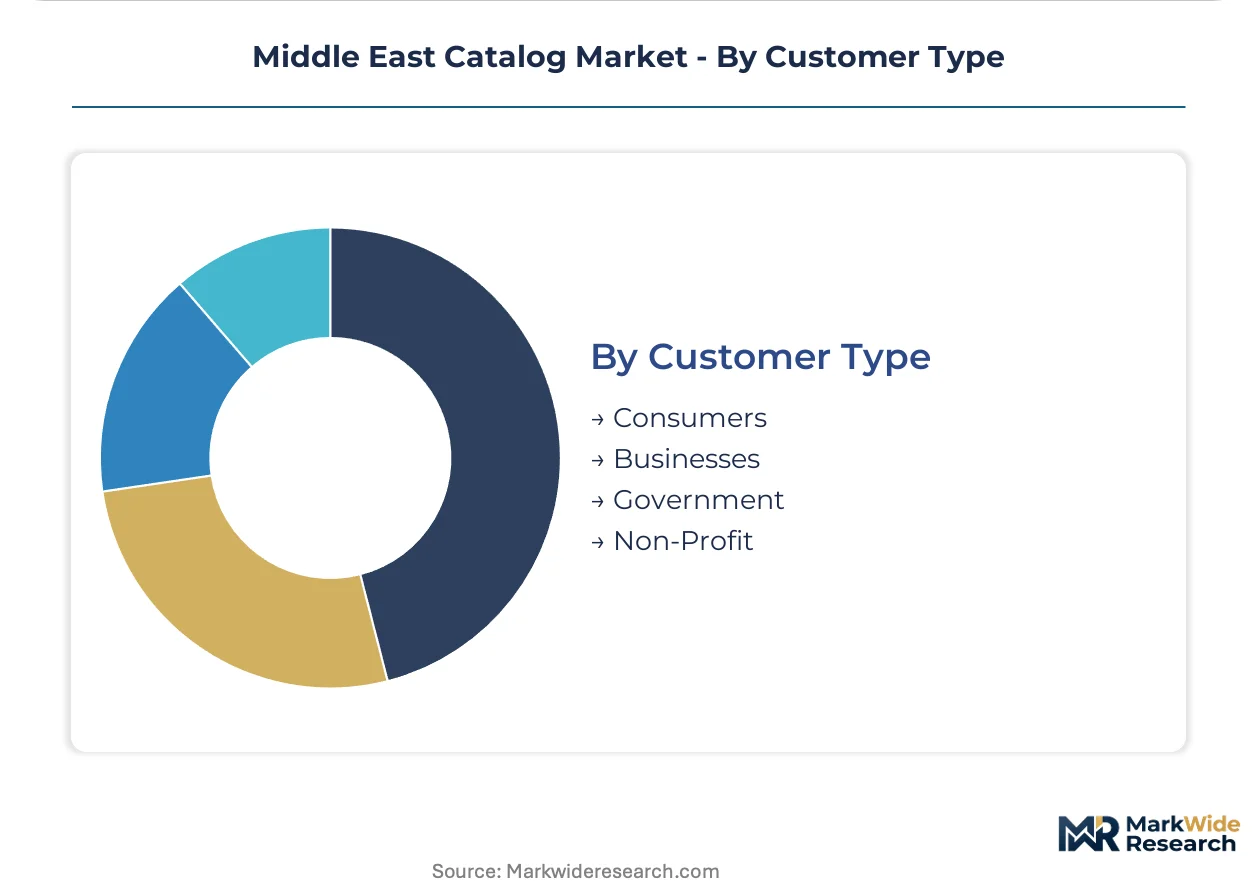
Customer Type:
Procurement cycle length and decision authority structure differentiate segment economics, with government tenders extending across fiscal years while consumer purchases compress to impulse timeframes.
- Consumers:Individual purchasers with mobile-dominant access patterns drive volume in UAE and Qatar markets, where smartphone catalog consumption exceeds fixed-line alternatives.
- Businesses:Corporate procurement committees in Saudi construction and oilfield services now mandate standalone platform access with transparent pricing, displacing traditional distributor-captive relationships.
- Government:Formal tender processes with disclosure and audit requirements shape catalog platform compliance investments, particularly under Saudi and Egyptian e-commerce regulatory frameworks.
- Non-Profit:Donor-funded procurement with restricted budget cycles and transparency mandates operates at smaller scale, concentrated in UAE and Saudi humanitarian organization headquarters.
Business customers dominate contract value. Consumer segments are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Catalog consumption patterns diverge sharply across the Middle East, with Gulf markets prioritizing mobile-first digital interfaces while Egyptian and Saudi B2B procurement committees retain tactile print formats for high-value industrial transactions.
Saudi Arabia
SFDA e-commerce disclosure mandates and data localization requirements are forcing catalog operators to deploy in-country cloud infrastructure, elevating compliance costs for cross-border platforms. Riyadh's industrial zones sustain demand for heavy-stock printed catalogs in construction and oilfield services procurement. Jeddah's logistics corridors enable same-day fulfillment for digital catalog operators serving western region consumers.
United Arab Emirates
Dubai's mall operators convert physical foot traffic into registered catalog users through QR-activated digital interfaces and click-and-collect integration. MOHAP's data protection framework mandates explicit consent mechanisms for customer data processing, with particular scrutiny on cross-border transfers. Jebel Ali's free zone infrastructure anchors GCC-wide fulfillment networks for SKU-intensive retail catalogs.
Egypt
Cairo's evolving consumer protection standards create compliance runway for catalog platforms that preemptively implement disclosure infrastructure. Lower smartphone penetration in rural Delta regions sustains direct mail distribution for price-sensitive consumer segments. Alexandria's port logistics support cross-border catalog fulfillment for European-origin goods.
Qatar
Smartphone-first catalog consumption dominates among younger demographics, with mobile app distribution capturing highest session frequency. The country's national data protection authority imposes consent requirements similar to GCC counterparts. Doha's retail clustering supports hybrid digital-physical catalog experiences in luxury and fashion verticals.
Middle East Catalog Market Competitive Landscape
Capability concentration sits with regional specialists possessing fulfillment infrastructure and regulatory expertise; scale advantage sits with global platforms leveraging technology investment and brand recognition. The vendor base stratifies across three tiers: Gulf-based retail conglomerates with mall-to-digital hybrid capabilities, international marketplace operators with Prime-integrated logistics, and pure-play fashion specialists with rapid inventory turnover workflows. Dominant competitive moves include strategic partnerships with last-mile delivery networks and portfolio diversification into financial services attached to catalog platforms.
Among UAE-based retail conglomerates, Majid Al Futtaim and LuLu Group International occupy positions bridging physical mall traffic with digital catalog registration, while noon exemplifies the regional marketplace archetype with captive fulfillment infrastructure spanning Saudi Arabia and Egypt. Amazon.ae represents the global platform model with logistics-integrated subscription services.
| Leading Market Players |
|---|
| noon |
| Amazon.ae |
| Souq |
| Namshi General Trading LLC |
| Majid Al Futtaim |
| LuLu Group International |
| Carrefour |
| Trendyol |
| Jumia Technologies AG |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Dubai's Jebel Ali free zone fulfillment infrastructure is compressing logistics margins and forcing catalog operators to absorb delivery subsidies while competing on platform fees. This utilization dynamic simultaneously elevates working capital requirements for inventory-heavy retailers and creates pricing power asymmetries between captive fulfillment networks and third-party-dependent entrants.
Pricing Analysis
Long-term offtake contracts anchor B2B industrial catalog procurement in Saudi Arabia's construction and oilfield services sectors, while spot transactional pricing dominates UAE consumer retail platforms. Three-tier pricing structure across premium, standard, and economy levels reflects fulfillment speed guarantees and after-sales service bundling. Cost compression in standard-tier digital catalogs is intensifying because noon and Amazon.ae subsidize same-day delivery to capture wallet share. SME procurement committees exhibit highest price sensitivity, whereas luxury real estate investors prioritize presentation quality over unit economics.
Supply Chain Analysis
Export-control regimes on AR visualization engines and real-time inventory API middleware constrain technology flows into Saudi Arabia's data-localized infrastructure requirements. Manufacturing concentration centers on China for consumer electronics catalog SKUs, India for textile and fashion inventory, and Germany for precision automotive parts databases. Raw material dependencies span high-grade paper stock for Saudi B2B print catalogs, cloud compute capacity for UAE digital platforms, and last-mile delivery fleet assets for Egyptian fulfillment expansion. Single-source vulnerability concentrates in Dubai's Jebel Ali logistics clustering, where distribution runs through consolidated free-zone operators serving GCC-wide catalog fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA's e-commerce disclosure mandates are accelerating formalization of previously informal marketplace transactions, creating structural disruption for catalog operators that must rebuild compliance infrastructure from scratch.
For Market Incumbents: Pre-empt regulatory fragmentation by deploying country-specific cloud instances ahead of formal Saudi data localization enforcement. Consolidate mall-to-digital hybrid capabilities through QR-activated catalog registration systems that convert Majid Al Futtaim's physical foot traffic into captive platform users. Vertical integration into last-mile delivery networks defends margin position against noon's captive fulfillment cost advantages.
For New Entrants and Emerging Players: Pursue Egypt's consumer protection alignment runway by preemptively implementing disclosure and dispute-resolution infrastructure ahead of formal Cairo enforcement. Target Saudi Arabia's western region around Jeddah, where logistics corridors enable same-day fulfillment with lower incumbent saturation than Riyadh. Lead with AR-integrated furniture visualization to differentiate from commodity catalog platforms.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across interactive catalog formats requiring AR engine licensing and real-time inventory API development. Long-term viability favors operators with captive fulfillment infrastructure spanning multiple GCC markets rather than pure-play technology vendors. Watch smartphone-first consumption penetration in Qatar and UAE youth demographics as the signal indicating when mobile-optimized catalog platforms will displace browser-based alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Data Localization Infrastructure Deployment | SFDA mandates force in-country cloud investment, elevating compliance costs for cross-border operators. |
| Mall-to-Digital Hybrid Activation | QR-triggered catalog registration converts Dubai mall foot traffic into registered platform users. |
| AR Visualization Engine Integration | Furniture and automotive parts verticals deploy immersive tools to compress purchase decision cycles. |
| Last-Mile Delivery Network Expansion | noon's captive fulfillment across Saudi Arabia and Egypt sustains same-day delivery cost advantages. |
| Multilingual Content Operations Investment | Parallel Arabic-English metadata workflows slow SKU onboarding but enable regulatory compliance across GCC markets. |
Research Methodology
Desk research of customs and trade flow databases, SEC filings from marketplace operators, and SFDA regulatory disclosure frameworks preceded structured interviews with catalog platform CTOs, UAE mall operations directors, Saudi procurement committee leads, Egyptian logistics coordinators, and GCC regulatory compliance officers. Primary fieldwork combined with secondary validation across Jebel Ali free-zone operator reports, MOHAP data protection guidance documents, and smartphone penetration statistics from national telecommunications authorities. Bottom-up SKU velocity modeling triangulated against top-down retail e-commerce spend estimates.
Assumptions held fixed include SFDA enforcement timelines, MOHAP consent mechanism requirements, and GCC VAT harmonization progress, while smartphone penetration trajectories and cloud capacity buildout rates were varied across sensitivity scenarios. Segmentation modeling spanned product format, industry vertical, distribution channel, and customer type dimensions, with additional granularity on data localization compliance status. CAGRs derived from logistic diffusion curves fitted to historical platform adoption patterns, incorporating fulfillment infrastructure investment cycles and regulatory implementation lags as industry-specific forecast inputs.
Sensitivities concentrate around Saudi data center capacity buildout delays, Egyptian consumer protection enforcement acceleration, and GCC-wide VAT rate convergence timing. Forecasts reflect assumptions on regulatory implementation schedules and technology adoption curves without claiming predictive certainty. Material shifts in SFDA disclosure mandate scope or UAE data protection cross-border transfer restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Publishing
Digital Reading Market
Digital Publishing
Europe E-Book Market
Digital Publishing
Japan Catalog Market
Digital Publishing
News and Magazines App Market
Digital Publishing
US Newspaper Market
Digital Publishing
Digital Music Publishing Market
Digital Publishing
Digital Newspapers and Magazines Market
Digital Publishing
GCC Commercial Printing Market
Digital Publishing
China Catalog Market
Digital Publishing
Digital Comics Distribution and Consumption Platforms Market
Digital Publishing
Ebook Publishing Platform Market
Digital Publishing
Adaptive Content Publishing Market
Digital Publishing
Comic Book Market
Digital Publishing
Editor App Market
Digital Publishing
Digital Comics Platform Market
Digital Publishing
Newspaper Market