
 Children Illustration Book Market | 2026-2036
Children Illustration Book Market Size, Share, and Industry Trends Forecast 2026-2036
Children Illustration Book Market Insights
Soy-based ink is pivoting away from petroleum-derived alternatives across major printing contracts, cutting unit costs for long-run color titles while meeting tightened chemical-safety thresholds for juvenile products. Scholastic leverages its captive school distribution network to lock in institutional purchase commitments. HarperCollins anchors premium hardcover releases through illustrated classics repositioning. Penguin Random House dominates digital-first illustration pipelines, compressing concept-to-shelf timelines.
Children illustration books are bound publications where narrative text integrates with visual artwork—typically produced via offset lithography or digital inkjet on coated paper stocks between 80–150 gsm—to foster literacy, emotional development, and visual literacy in readers from birth through twelve years. Picture books command the highest absolute dollar volume within the Book Type dimension, though Educational Books carry superior margin stability through recurring school-district adoption cycles. Distribution Channel dynamics bifurcate sharply: Online Retail captures impulse and gift purchases with algorithmic discovery, while Educational Institutions provide multi-year procurement visibility that insulates publishers from consumer cyclicality.
FDA guidelines on toy and juvenile product safety, including lead-content thresholds in substrate materials, directly constrain paper and binding supplier qualification for US-market titles. REACH chemical restrictions in Europe and the EU Green Deal packaging-waste directives are pushing publishers toward FSC-certified paper sourcing and reduced plastic lamination. Stakeholders must monitor how carbon-border adjustments and evolving digital-sales tax regimes reshape the cost structure of cross-border illustrated title distribution.
Market Dynamics
Digital illustration workflows and print-on-demand technologies are compressing production cycles from concept to shelf, while REACH chemical restrictions and FDA substrate-safety thresholds reshape supplier qualification criteria across major publishing contracts.
Growth Catalysts
- Elementary curriculum adoption:North American and European school districts are expanding illustrated title procurement for early literacy programs, creating multi-year visibility for educational publishers.
- Soy-based ink substitution:Petroleum-derived alternatives face displacement across long-run color contracts, cutting unit production costs while meeting tightened juvenile-product chemical-safety thresholds.
- Library procurement budgets:United States, United Kingdom, and German public library systems sustain elevated per-title spending through direct-to-consumer subscription model adjacencies.
Market Restraints
- FSC-certified paper cost premium:EU Green Deal packaging-waste directives and carbon-border adjustment mechanisms inflate substrate sourcing expenses for cross-border distribution.
- Binding supplier concentration:Lead-content qualification requirements under FDA juvenile-product guidelines limit viable US-market substrate vendors to a narrow qualified pool.
- Digital piracy substitution:Unlicensed scan distribution erodes hardcover revenue for premium illustrated classics repositioning efforts.
Strategic Opportunities
- German direct-to-consumer channels:Algorithmic discovery platforms capture gift and impulse purchase occasions underserved by traditional retail distribution.
- Digital-first illustration pipelines:Convergence of cloud-based asset management and AI-assisted layout tools enables compressed concept-to-shelf timelines for mid-list titles.
- UK educational institution procurement:Multi-year adoption cycles for picture books in primary curricula provide margin stability insulated from consumer cyclicality.
Industry Challenges
- Illustrator talent pipeline constraints:Specialized visual narrative skills for juvenile literacy development face scarcity against technology-sector compensation competition.
- Dual certification timelines:Parallel FDA substrate review and ECHA REACH compliance processes extend pre-production qualification periods for transatlantic releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Children Illustration Book Market |
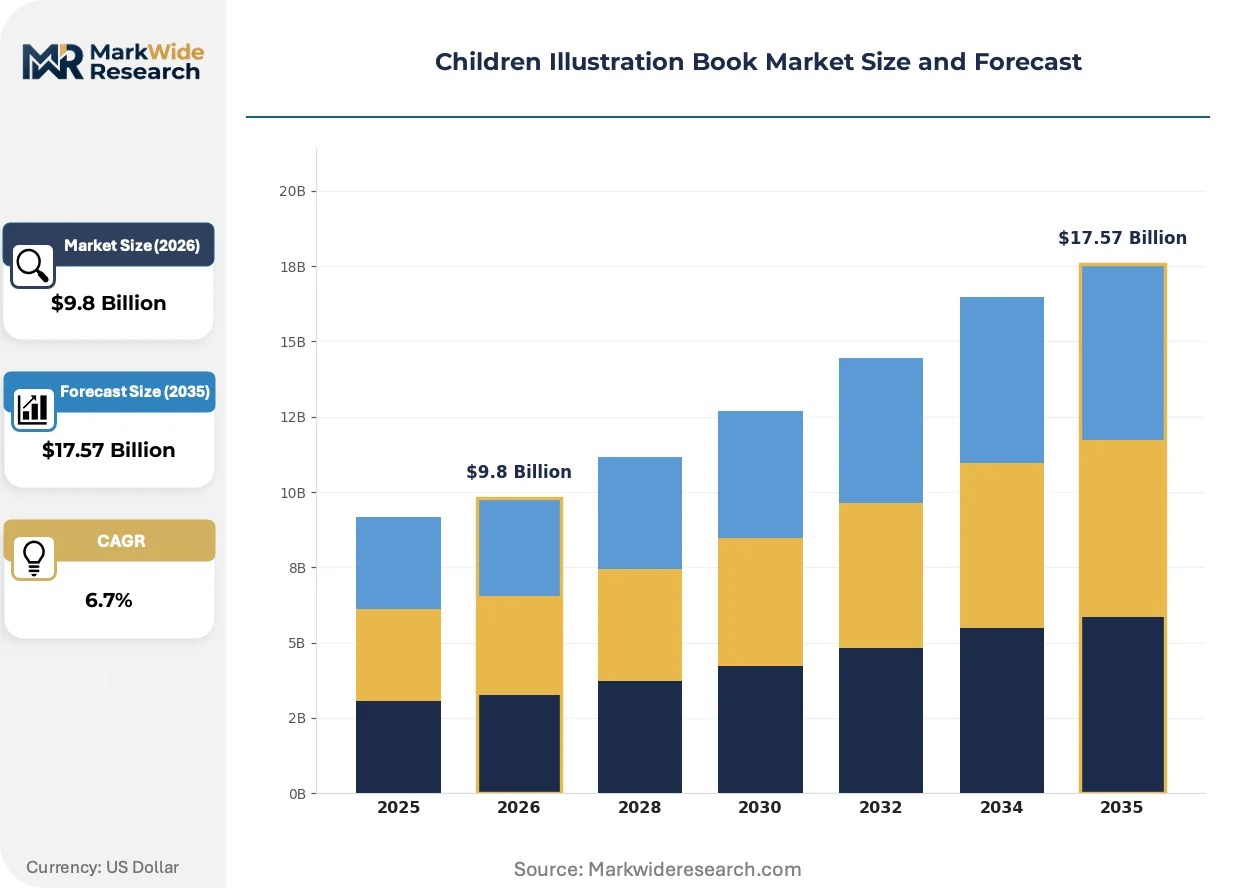
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Book Type: Picture Books, Activity Books, Educational Books, Storybooks Target Age Group: Toddlers, Preschoolers, Early Readers, Middle Grade Illustration Style: Digital Art, Watercolor, Collage, Cartoon Distribution Channel: Online Retail, Bookstores, Libraries, Educational Institutions |
| Companies Covered | Penguin Random House, Scholastic, HarperCollins, Hachette Livre, Simon & Schuster, Disney Publishing Worldwide, Houghton Mifflin Harcourt, Walker Books, Chronicle Books, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Children Illustration Book Market Trends and Innovations
Workflow digitization and regulatory chemistry constraints are simultaneously compressing production timelines and reshaping material specifications across the value chain.
AI-assisted layout and color-separation tools are automating pre-press preparation for offset lithography and digital inkjet workflows. Mid-tier publishers with limited in-house art departments adopt these platforms fastest, compressing concept-to-proof cycles from weeks to days. This compression is automating the traditional bottleneck between illustration finalization and print-ready file generation.
REACH chemical restrictions in Europe now mandate reduced plastic lamination and FSC-certified paper sourcing for juvenile-market titles. The industrial consequence is supplier base consolidation toward vertically integrated paper mills with chain-of-custody certification. Picture book hardcover releases face the steepest cost adjustments, with German and UK publishers accelerating alternative substrate qualification.
Library systems in the United States and United Kingdom are unbundling acquisition from physical processing, contracting directly with publishers for digital-asset licenses while outsourcing binding and cataloging to regional service bureaus. This disintermediates traditional wholesale distributors. The shift is most visible in metropolitan systems with centralized procurement authority and established digital-asset management infrastructure.
Children Illustration Book Market Segmentation
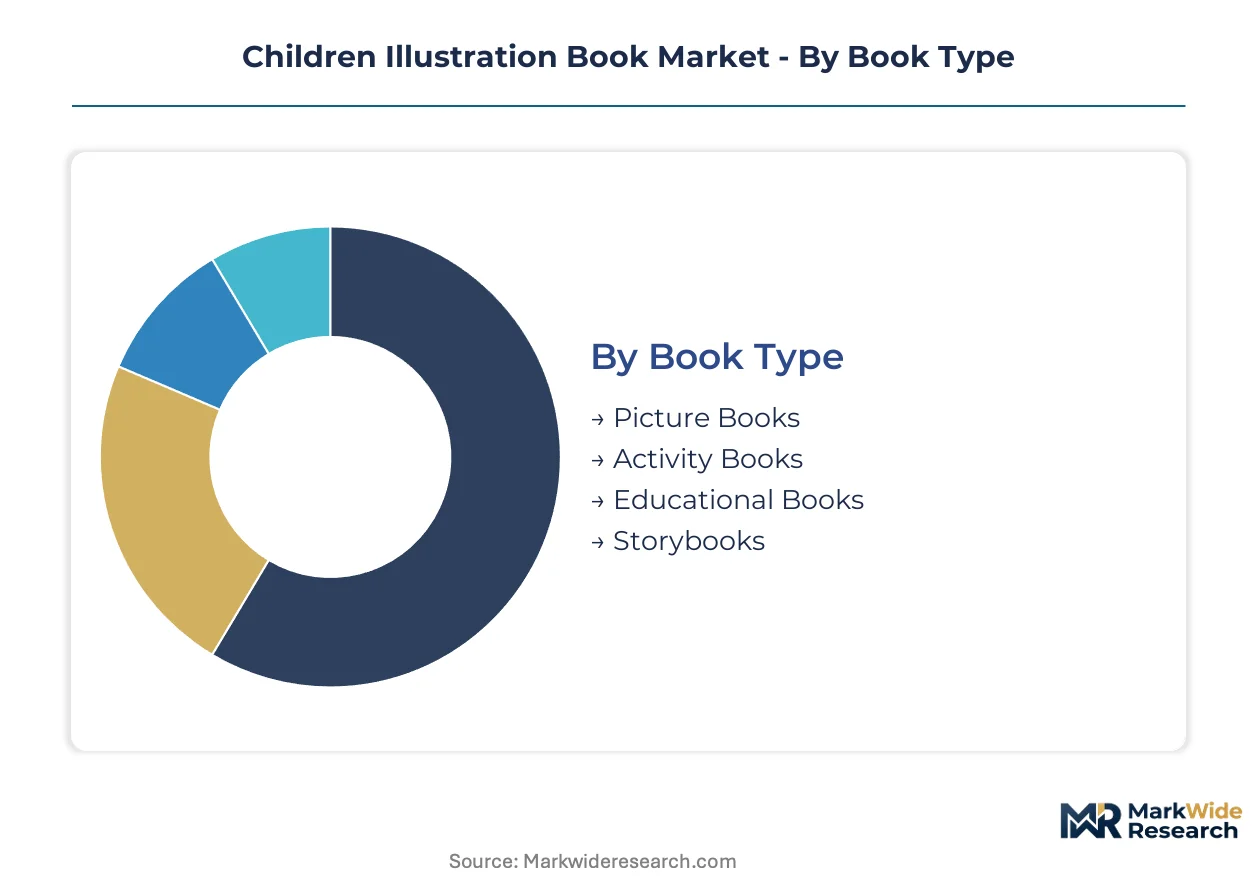
Segmentation in children's illustration books reveals how capital deployment, creative labor intensity, and procurement channel dynamics split value capture across the supply chain. Publishers calibrate format, aesthetic, and access strategy to match the diverging economics of institutional buyers versus gift purchasers.
Book Type:
Capital intensity varies sharply by format, with full-bleed color reproduction and binding durability requirements driving upfront investment thresholds.
- Picture Books:Full-spread illustrated narratives on coated paper stocks demand the highest pre-press investment per title. United States library systems sustain elevated per-title procurement for hardcover releases, though FSC-certified substrate premiums compress margins on long-run contracts.
- Educational Books:Curriculum-aligned titles with integrated visual literacy components require specialized pedagogical review cycles. North American school districts provide multi-year adoption visibility that insulates publishers from consumer cyclicality.
- Activity Books:Workbook formats with reproducible content pages carry lower illustration origination costs per unit. German direct-to-consumer channels capture impulse purchase occasions through algorithmic discovery platforms.
- Storybooks:Text-dominant formats with spot illustration reduce color-separation pre-press requirements. UK educational institution procurement concentrates on leveled reading series for primary curricula.
Most installed capacity flows through Picture Books. Expansion is steepest in Educational Books.
Target Age Group:
Developmental stage determines illustration complexity, substrate safety certification, and the balance between direct-to-consumer and institutional channel mix.
- Toddlers:Board book formats with rounded corners and tear-resistant substrates face the strictest FDA lead-content thresholds. Binding supplier concentration in the United States limits viable vendor pools for transatlantic releases.
- Preschoolers:Picture-heavy narratives with simple sentence structures dominate library acquisition budgets. Metropolitan systems in the United Kingdom unbundle digital-asset licensing from physical processing through regional service bureaus.
- Early Readers:Leveled text with supporting visual cues requires alignment with district literacy standards. Soy-based ink substitution cuts unit production costs for high-volume curriculum adoptions.
- Middle Grade:Chapter-book formats with intermittent spot illustration shift toward online retail discovery. Algorithmic recommendation engines capture gift purchase occasions underserved by traditional bookstore placement.
Toddler formats absorb the highest per-unit compliance costs. Middle Grade titles are gaining share fastest through digital-first distribution.
Illustration Style:
Production workflow digitization and artisan labor scarcity reshape cost structures and timeline compression potential across aesthetic categories.
- Digital Art:Cloud-based asset management and AI-assisted color separation compress concept-to-proof cycles from weeks to days. Mid-tier publishers with limited in-house art departments adopt these platforms fastest.
- Watercolor:Traditional hand-painted originals require specialized scanning protocols and color-matching expertise for lithographic reproduction. Illustrator talent pipeline constraints intensify against technology-sector compensation competition.
- Collage:Mixed-media compositions with layered physical materials demand extended pre-press preparation for texture fidelity. EU Green Deal packaging-waste directives push publishers toward reduced plastic lamination alternatives.
- Cartoon:Vector-based linework enables rapid iteration and regional localization for licensed character properties. German publishers leverage direct-to-consumer subscription models for serialized release structures.
Digital Art commands the dominant share of new title origination. Watercolor maintains premium positioning in gift and collector segments.
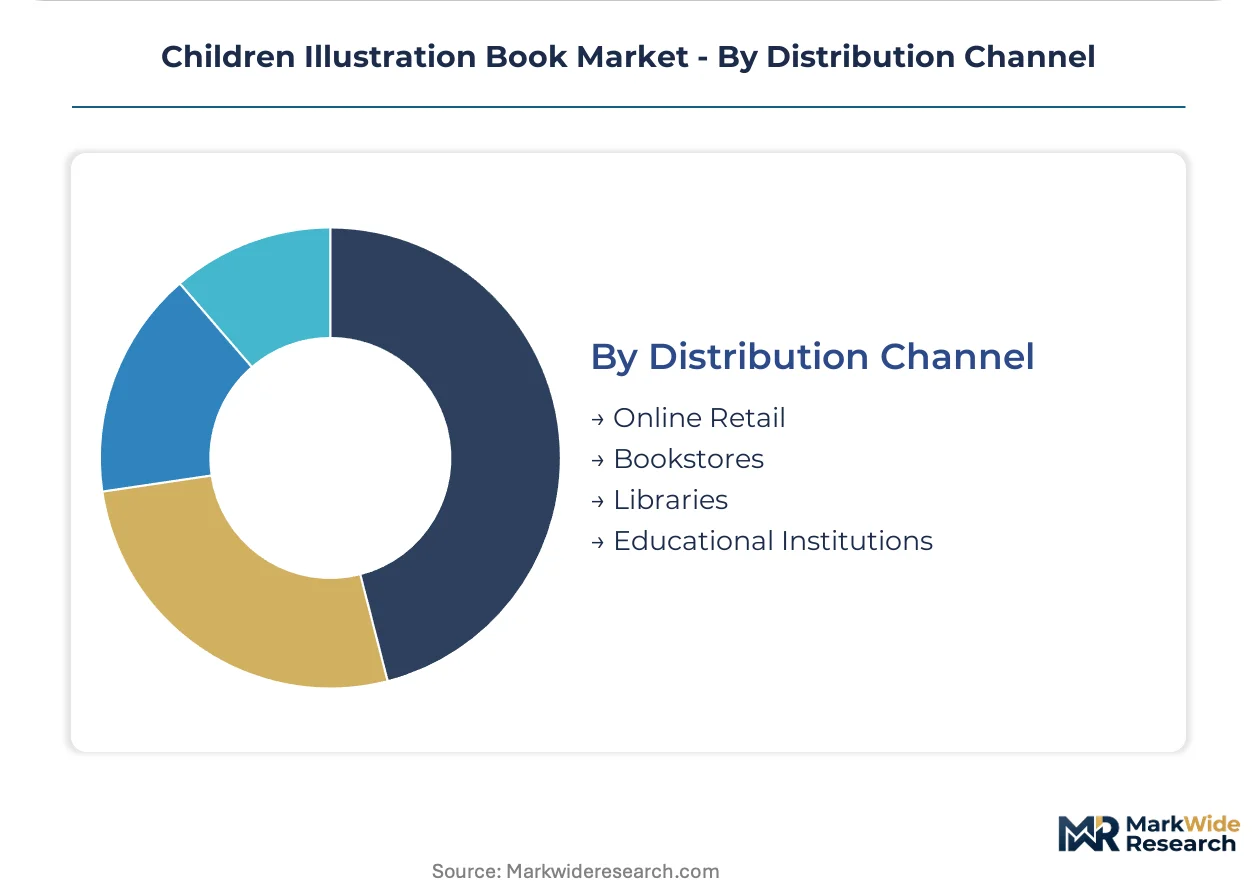
Distribution Channel:
Channel selection determines working capital requirements, return-rate exposure, and the feasibility of print-on-demand versus offset lithography production commitments.
- Online Retail:Algorithmic discovery platforms capture impulse and gift purchases with minimal inventory carry. United States consumers drive highest absolute dollar volume through direct-to-consumer subscription adjacencies.
- Bookstores:Physical browse environments favor premium hardcover releases with tactile production values. Co-op placement fees and return privileges strain working capital for mid-list publishers.
- Libraries:Centralized procurement authority in metropolitan systems enables multi-copy acquisition with extended circulation durability requirements. United Kingdom systems accelerate digital-asset licensing unbundling from physical processing.
- Educational Institutions:Multi-year adoption cycles for curriculum-aligned titles provide revenue visibility that offsets longer sales cycles. North American school districts expand illustrated title procurement for early literacy programs.
Educational Institutions anchor the most stable revenue base. Online Retail is climbing the fastest as algorithmic discovery displaces traditional browse behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's publishing corridor concentrates editorial talent and rights-trading infrastructure for illustrated juvenile titles. School district procurement in North America and Western Europe anchors institutional demand clusters. Regulatory divergence between FDA substrate rules and REACH chemical mandates shapes transatlantic distribution economics.
United States
Metropolitan library systems in New York and Chicago sustain elevated per-title acquisition budgets for hardcover picture books. FDA lead-content thresholds for juvenile products constrain binding supplier pools to qualified vendors meeting substrate safety protocols. California school districts expand illustrated title procurement for early literacy curriculum adoption.
Germany
Direct-to-consumer subscription models in Berlin and Munich capture gift purchase occasions through algorithmic discovery platforms. EU Green Deal packaging-waste directives accelerate FSC-certified paper sourcing requirements for domestic publishers. Bavarian printing clusters specialize in soy-based ink long-run contracts for educational book releases.
United Kingdom
Primary school curriculum alignment drives multi-year adoption cycles for leveled reading series in London and Birmingham. REACH chemical restrictions mandate reduced plastic lamination in juvenile-market hardcover production. Scottish library systems unbundle digital-asset licensing from physical processing through regional service bureaus.
Japan
Kanto region publishers leverage cloud-based asset management for compressed concept-to-shelf timelines in Tokyo and Yokohama. METI standards for juvenile product safety influence substrate qualification protocols for export-market titles. Osaka-based distributors specialize in character-licensed cartoon illustration formats for serialized release structures.
France
Parisian editorial houses anchor premium hardcover positioning for illustrated classics repositioning efforts. ECHA compliance timelines extend pre-production qualification for transatlantic co-editions. Lyon printing clusters concentrate on watercolor reproduction expertise for gift-segment collector titles.
Children Illustration Book Market Competitive Landscape
Global majors compete with regional champions across distribution channel access and institutional procurement relationships. The vendor base stratifies into three tiers: multinational conglomerates with captive school networks, mid-tier specialists with digital-first pipelines, and boutique houses with artisan illustration positioning. Two dominant competitive moves define current dynamics: backward integration into print-on-demand capacity and exclusive licensing of character properties for recurring revenue streams.
Within the multinational conglomerate tier, Penguin Random House and Scholastic occupy positions defined by divergent channel strategies. Penguin Random House exemplifies digital-first illustration pipeline investment with compressed production timelines. Scholastic anchors institutional procurement through captive school distribution networks. HarperCollins sits within the premium hardcover repositioning archetype, emphasizing tactile production values for gift-market segments.
| Leading Market Players |
|---|
| Penguin Random House |
| Scholastic |
| HarperCollins |
| Hachette Livre |
| Simon & Schuster |
| Disney Publishing Worldwide |
| Houghton Mifflin Harcourt |
| Walker Books |
| Chronicle Books |
| Others |
Pricing and Supply Chain Analysis
Illustrator talent concentration in London, New York, and Tokyo generates labor-cost differentials that widen pricing-tier spreads between artisan watercolor originals and digitally assisted mid-list titles. Publishers in Germany and the United Kingdom absorb premium origination costs for hand-painted artwork while mid-tier houses in North America leverage AI-assisted pipelines to compress production expenses.
Pricing Analysis
Input-cost pass-through from FSC-certified paper premiums and soy-based ink contracts shapes publisher margin structures across format tiers. Three-tier pricing structure across premium hardcover, standard trade paperback, and economy mass-market levels separates gift-segment collectors from institutional bulk purchasers. Pricing pressure stems from EU carbon-border adjustments inflating cross-border substrate sourcing. Educational institutions exhibit lowest price sensitivity due to multi-year adoption cycle visibility, while direct-to-consumer gift buyers show highest elasticity to unit cost shifts.
Supply Chain Analysis
Workforce availability for specialized juvenile-market illustration skills concentrates in the United Kingdom, Germany, and Japan, with technology-sector compensation competition draining talent pools in metropolitan creative clusters. Raw material dependencies center on FSC-certified coated paper stocks, soy-based ink formulations, and lead-compliant board book substrates. Supply chain risk manifests in single-source vulnerability for FDA-qualified binding vendors serving US-market toddler formats. Distribution runs through hybrid structures combining publisher direct sales to educational institutions with algorithmic platforms for consumer discovery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-compliant European production with elevated substrate costs and North American digital-first pipelines with compressed illustration timelines.
For Market Incumbents: To counter digital piracy substitution eroding hardcover revenue, Scholastic and HarperCollins should deepen backward integration into print-on-demand capacity for mid-list titles while locking exclusive licensing of character properties for recurring royalty streams. Captive school distribution networks provide defensive moats against algorithmic discovery platforms. For New Entrants and Emerging Players: Capture algorithmic discovery white space in German direct-to-consumer subscription models where traditional retail distribution remains underserved. Mid-tier digital art pipelines offer lowest barrier-to-entry for picture book origination. Target UK educational institution procurement for leveled reading series with curriculum-alignment positioning. For Investors and Strategic Acquirers: Mid-tier publishers with AI-assisted illustration workflows are the most active acquirer targets in this space for conglomerates seeking compressed concept-to-shelf capabilities. Long-term viability hinges on regulatory chemistry compliance rather than format innovation. Watch for FDA substrate rule amendments as inflection signal for transatlantic distribution cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Digital-First Illustration Pipeline Investment | Cloud-based asset management and AI-assisted color separation compress proof cycles from weeks to days for mid-tier publishers. |
| FSC-Certified Paper Sourcing Transition | EU Green Deal packaging-waste directives and REACH chemical restrictions mandate reduced plastic lamination alternatives. |
| Direct-to-Consumer Subscription Launch | Algorithmic discovery platforms in Germany capture gift purchase occasions underserved by traditional bookstore placement. |
| Educational Institution Procurement Lock-In | Multi-year adoption cycles for North American school district early literacy programs provide revenue visibility. |
| Character Property Exclusive Licensing | Serialized release structures through subscription models generate recurring royalty streams insulated from single-title volatility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with publishing executives, art department directors, school district procurement officers, and library acquisition librarians alongside secondary validation through customs records, Nielsen BookScan retail audit data, and SEC 10-K filings from listed publishers. Bottom-up title origination counts and top-down market sizing triangulated volume estimates across the analysis window.
Comparable-period anchoring to historical curriculum adoption cycles and library budget appropriations informed the projection framework. Segmentation dimensions modeled include book type, target age group, illustration style, and distribution channel with regional regulatory cluster overlays. CAGRs derived from weighted average of trend extrapolation and driver elasticity analysis, with specific inputs from soy-based ink substitution rates and FSC-certified paper penetration curves.
Regulatory amendment timelines, illustrator labor pool migration, and digital piracy enforcement intensity are the dominant revision risks to forecast assumptions. Material deviation in named triggers warrants pause and re-evaluation of publisher margin and volume trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Publishing
Online Comic Market
Digital Publishing
Digital Publishing Platforms Market
Digital Publishing
Europe E-Book Market
Digital Publishing
Comic Book Market
Digital Publishing
Digital Music Publishing Market
Digital Publishing
Global E-Book Market
Digital Publishing
Digital Reading Market
Digital Publishing
GCC Commercial Printing Market
Digital Publishing
Africa Catalog Market
Digital Publishing
Japan Catalog Market
Digital Publishing
Digital Newspapers and Magazines Market
Digital Publishing
Middle East Catalog Market
Digital Publishing
US Newspaper Market
Digital Publishing
Digital Comics Market
Digital Publishing
France Catalog Market
Digital Publishing
Digital Comics Distribution and Consumption Platforms Market