
 Dog Water Bottle Market | 2026-2036
Dog Water Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Water Bottle Market Analytics
Millennial and Gen Z pet owners is rotating demand toward premium portable hydration products that integrate with active lifestyles. PETKIT leverages app-connected inventory management to sustain channel control across direct-to-consumer platforms. Springer Pets anchors its position through veterinary-grade material certification and specialty retail partnerships. MalsiPree competes on collapsible design patents that reduce storage footprint for urban apartment dwellers.
A dog water bottle is a portable, sealed vessel engineered to dispense controlled water flow to canines during transit, exercise, or travel, typically incorporating one-way valves, silicone seals, and integrated drinking troughs to prevent spillage and contamination. Stainless steel variants dominate the material segment due to thermal retention properties and dishwasher-safe compliance, while BPA-free plastic occupies volume leadership through lower unit economics and color customization options. Nozzle bottles lead the product type hierarchy for leash-clip portability, whereas gravity bottles capture extended-trip use cases with larger reservoir capacity.
FDA Center for Veterinary Medicine oversight on pet product material safety, combined with state-level California Proposition 65 enforcement on chemical disclosures, elevates compliance costs for cross-border suppliers. The EU REACH framework restricts certain plasticizers in pet-contact articles, redirecting export-focused manufacturers toward silicon and glass alternatives. Stakeholders must monitor evolving biodegradable material certifications and retailer-specific sustainability scorecards that increasingly gate shelf access.
Market Dynamics
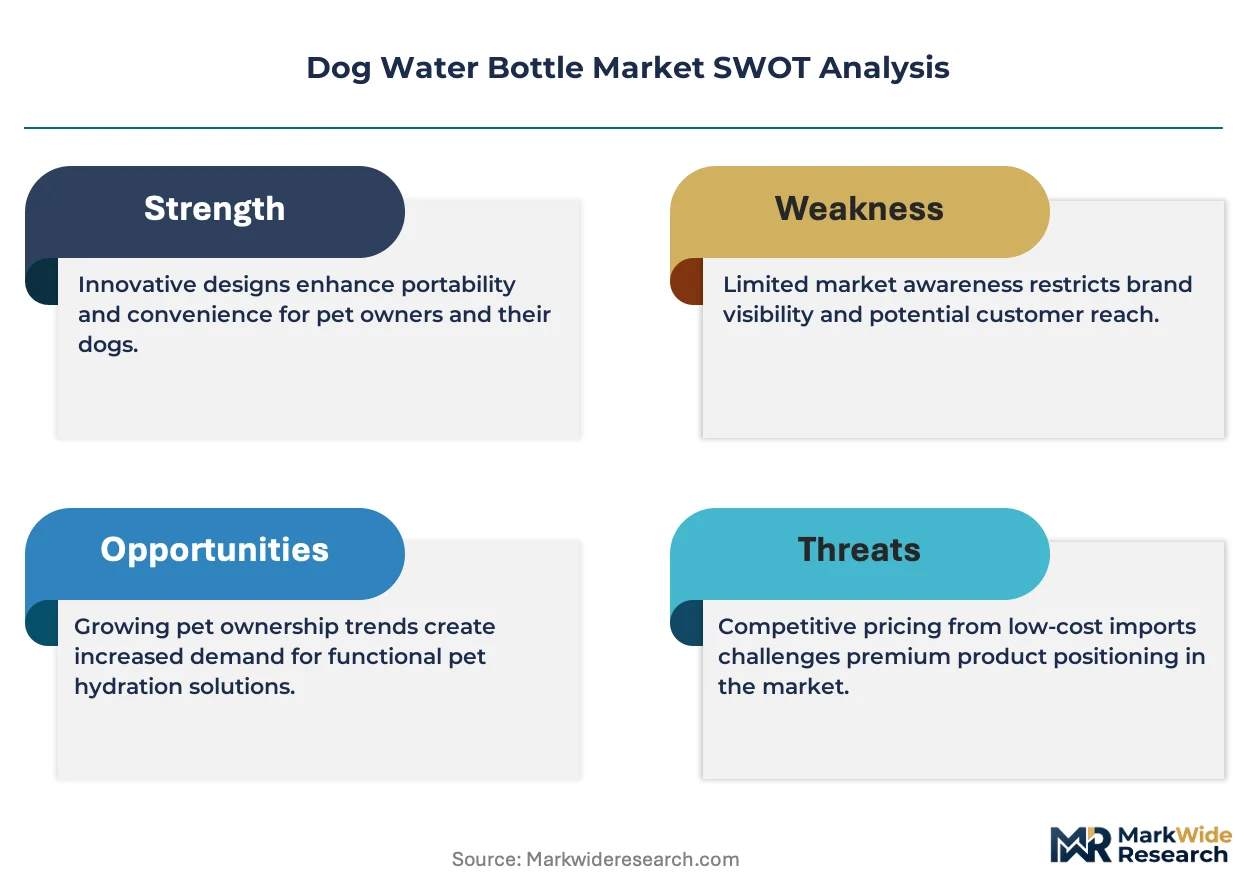
Pet humanization among millennial and Gen Z owners is compressing product lifecycles and forcing rapid design iteration across portable hydration solutions. Manufacturers now face simultaneous pressure from FDA material safety mandates and retailer sustainability scorecards that gate shelf access.
Growth Catalysts
- California Proposition 65 enforcement:Chemical disclosure mandates are accelerating BPA-free material transitions and creating first-mover advantages for compliant suppliers.
- Urban apartment dwelling:Space-constrained households in dense metropolitan areas are driving demand for collapsible and multi-functional bottle designs.
- Silicone valve technology:One-way dispensing mechanisms are eliminating spillage concerns and expanding use cases to vehicle interiors and public transit.
Market Restraints
- Stainless steel input volatility:Thermal-grade 304 and 316 alloys face price swings tied to nickel markets, compressing margin buffers for mid-tier producers.
- EU REACH plasticizer restrictions:Cross-border suppliers face reformulation costs or market exclusion when phthalate alternatives fail migration testing.
- Gravity bottle technical ceiling:Larger reservoir designs hit thermal retention limits and dishwasher compatibility trade-offs that cap premium pricing power.
Strategic Opportunities
- Biodegradable certification pathways:Emerging compostable material standards in California and the EU are opening shelf placement with specialty pet retailers.
- Veterinary clinic channel:Direct distribution through veterinary practices offers margin protection and clinical credibility transfer.
- App-integrated inventory tracking:Bluetooth-enabled hydration monitoring converges with pet wearable ecosystems to create recurring data revenue streams.
Industry Challenges
- FDA Center for Veterinary Medicine clearance timelines:Novel material submissions face 18-24 month review cycles that delay product launches.
- Multi-material bonding expertise:Seamless integration of silicone seals, stainless steel bodies, and plastic components requires specialized polymer engineering talent in short supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Water Bottle Market |
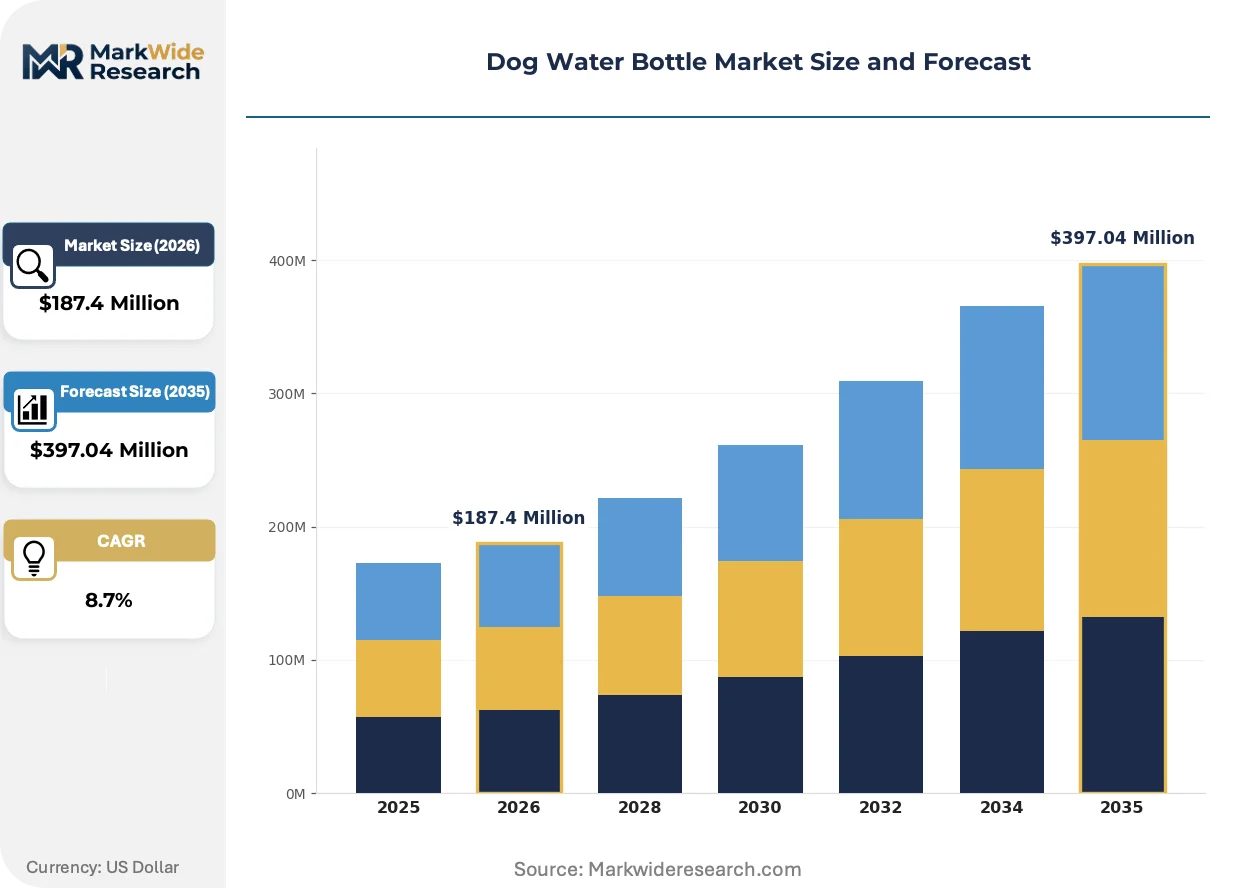
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foldable Bottle, Nozzle Bottle, Gravity Bottle, Travel Mug Material: Stainless Steel, BPA-Free Plastic, Silicon, Glass Size: 350ml, 500ml, 750ml, 1L Brand: KONG, PetFusion, Lixit, Avantree |
| Companies Covered | WePet, PETKIT, Springer Pets, AVELORA, Kalimdor, MalsiPree, OllyDog, Gardner Pet, PupFlask, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Water Bottle Market Evolving Landscape
Smart connectivity and sustainable material science are converging to redefine product value propositions. Competitive differentiation now hinges on data integration capabilities rather than purely physical design attributes.
Double-wall vacuum insulation is supplanting single-layer construction in premium segments. Active outdoor enthusiasts and frequent travelers are adopting thermal-retention bottles at accelerating rates. This shift is compressing demand for basic plastic variants and forcing volume manufacturers to defend position through color customization rather than performance claims.
EU REACH framework amendments on endocrine-disrupting chemicals are tightening migration limits for pet-contact articles. Manufacturers serving European export markets are redirecting R&D toward glass and medical-grade silicone alternatives. Specialty retailers in Germany and France are now requiring full material origin documentation as a listing prerequisite.
Subscription-based replenishment models are disrupting traditional retail replenishment cycles. Direct-to-consumer platforms are capturing recurring revenue through filter cartridge and replacement seal programs. Urban markets in the United States show highest conversion rates for bundled hydration and nutrition delivery services.
Dog Water Bottle Market Segmentation
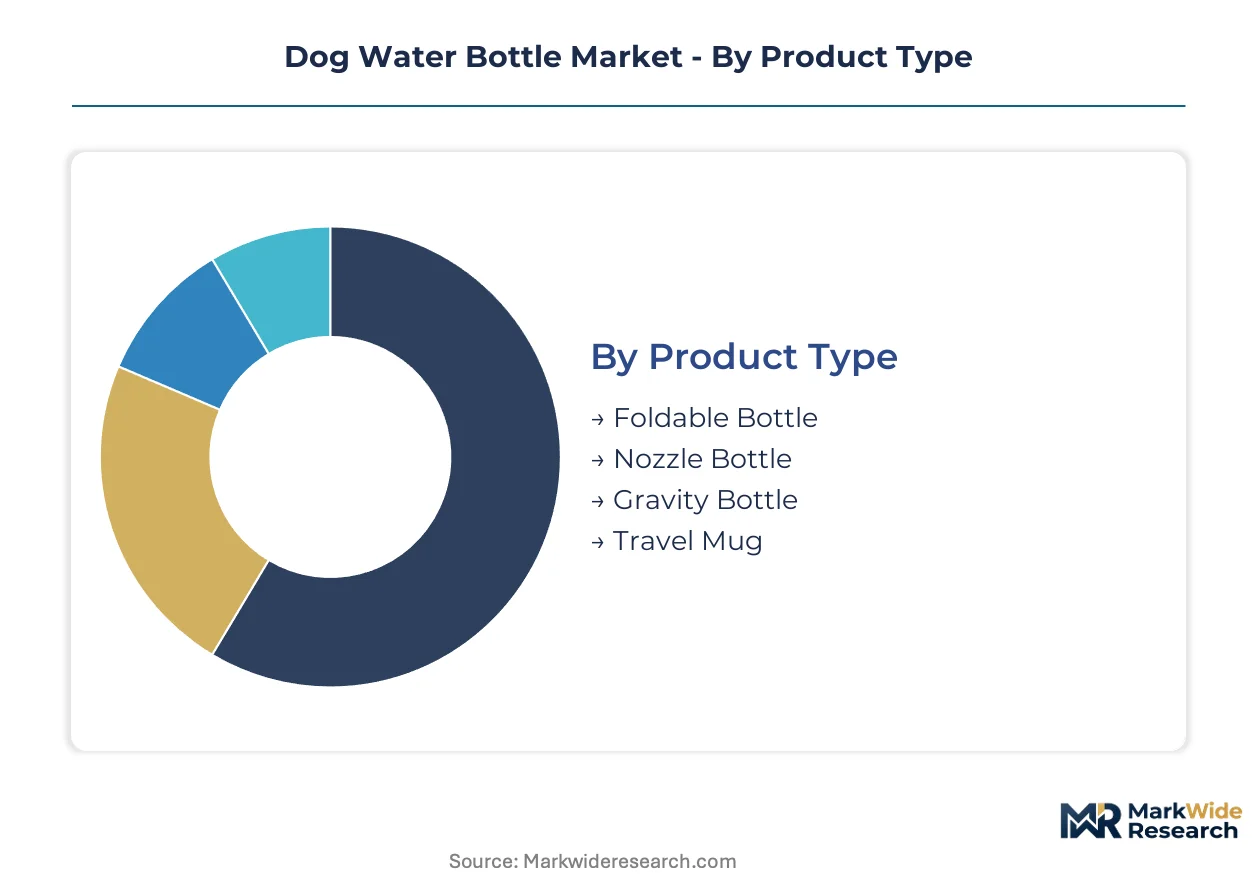
Segmentation in the dog water bottle market reveals how pet owner lifestyles fragment demand across portability, durability, and capacity requirements. Manufacturers must align production configurations with distinct use cases ranging from urban commuting to extended outdoor recreation.
Product Type:
Nozzle bottles face intensifying substitution pressure from collapsible alternatives in space-constrained urban environments, while gravity designs compete against portable filtration systems for multi-day trip applications.
- Nozzle Bottle:Features a one-way valve mechanism that releases water when the dog licks, preventing backflow contamination and spillage in vehicle interiors. Demand concentrates among daily commuters in dense metropolitan areas where leash-clip portability drives purchase decisions. FDA material compliance for valve components elevates production costs for cross-border suppliers.
- Gravity Bottle:Utilizes elevated reservoir positioning with continuous flow troughs suited for extended travel and camping scenarios. Adoption accelerates among outdoor recreation enthusiasts in the western United States where trail access and vehicle-based adventure culture predominate. Thermal retention limitations and dishwasher incompatibility constrain premium pricing flexibility.
- Foldable Bottle:Silicone or fabric-based collapsible designs compress to minimal storage footprint for apartment dwellers.
- Travel Mug:Dual-purpose vessels serving both human and canine hydration with integrated sharing mechanisms.
Nozzle bottles retain volume leadership; gravity bottles hold the steepest expansion curve.
Material:
Cost tier stratification separates medical-grade certified suppliers from commodity producers, with stainless steel commanding three-to-four times the unit economics of polymer alternatives.
- Stainless Steel:Double-wall vacuum construction delivers thermal retention for temperature-sensitive hydration needs across seasonal conditions. Premium positioning targets active outdoor enthusiasts in Colorado, Oregon, and Washington where trail culture and climate variability elevate performance requirements. Nickel price volatility in thermal-grade 304 and 316 alloys compresses margin buffers for mid-tier manufacturers.
- BPA-Free Plastic:Injection-molded copolyester and Tritan variants dominate mass-market volume through color customization and lightweight portability. Volume leadership persists among price-sensitive first-time pet owners in suburban and rural markets. California Proposition 65 enforcement accelerates material transition costs for non-compliant suppliers.
- Silicon:Medical-grade formulations offer collapsibility and bite-resistant durability for aggressive chewers.
- Glass:Borosilicate construction appeals to chemical-averse consumers prioritizing material purity over impact resistance.
BPA-free plastic retains volume leadership; stainless steel holds the steepest expansion curve.
Size:
Application-based sizing separates single-serve urban mobility from multi-hour outdoor endurance, with 500ml emerging as the crossover threshold for daily use versatility.
- 500ml:Mid-capacity design balances portability with sufficient hydration for medium breeds during standard exercise durations. Demand concentrates among urban dog owners in New York, Chicago, and San Francisco where commute-integrated walking routines predominate. Retailer shelf placement favors this format as the default recommendation for undefined breed purchases.
- 750ml:Extended-capacity reservoir serves large breeds and multi-dog households without requiring refill logistics. Adoption accelerates among suburban families with active Labrador, Golden Retriever, and German Shepherd populations in Texas and Florida markets. Weight distribution challenges limit leash-clip attachment feasibility.
- 350ml:Compact format targets toy breeds and purse-portable convenience for air travel compliance.
- 1L:Maximum capacity design addresses working dog handlers and search-and-rescue applications with extended field requirements.
500ml retains volume leadership; 750ml holds the steepest expansion curve.
Brand:
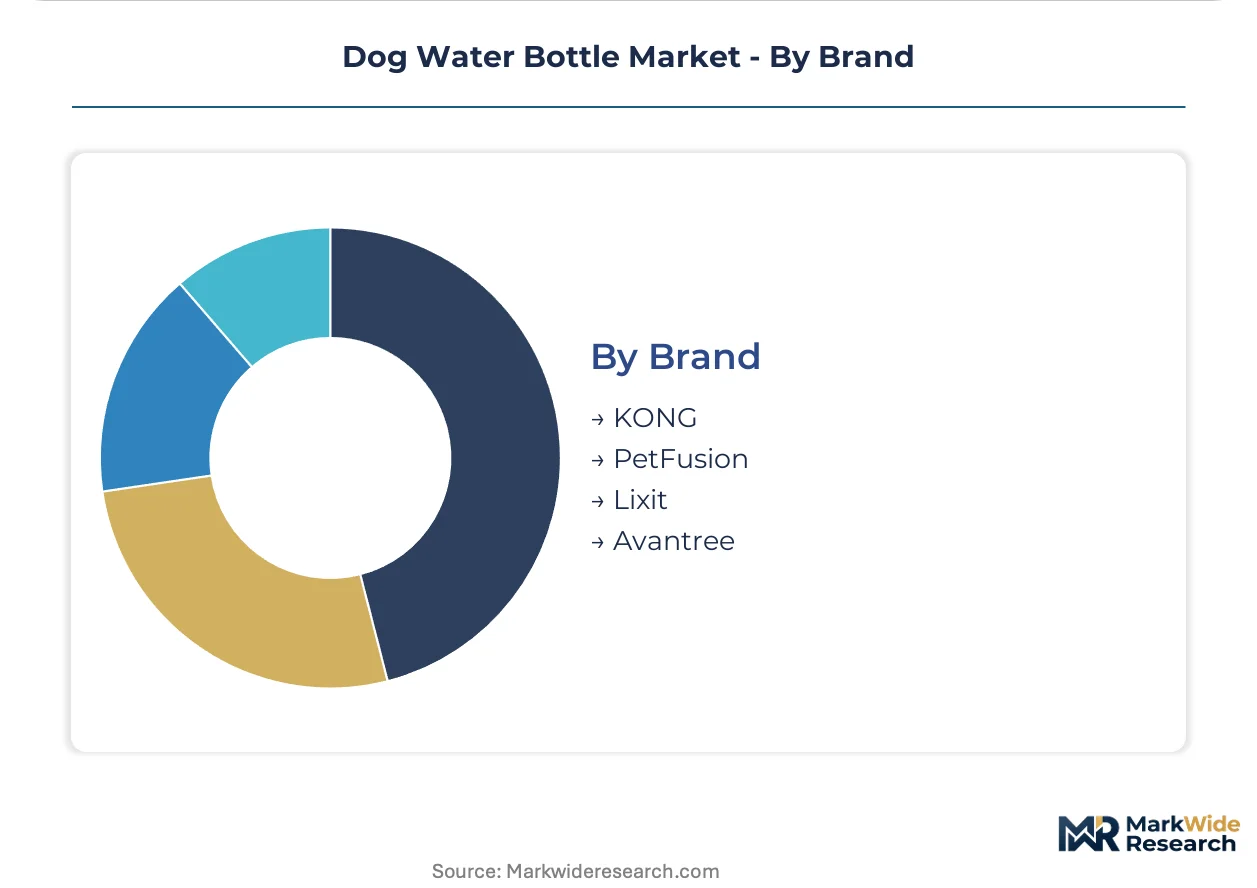
Customer-type fragmentation separates veterinary-credentialed premium positioning from mass-retail accessibility, with specialty pet channel presence determining margin architecture.
- KONG:Leverages chew-toy brand equity and veterinary behaviorist endorsements to command shelf placement in specialty pet retailers. Demand concentrates among training-focused owners in the northeastern United States where behavior modification protocols integrate hydration management. Product extension strategy exploits existing distributor relationships with Petco and independent pet stores.
- PetFusion:Direct-to-consumer platform integration with subscription replenishment models captures recurring revenue through filter cartridge programs. Digital-native millennial and Gen Z owners in California and Washington show highest conversion rates for bundled hydration and nutrition delivery services. Amazon algorithmic visibility depends on review velocity maintenance.
- Lixit:Small-animal heritage brand expanding into canine hydration through cage-mount and vehicle-secure attachment systems.
- Avantree:Electronics crossover manufacturer applying consumer tech supply chain efficiencies to pet accessory production.
KONG retains volume leadership; PetFusion holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban millennial and Gen Z pet owners concentrate demand in metropolitan corridors with active outdoor cultures, while regulatory pressure on material safety reshapes supplier geography. FDA enforcement in North America and EU REACH amendments in Europe are redirecting manufacturing investment toward compliant material hubs.
United States
Daily commuters in New York, Chicago, and San Francisco drive nozzle bottle adoption for leash-clip portability during transit-integrated walking routines. FDA Center for Veterinary Medicine oversight elevates compliance costs for valve component suppliers. Colorado and Oregon clusters concentrate thermal-retention stainless steel demand among trail-accessible outdoor recreationists.
Germany
Specialty retailers in Berlin and Hamburg now require full material origin documentation as a listing prerequisite under tightened EU REACH plasticizer restrictions. ECHA migration limit amendments are accelerating glass and medical-grade silicone transitions among export-focused manufacturers. Bavaria-based fabricators are redirecting R&D toward biodegradable certification pathways for compostable shelf placement.
United Kingdom
Digital-native millennial owners in London and Manchester show highest conversion rates for subscription-based filter cartridge replenishment models. Post-Brexit divergence from EU chemical regulations is creating dual compliance burdens for cross-channel suppliers. Midlands distribution hubs are consolidating inventory for direct-to-consumer platform fulfillment.
Japan
Compact 350ml formats dominate Tokyo and Osaka apartment dwellers prioritizing purse-portable convenience for public transit compliance. METI standards on pet product material safety are converging with voluntary industry sustainability commitments. Nagoya industrial clusters specialize in precision silicone valve molding for spill-resistant mechanisms.
Australia
Extended-capacity gravity bottles accelerate among vehicle-based adventure culture in Queensland and Western Australia where multi-day trail access predominates. TGA-aligned state regulators are adopting FDA-equivalent material safety benchmarks for import clearance. Melbourne specialty retailers are gatekeeping shelf access through sustainability scorecard requirements.
Dog Water Bottle Market Competitive Landscape
Player mix skews toward digitally native direct-to-consumer specialists and veterinary-credentialed heritage brands. Market structure fragments across three functional tiers: app-integrated technology platforms, material-certified premium positioning, and collapsible design patent holders. Consolidation pressure is minimal; competitive intensity centers on channel control and recurring revenue model construction rather than scale-driven M&A. Geographic expansion and subscription replenishment program launches represent dominant competitive moves.
Within the technology-integrated tier, PETKIT exemplifies app-connected inventory management archetypes, while Springer Pets occupies veterinary-grade certification positioning. MalsiPree represents collapsible design specialization for space-constrained urban segments. These three anchors illustrate how competitive differentiation now hinges on data integration capabilities and material compliance credentials rather than purely physical product attributes.
| Leading Market Players |
|---|
| WePet |
| PETKIT |
| Springer Pets |
| AVELORA |
| Kalimdor |
| MalsiPree |
| OllyDog |
| Gardner Pet |
| PupFlask |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between thermal-grade stainless steel suppliers and premium bottle manufacturers lock in nickel price visibility while securing alloy allocation for FDA-compliant production runs. These contracts insulate tier-one brands from spot market volatility that compresses margins for mid-tier competitors sourcing 304-grade inputs on monthly price resets.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate raw material procurement, passing nickel volatility through to finished goods pricing. Three-tier pricing structure across premium, standard, and economy levels separates veterinary-certified stainless steel from injection-molded Tritan and uncertified polymer alternatives. Price differentiation hinges on FDA material compliance tier and thermal retention performance certification. Cost compression in the BPA-free plastic tier intensifies because California Proposition 65 enforcement accelerates reformulation expenses. First-time pet owners in suburban markets exhibit highest price sensitivity; trail-access outdoor enthusiasts in Colorado and Oregon show lowest sensitivity to premium positioning.
Supply Chain Analysis
China and Vietnam anchor injection-molded copolyester component fabrication, while Japan and South Korea specialize in precision silicone valve molding for spill-resistant mechanisms. Raw material dependencies draw from nickel mining in Indonesia and Australia, medical-grade silicone feedstock from Germany, and colorant masterbatch from domestic US compounders. Single-source vulnerability concentrates in thermal-grade 316 alloy supply from specific Japanese mills. Distribution runs through Petco and independent specialty retailers for premium tiers, Amazon Marketplace for direct-to-consumer volume, and veterinary clinic networks for certified medical-grade positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dog water bottle market sits in early-cycle expansion as subscription-based replenishment models disrupt traditional retail replenishment cycles and capture recurring revenue through filter cartridge programs.
For Market Incumbents: Fortify channel control through exclusive veterinary clinic distribution partnerships that transfer clinical credibility and protect margin architecture. Deepen backward integration into medical-grade silicone compounding to reduce exposure to ECHA migration limit amendments. Priority defensive investments center on FDA Center for Veterinary Medicine pre-clearance holdings that delay competitive launches by 18-24 months. For New Entrants and Emerging Players: App-integrated hydration monitoring represents a service-layer gap where incumbents under-serve data-centric millennial owners. Target the collapsible design segment for urban apartment dwellers in New York and San Francisco where space constraints override brand loyalty. Go-to-market angle should emphasize Bluetooth-enabled inventory tracking that converges with pet wearable ecosystems. For Investors and Strategic Acquirers: Direct-to-consumer specialists with subscription replenishment infrastructure present the most compelling acquisition target archetype for portfolio exposure to recurring revenue models. Long-term viability frames around data integration capabilities and material compliance credentials rather than physical manufacturing scale. Signal to watch is specialty retailer sustainability scorecard adoption rates gating shelf access for non-compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Clinic Channel Expansion | Direct distribution through veterinary practices transfers clinical credibility and protects premium margin architecture. |
| Biodegradable Certification Pathway | Compostable material standards in California and EU open shelf placement with specialty pet retailers. |
| App-Integrated Inventory Tracking | Bluetooth-enabled hydration monitoring converges with PETKIT-style pet wearable ecosystems for data revenue. |
| Backward Integration into Silicone Compounding | In-house production of medical-grade silicone reduces ECHA migration limit exposure and secures valve component supply. |
| Subscription Replenishment Model Launch | Recurring filter cartridge revenue captures lifetime value from digital-native millennial and Gen Z owners. |
Research Methodology
The analysis maps nozzle bottle, gravity bottle, collapsible, and dual-purpose travel mug sub-sectors, each validated through product development directors at PETKIT and Springer Pets, specialty retail category buyers at Petco, veterinary clinic procurement managers, and silicone valve molding engineers. Secondary validation draws from FDA Center for Veterinary Medicine guidance documents, ECHA REACH amendment filings, California Proposition 65 enforcement records, and customs trade data on thermal-grade stainless steel imports. Bottom-up unit economics modeling triangulates against top-down category spend estimates from retail audit databases.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models product type, material grade tier, capacity sizing, and distribution channel segmentation dimensions. CAGRs derive from historical adoption curve analysis and penetration rate assumptions. Industry-specific forecast inputs include pet humanization index trajectories and FDA material safety clearance timeline distributions.
Forecasts assume regulatory continuity in FDA Center for Veterinary Medicine oversight and EU REACH plasticizer restrictions; material policy shifts would require re-modeling. Specific risks that could revise projections include nickel price spike volatility, biodegradable certification standard delays, and specialty retailer sustainability scorecard threshold changes. Recalibration cycles align with material shifts in pet wearable ecosystem integration rates and veterinary channel penetration metrics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
North America Functional Pet Treat Market
Pet Care Products
South Korea Dog Food Market
Pet Care Products
Dog Shampoo Market
Pet Care Products
US and Mexico Cat Litter Market
Pet Care Products
Frozen and Freeze-Dried Pet Food Market
Pet Care Products
Pet Tag Market
Pet Care Products
Large Breed Dog Food Market
Pet Care Products
Poland Pet Food Market
Pet Care Products
Sensitive Stomach Cat Food Market
Pet Care Products
Dog Raincoats Market
Pet Care Products
Spain Pet Food Market
Pet Care Products
Pet Pee Pads Market
Pet Care Products
Smart Pet Camera Market
Pet Care Products
Dog Bowl Market
Pet Care Products
Pet Bathing Supplies Market
Pet Care Products
Outdoor Dog Bed Market