
 Organic and Natural Dog Foods Market | 2026-2036
Organic and Natural Dog Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Organic and Natural Dog Foods Market Insights
AAFCO nutrient profiles is realigning the cost-of-entry calculus for new entrants by mandating minimum protein and fat thresholds that synthetic-free formulations struggle to meet cost-effectively. Nestlé Purina PetCare leverages captive supply chains for organic meat sourcing to buffer ingredient volatility. Mars Petcare anchors its position through veterinary channel exclusivity for prescription-grade natural lines. The Honest Kitchen differentiates via human-grade facility certification, a standard few competitors replicate.
Organic and natural dog foods comprise minimally processed formulations using certified organic proteins, whole vegetables, and grain or grain-free bases free from artificial preservatives, colors, and flavors, typically manufactured through cold-pressing, dehydration, or gentle cooking below standard extrusion temperatures to preserve enzymatic activity and micronutrient density. These products serve commercial purposes by commanding shelf price premiums of two to four times conventional kibble while addressing owner concerns about allergenicity, digestibility, and longevity outcomes. Dry food occupies the dominant volume share due to logistics efficiency and storage convenience, though raw food segments attract the fastest-growing margin pools as subscription direct-to-consumer models reduce retail markup capture. Online retail channels now outpace pet store growth in customer acquisition velocity, while premium brand types concentrate profitability through ingredient storytelling and transparent sourcing narratives.
FDA Center for Veterinary Medicine oversight and USDA National Organic Program certification together determine which products qualify for organic labeling and what safety thresholds apply to raw formulations. State-level feed control officials enforce AAFCO compliance variably, creating patchwork market access conditions that favor multi-state registration investment by established players. Stakeholders must monitor evolving EPA pesticide residue limits for imported organic ingredients and anticipate whether USDA will expand domestic organic livestock supply to match formulation demand.
Market Dynamics
AAFCO nutrient profile mandates are compressing formulation margins for synthetic-free entrants while concentrating production among vertically integrated processors with captive organic meat supplies.
Growth Catalysts
- USDA National Organic Program certification:Federal organic labeling standards create price premiums that reward verified supply chain investment, accelerating category premiumization.
- Subscription direct-to-consumer models:Raw food segments leverage recurring revenue structures to bypass retail markup capture and deepen customer lifetime value.
- Millennial and Gen Z urban pet ownership:Demographic concentration in metropolitan centers drives demand for transparent sourcing narratives and human-grade facility standards.
Market Restraints
- Organic protein input volatility:Domestic organic livestock supply lags formulation demand, forcing reliance on imported certified meats subject to EPA pesticide residue scrutiny.
- Cold-pressing equipment capex thresholds:Gentle cooking infrastructure requires specialized dehydration and extrusion alternatives that limit production scale for mid-cap entrants.
- State-level feed control official variability:Patchwork AAFCO enforcement across jurisdictions creates multi-state registration burdens that favor established players with compliance infrastructure.
Strategic Opportunities
- Veterinary channel exclusivity:Prescription-grade natural lines anchored through clinic networks capture margin pools inaccessible to mass retail competitors.
- Human-grade facility certification:Third-party audited production standards differentiate premium positioning in an environment where few competitors replicate compliance depth.
- Raw food subscription logistics:Frozen direct-to-consumer fulfillment infrastructure remains underdeveloped relative to dry kibble, creating first-mover advantages in cold-chain pet nutrition.
Industry Challenges
- AAFCO compliance timeline compression:Evolving minimum protein and fat thresholds force continuous reformulation cycles that strain R&D bandwidth.
- Ingredient storytelling verification:Consumer demand for transparent sourcing requires blockchain or equivalent traceability systems that increase administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic and Natural Dog Foods Market |
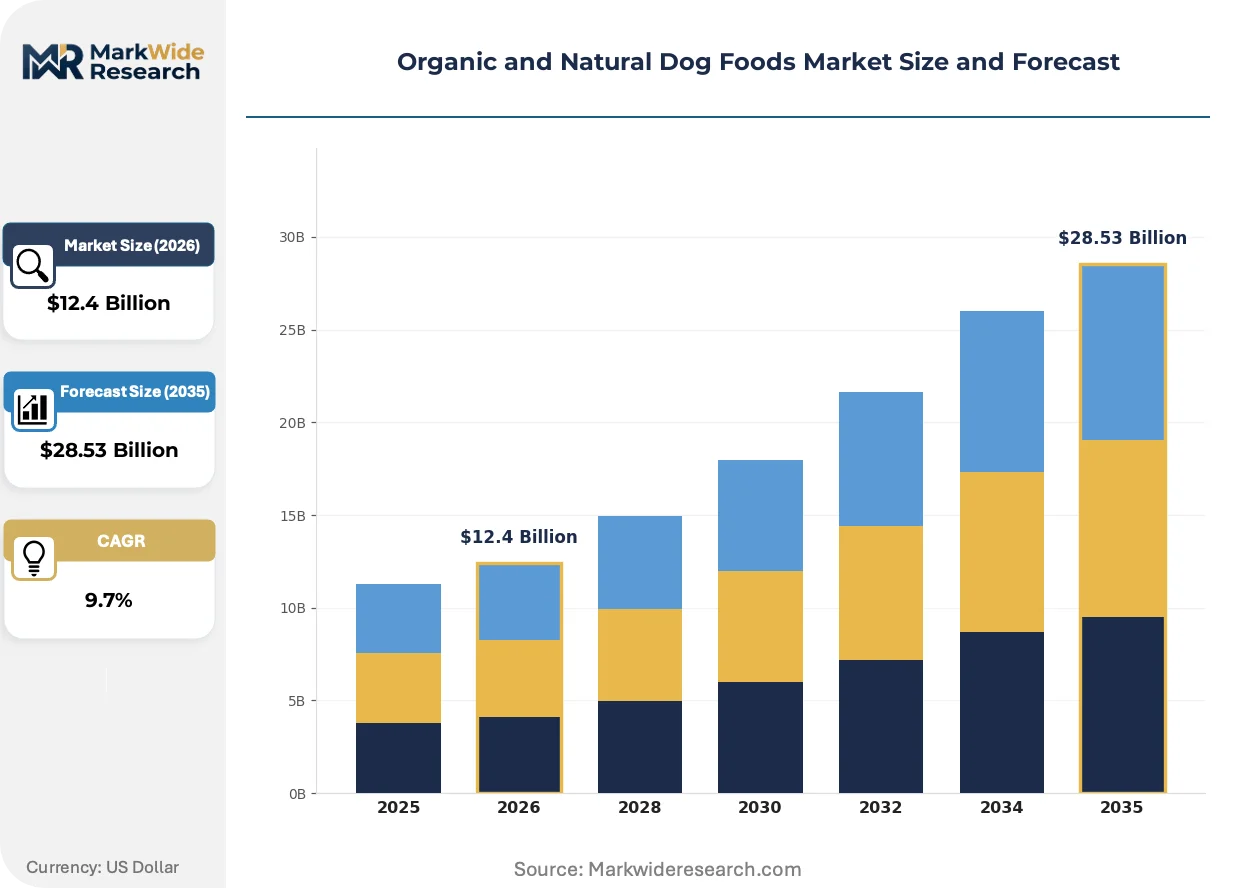
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $28.53 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Food Ingredients: Meat, Vegetables, Grains, Superfoods Distribution Channel: Pet Stores, Online Retail, Supermarkets, Specialty Stores Brand Type: Premium, Mid-range, Economy, Private Label |
| Companies Covered | Nestlé Purina PetCare, Mars Petcare, The J.M. Smucker Company, Hill's Pet Nutrition, General Mills, The Honest Kitchen, Castor & Pollux, Newman's Own, Wellness Pet Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic and Natural Dog Foods Market Trends and Innovations
Formulation technology and certification standards are restructuring competitive advantage around supply chain verifiability rather than marketing expenditure alone.
High-pressure processing (HPP) is modularizing raw food safety protocols by eliminating pathogen loads without thermal degradation of enzymatic activity. Premium subscription brands adopt HPP systems to extend refrigerated shelf life while preserving the nutritional narrative driving consumer willingness to pay. This technology is modularizing the trade-off between food safety liability and raw feeding ideology that previously constrained category expansion.
EU Green Deal farm-to-fork sustainability targets are pressuring imported organic ingredient documentation standards. European pet food distributors now require supply chain carbon footprint disclosures that exceed USDA National Organic Program scope, forcing reformulation around shorter-haul protein sourcing. Natural lines targeting EU market access face accelerated compliance investment timelines.
Specialty pet retailer consolidation is compressing shelf access for emerging brands as Petco and PetSmart reduce SKU counts in favor of exclusive house-label natural offerings. Direct-to-consumer acquisition costs have risen sharply, yet subscription retention rates justify the channel shift for brands with strong ingredient storytelling. Urban millennial concentrations in Austin, Denver, and Portland show highest subscription conversion velocity.
Organic and Natural Dog Foods Market Segmentation
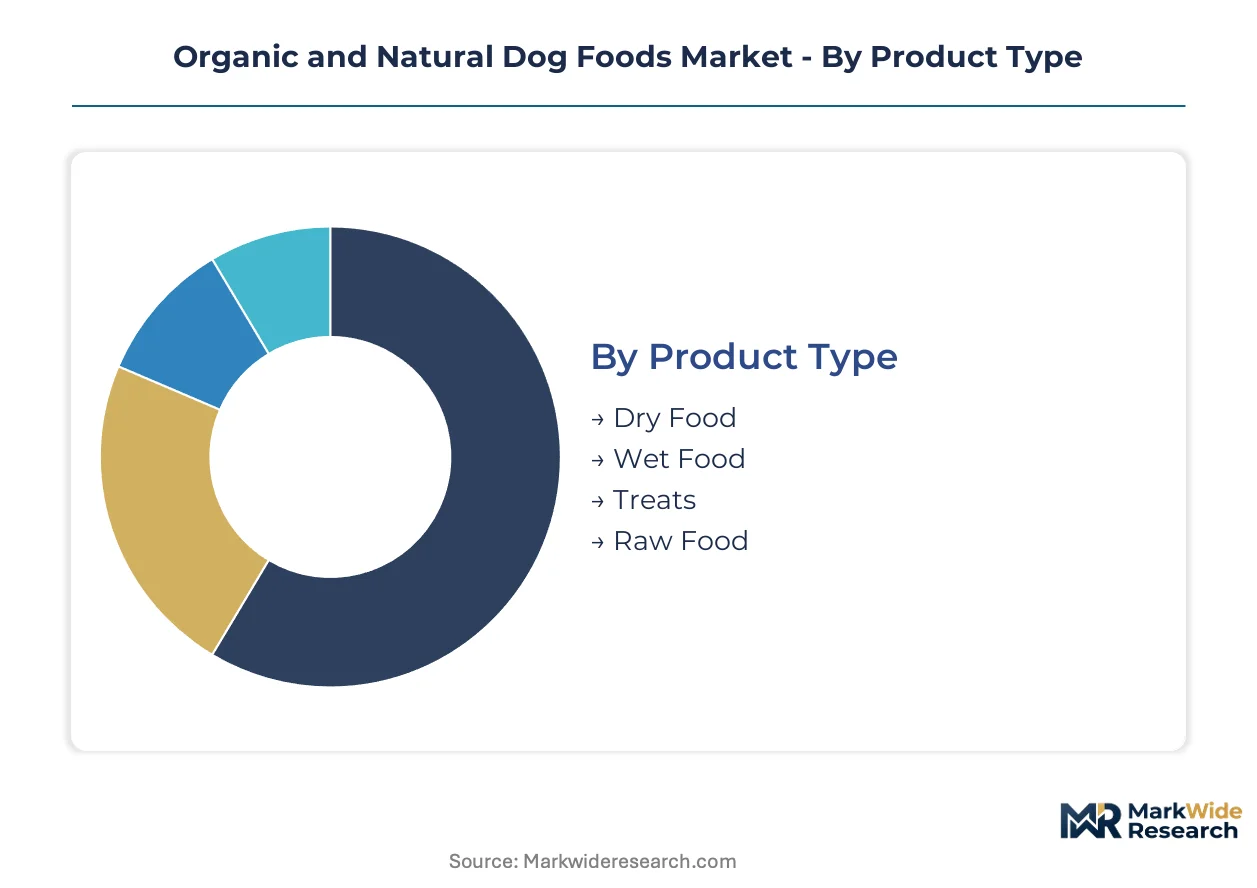
Segmentation in organic and natural dog foods reveals how certification requirements, supply chain configurations, and channel economics concentrate margin capture across distinct product tiers. Understanding these divides exposes where formulation investments translate to pricing power versus commodity exposure.
Product Type:
USDA National Organic Program certification applies variably across formats, with raw and dehydrated products facing additional FDA Center for Veterinary Medicine pathogen testing protocols that dry extruded kibble avoids.
- Dry Food:Extruded or cold-pressed formulations dominate volume throughput due to shelf stability and logistics efficiency. Demand concentrates in suburban households seeking convenience without synthetic preservatives, though AAFCO protein minimums strain synthetic-free formulation economics.
- Raw Food:Frozen or freeze-dried uncooked meats, organs, and bones preserved through high-pressure processing or flash-freezing. Subscription channels in Austin, Denver, and Portland show steepest customer acquisition velocity as pet owners prioritize enzymatic activity retention over storage convenience.
- Wet Food:Canned or pouch-packaged formulations with higher moisture content requiring retort processing or aseptic filling lines that add capital intensity.
- Treats:Bite-sized formulations including dental chews, training rewards, and functional supplements with shorter ingredient lists than complete diets.
Dry food sits at the top of the volume ranking, with raw food climbing the fastest.
Ingredients:
Cost tier stratification runs through ingredient sourcing depth, with certified organic proteins commanding multiples over conventional inputs and superfood inclusions justifying premium positioning through micronutrient density claims.
- Meat:Certified organic poultry, beef, lamb, and fish proteins supply amino acid completeness. Domestic organic livestock supply constraints in the United States force reliance on imported certified meats subject to EPA pesticide residue scrutiny.
- Superfoods:Blueberries, chia seeds, turmeric, and spirulina deliver antioxidant and anti-inflammatory positioning. Urban millennial concentrations drive willingness to pay for functional ingredient narratives supported by third-party testing documentation.
- Vegetables:Sweet potatoes, peas, carrots, and pumpkin provide fiber and micronutrients in grain-free and grain-inclusive formulations alike.
- Grains:Organic brown rice, oats, and barley serve as carbohydrate sources in formulations targeting digestibility over glycemic control.
Meat inputs anchor the cost structure, with superfood inclusions gaining share fastest as differentiation tools.
Distribution Channel:
Channel selection determines margin retention, with direct-to-consumer subscriptions capturing full markup while mass retail imposes slotting fees and promotional fund requirements that compress net pricing.
- Online Retail:Direct-to-consumer and third-party marketplace sales enable subscription models and ingredient storytelling unfiltered by retail buyer gatekeeping. Customer acquisition costs have risen sharply, yet retention rates justify channel investment for brands with transparent sourcing narratives.
- Specialty Stores:Independent pet retailers and natural grocery chains curate premium assortments with educated staff recommendations. Consolidation at Petco and PetSmart reduces SKU access for emerging brands in favor of exclusive house-label offerings.
- Pet Stores:Dedicated pet retail chains provide category-dominant shelf space with high foot traffic from committed pet owners.
- Supermarkets:Mass grocery placement reaches convenience-oriented purchasers but demands price competitiveness against conventional kibble.
Online retail leads volume contribution, with specialty stores expanding most quickly as experiential differentiation tools.
Brand Type:
Maturity gradients separate brand tiers, with premium players investing in human-grade facility certification and veterinary channel exclusivity while private label entrants exploit contract manufacturing overcapacity.
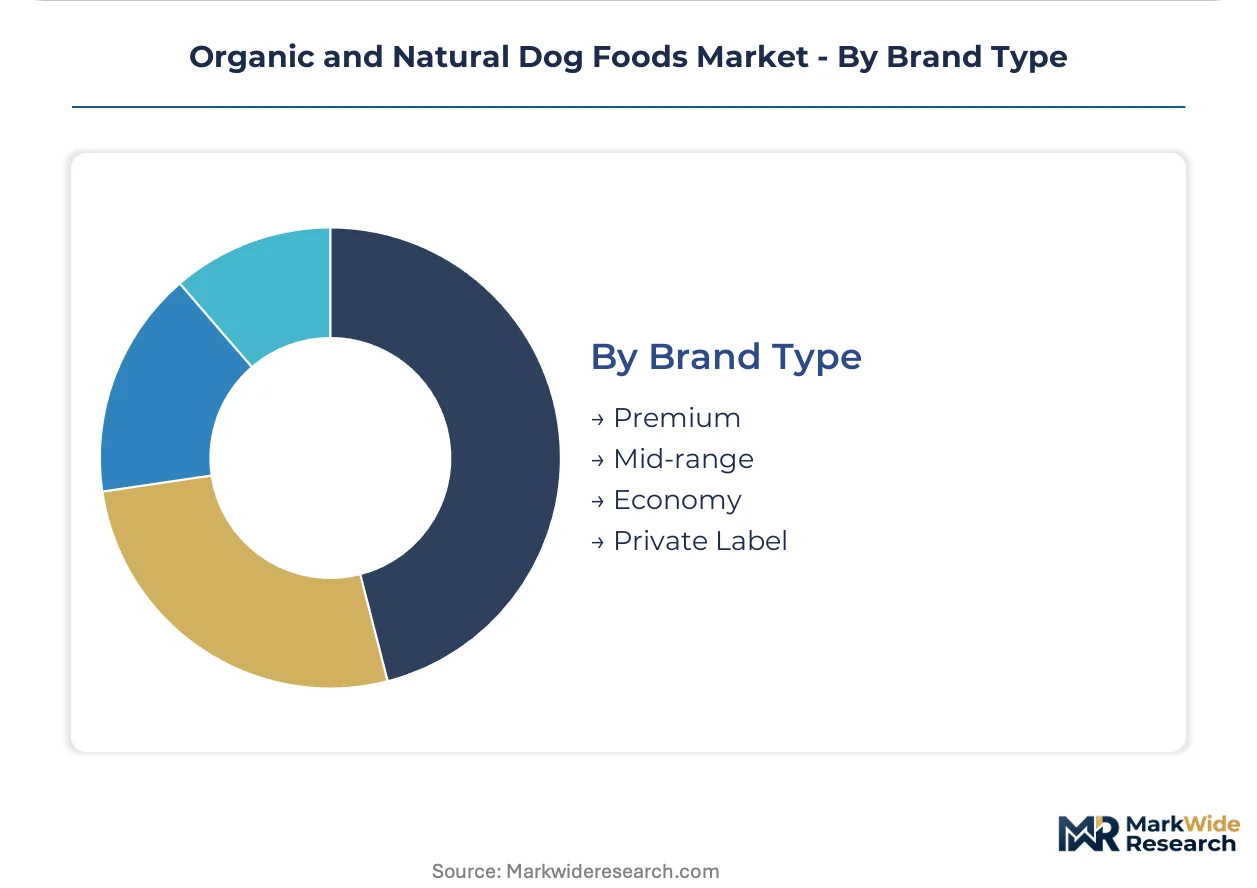
- Premium:USDA organic-certified lines with human-grade facility audits, transparent sourcing documentation, and veterinary channel distribution. These brands command shelf price multiples of two to four times economy tiers through ingredient storytelling and supply chain verifiability.
- Private Label:Retailer-controlled brands manufactured through contract processors, capturing margin from premium positioning without R&D overhead. Petco's WholeHearted and PetSmart's Simply Nourish exemplify this approach.
- Mid-range:Natural claims without full organic certification, targeting price-sensitive upgraders from conventional kibble.
- Economy:Basic natural formulations with limited ingredient transparency, competing primarily on price against conventional alternatives.
Premium brands dominate profitability pools, with private label gaining shelf space fastest through retailer consolidation leverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial and Gen Z pet owners concentrate in metropolitan corridors across five countries, driving premiumization through subscription channels and human-grade certification demands.
United States
Urban clusters in Austin, Denver, and Portland generate the steepest subscription conversion velocity for raw food formats. FDA Center for Veterinary Medicine pathogen testing protocols apply additional compliance burdens to frozen formulations that dry kibble avoids. Specialty pet retailer consolidation at Petco and PetSmart reduces third-party SKU access in favor of exclusive house-label natural offerings.
Germany
EU Green Deal farm-to-fork sustainability targets pressure imported organic ingredient documentation standards beyond USDA National Organic Program scope. EFSA safety thresholds and national feed control enforcement through the Federal Office of Consumer Protection and Food Safety create stringent market entry conditions. Berlin and Munich anchor premium brand distribution through veterinary clinic networks and natural grocery chains.
United Kingdom
London and Southeast England concentrate demand for transparent sourcing narratives and superfood ingredient positioning. FSA and DEFRA jointly oversee organic labeling compliance and raw food safety protocols. Independent pet retailers in metropolitan areas curate premium assortments with educated staff recommendations that bypass mass retail gatekeeping.
Canada
Health Canada and CFIA regulate organic pet food labeling through alignment with USDA National Organic Program standards, creating cross-border certification efficiency. Toronto and Vancouver metropolitan areas show highest penetration of subscription direct-to-consumer models. Provincial feed control officials enforce AAFCO nutrient profile compliance with variable stringency across Ontario, Quebec, and British Columbia.
Australia
TGA and FSANZ govern imported organic ingredient safety thresholds with particular scrutiny of EPA pesticide residue levels on certified meats from third-country suppliers. Sydney and Melbourne anchor premium brand distribution through specialty pet retailers and veterinary channel exclusivity arrangements. Domestic organic livestock supply constraints force reliance on imported certified proteins subject to extended supply chain carbon footprint disclosure requirements.
Organic and Natural Dog Foods Market Competitive Landscape
The competitive structure tilts toward diversified consumer goods conglomerates with captive supply chain infrastructure. Nestlé Purina PetCare and Mars Petcare anchor volume leadership through backward integration into organic meat sourcing and veterinary channel distribution networks. Three archetypes dominate: multinational CPG players with pet care divisions, premium specialists with human-grade facility certification, and private label contract manufacturers serving consolidated retail. Competitive moves concentrate on M&A for organic supply chain access and portfolio diversification into prescription-grade natural lines.
Among diversified food and beverage conglomerates, Nestlé Purina PetCare and Mars Petcare occupy positions exemplifying scale-driven supply chain control, while The Honest Kitchen represents the premium specialist archetype with differentiated facility certification standards. These three companies anchor the competitive spectrum from mass-market volume to subscription-based premium positioning.
| Leading Market Players |
|---|
| Nestlé Purina PetCare |
| Mars Petcare |
| The J.M. Smucker Company |
| Hill's Pet Nutrition |
| General Mills |
| The Honest Kitchen |
| Castor & Pollux |
| Newman's Own |
| Wellness Pet Company |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal farm-to-fork sustainability targets gate qualified supply access and premium-tier pricing power by imposing carbon footprint documentation requirements that exceed USDA National Organic Program scope. Formulators lacking verified shorter-haul protein sourcing face exclusion from EU market access while domestic competitors capture pricing premiums through compliance depth.
Pricing Analysis
Bundled subscription services versus unbundled per-unit retail purchases split pricing architecture across the market. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and human-grade facility audit status. Price differentiation stems from USDA organic certification completeness and veterinary channel exclusivity arrangements. Pricing pressure intensifies in mid-range tiers as private label entrants exploit contract manufacturing overcapacity. Mass retail buyers show highest price sensitivity while subscription direct-to-consumer purchasers accept sustained premiums for transparent sourcing narratives.
Supply Chain Analysis
USDA National Organic Program certification and FDA Center for Veterinary Medicine pathogen testing protocols gate supplier qualification before volume allocation. Domestic organic livestock supply in the United States, imported certified meats from Australia and New Zealand, and EU-sourced organic proteins concentrate qualified input availability. Raw material dependencies center on certified organic poultry, beef, and fish proteins alongside cold-pressed oil and superfood inclusions. Single-source vulnerability runs through contracted organic meat suppliers facing EPA pesticide residue scrutiny. Distribution runs through direct-to-consumer fulfillment infrastructure, specialty pet retailers, and veterinary clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between US and EU regulatory compliance costs, where domestic USDA certification efficiency contrasts with EU Green Deal documentation burdens that inflate European market entry investment.
For Market Incumbents: Hedge against organic protein input volatility through backward integration into captive livestock supply or long-term offtake agreements with certified ranching operations. Defensive consolidation through high-pressure processing equipment acquisition neutralizes emerging raw food subscription entrants. Veterinary channel exclusivity arrangements protect margin pools from mass retail private label displacement. For New Entrants and Emerging Players: Urban millennial pet owners in secondary metropolitan corridors represent an underserved buyer archetype with steep subscription conversion potential. White-space concentration exists in frozen direct-to-consumer fulfillment infrastructure for raw food formats, where cold-chain logistics remain underdeveloped relative to dry kibble. Human-grade facility certification investment unlocks premium positioning inaccessible to contract-manufactured competitors. For Investors and Strategic Acquirers: Roll-up economics work for regional organic pet food specialists because fragmented production capacity and patchwork state-level AAFCO enforcement create consolidation value through compliance infrastructure sharing. Five-to-ten year viability hinges on subscription retention rate durability and organic livestock supply expansion. The signal to watch is USDA domestic organic certification velocity relative to formulation demand growth.| Strategic Initiative | Industry Significance |
|---|---|
| Human-Grade Facility Certification | Third-party audited production standards differentiate premium positioning against contract-manufactured competitors. |
| Veterinary Channel Exclusivity | Prescription-grade natural lines anchored through clinic networks capture margin pools inaccessible to mass retail. |
| Direct-to-Consumer Subscription Launch | Recurring revenue structures bypass retail markup capture and deepen customer lifetime value in urban millennial segments. |
| Backward Integration into Organic Livestock | Captive supply chains buffer ingredient volatility and secure qualified protein inputs against EPA scrutiny. |
| High-Pressure Processing Equipment Deployment | HPP systems extend refrigerated shelf life while preserving enzymatic activity driving raw food willingness to pay. |
Research Methodology
Bottom-up pet owner demand modeling reconciled against top-down organic ingredient supply tracking forms the analytical core of this study. Primary interviews with veterinary nutritionists, specialty pet retailer category managers, organic livestock procurement directors, and direct-to-consumer brand operations heads combined with secondary validation from FDA Center for Veterinary Medicine filings, USDA National Organic Program certification databases, AAFCO nutrient profile documentation, and EPA pesticide residue monitoring reports. Triangulation between consumption endpoint estimation and production capacity assessment ensures cross-verified output integrity.
Input-output matrix framing connects organic protein availability, cold-pressing equipment capacity, and subscription channel penetration to volume and value outputs across the analysis window. Segmentation dimensions modeled include product format, certification tier, ingredient sourcing depth, distribution channel, and metropolitan demand cluster. CAGRs derive from curve-fitting historical trajectory against projected supply constraint resolution and regulatory compliance timeline compression. Forecast inputs incorporate organic livestock herd expansion rates and high-pressure processing equipment installation velocity.
Underlying measurement precision varies by segment; raw food subscription volumes carry tighter precision than emerging superfood ingredient categories due to established direct-to-consumer data availability. Forecasts reflect documented assumptions regarding USDA domestic organic supply expansion and EU Green Deal enforcement consistency. Model refresh is warranted upon material change in EPA pesticide residue limit stringency or state-level AAFCO enforcement harmonization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Mobile Pet Care Market
Pet Care Products
Natural Cat Litter Products Market
Pet Care Products
Pet Care Ingredients Market
Pet Care Products
Pet Hair Brush Market
Pet Care Products
Pet Tag Market
Pet Care Products
US Pet Boarding Market
Pet Care Products
Europe Farrier Products Market
Pet Care Products
China Pet Boarding Market
Pet Care Products
Dog Seat Covers Market
Pet Care Products
South America Cat Food Market
Pet Care Products
Dog Boot for Winters Market
Pet Care Products
US Pet Daycare Market
Pet Care Products
Dog Brush Market
Pet Care Products
Plant-Based Pet Food Market
Pet Care Products
High Protein Dog Food Market
Pet Care Products
Pet Bathing Supplies Market