
 Kitten Milk Replacer and Formula Market | 2026-2036
Kitten Milk Replacer and Formula Market Size, Share, and Industry Trends Forecast 2026-2036
Kitten Milk Replacer and Formula Market Foresight
Rescue organizations and neonatal foster networks is reorganizing demand patterns across the kitten milk replacer category. PetAg anchors the veterinary channel through its KMR product line and species-specific nutrition expertise. Royal Canin competes on breed-stage precision, leveraging Mars Petcare's global manufacturing scale. Hartz extends mass-market reach through big-box retail distribution and price-accessible powder formats.
Kitten milk replacer and formula constitutes a nutritionally complete synthetic milk substitute engineered to match feline maternal milk composition, typically containing percent protein and fat ratios near crude protein minimums with added taurine, arginine, and omega fatty acids for metabolic development. Powder formulations dominate volume due to extended shelf stability and lower logistics costs, while ready-to-feed liquid commands premium positioning in emergency veterinary settings. Goat's milk-based formulations gain traction among owners seeking reduced-lactose alternatives, though cow's milk-derived variants sustain cost leadership in bulk institutional procurement.
The FDA's Center for Veterinary Medicine regulates label claims and manufacturing safety under the Federal Food, Drug, and Cosmetic Act, while state feed control officials enforce AAFCO nutrient profiles at the retail level. The USDA's Animal and Plant Health Inspection Service influences interstate commerce standards for animal nutritional products. Stakeholders must monitor evolving state-level raw milk restrictions and veterinary telehealth expansions that reshape how orphaned kittens access professional feeding guidance.
Market Dynamics
Veterinary clinics and neonatal foster networks professionalizing orphaned kitten care protocols is concentrating demand around species-specific nutritional formulations. This structural shift rewards manufacturers with veterinary channel access and regulatory compliance infrastructure.
Growth Catalysts
- FDA Center for Veterinary Medicine oversight:Tightened labeling and nutrient claim standards elevate barriers for marginal suppliers, concentrating volume among compliant manufacturers with established safety documentation.
- Pet humanization in the United States:Owners treating kittens as family members drives willingness to purchase premium milk replacers with specialized fatty acid and amino acid profiles.
- Neonatal care protocol standardization:Animal shelters and rescue organizations adopting evidence-based feeding schedules create predictable institutional procurement volumes.
Market Restraints
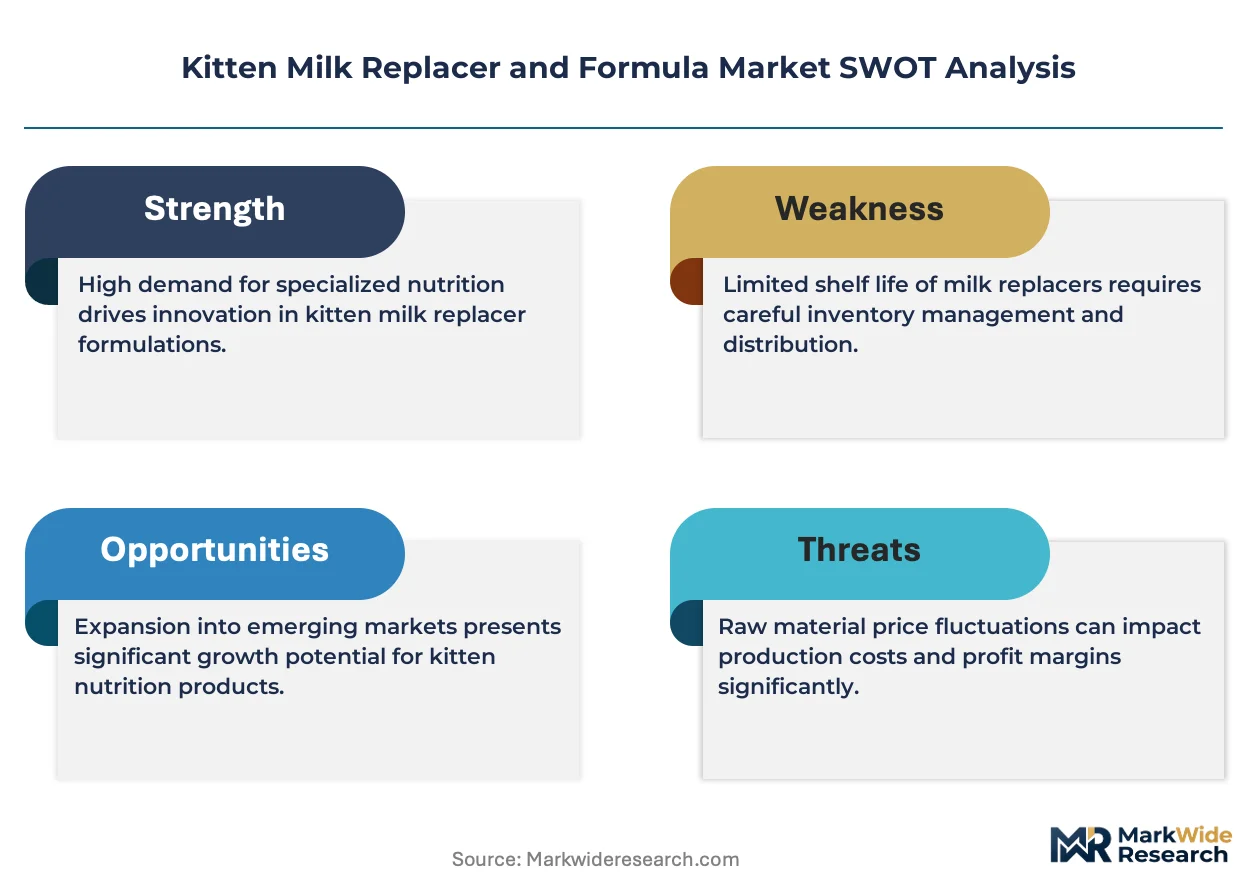
- Dairy input cost volatility:Powder formulations depend on whey protein and milk fat derivatives subject to agricultural commodity price swings.
- Supply concentration in North American manufacturing:Limited domestic production of species-specific milk protein isolates creates import dependency for quality-critical ingredients.
- Raw milk restriction variability:State-level prohibitions on unpasteurized dairy commerce complicate goat's milk-based formulation sourcing.
Strategic Opportunities
- Veterinary telehealth expansion:Remote feeding guidance protocols create channel opportunities for manufacturers bundling product with digital support services.
- Reduced-lactose formulation segment:Goat's milk alternatives address digestive sensitivity concerns among premium-paying foster networks.
- AAFCO nutrient profile harmonization:State feed control official coordination reduces interstate formulation complexity for national distribution.
Industry Challenges
- Veterinary nutritionist talent scarcity:Formulating species-specific milk replacers requires feline metabolic expertise concentrated in academic and research institutions.
- Extended stability certification timelines:Powder shelf-life validation and packaging integrity testing delay product iteration cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kitten Milk Replacer and Formula Market |
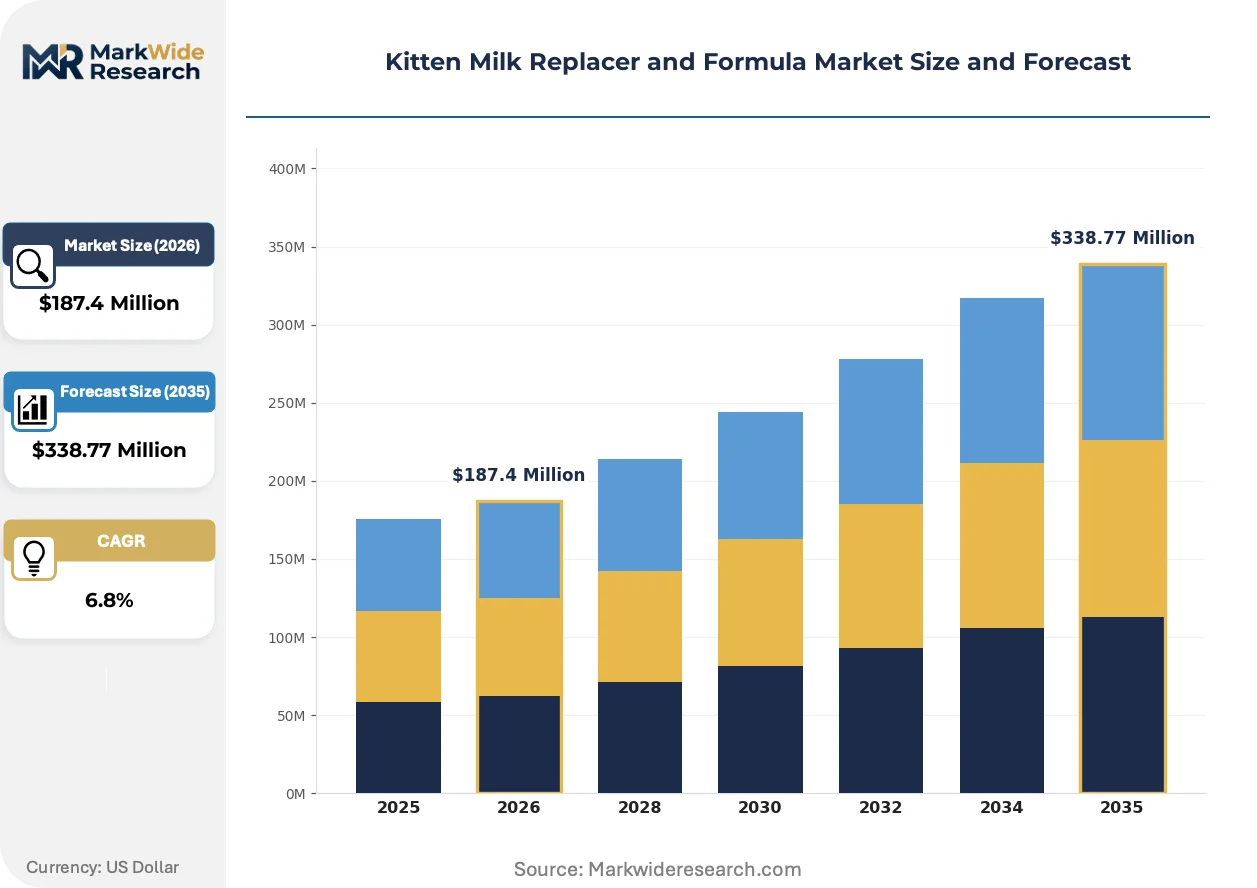
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Ready-to-Feed, Concentrate Formulation: Goat's Milk-Based, Cow's Milk-Based, Soy-Based, Nutrient-Enriched Age Group: Neonatal, Pre-Weaning, Post-Weaning, All Ages Packaging Type: Bulk, Single Serve, Tetra Pak, Pouch |
| Companies Covered | Hartz, Tailspring, PetAg, Vetoquinol, Manna Pro, Royal Canin, Beaphar, Land O'Lakes, Nutri-Vet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kitten Milk Replacer and Formula Market Shifts & Advancements
Formulation science and distribution infrastructure are converging to reshape how orphaned kittens access nutritional support. Three distinct developments are restructuring competitive positioning.
Encapsulation technology for sensitive nutrients is miniaturizing. Lipid microencapsulation protects omega fatty acids and fat-soluble vitamins from oxidation during extended storage. Emergency veterinary clinics adopting ready-to-feed liquid formats with stabilized nutrient payloads reduce preparation error rates. This compression of formulation-to-consumption timelines is miniaturizing the traditional powder-reconstitution workflow.
AAFCO model bill harmonization across state legislatures is reducing regulatory fragmentation. Uniform nutrient profile definitions enable manufacturers to design single SKUs for multi-state distribution. Small regional formulators face compliance cost compression as labeling and testing requirements standardize. Western and Midwestern states with active feed control programs are accelerating adoption.
Foster network procurement collectives are aggregating demand. Neonatal rescue organizations coordinate bulk purchasing through shared digital platforms, displacing individual retail transactions. Manufacturers responding with institutional packaging formats and direct-ship logistics capture volume previously flowing through pet specialty retail. This concentration is most visible in metropolitan shelter systems with established foster coordinator roles.
Kitten Milk Replacer and Formula Market Segmentation
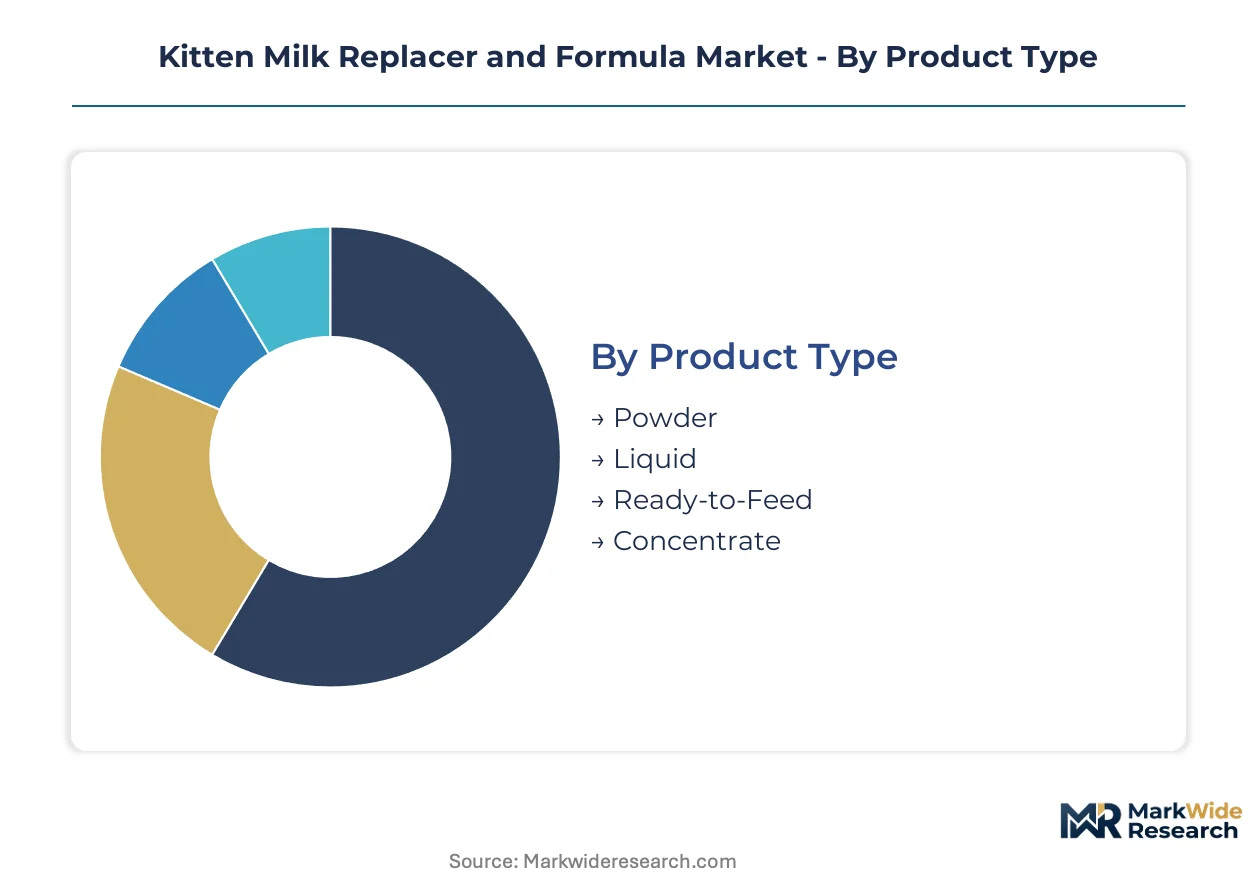
Segmentation in the kitten milk replacer market reveals how formulation science, packaging logistics, and age-specific metabolic requirements create distinct commercial battlegrounds. Manufacturers optimize production lines and distribution strategies around these divides.
Product Type:
Powder formats dominate domestic manufacturing footprints due to extended shelf stability and lower freight costs, while liquid and ready-to-feed variants concentrate in import-dependent premium channels.
- Powder:Dehydrated formulations requiring reconstitution with water deliver 18-24 month shelf stability through moisture exclusion. Demand concentrates in United States animal shelters and multi-foster networks where volume procurement and storage efficiency override convenience premiums. Dairy input cost volatility compresses margins during whey protein concentrate price spikes.
- Liquid:Ready-to-pour formulations in aseptic packaging reduce preparation error rates in emergency veterinary settings. United States metropolitan clinics with high neonatal intake volumes drive procurement, though refrigerated logistics constrain distribution radius to regional cold-chain hubs.
- Ready-to-Feed:Sterilized complete nutrition in single-serve containers eliminates mixing protocols. Foster networks with limited veterinary training access favor this format for orphaned kitten stabilization.
- Concentrate:Dilution-required formulations balancing storage efficiency with preparation flexibility. Institutional buyers in high-volume shelter systems utilize this intermediate format.
Powder holds the largest share; momentum sits with Ready-to-Feed as foster network professionalization accelerates.
Formulation:
Cost tier stratification separates commodity dairy derivatives from premium reduced-lactose alternatives, with nutrient enrichment commanding veterinary channel premiums.
- Goat's Milk-Based:Naturally homogenized fat structure and reduced lactose content address digestive sensitivity in neonatal kittens. Premium-paying foster networks in California and Texas drive demand, though state-level raw milk restrictions complicate sourcing consistency.
- Cow's Milk-Based:Whey protein and milk fat derivatives provide cost leadership through established dairy commodity supply chains. Bulk institutional procurement in United States municipal shelter systems sustains volume, despite higher lactose loads requiring digestive adaptation.
- Soy-Based:Plant-derived protein isolates for dairy-allergy protocols in specialized rescue populations.
- Nutrient-Enriched:Taurine, arginine, and omega fatty acid supplementation for metabolic development optimization.
Cow's Milk-Based commands institutional volume; Goat's Milk-Based gains share fastest among premium foster networks.
Age Group:
Application specificity intensifies toward neonatal stages where metabolic immaturity demands precise nutritional intervention, while post-weaning segments compete with solid food transitions.
- Neonatal:Formulations for kittens under two weeks with immature digestive enzyme production and thermoregulatory deficits. United States veterinary emergency clinics and specialized neonatal foster coordinators drive procurement concentration.
- Pre-Weaning:Transitional nutrition supporting developing gastrointestinal capacity before solid food introduction.
- Post-Weaning:Supplementary feeding for delayed weaning or recovery protocols.
- All Ages:Generalist formulations for multi-stage shelter populations with variable age documentation.
Neonatal captures the highest per-unit pricing; Pre-Weaning shows steepest expansion trajectory as protocol standardization spreads.
Packaging Type:
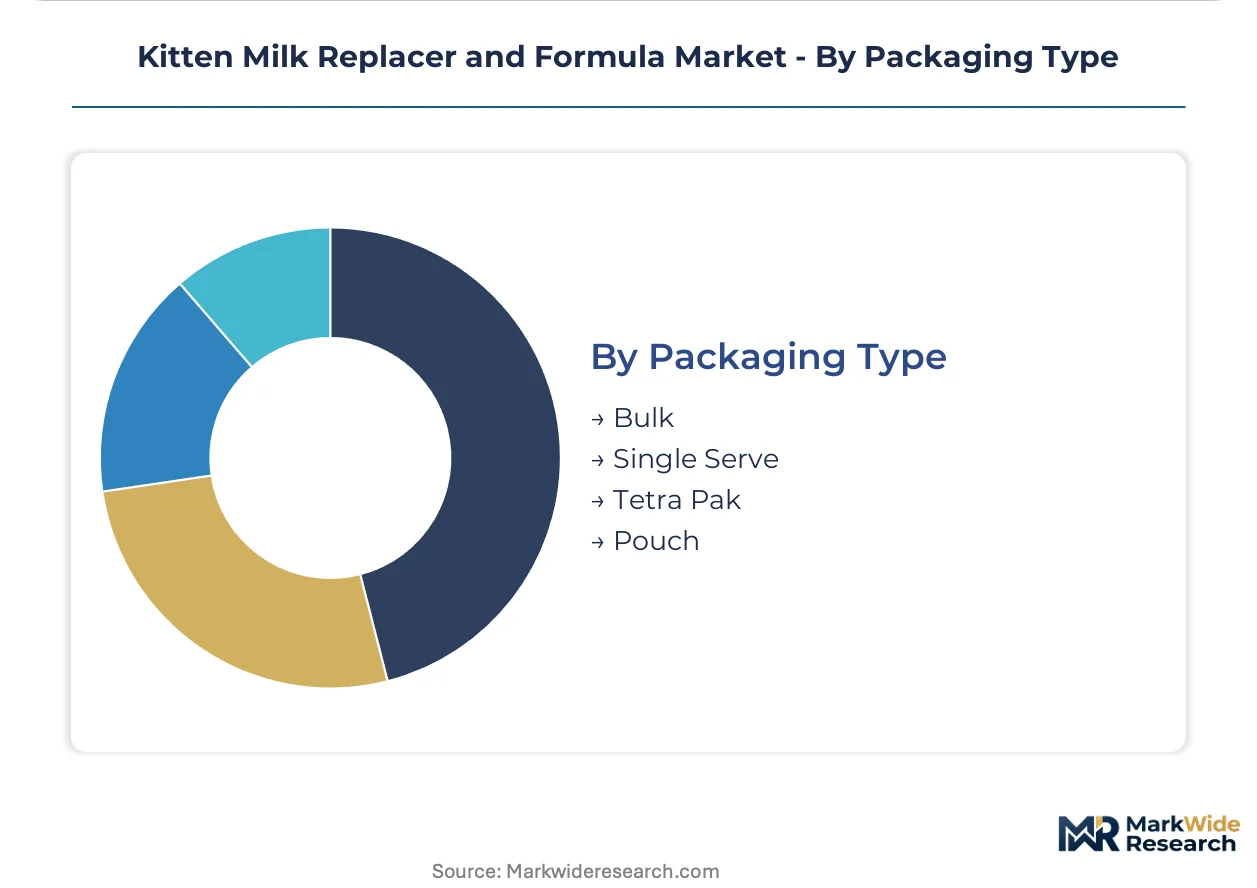
Customer type and volume scale dictate packaging selection, with bulk formats serving institutional procurement and single-serve addressing distributed foster networks.
- Bulk:Multi-kilogram containers for high-volume shelter operations with dedicated storage facilities and trained staff.
- Single Serve:Pre-portioned sachets eliminating measurement error in volunteer-dependent foster networks. United States metropolitan rescue collectives with rotating caregiver bases drive adoption.
- Tetra Pak:Aseptic carton technology extending ambient shelf stability for liquid formulations.
- Pouch:Flexible film packaging reducing shipping cube and disposal volume for remote distribution.
Bulk maintains institutional dominance; Single Serve expands most quickly through foster network procurement collectives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles anchors trans-Pacific distribution for North American pet nutrition imports, while Rotterdam's Europoort terminal handles comparable volumes for European veterinary supply chains.
United States
Veterinary telehealth expansion and neonatal foster network professionalization concentrate demand in California and Texas metropolitan shelter systems. The FDA's Center for Veterinary Medicine enforces labeling standards under the Federal Food, Drug, and Cosmetic Act. Greater Los Angeles rescue collectives coordinate bulk procurement through shared digital platforms, displacing individual retail transactions.
Germany
Specialized veterinary clinics in Bavaria and North Rhine-Westphalia drive premium formulation adoption for orphaned kitten protocols. EFSA guidelines on pet food nutritional adequacy inform national enforcement through the Federal Office of Consumer Protection and Food Safety. Munich's veterinary university hospital anchors feline metabolic research that shapes regional formulation standards.
United Kingdom
RSPCA-affiliated rescue networks in Greater London and the Midlands generate institutional procurement volumes for standardized neonatal care. The Veterinary Medicines Directorate oversees nutritional product safety alongside DEFRA feed regulations. Manchester's shelter medicine consortium coordinates multi-site feeding protocol harmonization across northern England.
Japan
Pet humanization trends in Tokyo and Osaka metropolitan areas sustain premium milk replacer demand for pedigree breeding programs. METI's consumer product safety framework and JIS standards govern manufacturing quality. Yokohama's veterinary import distributors manage cold-chain logistics for liquid formulations from European suppliers.
Australia
Feral kitten trap-neuter-return programs in New South Wales and Victoria create predictable institutional demand for bulk powder formats. The TGA's complementary medicines framework and state-level feed control officials enforce product safety standards. Sydney's animal welfare league coordinates procurement collectives serving regional shelter networks.
Kitten Milk Replacer and Formula Market Competitive Landscape
Listed leaders compete with private specialists across regulatory compliance infrastructure and veterinary channel access. The market structure concentrates volume among manufacturers with established FDA safety documentation and AAFCO nutrient profile validation. Three archetypes dominate: multinational pet nutrition conglomerates with species-specific R&D divisions, regional dairy processors extending into veterinary formulations, and specialized neonatal nutrition pure-plays. Competitive moves center on veterinary telehealth partnership bundling and reduced-lactose formulation line extensions.
Within the veterinary-specialist tier, PetAg and Vetoquinol exemplify archetypes anchored in species-specific expertise and pharmaceutical-grade manufacturing discipline respectively. Royal Canin occupies a position representing multinational scale advantages in metabolic research translation. These three demonstrate how regulatory compliance infrastructure and veterinary channel relationships function as competitive moats distinct from mass-market retail presence.
| Leading Market Players |
|---|
| Hartz |
| Tailspring |
| PetAg |
| Vetoquinol |
| Manna Pro |
| Royal Canin |
| Beaphar |
| Land O'Lakes |
| Nutri-Vet |
| Others |
Supply & Pricing Matrix
Extended powder-form production runs in Wisconsin and Minnesota dairy processing corridors generate unit cost advantages that compress price floors for bulk institutional procurement while elevating barriers for small-batch formulators lacking captive whey protein concentrate sourcing. This scale concentration enables PetAg and Land O'Lakes to maintain margin discipline during agricultural commodity volatility, whereas regional competitors face input cost pass-through pressures that erode veterinary channel competitiveness.
Pricing Analysis
Volume-discount tiering separates municipal shelter systems receiving pallet-scale pricing from individual foster networks purchasing single-serve formats at premium multiples. Three-tier pricing structure across premium, standard, and economy levels reflects formulation complexity, with goat's milk-based variants commanding 40-60% premiums over cow's milk-derived alternatives due to reduced-lactose positioning and sourcing constraints. Pricing pressure stems from dairy input cost volatility, particularly whey protein concentrate spikes tied to cheese production cycles. Municipal procurement officers exhibit highest price sensitivity, while specialized neonatal foster coordinators prioritize metabolic precision over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate liquid and ready-to-feed segments where refrigerated logistics constrain shelf-life extension, whereas powder formulations favor strategic stockpiling among high-volume shelter systems buffering against whey protein price spikes. Manufacturing concentrates in the United States, New Zealand, and the Netherlands, with the latter two supplying premium goat's milk protein isolates subject to state-level raw milk commerce restrictions. Raw material dependencies center on whey protein concentrate, milk fat derivatives, and microencapsulated omega fatty acids. Single-source vulnerability concentrates in species-specific taurine and arginine premix suppliers. Distribution runs through veterinary distribution cooperatives and direct-ship platforms serving aggregated foster network procurement collectives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foster network procurement collectives function as nascent platform intermediaries, with digital coordination tools enabling demand aggregation that shifts bargaining power toward institutional buyers and rewards manufacturers with direct-ship logistics capabilities.
For Market Incumbents: Fortify veterinary channel relationships through embedded telehealth support bundling, defending against emerging entrants leveraging reduced-lactose formulation differentiation to capture premium foster network segments. Backward integration into microencapsulated nutrient sourcing mitigates single-supplier premix vulnerability while extending formulation-to-consumption timeline control. For New Entrants and Emerging Players: Anchor in goat's milk-based formulation segments where state-level raw milk restrictions create sourcing complexity that advantages nimble regional processors over multinational dairy conglomerates. Metropolitan California and Texas foster networks present the most penetrable white-space, with direct-to-foster digital platforms offering lower customer acquisition costs than veterinary channel establishment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized neonatal nutrition pure-plays with FDA safety documentation infrastructure and AAFCO nutrient profile validation, as regulatory compliance moats compound over extended stability certification timelines. Long-term viability hinges on telehealth partnership density and reduced-lactose pipeline depth. The signal to watch is veterinary telehealth reimbursement policy expansion indicating professional feeding guidance protocol institutionalization.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Telehealth Partnership | FDA-compliant manufacturers bundling product with remote feeding guidance capture foster network procurement shifts. |
| Reduced-Lactose Line Extension | Goat's milk formulation investments address digestive sensitivity premiums in California and Texas metropolitan markets. |
| Direct-Ship Logistics Infrastructure | Manufacturer-controlled fulfillment displaces pet specialty retail margin capture in aggregated foster collective procurement. |
| Microencapsulation R&D Investment | Lipid stabilization technology extends ready-to-feed liquid shelf stability for emergency veterinary clinic adoption. |
| AAFCO Harmonization Advocacy | Single-SKU multi-state distribution reduces compliance cost burden on regional formulators seeking national scale. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with veterinary nutritionists, neonatal foster coordinators, shelter procurement managers, and dairy ingredient procurement specialists at formulation manufacturers. Secondary validation drew from FDA Center for Veterinary Medicine labeling guidance documents, AAFCO model bill adoption tracking across state legislatures, USDA dairy commodity price reporting, and veterinary telehealth platform utilization disclosures. Bottom-up segment sizing triangulated against top-down category value estimates derived from institutional procurement volume aggregation.
Across the modeling period, forecasts applied a multi-dimensional analytical framework spanning product type, formulation base, age-specific application, packaging format, and regional regulatory cluster. CAGRs were derived from trend extrapolation of veterinary channel penetration rates and foster network professionalization indices, with cross-validation against dairy input cost elasticity assumptions and species-specific metabolic research translation timelines.
Underlying assumptions cover sustained pet humanization expenditure patterns and AAFCO harmonization momentum, with deviation risk concentrated in state-level raw milk restriction tightening and veterinary nutritionist talent scarcity limiting formulation innovation velocity. Revision becomes warranted when telehealth reimbursement policy crosses threshold adoption rates or when dairy commodity price volatility exceeds historical bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Outdoor Cat Houses and Furniture Market
Pet Care Products
Cat Diets Market
Pet Care Products
Dog Pad Market
Pet Care Products
Pet Snacks and Treats Market
Pet Care Products
China Pet Food Market
Pet Care Products
Pet Apparel Market
Pet Care Products
Asia Pacific Pet Diet Market
Pet Care Products
Asia-Pacific Pet Food Market
Pet Care Products
Cat Litter Boxes Market
Pet Care Products
South Korea Pet Food Market
Pet Care Products
Europe Pet Food Market
Pet Care Products
Pet Transport Cage Market
Pet Care Products
Pet Fitness Care Market
Pet Care Products
France Pet Food Market
Pet Care Products
Saudi Arabia Pet Boarding Market
Pet Care Products
Smart Pet Kennel Market