
 Panama Telecom Market | 2026-2036
Panama Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Panama Telecom Market Insights
Enterprise buyers are redrawing demand patterns across the Panama telecom landscape. Cable & Wireless Panama leverages its legacy fiber backbone to anchor wholesale connectivity contracts with multinational logistics operators. Tigo Panama competes through aggressive mobile spectrum deployment along the interoceanic corridor. Digicel Panama specializes in prepaid mobile penetration across underserved provincial zones.
Panama telecom encompasses the transmission infrastructure, switching systems, and service delivery platforms enabling voice, data, and video communications across the isthmus. Fiber optic cables with latency specifications under 50 milliseconds dominate backbone architecture, serving Panama's role as a hemispheric data transit hub connecting North and South American networks. Mobile services command the largest revenue pool among service type segments, while 5G technology represents the fastest-expanding infrastructure category as operators migrate from 4G radio access networks. Business enterprises generate the highest-margin end user segment due to dedicated leased-line and SD-WAN requirements.
ASEP, Panama's public services regulator, mandates infrastructure-sharing obligations that lower barriers for secondary operators entering provincial markets. The national cybersecurity framework issued by the Ministry of Public Security imposes data localization standards on critical telecom infrastructure operators. Stakeholders must monitor spectrum auction timelines and submarine cable landing rights as decisive variables for capacity planning and capital allocation.
Market Dynamics
ASEP's infrastructure-sharing mandates are compressing capital requirements for secondary operators while forcing incumbents to monetize fiber assets through wholesale rather than retail dominance.
Growth Catalysts
- ASEP Infrastructure Mandates:The regulator's co-location requirements slash entry costs for provincial broadband providers and accelerate rural network buildout timelines.
- Colón Data Center Cluster:Hyperscale facility expansions along the interoceanic corridor generate dedicated fiber demand for low-latency cross-border connectivity.
- 5G Spectrum Migration:Radio access network upgrades enable network slicing capabilities that logistics operators require for autonomous port equipment coordination.
Market Restraints
- Submarine Cable Concentration:Five cable systems terminate at Pacific and Atlantic landing stations, creating single-point vulnerability for international bandwidth supply.
- Provincial Right-of-Way Costs:Municipal permitting fees for fiber trenching in Darién and Veraguas provinces exceed metropolitan benchmarks by substantial margins.
- Mobile Saturation Ceiling:Prepaid subscriber penetration approaches theoretical maximums in Panama City, compressing organic subscriber growth potential.
Strategic Opportunities
- Chiriquí Agricultural IoT:Precision farming networks in western highlands remain underserved by dedicated low-power wide-area connectivity infrastructure.
- SD-WAN Convergence:Software-defined networking integration with existing MPLS backbones creates migration pathways for enterprise branch office consolidation.
- Free Trade Zone Edge Computing:Colón's logistics parks generate demand for localized processing nodes that reduce cloud latency for customs clearance systems.
Industry Challenges
- Fiber Splicing Technician Scarcity:Specialized fusion splicing certification programs produce insufficient graduates to support accelerated provincial deployment schedules.
- Legacy Copper Decommissioning:PSTN switch replacement timelines conflict with enterprise customers maintaining analog fax and alarm circuits for compliance purposes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Panama Telecom Market |
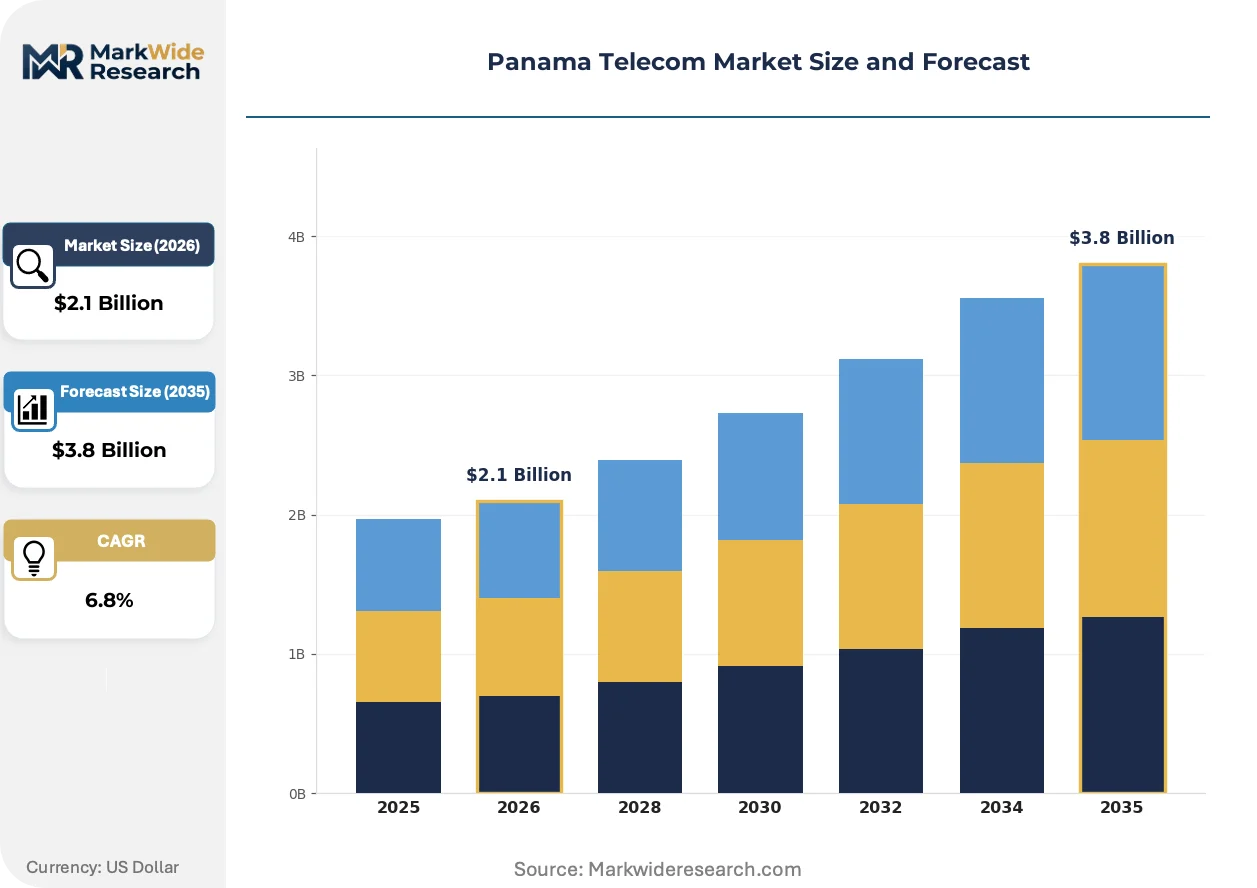
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Services, Fixed Line Services, Internet Services, Pay-TV Technology: 4G, 5G, Fiber Optics, DSL End User: Residential Users, Business Enterprises, Government Agencies, Educational Institutions Distribution Channel: Retail Stores, Online Platforms, Direct Sales, Authorized Resellers |
| Companies Covered | Cable & Wireless Panama, Digicel Panama, +Móvil, Movistar, Cable Onda, Tigo Panama, Liberty Latin America, América Móvil, Claro, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Panama Telecom Market Trends and Innovations
Open RAN architectures are disrupting vendor lock-in patterns across mobile infrastructure procurement. Network operators now evaluate disaggregated hardware-software stacks that reduce dependence on integrated equipment suppliers.
Virtualized radio access networks are fragmenting traditional equipment procurement patterns. Cable & Wireless Panama and Tigo Panama pilot multi-vendor RAN deployments in Panama City metro cells. This disaggregation is compressing capital expenditure cycles and enabling faster feature deployment through software updates rather than hardware swaps.
ASEP's cybersecurity framework issued by the Ministry of Public Security imposes data localization standards on critical infrastructure operators. Telecom providers must maintain domestic data residency for subscriber information and traffic metadata. Mobile operators and data center landlords are redesigning storage architectures to satisfy audit requirements for government and financial sector contracts.
Enterprise buyers are consolidating vendor relationships through managed service contracts that bundle connectivity with security operations. Logistics firms operating the canal corridor now procure unified communications through single-source agreements rather than maintaining separate contracts for voice, data, and cloud access. This concentration is most visible among multinational freight forwarders headquartered in the Colón Free Trade Zone.
Panama Telecom Market Segmentation
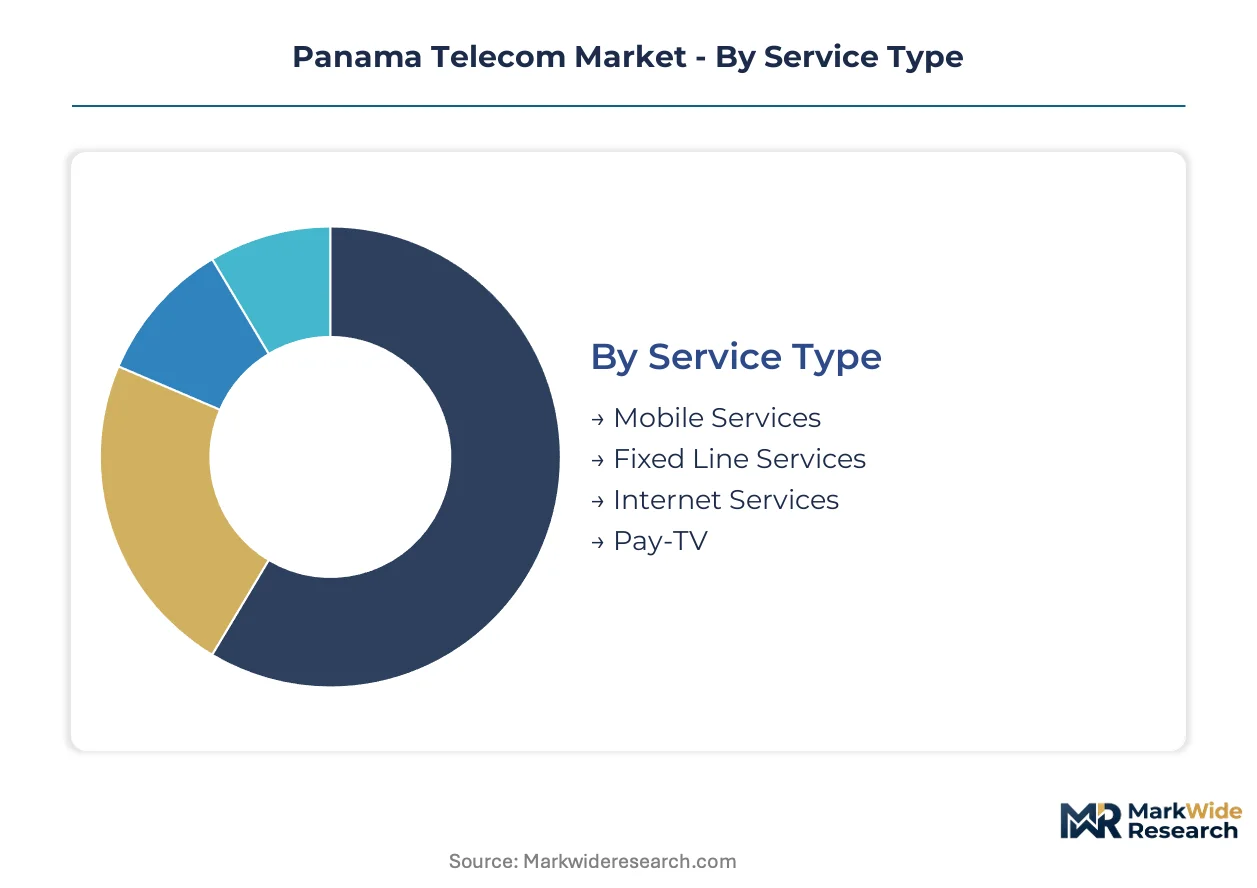
Segmentation reveals how demand fragments across distinct commercial pathways in Panama's telecom landscape. Channel strategies, technology migration timelines, and end-user procurement patterns vary sharply between Panama City's corporate corridor and provincial markets.
Service Type:
Mobile services flow primarily through retail stores and authorized resellers in provincial zones, while fixed-line and internet services concentrate in direct sales channels targeting enterprise buyers in the Colón Free Trade Zone.
- Mobile Services:Prepaid and postpaid voice and data subscriptions dominate revenue pools across the isthmus. Demand concentrates among logistics operators along the interoceanic corridor and residential subscribers in Panama City, driven by 5G spectrum migration enabling network slicing for autonomous port coordination.
- Internet Services:Fixed and mobile broadband connectivity spans fiber-to-the-home, cable modem, and wireless delivery platforms. Enterprise adoption clusters in Panama City and Colón, where data center interconnectivity requirements intensify and cloud-based unified communications expand among canal corridor operators.
- Fixed Line Services:Traditional PSTN voice and dedicated leased-line circuits maintain residual enterprise demand. Government agencies and financial institutions in the capital sustain procurement for compliance-mandated analog systems.
- Pay-TV:Cable and satellite television distribution reaches residential subscribers through bundled internet packages. Urban markets show accelerating cord-cutting migration toward streaming platforms.
Mobile services dominate installed base. Internet services are where expansion concentrates.
Technology:
Cost tier differentiation separates premium fiber deployments from economy DSL offerings, with 5G positioning as a mid-tier alternative for mobile-centric households and small enterprises.
- 5G:Next-generation radio access networks enable sub-50 millisecond latency specifications essential for hemispheric data transit. Deployment concentrates in Panama City metro cells and Colón logistics parks, where ASEP spectrum mandates accelerate infrastructure buildout.
- Fiber Optics:Backbone and last-mile optical cable systems with latency specifications under 50 milliseconds anchor hemispheric connectivity. Cable & Wireless Panama leverages this infrastructure for wholesale contracts with multinational logistics operators.
- 4G:Legacy LTE networks maintain coverage across provincial zones pending 5G migration. Tigo Panama competes through aggressive spectrum deployment along the interoceanic corridor.
- DSL:Copper-based digital subscriber line technology serves residual rural markets where fiber trenching costs prove prohibitive. Municipal permitting fees in Darién and Veraguas provinces exceed metropolitan benchmarks substantially.
Fiber optics commands the premium tier. 5G is climbing the fastest among infrastructure categories.
End User:
Volume concentration varies by margin profile, with business enterprises generating the highest-margin requirements for dedicated leased-line and SD-WAN solutions.
- Business Enterprises:Corporate buyers procure unified communications, dedicated internet access, and managed security services through single-source agreements. Multinational freight forwarders in the Colón Free Trade Zone drive consolidation of vendor relationships.
- Residential Users:Household subscribers consume prepaid mobile, broadband internet, and bundled entertainment packages. Panama City shows prepaid saturation approaching theoretical maximums.
- Government Agencies:Public sector procurement emphasizes cybersecurity compliance and data localization standards under Ministry of Public Security frameworks. Critical infrastructure operators must maintain domestic data residency.
- Educational Institutions:Schools and universities require connectivity for administrative systems and remote learning platforms. Provincial deployment lags metropolitan benchmarks.
Residential users dominate subscriber counts. Business enterprises are where margin expansion concentrates.
Distribution Channel:
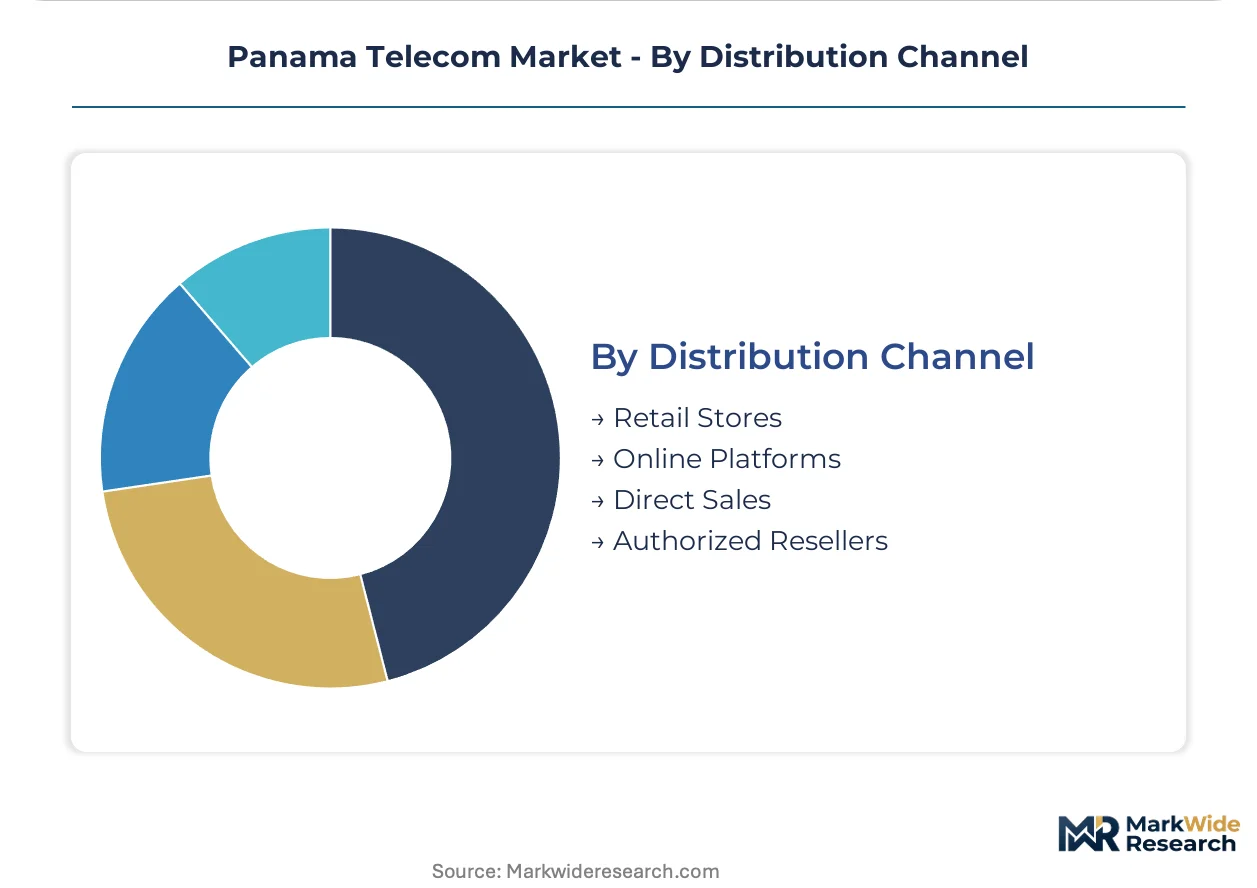
Geographic reach determines channel effectiveness, with retail density correlating to population concentration and direct sales penetrating enterprise clusters.
- Retail Stores:Branded physical outlets and electronics retailers distribute prepaid mobile and consumer broadband. Digicel Panama specializes in prepaid penetration across underserved provincial zones through this channel.
- Direct Sales:Enterprise account teams negotiate managed service contracts and wholesale connectivity agreements. Cable & Wireless Panama anchors wholesale fiber contracts through dedicated sales operations.
- Online Platforms:Self-service portals and mobile applications enable plan management and top-up transactions. Urban demographics show accelerating digital channel adoption.
- Authorized Resellers:Third-party agents extend reach into rural municipalities where operator-owned retail proves uneconomical. ASEP infrastructure-sharing mandates lower barriers for secondary operators entering these markets.
Retail stores dominate prepaid mobile volumes. Direct sales are where enterprise value concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers concentrate procurement decisions in Panama City and Colón Free Trade Zone corridors, while provincial markets remain fragmented across secondary operators leveraging infrastructure-sharing mandates. Residential demand clusters along the interoceanic logistics belt, with data center interconnectivity requirements intensifying cross-border fiber deployments.
Panama City Metro
Corporate headquarters and multinational logistics operators anchor premium connectivity demand through dedicated leased-line and SD-WAN contracts. ASEP's cybersecurity framework imposes data localization standards on critical infrastructure operators serving government and financial sector clients. The capital's data center cluster generates low-latency fiber requirements for hemispheric network transit.
Colón Free Trade Zone
Hyperscale facility expansions drive dedicated fiber demand for cross-border connectivity among freight forwarders and customs clearance systems. The Ministry of Public Security's national cybersecurity framework mandates domestic data residency for operators serving critical logistics infrastructure. Edge computing nodes localize processing for port automation and autonomous equipment coordination.
Chiriquí Highlands
Precision farming networks in western agricultural zones generate underserved demand for low-power wide-area IoT connectivity. Provincial right-of-way costs for fiber trenching exceed metropolitan benchmarks, slowing infrastructure deployment. David city anchors regional commercial activity with growing enterprise requirements for cloud-based unified communications.
Darién Province
Municipal permitting fees for fiber infrastructure substantially exceed Panama City benchmarks, constraining broadband penetration. ASEP infrastructure-sharing mandates lower capital barriers for secondary operators entering this historically underserved market. Mobile services dominate connectivity provision through prepaid subscriber models.
Veraguas Province
Rural broadband deployment accelerates through regulator-mandated co-location requirements reducing entry costs for provincial providers. Agricultural and fishing cooperatives drive enterprise connectivity demand in Santiago and surrounding municipalities. Legacy copper decommissioning timelines conflict with compliance-mandated analog systems maintained by public sector agencies.
Panama Telecom Market Competitive Landscape
Player mix skews toward integrated incumbents with legacy fiber backbone assets and mobile-first challengers deploying aggressive spectrum strategies. The market structure concentrates around three archetypes: infrastructure-heavy incumbents monetizing wholesale fiber dominance, mobile specialists pursuing prepaid penetration in provincial zones, and regional Latin American conglomerates leveraging scale across multiple markets. Dominant competitive moves include infrastructure-sharing compliance to reduce capital requirements and managed service bundling to consolidate enterprise vendor relationships.
Within the integrated incumbent tier, Cable & Wireless Panama and Tigo Panama occupy positions defined by legacy asset bases and wholesale contract anchoring. Digicel Panama exemplifies the mobile-specialist archetype through prepaid market penetration strategies. These three operators collectively represent the competitive spectrum spanning infrastructure-heavy to mobile-first positioning across Panama's telecom landscape.
| Leading Market Players |
|---|
| Cable & Wireless Panama |
| Digicel Panama |
| +Móvil |
| Movistar |
| Cable Onda |
| Tigo Panama |
| Liberty Latin America |
| América Móvil |
| Claro |
| Others |
Pricing and Supply Chain Analysis
Long-term wholesale fiber contracts with take-or-pay provisions lock in supply access for Colón Free Trade Zone logistics operators while anchoring price visibility across ASEP-mandated infrastructure-sharing arrangements. These agreements insulate multinational freight forwarders from spot-market volatility in international bandwidth pricing.
Pricing Analysis
Cost-plus enterprise connectivity contracts with bandwidth-indexed pricing dominate the Panama telecom landscape. Three-tier pricing structure across premium fiber, standard 5G, and economy DSL levels separates multinational logistics operators from provincial small enterprises from rural residential subscribers. Pricing pressure stems from ASEP's infrastructure-sharing mandates compressing wholesale margins for incumbent fiber owners. Residential prepaid mobile subscribers exhibit highest price sensitivity, while business enterprises procuring SD-WAN bundles demonstrate lowest sensitivity due to compliance-mandated uptime requirements.
Supply Chain Analysis
Inbound logistics costs for submarine cable landing equipment hinge on Pacific-Atlantic container availability through the Panama Canal corridor. Equipment procurement draws from China, South Korea, and Finland for optical transmission gear, radio access network components, and core switching systems. Single-source vulnerability concentrates in submarine cable landing station terminal equipment. Distribution runs through manufacturer-direct relationships with Cable & Wireless Panama and Tigo Panama, supplemented by authorized resellers for provincial enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed security service attach rates are expanding faster than raw connectivity provisioning across Panama's enterprise telecom market. Recurring revenue from unified communications bundles now exceeds hardware-centric infrastructure deployment growth.
For Market Incumbents: Secure wholesale fiber dominance through ASEP-compliant infrastructure-sharing arrangements that monetize stranded provincial capacity. Defend against Open RAN disaggregation by anchoring integrated vendor relationships with government agencies subject to Ministry of Public Security data localization mandates. Prioritize certification investment in fusion splicing technician training programs to alleviate deployment bottlenecks in Darién and Veraguas provinces. For New Entrants and Emerging Players: Lead with agricultural IoT connectivity offerings targeting Chiriquí Highlands precision farming cooperatives underserved by existing low-power wide-area infrastructure. Penetrate the provincial authorized reseller channel where ASEP co-location requirements slash capital barriers. Position SD-WAN migration services for Santiago-based enterprise branch offices seeking cloud-based unified communications consolidation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed service providers bundling security operations with connectivity across the Colón Free Trade Zone corridor. Long-term viability favors operators with demonstrated compliance under ASEP cybersecurity frameworks and established landing rights at Pacific and Atlantic cable stations. Monitor spectrum auction timelines as the decisive inflection indicator for mobile infrastructure valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| Infrastructure-Sharing Compliance | ASEP co-location mandates enable wholesale fiber monetization without retail channel buildout. |
| Managed Security Service Launch | Ministry of Public Security data localization requirements create attach-rate expansion for compliant operators. |
| Open RAN Pilot Deployment | Multi-vendor radio access networks reduce equipment procurement dependence on integrated suppliers. |
| Edge Computing Node Installation | Colón logistics parks generate localized processing demand for customs clearance latency reduction. |
| Submarine Cable Landing Rights Acquisition | Pacific and Atlantic station access secures hemispheric bandwidth transit positioning. |
Research Methodology
A spread of perspectives from network operations executives at incumbent carriers, ASEP regulatory affairs officers, procurement leads at Colón Free Trade Zone logistics firms, and data center infrastructure managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through submarine cable landing station filings, ASEP spectrum auction documentation, and Ministry of Public Security cybersecurity framework disclosures. Bottom-up service revenue modeling triangulated against top-down infrastructure capacity estimates.
Segmentation dimensions modeled span service type, technology tier, end-user vertical, and distribution channel across the projection horizon. CAGRs derived from equipment deployment timelines, subscriber migration curves, and enterprise contract renewal patterns. Industry-specific forecast inputs include ASEP infrastructure-sharing mandate compliance rates and 5G radio access network upgrade capital expenditure trajectories.
Forecasts assume regulatory continuity in ASEP public services oversight and Ministry of Public Security cybersecurity enforcement; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Global Optical Transport Network (OTN) Equipment Market
Telecommunications Infrastructure
Global Telecom Towers Market
Telecommunications Infrastructure
China Telecom Equipment Market
Telecommunications Infrastructure
Saudi Arabia Telecom Towers Market
Telecommunications Infrastructure
Japan Telecom Market
Telecommunications Infrastructure
Slovenia Telecom Market
Telecommunications Infrastructure
United Kingdom Telecom Towers Market
Telecommunications Infrastructure
NLD and ILD Telecom Service Market
Telecommunications Infrastructure
Asia Pacific Voice Over LTE Market
Telecommunications Infrastructure
5G Network Infrastructure Market
Telecommunications Infrastructure
Telecom Network Infrastructure Market
Telecommunications Infrastructure
United States Telecom Towers Market
Telecommunications Infrastructure
Small Cell Backhaul Market
Telecommunications Infrastructure
Global Integrated Telecom Infrastructure Market
Telecommunications Infrastructure
Spain Telecom Towers Market
Telecommunications Infrastructure
Session Initiation Protocol (SIP) Trunk Market