
 Smoked Salmon Market | 2026-2036
Smoked Salmon Market Size, Share, and Industry Trends Forecast 2026-2036
Smoked Salmon Market Analysis
Automated filleting and precision cold-smoking with computer-controlled humidity and temperature profiles is reconfiguring yield economics and texture consistency across the smoked salmon value chain. SalMar ASA leverages its integrated Norwegian farming operations to control biomass from egg to plate, sustaining supply security for European retail contracts. Acme Smoked Fish Corporation anchors its position through Brooklyn-based artisanal processing heritage combined with scaled distribution into North American foodservice channels. Mowi ASA competes on global volume, operating processing plants across multiple geographies to balance seasonal supply fluctuations.
Smoked salmon comprises Atlantic or Pacific salmon fillets cured with salt and exposed to controlled smoke from wood sources such as oak or alder, with cold-smoked variants held below 30°C to preserve raw texture and hot-smoked products cooked through during the smoking process. Cold smoked formats dominate premium retail margins due to longer shelf life under vacuum sealing and delicate flavor profiles favored in European gastronomy, while hot smoked variants lead volume growth in North American club stores and casual dining applications where firmer texture and pronounced smoke intensity align with regional palates. Sliced packaging under modified atmosphere commands disproportionate margin pools in supermarket chilled cabinets, whereas whole-side and portion-cut formats concentrate in wholesale and catering channels where downstream processing flexibility carries value.
Norway's Food Safety Authority and the Scottish Environment Protection Agency enforce strict sea lice thresholds and escape prevention standards that shape farming density decisions and treatment cost structures across North Atlantic operations. The EU's REACH regulation and EFSA contaminant monitoring for polycyclic aromatic hydrocarbons in smoked fish products create compliance barriers for non-European exporters seeking supermarket shelf placement. Stakeholders must monitor evolving carbon accounting requirements under the EU Green Deal, as Scope 3 emissions from feed production and air freight increasingly influence retailer procurement criteria and consumer-facing sustainability claims.
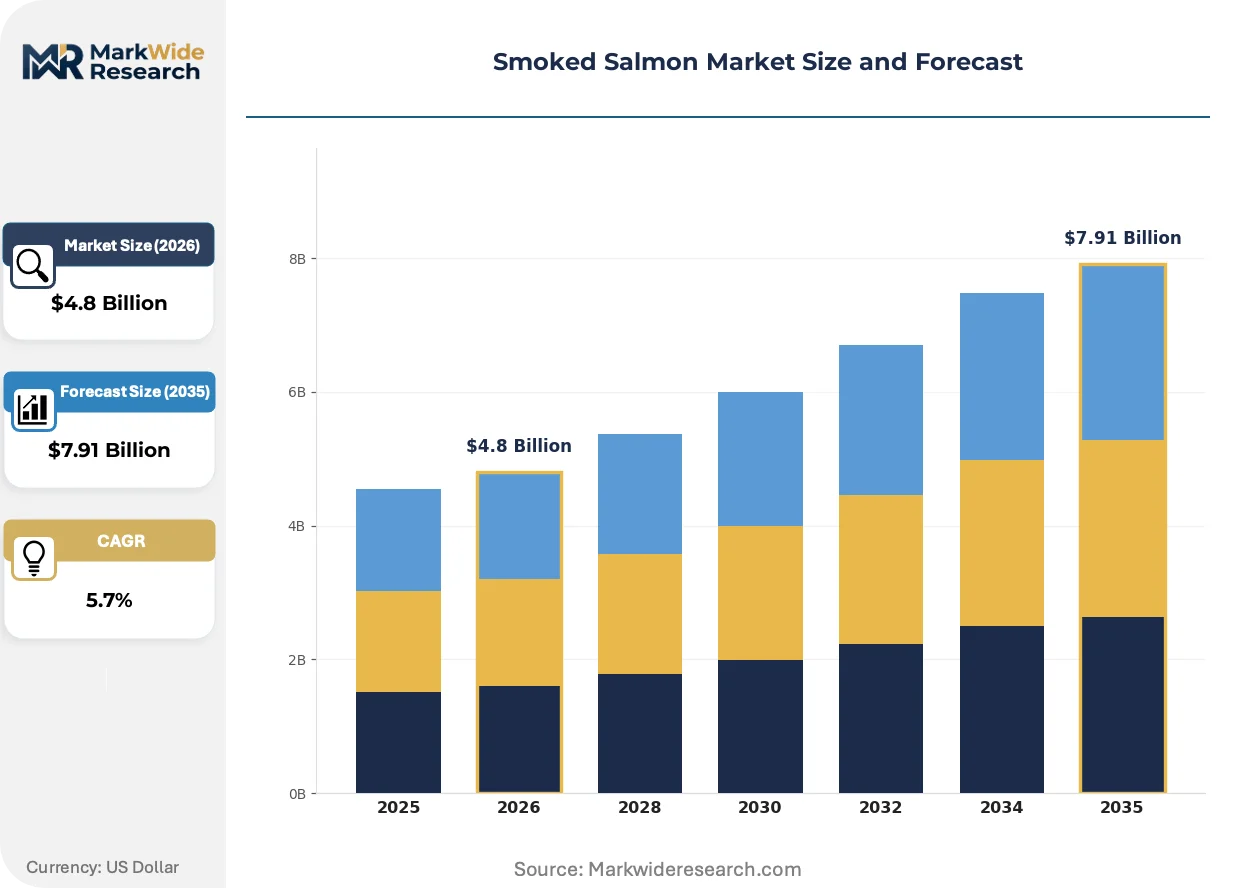
Market Dynamics
EU Green Deal carbon accounting mandates and EFSA polycyclic aromatic hydrocarbon monitoring are compressing margins for non-integrated processors while rewarding Norwegian and Scottish operators with captive biomass control.
Growth Catalysts
- Cold-smoking automation:Computer-controlled humidity and temperature profiles enable precise texture consistency that premium European retailers demand for private-label contracts.
- REACH compliance:ECHA contaminant thresholds for smoked fish products create procurement preference for EU-certified suppliers in German and French supermarket chains.
- Foodservice premiumization:London's restaurant density sustains above-average volume absorption for sliced formats in chilled deli cabinets.
Market Restraints
- Feed cost volatility:Marine and vegetable feed ingredient prices fluctuate with commodity markets, squeezing farming margins in Scottish loch operations.
- North Atlantic supply concentration:Norwegian and Scottish biomass dominance creates geographic risk if sea lice treatments disrupt harvest timing.
- Sea lice regulatory thresholds:Norway's Food Safety Authority enforcement of treatment windows limits stocking density and elevates operational costs.
Strategic Opportunities
- Modified atmosphere packaging innovation:Extended shelf-life technologies open club store penetration in North American retail channels.
- EU Green Deal tailwinds:Scope 3 emissions disclosure requirements favor vertically integrated operators with feed-to-plate carbon traceability.
- Hot-smoked format expansion:Firmer texture profiles align with casual dining and prepared meal applications in US foodservice.
Industry Challenges
- Artisanal skill scarcity:Traditional cold-smoking expertise competes with automated production lines for talent in Brooklyn and Scottish processing hubs.
- Certification timeline compression:Aquaculture Stewardship Council and national organic schemes require multi-year farm conversion before market access.
- Air freight carbon accounting:Fresh product logistics face mounting scrutiny under retailer Scope 3 procurement criteria.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smoked Salmon Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Smoked, Hot Smoked, Oak Smoked, Lemon Pepper Smoked Packaging Type: Vacuum Sealed, Canned, Fresh, Sliced Distribution Channel: Supermarkets, Online Stores, Specialty Shops, Wholesale End User: Restaurants, Retail Consumers, Catering Services, Food Manufacturers |
| Companies Covered | SalMar ASA, H Forman & Son, Acme Smoked Fish Corporation, Marine Harvest, Trident Seafoods, Mowi ASA, Multiexport Foods S.A., BSF Impex LLC, Lerøy Seafood Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smoked Salmon Market Emerging Trajectories
Automation in filleting and precision smoking systems is compressing labor dependency while regulatory carbon tracking is rewiring supplier qualification protocols across European retail procurement.
Hyperspectral imaging systems for real-time fat content and color grading are rendering obsolete manual quality inspection stations in high-volume processing plants. Norwegian integrated operators deploy these systems across filleting lines to standardize output for fixed-weight retail packs. The technology is rendering obsolete batch-to-batch variation that previously required skilled human graders.
EFSA's tightened monitoring protocols for polycyclic aromatic hydrocarbons in smoked fish products are forcing processor investment in filtered smoke generation and post-smoke surface testing. German retail chains now require documented PAH compliance certificates for shelf placement. Cold-smoked Atlantic salmon imports from non-EU origins face extended laboratory verification delays at Rotterdam and Hamburg entry points.
Buyer consolidation among European supermarket alliances is compressing supplier rosters and extending contract durations in exchange for volume commitments. British grocery multiples now run centralized chilled seafood procurement for entire national store networks. This concentration is most visible in the United Kingdom, where Tesco and Sainsbury's combined buying power dictates sliced format specifications and delivery frequency.
Smoked Salmon Market Segmentation
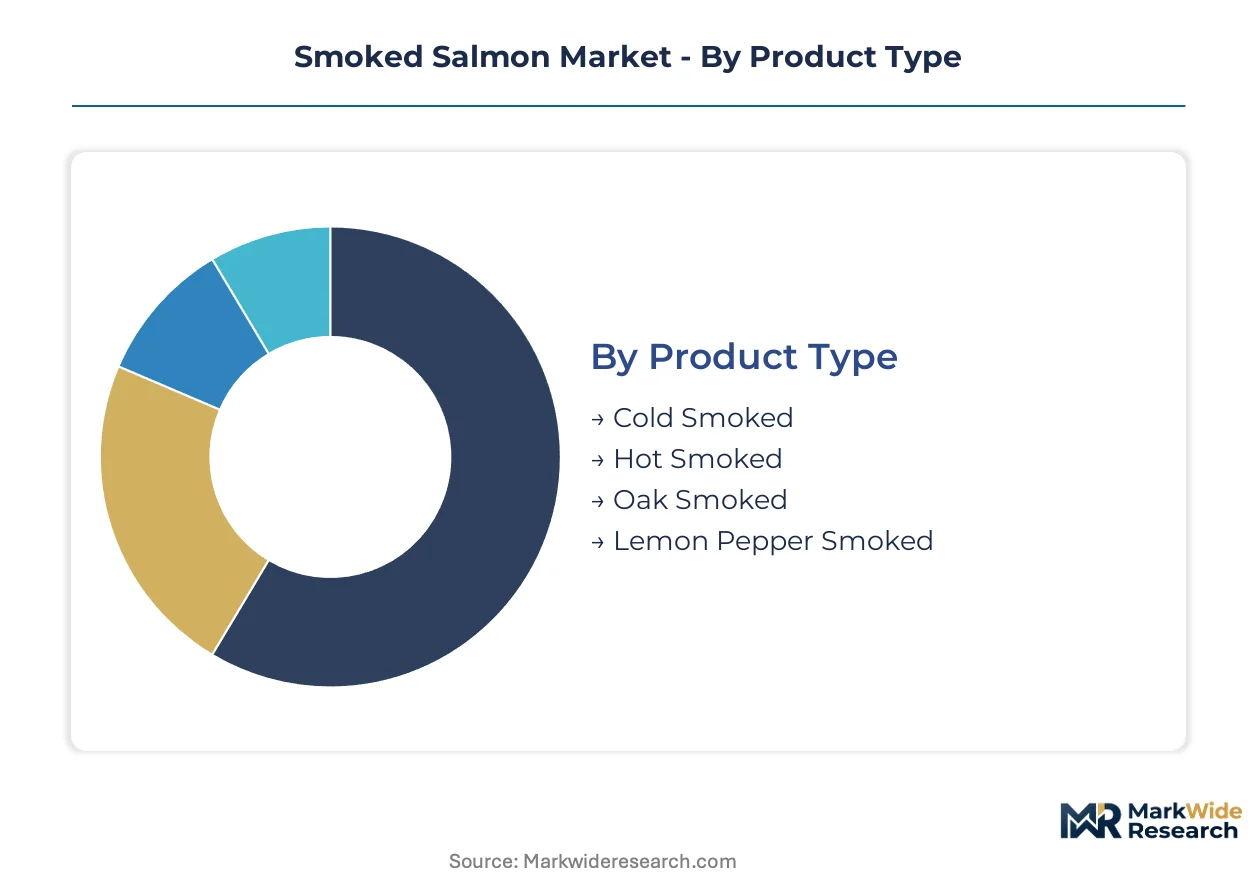
Smoked salmon producers configure operations around four distinct segmentation axes. Product format determines processing capital requirements, packaging dictates shelf-life economics, distribution channel shapes margin capture, and end-user specification drives flavor and texture engineering.
Product Type:
Use-case spectrum spans raw-consumption delicatessen formats through fully-cooked prepared meal ingredients.
- Cold Smoked:Salmon fillets cured below 30°C retain raw, silky texture prized in European gastronomy. London's restaurant density and chilled deli cabinet placement in British grocery multiples absorb disproportionate volume for private-label contracts.
- Hot Smoked:Higher-temperature exposure cooks flesh through, yielding firmer flakes suited to casual dining applications. North American club stores and US foodservice channels favor this format for prepared meal compatibility and pronounced smoke intensity.
- Oak Smoked:Hardwood smoke imparts distinctive tannic notes commanding premium positioning in specialty retail.
- Lemon Pepper Smoked:Pre-seasoned variants reduce downstream kitchen labor for catering and food manufacturing accounts.
Established volume favors cold smoked; emerging adoption favors hot smoked.
Packaging Type:
Cost tier separates premium preservation technologies from commodity containment.
- Vacuum Sealed:Oxygen exclusion extends chilled shelf life to 21-28 days, enabling centralized production for national retail distribution. Modified atmosphere variants with CO2/N2 flushing now penetrate North American club store channels seeking extended case-ready display windows.
- Sliced:Pre-portioned packs command disproportionate margin pools in supermarket chilled cabinets where labor reduction carries measurable value. British grocery multiples specify exact slice thickness and weight tolerances for automated deli counter replenishment.
- Canned:Retort sterilization enables ambient distribution to remote foodservice nodes and emergency catering reserves.
- Fresh:Unprocessed whole sides concentrate in wholesale and catering channels where downstream flexibility outweighs convenience premium.
Margin concentration sits with sliced; volume scale sits with vacuum sealed.
Distribution Channel:
Customer type determines service intensity and payment term structures.
- Supermarkets:National chains in the United Kingdom and Germany consolidate procurement through centralized chilled seafood buying desks. Tesco and Sainsbury's combined specifications for sliced format delivery frequency now dictate supplier scheduling across North Atlantic processing plants.
- Wholesale:Foodservice distributors absorb whole-side and portion-cut formats for downstream catering and restaurant processing flexibility.
- Specialty Shops:Curated assortments of oak-smoked and artisanal variants serve premium urban consumers in Brooklyn and Edinburgh.
- Online Stores:Direct-to-consumer fulfillment demands insulated packaging investment for temperature integrity in last-mile logistics.
Procurement consolidation favors supermarkets; margin recovery favors specialty shops.
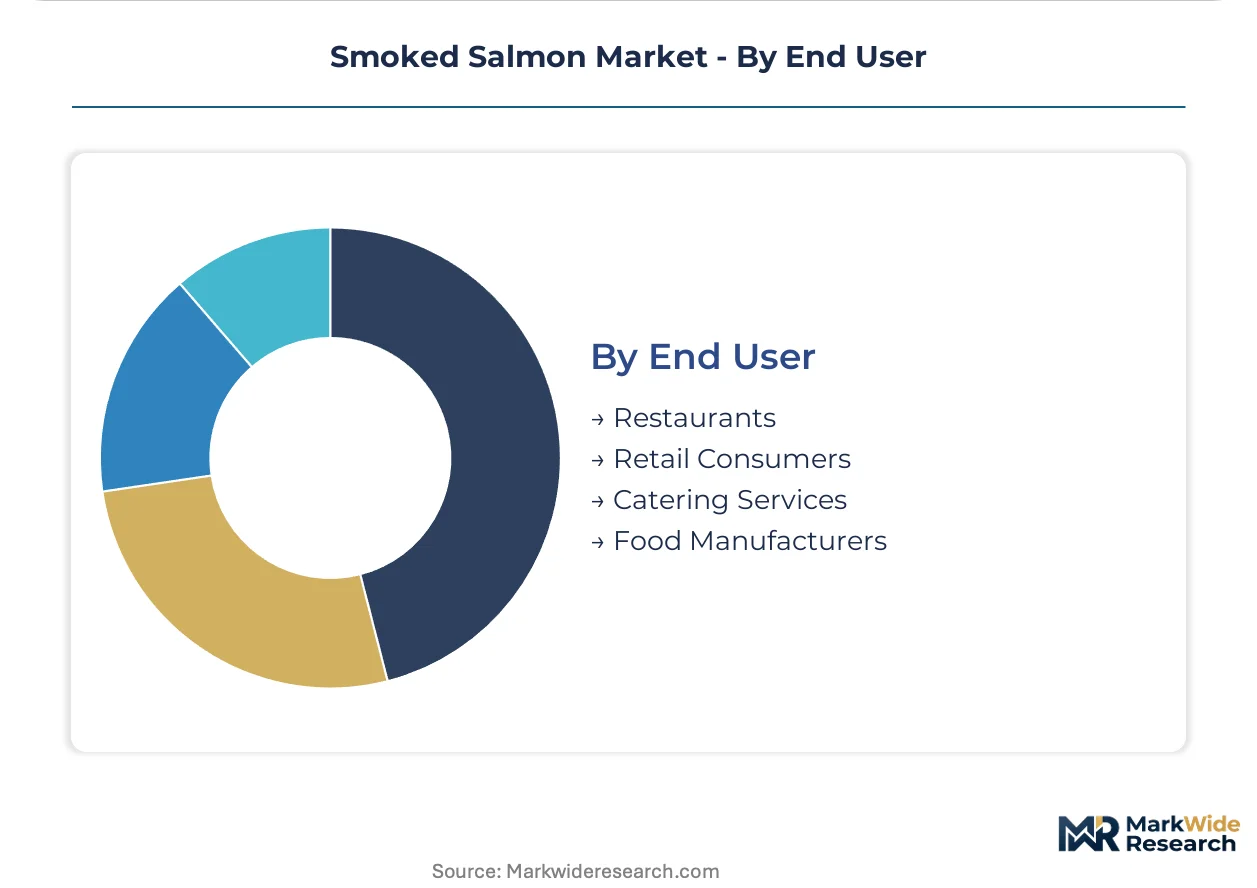
End User:
Application maturity separates developed foodservice demand from emerging prepared meal manufacturing.
- Restaurants:London's foodservice density sustains above-average absorption for cold-smoked sliced formats in fine-dining and fast-casual applications alike. Plated presentation requirements drive exacting color and fat content specifications.
- Retail Consumers:Home consumption concentrates in weekend brunch occasions and holiday entertaining, with vacuum-sealed packs dominating refrigerator staple purchases.
- Catering Services:Volume events demand consistent portion control and extended holding stability under buffet conditions.
- Food Manufacturers:Ingredient supply for prepared salads, sandwiches, and ready meals requires flake-resistant texture and standardized yield rates.
Volume scale favors restaurants; specification intensity favors food manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian exporters dominate Atlantic salmon flows into German and British retail channels, while Scottish processors supply London's foodservice density and French gastronomy markets. Trade corridors concentrate biomass movement from North Atlantic farming zones into European Union chilled distribution networks.
Norway
Oslo-listed integrated operators control egg-to-plate biomass chains for continental supermarket contracts. The Norwegian Food Safety Authority enforces strict sea lice treatment windows that elevate operational compliance costs. Bergen and Trøndelag processing clusters deploy precision cold-smoking automation for fixed-weight retail packs destined for Hamburg and Rotterdam entry points.
United Kingdom
London's restaurant density absorbs disproportionate volumes of sliced cold-smoked formats for deli cabinet placement. The Food Standards Agency applies EFSA-aligned polycyclic aromatic hydrocarbon monitoring protocols for domestic processors. Scottish loch farming in the Highlands and Islands feeds Grimsby and Peterhead smoking facilities serving Tesco and Sainsbury's national procurement networks.
Germany
Discounter and premium supermarket chains consolidate smoked salmon procurement through centralized chilled seafood buying desks. ECHA REACH contaminant thresholds create documented compliance requirements for shelf placement authorization. Hamburg port facilities handle laboratory verification delays for non-EU cold-smoked imports seeking distribution into Bavarian and North Rhine-Westphalia retail regions.
United States
Brooklyn-based artisanal heritage anchors specialty retail positioning while scaled distributors penetrate club store channels. FDA seafood HACCP regulations govern cold-smoked processing safety protocols for interstate commerce. Pacific Northwest processing nodes in Washington and Alaska balance seasonal supply fluctuations for foodservice distributors serving New York Metro and California demand clusters.
France
Parisian gastronomy channels sustain premium absorption for oak-smoked and traditional cured formats. ANSM enforces EU harmonized food safety standards with particular scrutiny on imported smoked fish contaminant profiles. Brittany and Normandy coastal processing facilities supply Île-de-France retail networks with regionally branded salmon products.
Smoked Salmon Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated Norwegian operators with captive biomass control, while fragmented artisanal processors occupy premium urban niches. Three strategic archetypes dominate: North Atlantic integrated farming-smoking conglomerates, Brooklyn-anchored heritage smokehouses with scaled distribution arms, and Chilean volume exporters serving price-sensitive retail tiers. Competitive moves concentrate on backward integration into feed production and automated filleting capacity expansion.
Within the integrated archetype, SalMar ASA and Mowi ASA exemplify egg-to-plate biomass control strategies that secure European retail contract stability. Acme Smoked Fish Corporation occupies a distinct position combining Brooklyn artisanal heritage with North American foodservice channel penetration. Among specialist smokehouses, H Forman & Son represents London-anchored premium positioning sustained by British grocery multiple supply relationships.
| Leading Market Players |
|---|
| SalMar ASA |
| H Forman & Son |
| Acme Smoked Fish Corporation |
| Marine Harvest |
| Trident Seafoods |
| Mowi ASA |
| Multiexport Foods S.A. |
| BSF Impex LLC |
| Lerøy Seafood Group |
| Others |
Supply Flow & Price Mechanics
Norwegian and Scottish farming concentration upstream anchors margin capture at the processing and branded retail tiers downstream. Cold-smoked formats command premium positioning through vacuum-sealed shelf-life extension, while hot-smoked variants compete on volume scale in North American club stores.
Pricing Analysis
Automation-generation pricing gaps separate precision cold-smoking facilities with computer-controlled humidity systems from legacy smokehouse operations still dependent on manual grading. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and geographic origin, with Aquaculture Stewardship Council-certified Norwegian biomass commanding measurable premiums over conventional Scottish supply. Pricing pressure stems from feed cost volatility in marine and vegetable ingredient markets, squeezing farming margins before processing value-add. Foodservice distributors exhibit highest price sensitivity due to contract bidding cycles, while specialty retail channels absorb premiums for provenance storytelling.
Supply Chain Analysis
Contract manufacturing concentration sits with integrated Norwegian operators SalMar ASA and Mowi ASA controlling captive biomass from egg to plate, supplemented by Scottish loch farming clusters around the Highlands and Islands. Atlantic salmon smolt, marine feed formulations, and oak/alder hardwood smoke sources constitute critical input dependencies. Single-source vulnerability concentrates in North Atlantic farming zones where sea lice treatment windows can disrupt harvest timing across entire regional cohorts. Distribution runs through centralized chilled seafood procurement desks at British grocery multiples, with Rotterdam and Hamburg port facilities handling continental EU entry verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward consolidated supermarket alliances in the United Kingdom and Germany, where Tesco and Sainsbury's combined specifications now dictate supplier scheduling and delivery frequency terms.
For Market Incumbents: Insulate contract stability through backward integration into feed production and precision smoking automation capacity expansion. Norwegian integrated operators should secure biomass control against emerging Chilean volume exporters, while investing in filtered smoke generation systems to preempt EFSA polycyclic aromatic hydrocarbon compliance barriers. Certification maintenance under national organic schemes and Aquaculture Stewardship Council standards preserves shelf placement authorization. For New Entrants and Emerging Players: Hot-smoked format penetration in North American casual dining and prepared meal manufacturing represents the most penetrable entry point for non-integrated processors. Mid-tier private-label supply to German discounter chains offers volume scale without premium positioning requirements. Direct-to-consumer fulfillment through insulated last-mile packaging targets urban specialty consumers in Brooklyn and Edinburgh underserved by mass retail distribution. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated farming-smoking conglomerates with captive biomass control and established European retail contract relationships. Long-term viability hinges on carbon traceability capabilities under EU Green Deal Scope 3 disclosure requirements. The signal to watch is retailer procurement criteria evolution toward feed-to-plate emissions accounting, favoring operators with documented supply chain transparency.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Cold-Smoking Automation | Computer-controlled humidity systems standardize texture for fixed-weight retail packs demanded by British grocery multiples. |
| Backward Integration into Feed Production | In-house marine and vegetable ingredient sourcing buffers margin compression from commodity market volatility. |
| Modified Atmosphere Packaging Innovation | Extended shelf-life CO2/N2 flushing technologies enable club store penetration in North American retail channels. |
| Aquaculture Stewardship Council Certification | Documented compliance opens shelf placement in German and French supermarket chains with tightened procurement criteria. |
| Hot-Smoked Format Capacity Expansion | Firmer texture profiles align with casual dining applications and prepared meal manufacturing in US foodservice. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EU customs trade data, Norwegian Food Safety Authority harvest reports, and SEC filings from listed aquaculture operators. Interviews with processing plant managers, chilled seafood procurement directors at British grocery multiples, and foodservice distribution channel partners informed operational cost structures and contract term dynamics. Secondary validation drew from EFSA contaminant monitoring databases, ECHA REACH compliance registries, and supermarket private-label specification sheets. Bottom-up volume modeling triangulated against top-down value projections across the analysis window.
Forecast inputs incorporate smoking format adoption curves, packaging technology penetration rates, and regulatory compliance cost trajectories. Segmentation dimensions span product type, packaging configuration, distribution channel, and end-use application, with geographic regulatory clustering for EU, US, and North Atlantic supply zones. CAGRs derive from historical volume trajectory analysis adjusted for feed cost elasticity and buyer consolidation effects. Industry-specific inputs include sea lice treatment frequency data and carbon accounting disclosure timelines under EU Green Deal implementation.
Practitioners should monitor feed ingredient commodity indices, sea lice treatment window enforcement patterns, and retailer Scope 3 procurement criteria activation for early signals of forecast revision. Quarterly review of EFSA polycyclic aromatic hydrocarbon alert levels and supermarket alliance buying desk consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
United States Seafood Market
Seafood
Fried Dace with Salted Black Beans Market
Seafood
Shellfish Extract Market
Seafood
Salmon Market
Seafood
North America Frozen and Canned Seafood Market
Seafood
North America Salmon Market
Seafood
Organic Salmon Market
Seafood
China Crustaceans Market
Seafood
Fish Powder Market
Seafood
COD Market
Seafood
Fin Fish Market
Seafood
Europe Shrimp Market
Seafood
Asia-Pacific Seafood Market
Seafood
Canned Tuna Market
Seafood
US Crustacean Market
Seafood
Japan Lobster Market