
 Missouri Medical Cannabis Market | 2026-2036
Missouri Medical Cannabis Market Size, Share, and Industry Trends Forecast 2026-2036
Missouri Medical Cannabis Market Intelligence
Chronic pain patients are redrawing demand patterns across the Missouri Medical Cannabis Market as qualifying condition expansions broaden the addressable patient base. Proper Cannabis leverages vertical integration from cultivation to retail to sustain margin control across its operations. Illicit Gardens anchors its competitive position through craft flower specialization and limited-batch genetics that command premium shelf placement in dispensaries.
Missouri medical cannabis comprises state-licensed marijuana cultivated, processed, and dispensed under constitutional amendment authority for qualifying patients, with products tested for potency, microbial contaminants, and residual solvents before retail release. The market serves therapeutic applications including chronic pain management, seizure disorders, and psychiatric symptom relief under physician supervision. Flower dominates current product mix as the entry format for new patients, while concentrates capture expanding share among experienced users seeking higher potency per dollar. Tinctures represent the fastest-growing delivery category as sublingual dosing gains traction among patients avoiding inhalation. The caregiver segment structures bulk purchasing behavior, with designated providers controlling multi-patient acquisition volumes that shape wholesale pricing tiers.
Missouri Department of Health and Senior Services oversees licensing, product testing standards, and dispensary compliance through rules aligned with Article XIV constitutional provisions. Metrc tracking mandates create operational barriers for unlicensed supply while reinforcing product provenance verification for patients and regulators. Stakeholders must monitor potential statutory revisions to possession limits, home cultivation rights, and reciprocity agreements with neighboring states as political majorities shift in Jefferson City.
Market Dynamics
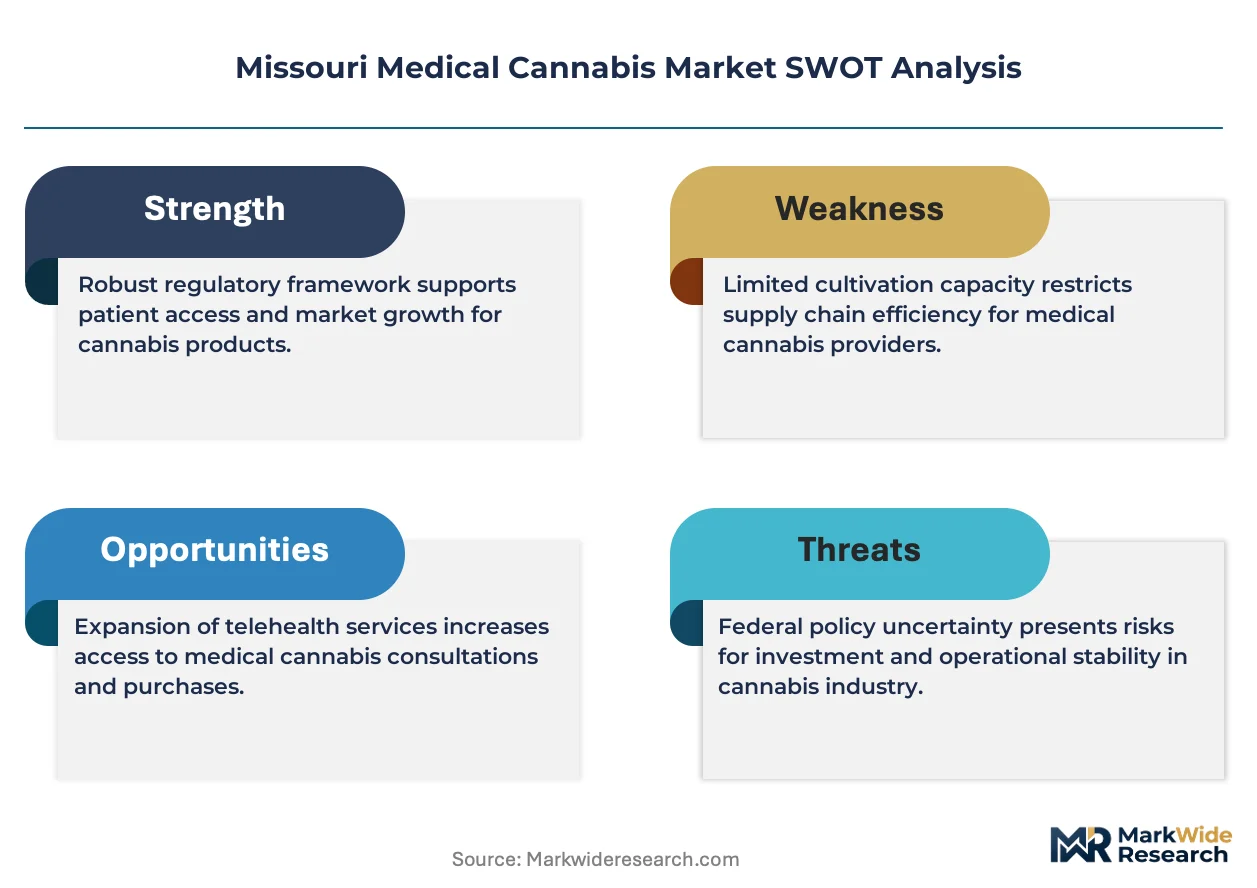
Metrc seed-to-sale tracking mandates are compressing operational margins for Missouri cultivators while simultaneously erecting compliance barriers that favor capitalized multi-facility operators over single-license competitors.
Growth Catalysts
- Chronic pain qualification expansion:Missouri's broadening list of qualifying medical conditions under Article XIV constitutional provisions is enlarging the addressable patient pool faster than any other buyer segment.
- St. Louis corridor concentration:The metropolitan statistical area's superior physician certification density and dispensary accessibility is creating self-reinforcing demand gravity that pulls rural patients into urban procurement zones.
- Metrc compliance infrastructure:State-mandated tracking systems are professionalizing supply chain transparency, enabling compliant operators to differentiate against legacy market alternatives through verified product provenance.
Market Restraints
- Capital intensity for vertical buildout:Missouri regulations require separate licensing for cultivation, processing, and retail, forcing operators to deploy substantial capital across three facility categories or accept margin leakage to wholesale intermediaries.
- Testing bottleneck concentration:The state has approved limited independent testing laboratories, creating queue congestion that delays product release and compresses cash conversion cycles for cultivators.
- Home cultivation substitution:Constitutional patient cultivation rights allow qualifying individuals to grow up to six flowering plants, siphoning volume from commercial flower sales among price-sensitive long-term patients.
Strategic Opportunities
- Caregiver network formalization:Missouri's designated caregiver provisions permit bulk purchasing across multiple patients, creating wholesale-scale demand aggregation that rewards operators with flexible volume pricing architectures.
- Tincture sublingual adoption:Patients avoiding inhalation are migrating toward tincture formats, opening formulation specialization opportunities for processors with extraction and emulsion capabilities.
- Concentrate potency premium capture:Experienced patient segments demonstrate willingness to pay elevated per-gram prices for high-THC concentrates, rewarding processors with hydrocarbon or solventless extraction expertise.
Industry Challenges
- Metrc integration complexity:Cultivators and dispensaries must reconcile legacy inventory management systems with state-mandated RFID tracking, requiring specialized IT expenditure and staff retraining.
- Batch consistency certification:Missouri Department of Health and Senior Services testing protocols for potency variance and microbial screening create failure-rate risk that can invalidate entire harvests.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Missouri Medical Cannabis Market |
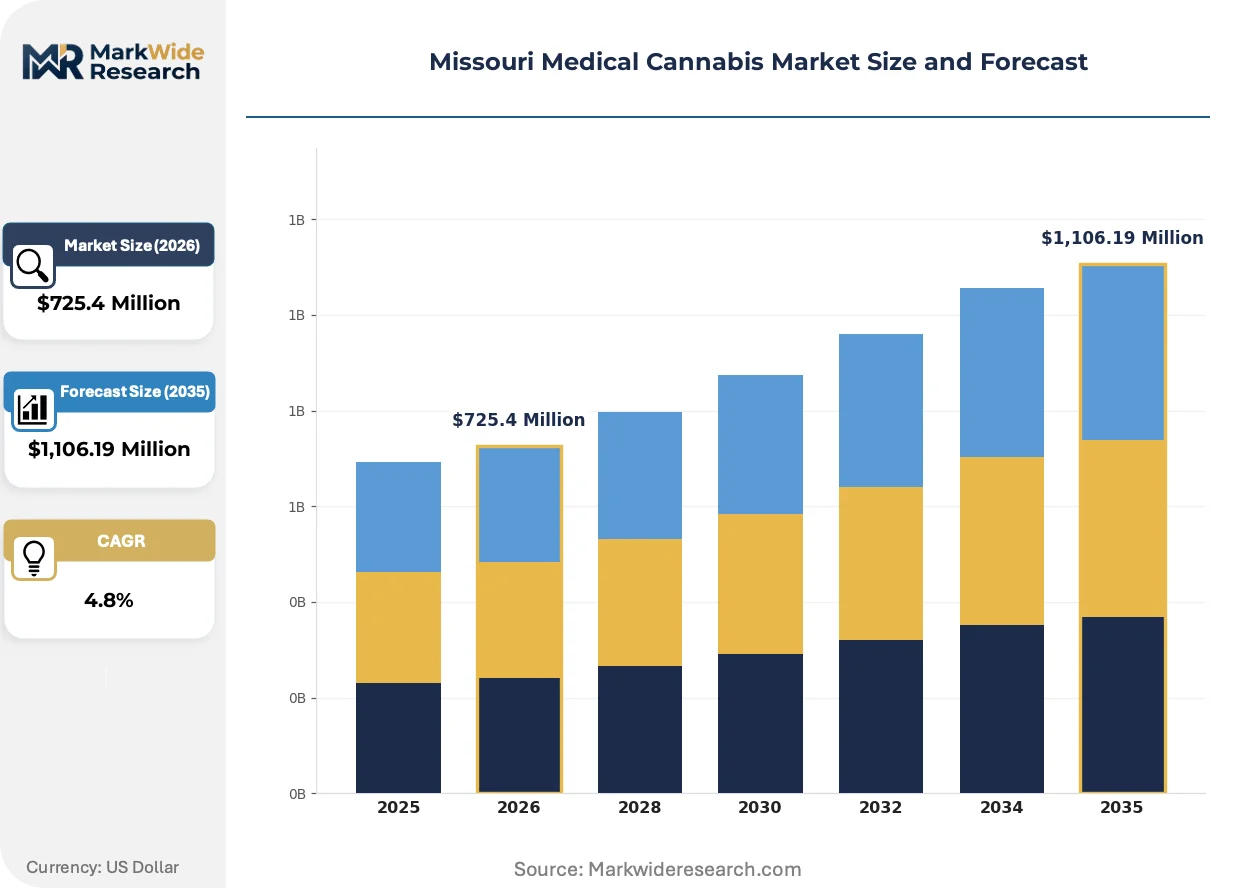
| Market Size in 2026 | $725.4 Million |
| Market Size in 2035 | $1,106.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flower, Concentrates, Edibles, Tinctures Use Case: Chronic Pain, Anxiety, Insomnia, Epilepsy Delivery Mode: Vaping, Ingestion, Sublingual, Topical Customer Type: Patients, Caregivers, Dispensaries, Physicians |
| Companies Covered | Illicit Gardens, STIIIZY, Proper Cannabis, Organic Remedies, BeLeaf Medical, Blue Sage Cannabis Co., Amaze Cannabis, Show Me Alternatives, Heya Wellness, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Missouri Medical Cannabis Market Strategic Shifts & Innovations
Missouri's medical cannabis sector is experiencing rapid format diversification as patient sophistication increases and processors compete on delivery mechanism differentiation rather than raw flower commoditization.
Portable vaporizer hardware is miniaturizing consumption rituals for Missouri patients seeking discretion in workplace and public settings. Younger demographic segments are adopting pod-based systems at accelerating rates. This technology compression is enabling retail formats to capture premium shelf space previously dominated by traditional combustion accessories.
Article XIV constitutional provisions are stabilizing after initial implementation volatility, with Missouri Department of Health and Senior Services rulemaking now concentrating on operational refinements rather than structural overhauls. Dispensary licensing caps are creating scarcity value for existing permit holders. St. Louis and Kansas City operators are responding by locking in extended lease terms to secure location advantages.
Caregiver-mediated procurement is restructuring volume relationships between wholesale cultivators and end patients. Multi-patient designated providers are consolidating demand into bulk purchasing agreements that bypass retail markup structures. This channel disintermediation is most visible in rural Missouri counties where dispensary density remains insufficient to serve dispersed patient populations.
Missouri Medical Cannabis Market Segmentation
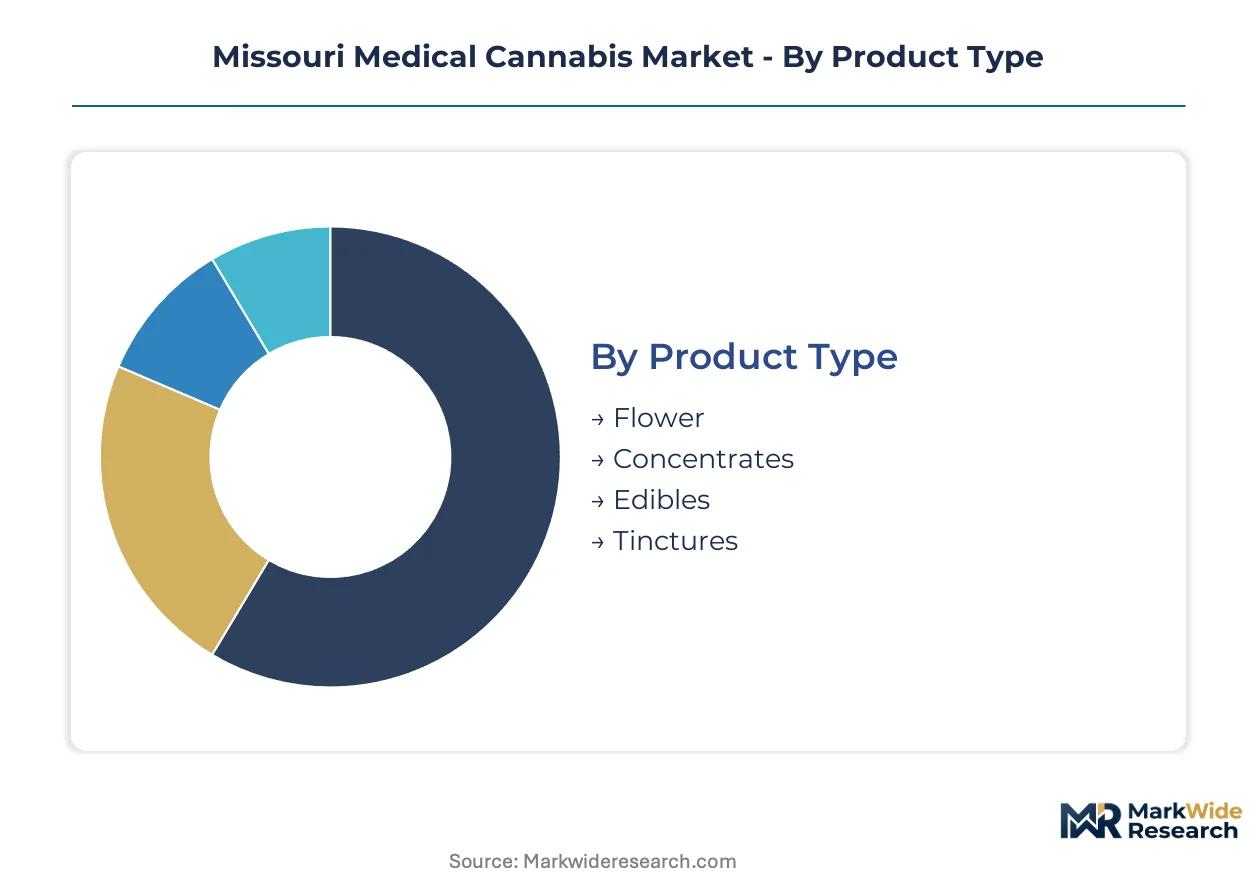
Missouri's medical cannabis market fragments across product chemistry, therapeutic application, and procurement channel. Each segmentation axis reveals distinct margin profiles and regulatory exposure that shape operator strategy.
Product Type:
Domestic cultivation supplies all product categories, with no legal export pathway from Missouri's closed system. Import substitution is prohibited by constitutional mandate.
- Flower:Dried and cured cannabis buds retain the highest volume share across Missouri dispensaries. Entry-level patients in the St. Louis corridor default to this familiar format, though home cultivation rights compress commercial pricing power for standardized strains.
- Concentrates:Extracted oils, waxes, and shatter deliver elevated THC potency per unit weight. Experienced users in Kansas City and Columbia metro areas drive demand for hydrocarbon and solventless variants that command wholesale premiums above raw flower benchmarks.
- Edibles:Infused food products require licensed processing facilities with kitchen-grade sanitation certification under Missouri Department of Health and Senior Services rules.
- Tinctures:Alcohol or oil-based sublingual formulations attract patients avoiding inhalation, with demand climbing fastest among older demographics seeking precise dosing control.
Flower commands the established base. The steepest expansion runs through tinctures.
Use Case:
Cost tier stratification separates high-frequency chronic conditions from episodic symptom management, with reimbursement-adjacent documentation requirements varying by indication.
- Chronic Pain:Persistent pain conditions generate the highest patient enrollment volumes under Article XIV expansion protocols. Missouri physicians certify these cases at rates exceeding seizure and psychiatric indications combined, concentrating demand in suburban St. Louis and Jackson County clinics.
- Anxiety:Qualifying psychiatric symptom relief requires specific diagnostic documentation that slows certification velocity relative to pain pathways. Younger patient cohorts in university-adjacent markets drive concentrate preference for rapid onset.
- Insomnia:Sleep disorder qualification depends on documented failure of conventional pharmacotherapy, creating a narrower addressable pool with higher per-patient spending on sustained-release edibles.
- Epilepsy:Pediatric and intractable seizure cases were the original constitutional mandate focus, now representing a mature, stable prescription base with strong caregiver involvement.
Chronic pain dominates volume concentration. Anxiety shows the fastest certification velocity among expanding indications.
Delivery Mode:
Volume throughput concentrates in inhalation formats, while margin accretion favors non-combustible alternatives that bypass home cultivation substitution.
- Vaping:Heated oil or flower vaporization delivers rapid cannabinoid absorption without combustion byproducts. Pod-based hardware miniaturization is reshaping procurement patterns among employed patients seeking workplace discretion.
- Ingestion:Gastrointestinal absorption through edibles or capsules provides extended duration effects preferred for overnight symptom management. Onset latency of 60-120 minutes limits use cases despite superior duration.
- Sublingual:Mucosal absorption under the tongue bridges speed and duration, with tincture formulations capturing share from patients dissatisfied with inhalation harshness or edible unpredictability.
- Topical:Transdermal creams and patches address localized inflammation without systemic psychoactivity, occupying a niche in athletic and geriatric segments.
Vaping anchors current throughput. Sublingual delivery is climbing the fastest as patient sophistication matures.
Customer Type:
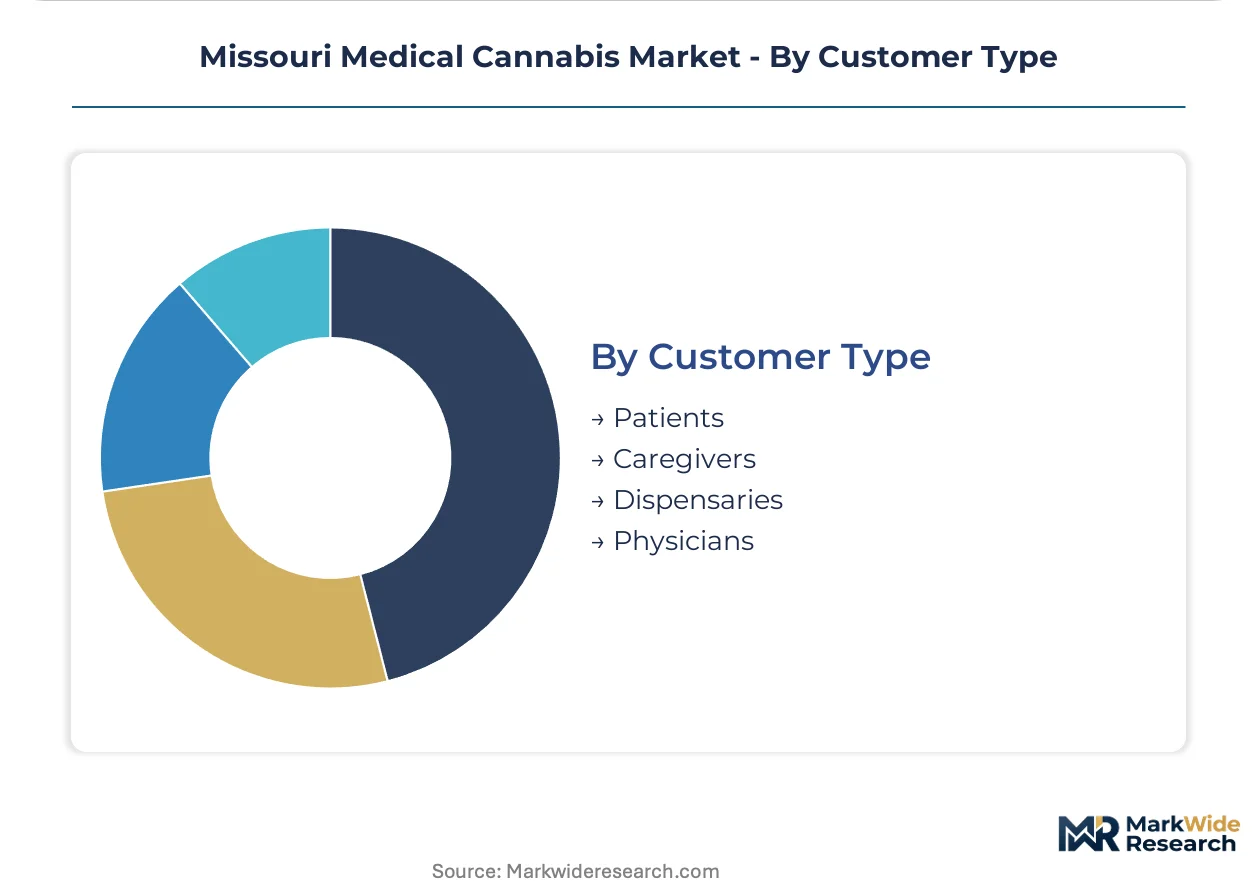
Procurement authority fragments between individual patients and designated intermediaries, with bulk purchasing behavior reshaping wholesale pricing architecture.
- Patients:Individual qualifying consumers hold direct purchasing rights at licensed dispensaries. First-time certification growth in St. Louis and Kansas City metros sustains retail foot traffic and new-patient onboarding costs.
- Caregivers:Designated providers may acquire product for up to three patients under Missouri rules, consolidating demand into volume-tiered transactions that bypass retail markup. Rural counties with sparse dispensary density depend on this channel.
- Dispensaries:Licensed retailers control final patient access and product curation, with location scarcity under constitutional caps creating defensive moats for incumbent permit holders.
- Physicians:Certifying practitioners function as gatekeepers rather than direct purchasers, with their recommendation patterns determining addressable market expansion velocity.
Individual patients command the established base. Caregiver-mediated procurement is gaining share fastest in underserved geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Interstate 70 and Interstate 44 corridors anchor Missouri's medical cannabis distribution infrastructure, connecting cultivation zones in central Missouri to patient populations concentrated in the state's two major metropolitan hubs.
St. Louis Metropolitan Corridor
Chronic pain certification rates and dispensary accessibility drive demand concentration in this eastern Missouri hub. Article XIV constitutional provisions establish licensing caps that create scarcity value for incumbent permit holders. The corridor's physician certification density exceeds rural counties by multiples, pulling dispersed patients into urban procurement zones.
Kansas City Metro
Cross-state patient mobility and Jackson County's elevated dispensary penetration sustain competitive pricing pressure. Missouri Department of Health and Senior Services oversight applies uniform testing standards regardless of proximity to the Kansas border. The metro's processing facility concentration supports concentrate production for experienced user segments.
Central Missouri Cultivation Belt
Lower real estate costs and agricultural zoning flexibility attract multi-facility cultivation operations. Metrc seed-to-sale tracking mandates apply equally across all licensed facilities regardless of location. The region's warehouse conversion activity is expanding climate-controlled grow space faster than coastal state comparables.
Southwest Missouri
Springfield's emerging dispensary cluster serves a catchment area extending into rural counties with sparse physician certification. Caregiver-mediated procurement dominates patient access in outlying areas where retail density remains insufficient. The region's testing laboratory queue congestion delays product release cycles compared to St. Louis benchmarks.
Mid-Missouri Corridor
Columbia's university-adjacent market exhibits younger demographic skew toward concentrate and vaporizer formats. Home cultivation rights under Article XIV compress commercial flower pricing power among price-sensitive long-term patients. The corridor's position between Kansas City and St. Louis creates wholesale distribution advantages for processors serving both metros.
Missouri Medical Cannabis Market Key Industry Players
Listed leaders compete with private specialists across licensing tier access, with capitalized multi-facility operators facing off against single-license craft cultivators. Missouri's separate licensing requirements for cultivation, processing, and retail create structural pressure toward consolidation or strategic alliance formation. Three archetypes dominate: vertically integrated operators controlling supply chain stages, craft specialists emphasizing limited-batch genetics, and retail-focused dispensary chains sourcing through wholesale agreements. Dominant competitive moves include facility expansion to capture additional license categories and lease term extensions to secure location advantages under constitutional caps.
Within the craft specialization tier, Illicit Gardens and Amaze Cannabis exemplify operators competing through genetic differentiation rather than scale economics. Proper Cannabis occupies a position representing vertical integration from cultivation through retail, while BeLeaf Medical anchors the caregiver-accessible distribution vector. STIIIZY sits within the hardware-anchored brand extension archetype, leveraging portable vaporizer format adoption among employed patients seeking discretion.
| Leading Market Players |
|---|
| Illicit Gardens |
| STIIIZY |
| Proper Cannabis |
| Organic Remedies |
| BeLeaf Medical |
| Blue Sage Cannabis Co. |
| Amaze Cannabis |
| Show Me Alternatives |
| Heya Wellness |
| Others |
Cost & Logistics Intelligence
Metrc seed-to-sale tracking mandates from Missouri Department of Health and Senior Services gate both operational qualification and price differentiation simultaneously, as compliant operators leverage verified provenance to command premiums while non-compliant supply faces exclusion from legal channels.
Pricing Analysis
Volume-discount tiering structures dominate caregiver-mediated procurement, with designated providers consolidating multi-patient demand into wholesale-scale agreements that bypass retail markup. Price differentiation hinges on genetic rarity and batch-limited craft positioning versus standardized greenhouse supply. Cost compression in mid-tier flower intensifies as home cultivation rights siphon price-sensitive long-term patients. Chronic pain patients show highest price sensitivity, while concentrate buyers seeking hydrocarbon extraction quality demonstrate lowest.
Supply Chain Analysis
Strategic stockpile preferences prevail among multi-facility operators buffering against Metrc compliance delays and testing laboratory queue congestion. Domestic cultivation supplies all product categories, with no legal import pathway permitted under Article XIV constitutional provisions. Raw material dependencies center on specialized lighting systems, climate control infrastructure, and proprietary genetics. Single-source vulnerability concentrates in the limited approved independent testing laboratory network. Distribution runs through licensed dispensaries capped by constitutional scarcity provisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Missouri medical cannabis incumbents face substitution defense imperatives as unlicensed legacy market supply and patient home cultivation rights erode commercial volume capture.
For Market Incumbents: Shield margin position through backward integration into cultivation capacity and processing capabilities, eliminating wholesale intermediary leakage. Lock extended lease terms under constitutional dispensary caps to secure location moats against permit scarcity relaxation. Prioritize caregiver network formalization to capture bulk purchasing volume that bypasses retail markup structures.
For New Entrants and Emerging Players: Differentiate on craft genetics specialization and limited-batch positioning that commands shelf space premiums unavailable to commoditized greenhouse operators. Target rural counties with sparse dispensary density where caregiver-mediated procurement dominates patient access. Pursue tincture formulation specialization as the fastest-expanding delivery category among patients avoiding inhalation.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multi-facility vertical buildout as separate licensing requirements for cultivation, processing, and retail force capital deployment across three facility categories. Favor acquisition targets with existing Metrc compliance infrastructure and established caregiver channel relationships. Watch statutory revision signals on possession limits and home cultivation rights as inflection indicators for commercial volume trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Caregiver Network Formalization | Captures bulk purchasing volume aggregation that rewards flexible pricing architectures in rural counties. |
| Tincture Formulation Specialization | Addresses fastest-growing delivery category as sublingual dosing gains traction among patients avoiding inhalation. |
| Extended Lease Term Lock-in | Secures location advantages under constitutional dispensary caps that create scarcity value for incumbent permit holders. |
| Genetic Differentiation Investment | Commands premium shelf placement through limited-batch craft positioning unavailable to standardized supply. |
| Metrc Compliance Infrastructure | Erects operational barriers against unlicensed competitors while enabling verified provenance differentiation. |
Research Approach
A standing panel of dispensary operations directors, cultivation facility managers, caregiver network coordinators, and Missouri Department of Health and Senior Services compliance officers provided ongoing calibration across the research cycle. Primary fieldwork combined structured interviews with these stakeholder categories against secondary validation through state regulatory filings, Metrc system utilization reports, and Article XIV constitutional implementation records. Bottom-up patient enrollment and product flow estimates triangulated against top-down market sizing from licensed facility capacity and testing laboratory throughput data.
Consistency checks validated volume and value outputs against external benchmarks including comparable state medical cannabis market maturation curves and caregiver-mediated procurement patterns in adjacent jurisdictions. The analytical framework modeled segmentation dimensions across product chemistry, therapeutic application, procurement channel, and metropolitan corridor concentration across the projection horizon. CAGRs derived from patient enrollment velocity, qualifying condition expansion rates, and format migration patterns among experienced user segments.
Material uncertainties — statutory revisions to possession limits, home cultivation rights, and reciprocity agreements — sit outside the modeled envelope. Forecasts reflect assumptions on physician certification velocity and testing laboratory capacity expansion. Revision becomes warranted when legislative action on constitutional provisions crosses thresholds altering addressable patient base or supply chain compliance requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Synthetic Cannabinoids Market
Cannabis/Marijuana
Australia Medicinal Cannabis Testing Market
Cannabis/Marijuana
US Medical Marijuana Market
Cannabis/Marijuana
Butane Hash Oil Market
Cannabis/Marijuana
CBD-Infused Products Market
Cannabis/Marijuana
Global Cannabis Market
Cannabis/Marijuana
Middle East and Africa CBD Patch Market
Cannabis/Marijuana
Cannabinoid Therapy Market
Cannabis/Marijuana
Middle East and Africa Cannabidiol (CBD) Market
Cannabis/Marijuana
Cannabidiol Extract Market
Cannabis/Marijuana
Europe CBD Oil Market
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
Latin America and Caribbean Hemp-Derived Cannabidiol Market
Cannabis/Marijuana
Germany and Netherlands Medical Marijuana Market
Cannabis/Marijuana
US Cannabis Market
Cannabis/Marijuana
North America Legal Cannabis Market