
 North America Cannabidiol (CBD) Vape Juice Market | 2026-2036
North America Cannabidiol (CBD) Vape Juice Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cannabidiol (CBD) Vape Juice Market Analytics
Canada is narrowing its position as a controlled-supply hub for hemp-derived CBD inputs entering North American vape juice manufacturing. CBDfx leverages backward integration into hemp sourcing to secure batch consistency for its e-liquid lines. Charlotte's Web anchors its competitive stance through pharmacist-facing educational programs that build prescriber confidence. Green Roads differentiates via third-party laboratory transparency, publishing full cannabinoid profiles per SKU.
North America Cannabidiol (CBD) Vape Juice comprises propylene glycol or vegetable glycerin-based carrier fluids infused with hemp-derived cannabidiol extract, typically vaporized at temperatures between 180°C and 220°C for pulmonary absorption without combustion byproducts. The product serves consumers seeking rapid-onset cannabinoid delivery for anxiety management, sleep support, or nicotine replacement protocols. Full spectrum formulations retain trace terpenes and minor cannabinoids that command premium shelf positioning, while isolate-based SKUs compete on standardization and THC-free assurance. Distribution through specialty shops captures the highest-margin transactions, though online stores now aggregate the largest volume share across the region.
The FDA maintains prohibitions on CBD-infused food and dietary supplement claims, creating jurisdictional friction with state cannabis regulators in Colorado and Oregon that permit broader retail access. Health Canada enforces strict THC caps and packaging standards under the Cannabis Act, forcing cross-border product line divergence. Farm Bill compliance testing for delta-9 THC concentration shapes raw material procurement geography. Stakeholders must monitor pending federal rescheduling proceedings and corresponding state tax code adjustments that would recast interstate commerce economics.
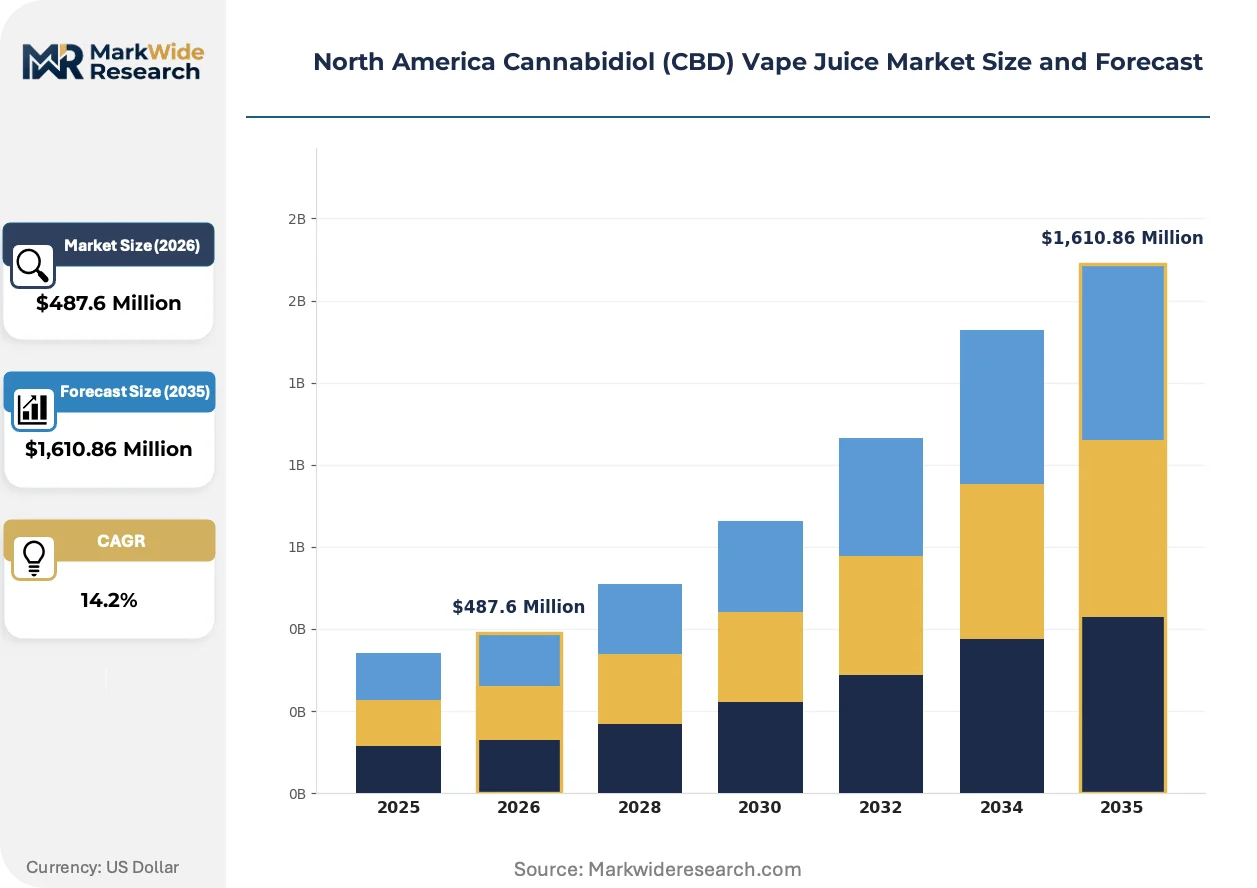
Market Dynamics
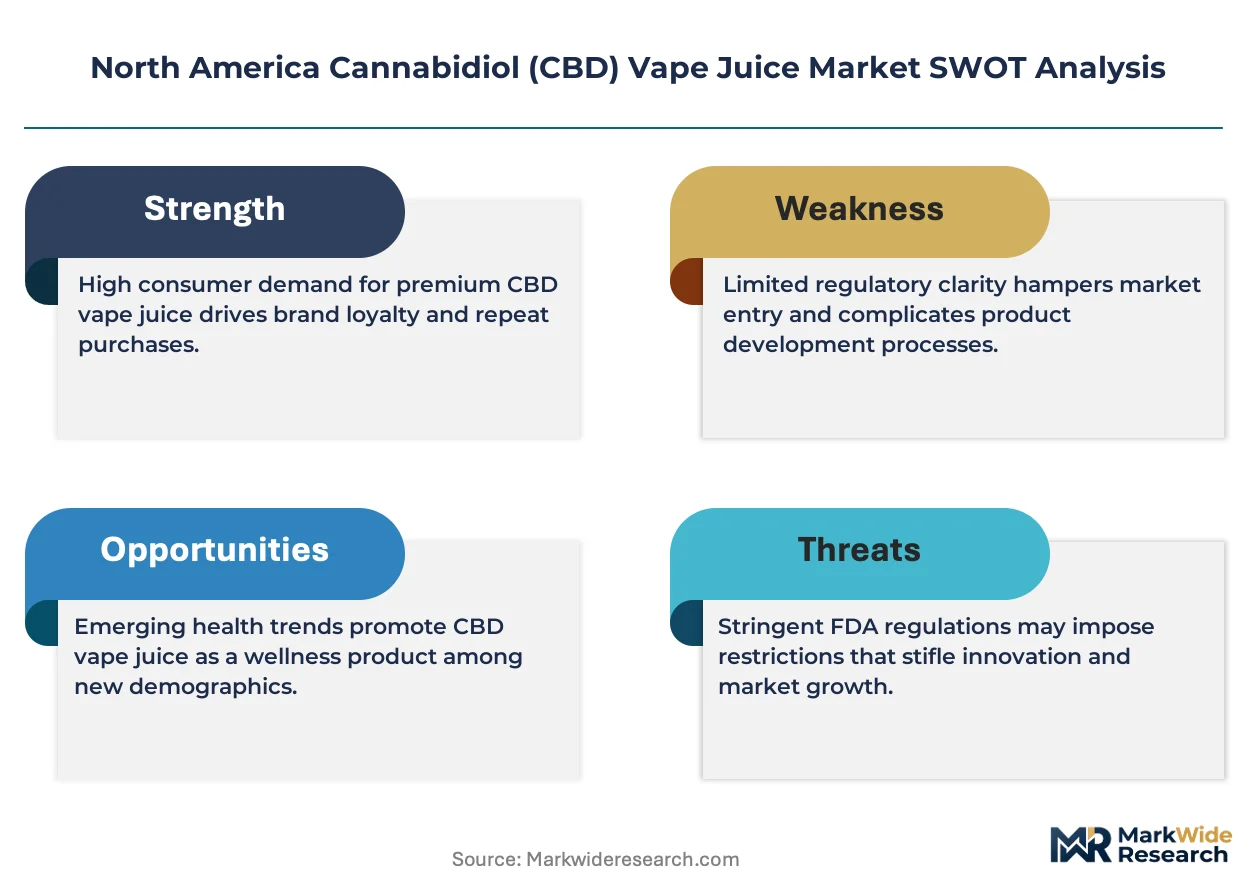
The North America CBD vape juice market is experiencing acute formulation pressure as the FDA's dietary supplement prohibition clashes with state-level cannabis permissiveness, forcing manufacturers to maintain parallel product architectures.
Growth Catalysts
- Wellness consumer migration:Nicotine vape users and former combustible smokers are pivoting to CBD formulations for perceived anxiety modulation without intoxication, expanding addressable demand beyond legacy cannabis consumers.
- 2018 Farm Bill compliance infrastructure:The 0.3% delta-9 THC threshold established federally legal hemp sourcing channels, enabling interstate raw material commerce that previously operated in legal ambiguity.
- Mature California dispensary networks:The state's vertically integrated retail infrastructure provides consumer education and product accessibility benchmarks that lower adoption barriers across neighboring jurisdictions.
Market Restraints
- Carrier fluid cost volatility:Pharmaceutical-grade propylene glycol and vegetable glycerin prices fluctuate with petrochemical feedstock markets, compressing gross margins on isolate-based SKUs competing at economy price points.
- Canadian supply concentration:Hemp biomass inputs for extraction-grade CBD concentrate increasingly originate from Prairie Province cultivation, creating tariff-exposure and currency-hedging complexity for US formulators.
- FDA interstate commerce friction:The agency's position that CBD cannot be marketed as a dietary supplement prevents standardized health claims, forcing state-by-state label variation that fragments brand equity.
Strategic Opportunities
- Texas and Florida retail expansion:These populous states currently restrict dispensary density but show legislative momentum toward broader hemp-derived product access, positioning early entrants for regulatory inflection capture.
- Minor cannabinoid formulation:CBG and CBN infusion at functional doses creates premium positioning distinct from commodity CBD isolate, commanding shelf space in specialty channels.
- Direct-to-consumer subscription models:Recurring revenue structures bypass wholesale margin stacking while capturing consumption-pattern data that informs flavor and potency development.
Industry Challenges
- Analytical chemistry talent scarcity:HPLC and mass spectrometry proficiency for cannabinoid quantification and terpene profiling remains concentrated in legacy cannabis testing laboratories, constraining in-house quality control scaling.
- Health Canada divergence compliance:Cross-border manufacturers must maintain separate packaging, THC caps, and excise stamping for Canadian market access, doubling regulatory affairs overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cannabidiol (CBD) Vape Juice Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,610.86 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Spectrum, Broad Spectrum, Isolate, CBD Oil Formulation: Ready-to-Use, Concentrated, Infused, Flavor Enhanced Distribution Channel: Online Stores, Specialty Shops, Pharmacies, Convenience Stores Consumer Type: Recreational Users, Medicinal Users, First-Time Users, Regular Consumers |
| Companies Covered | CBDfx, Hemp Bombs, Green Roads, Koi CBD, JustCBD, Aurora Cannabis Inc., Charlotte's Web, Endoca, CV Sciences, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cannabidiol (CBD) Vape Juice Market Evolving Landscape
Formulation science and inhalation hardware are converging to reshape product performance benchmarks, while regulatory fragmentation forces operational flexibility as a core competency rather than a transitional state.
Ceramic coil vaporization technology is rendering obsolete traditional wick-based heating elements in premium device pairings. Wellness-oriented consumers migrating from nicotine systems demand temperature precision and elimination of metallic aftertaste. This engineering shift is compressing the addressable market for commodity 510-thread batteries lacking thermal regulation.
The FDA's ongoing CBD policy evaluation and potential rescheduling proceedings are creating formulation uncertainty that favors multi-jurisdictional compliance architectures. Manufacturers are pre-positioning label claims and batch testing protocols for multiple regulatory outcomes. Colorado and Oregon state regulators are advancing product integrity standards that exceed federal minimums, forcing national brand holders to tier quality systems.
Specialty vape shop foot traffic is fragmenting toward online aggregation platforms that consolidate third-party lab results and consumer reviews. Convenience-seeking buyers prioritize SKU transparency over tactile product evaluation. California and Washington State exhibit the most pronounced channel migration, where delivery logistics infrastructure supports same-day fulfillment economics.
North America Cannabidiol (CBD) Vape Juice Market Segmentation
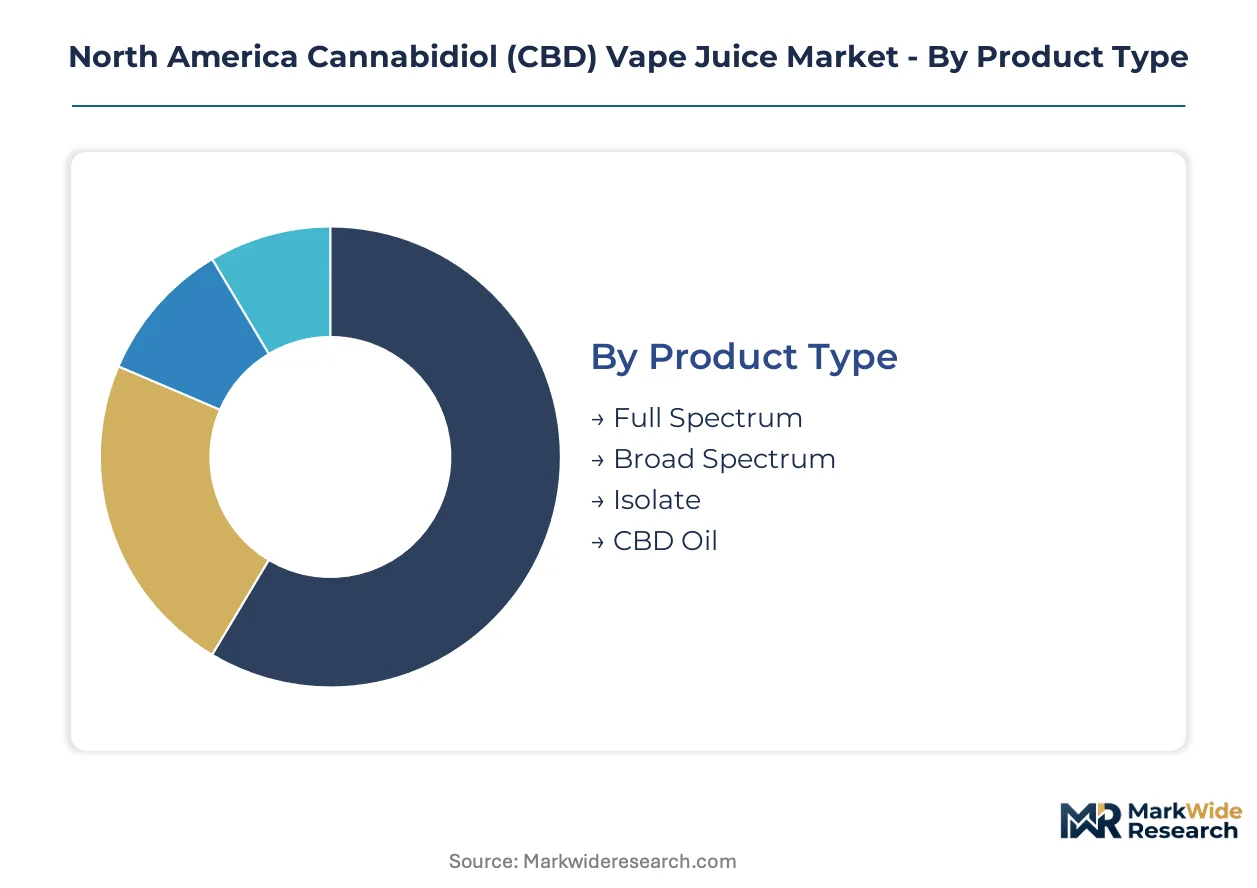
Segmentation in North American CBD vape juice reveals how formulation philosophy, purchase context, and user experience level create distinct margin profiles and regulatory exposure. Each dimension shapes inventory strategy, compliance architecture, and channel investment priorities differently.
Product Type:
Mature full-spectrum offerings coexist with emerging isolate formats as consumer sophistication and drug-testing anxiety split demand trajectories.
- Full Spectrum:Retains trace cannabinoids and terpenes from hemp biomass, delivering an entourage effect that commands premium positioning in California and Colorado dispensaries. Wellness-oriented recreational users in these jurisdictions drive repeat purchase rates above national averages, though interstate shipment restrictions limit brand geographic coherence.
- Broad Spectrum:THC-free formulations that preserve minor cannabinoids and selected terpenes, targeting professional athletes and federal employees subject to workplace testing. Texas and Florida consumers gravitate toward this middle tier as legislative ambiguity around THC thresholds persists.
- Isolate:Crystalline CBD at 99%+ purity enables precise dosing and flavor neutrality, competing primarily on unit economics in online channels.
- CBD Oil:Unvaporized tincture formats that share manufacturing infrastructure but serve distinct consumption rituals and regulatory classifications.
Full Spectrum handles the majority of throughput; Isolate is gaining share fastest as standardization appeals to risk-averse procurement officers.
Formulation:
Cost tier differentiation separates convenience-driven purchases from enthusiast preparation rituals, with margin stacking concentrated in value-added processing stages.
- Ready-to-Use:Pre-mixed solutions in sealed cartridges or disposable devices eliminate consumer handling of raw concentrates. California delivery services and Florida smoke shops stock these formats for transaction velocity, though per-milligram CBD economics disadvantage heavy users.
- Concentrated:High-potency extracts requiring dilution into carrier fluids, purchased by experienced consumers seeking dosage control and cost efficiency. Pacific Northwest markets show disproportionate concentration here due to legacy cannabis user migration patterns.
- Infused:CBD addition to existing nicotine or flavor bases, capturing dual-use consumers in transition.
- Flavor Enhanced:Terpene-forward or synthetic flavor profiles masking hemp earthiness, prevalent in first-time user acquisition.
Ready-to-Use dominates transaction volume; Concentrated climbs fastest on unit economics appeal.
Distribution Channel:
Geography of purchase determines compliance burden, with state-level hemp and cannabis regulations fragmenting channel economics.
- Online Stores:Aggregators with third-party lab result databases capture the largest volume share across the region, particularly in states with restricted dispensary infrastructure. Same-day fulfillment networks in California and Washington State compress delivery windows to parity with physical retail.
- Specialty Shops:Vape-focused retailers with educated floor staff generate the highest-margin transactions through device bundling and flavor sampling. Texas and Florida legislative momentum toward broader hemp access positions these channels for regulatory inflection capture.
- Pharmacies:Limited presence due to FDA dietary supplement prohibition, with Charlotte's Web-style prescriber education programs creating narrow access corridors.
- Convenience Stores:Impulse-oriented placement of sealed, low-dose formats in jurisdictions with permissive hemp retail statutes.
Online Stores aggregate the most volume; Specialty Shops deliver the steepest margin expansion trajectory.
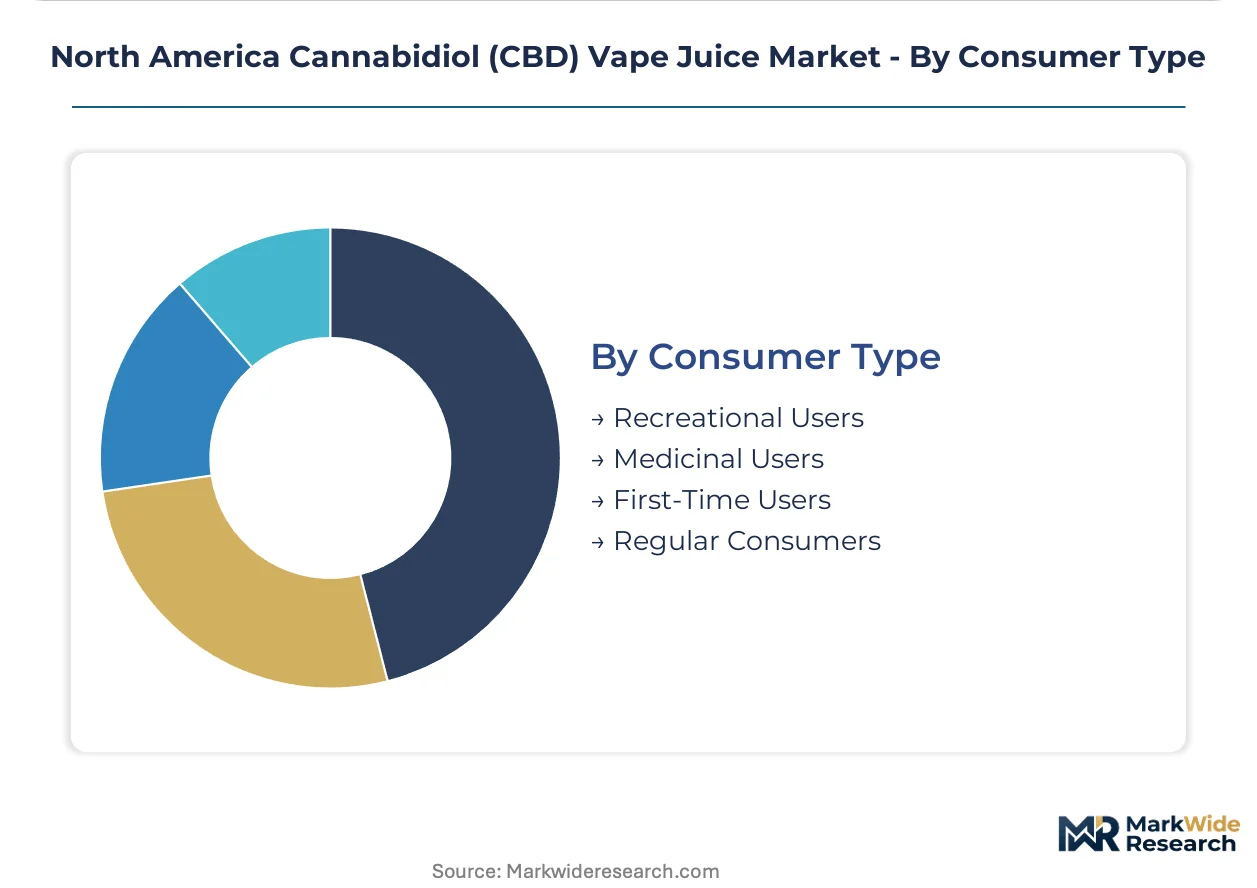
Consumer Type:
Customer lifecycle stage determines price sensitivity, information needs, and product format preferences that shape acquisition cost and lifetime value calculations.
- Recreational Users:Wellness-motivated consumers seeking stress modulation without intoxication, representing the fastest-expanding cohort. California and Colorado markets exhibit the highest penetration here, with ceramic coil device upgrades driving premium SKU attachment.
- Medicinal Users:Symptom-targeted consumers with specific condition management protocols, concentrated in states with medical cannabis frameworks that permit higher THC thresholds alongside CBD.
- First-Time Users:Low-dose, flavor-forward trial formats with high churn risk but significant viral referral potential.
- Regular Consumers:Subscription-amenable heavy users with predictable reorder patterns and carrier fluid cost sensitivity.
Recreational Users constitute the largest addressable base; First-Time Users expand most quickly as nicotine vape migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across North America diverge sharply by jurisdiction maturity. California consumers prioritize full-spectrum formulations with terpene preservation, while Texas and Florida buyers favor THC-free isolates amid legislative ambiguity. Canadian demand concentrates in Prairie Province-sourced biomass with strict Health Canada THC caps.
United States
Wellness-motivated recreational users drive the fastest expansion, particularly in California where vertically integrated dispensary networks enable consumer education at scale. The FDA's dietary supplement prohibition forces state-by-state label variation that fragments brand equity. Colorado and Oregon regulators advance product integrity standards exceeding federal minimums, forcing national brands to tier quality systems.
Canada
Prairie Province hemp cultivation supplies extraction-grade biomass for cross-border manufacturing, creating tariff-exposure and currency-hedging complexity for US formulators. Health Canada enforces strict THC caps and packaging standards under the Cannabis Act, forcing separate product architectures for Canadian market access. Ontario and British Columbia concentrate distribution infrastructure for domestic vape juice manufacturing.
California
Ceramic coil device upgrades and premium SKU attachment dominate consumer behavior among wellness-oriented recreational users. The state's mature delivery logistics infrastructure supports same-day fulfillment economics that compress online retail delivery windows to parity with physical retail. Los Angeles and San Francisco anchor specialty vape shop density with educated floor staff generating highest-margin transactions.
Texas
Professional athletes and federal employees subject to workplace testing gravitate toward broad-spectrum THC-free formulations. Legislative momentum toward broader hemp-derived product access positions early entrants for regulatory inflection capture. Dallas-Fort Worth and Houston concentrate smoke shop retail infrastructure awaiting statutory clarity on dispensary expansion.
Florida
First-time users and nicotine vape migrants drive trial-format demand for low-dose, flavor-forward SKUs. Restricted dispensary density relative to population size channels volume toward online aggregators with third-party lab result databases. Miami and Tampa Bay anchor convenience-oriented retail placement of sealed, low-dose formats in permissive hemp jurisdictions.
North America Cannabidiol (CBD) Vape Juice Market Competitive Landscape
Capability concentration sits with vertically integrated cultivators controlling hemp biomass quality; scale advantage sits with direct-to-consumer platforms aggregating third-party lab transparency. The vendor base fragments across three strategic tiers: backward-integrated hemp operators securing batch consistency, pharmacist-facing educators building prescriber confidence, and laboratory-transparent publishers of full cannabinoid profiles. Dominant competitive moves include geographic expansion into Texas and Florida legislative inflection zones, and minor cannabinoid formulation diversification into CBG and CBN functional doses.
Within the backward-integrated tier, CBDfx anchors supply security through captive hemp sourcing. Charlotte's Web occupies a position exemplifying prescriber education as a channel strategy. Green Roads represents laboratory transparency archetypes publishing per-SKU cannabinoid profiles. These three patterns illustrate how competitive positioning in North American CBD vape juice depends on which stakeholder trust relationship a manufacturer chooses to prioritize.
| Leading Market Players |
|---|
| CBDfx |
| Hemp Bombs |
| Green Roads |
| Koi CBD |
| JustCBD |
| Aurora Cannabis Inc. |
| Charlotte's Web |
| Endoca |
| CV Sciences, Inc. |
| Others |
Value Network & Pricing Analysis
Interstate freight corridors connecting Prairie Province hemp cultivation to US formulation facilities carry cost volatility that amplifies price differentiation between full-spectrum and isolate tiers. Carrier fluid procurement from petrochemical feedstock markets adds secondary pressure, compressing margins on economy-positioned SKUs while premium ceramic coil pairings absorb logistics overhead through device bundling.
Pricing Analysis
Long-term offtake contracts for hemp biomass anchor pricing stability for backward-integrated manufacturers, while spot-market isolate purchases expose formulators to CBD concentrate price swings. Certification tier differentiation separates GMP-compliant SKUs from unverified imports, with FDA dietary supplement prohibition forcing state-by-state label variation that fragments brand equity. Cost compression in isolate-based economy tiers intensifies because pharmaceutical-grade propylene glycol and vegetable glycerin prices fluctuate with crude oil indices. Subscription-amenable regular consumers exhibit lowest price sensitivity; first-time trial format buyers show highest elasticity.
Supply Chain Analysis
Contract manufacturing concentration sits with Canadian extraction facilities processing Prairie Province hemp biomass and US-based e-liquid bottlers in Colorado and California. Raw material dependencies center on hemp-derived CBD isolate, pharmaceutical-grade carrier fluids, and ceramic coil heating elements sourced from specialized electronics foundries. Tariff exposure on cross-border hemp concentrate movements creates margin vulnerability for US formulators lacking captive cultivation. Distribution runs through vertically integrated California dispensary networks and online aggregators with third-party lab transparency databases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analytical chemistry proficiency for cannabinoid quantification and terpene profiling remains concentrated in legacy cannabis testing laboratories, constraining quality control scaling for manufacturers seeking multi-jurisdictional compliance. This talent bottleneck shapes competitive positioning across formulation tiers.
For Market Incumbents: Harden supply security through backward integration into hemp sourcing or exclusive offtake agreements with Prairie Province cultivators. Invest in Health Canada-divergent packaging infrastructure to capture Canadian market access without product line contamination. FDA rescheduling proceedings threaten to recast interstate commerce economics; pre-position batch testing protocols for multiple regulatory outcomes. For New Entrants and Emerging Players: Establish a beachhead in Texas and Florida specialty vape shop channels ahead of anticipated legislative inflection on dispensary expansion. Minor cannabinoid formulation into CBG and CBN functional doses offers premium positioning distinct from commodity CBD saturation. Direct-to-consumer subscription models bypass wholesale margin stacking while capturing consumption-pattern data. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated operators controlling hemp biomass quality through ceramic coil device ecosystem bundling. Five-to-ten year viability hinges on federal rescheduling outcomes and corresponding state tax code adjustments. Watch FDA policy evaluation timelines as the primary inflection signal for interstate commerce economics recalculation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hemp Sourcing | Captive biomass supply secures batch consistency against Prairie Province tariff exposure. |
| Minor Cannabinoid Formulation Expansion | CBG and CBN infusion at functional doses commands specialty channel shelf space. |
| Direct-to-Consumer Subscription Launch | Recurring revenue structures capture consumption-pattern data for flavor development. |
| Health Canada Compliance Architecture | Separate packaging and THC cap protocols enable cross-border market access. |
| Ceramic Coil Technology Partnership | Temperature precision eliminates metallic aftertaste for wellness-oriented nicotine migrants. |
Research Methodology
Desk research of FDA enforcement letters, Health Canada Cannabis Act guidance documents, and state-level hemp statutes preceded structured interviews with extraction facility operators, e-liquid formulation chemists, dispensary procurement managers, and third-party testing laboratory directors. Secondary validation drew from USDA Farm Bulletins, customs records tracking hemp biomass cross-border movements, and SEC filings of publicly traded cannabis operators. Bottom-up SKU-level volume estimates triangulated against top-down category spending projections from channel partner interviews.
Assumptions around FDA dietary supplement prohibition persistence and Health Canada THC cap maintenance were held fixed across baseline scenarios, while federal rescheduling probability and Texas-Florida legislative momentum were varied in sensitivity testing. Segmentation modeling spanned product type, formulation preparation level, distribution channel, and consumer lifecycle stage. CAGRs were derived from fitted growth curves calibrated to historical adoption patterns in California and Colorado. Forecast inputs included ceramic coil device penetration rates and carrier fluid cost indices.
Stress conditions across Prairie Province currency fluctuation, FDA enforcement intensity, and propylene glycol feedstock pricing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding state-level regulatory divergence persistence. Quarterly review of FDA policy evaluation proceedings and Texas-Florida legislative committee activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Middle East and Africa CBD Patch Market
Cannabis/Marijuana
CBD Market
Cannabis/Marijuana
Asia-Pacific Medical Cannabis Market
Cannabis/Marijuana
Latin America and Caribbean Hemp-Derived Cannabidiol Market
Cannabis/Marijuana
Cannabigerol (CBG) Market
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
CBD Hemp Oil Market
Cannabis/Marijuana
Missouri Legal Cannabis Market
Cannabis/Marijuana
CBD-Infused Products Market
Cannabis/Marijuana
Legal Cannabis Market
Cannabis/Marijuana
Cannabis Lighting Market
Cannabis/Marijuana
Cannabis Concentrate Market
Cannabis/Marijuana
Cannabis Use Disorder Treatment Market
Cannabis/Marijuana
Handheld Marijuana Vaporizer Market
Cannabis/Marijuana
Global Cannabis Industry Software Market
Cannabis/Marijuana
Morocco Medical Cannabis Market