
 Cannabis Lighting Market | 2026-2036
Cannabis Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabis Lighting Market Analysis
A capital-intensity divergence between vertically integrated manufacturers and component assemblers is redrawing competitive boundaries in cannabis lighting. Signify sustains technology leadership through captive LED chip fabrication and spectral tuning IP. Gavita Holland BV dominates professional greenhouse channels with high-output plasma and HID legacy installations. Fluorescent specialists such as Hydrofarm Holdings Group, Inc. navigate margin compression by controlling North American distribution infrastructure for hobbyist and mid-tier cultivators.
Cannabis lighting encompasses engineered photon delivery systems designed to replicate or exceed solar spectral output for controlled-environment agriculture, typically operating across photosynthetically active radiation bands from 400 to 700 nanometers with supplemental far-red and ultraviolet configurations for terpene and cannabinoid modulation. LED product lines now command structural priority as energy costs and heat-load constraints displace HID dominance in indoor facilities; greenhouse applications retain mixed-technology portfolios where solar supplementation reduces electrical dependency. Technology segmentation tracks cultivation methodology rather than hardware alone, with hydroponics and vertical farming configurations demanding precise photon flux density management that software-integrated LED arrays deliver most efficiently.
The U.S. Department of Energy appliance standards program and state-level public utility commissions shape retrofit incentives through demand-side management rebates, while the FCC regulates wireless control interfaces increasingly embedded in networked grow-light systems. Canada's PMRA and provincial energy authorities impose parallel efficiency benchmarks that filter import eligibility for lighting equipment destined for licensed producers. Stakeholders must monitor how evolving state cannabis regulatory frameworks synchronize with utility decarbonization targets to determine timing and scale of infrastructure commitments.
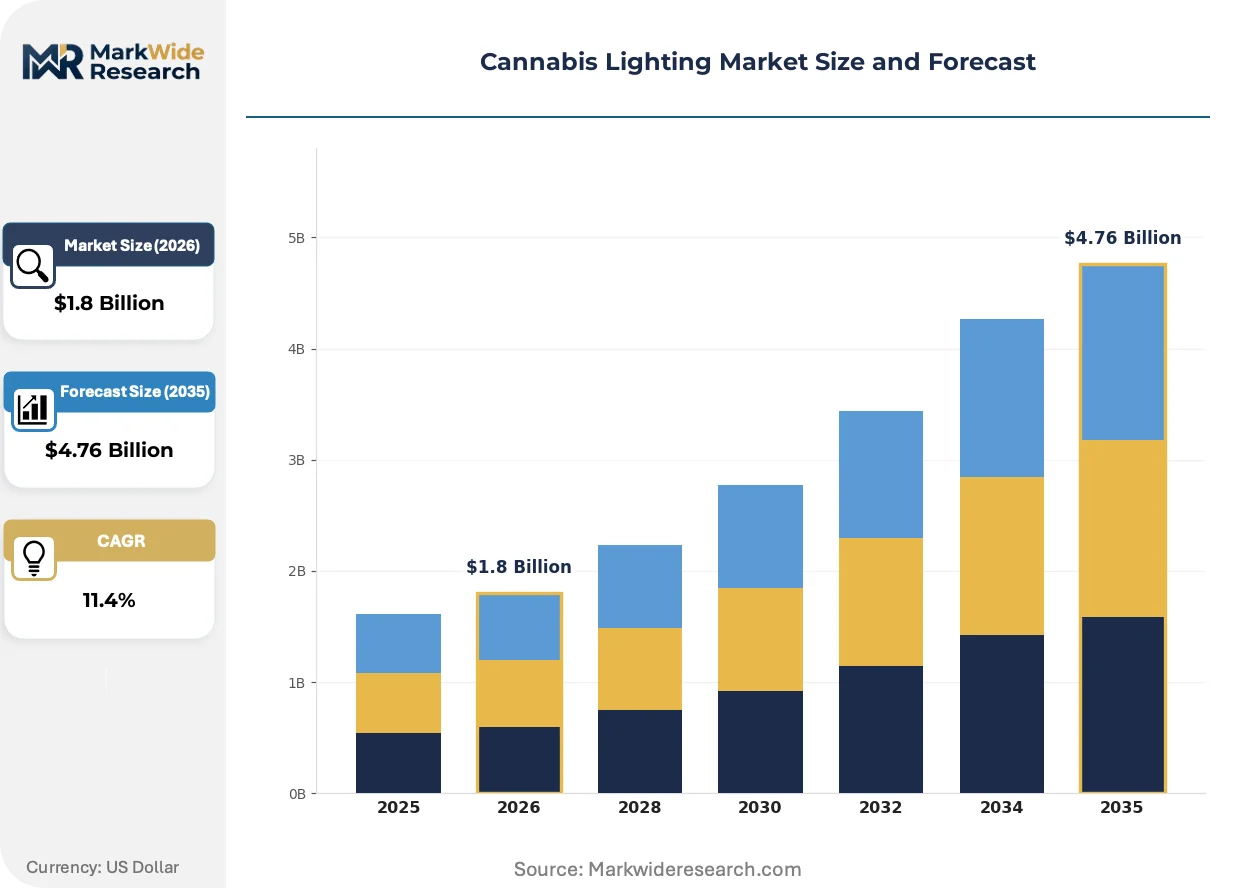
Market Dynamics
LED retrofits are compressing the installed base of high-pressure sodium systems as utility rebate programs in California, Colorado, and Michigan restructure cultivator capital allocation toward spectral-tunable architectures.
Growth Catalysts
- State-level legalization frameworks:Expanding operational licensing in Michigan and Colorado creates incremental demand for controlled-environment agriculture infrastructure. New facility construction mandates photon delivery system procurement.
- Utility demand-side management rebates:California Public Utilities Commission incentives offset capital expenditure for energy-efficient LED conversions. Commercial indoor operators accelerate replacement cycles.
- Spectral tuning IP maturation:Far-red and ultraviolet configuration capabilities enable cannabinoid and terpene modulation. Cultivators adopt programmable arrays for strain-specific outcomes.
Market Restraints
- LED chip supply concentration:Captive fabrication capabilities concentrate among vertically integrated manufacturers. Component assemblers face margin compression and sourcing vulnerability.
- Heat-load infrastructure lock-in:Existing HVAC systems sized for high-pressure sodium thermal profiles require costly reconfiguration. Retrofit economics degrade for older facilities.
- Interstate commerce prohibition:Federal cannabis scheduling creates fragmented state markets. Equipment manufacturers navigate incompatible regulatory requirements across jurisdictions.
Strategic Opportunities
- Greenhouse mixed-technology portfolios:Solar-supplemented operations retain HID and plasma installations alongside LED zones. Equipment suppliers bundle multi-source lighting packages.
- Wireless control interface integration:FCC-regulated networked grow-light systems enable remote photon flux density management. Software-integrated arrays command premium positioning.
- Canadian provincial energy benchmarks:PMRA and provincial authority efficiency standards filter import eligibility. Compliant manufacturers access licensed producer procurement channels.
Industry Challenges
- Spectral engineering talent scarcity:Photobiology expertise for PAR band optimization remains concentrated among specialized research institutions. Cultivators compete for qualified technical staff.
- Legacy HID disposal compliance:Mercury-containing high-pressure sodium lamps trigger EPA hazardous waste protocols. Decommissioning timelines extend facility retrofit schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabis Lighting Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HID, LED, Fluorescent, Incandescent Technology: Hydroponics, Aeroponics, Soil-Based, Vertical Farming Application: Indoor Cultivation, Greenhouse, Research & Development, Commercial Use Customer Type: Growers, Distributors, Retailers, Consultants |
| Companies Covered | Signify (Philips), OSRAM Licht AG, Gavita Holland BV, Cree Inc, Fluence, Illumitex Inc., Hydrofarm Holdings Group, Inc., California LightWorks, Valoya, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabis Lighting Market Emerging Trajectories
Spectral programmability and networked control architectures are restructuring how cultivators procure, operate, and optimize photon delivery systems across facility types.
Tunable spectrum LED arrays are decomposing the traditional hardware-software boundary in controlled-environment agriculture. Commercial indoor operators in California and Colorado are deploying fixture-integrated sensors for real-time DLI adjustment. This convergence is decomposing standalone environmental control systems into distributed edge-computing nodes.
EPA appliance standards and state public utility commission rebate programs are tightening efficiency thresholds for qualifying equipment. Demand-side management frameworks now require networked metering capabilities for incentive eligibility. Professional greenhouse operators in Michigan are restructuring procurement specifications to capture these incentives.
Buyer concentration among multi-state operators is compressing vendor negotiation cycles and unbundling after-sales service contracts. Large cultivators in Colorado and California are bringing spectral calibration in-house. Mid-tier facilities respond through cooperative purchasing alliances to restore bargaining leverage.
Cannabis Lighting Market Segmentation
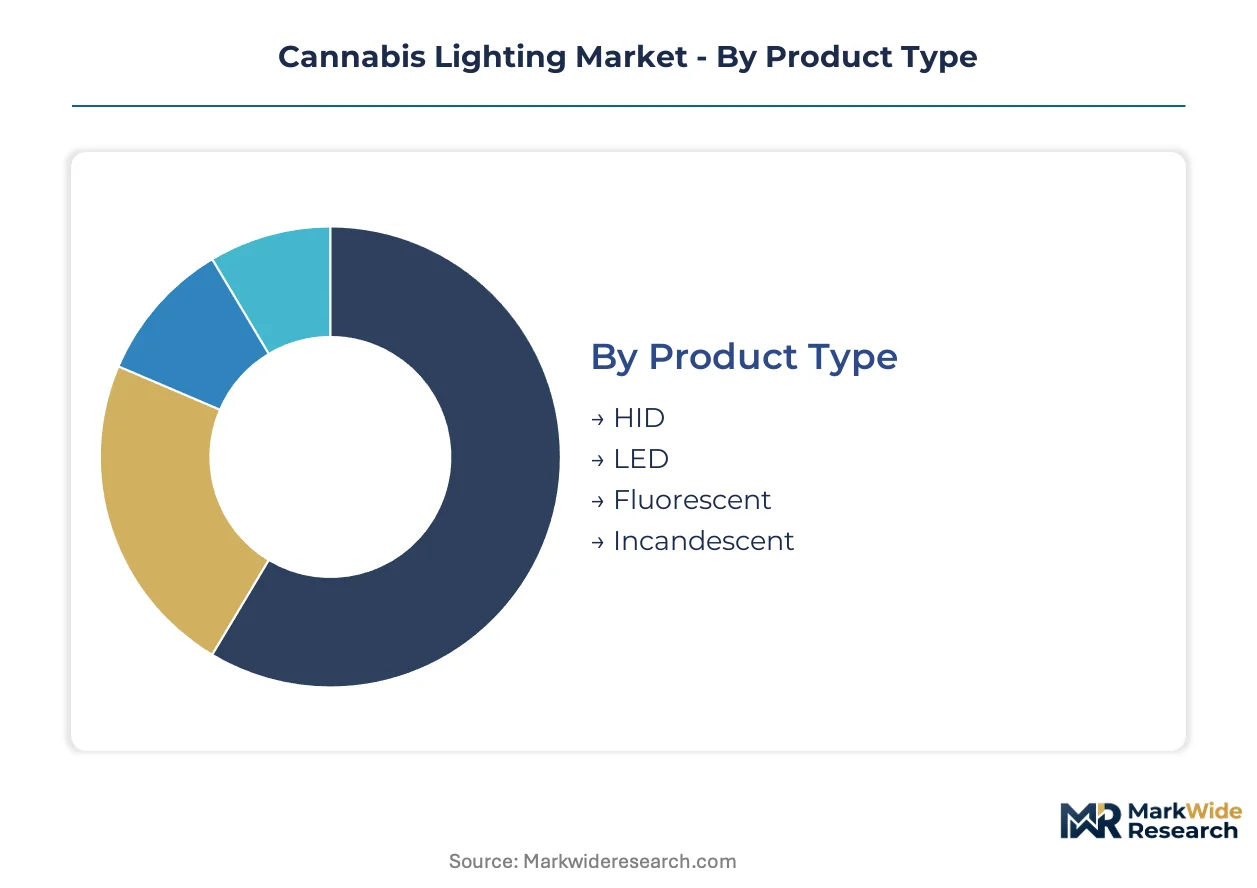
Segmentation in cannabis lighting tracks how cultivation methodology, facility infrastructure, and buyer sophistication reshape procurement patterns. Technology choice and application context determine spectral requirements, energy profiles, and software integration needs.
Product Type:
Regulatory differentiation in energy-efficiency standards and hazardous waste protocols splits procurement between legacy installations and next-generation architectures.
- HID:High-pressure sodium and metal halide systems deliver high photon flux density at lower capital cost. California and Colorado cultivators with grandfathered HVAC infrastructure retain these installations where utility rebates fail to offset reconfiguration expenses. Established volume favors HID; emerging adoption favors LED.
- LED:Tunable spectrum arrays with 400-700 nanometer PAR coverage plus supplemental far-red and ultraviolet channels enable cannabinoid modulation. Michigan commercial operators exploit Public Utilities Commission rebates to accelerate retrofit cycles. Demand concentrates among multi-state operators with capital for spectral programmability.
- Fluorescent:Compact and T5 tube configurations serve propagation and vegetative stages with lower heat output. Hobbyist cultivators in Colorado and mid-tier facilities prioritize these for seedling operations.
- Incandescent:Limited to specific photoperiod interruption applications requiring precise red spectrum delivery. Niche demand from research institutions and breeding programs.
Established volume favors HID; emerging adoption favors LED.
Technology:
Cost tier stratification separates capital-intensive precision systems from lower-barrier conventional methods.
- Hydroponics:Soilless cultivation with nutrient film technique or deep water culture demands precise photon flux density management. LED arrays with integrated environmental sensors dominate these installations. Indoor facilities in California deploy these configurations for water-scarce regions.
- Vertical Farming:Multi-tier racked systems with inter-canopy lighting require uniform PAR distribution and minimal heat load. Michigan and Colorado operators adopt these for maximum square-foot productivity. This segment climbs the fastest as real estate constraints intensify.
- Aeroponics:Mist-based root delivery systems pair with high-intensity lighting for accelerated growth cycles. Research institutions and premium cultivators employ these for phenotypic optimization.
- Soil-Based:Conventional substrate cultivation retains mixed-technology lighting portfolios. Greenhouse operators in Michigan favor these for organic certification pathways.
Precision requirements concentrate investment in hydroponics and vertical farming; soil-based methods retain cost-sensitive technology mixes.
Application:
Customer type determines specification rigor and service contract complexity.
- Indoor Cultivation:Fully controlled environments with zero solar supplementation require complete photon delivery infrastructure. California commercial operators specify networked LED arrays with FCC-compliant wireless control interfaces.
- Greenhouse:Solar-supplemented operations deploy mixed-technology portfolios balancing electrical dependency with spectral precision. Colorado facilities optimize for seasonal light variation.
- Research & Development:Universities and breeding programs demand programmable spectral arrays for controlled photobiology studies. EPA appliance standards compliance filters equipment selection.
- Commercial Use:Multi-state operators standardize procurement specifications across facility footprints. Michigan licensees prioritize utility rebate eligibility in vendor selection.
Scale economies favor commercial use standardization; technical sophistication favors research and development procurement.
Customer Type:
Margin structure varies across direct cultivation versus intermediary channels.
- Growers:Licensed cultivators drive specification-setting with direct spectral calibration requirements. California and Colorado operators bring photon flux density optimization in-house.
- Distributors:Inventory aggregation and logistics services connect manufacturers with fragmented facility bases. North American infrastructure controls determine competitive positioning.
- Retailers:Point-of-sale equipment providers serve hobbyist segments with lower technical support obligations. Margin compression favors volume throughput over service depth.
- Consultants:Design and commissioning services influence procurement decisions for new facility construction. Technical credibility with utility rebate program navigation determines engagement.
Direct cultivation relationships favor growers; channel efficiency favors distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Dutch and North American supply channels while Chinese manufacturing clusters compress margins for component sourcing. Utility rebate arbitrage between California and Michigan creates divergent procurement economics for identical LED architectures.
United States
California, Colorado, and Michigan drive facility construction as state-level legalization frameworks expand operational licensing. The California Public Utilities Commission and state energy authorities structure demand-side management rebates that offset capital expenditure for LED conversions. Los Angeles and Denver metropolitan clusters concentrate multi-state operator headquarters where procurement standardization accelerates spectral-tunable adoption.
Canada
Licensed producers in Ontario and British Columbia scale controlled-environment agriculture infrastructure under federal cannabis regulations. Health Canada's PMRA and provincial energy authorities impose efficiency benchmarks that filter import eligibility for lighting equipment. Toronto and Vancouver serve as distribution hubs where compliant manufacturers access procurement channels for commercial cultivation facilities.
Netherlands
Professional greenhouse channels retain mixed-technology portfolios where solar supplementation reduces electrical dependency. The country's national agricultural regulator and EU energy efficiency directives shape equipment standards for horticultural lighting exports. Westland municipality anchors greenhouse technology development where plasma and HID legacy installations coexist with LED zones.
Germany
Medical cannabis cultivation licensing under federal narcotics law creates demand for pharmaceutical-grade controlled-environment systems. The KBA and federal energy efficiency frameworks influence equipment specifications for licensed producers. Bavaria and North Rhine-Westphalia concentrate research institutions where photobiology expertise for PAR band optimization develops.
China
LED chip fabrication capabilities concentrate manufacturing supply for downstream fixture assemblers. The country's national standards administration and MIIT shape export eligibility for horticultural lighting components. Shenzhen and Dongguan industrial clusters produce tunable spectrum arrays where captive fabrication capabilities differentiate vertically integrated manufacturers from component-dependent competitors.
Cannabis Lighting Market Vendor Landscape
Concentration sits with vertically integrated manufacturers controlling captive LED chip fabrication and spectral tuning intellectual property. Component assemblers face margin compression and sourcing vulnerability as supply concentrates among upstream specialists. Two strategic archetypes dominate: technology leaders with in-house semiconductor production, and distribution-heavy intermediaries controlling North American logistics infrastructure. Competitive moves center on M&A for spectral IP portfolios and strategic partnerships for utility rebate program navigation.
Among Netherlands-based horticultural specialists, Gavita Holland BV occupies a position exemplifying professional greenhouse channel dominance through high-output plasma and HID legacy installations. Signify represents the technology leadership archetype with captive LED chip fabrication capabilities. Hydrofarm Holdings Group, Inc. anchors the distribution-centric tier, controlling North American infrastructure for fragmented facility bases.
| Leading Market Players |
|---|
| Signify (Philips) |
| OSRAM Licht AG |
| Gavita Holland BV |
| Cree Inc |
| Fluence |
| Illumitex Inc. |
| Hydrofarm Holdings Group, Inc. |
| California LightWorks |
| Valoya |
| Others |
Supply Flow & Price Mechanics
LED chip substitution for high-pressure sodium lamp components simultaneously shifts supply geography toward Shenzhen and Dongguan manufacturing clusters and compresses fixture-level pricing through captive fabrication economies. This input transition rewards vertically integrated manufacturers while squeezing margin structures for component assemblers dependent on merchant semiconductor sourcing.
Pricing Analysis
The customization-premium spread separates tunable spectrum arrays with far-red and ultraviolet configuration capabilities from standard PAR-band fixtures. Three-tier pricing structure across premium, standard, and economy levels reflects spectral programmability depth, FCC-compliant wireless control integration, and utility rebate eligibility certification. Pricing pressure stems from Chinese LED chip oversupply and utility demand-side management rebate arbitrage between California and Michigan. Multi-state operators exhibit lowest price sensitivity due to procurement standardization economies; hobbyist cultivators through retail channels face highest cost compression.
Supply Chain Analysis
Strait of Hormuz transit vulnerability for indium phosphide substrates underscores raw material security exposure in III-V semiconductor supply chains serving horticultural LED fabrication. LED chip fabrication concentrates in China, South Korea, and Taiwan; downstream fixture assembly clusters in the Netherlands and North America. Aluminum heat sink extrusions, driver electronics, and optical-grade polycarbonate lenses constitute critical component dependencies. Single-source vulnerability concentrates in merchant semiconductor supply for non-integrated assemblers. Distribution runs through licensed producer procurement channels and North American horticultural supply distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cannabis lighting constitutes a high-growth disruption as state-level legalization frameworks expand operational licensing and utility rebate programs accelerate spectral-tunable LED retrofits. The technological inflection sits at fixture-integrated sensor deployment for real-time DLI adjustment.
For Market Incumbents: Fortify spectral tuning intellectual property portfolios through targeted acquisition of photobiology research institutions and captive LED chip fabrication capacity expansion in Shenzhen industrial clusters. Defend against margin compression from Chinese component assemblers by deepening FCC-compliant wireless control interface integration and securing exclusive utility rebate program partnerships in California and Michigan. For New Entrants and Emerging Players: Anchor in mid-tier greenhouse operators in Colorado requiring mixed-technology lighting portfolios balancing HID legacy infrastructure with LED zone retrofits. Target research institution procurement channels for programmable spectral arrays serving breeding programs. Pursue cooperative purchasing alliance participation to bypass multi-state operator procurement standardization barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed North American distribution infrastructure players controlling hobbyist and mid-tier cultivator channels. Long-term viability hinges on spectral programmability software recurring revenue attachment rates and utility rebate program navigation capabilities. Watch for federal cannabis rescheduling signals as inflection indicator for interstate commerce infrastructure investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Spectral IP Acquisition | Captures photobiology expertise from research institutions for cannabinoid modulation capabilities. |
| Utility Rebate Partnership | Secures California Public Utilities Commission incentive eligibility for LED conversion acceleration. |
| Wireless Control Integration | Enables FCC-compliant networked grow-light systems for remote photon flux density management. |
| Captive Fabrication Expansion | Establishes Shenzhen LED chip production to reduce sourcing vulnerability and margin compression. |
| Cooperative Purchasing Alliance | Restores bargaining leverage for mid-tier facilities against multi-state operator procurement concentration. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA appliance standards filings, state public utility commission rebate program documentation, and horticultural lighting patent databases. Primary interviews engaged cultivation facility operators, utility demand-side management program administrators, LED fixture procurement managers, and spectral engineering consultants. Secondary validation drew from FCC equipment authorization records, Health Canada PMRA import eligibility standards, and EU energy efficiency directive horticultural lighting amendments. Bottom-up facility-level capacity estimates triangulate against top-down market value reconstruction.
Segmentation dimensions modeled span product type, cultivation technology, application context, and customer archetype across the analysis window. Hydroponics and vertical farming configurations receive distinct treatment given precision photon flux density requirements. CAGRs derive from facility construction pipeline analysis, utility rebate program budget trajectories, and spectral programmability adoption curves. Industry-specific forecast inputs include state-level legalization licensing velocity and PMRA efficiency benchmark compliance rates.
Material uncertainties — federal cannabis rescheduling decisions, LED chip supply disruption, and utility rebate program funding exhaustion — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding state regulatory framework expansion and spectral tuning IP maturation trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Cannabis Vaporizers Market
Cannabis/Marijuana
Europe CBD Patch Market
Cannabis/Marijuana
US Cannabinoids Market
Cannabis/Marijuana
Veterinary CBD Market
Cannabis/Marijuana
Missouri Legal Cannabis Market
Cannabis/Marijuana
Legal Marijuana Market
Cannabis/Marijuana
Cannabis Edibles Market
Cannabis/Marijuana
Missouri Medical Cannabis Market
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Market
Cannabis/Marijuana
Thailand Legal Cannabis Market
Cannabis/Marijuana
Mexico Hemp CBD Market
Cannabis/Marijuana
Global CBD Vape Juice Market
Cannabis/Marijuana
CBD Hemp Oil Market
Cannabis/Marijuana
Global Cannabis Extract Market
Cannabis/Marijuana
Cannabidiol (CBD) Market
Cannabis/Marijuana
Australia Legal Cannabis Market