
 Candle Jar Market | 2026-2036
Candle Jar Market Size, Share, and Industry Trends Forecast 2026-2036
Candle Jar Market Insights
REACH is repositioning the cost-of-entry calculus for European candle jar suppliers by mandating chemical safety disclosures across glass coatings and decorative finishes. Roetell leverages integrated glass-molding operations to absorb compliance costs without outsourcing testing. Sunny Glassware anchors its competitive stance through proprietary borosilicate formulations that preempt regulatory scrutiny. Jarsking differentiates via recycled-content certification that satisfies procurement thresholds set by major retail chains.
A candle jar constitutes a rigid container engineered from soda-lime glass, borosilicate glass, ceramic, or metal, typically featuring wall thicknesses of 2–5 millimeters and thermal shock resistance calibrated for combustion temperatures exceeding 60°C, designed primarily to contain molten wax while preserving fragrance integrity and ensuring consumer safety during burn cycles. Glass material type dominates volume owing to optical clarity and recyclability, though ceramic commands premium positioning in artisanal and gift segments where tactile aesthetics justify higher unit economics. Online retail represents the fastest-expanding sales channel, driven by subscription-based candle brands that bypass traditional wholesale markups and demand customized jar geometries at medium-scale minimum order quantities.
The EPA regulates volatile organic compound emissions from scented candles sold in the United States, while the FDA maintains oversight of cosmetic-grade fragrance additives that contact skin during handling. California's Proposition 65 disclosure requirements create a de facto national labeling standard that most suppliers adopt preemptively. Stakeholders must monitor evolving state-level extended producer responsibility laws that could impose post-consumer glass recovery obligations on jar manufacturers and brand owners alike.
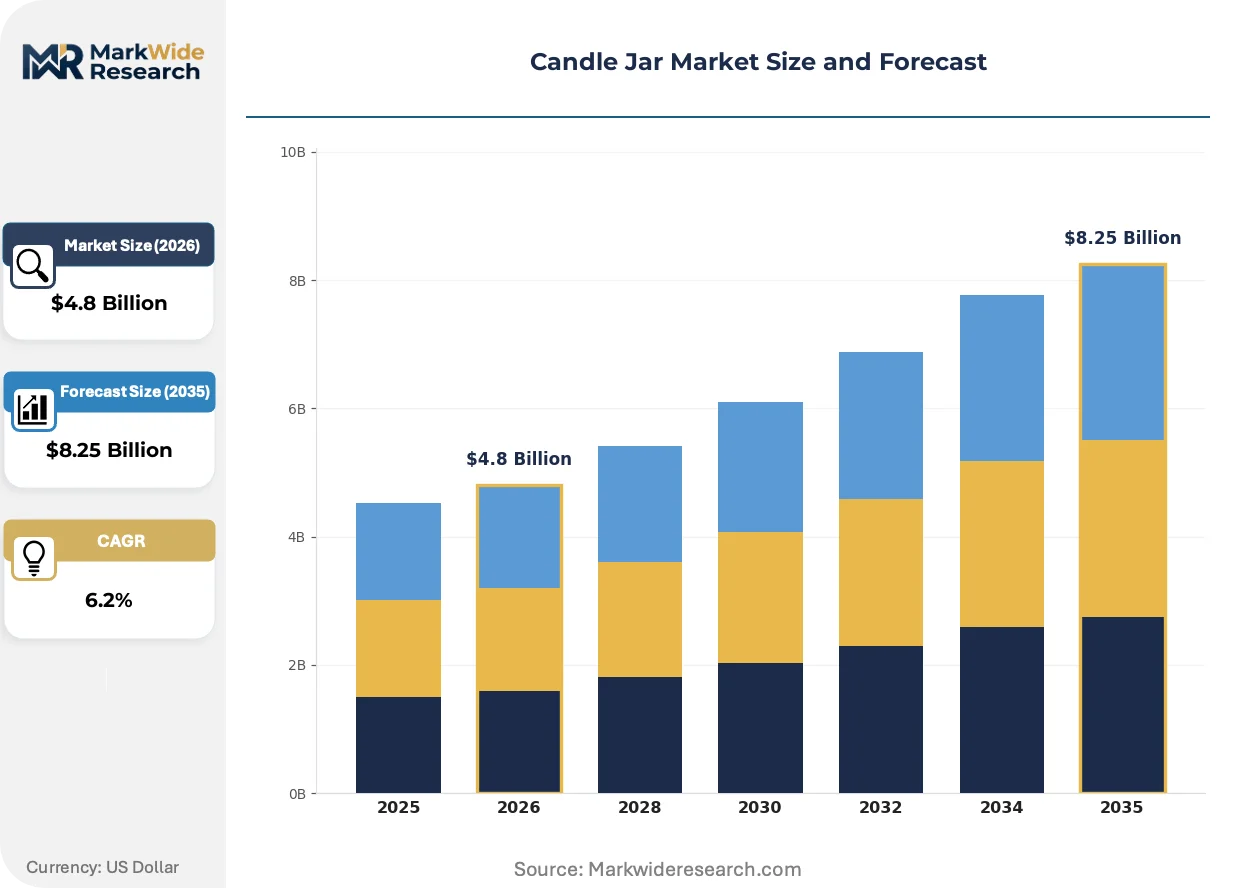
Market Dynamics
The candle jar market is experiencing structural pressure from the EU Green Deal's packaging sustainability mandates, which are forcing suppliers to reconfigure material sourcing and certification workflows ahead of enforcement deadlines.
Growth Catalysts
- REACH chemical disclosure mandates:European regulations on glass coatings are accelerating supplier consolidation as smaller molders exit due to testing cost burdens.
- Direct-to-consumer candle brands:Subscription-based home fragrance companies in the United States are driving demand for customized jar geometries at medium-scale order quantities.
- Recycled-content procurement thresholds:Major retail chains now require post-consumer glass certification, rewarding suppliers with verified circular supply chains.
Market Restraints
- Soda-lime glass feedstock volatility:Energy-intensive melting operations face input cost pressure from natural gas price fluctuations in European manufacturing clusters.
- Single-source borosilicate supply concentration:Technical-grade raw material for thermal-shock-resistant jars concentrates among limited specialty chemical producers.
- California Proposition 65 labeling friction:The state's disclosure requirements create compliance complexity for multi-market suppliers without harmonized federal standards.
Strategic Opportunities
- Extended producer responsibility tailwinds:Emerging state-level glass recovery obligations in the United States will favor jar manufacturers with captive recycling infrastructure.
- Artisanal ceramic positioning:Tactile aesthetics in gift segments command premium unit economics where borosilicate clarity offers no advantage.
- Online retail channel innovation:Bypassing wholesale markups through brand-owned e-commerce is compressing traditional distribution layers.
Industry Challenges
- Thermal shock testing certification timelines:Third-party validation for combustion temperature resistance creates product launch delays.
- Fragrance integrity engineering:Molten wax chemical compatibility with decorative glass coatings requires specialized formulation expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Candle Jar Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Glass, Metal, Ceramic, Silicone, Bamboo Design Style: Minimalist, Vintage, Modern, Rustic, Artisanal Capacity: Small, Medium, Large, Extra Large Sales Channel: Online Retail, Specialty Stores, Department Stores, Boutique Shops |
| Companies Covered | Glassnow, Roetell, LOM Glassworks, EAP Innovations, CandleScience, Fillmore Container, Midwest Bottles, Jarsking, Sunny Glassware, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Candle Jar Market Trends and Innovations
Material science advances and regulatory stringency are converging to reshape competitive positioning in candle jar manufacturing, with sustainability credentials becoming a primary sorting mechanism for procurement decisions.
Proprietary borosilicate formulations are electrifying the premium segment by delivering thermal shock resistance exceeding 60°C while maintaining optical clarity for luxury fragrance branding. Direct-to-consumer candle companies are adopting these formulations at accelerated pace to differentiate subscription offerings. The technology is electrifying traditional soda-lime glass economics by compressing acceptable performance thresholds upward.
The EPA's volatile organic compound emission standards for scented candles are forcing reformulation of fragrance loadings and wick specifications across United States production. Glass jar suppliers must now coordinate testing documentation with brand partners to demonstrate combustion safety compliance. California's Proposition 65 disclosure requirements are creating de facto national labeling standards that most suppliers adopt preemptively to avoid SKU fragmentation.
Buyer concentration among millennial and Gen Z households is rotating demand toward vessels that signal environmental responsibility through visible recycled content and minimalist aesthetic coding. Traditional wholesale procurement through distributor networks is losing share to direct manufacturer relationships that enable customized geometries and faster iteration cycles. This behavioral shift is most visible in United States urban markets where subscription candle services have achieved critical mass.
Candle Jar Market Segmentation
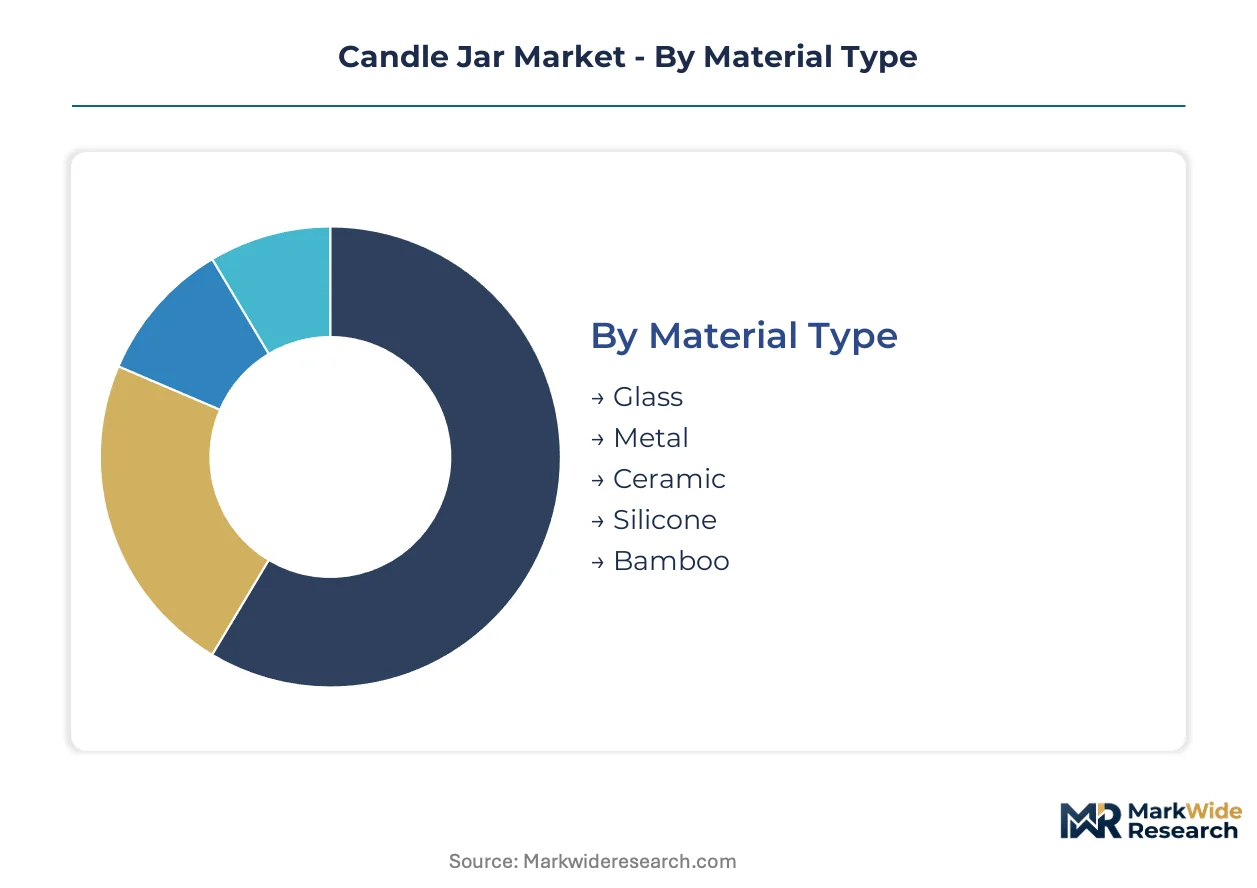
Candle jar procurement decisions cascade from material specifications through aesthetic positioning to volume economics. Each segmentation axis carries distinct capital requirements and margin profiles that shape supplier strategy and brand partnerships.
Material Type:
Glass molding demands the heaviest upfront investment in melting furnaces and forming equipment, while ceramic and alternative materials require specialized curing infrastructure with lower scale economies.
- Glass:Soda-lime and borosilicate formulations dominate procurement volumes through optical clarity and thermal shock resistance calibrated for combustion cycles. United States direct-to-consumer brands concentrate demand here for subscription box aesthetics and recyclability signaling. REACH compliance costs on decorative coatings are accelerating supplier consolidation toward integrated molders.
- Metal:Tinplate and aluminum vessels command premium positioning in travel and outdoor segments where shatter resistance outweighs visual transparency. European artisanal brands favor metal for matte finishes and embossing compatibility that differentiates gift assortments.
- Ceramic:Earthenware and stoneware jars target tactile luxury positioning with hand-glazed surfaces and substantial heft.
- Silicone:Flexible, collapsible formats serve camping and portable use cases with minimal thermal mass.
- Bamboo:Renewable outer shells with glass liners appeal to sustainability-forward millennial households in urban United States markets.
Most installed capacity flows through Glass. Expansion is steepest in Bamboo.
Design Style:
Production complexity and mold amortization schedules vary sharply across aesthetic categories, with artisanal formats requiring manual finishing that constrains throughput.
- Minimalist:Clean cylindrical geometries with single-color coatings minimize tooling changeovers and maximize furnace utilization rates. Gen Z household penetration in United States coastal cities drives fastest volume growth for private-label candle programs.
- Artisanal:Hand-applied textures, irregular rims, and reactive glazes command 3-4x unit economics in boutique retail channels. Ceramic material lock-in here limits supplier switching and extends partnership tenures.
- Vintage:Apothecary-inspired silhouettes with embossed logos and amber tinting.
- Modern:Angular profiles and metallic accents targeting urban loft aesthetics.
- Rustic:Distressed finishes and earthy palettes for farmhouse decor alignment.
Minimalist formats absorb the highest mold investment. Artisanal commands the steepest margin expansion trajectory.
Capacity:
Fill volume determines wax loading economics, shipping cube efficiency, and burn-time positioning against competitive sets.
- Medium:8-12 ounce vessels anchor mainstream subscription services and department store planograms with optimal wax-to-jar cost ratios. United States millennial household penetration concentrates here for trial-to-repeat conversion mechanics.
- Large:16-24 ounce formats serve gift and hospitality segments where extended burn duration justifies higher price points.
- Small:2-4 ounce trial sizes and travel formats.
- Extra Large:Statement pieces exceeding 32 ounces for luxury residential and commercial installations.
Medium capacity carries the densest production tooling. Extra Large is gaining share fastest in direct-to-consumer gifting.
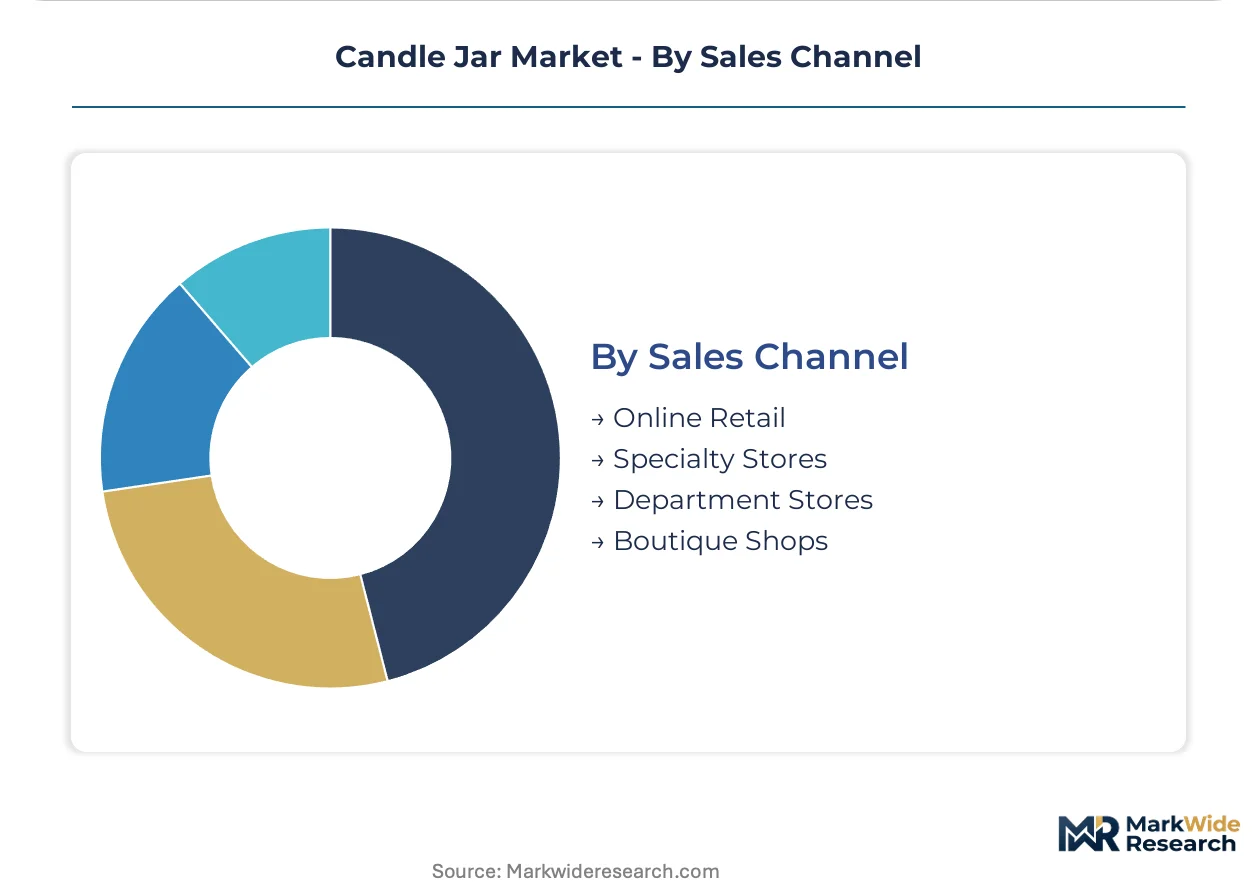
Sales Channel:
Channel selection dictates minimum order quantities, customization depth, and payment terms that reshape supplier working capital requirements.
- Online Retail:Brand-owned e-commerce and marketplace storefronts bypass wholesale markups while demanding customized geometries at medium-scale MOQs. United States subscription candle companies anchor demand here with 4-6 week iteration cycles.
- Specialty Stores:Curated home fragrance boutiques reward exclusive jar designs with premium shelf placement and editorial coverage.
- Department Stores:Mass luxury distribution with standardized SKUs and seasonal promotional calendars.
- Boutique Shops:Hyper-local retail with artisanal procurement preferences and limited volume commitments.
Department Stores still channel the most absolute volume. Online Retail is climbing the fastest as subscription models achieve critical mass.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled glassblowing artisans and mold-making engineers concentrate in specific manufacturing clusters across key candle jar markets, anchoring regional supply capabilities and shaping competitive dynamics through craft specialization and technical expertise.
United States
Millennial and Gen Z households in coastal metropolitan areas drive premium jar procurement for direct-to-consumer subscription brands. The EPA regulates volatile organic compound emissions from scented candles nationwide, while California's Proposition 65 creates de facto labeling standards adopted across state lines. Glass molding operations cluster in Ohio and Pennsylvania, where legacy container manufacturing infrastructure supports medium-scale customized production runs.
Germany
Artisanal ceramic and high-end glass formats command premium positioning in boutique retail channels throughout German-speaking Europe. REACH mandates from ECHA impose chemical safety disclosure requirements on decorative coatings and surface finishes. The North Rhine-Westphalia industrial corridor hosts specialized borosilicate fabricators serving thermal-shock-resistant specifications for luxury fragrance houses.
China
Volume production of soda-lime glass vessels supplies global private-label candle programs through integrated molding and coating operations. The country's national standards body maintains GB standards for glass container safety and chemical migration limits. Manufacturing concentrates in the Yangtze River Delta, where furnace scale economies and export logistics infrastructure dominate international procurement.
United Kingdom
Heritage apothecary-inspired jar designs anchor gift segment demand among urban professional households in London and Southeast England. Post-Brexit regulatory divergence from EU REACH creates parallel compliance workflows for suppliers serving both markets. Specialist glass decorators in the Midlands region maintain hand-finishing capabilities for limited-edition collaborative releases.
France
Luxury fragrance heritage drives demand for optically superior borosilicate and crystal-clear soda-lime presentations in Parisian retail and hospitality channels. ANSM oversees cosmetic-grade fragrance additive safety for skin-contact applications during candle handling. Glassmaking traditions in Île-de-France and Auvergne-Rhône-Alpes sustain small-batch artisanal suppliers alongside industrial molders.
Candle Jar Market Competitive Landscape
The competitive structure tilts toward integrated glass-molding specialists with captive furnace operations and certified compliance infrastructure. Mid-scale suppliers face consolidation pressure as regulatory testing costs and recycled-content certification requirements escalate capital thresholds. Two strategic archetypes dominate: vertically integrated manufacturers controlling raw material through finished jar logistics, and design-forward specialists partnering with subscription candle brands for rapid geometric iteration. Capacity expansion and strategic material partnerships constitute the primary competitive moves, with furnace rebuilds and borosilicate supply agreements reshaping cost positions.
Among China-based fabricators, Roetell exemplifies the integrated archetype through glass-molding operations that absorb REACH compliance costs internally. Sunny Glassware occupies a position anchored in proprietary material formulations, while Jarsking represents the sustainability-certification vector with recycled-content verification. These three entities illustrate how geographic concentration, regulatory adaptation, and circular supply chain credentials sort competitive positioning across procurement tiers.
| Leading Market Players |
|---|
| Glassnow |
| Roetell |
| LOM Glassworks |
| EAP Innovations |
| CandleScience |
| Fillmore Container |
| Midwest Bottles |
| Jarsking |
| Sunny Glassware |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap glass molders in Ohio and Pennsylvania anchor supply-side discipline through captive furnace operations that buffer pricing volatility from natural gas feedstock swings. Their ownership structure enables patient capital deployment into REACH compliance infrastructure, insulating medium-scale order pricing from the cost pass-through pressures squeezing outsourced competitors.
Pricing Analysis
Bundled coating-and-certification services command 15-25% premiums over unbundled jar-only procurement, with REACH-compliant decorative finishes and recycled-content verification as the primary price differentiation drivers. Three-tier pricing structure across premium borosilicate, standard soda-lime, and economy imported glass tiers is compressing as energy costs in European manufacturing clusters force mid-tier repositioning. Subscription candle brands exhibit lowest price sensitivity due to packaging-as-brand economics, while mass private-label programs drive hardest bargain on volume scale.
Supply Chain Analysis
Borosilicate feedstock rests on specialty chemical producers concentrated in Germany, China, and Japan, with soda-lime glass batch materials drawing from limestone and soda ash operations across the United States, Mexico, and Turkey. Decorative coating chemistries hinge on pigment and resin supply from Italian and Dutch specialty chemical houses. Single-source vulnerability in technical-grade borosilicate creates qualification bottlenecks for thermal-shock-resistant specifications. Distribution runs through direct manufacturer relationships for subscription brands, while legacy wholesale channels serve department store and boutique retail procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The candle jar market functions as a stable compounder, with millennial and Gen Z household formation driving recurring demand for home fragrance vessels across economic cycles.
For Market Incumbents: Extend furnace utilization through medium-scale customization capabilities that match subscription brand iteration cycles, while deepening backward integration into recycled glass cullet sourcing to preempt state-level extended producer responsibility mandates. Ceramic artisanal positioning offers margin defense against commodity glass price erosion. For New Entrants and Emerging Players: Direct-to-consumer marketplace storefronts provide the lowest-friction entry vector, with bamboo-composite and silicone collapsible formats representing penetrable white-space in camping and portable use cases. Sustainability-forward millennial households in United States coastal metros reward visible recycled-content certification with brand loyalty and price tolerance. For Investors and Strategic Acquirers: Valuations sit cheapest among regional glass decorators with hand-finishing capabilities and established retail relationships, as furnace-scale players trade at capacity premiums. The five-to-ten-year viability window favors targets with captive recycling infrastructure and verified circular supply chains. Watch for state-level glass recovery obligation legislation as the inflection trigger for stranded asset risk in non-compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled-Content Certification Investment | Verified post-consumer glass thresholds unlock procurement from major retail chains enforcing EU Green Deal alignment. |
| Direct-to-Consumer Channel Partnership | Subscription candle brands in United States coastal cities demand customized geometries at compressed iteration cycles. |
| Borosilicate Supply Agreement | Technical-grade raw material lock-in secures thermal-shock-resistant positioning for premium fragrance house contracts. |
| Artisanal Ceramic Capacity Addition | Hand-glazed earthenware commands 3-4x unit economics in boutique gift channels where tactile aesthetics dominate. |
| Extended Producer Responsibility Infrastructure | Captive glass recovery operations preempt emerging state-level post-consumer recovery obligations on jar manufacturers. |
Research Methodology
Multiple input streams — structured interviews with glass molding plant managers and candle brand procurement leads, trade data from United States and European customs authorities, and regulatory filings with ECHA and EPA — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from furnace utilization surveys, recycled-content certification databases, and retail procurement threshold disclosures. Primary fieldwork captured iteration cycle timing and minimum order quantity economics from subscription candle company operations directors.
Historical volume trajectories were cross-referenced against panel input from glass industry technical directors to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated material type, capacity tier, design style, and sales channel dimensions, with CAGR derivation reflecting furnace rebuild cycles and borosilicate supply agreement tenors as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for electrified glass melting would alter the outlook for energy cost structures and regional competitive positioning. Forecasts reflect assumptions around REACH enforcement timelines and state-level extended producer responsibility adoption rates. A small set of triggers — natural gas price volatility, borosilicate supply disruption, and regulatory divergence between United States and European chemical safety standards — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Electric Air Freshener Market
Household Items
Portable Steamers Market
Household Items
Toilet Cistern Blocks Market
Household Items
Hand Wash Station Market
Household Items
HEPA Vacuum Cleaners Market
Household Items
Portable Iron Market
Household Items
Gel Warmers Market
Household Items
North America Ceramic Barbeque Grill Market
Household Items
Deodorizer Bag Market
Household Items
Global Laptop Tables Market
Household Items
Jet Hand Dryer Market
Household Items
China Cookware Market
Household Items
Global Sports Bottle Market
Household Items
Washing Capsules Market
Household Items
Insulated Tumblers Market
Household Items
Middle East and Africa B2B Air Care Market