
 Camping Utensils Market | 2026-2036
Camping Utensils Market Size, Share, and Industry Trends Forecast 2026-2036
Camping Utensils Market Outlook
Titanium is recalibrating product economics across the camping utensils landscape as brands trade stainless steel heft for gram-count reductions. Newell Brands leverages its multi-brand portfolio to sustain shelf dominance across mass retail channels in North America. Johnson Outdoors anchors its position through specialized marine and outdoor divisions with differentiated R&D pipelines. Oase Outdoors ApS competes on Nordic design heritage and direct-to-consumer channel control.
Camping utensils comprise portable eating implements engineered for outdoor meal preparation and consumption, typically weighing under 50 grams per piece and manufactured through CNC machining, injection molding, or titanium sintering to withstand repeated thermal cycling and mechanical stress in field conditions. Stainless steel sporks and full-size titanium cutlery occupy mature margin pools with established OEM supply chains, while silicone-collapsible and multi-tool formats represent faster-growing niches as backpackers prioritize packability. Plastic utensils face structural pressure from material substitution trends and regulatory bans on single-use equivalents.
The US FDA governs food-contact surface standards for camping utensils sold through domestic retail, while the EU REACH framework restricts phthalates and heavy metals in polymer-based outdoor tableware. Japan's METI enforces JIS standards for metal migration limits in portable cookware, creating compliance thresholds for Asian export manufacturers. Stakeholders must monitor evolving chemical disclosure requirements and material certification protocols to maintain cross-border market access.
Market Dynamics
Ultralight backpacking culture is compressing gram-count tolerances across the camping utensils supply base, forcing manufacturers to abandon stainless steel stamping in favor of titanium sintering and hollow-handle geometries.
Growth Catalysts
- REACH chemical restrictions:ECHA's tightening phthalate and heavy metal limits in polymer-based outdoor tableware are accelerating material substitution toward food-grade silicone and titanium across European retail channels.
- Alpine manufacturing clusters:Germany's precision metalworking corridor around Solingen and Pforzheim provides CNC machining density that shortens prototype-to-production cycles for ultralight cutlery brands.
- Thru-hiker equipment turnover:Pacific Crest Trail and Appalachian Trail completionists replace utensil sets every 2,000-mile season, creating predictable replacement demand cycles.
Market Restraints
- Sponge titanium input volatility:Aerospace sector competition for Grade 1 titanium sponge from Ukrainian and Russian suppliers generates price swings that compress margin pools for mid-tier camping brands.
- Single-source anodizing concentration:Color-finish capabilities for titanium utensils cluster in Guangdong Province workshops, creating geographic supply risk for brands requiring aesthetic differentiation.
- Bioplastic performance ceiling:Polylactic acid alternatives lack the thermal cycling durability for repeated hot-meal contact, limiting substitution of petroleum-based polymers in collapsible formats.
Strategic Opportunities
- Nordic direct-to-consumer channel control:Scandinavian outdoor retailers with owned digital platforms bypass wholesale markups and capture full margin on titanium cutlery sets.
- Silicone-titanium hybrid convergence:Foldable silicone bowl sets with embedded titanium reinforcing ribs address packability without sacrificing structural integrity for hot liquids.
- US Inflation Reduction Act domestic content:Camping brands qualifying for domestic manufacturing tax credits can reposition titanium-milled products against imported stainless steel alternatives.
Industry Challenges
- Food-contact certification timelines:FDA 21 CFR compliance documentation for novel silicone formulations extends new product introduction cycles by 8-14 months.
- CNC programming talent scarcity:Hollow-handle titanium geometries require 5-axis machining expertise concentrated in aerospace job shops with limited outdoor industry crossover.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camping Utensils Market |
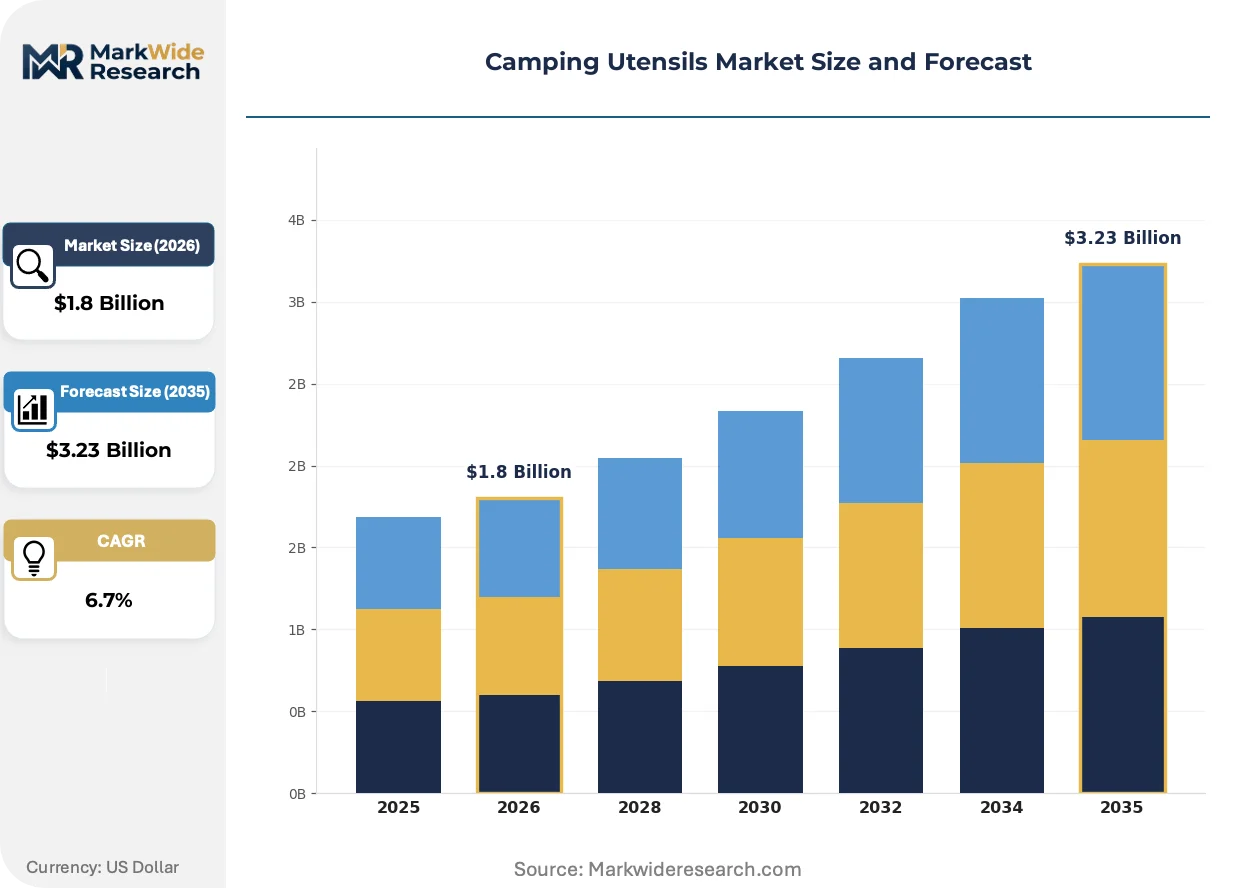
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sporks, Spoons, Forks, Knives Material: Stainless Steel, Titanium, Plastic, Silicone Size: Compact, Full-Size, Travel, Multi-Tool Use Case: Backpacking, Car Camping, Picnics, Survival |
| Companies Covered | Newell Brands, Johnson Outdoors, Big Agnes, Dometic Group AB, Oase Outdoors ApS, AMG Group, Exxel Outdoors, Hilleberg The Tentmaker, Nemo Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camping Utensils Market Strategic Shifts
Active material science and regulatory chemistry are rewriting the competitive map for portable tableware, collapsing the historical divide between performance gear and consumer product safety regimes.
Titanium additive manufacturing is converging with topology optimization software to produce lattice-structured handles that maintain torsional rigidity at 40% weight reduction versus solid bar stock. Thru-hikers and alpine climbers are adopting these geometries fastest, with trail forums documenting load-bearing tests that compress traditional brand loyalty cycles. The technology is converging with generative design platforms to collapse the engineering validation phase from months to weeks.
EU REACH Annex XVII updates are restricting bisphenol A migration limits in epoxy-coated metal utensils below 0.05 mg/L, forcing manufacturers to abandon powder-coat finishes for bare titanium or PVD ceramic alternatives. The industrial consequence is a capital reallocation toward vacuum deposition equipment and away from electrostatic spray lines. Scandinavian and German brands with existing PVD partnerships are absorbing market share from southern European competitors dependent on legacy coating supply chains.
Subscription-based gear replacement programs are displacing single-transaction retail for ultralight utensil sets, with outdoor co-ops and direct brands offering annual refresh cycles tied to mileage thresholds. The channel disruption concentrates in US and Canadian markets where REI membership density and trail registration data enable predictive logistics. Pacific Northwest thru-hiker communities exhibit the highest enrollment rates, with seasonal migration patterns driving regional warehouse positioning.
Camping Utensils Market Segmentation
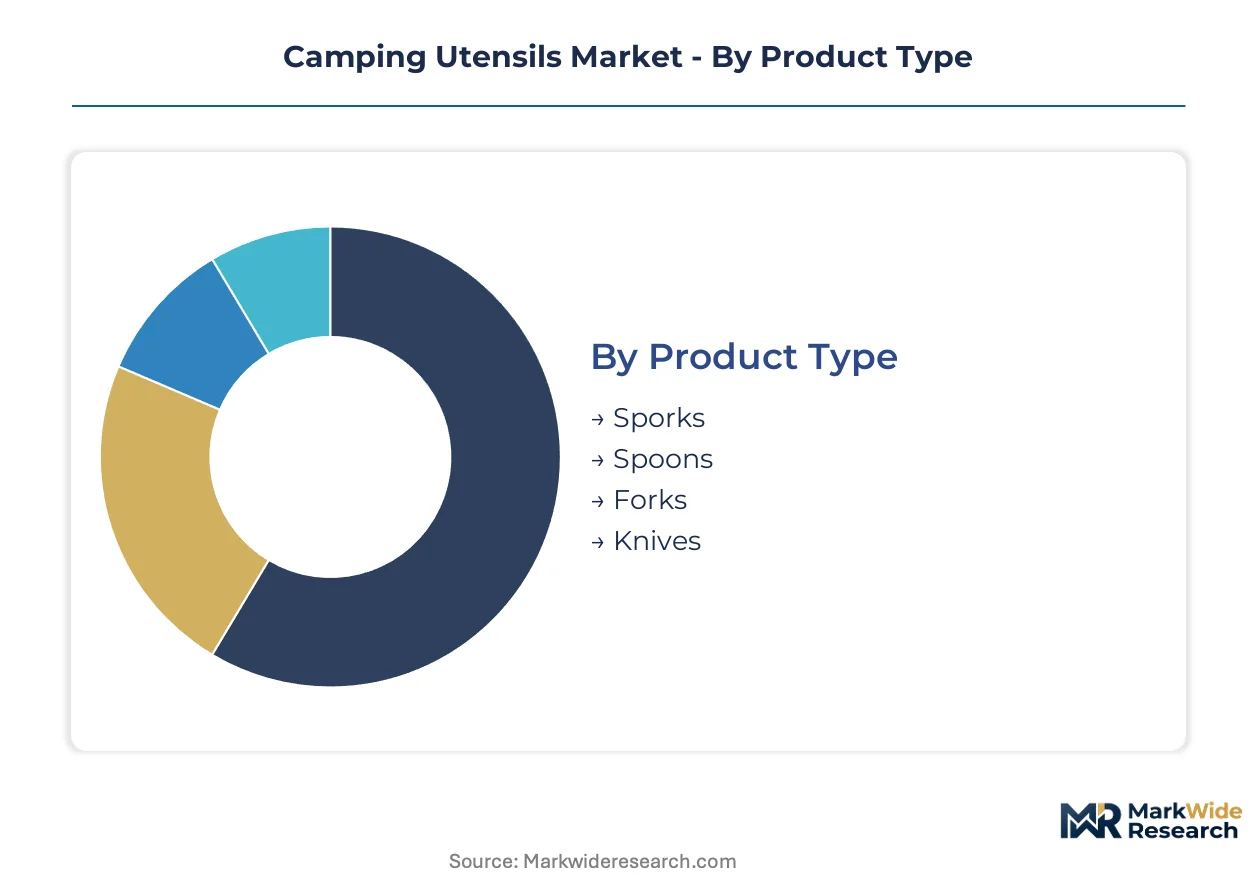
Segmentation in camping utensils determines compliance pathways and manufacturing location decisions. FDA 21 CFR food-contact certification requirements vary sharply across material categories, while REACH Annex XVII restrictions create divergent cost structures for European-bound production.
Product Type:
Sporks require dual-surface FDA validation for spoon and fork functions, while knives trigger blade-length regulations in multiple jurisdictions.
- Sporks:Hybrid implements combine concave scoop geometry with tined tips through single-piece stamping or titanium sintering. Thru-hiker demand concentrates in US Pacific Northwest trail corridors where gram-count discipline overrides single-function preference.
- Spoons:Deep-bowl designs for dehydrated meal rehydration dominate backpacking applications. Scandinavian direct-to-consumer brands capture margin premiums on titanium spoon sets with anodized color finishes.
- Forks:Tine-reinforced geometries address structural failure risks in polymer formats. Car camping segments in Germany and Austria sustain stainless steel fork demand through durability expectations.
- Knives:Blade-edge regulations in Japan and Switzerland constrain folding knife-utensil hybrids to sub-6cm lengths for unrestricted carry.
Sporks sit at the top of the volume ranking, with titanium spoons climbing the fastest.
Material:
Material selection dictates thermal cycling tolerance and regulatory documentation burdens across export markets.
- Stainless Steel:304 and 316L grades dominate mass retail through established OEM stamping supply chains in China's Zhejiang Province. FDA compliance documentation is standardized, shortening new product introduction timelines.
- Titanium:Grade 1 and Grade 2 titanium sintering enables hollow-handle geometries below 15 grams per piece. Aerospace sponge competition from Ukrainian and Russian suppliers generates input price volatility.
- Plastic:Petroleum-based polymers face substitution pressure from EU single-use bans. Polylactic acid alternatives lack hot-liquid durability for repeated meal contact.
- Silicone:Food-grade platinum-cured formulations enable collapsible bowl-utensil hybrids. ECHA phthalate restrictions favor silicone over PVC in European retail channels.
Stainless steel retains the largest revenue base, though titanium gains share fastest among specialty retailers.
Size:
Size categories align with packability requirements and multi-function integration trends in ultralight equipment.
- Compact:Sub-15cm folded lengths fit insulated jacket pockets for alpine climbing approaches. CNC-machined titanium dominates this format through precision tolerances.
- Full-Size:Standard 18-20cm lengths replicate domestic cutlery ergonomics for car camping comfort priorities. Stainless steel stamping maintains cost advantages at volume.
- Travel:Nesting sets with neoprene or silicone cases target airline carry-on compliance. Japanese METI metal migration standards apply to titanium travel sets sold domestically.
- Multi-Tool:Integrated can openers, bottle openers, and ferro-rod strikers add functional density. Appalachian Trail thru-hikers drive replacement cycles every 2,000-mile season.
Compact formats lead unit shipments, with multi-tool configurations expanding most quickly in specialty channels.
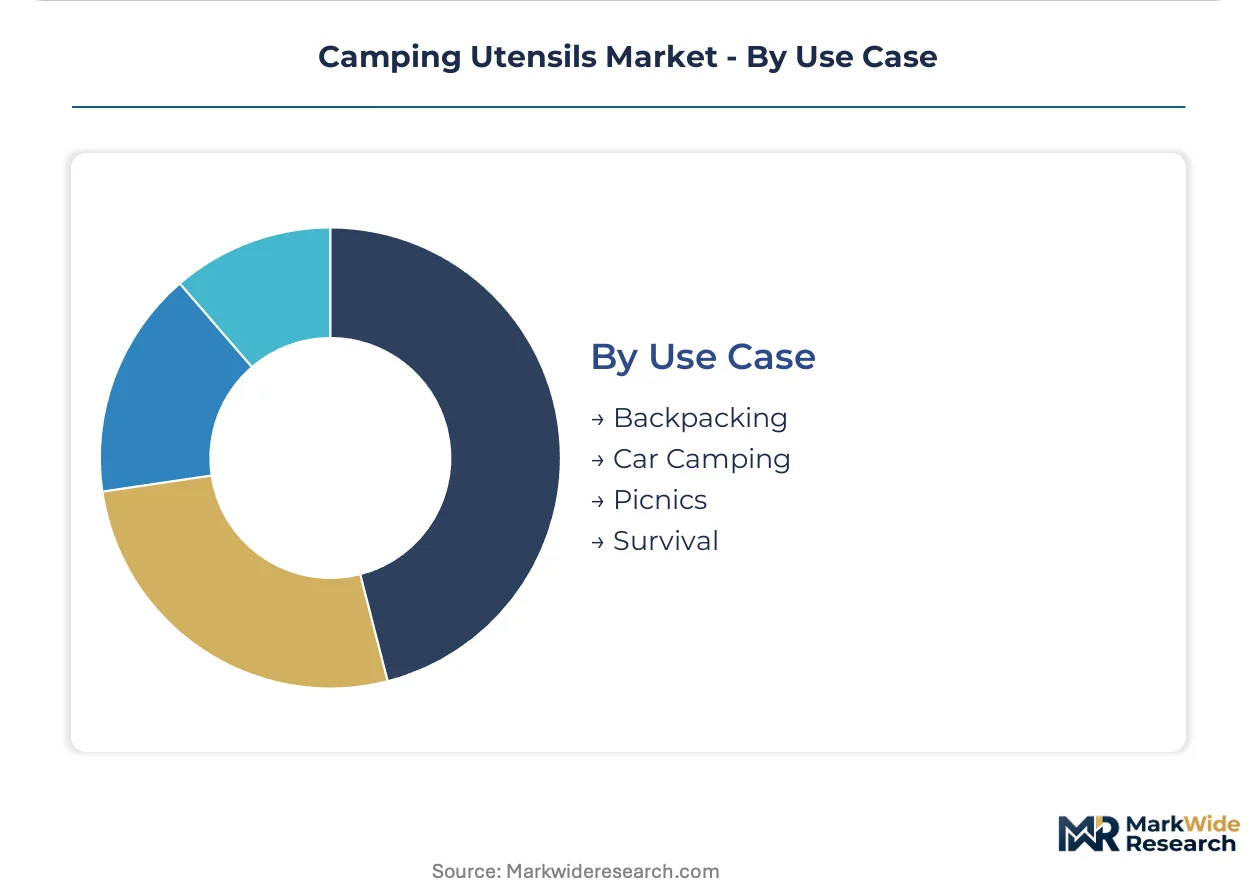
Use Case:
Use case segmentation determines durability specifications and replacement frequency patterns across outdoor activity types.
- Backpacking:Ultralight gram-count tolerances below 25 grams per piece force titanium adoption. Pacific Crest Trail completionists sustain predictable seasonal demand.
- Car Camping:Weight tolerance relaxation enables stainless steel and enamel-coated formats. German Alpine manufacturing clusters supply precision metalworking for premium car camping sets.
- Picnics:Aesthetic presentation priorities drive bamboo and wood composite demand. REACH chemical restrictions limit treated wood finishes in EU markets.
- Survival:Multi-function durability requirements favor titanium with integrated fire-starting features. Military and emergency preparedness procurement in Switzerland and Austria sustains niche volume.
Backpacking anchors absolute volume, while survival applications show the steepest expansion trajectory in professional channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Solingen's precision metalworking corridor anchors titanium machining capacity for ultralight cutlery brands serving thru-hiker demand across the Pacific Crest Trail and Appalachian Trail corridors. REACH chemical restrictions and FDA food-contact standards create divergent compliance pathways that reshape manufacturing location decisions.
United States
Thru-hiker equipment turnover on the Pacific Crest Trail and Appalachian Trail generates predictable replacement cycles every 2,000-mile season. The US FDA governs food-contact surface standards for camping utensils sold through domestic retail channels. Pacific Northwest trail communities concentrate highest subscription-based gear replacement program enrollment, driving regional warehouse positioning for direct-to-consumer brands.
Germany
Alpine manufacturing clusters around Solingen and Pforzheim provide CNC machining density that shortens prototype-to-production cycles for ultralight cutlery. ECHA's REACH Annex XVII restrictions on phthalates and heavy metals in polymer-based outdoor tableware accelerate material substitution toward food-grade silicone and titanium. Baden-Württemberg's precision metalworking corridor supplies titanium sintering expertise for hollow-handle geometries below 15 grams per piece.
China
Guangdong Province workshops concentrate color-finish capabilities for titanium utensil anodizing, creating geographic supply risk for brands requiring aesthetic differentiation. The country's national standards regulator enforces GB food-contact material standards that parallel FDA 21 CFR requirements for export-bound production. Zhejiang Province maintains established OEM stamping supply chains for 304 and 316L stainless steel formats serving mass retail channels.
Japan
METI enforces JIS standards for metal migration limits in portable cookware, creating compliance thresholds for Asian export manufacturers targeting domestic consumers. Japanese consumers sustain demand for travel-format nesting sets with neoprene or silicone cases targeting airline carry-on compliance. Osaka-based metalworking specialists supply precision titanium milling for sub-15cm compact formats fitting insulated jacket pockets.
Switzerland
Blade-edge regulations constrain folding knife-utensil hybrids to sub-6cm lengths for unrestricted carry, shaping multi-tool format development. Military and emergency preparedness procurement sustains niche volume for survival applications with integrated fire-starting features. Swiss metalworking heritage supports premium positioning for titanium cutlery with PVD ceramic finishes replacing REACH-restricted epoxy coatings.
Camping Utensils Market Competitive Environment
Global majors compete with regional champions across material certification and channel control dimensions, producing a tiered structure where mass retail shelf dominance contrasts with direct-to-consumer margin capture. The vendor base spans diversified outdoor conglomerates, specialized Nordic design houses, and precision metalworking specialists. Three archetypes dominate: multi-brand portfolio operators leveraging scale economies, heritage-driven regional champions emphasizing design authenticity, and CNC machining specialists converting aerospace expertise into ultralight formats. Competitive moves concentrate on direct-to-consumer channel bypass of wholesale markups and material substitution toward REACH-compliant titanium and silicone alternatives.
Among diversified outdoor conglomerates, Newell Brands and Johnson Outdoors occupy positions reflecting multi-divisional structures with differentiated R&D pipelines. Oase Outdoors ApS exemplifies the Nordic design heritage archetype, competing through direct-to-consumer channel control and regional aesthetic positioning. These three anchors illustrate the competitive tension between scale-driven mass retail presence and specialized ultralight product development.
| Leading Market Players |
|---|
| Newell Brands |
| Johnson Outdoors |
| Big Agnes |
| Dometic Group AB |
| Oase Outdoors ApS |
| AMG Group |
| Exxel Outdoors |
| Hilleberg The Tentmaker |
| Nemo Equipment |
| Others |
Value Chain & Pricing Dynamics
EU REACH Annex XVII chemical restrictions gate qualified supply for camping utensils, reserving premium-tier pricing access to manufacturers with titanium sintering capabilities and PVD ceramic finish certifications that bypass restricted epoxy coatings.
Pricing Analysis
Input-cost pass-through from Grade 1 titanium sponge volatility compresses margin pools for mid-tier brands unable to absorb aerospace sector competition for Ukrainian and Russian supply. Three-tier pricing structure across premium, standard, and economy levels separates PVD-finished titanium sets from anodized alternatives and mass-market stainless steel. Pricing pressure stems from Guangdong Province anodizing workshop concentration creating single-source bottlenecks for color differentiation. Thru-hikers in the Pacific Northwest exhibit lowest price sensitivity, prioritizing gram-count reductions over cost.
Supply Chain Analysis
Regional distribution centers in Germany's Solingen-Pforzheim corridor and Guangdong Province feed hub-and-spoke patterns serving North American specialty retail and European direct-to-consumer channels. Manufacturing concentrates in China, Germany, and Japan, with Zhejiang Province stamping 304 stainless steel, Baden-Württemberg machining hollow-handle titanium, and Osaka specialists milling sub-15cm compact formats. Raw material dependencies center on Grade 1 titanium sponge, food-grade platinum-cured silicone, and 316L stainless steel bar stock. Single-source anodizing concentration in Guangdong creates geographic supply risk. Distribution runs through outdoor co-op warehousing in the Pacific Northwest and Nordic-owned digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
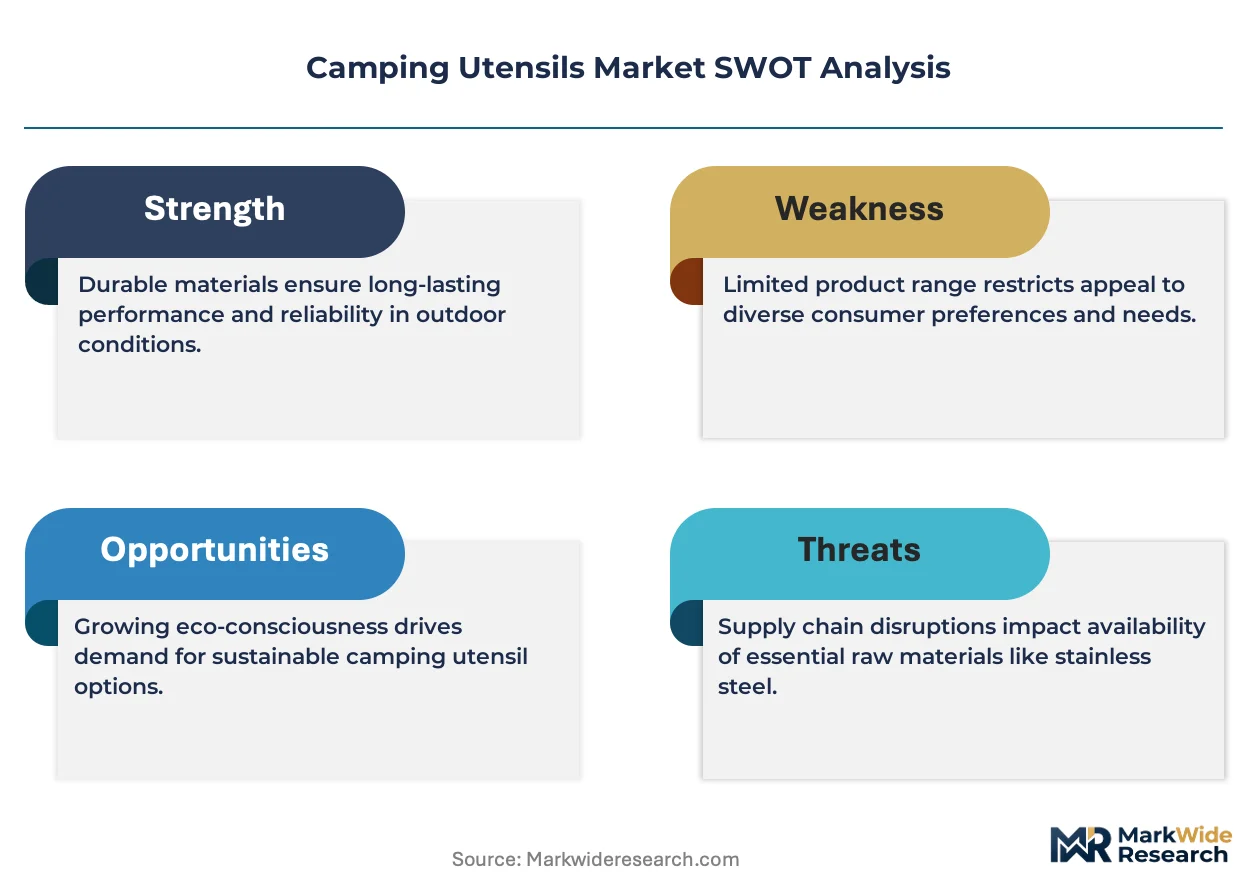
Camping utensils function as a regulatory compounder where ECHA REACH Annex XVII tightening accelerates material substitution demand toward compliant titanium and silicone alternatives.
For Market Incumbents: Cement shelf dominance by acquiring CNC machining specialists in Solingen with 5-axis aerospace crossover capability, countering hollow-handle geometry talent scarcity. Deepen backward integration into titanium sponge offtake agreements to buffer aerospace sector price volatility. Prioritize PVD ceramic finish partnerships ahead of epoxy-coat regulatory obsolescence.
For New Entrants and Emerging Players: REACH Annex XVII in Europe opens a window for silicone-titanium hybrid convergence plays targeting collapsible bowl-utensil formats with embedded reinforcing ribs. White-space concentrates in subscription-based gear replacement programs for thru-hiker mileage thresholds, and in US Inflation Reduction Act domestic content qualification for titanium-milled repositioning against imports. Go-to-market through Pacific Northwest trail community micro-influencer density.
For Investors and Strategic Acquirers: Roll-up economics work for precision metalworking specialists because CNC programming talent scarcity and FDA 21 CFR certification timelines create defensive moats against commoditization. Long-term viability hinges on titanium additive manufacturing convergence with topology optimization software. Watch for Appalachian Trail and Pacific Crest Trail registration data inflection as predictive logistics input for subscription program enrollment rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Nordic brands bypass wholesale markups and capture full margin on titanium sets through owned digital platforms. |
| Material Certification Investment | FDA 21 CFR compliance documentation for novel silicone formulations defends market access despite 8-14 month introduction delays. |
| Domestic Manufacturing Repositioning | US Inflation Reduction Act tax credits enable titanium-milled products to compete against imported stainless steel alternatives. |
| Subscription Program Launch | Annual refresh cycles tied to mileage thresholds concentrate in REI membership-dense Pacific Northwest communities. |
| PVD Ceramic Finish Adoption | Vacuum deposition equipment investment absorbs market share from southern European competitors dependent on legacy epoxy coatings. |
Study Parameters
Direct dialogue with CNC machining specialists, outdoor gear brand product managers, thru-hiker community organizers, titanium sponge procurement leads, and FDA regulatory consultants grounded qualitative findings. Secondary validation drew from ECHA REACH Annex XVII updates, FDA 21 CFR food-contact documentation, METI JIS standards filings, US trail registration databases, and Nordic outdoor retail audit data. Bottom-up and top-down triangulation reconciled unit shipment estimates with material input demand curves.
Bottom-up modeling segmented volume and value across product type, material grade, size format, and use case, with titanium sintering adoption curves and silicone substitution rates as industry-specific inputs. Top-down cross-checks anchored aggregate figures to precision metalworking capacity in Solingen-Pforzheim and Guangdong anodizing throughput. CAGRs derived from gear replacement frequency patterns among Pacific Crest Trail and Appalachian Trail completionists.
Revisions become necessary when ECHA REACH chemical restriction timelines accelerate, aerospace titanium sponge allocation priorities shift, or thru-hiker trail registration data inflects unexpectedly. Forecasts reflect documented assumptions about regulatory compliance cost pass-through and material substitution elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Cold Plunge Pools Market
Outdoor & Sports
Golf Trolley Market
Outdoor & Sports
Swimming Pool Accessories Market
Outdoor & Sports
Camping Cookware Market
Outdoor & Sports
Above Ground Swimming Pools Market
Outdoor & Sports
Europe Swimming Pools and Spas Market
Outdoor & Sports
Global Scuba Diving Equipment Market
Outdoor & Sports
Global Sailing Dinghy Masts Market
Outdoor & Sports
Camping Beds and Mats Market
Outdoor & Sports
Walkbehind Lawnmower Market
Outdoor & Sports
Swimming Pool Equipment Market
Outdoor & Sports
Global Pool Floats Market
Outdoor & Sports
Global Swimming Pool Market
Outdoor & Sports
Skateboard Ramp Market
Outdoor & Sports
Fish Hunting Equipment Market
Outdoor & Sports
Fire Pits Market