
 Chalcedony Earrings Market | 2026-2036
Chalcedony Earrings Market Size, Share, and Industry Trends Forecast 2026-2036
Chalcedony Earrings Market Analysis
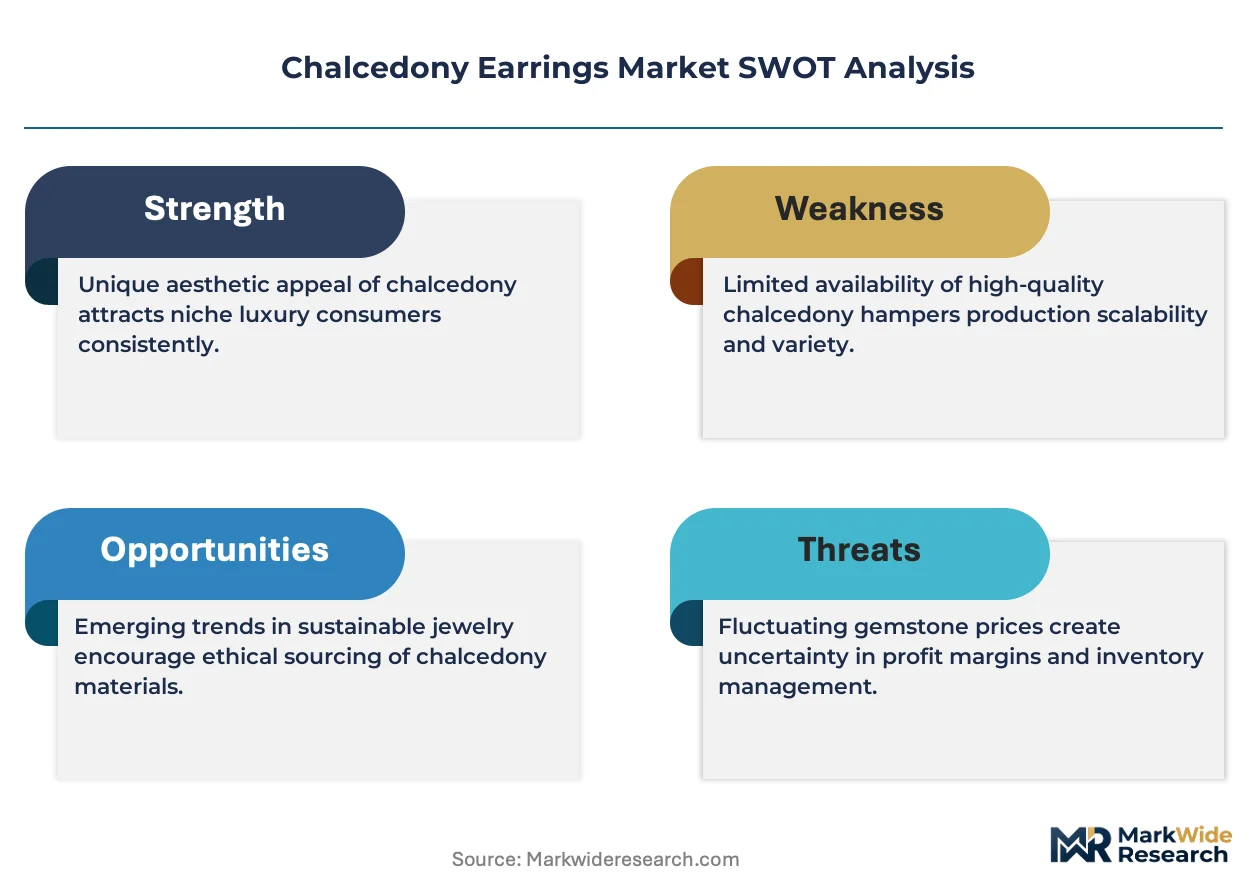
Asset-light consignment models is fragmenting competitive barriers in chalcedony earring retail, enabling smaller designers to access inventory without capital-heavy gemstone procurement. Tiffany & Co. leverages its vertically integrated sourcing architecture to secure premium chalcedony lots from established cutting centers. Pyramid & Precious International anchors its position through specialized lapidary relationships in Rajasthan. Wanderlust Life competes via direct artisan partnerships that emphasize provenance storytelling over scale.
Chalcedony earrings feature silica-based cryptocrystalline quartz fashioned into calibrated cabochons or faceted stones, typically measuring 6–12 mm, set in precious or base metal mountings for personal adornment. The material dimension stratifies sharply: gold settings capture the premium margin pool, while silver dominates unit volume among price-sensitive demographics. Stud configurations lead in everyday wear frequency, though bohemian-styled drops exhibit the strongest momentum in experiential retail and festival-adjacent commerce.
FDA oversight governs metal alloy safety in US-distributed chalcedony jewelry, while REACH and RoHS frameworks in Europe restrict cadmium and nickel content in earring posts and findings. These standards compel manufacturers to certify plating chemistries and solder compositions, raising compliance costs for cross-border sellers. Stakeholders must monitor evolving conflict-mineral disclosure rules and synthetic chalcedony detection protocols as laboratory-grown alternatives enter wholesale channels.
Market Dynamics
REACH compliance and artisanal sourcing transparency are compressing margins for mid-tier chalcedony earring manufacturers while rewarding vertically integrated ateliers with documented Rajasthan lapidary relationships.
Growth Catalysts
- Jaipur Cutting Clusters:Specialized gemstone-cutting infrastructure in Rajasthan supplies calibrated cabochons to global jewelry houses, reducing lead times for finished earring production.
- REACH Traceability Mandates:European Union chemical safety frameworks compel documented supply chains, favoring established ateliers with existing compliance infrastructure over opportunistic entrants.
- Direct-to-Consumer Ateliers:Millennial and Gen-Z buyers gravitate toward provenance-transparent purchasing models that bypass traditional wholesale markup structures.
Market Restraints
- Input Cost Volatility:Rough chalcedony pricing fluctuates with Ethiopian and Turkish mine output variability, compressing margin predictability for calibrated cabochon producers.
- Supply Concentration Risk:Jaipur's lapidary workshops handle an outsized share of global chalcedony cutting, creating single-point vulnerability for finished stone availability.
- Regulatory Friction:FDA metal alloy testing requirements for US-bound jewelry extend certification timelines, delaying inventory velocity for cross-border sellers.
Strategic Opportunities
- Laboratory-Grown Detection Protocols:Synthetic chalcedony identification standards create service revenue streams for gemological laboratories certifying natural origin claims.
- Festival-Adjacent Commerce:Bohemian-styled drop earrings capture experiential retail moments at music and wellness gatherings, bypassing traditional jewelry store distribution.
- Indian Domestic Demand:Urban Indian consumers exhibit rising appetite for semi-precious stone jewelry, creating localized growth outside export-dependent business models.
Industry Challenges
- Lapidary Skill Attrition:Master cabochon cutters in Rajasthan face generational succession gaps as younger workers migrate to technology sectors.
- Cross-Border Compliance Timelines:Dual certification requirements under REACH and FDA frameworks extend product launch cycles for multi-territory jewelry brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chalcedony Earrings Market |
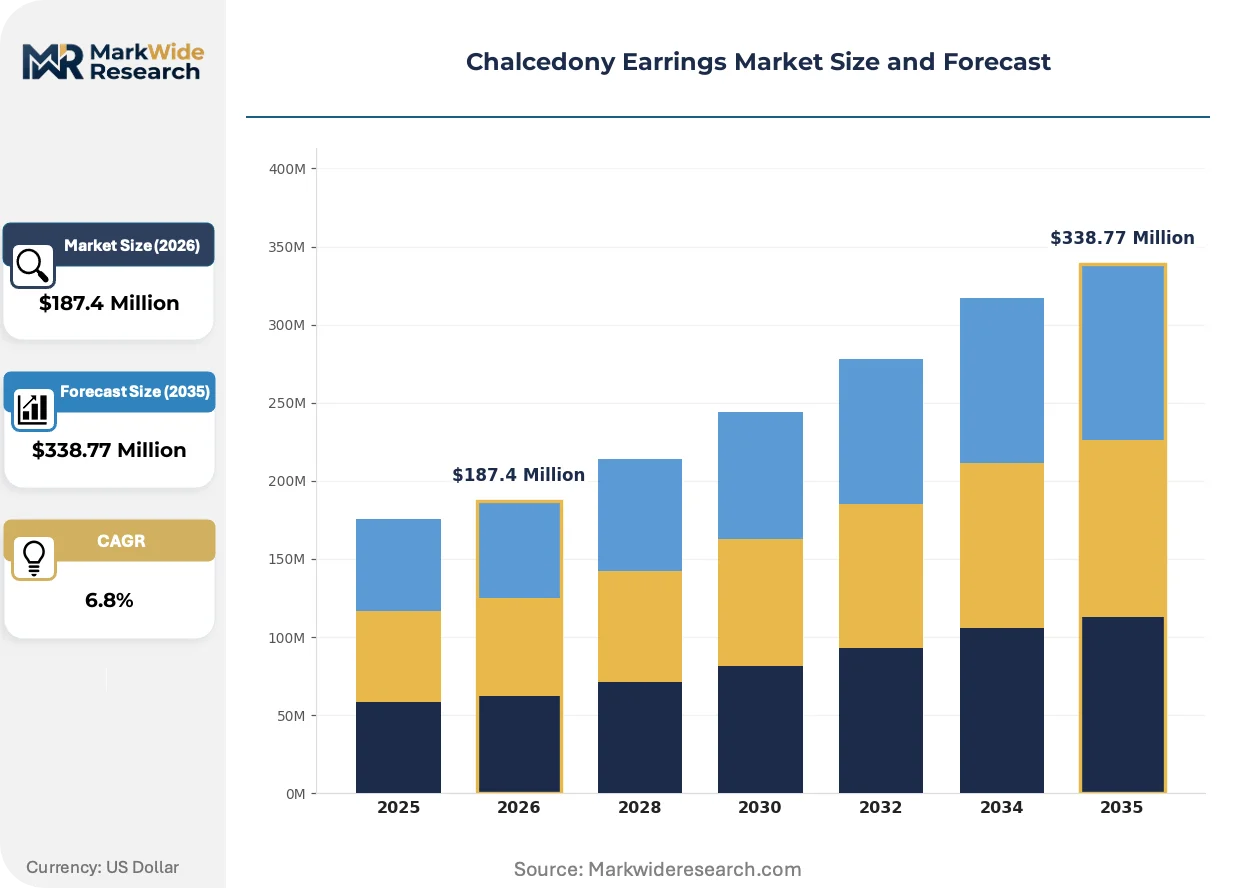
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Studs, Hoops, Drops, Chandeliers Material: Gold, Silver, Platinum, Brass Style: Contemporary, Vintage, Bohemian, Minimalist Target Audience: Women, Teens, Fashion Enthusiasts, Gift Buyers |
| Companies Covered | The Jewelry Channel, BLOOM JEWELRY LLC, Tiffany & Co., Pyramid & Precious International, Wanderlust Life, Gemporia Ltd., NOVICA United, Inc., Stauer.com, Ana Silver Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chalcedony Earrings Market Emerging Trajectories
Digital provenance verification and synthetic stone detection are reshaping trust architecture in chalcedony jewelry commerce, compressing the information advantage historically held by established dealers.
Laser-induced breakdown spectroscopy for origin verification is rendering obsolete traditional dealer-based provenance claims in high-value chalcedony transactions. Auction houses and collector-focused ateliers adopt portable spectrometers to validate Ethiopian versus Turkish source attribution. This technology is rendering obsolete the opacity that previously justified premium pricing for undocumented stones.
EU Green Deal sustainability disclosure requirements now extend to jewelry supply chains, mandating carbon footprint documentation for imported semi-precious stones. German and French retailers demand batch-level traceability certificates from Rajasthan suppliers. Small-scale Jaipur cutters without environmental management systems face exclusion from premium European retail channels.
Consignment-based inventory access lets emerging designers test chalcedony earring designs without capital-heavy gemstone procurement. Festival circuit vendors and direct-to-consumer ateliers replace wholesale showroom commitments with revenue-share arrangements. This model concentrates most visibly in Australian and Californian wellness-adjacent retail environments where brand storytelling outweighs inventory depth.
Chalcedony Earrings Market Segmentation
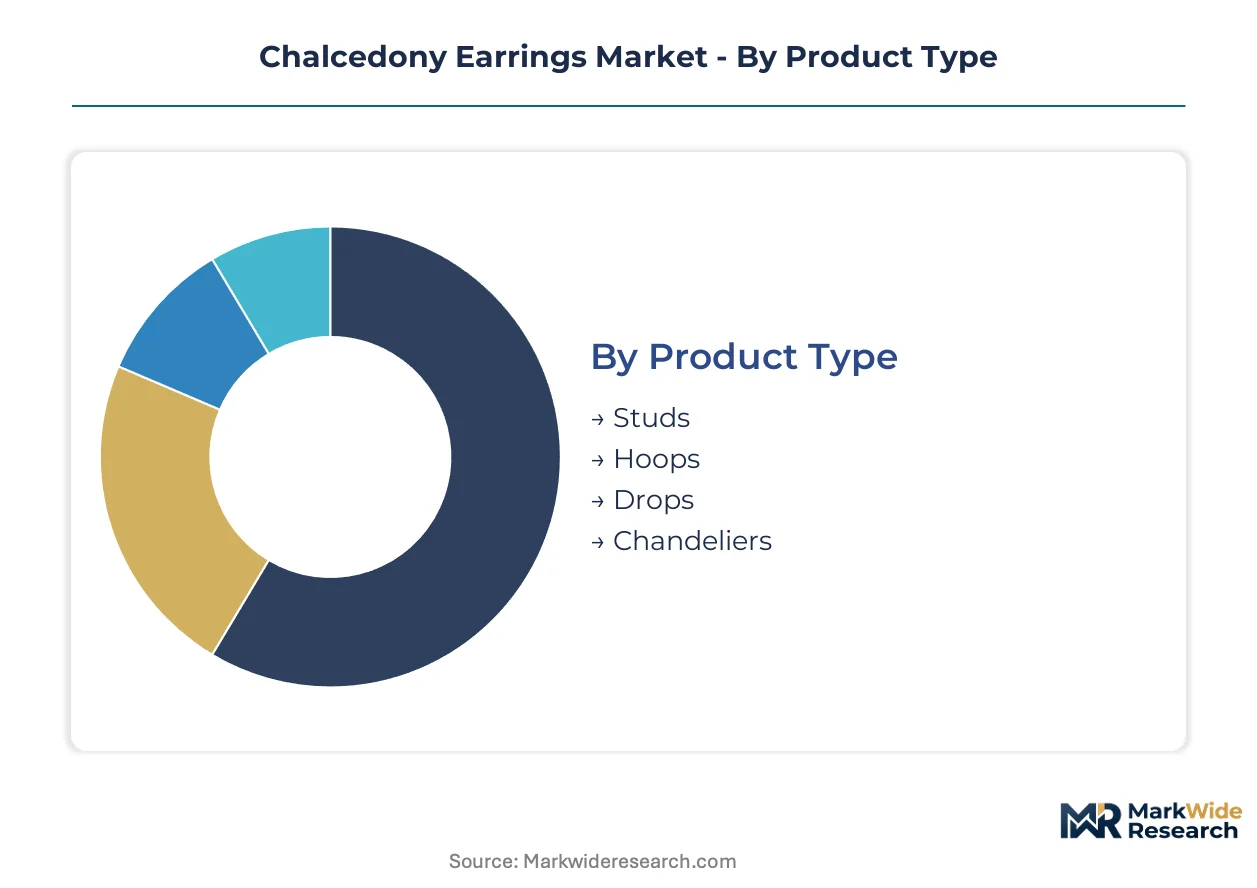
Chalcedony earring manufacturers configure production lines around distinct technical and aesthetic specifications. Each segment carries unique sourcing requirements, metalworking tolerances, and distribution channel preferences that shape margin structures.
Product Type:
After-sales service intensity varies dramatically across earring configurations, with complex multi-component designs demanding repair networks that simple studs rarely require.
- Studs:Single-stone cabochon settings dominate everyday wear frequency. Indian urban consumers and Western millennial buyers drive volume through direct-to-consumer channels that minimize post-purchase service touchpoints.
- Drops:Suspended stone arrangements require precise balance calibration and occasional component replacement. Festival-adjacent commerce and experiential retail in California and Australian wellness markets favor bohemian-styled drops with the steepest expansion trajectory among all configurations.
- Hoops:Continuous metal forms with integrated chalcedony accents demand hinge durability testing under FDA metal alloy frameworks.
- Chandeliers:Multi-tiered cascading designs concentrate in bridal and formal occasion segments with highest service incident rates.
By volume, Studs leads. By growth pace, Drops is ahead.
Material:
Cost tier stratification separates precious metal mountings from base metal alternatives, with plating chemistries subject to divergent regulatory burdens.
- Gold:Karat specifications from 10K to 18K determine alloy composition and REACH nickel content compliance. Premium margin pools concentrate here, though Ethiopian rough price volatility compresses predictability for finished goods.
- Silver:Sterling and Argentium variants capture unit volume leadership among price-sensitive demographics. German and French retailers now demand batch-level carbon footprint documentation from Rajasthan suppliers serving this tier.
- Platinum:Hypoallergenic properties command medical-adjacent positioning for sensitive skin segments.
- Brass:Base metal core with precious plating dominates fast-fashion and consignment-based inventory access models.
Gold commands the highest unit economics. Silver delivers the widest geographic penetration.
Style:
Application context dictates design vocabulary, with occasion-based usage patterns driving distinct procurement rhythms.
- Bohemian:Asymmetrical forms and mixed-metal aesthetics align with festival circuit vendors and wellness-adjacent retail. Laser-induced breakdown spectroscopy verification increasingly accompanies high-value pieces in this segment.
- Minimalist:Clean geometric lines and reduced metal weight appeal to Japanese METI-influenced quality standards and Scandinavian design preferences.
- Contemporary:Trend-responsive collections rotate quarterly through direct-to-consumer ateliers.
- Vintage:Period-reproduction settings require specialized lapidary relationships for calibrated cabochon matching.
Minimalist styling gains share in professional wardrobe contexts. Bohemian designs expand most quickly in experiential retail.
Target Audience:
Customer type determines channel strategy, with gift purchasers exhibiting distinct seasonal concentration and price elasticity profiles.
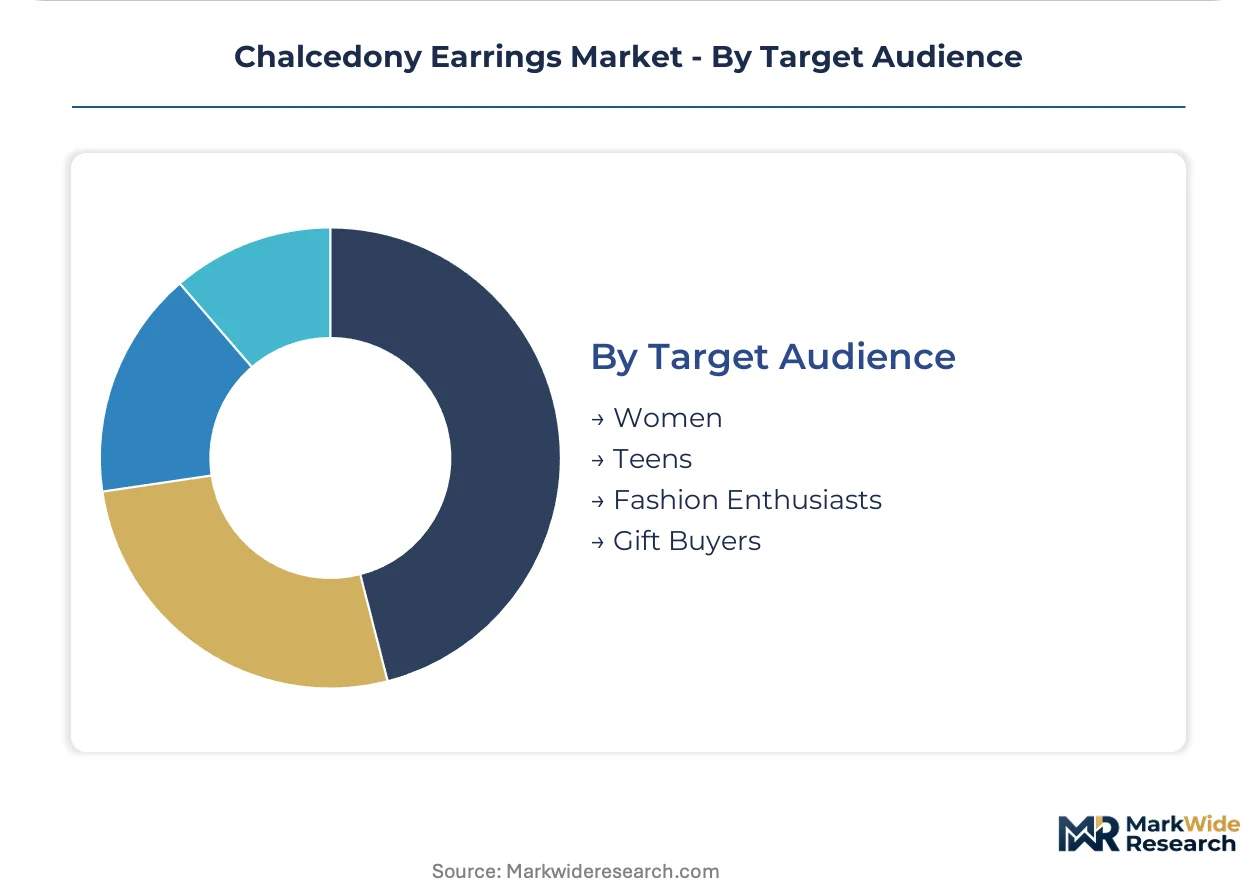
- Women:Core demographic spanning self-purchase and received-gift occasions. Urban Indian demand for semi-precious stone jewelry creates localized growth outside export-dependent models.
- Fashion Enthusiasts:Early adopters of synthetic chalcedony detection protocols and digital provenance verification systems.
- Teens:Entry-price sensitivity drives silver and brass concentration with social media-influenced design turnover.
- Gift Buyers:Occasion-driven purchasing concentrates around cultural calendar events, requiring packaging and certification bundles.
Women generate the revenue base. Fashion Enthusiasts set the technology adoption pace.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented jewelry manufacturing clusters in India and Turkey supply calibrated chalcedony cabochons to finished goods producers across North America and Europe. Import-dependent markets in the United States and Germany concentrate value-add activities in design and retail distribution rather than rough stone procurement.
United States
Direct-to-consumer ateliers in California and New York drive demand for provenance-transparent chalcedony earrings among millennial buyers. FDA metal alloy testing requirements extend certification timelines for cross-border sellers. Los Angeles-based consignment platforms enable emerging designers to access inventory without capital-heavy gemstone procurement.
Germany
EU Green Deal sustainability disclosure mandates now extend to jewelry supply chains, requiring carbon footprint documentation from Rajasthan suppliers. Berlin and Munich retailers demand batch-level traceability certificates for semi-precious stone imports. ECHA enforcement of REACH nickel content restrictions tightens plating chemistry standards for earring posts.
India
Urban consumers in Mumbai and Delhi exhibit rising appetite for semi-precious stone jewelry outside export-dependent business models. BIS quality certification requirements govern precious metal alloy specifications for domestic distribution. Jaipur's gemstone-cutting clusters supply calibrated cabochons to global manufacturers while facing generational succession gaps among master lapidary workers.
United Kingdom
London-based artisan jewelry collectives compete via provenance storytelling over scale, targeting festival-adjacent commerce and wellness-adjacent retail. UKCA marking requirements post-Brexit create parallel certification burdens alongside EU CE obligations. Birmingham's jewelry quarter maintains specialized metalworking capacity for precious metal mountings.
Australia
Wellness-adjacent retail environments in Sydney and Melbourne favor bohemian-styled drop earrings with digital provenance verification. TGA oversight of metal biocompatibility influences alloy selection for sensitive-skin positioning. Melbourne-based consignment platforms concentrate revenue-share arrangements for emerging designers testing chalcedony configurations.
Chalcedony Earrings Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in lapidary and metalworking functions. The vendor base stratifies between vertically integrated heritage houses and asset-light consignment-based ateliers. Three archetypes dominate: established jewelry houses with captive sourcing networks, direct-to-consumer brands emphasizing provenance transparency, and specialized lapidary-dependent exporters. Competitive moves concentrate on backward integration into Rajasthan cutting relationships and technology licensing for synthetic stone detection protocols.
Among heritage jewelry houses, Tiffany & Co. exemplifies the vertically integrated archetype with established cutting center relationships. Pyramid & Precious International occupies a position within the specialized lapidary-dependent tier. Wanderlust Life represents the direct-to-consumer model built on artisan partnerships rather than scale-driven manufacturing.
| Leading Market Players |
|---|
| The Jewelry Channel |
| BLOOM JEWELRY LLC |
| Tiffany & Co. |
| Pyramid & Precious International |
| Wanderlust Life |
| Gemporia Ltd. |
| NOVICA United, Inc. |
| Stauer.com |
| Ana Silver Co. |
| Others |
Supply Flow & Price Mechanics
Jaipur's lapidary workshops concentrate global chalcedony cutting capacity, anchoring margin pools in provenance-verified premium tiers while consignment-based retail fragments pricing power downstream. Gold-mounted calibrated cabochons capture the widest spreads, yet REACH compliance costs and synthetic detection protocols compress mid-tier manufacturer returns.
Pricing Analysis
Direct-to-consumer ateliers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on provenance documentation quality and metal alloy certification tier under FDA and REACH frameworks. Pricing pressure stems from Ethiopian rough volatility and laboratory-grown chalcedony detection investments. Teens and entry-price buyers exhibit highest sensitivity, while heritage jewelry houses with captive Rajasthan relationships maintain lowest price elasticity.
Supply Chain Analysis
Extended payment terms from German and French retailers strain Jaipur cutter cash conversion cycles, accelerating supply-chain finance facility adoption. Raw material flows draw from Ethiopian and Turkish rough deposits, with calibrated cabochon finishing concentrated in India. Single-source vulnerability concentrates in Rajasthan's aging master lapidary workforce. Distribution runs through direct-to-consumer ateliers, consignment platforms, and heritage jewelry houses with divergent markup structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward millennial and Gen-Z consumers aggregating through direct-to-consumer channels, fragmenting traditional wholesale gatekeeper control. This consolidation of purchase influence around provenance-transparent ateliers rewards documented supply chains over scale-driven manufacturing.
For Market Incumbents: Pre-empt synthetic chalcedony detection protocol standardization by licensing laser-induced breakdown spectroscopy capabilities before gemological laboratories capture service revenue streams. Deepen upstream control over Rajasthan lapidary relationships as generational succession gaps threaten calibrated cabochon supply security. Fortify REACH and FDA compliance infrastructure to extend certification timeline advantages over cross-border opportunists. For New Entrants and Emerging Players: Pursue festival-adjacent commerce white space in Australian and Californian wellness markets where bohemian-styled drops outperform traditional retail velocity. Target Indian domestic demand expansion in Mumbai and Delhi urban corridors outside export-dependent business models. Leverage consignment-based inventory access to test chalcedony configurations without capital-heavy gemstone procurement. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed direct-to-consumer jewelry platforms that have scaled provenance storytelling without captive manufacturing. Long-term viability over a 5-10 year window favors ateliers with documented Rajasthan lapidary partnerships and EU Green Deal carbon footprint compliance infrastructure. Monitor ECHA enforcement intensity on REACH nickel content restrictions as inflection indicator for plating chemistry investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory-Grown Detection Protocol Licensing | Gemological laboratories capture service revenue from natural origin certification demands under tightening EU disclosure rules. |
| Rajasthan Lapidary Partnership Deepening | Master cabochon cutter succession gaps threaten supply security for calibrated stone-dependent manufacturers. |
| Consignment Platform Expansion | Revenue-share arrangements enable emerging designers to bypass capital-heavy inventory procurement in California and Australian markets. |
| REACH Compliance Infrastructure Investment | ECHA nickel content enforcement tightens plating chemistry standards for earring posts and findings. |
| Indian Domestic Channel Development | BIS quality certification requirements govern precious metal specifications for Mumbai and Delhi urban consumer growth. |
Methodological Framework
Operator-level perspectives from Jaipur lapidary workshop owners, German jewelry retail procurement heads, California direct-to-consumer atelier founders, and FDA regulatory compliance consultants anchored the qualitative base. Secondary validation drew from ECHA enforcement bulletins, BIS certification registries, EU Green Deal supply chain disclosure mandates, and customs trade data on semi-precious stone flows. Bottom-up segment sizing triangulated against top-down market construction across product type, material, style, and target audience dimensions.
Scenario-bracketing framed volume and value outputs across the projection horizon, with CAGRs derived from calibrated growth rate synthesis rather than single-point extrapolation. Segmentation modeling spanned earring configuration, precious versus base metal mounting, design aesthetic category, and generational buyer archetype. Forecast inputs incorporated REACH regulatory friction timelines, Ethiopian mine output variability patterns, and synthetic chalcedony penetration assumptions in wholesale channels.
Sensitivities concentrate around ECHA enforcement intensity, master lapidary workforce attrition rates, and laboratory-grown stone detection protocol adoption speed. Forecasts reflect documented assumptions on regulatory trajectory and supply concentration stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Colorful Gold Jewelry Market
Jewelry
Pearl Jewelry Market
Jewelry
China Luxury Jewelry Market
Jewelry
Latin America Jewelry Market
Jewelry
Crystal Bracelets Market
Jewelry
Diamond Jewelry Market
Jewelry
Global Gems and Jewelry Market
Jewelry
Canada Luxury Jewelry Market
Jewelry
3D Printed Jewelry Market
Jewelry
China Jewellery Market
Jewelry
Jewellery Market
Jewelry
Imitation Jewelry Market
Jewelry
3D Printing Jewelry Service Market
Jewelry
Asia-Pacific Luxury Jewelry Market
Jewelry
Qatar Jewelry Market
Jewelry
Wedding Rings Market