
 Shoe Dryer Market | 2026-2036
Shoe Dryer Market Size, Share, and Industry Trends Forecast 2026-2036
Shoe Dryer Market Analysis
Premium-grade thermal management is unwinding the commodity layer of the shoe dryer category. Peet Shoe Dryer, Inc. leverages its convection-based heritage to sustain loyalty among hunting and military supply channels. IMPLUS dominates mass retail placement through broad sporting-goods distribution, while Williams Direct Dryers anchors the commercial-laundry and institutional segment with heavy-duty stainless-steel constructions.
A shoe dryer is an electromechanical appliance engineered to remove moisture from footwear through controlled heat dissipation, forced air circulation, or ultraviolet irradiation, typically operating within a temperature band of 40°C to 70°C to preserve material integrity. The device serves industrial hygiene programs, athletic facilities, and residential consumers seeking to extend footwear lifespan and prevent microbial colonization. Electric and heat-blowing configurations currently occupy the largest installed base, though UV-C and thermoelectric variants are capturing margin pools in medical and premium outdoor applications. Residential end users represent the volume foundation, while commercial sports teams and industrial safety programs generate the highest per-unit revenue and replacement frequency.
ISO 9001 quality-system certification and IEC 60335 household appliance safety standards govern electrical and thermal design parameters for export-oriented manufacturers. The EU F-Gas Regulation and REACH chemical-compliance frameworks restrict certain insulating and coating materials, compelling reformulation of heating-element housings. Stakeholders must monitor how emerging state-level energy-labelling requirements in the United States reshape minimum-efficiency thresholds and retail-access conditions.
Market Dynamics
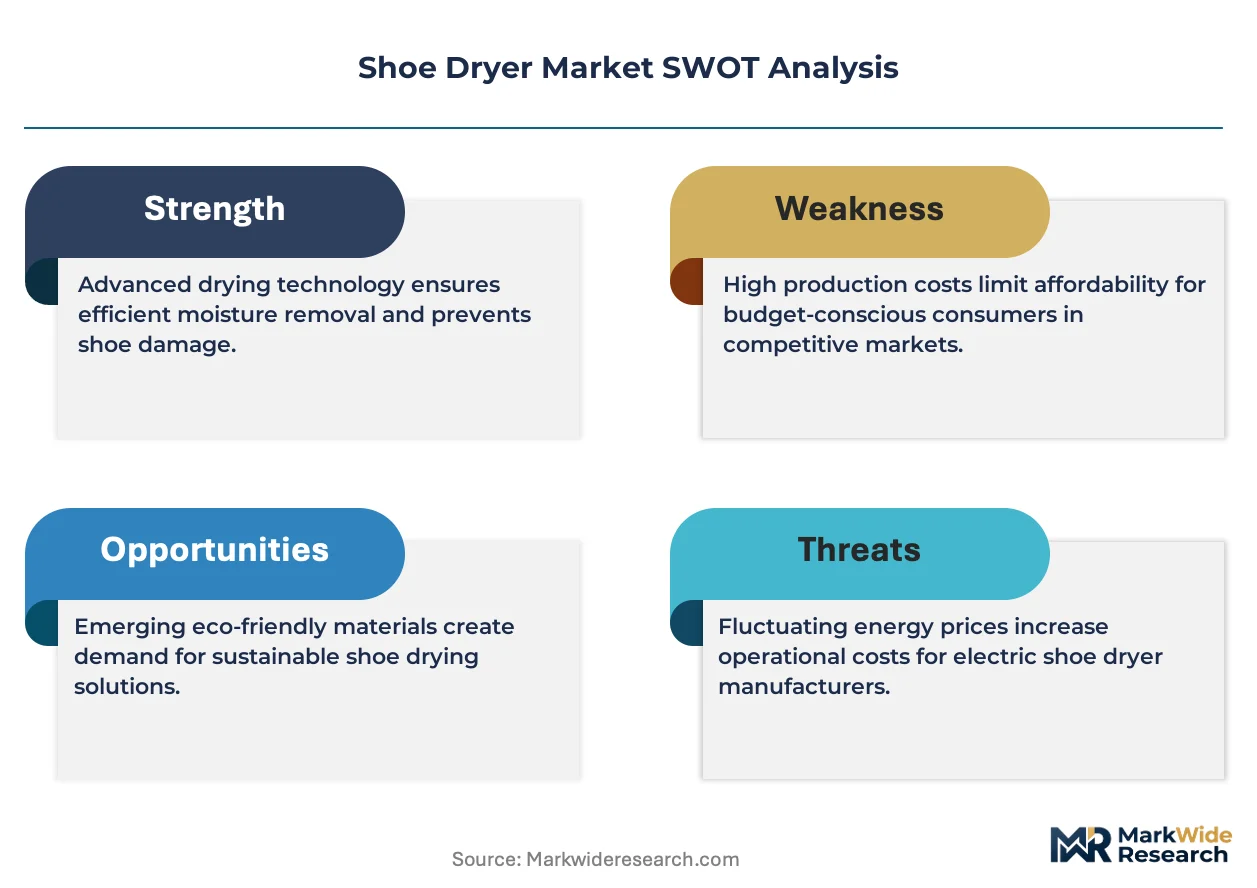
The EU Ecodesign Directive's tightening energy-efficiency mandates are forcing manufacturers to abandon high-wattage resistive heating in favor of thermoelectric and convection architectures, compressing margins for legacy thermal designs while rewarding engineering-heavy suppliers.
Growth Catalysts
- Institutional maintenance protocols:University athletic departments and professional sports franchises now mandate scheduled drying cycles as standard equipment hygiene, creating recurring replacement demand for commercial-grade units.
- REACH chemical compliance:Reformulation of heating-element housings to eliminate restricted coatings and insulators is accelerating product refresh cycles across European export channels.
- German building-energy codes:Strict residential efficiency standards in Germany are driving dual adoption of low-wattage residential units alongside commercial installations in outdoor retail and hospitality sectors.
Market Restraints
- Copper and nickel price volatility:Heating-element manufacturing remains exposed to base-metal commodity swings, compressing gross margins for mid-tier producers without long-term supply agreements.
- Input concentration in East Asian thermal componentry:Sourcing of PTC thermistors and mica insulating substrates clusters in specific manufacturing zones, creating geographic vulnerability in supply continuity.
- IEC 60335 certification timelines:Extended safety-testing protocols for household appliance export certification delay new product launches by 8-14 months, freezing working capital in pre-revenue inventory.
Strategic Opportunities
- UV-C medical applications:Ultraviolet irradiation variants are penetrating podiatric clinics and hospital infection-control programs, commanding 40-60% price premiums over thermal equivalents.
- US state-level energy-labelling expansion:Emerging efficiency-disclosure mandates in California, New York, and Massachusetts are creating first-mover advantage for pre-certified low-wattage designs.
- Direct-to-consumer outdoor channels:Specialty hunting, military-surplus, and backcountry retailers are bypassing mass sporting-goods intermediaries, capturing higher margins through enthusiast community targeting.
Industry Challenges
- Thermal engineering talent scarcity:Cross-disciplinary expertise combining materials science, fluid dynamics, and safety-system design concentrates in automotive and HVAC sectors, draining available labor pools for appliance-specialist firms.
- Legacy system integration friction:Industrial laundry and athletic-facility clients demand API connectivity with existing building-management platforms, forcing firmware-development investments outside core mechanical competencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shoe Dryer Market |
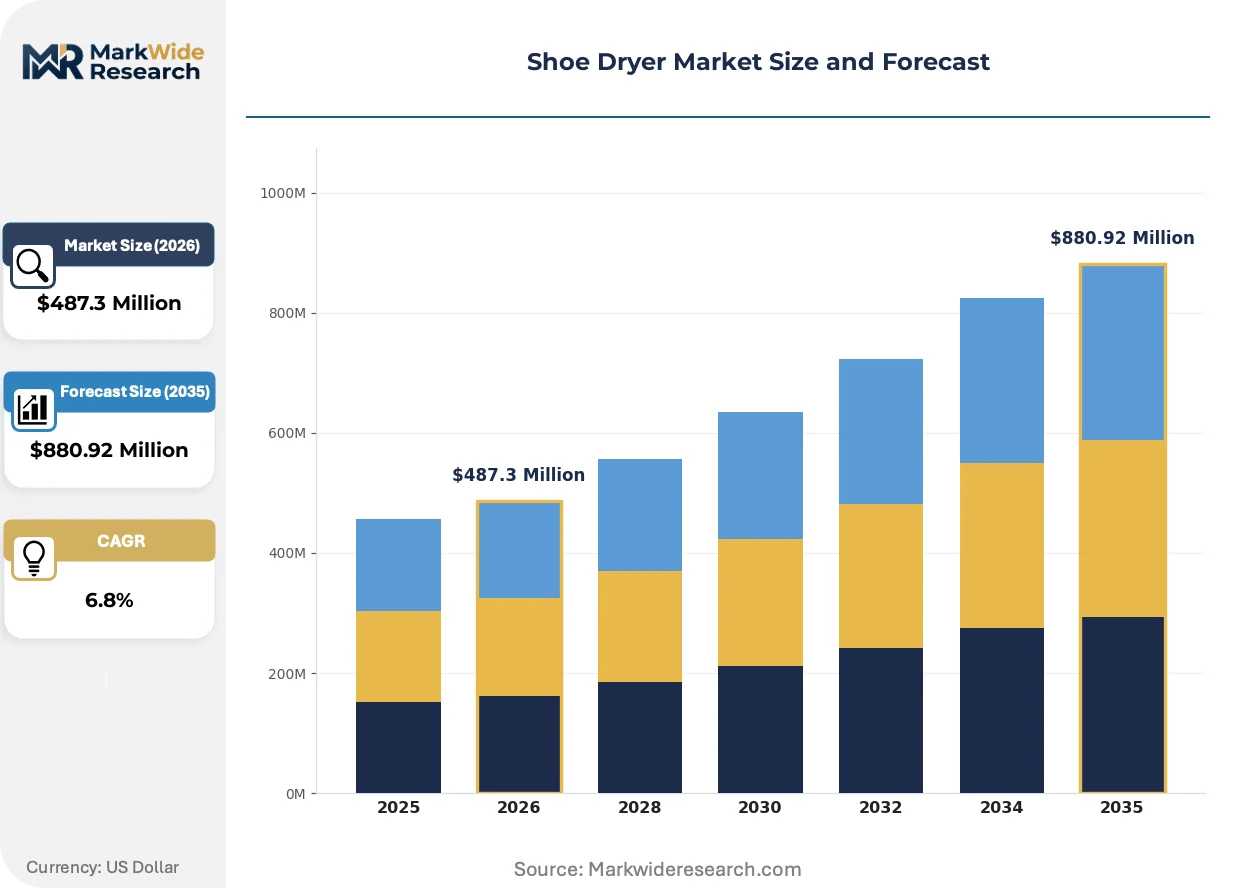
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Electric, Boot, UV-C Technology: Heat Blowing, Air Circulation, UV Sanitization, Thermoelectric End User: Residential, Commercial, Sports Teams, Industrial Installation: Wall-Mounted, Free-Standing, Compact, Built-In |
| Companies Covered | ADAX, StinkBOSS, Peet Shoe Dryer, Inc., Housmile Electronics, Taizhou Renjie Electric, IMPLUS, Williams Direct Dryers, Zhejiang Superhuman Technology, Caframo Limited (DryGuy), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shoe Dryer Market Emerging Trajectories
Thermoelectric cooling technology and ultraviolet sterilization are actively fragmenting what was once a uniform resistive-heating market, while procurement patterns in institutional channels shift toward lifecycle-cost contracting.
PTC (positive temperature coefficient) ceramic heating elements is bifurcating the installed base between legacy wire-wound resistive designs and self-regulating thermal architectures. Military procurement offices and alpine rescue services are specifying PTC-based units for field reliability, while budget-conscious residential buyers remain anchored to conventional convection models. This technology split is compressing the middle-market tier as engineering investment concentrates at opposite ends of the performance spectrum.
REACH and the EU F-Gas Regulation are restricting halogenated flame retardants and specific insulating polymers used in heating-element housings. Manufacturers serving European export markets must reformulate material specifications or face market exclusion, with the heaviest compliance burden falling on small-to-mid-tier producers lacking in-house toxicology and materials-science capabilities. German and Dutch testing laboratories report 18-month backlogs for alternative-substance verification.
Facility managers at collegiate athletic departments and municipal recreation centers are unbundling equipment procurement from maintenance contracts, preferring to lease drying systems with bundled service agreements rather than purchase capital assets outright. This shift compresses upfront revenue recognition while extending customer lifetime value for vendors with service-network density. The pattern is most pronounced in the US Northeast and Pacific Northwest, where deferred-maintenance backlogs have eroded confidence in self-managed equipment lifecycles.
Shoe Dryer Market Segmentation
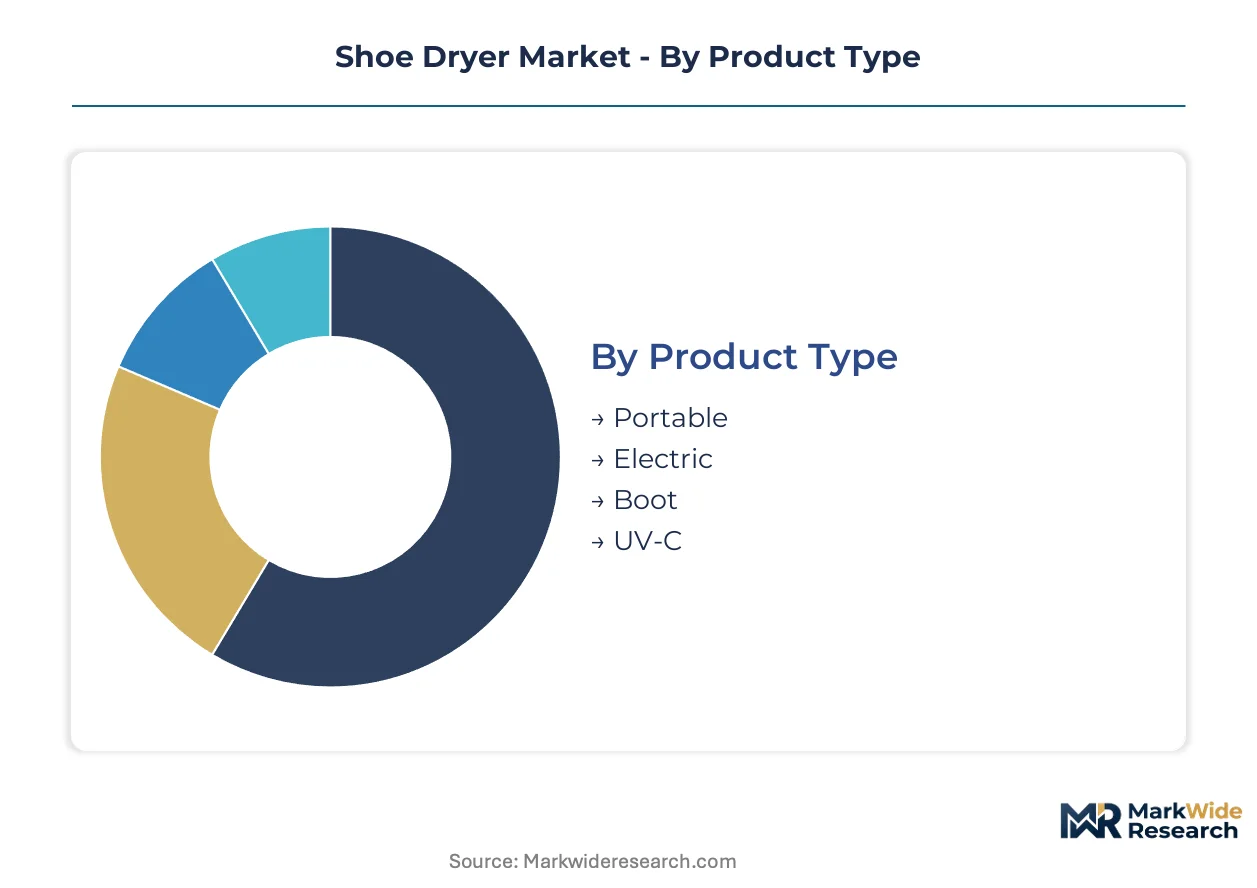
Segmentation in the shoe dryer market reveals how thermal engineering choices and installation constraints split purchasing behavior across consumer, institutional, and industrial channels. Understanding these divides exposes where engineering investment concentrates and which compliance frameworks govern each revenue pool.
Product Type:
Margin pools concentrate in specialized configurations that command durability premiums from institutional buyers rather than commoditized residential formats.
- Portable:Battery-operated or foldable units designed for field deployment by alpine rescue services and military supply chains. Demand from German outdoor retailers and Pacific Northwest hunting outfitters sustains price premiums despite lower wattage output.
- Electric:Standard plug-in convection or forced-air designs serving residential basements and small athletic facilities. IEC 60335 household appliance certification requirements and REACH material restrictions compress margins for manufacturers lacking in-house compliance teams.
- Boot:Heavy-duty configurations with extended shafts for waders, ski boots, and tactical footwear. Commercial fishing operations in Alaska and North Sea offshore platforms generate replacement cycles every 18-24 months due to salt corrosion exposure.
- UV-C:Ultraviolet irradiation modules penetrating podiatric clinics and hospital infection-control programs. Medical-grade certification and 40-60% price premiums over thermal equivalents attract engineering-heavy suppliers with existing healthcare channel relationships.
The dominant share belongs to Electric, while UV-C is closing the gap fastest.
Technology:
Architectural choices around thermal regulation determine which suppliers can access institutional procurement channels versus mass retail placement.
- Heat Blowing:Forced-air systems with resistive heating elements. Volume concentration in US big-box sporting goods and European home-improvement chains leaves little room for differentiation beyond wattage claims and timer features.
- Air Circulation:Passive convection designs leveraging natural airflow without active heating. Peet Shoe Dryer's heritage technology dominates hunting and military supply channels where silent operation and zero electromagnetic signature matter.
- UV Sanitization:Ultraviolet-C irradiation targeting microbial colonization in medical and premium outdoor applications. FDA device classification pathways and hospital procurement standards create barriers that filter out commodity manufacturers.
- Thermoelectric:Solid-state Peltier modules enabling precise temperature control without moving parts. EU Ecodesign Directive efficiency mandates and German building-energy codes accelerate specification in new construction and facility retrofits.
Thermoelectric configurations are expanding most quickly among institutional buyers, though Heat Blowing retains the largest installed base.
End User:
Customer type dictates service-model requirements and whether procurement favors capital purchase or operational expenditure structures.
- Residential:Individual consumers purchasing through retail or direct-to-consumer channels. German strict building-energy codes and US state-level efficiency-labelling expansion reshape minimum specifications and retail-access conditions.
- Commercial:Hotels, outdoor retail, and hospitality operations requiring continuous-duty cycles. Lifecycle-cost contracting and bundled maintenance agreements are displacing outright purchase in the US Northeast and Pacific Northwest.
- Sports Teams:University athletic departments and professional franchises mandating scheduled drying protocols. Recurring replacement demand and API connectivity requirements with building-management platforms favor vendors with service-network density.
- Industrial:Safety programs in mining, construction, and chemical processing where footwear integrity affects regulatory compliance. Per-unit revenue and replacement frequency exceed all other segments, though procurement cycles tie to capital budgeting calendars.
Residential volume foundations support manufacturer scale, while Industrial end users generate the steepest expansion trajectory in per-unit revenue terms.
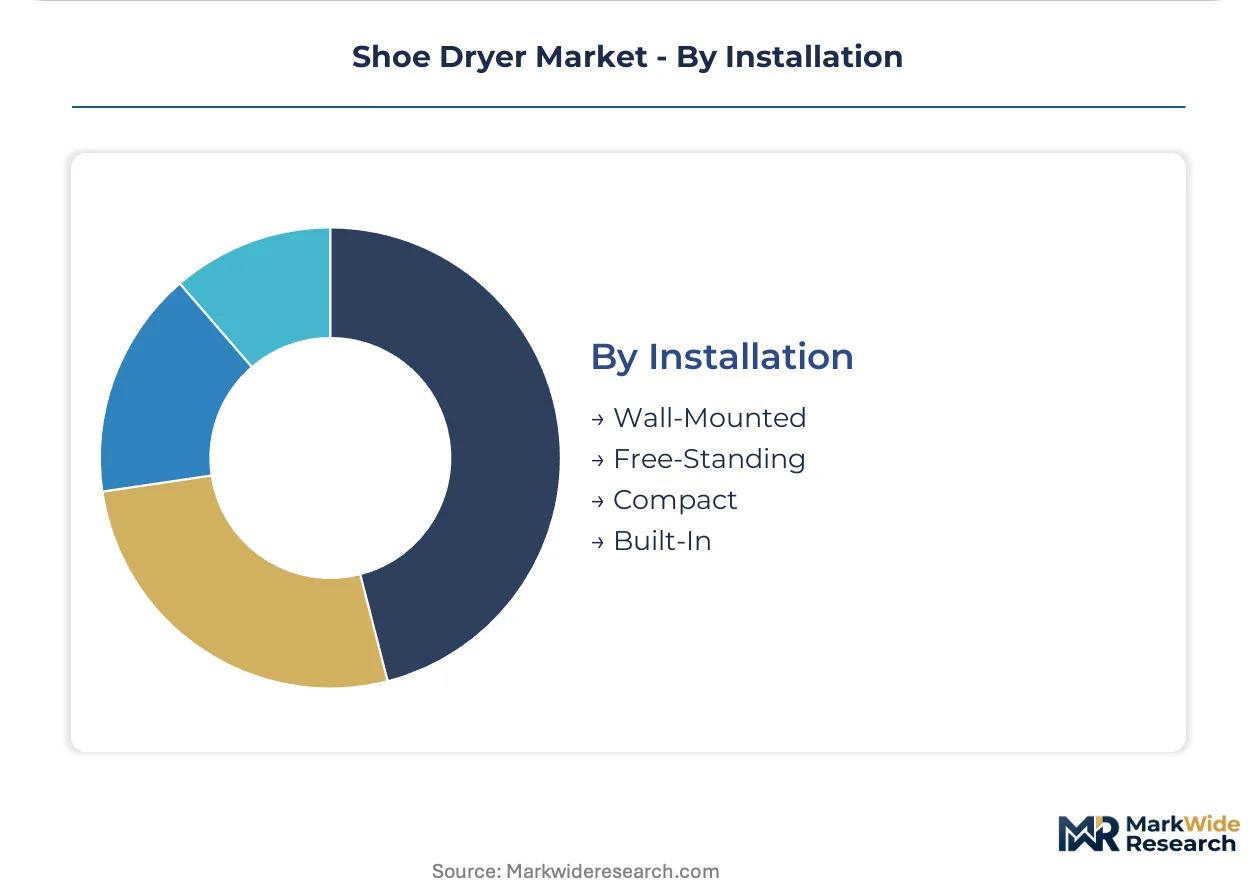
Installation:
Physical integration requirements separate retrofit opportunities from new-construction specification channels.
- Wall-Mounted:Fixed installations common in locker rooms, fire stations, and commercial laundry facilities. Municipal recreation centers and collegiate athletic departments favor space-efficient configurations that clear floor areas for other equipment.
- Free-Standing:Movable units on casters or stable bases serving multi-purpose spaces. Flexibility appeals to seasonal operations and rental properties where permanent modification is prohibited.
- Compact:Space-constrained designs for urban apartments, RVs, and marine vessels. Japanese METI efficiency standards and compact-living trends in Seoul and Singapore shape product development priorities.
- Built-In:Custom-integrated systems specified during construction or major renovation. German and Dutch building codes for new hospitality and healthcare construction create specification windows that close once drywall is sealed.
Free-Standing units hold the dominant share, though Built-In configurations are gaining share fastest in new European construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German buyers absorb efficiency premiums under strict building codes, while US mass-market consumers gravitate toward entry-level convection units. Emerging Asian demand concentrates in compact, low-wattage formats suited to dense urban housing.
Germany
Outdoor retail culture and stringent efficiency mandates drive dual adoption of residential and commercial units. The EU Ecodesign Directive and national building-energy codes enforce low-wattage thermal designs. Munich and Stuttgart anchor manufacturing clusters where alpine rescue services and hunting outfitters specify PTC-based field units.
United States
University athletic departments and professional sports franchises mandate scheduled drying protocols as standard equipment maintenance. Emerging state-level energy-labelling requirements in California, New York, and Massachusetts reshape retail-access conditions. The Pacific Northwest and Northeast concentrate lifecycle-cost contracting for commercial installations.
China
Domestic demand concentrates in compact formats for urban apartments and export manufacturing serves global private-label contracts. GB standards and MIIT efficiency guidelines shape product specifications. The Yangtze River Delta and Pearl River Delta host thermal component fabrication clusters for PTC thermistors and mica substrates.
Japan
METI efficiency standards and compact-living trends in Tokyo and Osaka prioritize space-constrained designs. Domestic procurement favors thermoelectric architectures for silent operation in dense residential settings. Nagoya-area manufacturers supply precision thermal regulation modules to regional appliance brands.
Netherlands
Hospitality and healthcare construction in Amsterdam and Rotterdam creates specification windows for built-in drying systems. REACH chemical-compliance frameworks and EU F-Gas Regulation restrict insulating materials, compelling reformulation of heating-element housings. Dutch testing laboratories report extended backlogs for alternative-substance verification.
Shoe Dryer Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the shoe dryer market. Engineering-intensive suppliers capture institutional premiums through thermoelectric and UV-C architectures, while mass-market placement rewards scale-driven manufacturers with broad sporting-goods distribution. The competitive terrain splits into heritage convection specialists, diversified appliance conglomerates, and medical-grade sterilization entrants. Dominant competitive moves include geographic expansion into direct-to-consumer outdoor channels and portfolio diversification toward UV-C medical applications.
Within the heritage convection tier, Peet Shoe Dryer, Inc. and Caframo Limited (DryGuy) occupy positions anchored by hunting and military supply relationships. Among diversified mass-market players, IMPLUS exemplifies scale-driven placement through sporting-goods retail networks. Williams Direct Dryers represents the commercial-laundry and institutional segment with heavy-duty stainless-steel fabrications. Zhejiang Superhuman Technology and Taizhou Renjie Electric sit within the export manufacturing cluster serving global private-label demand.
| Leading Market Players |
|---|
| ADAX |
| StinkBOSS |
| Peet Shoe Dryer, Inc. |
| Housmile Electronics |
| Taizhou Renjie Electric |
| IMPLUS |
| Williams Direct Dryers |
| Zhejiang Superhuman Technology |
| Caframo Limited (DryGuy) |
| Others |
Supply Flow & Price Mechanics
PTC ceramic heating elements displacing wire-wound resistive designs in institutional procurement are simultaneously shifting sourcing geography toward Yangtze River Delta fabrication clusters and compressing price premiums for legacy thermal architectures.
Pricing Analysis
After-sales service revenue from bundled maintenance contracts and replacement heating-element subscriptions drives lifetime value for commercial-grade suppliers. Three-tier pricing structure across premium thermoelectric, standard convection, and economy resistive levels separates institutional buyers from mass-market consumers. Pricing pressure stems from copper and nickel commodity volatility in heating-element manufacturing, squeezing mid-tier producers lacking long-term metal supply agreements. Industrial safety programs exhibit lowest price sensitivity due to regulatory compliance mandates, while residential consumers in big-box retail channels demonstrate highest elasticity.
Supply Chain Analysis
Inbound logistics costs through Shanghai-Ningbo and Shenzhen port corridors determine landed cost competitiveness for thermal component imports. PTC thermistor fabrication concentrates in China's Yangtze River Delta, mica insulating substrate production clusters in India's Kerala and Tamil Nadu regions, and precision thermal regulation module assembly anchors in Japan's Nagoya industrial belt. Raw material dependencies span copper-nickel heating alloys, ceramic PTC substrates, and halogen-free flame-retardant polymers. Single-source vulnerability in East Asian thermistor supply creates geographic concentration risk. Distribution runs through sporting-goods retail networks, direct-to-consumer outdoor channels, and institutional procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API connectivity requirements with building-management platforms signal a platform-economics inflection, as athletic facilities and commercial laundry operators demand firmware-integrated drying systems rather than standalone appliances.
For Market Incumbents: Secure exclusive distribution partnerships with German outdoor retail chains and Pacific Northwest hunting outfitters to defend against direct-to-consumer entrants. Deepen backward integration into PTC thermistor sourcing through captive supply agreements with Yangtze River Delta fabricators. Accelerate IEC 60335 pre-certification for low-wattage portfolios ahead of US state-level energy-labelling expansion.
For New Entrants and Emerging Players: Firmware-development capabilities for building-management platform integration represent a service-layer gap where established mechanical specialists under-serve institutional buyers. Target collegiate athletic departments in the US Northeast with lifecycle-cost contracting models that bundle equipment lease and predictive maintenance. Penetrate podiatric clinic channels through FDA device classification pathways for UV-C sterilization variants.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed diversified appliance conglomerates seeking portfolio rationalization toward higher-margin healthcare and industrial verticals. Five-to-ten-year viability hinges on thermoelectric and UV-C technology migration rather than legacy resistive heating exposure. Acquisition target archetype: engineering-heavy suppliers with existing healthcare channel relationships and in-house REACH compliance capabilities. Watch for REACH alternative-substance verification backlog resolution at Dutch and German testing laboratories as inflection indicator for European export channel access.
| Strategic Initiative | Industry Significance |
|---|---|
| PTC Thermistor Backward Integration | Captive supply from Yangtze River Delta fabricators insulates margin from copper-nickel volatility. |
| API-Enabled Firmware Development | Building-management platform connectivity satisfies collegiate athletic department procurement mandates. |
| UV-C Medical Certification Pathway | FDA device classification unlocks podiatric clinic and hospital infection-control revenue pools. |
| REACH Alternative-Substance Pre-Verification | Dutch and German laboratory relationships accelerate European export channel compliance timelines. |
| Direct-to-Consumer Outdoor Channel Expansion | Specialty hunting and military-surplus retail bypasses mass sporting-goods margin compression. |
Methodological Framework
Operator-level perspectives from facility managers at collegiate athletic departments, commercial laundry procurement directors, and aftermarket service heads at industrial safety programs anchored the qualitative base. Primary interview findings triangulated against secondary validation from customs records of thermal component trade flows, SEC filings of diversified appliance manufacturers, and EU Ecodesign Directive implementation reports. Bottom-up unit economics from product-type and end-user segmentation combined with top-down macroeconomic drivers across the analysis window.
Sensitivity analysis tested forecast robustness against copper-nickel price volatility scenarios and REACH compliance timeline variations. The analytical framework modeled volume and value outputs across product type, technology architecture, end-user category, and installation format dimensions throughout the projection horizon. CAGRs derived from fitted growth curves incorporating EU Ecodesign Directive efficiency mandate adoption rates and US state-level energy-labelling expansion patterns.
Underlying assumptions cover sustained institutional procurement shift toward lifecycle-cost contracting, with deviation risk concentrated in IEC 60335 certification timeline extensions and East Asian thermal component supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Bladeless Neck Fan Market
Household Items
Cups and Pots Market
Household Items
Aquarium Heaters and Chillers Market
Household Items
Air Care Market
Household Items
Handheld Fans Market
Household Items
Floor-Standing Integrated Smart Toilet Market
Household Items
Soap Tablet Market
Household Items
Asia Pacific Residential Vacuum Cleaners Market
Household Items
Smart Fork Market
Household Items
Coffin and Cremation Urn Market
Household Items
Smart Memory Foam Market
Household Items
Mosquito Repellent Candles Market
Household Items
Dosage Spoon Market
Household Items
Dryer Sheets Market
Household Items
Basin, Bowl, and Cup Market
Household Items
Copper Water Bottle Market