
 Global Digital Experience Management Software Market | 2026-2036
Global Digital Experience Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Experience Management Software Market Foresight
The capability gap between cloud-native architectures and legacy on-premise stacks is reorganizing competitive hierarchies in digital experience management. Adobe leverages its creative cloud ecosystem to extend platform stickiness across enterprise marketing workflows. Sitecore anchors its position through deep .NET specialization that sustains loyalty among large European manufacturers. Oracle competes by embedding experience tools within its broader database and ERP infrastructure, controlling procurement decisions at the CIO level.
Digital experience management software orchestrates content delivery, user interaction analytics, and cross-channel personalization through API-first platforms that typically process sub-100-millisecond response thresholds for real-time engagement. Its primary commercial purpose is to unify fragmented customer touchpoints into measurable, optimizable journeys that drive conversion and retention. Cloud deployment now leads solution delivery as enterprises prioritize elastic scaling over capital-intensive data center commitments. Personalization engines represent the fastest-growing solution offering as first-party data strategies replace deprecated third-party cookie infrastructures. Customer journey analytics commands premium pricing due to the scarcity of vendors combining behavioral modeling with privacy-compliant identity resolution.
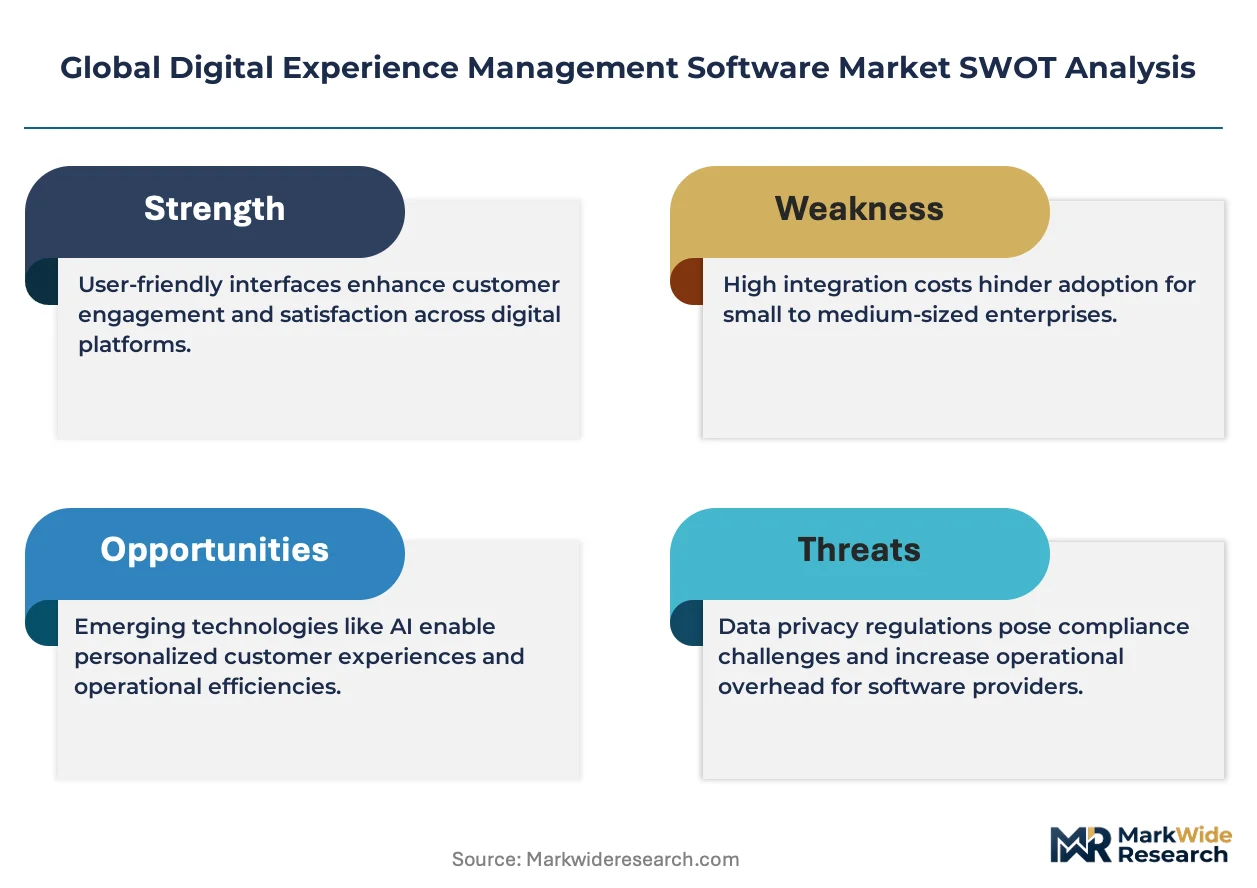
The EU AI Act and GDPR jointly constrain how personalization engines deploy automated profiling, forcing vendors to build explainability layers and consent management into core architectures. The US FTC's emerging guidance on dark patterns and deceptive design further shapes product roadmaps for domestic and multinational suppliers. Stakeholders must weigh interoperability investments against the risk of vendor lock-in as platform consolidation accelerates and regulatory fragmentation deepens across jurisdictions.
Market Dynamics
The deprecation of third-party cookies is decomposing legacy personalization architectures, forcing enterprises to rebuild engagement stacks around first-party data lakes and server-side identity resolution. Cloud-native vendors capture this displacement while incumbents retrofit consent management and edge computing layers into aging codebases.
Growth Catalysts
- EU AI Act compliance mandates:Automated decision-making transparency requirements are accelerating procurement of explainable personalization engines with built-in audit trails.
- Financial services digitization:Banks and insurers are deploying compliant customer engagement platforms to unify branch, mobile, and advisor touchpoints under single governance frameworks.
- Edge computing infrastructure:Sub-100-millisecond response requirements for real-time personalization are pulling compute closer to end users through distributed architecture investments.
Market Restraints
- GDPR Article 22 friction:Automated profiling restrictions in the European Union create legal uncertainty that slows deployment of AI-driven recommendation engines.
- Cloud egress cost volatility:Unpredictable data transfer fees between hyperscale providers and edge nodes compress margins for API-first platform vendors.
- Legacy .NET codebases:Deep entrenchment of proprietary Microsoft stacks in European manufacturing creates switching costs that delay modernization cycles.
Strategic Opportunities
- Industrial B2B commerce digitization:German manufacturers are rebuilding procurement portals and dealer networks with composable experience layers.
- Composable architecture convergence:MACH (Microservices, API-first, Cloud-native, Headless) standards are enabling interoperability between best-of-breed vendors.
- US FTC dark patterns guidance:Emerging enforcement against deceptive design creates demand for ethical UX auditing and compliant engagement frameworks.
Industry Challenges
- Identity resolution engineering scarcity:Shortage of specialists who can unify behavioral signals across devices without violating privacy regulations.
- Multi-cloud orchestration complexity:Enterprises struggle to maintain consistent personalization logic across AWS, Azure, and Google Cloud environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Experience Management Software Market |
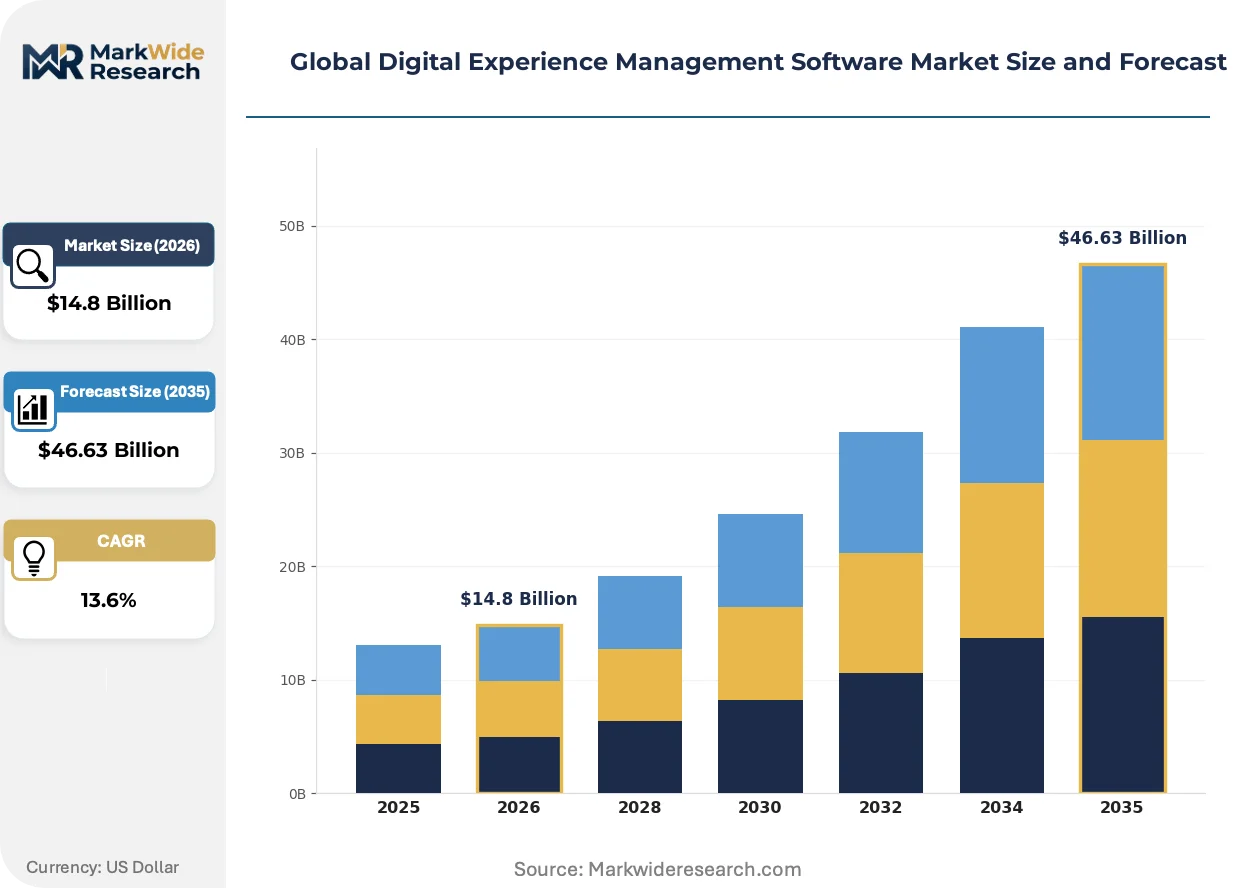
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $46.63 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud, On-Premise, Hybrid, SaaS, Managed Services Solution Offering: Customer Journey Analytics, Content Management, Personalization Engine, Marketing Automation, Digital Asset Management Use Case: Customer Engagement, Brand Experience, Campaign Optimization, User Behavior Tracking, Lead Generation End User Industry: Telecommunications, Media & Entertainment, Financial Services, Education, Public Sector |
| Companies Covered | Adobe, Sitecore, Acquia, Oracle, Salesforce, SAP, Liferay, Optimizely, Bloomreach, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Experience Management Software Market Shifts & Advancements
Experience orchestration is fragmenting into specialized microservices that enterprises assemble through API marketplaces rather than monolithic suites. This architectural shift is redistributing value toward integration specialists and away from full-stack incumbents.
Headless content management is decomposing traditional page-based publishing into modular content APIs that feed any frontend. Retailers and media companies are adopting these architectures fastest, decoupling content creation from presentation layers. The structural consequence is collapsing vendor switching costs as enterprises mix content sources rather than accepting single-platform lock-in.
The EU AI Act's risk classification system is forcing vendors to build algorithmic impact assessments into product workflows. High-risk personalization systems now require human oversight mechanisms and documentation trails. Financial services and healthcare sectors in Germany and France are restructuring procurement to prioritize vendors with pre-certified compliance architectures.
Subscription pricing for experience platforms is displacing perpetual licenses as buyers prioritize operational flexibility over capital ownership. Mid-market enterprises in the United States are driving this shift, demanding consumption-based models that scale with traffic volatility. The change compresses upfront revenue for vendors while extending customer lifetime value through recurring engagement.
Global Digital Experience Management Software Market Segmentation
Segmentation in digital experience management software reveals how deployment constraints, solution maturity, and industry-specific compliance requirements reshape vendor strategies. Each dimension exposes different purchasing logics: infrastructure teams prioritize deployment flexibility while marketing operations demand solution-specific capabilities.
Deployment:
Cloud-native architectures dominate North American procurement cycles, while European and Asian enterprises retain substantial on-premise footprints due to data sovereignty mandates.
- Cloud:Elastic scaling architectures process personalization workloads across distributed regions with sub-100-millisecond latency requirements. Financial services firms in Singapore and the United States favor this model for disaster recovery flexibility.
- On-Premise:Dedicated infrastructure maintains full data custody within enterprise firewalls, satisfying German industrial manufacturers and Japanese financial institutions with strict localization requirements. High capital expenditure and 3-5 year refresh cycles constrain agility.
- Hybrid:Workload portability between private data centers and public cloud instances enables phased migration for legacy-dependent sectors.
- SaaS:Multi-tenant platforms eliminate infrastructure management overhead, accelerating procurement for mid-market enterprises without dedicated DevOps resources.
- Managed Services:Third-party operational control combines cloud economics with compliance expertise, appealing to healthcare and public sector buyers in France and Canada.
Cloud commands the established base. The steepest expansion runs through SaaS.
Solution Offering:
Customer-facing capabilities attract premium pricing while back-office infrastructure solutions compete on operational efficiency metrics.
- Customer Journey Analytics:Behavioral modeling platforms unify cross-channel signals into attribution frameworks, commanding premium valuations due to scarce privacy-compliant identity resolution engineering. German automotive and telecommunications sectors drive concentrated demand.
- Personalization Engine:Real-time decisioning systems deploy machine learning models for individualized content delivery, replacing deprecated third-party cookie infrastructures. EU AI Act explainability requirements reshape vendor architectures.
- Content Management:Headless APIs decouple creation from presentation, collapsing switching costs as enterprises mix sources.
- Marketing Automation:Campaign orchestration tools trigger multi-step engagement sequences based on behavioral thresholds.
- Digital Asset Management:Centralized media repositories enforce brand governance across distributed creative workflows.
Content management anchors legacy installed bases. Personalization engines are gaining share fastest.
Use Case:
Revenue-generating applications outpace cost-center implementations in procurement priority and budget allocation.
- Customer Engagement:Unified touchpoint orchestration integrates branch, mobile, and advisor channels under single governance frameworks. Banks in Switzerland and Australia prioritize compliant engagement platforms.
- Lead Generation:Conversion-optimized experiences capture prospect intent through progressive profiling and dynamic form adaptation. B2B technology vendors in Israel and the United States deploy these most aggressively.
- Brand Experience:Consistent visual and tonal identity execution across markets protects enterprise equity value.
- Campaign Optimization:Real-time creative and audience testing improves media efficiency for consumer-facing advertisers.
- User Behavior Tracking:Privacy-preserving analytics reconstruct session flows without persistent identifiers.
Brand experience holds incumbent positions. Lead generation shows the steepest climb.
End User Industry:
Regulatory intensity varies dramatically, with financial services and public sector imposing the strictest procurement standards.
- Financial Services:Banks and insurers deploy compliant engagement platforms to unify customer touchpoints while satisfying SEC, FCA, and MAS oversight. First-party data strategies replace third-party dependencies.
- Telecommunications:Subscriber retention platforms process billions of interaction events across billing, support, and upgrade journeys. Operators in South Korea and Brazil invest heavily in churn prediction.
- Media & Entertainment:Subscription and advertising revenue optimization drives personalization depth for streaming and publishing properties.
- Education:Student lifecycle management unifies recruitment, retention, and alumni engagement for universities.
- Public Sector:Citizen service portals must satisfy accessibility mandates and procurement transparency requirements.
Telecommunications maintains volume leadership. Financial services delivers the sharpest upward trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by jurisdiction. United States enterprises prioritize cloud-native elasticity and consumption-based pricing. German manufacturers demand on-premise data custody and EU AI Act-compliant explainability layers. Financial services firms in Singapore and Switzerland anchor compliance-heavy procurement cycles.
United States
Financial services digitization and media streaming personalization drive deployment velocity. FTC guidance on dark patterns and deceptive design reshapes product roadmaps for domestic suppliers. New York and San Francisco metro clusters concentrate vendor headquarters and enterprise buyer decision-making.
Germany
Industrial B2B commerce digitization and automotive supplier network modernization command procurement budgets. GDPR Article 22 and EU AI Act risk classifications constrain automated profiling deployments. Munich and Stuttgart manufacturing belts rebuild procurement portals with composable experience architectures.
United Kingdom
Retail media networks and subscription publishing platforms invest in first-party data infrastructure. UK Information Commissioner's Office enforcement on cookie consent mechanisms accelerates server-side identity resolution adoption. London's fintech corridor demands compliant customer engagement frameworks for wealth management interfaces.
Japan
Telecommunications subscriber retention and loyalty program digitization absorb platform investment. METI guidelines on data governance influence vendor selection criteria for domestic enterprises. Tokyo and Osaka metropolitan enterprises balance cloud migration with strict localization requirements for financial data.
Singapore
Wealth management digitization and cross-border trade finance platforms prioritize low-latency personalization. Monetary Authority of Singapore technology risk management guidelines shape procurement standards for banking technology. The city-state's regional headquarters concentration positions it as ASEAN deployment coordination hub.
Global Digital Experience Management Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that fragments across solution categories. Cloud-native challengers displace legacy on-premise incumbents through API-first architectures and composable deployment models. Strategic archetypes include creative ecosystem bundlers, ERP-embedded platform vendors, and headless commerce specialists. Competitive moves concentrate on M&A for identity resolution capabilities and strategic partnerships for edge computing infrastructure.
Within the integrated leader tier, Adobe and Salesforce occupy positions defined by creative cloud and CRM ecosystem bundling respectively. Oracle exemplifies the database-anchored archetype that controls procurement through CIO-level infrastructure relationships. Sitecore represents the .NET-specialized incumbent sustaining loyalty among European manufacturing through deep legacy stack integration.
| Leading Market Players |
|---|
| Adobe |
| Sitecore |
| Acquia |
| Oracle |
| Salesforce |
| SAP |
| Liferay |
| Optimizely |
| Bloomreach |
| Others |
Supply & Pricing Matrix
Hyperscale cloud capacity utilization above eighty percent in AWS US-East and Azure Frankfurt regions compresses marginal compute costs for API-first platform vendors, concentrating pricing power among vendors with captive infrastructure while forcing smaller players toward multi-tenant SaaS models with thinner margins.
Pricing Analysis
Managed services and extended implementation contracts drive lifetime value for digital experience management platforms, with subscription tiers stratifying across enterprise, mid-market, and entry-level bands based on API call volumes and identity resolution complexity. Price differentiation rests on GDPR compliance certification tiers and edge node geographic density, with EU AI Act explainability features commanding premiums. Pricing pressure stems from cloud egress cost volatility between hyperscale providers, compressing margins for vendors without direct peering agreements. Mid-market enterprises in the United States exhibit highest price sensitivity, while German automotive manufacturers prioritize compliance over cost.
Supply Chain Analysis
Strait of Malacca cable transit underwrites sub-100-millisecond latency guarantees for ASEAN personalization workloads, creating infrastructure dependencies that concentrate risk. Software supply chains draw from United States hyperscale infrastructure, Indian engineering services clusters, and Irish data residency facilities for EU compliance. Dependencies center on GPU accelerators from Taiwan, identity resolution SDKs from Israel, and consent management frameworks from Germany. Single-source vulnerability in NVIDIA H100 allocation creates procurement bottlenecks for real-time inference workloads. Distribution runs through systems integrators and cloud marketplaces rather than direct enterprise sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composable architecture standards and MACH interoperability are fragmenting platform economics, redistributing value from monolithic suites toward integration specialists and API-first vendors.
For Market Incumbents: Compound platform stickiness through deeper creative cloud workflow embedding and edge computing infrastructure partnerships that lock in latency-sensitive financial services clients. Defend against headless commerce specialists by accelerating .NET modernization roadmaps for European manufacturing accounts. Prioritize EU AI Act pre-certification investments to capture German automotive procurement cycles.
For New Entrants and Emerging Players: Anchor in identity resolution engineering scarcity by building privacy-compliant server-side stitching tools for first-party data lakes. Target mid-market B2B manufacturers in the United States with composable experience layers that bypass legacy Sitecore dependencies. Lead with consumption-based pricing and rapid time-to-value implementations against perpetual-license incumbents.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vendors with pre-built EU AI Act compliance architectures and established edge node distribution. Long-term viability hinges on composable interoperability rather than full-stack bundling. Monitor FTC dark patterns enforcement intensity as a signal for ethical UX auditing demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Merges customer journey analytics with Salesforce CRM ecosystems for unified attribution. |
| Acquisition of Specialist Firm | Captures scarce identity resolution engineering talent from Israeli privacy-tech startups. |
| Strategic Partnership | Establishes edge computing nodes with AWS Local Zones for sub-100ms financial services latency. |
| Product Launch | Introduces explainable personalization engines with built-in EU AI Act audit trails. |
| Geographic Expansion | Builds German data residency facilities to capture GDPR Article 22-compliant manufacturing demand. |
Research Methodology
The analysis maps personalization engines, customer journey analytics, content management systems, and marketing automation platforms, each validated through CTOs at financial services firms, platform engineers at systems integrators, and procurement officers at German automotive manufacturers. Primary interviews triangulate with secondary sources including SEC filings from Adobe and Salesforce, hyperscaler capex disclosures from AWS and Azure, and EU AI Act implementation guidance from the European Commission. Bottom-up deployment modeling and top-down market sizing reconcile through iterative stakeholder validation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segments by deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs derive from elasticity-adjusted adoption curves and first-party data infrastructure investment cycles. Cloud-native displacement rates and legacy .NET modernization timelines serve as key forecast inputs.
Decision-makers should treat outputs as directional under sustained GDPR enforcement and EU AI Act rollout assumptions; material deviation in regulatory interpretation would warrant model refresh. Practitioners should keep alternative scenarios live as FTC dark patterns guidance and third-party cookie deprecation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Audit Software Market
Software & Services
Global Managed Application Services Market
Software & Services
Global Organizational Change Management Software Market
Software & Services
Global Reporting Software Market
Software & Services
OCR Scanning Software Market
Software & Services
Global Professional Service Automation (PSA) Software Market
Software & Services
Europe Human Resource (HR) Technology Market
Software & Services
Europe Contract Lifecycle Management Software Market
Software & Services
Global Brand Management Software Market
Software & Services
Data Conversion Services Market
Software & Services
Observability Platform Market
Software & Services
Global Cloud Enterprise Resource Planning Market
Software & Services
Global Text to Speech (TTS) Software Market
Software & Services
File Analysis Software Market
Software & Services
Taxi Booking Software Market
Software & Services
Salesforce Services Market