
 ATM Outsourcing Services Market | 2026-2036
ATM Outsourcing Services Market Size, Share, and Industry Trends Forecast 2026-2036
ATM Outsourcing Services Market Analysis
Community banking and credit union verticals is realigning ATM outsourcing priorities toward managed services and remote monitoring. Cardtronics leverages its North American fleet density to sustain operational leverage across rural and urban networks. NCR Atleos differentiates through software integration capabilities that anchor multi-vendor ATM estates for mid-tier financial institutions.
ATM outsourcing services encompass the full operational delegation of automated teller machine deployment, maintenance, cash replenishment, and network management to third-party specialists, typically governed by service-level agreements specifying uptime thresholds of 99.5 percent and cash availability guarantees. These arrangements eliminate capital intensity for banks while ensuring continuous consumer cash access across distributed physical footprints. Cash management and security services command the largest revenue pools within service type segmentation, reflecting the labor-intensive nature of vault operations and PCI-DSS compliance burdens. Cloud-based solutions within technology segmentation represent the fastest-expanding category, as remote monitoring platforms displace on-premise legacy architectures and enable predictive maintenance algorithms.
The Federal Reserve's cash access policies and the Federal Deposit Insurance Corporation's operational risk guidelines shape outsourcing decisions for US banking institutions, while the European Banking Authority's outsourcing guidelines and the EU's Digital Operational Resilience Act impose stringent third-party oversight requirements across European markets. The Reserve Bank of India's financial inclusion mandates and cash handling regulations further standardize outsourced ATM operations in emerging markets. Stakeholders must evaluate whether captive ATM operations or third-party contracts offer superior resilience against evolving cybersecurity standards and central bank digital currency pilots.
Market Dynamics
Cloud-based remote monitoring architectures are compressing operational response times from days to hours, forcing incumbent service providers to restructure field technician deployment models and recalibrate cash forecasting algorithms around predictive analytics rather than static replenishment schedules.
Growth Catalysts
- PCI-DSS compliance mandates:United States financial institutions face escalating audit costs for in-house ATM security, accelerating delegation to specialists with certified vault operations and encrypted transaction processing infrastructure.
- Financial inclusion targets:Reserve Bank of India directives mandate expanded rural cash access, driving state banks toward managed service contracts that eliminate capital expenditure for low-density deployments.
- Predictive maintenance algorithms:Machine learning models trained on sensor telemetry reduce cash-out incidents and hardware downtime, converting reactive break-fix contracts into premium uptime-guarantee arrangements.
Market Restraints
- Armored logistics concentration:Cash-in-transit services depend on a limited pool of licensed security carriers, creating bottlenecks in rural route density and elevating per-site servicing costs.
- Legacy hardware heterogeneity:Multi-vendor ATM estates spanning NCR, Diebold, and Hyosung architectures complicate unified software integration and extend certification timelines for security patches.
- Central bank digital currency pilots:Experimental CBDC programs in India, China, and the European Union introduce long-term substitution risk for physical cash infrastructure investment decisions.
Strategic Opportunities
- Rural India penetration gap:Managed service providers can capture five-year exclusive contracts under the RBI's financial inclusion framework, locking in cash replenishment and first-line maintenance revenue.
- API-first platform convergence:Integration of ATM networks with mobile banking applications and real-time payment rails creates cross-selling channels for transaction-based service fees.
- EU Digital Operational Resilience Act:DORA's third-party risk management requirements position certified outsourcing vendors as mandatory compliance partners for European credit unions and regional banks.
Industry Challenges
- Certified technician scarcity:Multi-vendor hardware expertise combined with cybersecurity clearances creates recruitment bottlenecks, extending mean-time-to-repair in secondary markets.
- Legacy core banking integration:SOAP-based middleware and proprietary protocols in incumbent financial institutions complicate real-time cash position reporting and delay cloud migration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ATM Outsourcing Services Market |
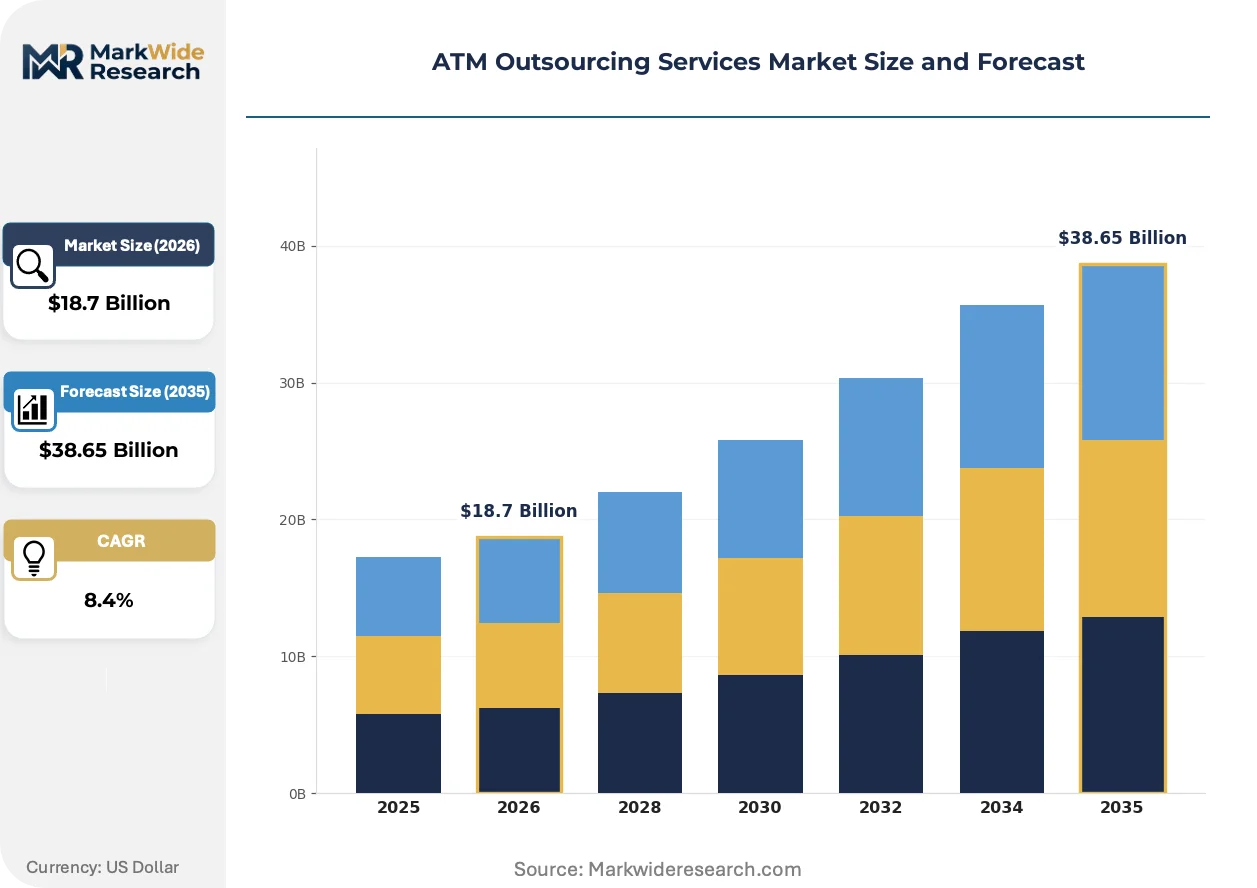
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cash Management, Maintenance, Telecommunications, Security Services Client Type: Banking Institutions, Retail Chains, Independent ATM Deployers, Financial Service Providers Deployment Model: On-site, Off-site, Managed Services, Full Service Technology: Cloud-based Solutions, Software Integration, Remote Monitoring, Security Protocols |
| Companies Covered | Cardtronics, Hitachi Channel Solutions, NCR Atleos, Euronet Worldwide, GRG Banking, Diebold Nixdorf, Fujitsu, Cennox, Brink’s, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ATM Outsourcing Services Market Emerging Trajectories
ATM outsourcing is pivoting from hardware maintenance contracts toward integrated cash-ecosystem management, with artificial intelligence and regulatory automation compressing the traditional service stack into unified platform offerings.
Edge computing nodes deployed within ATM cabinets is electrifying transaction processing latency and enabling real-time fraud detection without cloud round-trips. Tier-two financial institutions in the United States are adopting these architectures fastest, driven by FFIEC cybersecurity guidance. The structural consequence is a collapse in the distinction between hardware maintenance and software security services, forcing vendors to bundle both under single service-level agreements.
REACH regulations in the European Union now restrict hazardous substances in ATM component manufacturing, compelling fleet operators to audit supplier chemical disclosures and retrofit older machines with compliant power supplies and circuit boards. German and French banking consortiums have consolidated procurement specifications to pre-certified hardware lists, marginalizing vendors without documented substance compliance. The affected segment—cash recycler modules—faces accelerated replacement cycles as 2019-era equipment fails new environmental audits.
Subscription-based managed service contracts are displacing traditional break-fix arrangements across North American credit unions, with pricing indexed to transaction volume rather than device count. This shift compresses vendor revenue recognition into monthly recurring streams while transferring uptime risk to service providers. The transformation is most visible in community banking verticals, where IT staff consolidation has eliminated in-house ATM expertise entirely.
ATM Outsourcing Services Market Segmentation
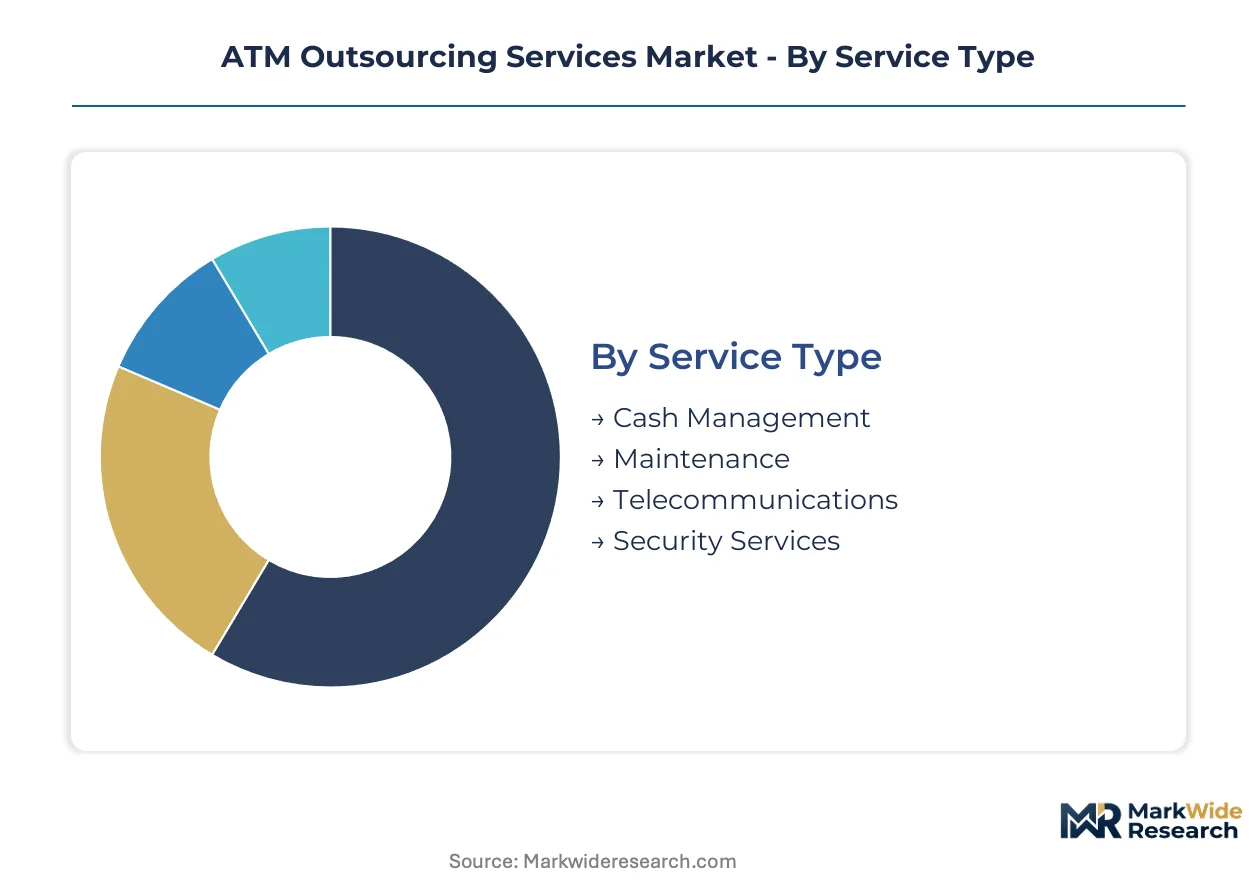
ATM outsourcing contracts stratify sharply by operational depth, with cash-intensive services commanding premium pricing while technology layers enable margin expansion through recurring software fees. Banks and retailers select service bundles based on capital constraints, regulatory exposure, and geographic dispersion of their ATM footprints.
Service Type:
Standalone cash handling commands the largest contract values, whereas integrated security and telecom services embed within broader managed service frameworks.
- Cash Management:Vault operations, cash forecasting, and replenishment scheduling absorb the highest labor and armored logistics costs. Indian state banks under RBI financial inclusion mandates deploy these services most intensively across rural low-density networks.
- Maintenance:Hardware break-fix and preventive servicing span multi-vendor estates of NCR, Diebold, and Hyosung machines. PCI-DSS compliance mandates in the United States accelerate outsourcing as certified technician scarcity raises in-house costs.
- Telecommunications:Dedicated leased lines and cellular backup connectivity ensure transaction uptime.
- Security Services:Encrypted transaction processing and physical vault certification.
Volume placements concentrate in Cash Management; the faster expansion belongs to Security Services.
Client Type:
Capital intensity and regulatory sophistication determine whether clients purchase discrete services or comprehensive managed arrangements.
- Banking Institutions:Tier-one and mid-tier banks with distributed branch networks. United States community banks consolidate ATM operations under outsourcing to eliminate in-house expertise gaps.
- Retail Chains:Grocery and convenience store operators expanding ATM footprints to reduce internal cash handling costs. Deployment concentrates in high-traffic urban corridors where transaction velocity offsets per-site servicing premiums.
- Independent ATM Deployers:Non-bank operators monetizing surcharge revenue.
- Financial Service Providers:Credit unions and payment processors.
Contract volumes skew toward Banking Institutions; Independent ATM Deployers are gaining share fastest through surcharge-funded rural expansion.
Deployment Model:
Ownership and risk allocation vary from client-managed hardware to complete third-party operational assumption.
- On-site:ATMs located within bank branches or retail premises with client-controlled access. European credit unions under DORA requirements favor this model for direct oversight of critical infrastructure.
- Off-site:Standalone machines in transit hubs, shopping centers, and convenience stores. Indian managed service providers capture five-year exclusive contracts for off-site rural deployments under RBI inclusion frameworks.
- Managed Services:Third-party operation with client-retained ownership.
- Full Service:Complete hardware, software, and operational delegation.
Revenue concentrates in Managed Services; Full Service contracts are climbing the fastest as subscription pricing displaces break-fix arrangements.
Technology:
Cloud architectures and API integration separate premium service tiers from legacy maintenance contracts.
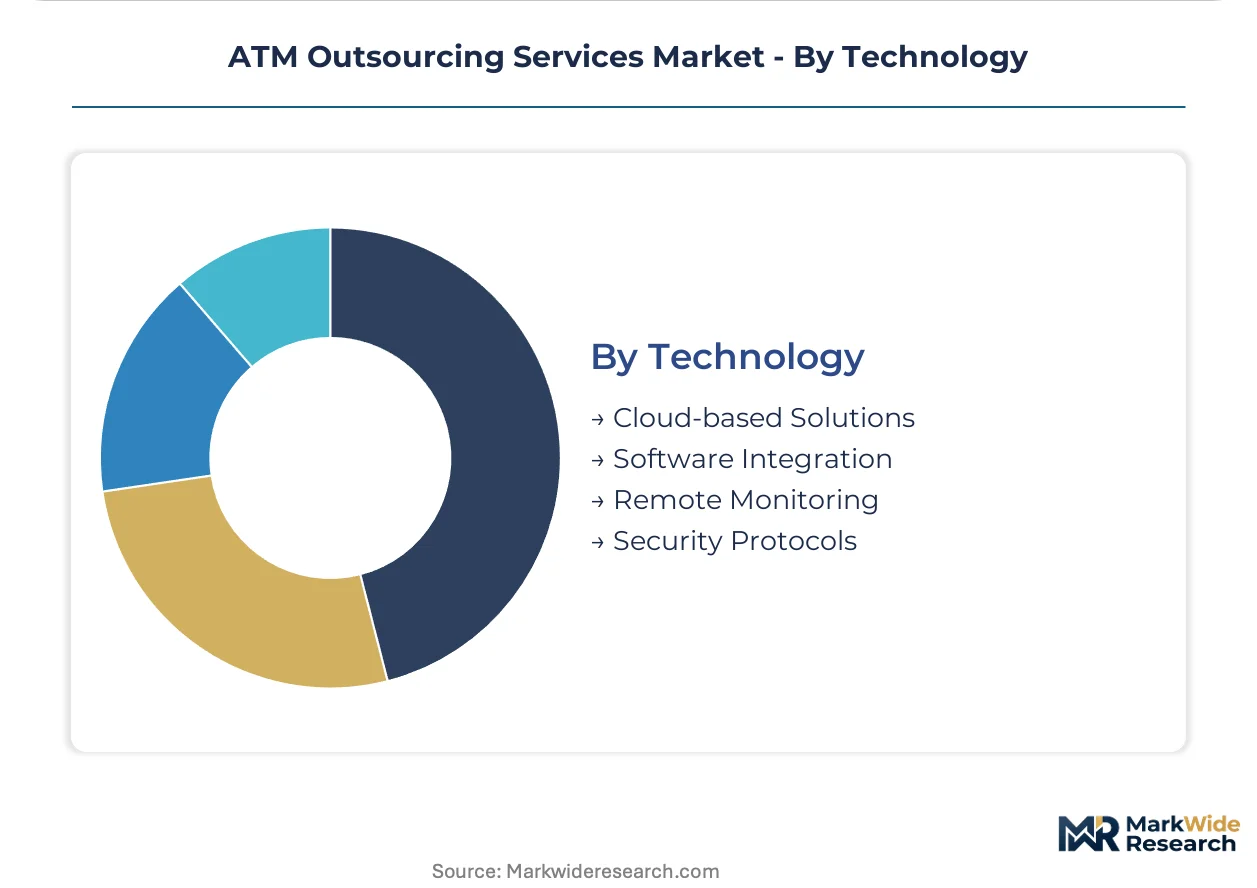
- Cloud-based Solutions:Remote monitoring platforms with predictive analytics and real-time cash position reporting. United States tier-two institutions adopt these fastest under FFIEC cybersecurity guidance.
- Software Integration:Middleware connecting multi-vendor ATM estates to core banking systems. SOAP-based legacy protocols in incumbent banks complicate deployment timelines.
- Remote Monitoring:Sensor telemetry enabling predictive maintenance algorithms.
- Security Protocols:PCI-DSS certified encryption and fraud detection layers.
Deployment volumes center on Software Integration; Cloud-based Solutions represent the steepest expansion trajectory as edge computing nodes compress response times from days to hours.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's special economic zones for financial technology infrastructure have concentrated ATM outsourcing contract awards in Mumbai and Bangalore corridors. State banks leverage these zones to minimize capital expenditure on rural deployments.
United States
Community banks in the Great Plains and Southeast regions delegate entire ATM estates to managed service providers. The Federal Deposit Insurance Corporation's operational risk guidelines force smaller institutions toward third-party operational resilience. Chicago and Dallas metropolitan clusters host the densest concentrations of armored logistics coordination centers.
Germany
Sparkassen and cooperative banking networks outsource cash recycler maintenance across Bavaria and North Rhine-Westphalia. The EU Digital Operational Resilience Act imposes mandatory third-party oversight requirements on critical infrastructure contracts. Frankfurt's banking consortiums have consolidated procurement specifications to pre-certified hardware lists.
India
State Bank of India and regional rural banks deploy managed services across Maharashtra and Gujarat under Reserve Bank of India inclusion mandates. The central bank's cash handling regulations standardize outsourced vault operations for low-density networks. Hyderabad and Chennai serve as operational hubs for predictive maintenance platform development.
United Kingdom
Building societies and credit unions consolidate ATM operations following IT staff reductions in Yorkshire and Scotland. The Financial Conduct Authority's outsourcing guidance mandates enhanced due diligence on critical service providers. London's fintech corridor attracts cloud-based remote monitoring platform vendors serving tier-two institutions.
Japan
Regional banks in Kyushu and Hokkaido outsource aging ATM fleet maintenance to specialists. The Financial Services Agency's operational risk guidelines accelerate delegation of security-intensive functions. Nagoya's industrial automation cluster supplies sensor telemetry hardware for predictive maintenance deployments.
ATM Outsourcing Services Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform providers commanding premium pricing against discrete service vendors. The vendor base clusters around three strategic archetypes: fleet-scale operators leveraging density economics, software-anchored integrators unifying multi-vendor estates, and security-centric specialists certified for armored logistics. Consolidation pressure intensifies as subscription pricing models displace break-fix arrangements. Dominant competitive moves include geographic expansion into RBI-mandated rural India corridors and technology licensing partnerships for edge computing node deployment.
Within the fleet-scale tier, Cardtronics and NCR Atleos exemplify operational leverage strategies. Cardtronics occupies a position as the North American density leader, while NCR Atleos anchors software integration capabilities for mid-tier financial institutions. Euronet Worldwide sits within the transaction-processing specialist archetype, representing cross-border payment rail integration potential.
| Leading Market Players |
|---|
| Cardtronics |
| Hitachi Channel Solutions |
| NCR Atleos |
| Euronet Worldwide |
| GRG Banking |
| Diebold Nixdorf |
| Fujitsu |
| Cennox |
| Brink's |
| Others |
Supply Flow & Price Mechanics
RBI-mandated financial inclusion targets in India are forcing managed service providers to absorb higher armored logistics costs for rural deployments, compressing margins and accelerating subscription-based pricing models that transfer uptime risk from banks to vendors. This demand-side pressure reshapes how contracts are structured across low-density networks.
Pricing Analysis
Short lead-time premiums for certified technician dispatch dominate pricing differentiation in maintenance contracts, while extended forecasting horizons attract volume discounts for cash replenishment scheduling. Three-tier pricing structure across premium, standard, and economy levels separates PCI-DSS certified encryption bundles from basic hardware break-fix arrangements. Pricing pressure stems from subscription pricing displacing break-fix revenue recognition into monthly recurring streams. Community banks exhibit highest price sensitivity due to IT staff consolidation, while tier-one institutions prioritize uptime guarantees over unit cost.
Supply Chain Analysis
PCI-DSS vault certification and REACH substance compliance gate supplier participation, limiting eligible hardware vendors and armored logistics carriers. Manufacturing concentrates in China, Germany, and Japan for cash recycler modules and sensor telemetry hardware. Raw material dependencies include semiconductor components for edge computing nodes, lithium batteries for power backup systems, and specialized alloys for vault construction. Single-source vulnerability runs through licensed cash-in-transit carriers with limited rural route density. Distribution runs through metropolitan coordination centers in Chicago, Dallas, and Mumbai that dispatch field technicians and armored vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based remote monitoring architectures are displacing legacy on-premise systems, converting reactive maintenance contracts into predictive uptime guarantees and collapsing the traditional service stack.
For Market Incumbents: Anchor software integration capabilities across multi-vendor ATM estates to defend against API-first platform entrants. Deepen backward integration into edge computing node production to control hardware-software bundle margins. Prioritize certification investment for EU DORA compliance to capture mandatory outsourcing mandates affecting European credit unions. For New Entrants and Emerging Players: Predictive maintenance algorithms trained on sensor telemetry offer a technology-first wedge into tier-two U.S. financial institutions under FFIEC cybersecurity guidance. Target rural India managed service contracts under RBI financial inclusion frameworks where five-year exclusivity terms lock in recurring revenue. Pursue white-label platform licensing to incumbent armored logistics providers seeking to upgrade legacy cash forecasting capabilities. For Investors and Strategic Acquirers: Re-rating potential sits with cloud-native remote monitoring specialists given FFIEC and DORA regulatory catalysts accelerating third-party risk management outsourcing. Long-term viability favors vendors with unified platform offerings spanning hardware maintenance, software security, and cash logistics rather than discrete service providers. Watch central bank digital currency pilot expansion as an inflection indicator for physical cash infrastructure investment decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures connect ATM networks to real-time payment rails for transaction-based fee expansion. |
| Geographic Expansion | RBI-mandated rural corridors in Maharashtra and Gujarat offer exclusive contract capture under financial inclusion targets. |
| Acquisition of Specialist Firm | Edge computing node developers compress response times from days to hours for predictive maintenance deployment. |
| Strategic Partnership | Armored logistics alliances address certified carrier scarcity bottlenecks in low-density route networks. |
| Product Launch | Subscription-based managed service contracts displace break-fix arrangements with pricing indexed to transaction volume. |
Methodological Framework
Document review covered regulatory filings from the Federal Reserve, FDIC, RBI, and European Banking Authority, complemented by interviews with ATM fleet operations directors, managed service procurement leads at regional banks, armored logistics coordinators, and cybersecurity compliance officers. Secondary validation drew from PCI-DSS certification databases, EU REACH substance compliance registries, and central bank cash handling regulations. Bottom-up contract value analysis triangulated against top-down market sizing across service type and deployment model segments.
Cross-referencing historical outsourcing penetration rates with panel input from vendor sales executives and bank procurement committees informed the analytical framework across the projection horizon. Segmentation dimensions modeled include service type intensity, client capital constraints, deployment ownership structure, and technology architecture maturity. CAGRs were derived from weighted scenario analysis incorporating RBI financial inclusion target pacing and DORA implementation timelines. Forecast inputs incorporated armored logistics route density economics and certified technician availability indices.
Several conditions sit outside the modeled scope, including central bank digital currency pilot outcomes, geopolitical disruption to semiconductor supply chains, and abrupt shifts in cash velocity preferences. Forecasts reflect documented assumptions regarding regulatory implementation schedules and technology adoption curves. A model refresh is warranted upon material change in central bank cash access policy or PCI-DSS audit cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Digital Account Opening Market
Financial Services
Africa Lottery Market
Financial Services
Reverse Factoring Market
Financial Services
CFD Trading Affiliate Programs Market
Financial Services
Germany E-Brokerage Market
Financial Services
Belgium Gift Card and Incentive Card Market
Financial Services
China Trade Finance Market
Financial Services
BFSI Contact Center Analytics Market
Financial Services
Debt Collection Software and Service Market
Financial Services
Financial Advisory Services Market
Financial Services
Reconciliation Software Market
Financial Services
Global Treasury Management System (TMS) Market
Financial Services
Mobile Notary Service Market
Financial Services
Intellectual Property Rights and Royalty Management Market
Financial Services
Commodity Trade Finance Market
Financial Services
Financial Auditing Professional Services Market