
 Assortment Analytics Market | 2026-2036
Assortment Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Assortment Analytics Market Analysis
Subscription-based software-defined features is broadening what vendors monetize beyond perpetual licenses in assortment analytics. Microsoft leverages its cloud infrastructure to anchor enterprise-grade deployment models across retail chains. SAP sustains deep ERP integration that positions its analytics modules within existing procurement workflows. NielsenIQ dominates shelf-level measurement by controlling proprietary store audit panels that competitors cannot easily replicate.
Assortment analytics comprises data science methodologies that optimize product selection, space allocation, and inventory mix using demand signals, elasticities, and constraint-based solvers; its primary purpose is to maximize revenue per square foot while minimizing stockouts and markdown losses. The clothing and groceries product type segments sit at opposite ends of the maturity curve, with fashion assortments requiring rapid seasonal turnover algorithms and food retail demanding freshness-weighted optimization. Margin pools concentrate among large enterprises in the end user dimension, where procurement scale justifies dedicated data science teams and custom model development.
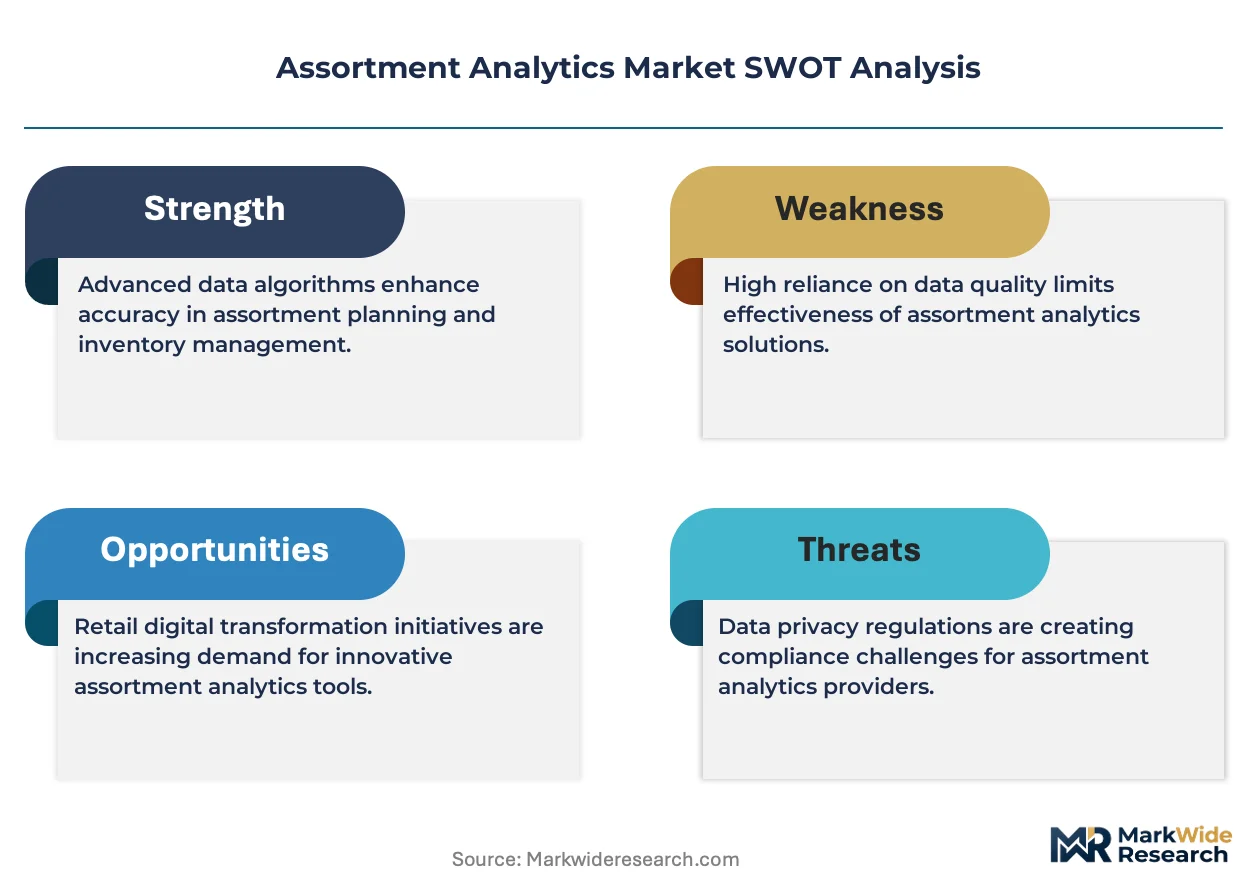
The Federal Trade Commission and state-level consumer privacy statutes in California and Virginia shape how shopper-level data feeds into assortment models, restricting certain predictive uses and manduring opt-in architectures. The National Institute of Standards and Technology provides cybersecurity frameworks that retailers must satisfy before deploying cloud-native analytics platforms housing transaction-level detail. Stakeholders should monitor how evolving patchworks of state privacy laws fragment the data foundations upon which assortment optimization engines depend.
Market Dynamics
AI-driven shelf optimization tools are compressing the gap between inventory signals and assortment decisions, forcing retailers to rebuild analytics pipelines around real-time data flows rather than static planogram cycles.
Growth Catalysts
- Consumer Privacy Frameworks:The FTC and state-level statutes in California and Virginia mandate opt-in data architectures that paradoxically accelerate investment in privacy-compliant analytics infrastructure.
- Cloud-Native Deployment:Enterprise retailers are migrating constraint-based solvers to scalable cloud environments, reducing computational latency for multi-store assortment simulations.
- Grocery Chain Consolidation:Large-format food retailers in the United States are centralizing procurement analytics, creating concentrated demand for integrated shelf-space optimization platforms.
Market Restraints
- Proprietary Data Silos:NielsenIQ's controlled store audit panels create replication barriers that limit competitive shelf-measurement alternatives and inflate input costs for second-tier vendors.
- ERP Integration Friction:Deep SAP procurement workflow dependencies lock retailers into legacy module architectures, slowing migration to standalone analytics solutions.
- Freshness-Weighted Complexity:Perishable food categories require dynamic spoilage algorithms that multiply model training costs compared to stable general merchandise assortments.
Strategic Opportunities
- Fashion Seasonal Velocity:Rapid turnover algorithms for clothing assortments remain underdeveloped relative to grocery optimization, opening white space for specialized seasonal demand forecasting tools.
- Subscription Monetization:Software-defined feature packaging enables vendors to capture recurring revenue streams beyond traditional perpetual license models.
- NIST Cybersecurity Alignment:Federal framework compliance requirements create consultative service attach opportunities for cloud-native platform deployments in mid-market retail chains.
Industry Challenges
- State Law Fragmentation:Evolving patchworks of Virginia, California, and emerging state privacy statutes fragment the unified shopper-level data foundations upon which assortment engines depend.
- Data Science Talent Scarcity:Constraint-based optimization and demand elasticity modeling require specialized quantitative skills that retail organizations struggle to retain against technology sector competition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Assortment Analytics Market |
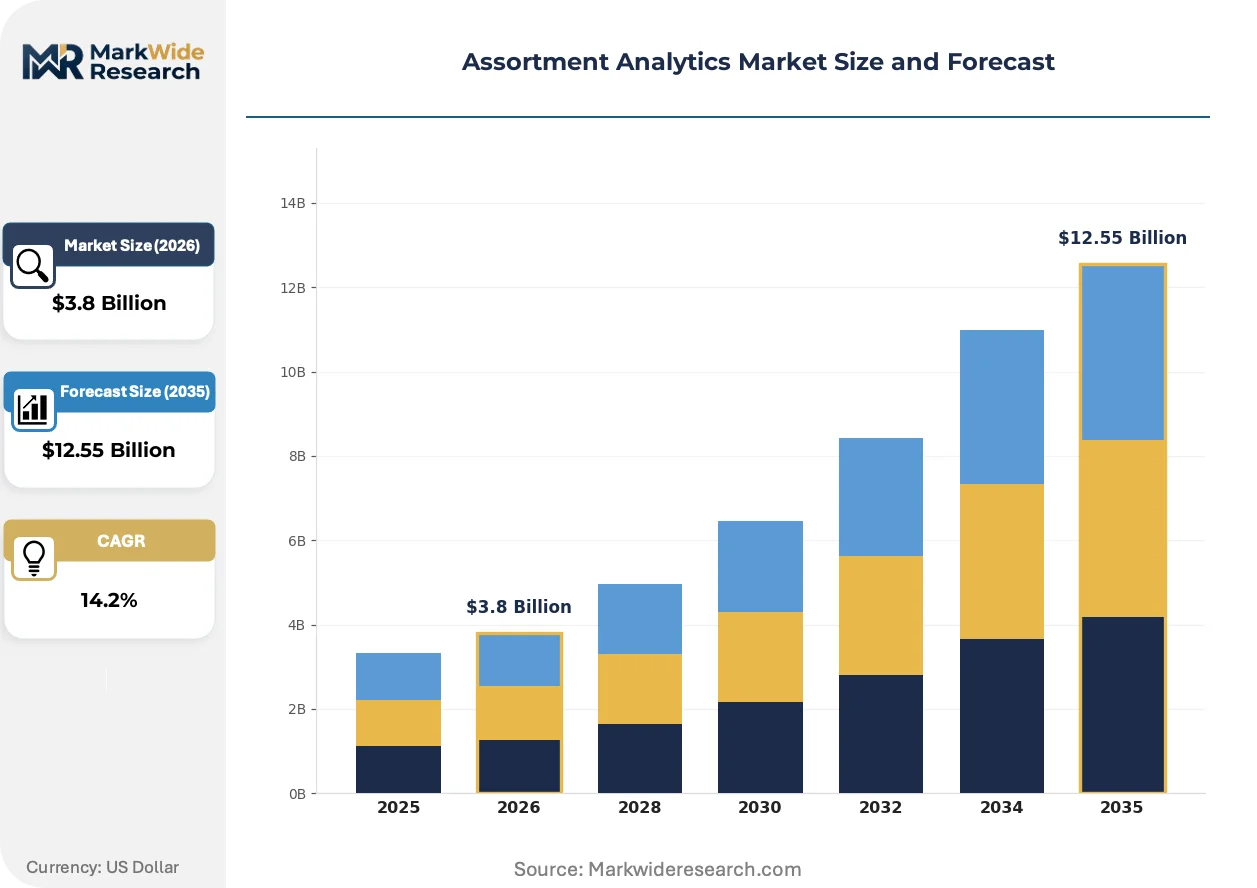
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clothing, Electronics, Home Goods, Groceries Customer Type: Retailers, E-commerce Platforms, Wholesalers, Distributors End User: Small Businesses, Large Enterprises, Startups, Franchisees Distribution Channel: Online, Offline, Direct Sales, Third-party Retailers |
| Companies Covered | NielsenIQ, Microsoft, IBM Corporation, o9 Solutions, Inc., SAP, Oracle Corporation, Blue Yonder Group Inc, Manthan, SAS Institute Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Assortment Analytics Market Emerging Trajectories
Real-time inventory-to-assortment pipelines are displacing batch-processed planogram updates, compressing decision cycles from weeks to hours across omnichannel retail operations.
Computer vision shelf-monitoring hardware is integrating edge-computing inference directly into retail fixtures, enabling continuous stock-level telemetry without manual audit labor. Grocery chains in the United States are deploying these systems at scale, capturing granular availability data that feeds directly into automated replenishment triggers. This sensor infrastructure is integrating with upstream supplier systems, collapsing information asymmetries between store operations and distribution centers.
The FTC's emerging guidance on algorithmic pricing transparency is restricting certain predictive uses of shopper-level data in assortment models, particularly for price-sensitive demographic targeting. Retailers must now document decision logic for regulatory examination, increasing compliance overhead for AI-driven shelf optimization. Food retail segments with thin margins are responding by shifting toward aggregate demand signals rather than individual-level predictions.
Mid-market retailers are consolidating vendor relationships, preferring integrated platform providers over point-solution specialists that require complex stitching. This concentration favors vendors with pre-built ERP connectors and cloud infrastructure scale. The United States grocery sector exhibits this pattern most acutely, where procurement teams prioritize single-contract accountability over best-of-breed component assembly.
Assortment Analytics Market Segmentation
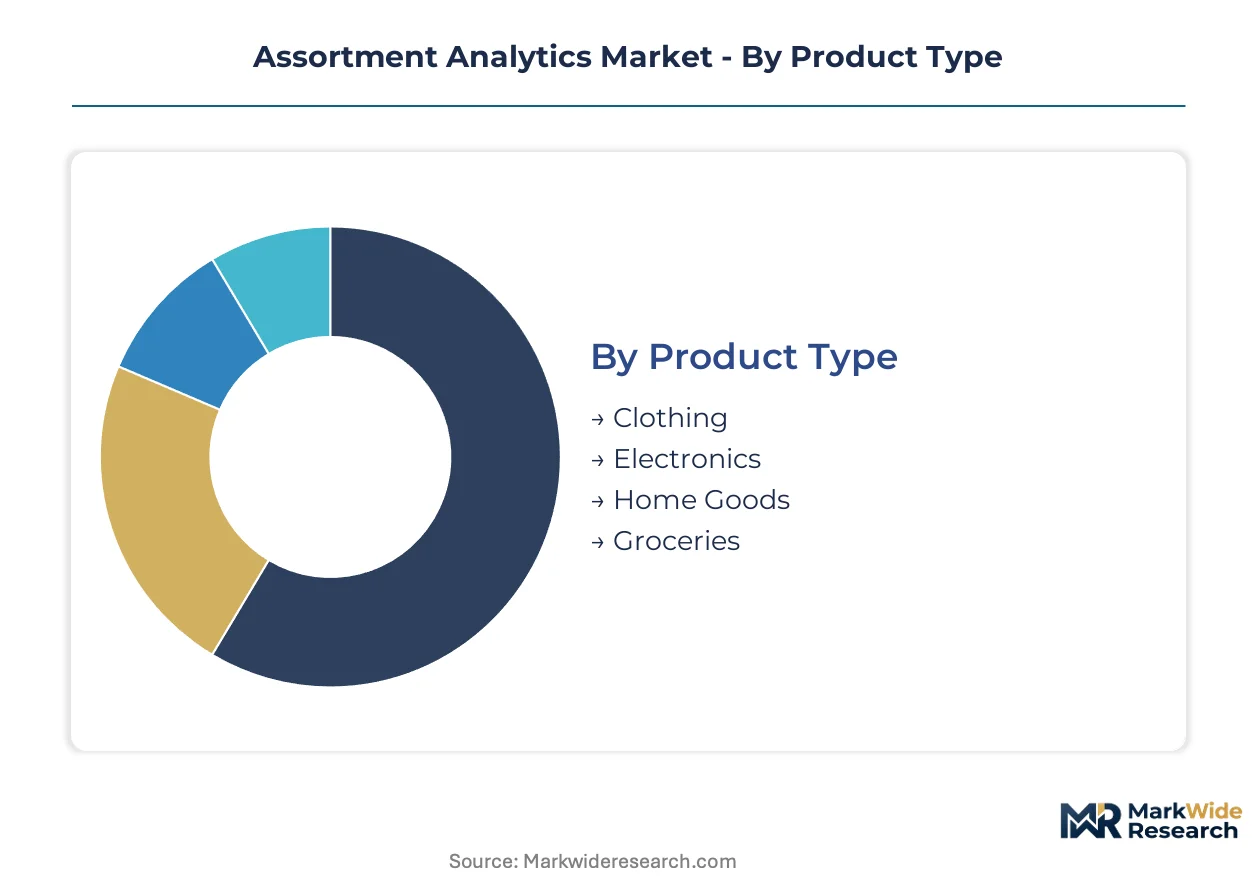
Segmentation in assortment analytics reflects how optimization complexity varies across product lifecycles, buyer procurement scale, and channel data granularity. Vendors configure pricing and deployment models around these divides.
Product Type:
Margin volatility and spoilage risk separate buyers in this category.
- Clothing:Rapid seasonal turnover algorithms manage style-level demand elasticity across compressed fashion cycles. United States department stores and fast-fashion chains deploy these tools to minimize markdown exposure on trend-dependent inventory.
- Groceries:Freshness-weighted optimization incorporates perishability curves and shrink forecasts into space allocation models. Large-format food retailers in the United States centralize these analytics to synchronize produce rotation with promotional calendars.
- Electronics:Short lifecycle forecasting addresses obsolescence risk and launch velocity for device categories.
- Home Goods:Stable demand patterns support longer planning horizons with lower replenishment frequency.
Groceries leads volumes today; clothing is gaining share fastest.
Customer Type:
Data infrastructure maturity determines procurement authority in this dimension.
- Retailers:Brick-and-mortar operators integrate shelf-level telemetry with legacy ERP systems to automate planogram execution. Grocery chains and big-box operators in the United States concentrate investment here, driven by thin-margin pressure to maximize revenue per square foot.
- E-commerce Platforms:Digital-native merchants deploy real-time assortment pipelines that collapse inventory signals into dynamic product recommendations. These buyers prioritize cloud-native architectures with API-first integration.
- Wholesalers:Bulk procurement analytics focus on volume-tier pricing and customer-specific SKU rationalization.
- Distributors:Multi-brand portfolio optimization requires cross-manufacturer space planning tools.
Retailers anchor current deployment; e-commerce platforms show the steepest expansion trajectory.
End User:
Internal data science capability separates organizational tiers in this category.
- Large Enterprises:Dedicated analytics teams build custom constraint-based solvers on cloud infrastructure. These organizations justify perpetual license investments through procurement scale across hundreds of locations.
- Small Businesses:SaaS-delivered modules with pre-configured templates address resource constraints. Franchise networks and independent operators in the United States adopt these lighter deployments.
- Startups:API-embedded analytics from commerce platforms substitute for standalone procurement.
- Franchisees:Corporate-mandated systems limit individual outlet customization.
Large enterprises dominate current spend; small businesses are expanding most quickly.
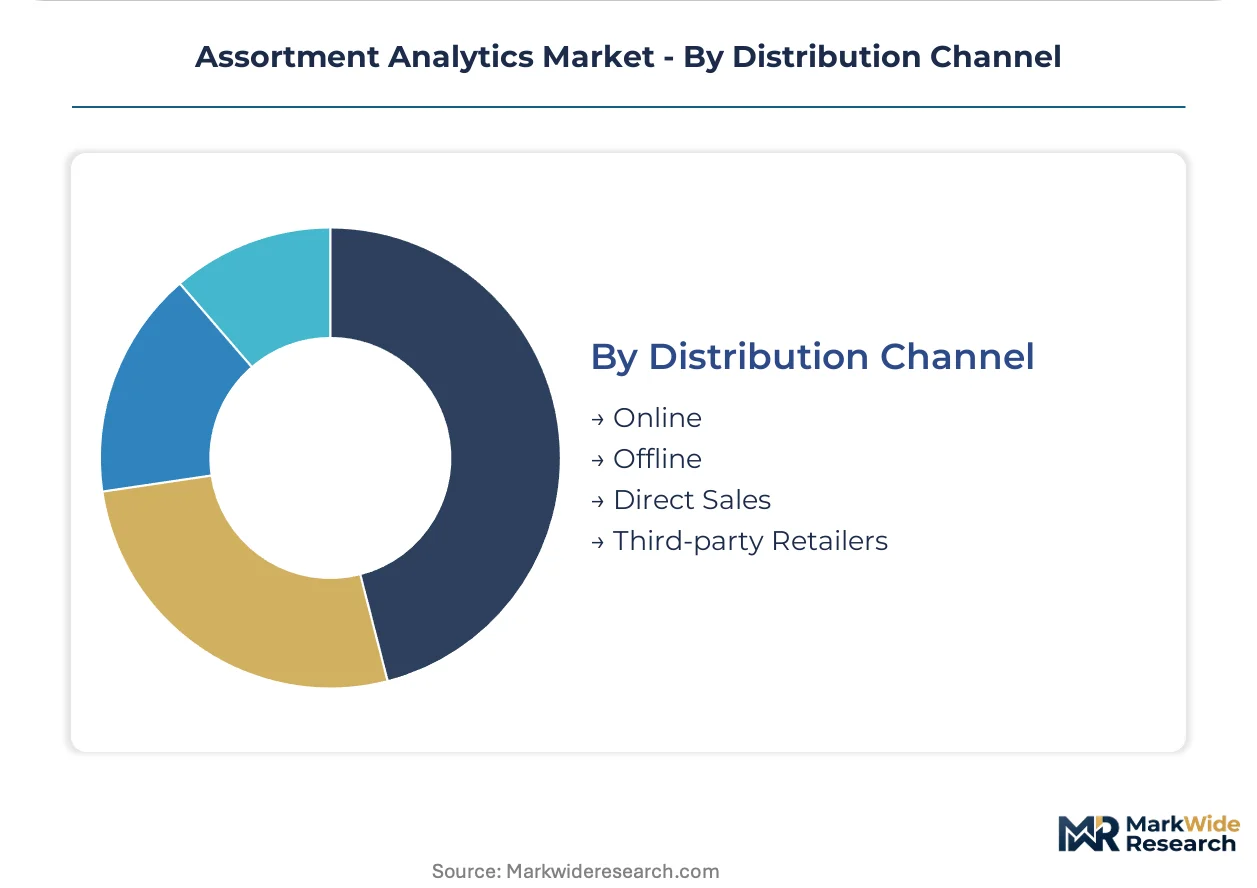
Distribution Channel:
Data capture modality shapes vendor configuration in this final dimension.
- Online:Clickstream-derived demand signals feed automated recommendation engines and dynamic pricing modules. E-commerce platforms in the United States deploy these systems at scale, constrained by emerging FTC guidance on algorithmic transparency.
- Offline:Computer vision shelf monitors and RFID telemetry generate continuous availability data for physical retail. United States grocery chains lead adoption of edge-computing fixtures that bypass manual audit labor.
- Direct Sales:Account-specific assortment customization serves B2B procurement relationships.
- Third-party Retailers:Marketplace sellers rely on platform-native analytics with limited customization.
Offline channels command present investment; online is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States grocery chains deploy real-time shelf optimization at scale, while German retailers prioritize ERP-integrated procurement analytics under stricter data governance standards.
United States
Grocery chain consolidation and thin-margin pressure drive concentrated investment in cloud-native assortment platforms. The FTC and state-level privacy statutes in California and Virginia mandate opt-in data architectures that accelerate privacy-compliant infrastructure spending. Chicago-based retail technology clusters host deployment centers where real-time inventory-to-assortment pipelines compress decision cycles from weeks to hours.
Germany
Precision retailing traditions and sustainability-weighted procurement favor constraint-based solvers with deep ERP integration. The EU AI Act and GDPR impose algorithmic transparency requirements that shape how shopper-level data feeds into assortment models. Baden-Württemberg's automotive-retail crossover clusters incubate shelf-space optimization tools adapted from manufacturing lean principles.
United Kingdom
Omnichannel grocery operators and fast-fashion chains demand seasonal velocity algorithms with rapid turnover capabilities. The UK Information Commissioner's Office enforces data minimization standards that restrict certain predictive uses in demographic targeting. London's fintech-retail convergence districts concentrate vendors offering subscription-based analytics modules to mid-market chains.
Japan
Convenience store density and freshness-centric food retail create demand for perishability-weighted optimization models. METI's digital transformation subsidies support cloud migration for constraint-based solvers in regional retail cooperatives. Tokyo-Osaka corridor technology providers integrate computer vision shelf monitoring with upstream supplier systems.
India
Modern trade expansion and kirana store digitization generate bifurcated demand for enterprise and SaaS-delivered assortment tools. The Digital Personal Data Protection Act establishes consent frameworks for shopper-level analytics in organized retail. Mumbai and Bangalore technology hubs host vendors building API-first platforms for marketplace sellers and franchise networks.
Assortment Analytics Market Vendor Landscape
Top-tier vendors anchor enterprise cloud infrastructure, while mid-tier specialists compete on vertical-specific algorithms and ERP connector depth. The market exhibits tiered concentration around three strategic archetypes: hyperscale cloud providers with retail verticalization, legacy ERP vendors with embedded analytics modules, and independent specialists with proprietary data assets. Competitive positioning hinges on M&A activity targeting computer vision capabilities and strategic partnerships with grocery chain consolidators.
Within the hyperscale tier, Microsoft exemplifies cloud-native deployment models leveraging infrastructure scale across retail chains. SAP occupies a position representing deep procurement workflow integration that locks retailers into legacy module architectures. NielsenIQ anchors the proprietary data tier through controlled store audit panels that create replication barriers for competitive shelf-measurement alternatives.
| Leading Market Players |
|---|
| NielsenIQ |
| Microsoft |
| IBM Corporation |
| o9 Solutions, Inc. |
| SAP |
| Oracle Corporation |
| Blue Yonder Group Inc |
| Manthan |
| SAS Institute Inc |
| Others |
Supply Flow & Price Mechanics
Mid-market retailer consolidation toward integrated platform providers is compressing vendor pricing power and forcing supply-side specialization around pre-built ERP connectors and cloud infrastructure scale.
Pricing Analysis
Capacity additions in cloud-native deployment environments are reshaping price floors for subscription-based assortment analytics modules. Pricing stratifies across enterprise perpetual licenses, SaaS tiered subscriptions, and API-embedded microservices, with differentiation driven by data science team access and custom model development scope. Cost compression in the small business tier is intensifying because hyperscale cloud providers leverage infrastructure scale to undercut standalone vendors. Franchise networks and independent operators exhibit the highest price sensitivity, while large enterprises with dedicated analytics teams demonstrate inelastic demand for custom constraint-based solvers.
Supply Chain Analysis
NIST cybersecurity framework compliance certification gates access to federal procurement channels and mid-market retail chain deployments in the United States. Software development concentrates in the United States, Germany, and India, with cloud infrastructure provisioning drawing from hyperscale data center networks in Northern Virginia, Frankfurt, and Mumbai. Supply chain risk centers on single-source vulnerability for proprietary store audit panel data controlled by dominant shelf-measurement vendors. Distribution runs through direct enterprise sales teams, cloud marketplace listings, and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The assortment analytics market functions as a stable compounder, with AI-driven shelf optimization tools embedding recurring revenue streams through subscription monetization that sustains steady expansion.
For Market Incumbents: Extend cloud infrastructure scale advantages by deepening vertical integration into computer vision hardware for edge-computing shelf monitors, neutralizing emerging specialists with sensor-capture capabilities. Fortify ERP connector depth against SAP and Oracle procurement workflow lock-in that threatens standalone analytics migration. Prioritize NIST cybersecurity framework certification investment to capture mid-market retail chain consultative service attach opportunities.
For New Entrants and Emerging Players: Fashion seasonal velocity algorithms represent an underserved buyer archetype with rapid turnover optimization tools remaining underdeveloped relative to grocery freshness-weighted models. Target United States department stores and fast-fashion chains with specialized demand forecasting modules that minimize markdown exposure on trend-dependent inventory. Pursue API-first go-to-market positioning that enables commerce platform embedding for startup and franchisee segments.
For Investors and Strategic Acquirers: Asymmetric upside sits with computer vision capability specialists that enable continuous stock-level telemetry without manual audit labor. Long-term viability favors vendors controlling proprietary data generation infrastructure rather than algorithmic layer pure-plays. Monitor FTC algorithmic pricing transparency guidance enforcement intensity as an inflection indicator for aggregate demand signal substitution trends.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Pre-built SAP and Oracle connectors lock retailers into unified procurement analytics contracts. |
| Acquisition of Specialist Firm | Computer vision shelf-monitoring hardware eliminates manual audit labor for grocery chains. |
| Strategic Partnership | Cloud infrastructure alliances with Microsoft Azure anchor enterprise-grade deployment scale. |
| Geographic Expansion | Chicago-based retail technology clusters concentrate real-time pipeline deployment expertise. |
| Product Launch | Freshness-weighted optimization modules address perishability curves for large-format food retailers. |
Methodological Framework
Multiple input streams — primary interviews with retail technology procurement officers, cloud platform engineers, and category management executives; secondary validation against SEC 10-K filings, hyperscaler capex disclosures, and NielsenIQ retail audit data; and customs records for computer vision hardware imports — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across deployment model, organization size, vertical specialization, integration complexity, and regional adoption pattern enabled CAGR derivation through constraint-based solver adoption curve modeling and cloud infrastructure provisioning trajectory analysis. Freshness-weighted optimization penetration rates and seasonal velocity algorithm deployment timelines served as industry-specific forecast inputs throughout the projection horizon.
Underlying measurement precision varies by segment; large enterprise perpetual license deployments carry tighter precision than small business SaaS module estimates. Forecasts reflect assumptions regarding FTC algorithmic transparency enforcement trajectories and state privacy law consolidation patterns. A model refresh is warranted upon material change in grocery chain consolidation velocity or NIST cybersecurity framework revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Sales Intelligence Market
Analytics
High Performance Computing (HPC) and High Performance Data Analytics (HPDA) Market
Analytics
Network Analysis Module (NAM) Market
Analytics
Legal Analytics Market
Analytics
In-Memory Analytics Tools Market
Analytics
India Geospatial Analytics Market
Analytics
Mobile Analytics Market
Analytics
Workforce Analytics Market
Analytics
Content Intelligence Market
Analytics
Network Traffic Analytics Market
Analytics
Data Mining Tools Market
Analytics
United Kingdom Geospatial Imagery Analytics Market
Analytics
Global Web Analytics Software Market
Analytics
North America Speech Analytics Market
Analytics
Embedded Analytics Software Market
Analytics
Investigative Analytics Market