
 CSP Network Analytics Market | 2026-2036
CSP Network Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
CSP Network Analytics Market Intelligence
The bundling of AI-driven security analytics with core network performance management suites is realigning buyer preferences toward integrated platforms. Cisco Systems Inc. leverages its extensive networking portfolio to offer these comprehensive solutions. Ericsson specializes in analytics tailored for mobile network optimization, particularly for 5G rollouts. IBM Corporation differentiates through its advanced AI and big data processing capabilities, serving complex operator needs.
CSP network analytics involves the application of software tools to process vast streams of operational data from network elements in real-time. Its primary purpose is to enable communication service providers to proactively manage network performance, optimize resource allocation, and enhance customer experience. While Telecom Operators remain the dominant end-user segment, cloud-based deployment models are rapidly gaining traction over traditional on-premises solutions. The adoption of AI & Machine Learning represents the fastest-growing technology segment, enabling predictive fault management.
Data privacy regulations like Europe's GDPR directly impact how CSPs handle subscriber data within analytics platforms. In the United States, FCC guidelines on network performance reporting create compliance-driven demand for accurate monitoring tools. Global standards from organizations such as the ITU also influence network management practices. Stakeholders must now balance the drive for granular, real-time insights with evolving data sovereignty and privacy mandates.
Market Dynamics
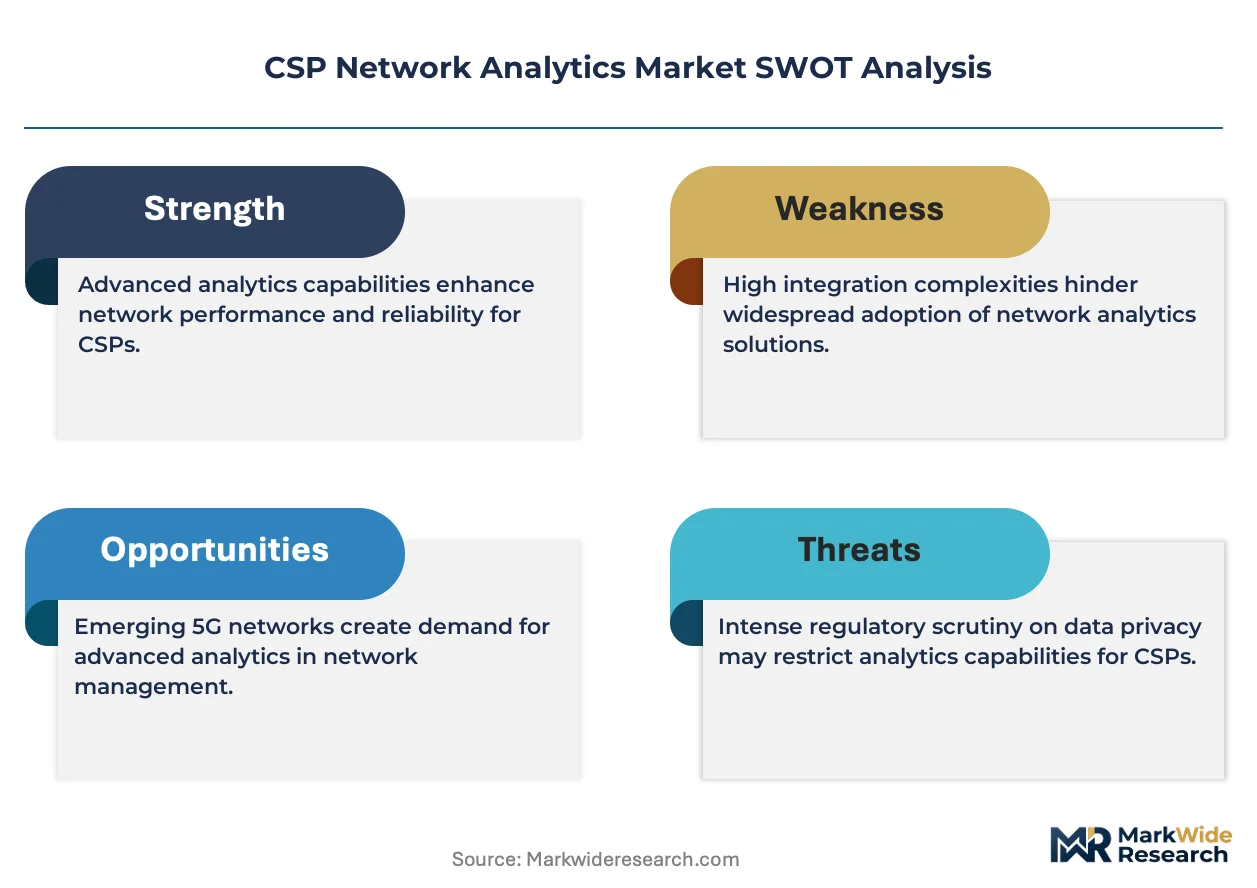
The central force shaping the CSP network analytics market is the massive data deluge from 5G, IoT, and edge computing deployments. This operational complexity makes traditional, manual network management untenable, compelling operators to invest in AI-driven automation for survival.
Growth Catalysts
- 5G Network Slicing:The commercialization of 5G network slicing for enterprise services creates a direct need for analytics to monitor and enforce stringent Service Level Agreements (SLAs), guaranteeing performance for dedicated use cases like automated manufacturing.
- AI Regulation:The EU AI Act is prompting vendors to build more transparent and explainable AI models into their analytics platforms, a feature that is becoming a key differentiator for operators concerned with regulatory compliance and risk.
- Enterprise Demand:The expansion of private cellular networks in industrial settings in countries like Germany and Japan is creating a B2B market for CSPs to offer managed analytics services, moving beyond their traditional consumer-focused operations.
Market Restraints
- Legacy System Integration:High costs and technical challenges persist in integrating modern analytics platforms with entrenched, often proprietary, legacy OSS/BSS systems, slowing down transformation projects for established telecom operators.
- Data Sovereignty Rules:National data localization mandates, such as those in India and China, complicate the architecture of analytics platforms for multinational carriers, often requiring separate, in-country data processing and storage instances.
- Talent Scarcity:A persistent shortage of data scientists and machine learning engineers who also possess deep knowledge of telecommunications network protocols and architecture limits the ability of CSPs to build and maintain advanced analytics capabilities in-house.
Strategic Opportunities
- IoT Vertical Monetization:There is a significant opportunity to develop specialized analytics applications for high-growth IoT verticals, such as connected logistics in Brazil or smart agriculture in Southeast Asia, creating new revenue streams beyond core connectivity.
- Edge Analytics Convergence:Integrating network analytics with Multi-access Edge Computing (MEC) allows for real-time, low-latency insights, enabling new services for industries like public safety and autonomous mobility where immediate action is critical.
- Compliance-as-a-Service:In the United States, FCC requirements for network performance and outage reporting, like the Network Outage Reporting System (NORS), create an opportunity for vendors to offer specialized, auditable analytics modules that automate compliance.
Industry Challenges
- Multi-Vendor Complexity:Operators face significant hurdles in normalizing and correlating data from a diverse array of equipment suppliers, each with unique data formats and APIs, which impedes the creation of a unified network view.
- AI Model Interoperability:A lack of standardization for AI and machine learning models makes it difficult for CSPs to port analytics use cases between different vendor platforms or combine insights from multiple tools without extensive custom engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CSP Network Analytics Market |
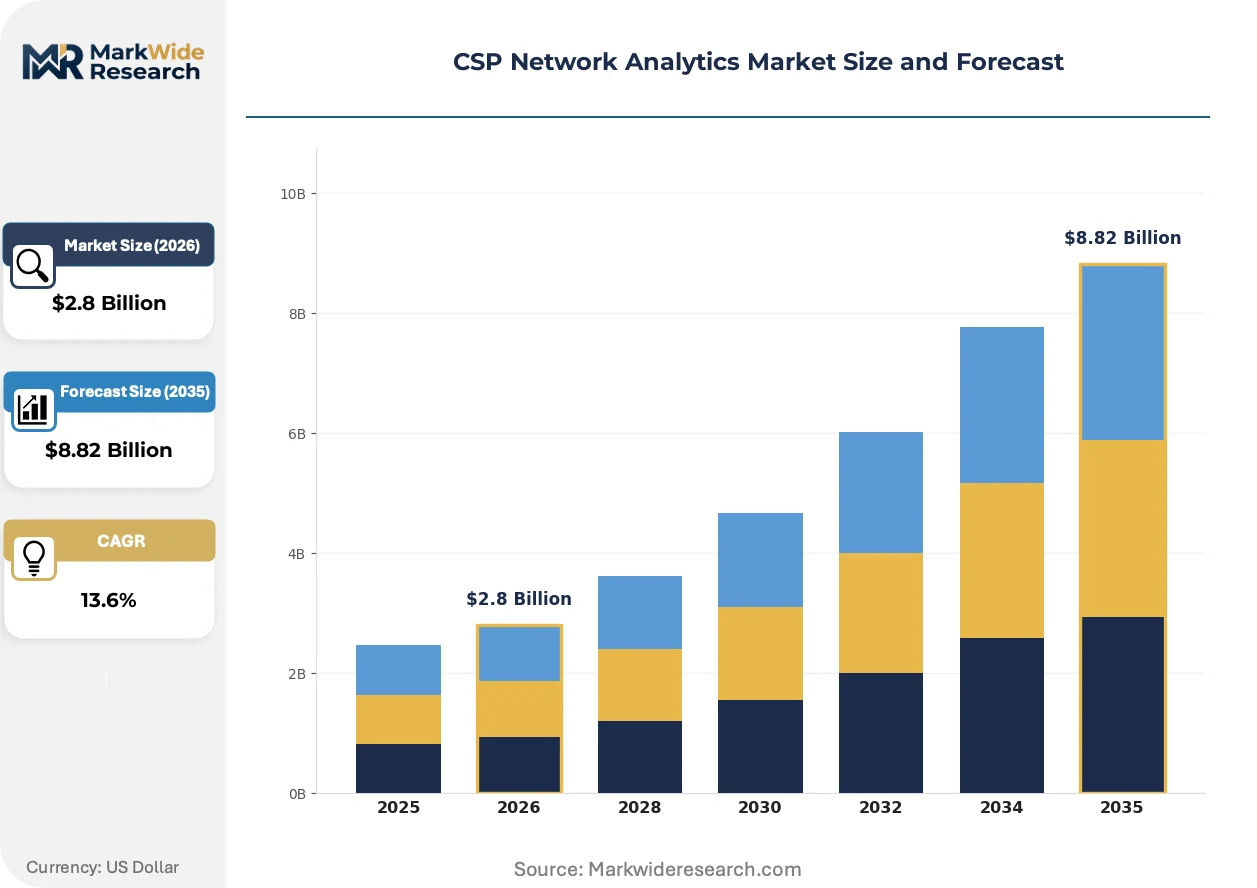
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.82 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
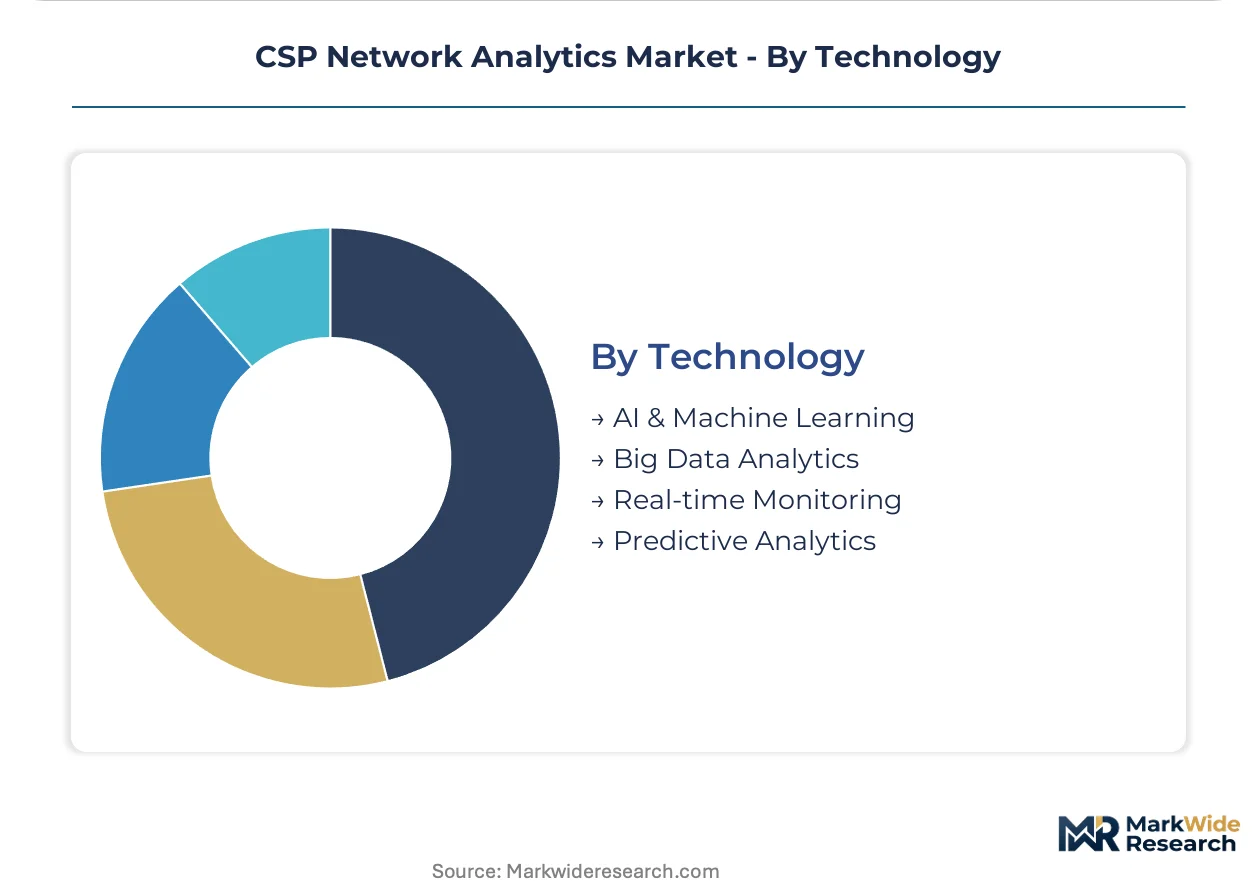
| Segmentation | Service Type: Network Optimization, Performance Management, Fault Management, Security Analytics End User: Telecom Operators, Internet Service Providers, Network Equipment Providers, Cloud Providers Deployment Model: On-premises, Cloud-based, Hybrid, Managed Services Technology: AI & Machine Learning, Big Data Analytics, Real-time Monitoring, Predictive Analytics |
| Companies Covered | Juniper Networks Inc., Huawei Technologies, IBM Corporation, Allot Communication, Accenture Plc, Cisco Systems Inc., Ericsson, SAS Institute Inc., Nokia Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CSP Network Analytics Market Strategic Shifts & Innovations
Automation is the defining theme, as analytics platforms evolve from passive monitoring tools into active, decision-making engines. The market is shifting from systems that merely report problems to those that predict, diagnose, and resolve them autonomously, fundamentally changing network operations centers.
Predictive analytics, which leverages machine learning to forecast potential network faults and performance degradation, is a primary technological focus. Telecom Operators in developed markets are adopting this technology to reduce mean time to repair and minimize service disruptions. This proactive methodology is overtaking traditional reactive fault management, which relies on post-event alarms and manual troubleshooting processes.
Regulatory frameworks like Europe's GDPR are directly influencing platform design. The regulation imposes strict mandates on how subscriber data is processed, requiring explicit consent and clear purpose limitations even for anonymized datasets used in analytics. This is forcing vendors to engineer privacy-by-design features and offer sovereign cloud deployment options to serve CSPs operating within the European Union.
Subscription-based models are transforming how analytics software is procured. CSPs are moving away from perpetual licenses with large upfront capital outlays and toward flexible Analytics-as-a-Service (AaaS) contracts. This pay-as-you-grow approach is most evident among smaller operators and MVNOs in markets like Canada and Australia, allowing them to access advanced capabilities without prohibitive initial investment.
CSP Network Analytics Market Segmentation
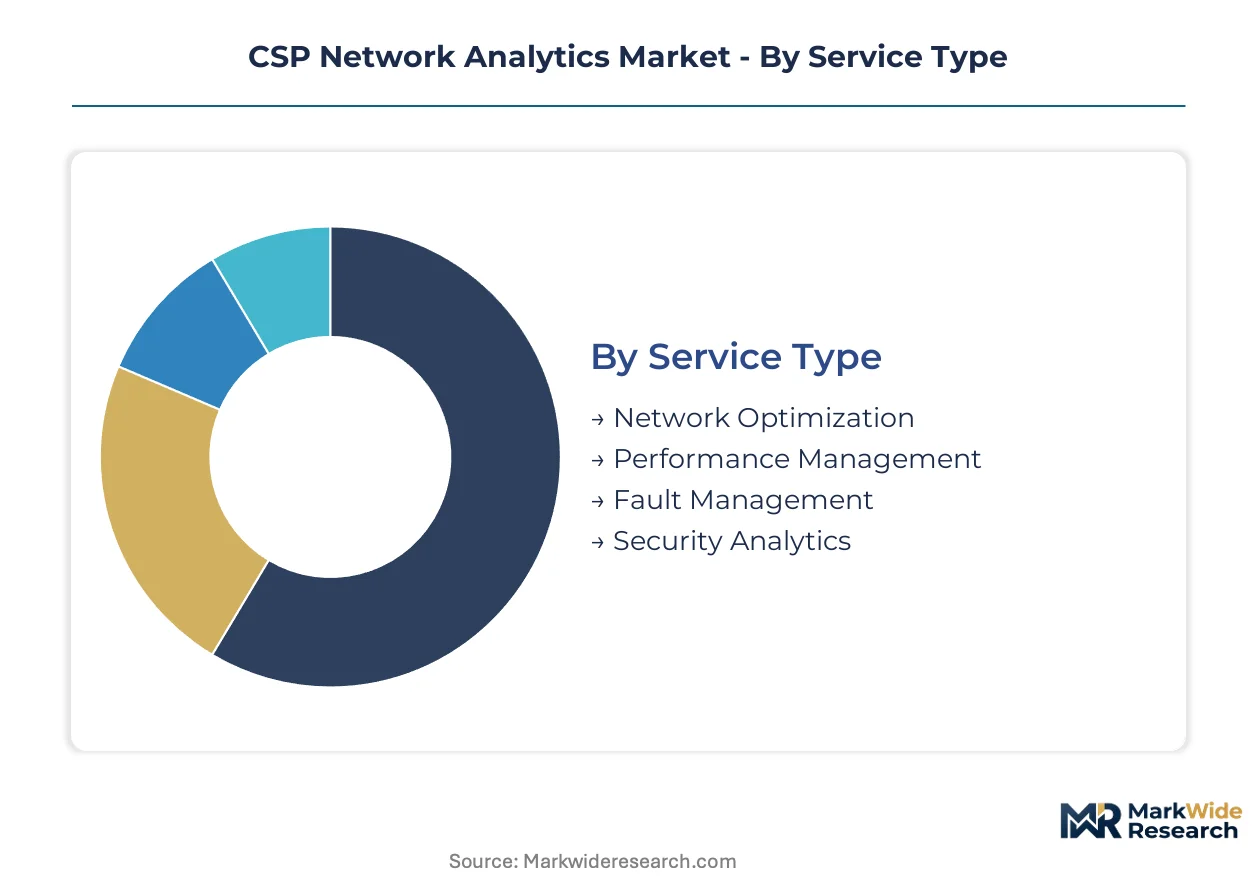
The CSP network analytics market segments based on the specific functionalities, operational models, and technological underpinnings that communication service providers require. Understanding these distinct categories provides clarity on where investment flows and where technological advancements create the most significant impact on network performance and customer experience.
Service Type:
The service type segmentation illustrates the balance between high-volume, foundational network management tasks and specialized, premium offerings that command higher value.
- Network Optimization:This service type focuses on maximizing network efficiency and resource utilization across diverse infrastructure components. Demand concentrates in developed markets like the United States where carriers continuously refine existing 5G and fiber networks for peak performance.
- Performance Management:Performance management involves continuous monitoring and analysis of network health metrics to ensure service quality and reliability. Telecom operators in Europe prioritize this to meet stringent regulatory SLAs and maintain subscriber satisfaction amidst increasing data traffic.
- Fault Management:This segment addresses the detection, isolation, and resolution of network outages and service degradations.
- Security Analytics:Security analytics applies data processing to identify and mitigate cyber threats targeting network infrastructure and subscriber data.
Today's leader: Network Optimization. Tomorrow's challenger: Security Analytics.
End User:
Customer type differentiation highlights the varied operational requirements and scale of entities consuming network analytics solutions.
- Telecom Operators:These are the primary consumers, leveraging analytics to manage extensive mobile and fixed-line networks, optimize 5G rollouts, and enhance subscriber services. Their investment in network modernization drives significant demand for integrated analytics platforms.
- Internet Service Providers:ISPs utilize analytics for traffic management, service assurance, and capacity planning across their internet backbone infrastructure.
- Network Equipment Providers:NEPs embed analytics into their hardware and software offerings to provide value-added services and improve equipment performance for operators.
- Cloud Providers:Cloud providers are increasingly adopting network analytics to manage their vast data center interconnects and optimize cloud-native network functions. This segment shows strong growth as enterprises migrate workloads and demand reliable cloud connectivity.
Telecom Operators currently dominate this segment, while Cloud Providers are expanding most quickly.
Deployment Model:
The deployment model segmentation reflects the evolving preferences for infrastructure management, from traditional in-house systems to flexible external services.
- On-premises:Traditional on-premises deployments involve software and hardware installed directly within the CSP's own data centers.
- Cloud-based:Cloud-based solutions offer scalability and reduced operational overhead by hosting analytics platforms on public or private cloud infrastructure. This model is gaining substantial traction due to its agility and lower upfront capital expenditure for new deployments.
- Hybrid:Hybrid models combine on-premises components with cloud-based services, balancing data control with scalability requirements.
- Managed Services:Managed services involve third-party vendors operating and maintaining the analytics platform on behalf of the CSP. This approach is favored by smaller operators and MVNOs in markets like Canada to access advanced capabilities without significant internal talent investment.
Cloud-based deployment models exhibit the steepest expansion trajectory, challenging the long-standing prevalence of on-premises solutions.
Technology:
Technological differentiation highlights the core innovations powering network analytics, from advanced data processing to predictive capabilities.
- AI & Machine Learning:This segment leverages sophisticated algorithms to automate insights, detect anomalies, and drive predictive fault management. The EU AI Act influences vendors to build more transparent AI models, a key differentiator for operators concerned with compliance.
- Big Data Analytics:Big data analytics processes massive volumes of network operational data to extract actionable intelligence and identify trends.
- Real-time Monitoring:Real-time monitoring provides immediate visibility into network performance, enabling rapid response to critical events and service issues.
- Predictive Analytics:Predictive analytics employs historical data and machine learning to forecast potential network faults and performance degradation before they impact services. Telecom operators in developed markets adopt this technology to minimize service disruptions and reduce mean time to repair.
AI & Machine Learning technologies are climbing the fastest, directly enabling the shift towards autonomous network operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The evolution of telecommunications networks, particularly with the advent of advanced mobile technologies, first scaled significantly in the United States. This foundational development created an early demand for sophisticated network analytics to manage increasing complexity. Today, global infrastructure investments continue to drive market expansion across diverse geographies.
United States
United States carriers heavily invest in network modernization, accelerating demand for advanced analytics. FCC guidelines on network performance reporting create compliance-driven demand for accurate monitoring tools. Major tech hubs in California lead the development of AI-driven network management solutions, ensuring robust performance.
Germany
Germany's industrial sector drives demand for analytics supporting private cellular networks and 5G network slicing. The EU AI Act influences transparent AI models for compliance, while GDPR shapes data handling. Industrial centers in Bavaria leverage network analytics for stringent SLA monitoring in automated manufacturing.
China
China's extensive 5G rollout and massive IoT deployments generate significant data requiring advanced analytics. National data localization mandates complicate platform architecture, often needing in-country processing. Technology hubs in Shenzhen concentrate innovation in real-time monitoring and predictive analytics for large-scale networks.
Japan
Japan's enterprise sector seeks managed analytics services for private cellular networks and 5G optimization. METI initiatives encourage digital transformation, boosting analytics adoption across industries. Manufacturing hubs in the Chubu region implement advanced network analytics for reliable smart factory operations.
India
India's rapid 5G expansion and digital infrastructure growth create substantial demand for network performance management. TRAI regulations influence how operators manage and report network quality. Technology centers in Bangalore are becoming key development hubs for analytics platforms supporting large-scale telecom operations.
CSP Network Analytics Market Key Industry Players
Premium-margin players sit above commodity-margin players across the solution complexity and integration dimension in the CSP network analytics market. This sector exhibits a tiered structure, with established technology giants and specialized telecom vendors competing for market share. Strategic archetypes include comprehensive platform providers, mobile network optimization specialists, and advanced AI/big data solution providers. Strategic partnerships, portfolio diversification, and targeted M&A are dominant competitive moves among these entities.
Within the comprehensive platform provider tier, IBM Corporation exemplifies advanced AI and big data processing capabilities, serving complex operator needs for data-intensive analytics. Cisco Systems Inc. leverages its extensive networking portfolio to offer integrated security analytics alongside core performance management suites. Ericsson occupies a position as a specialist in analytics tailored for mobile network optimization, particularly for 5G rollouts, demonstrating focused expertise. These companies drive innovation through their distinct technological strengths and market focus, influencing the direction of solution development.
| Leading Market Players |
|---|
| Juniper Networks Inc. |
| Huawei Technologies |
| IBM Corporation |
| Allot Communication |
| Accenture Plc |
| Cisco Systems Inc. |
| Ericsson |
| SAS Institute Inc. |
| Nokia Corporation |
| Others |
Cost & Logistics Intelligence
Specialized AI compute capacity pricing directly influences the cost structure of CSP network analytics platforms, cascading into tiered service offerings for operators. This dynamic shapes how vendors package their solutions and how communication service providers procure essential network management tools.
Pricing Analysis
Subscription-based Analytics-as-a-Service (AaaS) models define pricing in the CSP network analytics market. Price differentiation stems from capability tiers, offering basic monitoring to advanced AI-driven predictive features, and the complexity of integration with existing OSS/BSS systems. Pricing pressure stems from the rapid adoption of cloud-based solutions, which offer lower upfront capital expenditure. Smaller operators and MVNOs exhibit higher price sensitivity, seeking flexible pay-as-you-grow contracts.
Supply Chain Analysis
Global data center networks and regional cloud infrastructure form the distribution backbone for CSP network analytics solutions. Geographic supply concentration for development centers includes the United States, China, and India. The supply chain draws from specialized AI talent, cloud compute resources, and high-performance data processing hardware. Data sovereignty rules in countries like India and China represent a structural risk, often requiring separate in-country data processing. Downstream distribution runs through cloud-native global delivery and managed service models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CSP network analytics market is evolving into a late-cycle quality story, driven by a pronounced demand shift towards integrated, AI-driven platforms for proactive network management.
For Market Incumbents:
Anchor existing customer relationships by deepening portfolio integration, particularly between security analytics and core network performance management suites. Consolidate offerings to address multi-vendor complexity, providing unified network visibility. Strategic partnerships with cloud providers can expand edge analytics capabilities, mitigating threats from cloud-native challengers. Invest in explainable AI models to navigate evolving regulatory landscapes like the EU AI Act.
For New Entrants and Emerging Players:
A significant price-point gap exists between bespoke, high-end platforms and basic monitoring tools, creating an entry point for specialized AaaS providers. Target underpenetrated segments like smaller operators and MVNOs with flexible, subscription-based models. Focus on specific high-growth IoT verticals, such as smart agriculture or connected logistics, offering tailored analytics applications. Develop auditable compliance-as-a-service modules for markets like the United States, addressing specific FCC reporting requirements.
For Investors and Strategic Acquirers:
Asymmetric upside sits with specialized AI/ML analytics firms demonstrating explainable AI capabilities and strong vertical integration into cloud-native platforms. Long-term viability rests on companies enabling autonomous network operations and monetizing 5G network slicing. Acquisition targets should possess deep expertise in predictive fault management or offer robust data sovereignty solutions. The signal to watch is the increasing adoption rate of AI-powered analytics for proactive network resolution, displacing reactive manual processes.
| Strategic Initiative | Industry Significance |
|---|---|
| Launch AI-driven predictive analytics module | This action enables proactive fault management, reducing service disruptions for telecom operators. |
| Integrate security analytics with performance management | This strategy meets buyer preferences for comprehensive, unified network management platforms. |
| Form strategic partnership with cloud providers | This move enhances edge analytics capabilities and expands deployment options for low-latency insights. |
| Acquire specialist firm for IoT vertical expertise | This tactic creates new revenue streams by monetizing high-growth IoT applications beyond core connectivity. |
| Expand into markets with rapid 5G/IoT growth | This initiative captures new demand from countries undergoing extensive network modernization and digital transformation. |
Research Approach
Multiple input streams — primary interviews with industry stakeholders, secondary validation from regulatory bodies, and proprietary database analysis — were reconciled to construct this market view. Insights were gathered from telecom operators' CTOs, network architects, data scientists, and regulatory compliance officers. Secondary sources included FCC guidelines, TRAI regulations, EU AI Act documents, ITU standards, and company financial filings, facilitating both bottom-up and top-down triangulation.
Historical market data was cross-referenced against expert panel input to project market trajectories across the analysis window. The analytical framework modeled market segmentation across service type, end-user, deployment model, technology, and geographical adoption patterns. Compound Annual Growth Rates were derived from a multi-factor regression model, integrating key industry-specific forecast inputs like 5G rollout schedules and IoT device proliferation rates.
The model assumes a particular technology adoption path; alternative pathways for AI & Machine Learning integration would alter the outlook. Forecasts reflect underlying assumptions regarding technological advancement and regulatory stability. Unforeseen shifts in data privacy regulations or global economic downturns represent key risk factors that could revise projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Scientific Text Analytics and Annotators Market
Analytics
Global Enterprise Performance Management Market
Analytics
Hadoop Big Data Analytics Solution Market
Analytics
North America Crowd Analytics Market
Analytics
Online Analytical Processing Market
Analytics
Digital Analytics Solutions Market
Analytics
UK Geospatial Analytics Market
Analytics
Web Analytics Market
Analytics
Predictive and Prescriptive Analytics Market
Analytics
Investigative Analytics Market
Analytics
Event Stream Processing Market
Analytics
Global Recommendation Engine Market
Analytics
Process Analytics Market
Analytics
US Predictive Analytics Market
Analytics
Europe Supply Chain Analytics Market
Analytics
Voice Analytics Market