
 Tourism Industry Big Data Analytics Market | 2026-2036
Tourism Industry Big Data Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Tourism Industry Big Data Analytics Market Analytics
Subscription-based SaaS financing is narrowing the competitive field by lowering upfront capital barriers for mid-sized travel agencies and regional hotel chains. Oracle leverages its integrated cloud-application stack to anchor enterprise deployments across multinational hospitality groups. SAP competes through vertical-specific modules that embed tourism KPIs directly into ERP workflows. Google Cloud extends its position via AI-native tools that process multilingual booking signals and sentiment data at scale.
Tourism industry big data analytics encompasses the systematic extraction, processing, and modeling of structured and unstructured data from traveler touchpoints to generate actionable intelligence for revenue management and operational planning. The discipline applies machine learning algorithms to streaming datasets exceeding terabyte-scale, enabling real-time demand forecasting and personalized itinerary construction across digital channels. Predictive analytics leads current investment flows as airlines and hotel chains prioritize demand-forecasting accuracy over historical reporting. Cloud-based deployment is expanding fastest among tour operators seeking elastic compute capacity during seasonal demand spikes, while on-premises systems retain share where national data-residency laws mandate local storage. Diagnostic analytics occupies a narrower margin pool, serving primarily as a troubleshooting layer rather than a strategic decision engine.
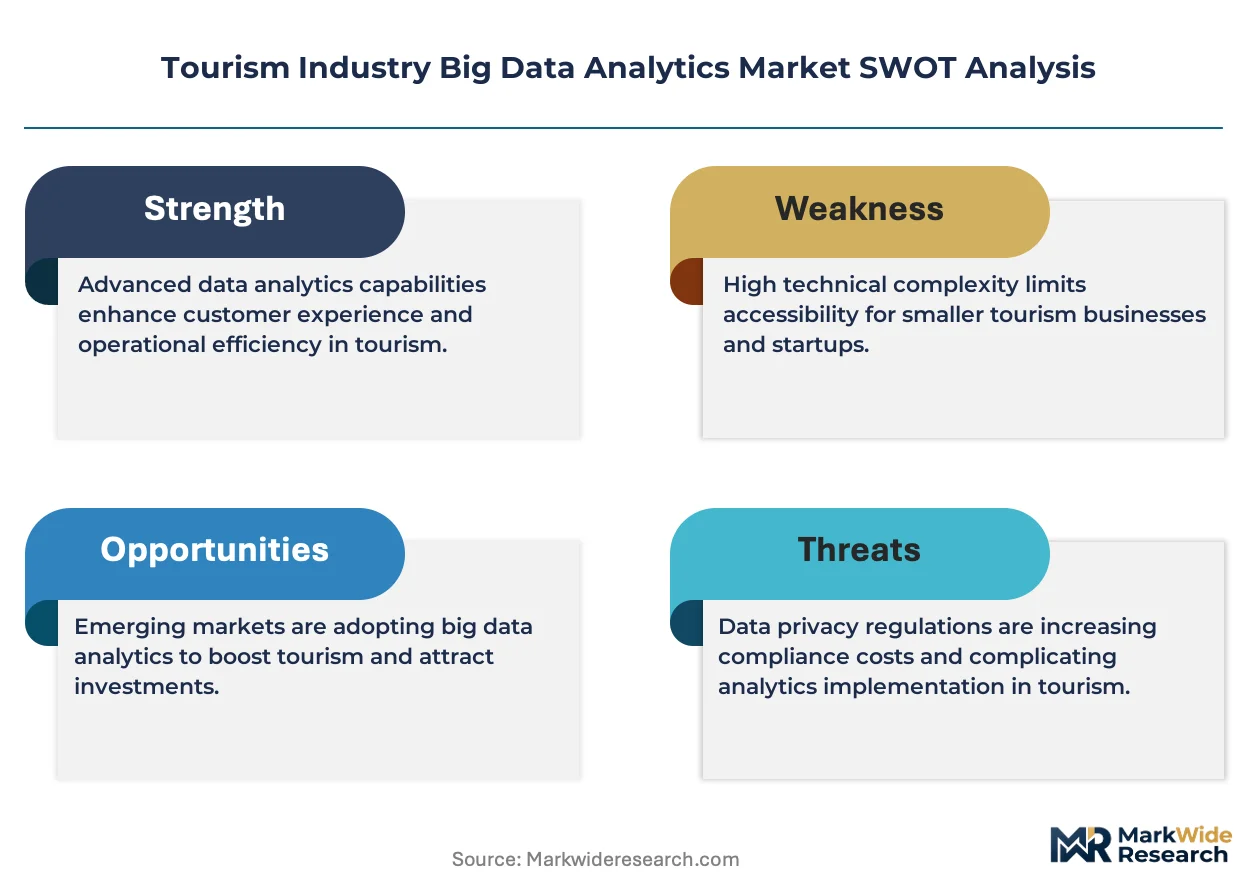
The EU AI Act and GDPR impose algorithmic transparency and consent-management requirements on European tourism platforms processing traveler behavioral data. The US Federal Trade Commission scrutinizes predictive pricing algorithms for potential discriminatory outcomes, shaping how American vendors architect their recommendation engines. ISO 27001 certification has become a de facto market-access threshold for analytics providers serving international hotel brands and global distribution systems. Stakeholders must monitor evolving cross-border data-transfer agreements between the European Union and major source markets, as these frameworks will determine where analytics processing can legally reside.
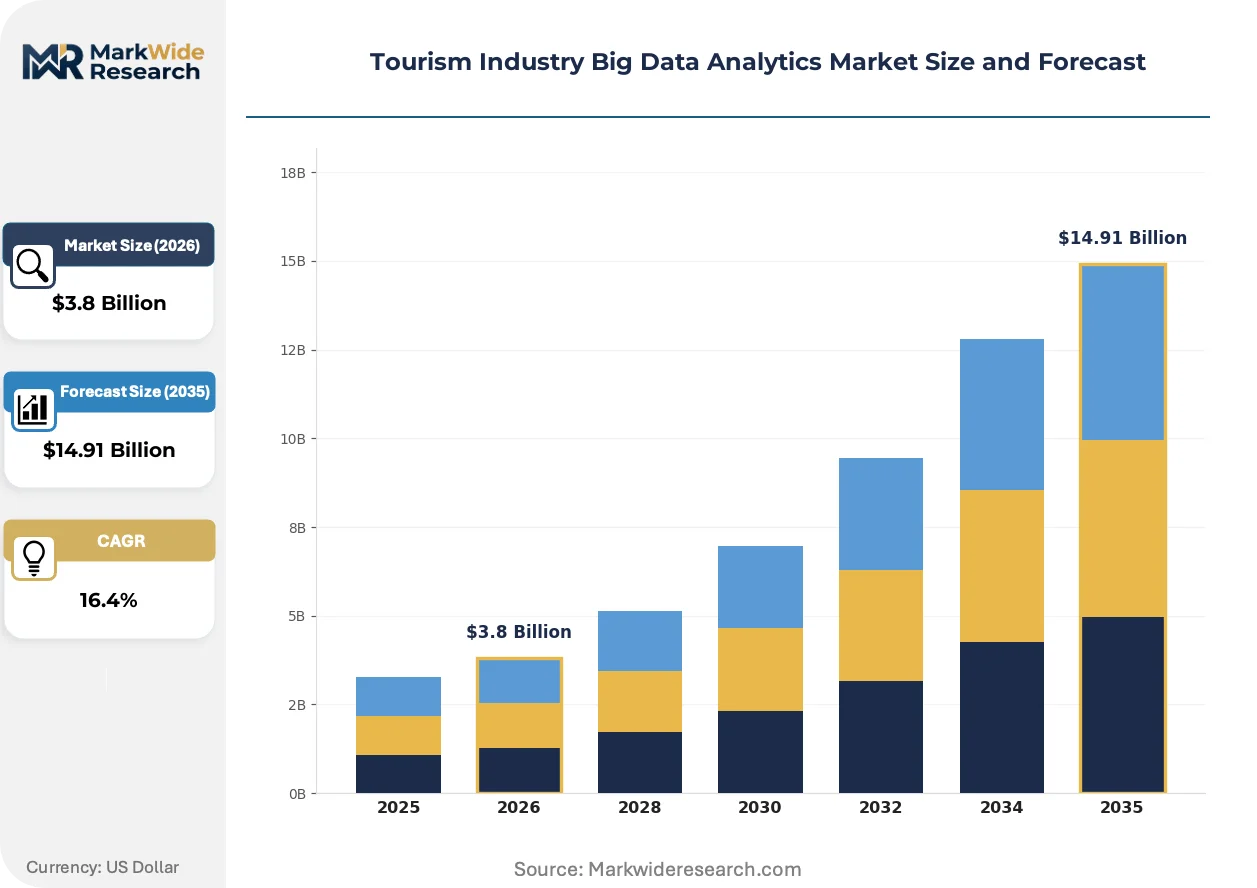
Market Dynamics
Predictive analytics for dynamic pricing is compressing decision cycles across hospitality chains, forcing legacy revenue-management systems into rapid cloud migration to maintain competitiveness.
Growth Catalysts
- GDPR-aligned data governance:European platforms modernizing consent-management infrastructure create pull-through demand for compliant analytics architectures across the continent.
- Airline demand-forecasting investments:Carriers prioritizing real-time capacity optimization over historical reporting are expanding procurement of streaming-data pipelines.
- United States hospitality concentration:Major chains and online travel agencies in this market are driving infrastructure spend for real-time analytics at scale.
Market Restraints
- Cloud compute cost volatility:Elastic capacity pricing during seasonal demand spikes strains operating budgets for mid-sized tour operators.
- EU AI Act algorithmic transparency mandates:Documentation requirements for recommendation engines impose compliance friction on European deployments.
- On-premises data residency requirements:National storage laws in select jurisdictions block full cloud migration for multinational hospitality groups.
Strategic Opportunities
- Regional hotel chain SaaS adoption:Subscription financing models are lowering capital barriers for mid-sized properties seeking predictive pricing capabilities.
- Sentiment analysis convergence with multilingual NLP:Processing of booking signals across languages opens white space in source-market analytics.
- ISO 27001 certification as market-access threshold:Compliance positioning creates differentiation for providers serving global distribution systems.
Industry Challenges
- Terabyte-scale streaming infrastructure:Talent scarcity in real-time data engineering limits deployment velocity for personalized itinerary systems.
- Legacy ERP integration complexity:Embedding tourism KPIs into existing workflows requires costly system reconfiguration for established operators.
- Cross-border data-transfer uncertainty:Evolving EU agreements with major source markets create legal ambiguity on processing location.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tourism Industry Big Data Analytics Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Data Source: Social Media, Booking Platforms, Travel Reviews, Website Analytics Analytics Type: Descriptive Analytics, Predictive Analytics, Prescriptive Analytics, Diagnostic Analytics End User: Travel Agencies, Hotels, Airlines, Tour Operators Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS |
| Companies Covered | IBM, Microsoft, Oracle, SAP, Google Cloud, Amazon, Hewlett Packard Enterprise, SAS Institute, Tableau Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tourism Industry Big Data Analytics Market Evolving Landscape
Machine learning architectures are virtualizing traditional revenue-management functions, compressing the gap between data ingestion and pricing action across digital channels.
Edge computing for property-level analytics is virtualizing the latency between guest behavior capture and dynamic rate adjustment. Boutique hotel chains in Spain and Italy are piloting localized inference nodes that process occupancy signals without round-trip cloud dependency. This architecture is virtualizing the cost structure of real-time pricing for properties with limited bandwidth budgets.
The EU AI Act's risk-classification framework for automated decision-making systems is forcing tourism platforms to rearchitect recommendation engines with built-in explainability layers. Providers serving European markets must now document algorithmic logic for pricing and personalization functions. Hotel chains with cross-border operations are responding by segmenting their analytics stacks between high-risk EU deployments and lower-risk jurisdictions.
Buyer concentration among online travel agencies is compressing switching cycles for analytics vendors. Independent hotels now procure pricing intelligence through aggregator-integrated modules rather than standalone platforms. This pattern is most visible in the United States, where major OTAs have consolidated middleware relationships with mid-market properties.
Tourism Industry Big Data Analytics Market Segmentation
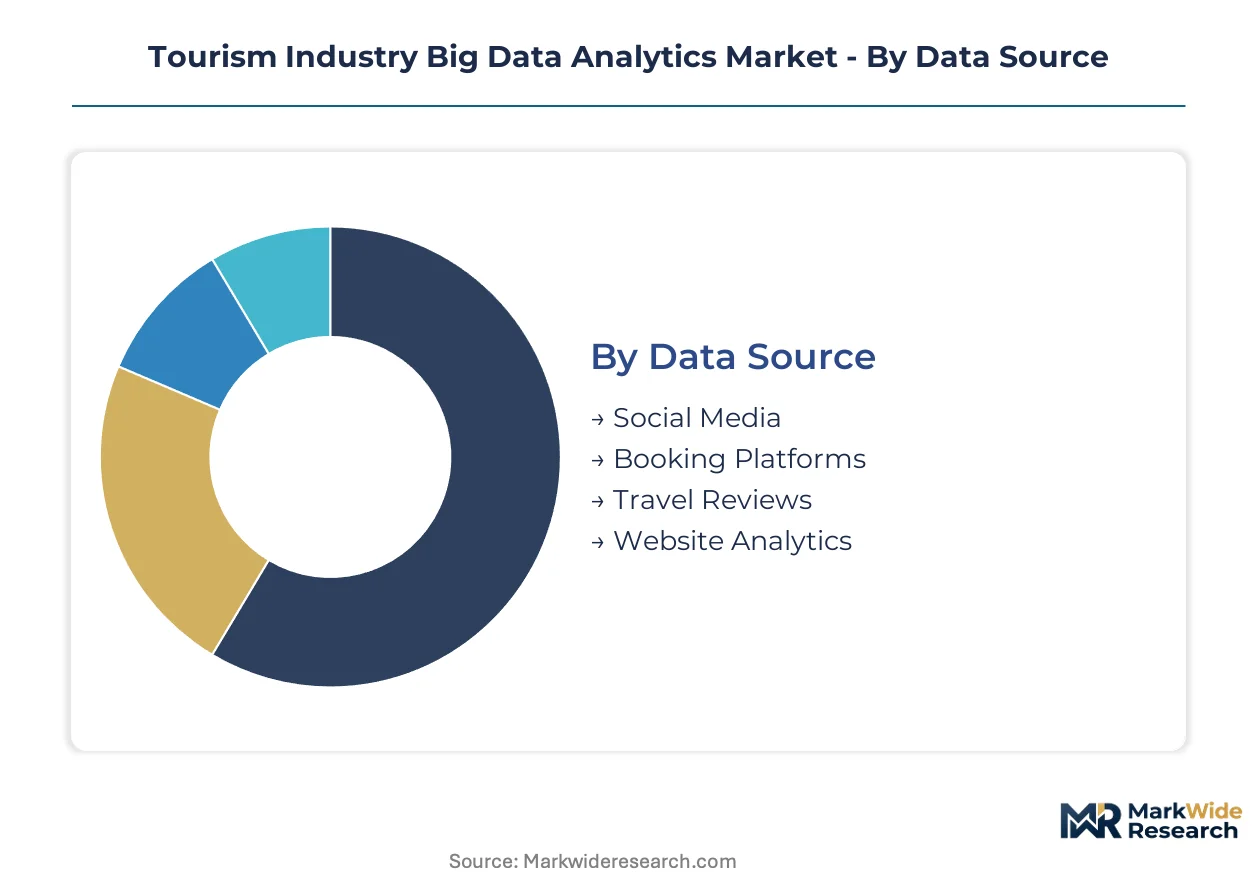
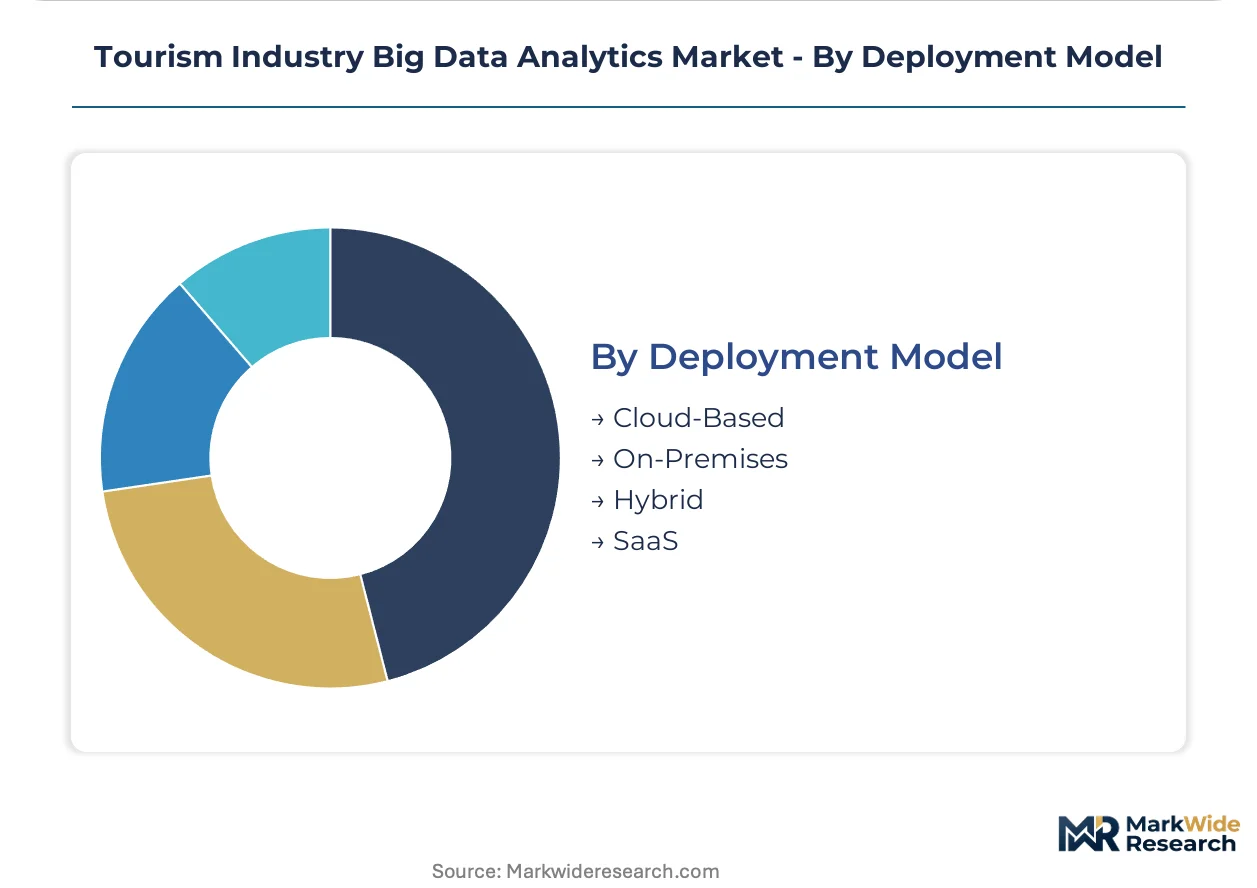
Tourism analytics vendors architect product roadmaps around four distinct segmentation axes. Each dimension reflects divergent technical requirements, compliance burdens, and buyer procurement patterns across hospitality chains, airlines, and digital travel platforms.
Data Source:
Mature collection channels dominate current infrastructure spend while emerging signal types reshape competitive differentiation.
- Social Media:Unstructured sentiment streams from platforms including Instagram, TikTok, and X require real-time NLP pipelines to extract destination intent signals. European tour operators processing GDPR-covered behavioral data invest heavily in consent-layered ingestion architectures.
- Booking Platforms:Transactional datasets from online travel agencies and direct reservation systems anchor demand-forecasting models. Airlines and hotel chains in the United States prioritize API integrations with major aggregator networks to capture competitive pricing intelligence.
- Travel Reviews:Aggregated feedback from TripAdvisor, Google Reviews, and specialty forums feeds reputation management dashboards. Mid-sized properties leverage this source for service recovery automation.
- Website Analytics:Clickstream and conversion funnel data from proprietary booking engines support personalization engines. Boutique operators deploy this to reduce abandonment rates on direct channels.
Booking platforms retain volume leadership; social media holds the steepest expansion curve.
Analytics Type:
Cost tier stratification separates enterprise-grade predictive systems from accessible diagnostic tools.
- Descriptive Analytics:Historical reporting dashboards visualize occupancy rates, revenue per available room, and channel mix performance. Regional hotel chains deploy these for board-level performance reviews with minimal data science overhead.
- Predictive Analytics:Machine learning models forecast demand curves, price elasticity, and cancellation probabilities. Airlines prioritize this category for real-time capacity optimization across route networks.
- Prescriptive Analytics:Optimization engines recommend specific pricing actions, inventory allocations, and marketing spend distributions. Multinational hospitality groups embed these into automated revenue management systems.
- Diagnostic Analytics:Root-cause analysis tools troubleshoot booking drop-offs and service failures. Properties use these sparingly as reactive troubleshooting layers rather than strategic engines.
Predictive analytics commands the premium tier; prescriptive systems are climbing fastest as automation matures.
End User:
Customer type determines deployment complexity and integration requirements across the buyer base.
- Travel Agencies:Consortiums and independent advisors leverage analytics for itinerary personalization and supplier negotiation. Subscription SaaS models lower capital barriers for mid-sized agencies.
- Hotels:Global chains deploy enterprise platforms with property-level edge nodes; independent properties procure through OTA-integrated modules. GDPR compliance drives architecture decisions for European portfolios.
- Airlines:Network carriers invest in streaming-data pipelines for dynamic fare adjustment and loyalty program optimization. Real-time processing requirements exceed hospitality norms.
- Tour Operators:Seasonal demand spikes create elastic compute requirements. Cloud-based deployment dominates this segment to avoid stranded capacity during off-peak periods.
Hotels generate the largest addressable base; airlines show the most intensive per-seat investment.
Deployment Model:
Supply concentration in hyperscale infrastructure shapes buyer options across control and flexibility trade-offs.
- Cloud-Based:Elastic compute and storage from AWS, Azure, and Google Cloud supports terabyte-scale streaming workloads. Tour operators and seasonal operators favor this model for cost-variable scaling.
- On-Premises:Local hardware installations satisfy data residency mandates in jurisdictions with strict national storage laws. Some Asian and Middle Eastern markets require this architecture for legal processing.
- Hybrid:Split configurations process sensitive traveler data locally while pushing anonymized analytics to cloud inference layers. Multinational hospitality groups adopt this to balance GDPR compliance with computational efficiency.
- SaaS:Subscription-delivered platforms reduce upfront capital requirements for mid-market properties. Regional chains access predictive pricing capabilities previously reserved for enterprise buyers.
Cloud-based deployment leads current installations; SaaS delivery is expanding most quickly among price-sensitive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial services trade surplus in tourism technology, exporting analytics platforms to European and Asian hospitality chains while importing specialized data engineering talent from India and Eastern Europe.
United States
Major hospitality chains and online travel agencies anchor demand for real-time analytics infrastructure. The Federal Trade Commission scrutinizes predictive pricing algorithms for discriminatory outcomes, shaping vendor architecture decisions. Silicon Valley clusters host streaming-data pipeline specialists serving airline network carriers.
Germany
Automotive-tourism convergence drives investment in traveler behavior analytics for connected vehicle fleets. The national data protection authority enforces GDPR-aligned consent management for platform deployments. Munich's enterprise software corridor hosts SAP-integrated hospitality analytics modules.
United Kingdom
London-based online travel agencies compress procurement cycles for pricing intelligence middleware. Post-Brexit data adequacy negotiations with the EU create legal ambiguity on cross-border processing locations. The City of London's fintech cluster supplies risk-modeling talent to revenue management vendors.
China
Domestic tourism platforms process multilingual booking signals at terabyte scale for outbound travel forecasting. The Ministry of Industry and Information Technology mandates local data residency for traveler behavioral analytics. Shenzhen's cloud infrastructure corridor hosts edge computing pilots for property-level pricing nodes.
India
Regional hotel chains access predictive pricing through subscription SaaS models lowering capital barriers. The central bank's data localization guidelines influence cloud architecture decisions for multinational hospitality groups. Bangalore's analytics services corridor supplies real-time data engineering talent to global vendors.
Tourism Industry Big Data Analytics Market Competitive Landscape
On the supply side, the industry is consolidating around integrated cloud stacks with enterprise resource planning anchoring multinational deployments. Hyperscale infrastructure providers and vertical software specialists compete across distinct capability tiers. Strategic archetypes include full-stack platform vendors, modular analytics specialists, and infrastructure-as-a-service operators. M&A activity concentrates on data pipeline startups and multilingual natural language processing assets.
Within the full-stack tier, Oracle and SAP occupy positions as enterprise anchors through integrated application stacks. Google Cloud exemplifies the AI-native archetype, processing multilingual sentiment signals at scale. IBM represents the hybrid-cloud positioning, serving hospitality groups with split compliance architectures spanning GDPR jurisdictions and lower-risk markets.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| Oracle |
| SAP |
| Google Cloud |
| Amazon |
| Hewlett Packard Enterprise |
| SAS Institute |
| Tableau Software |
| Others |
Value Network & Pricing Analysis
Bangalore's analytics services corridor anchors capacity for real-time data engineering talent, compressing downstream pricing power for cloud-based deployment tiers as hyperscale infrastructure providers compete for hospitality sector contracts. Subscription SaaS financing is narrowing the competitive field by lowering upfront capital barriers, forcing legacy on-premises vendors into defensive pricing postures.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in this market. Enterprise-grade predictive analytics with ISO 27001 certification command premium positioning, while diagnostic-only tiers face cost compression from open-source alternatives. Pricing pressure stems from cloud compute cost volatility during seasonal demand spikes. Mid-sized tour operators exhibit highest price sensitivity, whereas multinational hospitality groups prioritize compliance-grade solutions over unit cost.
Supply Chain Analysis
Export-control regimes limiting AI-native tool flows shape vendor geographic concentration across the United States, Germany, and India. Real-time data engineering talent draws from Bangalore and Eastern European clusters, while hyperscale infrastructure feeds from AWS, Azure, and Google Cloud data centers. Single-source vulnerability concentrates in multilingual NLP pipeline providers. Distribution runs through direct enterprise sales for global chains and OTA-integrated modules for independent properties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tourism industry big data analytics functions as a service-attach opportunity where subscription-based support and compliance-layer consulting expand faster than standalone platform licensing. Recurring-revenue streams from GDPR-aligned data governance and ISO 27001 certification maintenance outpace hardware-centric deployment models.
For Market Incumbents: Insulate enterprise positions through backward integration into proprietary data pipeline infrastructure and captive supply of real-time engineering talent. Oracle and SAP defend against AI-native challengers by embedding tourism KPIs deeper into ERP workflows. Certification investment in EU AI Act explainability layers creates switching costs for European multinational deployments. For New Entrants and Emerging Players: Southeast Asian regional hotel chains present the most penetrable white space, with subscription SaaS models lowering capital barriers for predictive pricing adoption. Boutique properties in Spain and Italy seeking edge-computing pilots offer a second entry vector. A channel partnership strategy with online travel agencies accelerates middleware integration without standalone sales overhead. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertical-specific analytics specialists with embedded compliance modules. Long-term viability favors providers with hybrid-cloud architectures spanning GDPR jurisdictions and lower-risk markets. Watch for inflection signals in cross-border data-transfer agreement finalization between the European Union and major source markets.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding predictive pricing into Oracle and SAP ERP workflows locks in multinational hospitality procurement. |
| Acquisition of Specialist Firm | Multilingual NLP assets from regional players extend Google Cloud's sentiment processing across source markets. |
| Geographic Expansion | Edge computing pilots in Spanish and Italian boutique chains virtualize latency for bandwidth-constrained properties. |
| Strategic Partnership | OTA middleware relationships compress switching cycles and consolidate pricing intelligence distribution. |
| Product Launch | Explainability-layer documentation tools address EU AI Act risk-classification requirements for European deployments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and airline regulatory submissions to validate market sizing. Conversations with revenue management executives at major hospitality chains, platform engineers at online travel agencies, and procurement leads at tour operators supplied demand-side intelligence. Bottom-up triangulation across deployment model segments and top-down validation against cloud infrastructure spending patterns anchored value estimates.
Forecast inputs include data source segmentation, analytics type tiering, and end-user procurement patterns across the projection horizon. The analytical framework models cloud-based, on-premises, hybrid, and SaaS deployment configurations alongside GDPR compliance intensity as a regional overlay. CAGRs derive from elasticity-adjusted demand curves and technology substitution rates in predictive versus diagnostic analytics.
Macroeconomic conditions sit as an overlay; deviation in hospitality sector capital expenditure cycles and cross-border data-transfer policy finalization would shift the trajectory. Forecasts reflect documented assumptions on cloud compute cost normalization and AI regulatory enforcement intensity. Material shifts in EU AI Act implementation timelines or major hospitality chain bankruptcy restructuring would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Augmented Analytics Market
Analytics
France Contact Center Analytics Market
Analytics
Global High Performance Data Analytics (HPDA) Market
Analytics
Business Analytics Market
Analytics
Investigative Analytics Market
Analytics
Content Intelligence Market
Analytics
Asia Pacific Speech Analytics Market
Analytics
South Korea Contact Center Analytics Market
Analytics
Network Analytics Services Market
Analytics
Global Analytics Software Market
Analytics
App Analytics Market
Analytics
Extract, Transform, Load (ETL) Market
Analytics
Latin America Location Based Data Analytics Market
Analytics
Big Data Analytics in Semiconductor and Electronics Market
Analytics
Analytics Sandbox Market
Analytics
Global Operational Analytics Market