
 Medicated Personal Care Products Market | 2026-2036
Medicated Personal Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Medicated Personal Care Products Market Foresight
Clinical-grade formulation standards is redrawing competitive boundaries in medicated personal care. Johnson & Johnson leverages its pharmaceutical heritage to anchor credibility in therapeutic skincare. Procter & Gamble competes through mass-market distribution of dermatologist-tested lines. Bayer AG specializes in medicated foot care and anti-fungal topicals with pharmacy channel dominance.
Medicated personal care products combine active pharmaceutical ingredients with cosmetic delivery systems, typically incorporating salicylic acid, benzoyl peroxide, or hyaluronic acid at concentrations requiring regulatory oversight for therapeutic claims. These formulations serve dual purposes: addressing specific dermatological conditions while maintaining aesthetic acceptability for daily consumer use. Moisturizers and cleansers lead product type revenue, though acne treatment applications demonstrate the fastest structural expansion as adolescent and adult-onset demand converges. Salicylic acid ingredient formulations command premium positioning due to established efficacy data and broader regulatory acceptance across jurisdictions.
FDA monograph compliance determines OTC market access for benzoyl peroxide and salicylic acid products in the United States, while EMA cosmetic-therapeutic borderline classifications shape European formulation strategies. REACH chemical registration requirements in Europe and emerging state-level ingredient restrictions in California are elevating formulation transparency costs. Stakeholders must monitor evolving regulatory divergence between cosmetic and drug classification thresholds as classification decisions directly determine distribution channel options and marketing claim permissibility.
Market Dynamics
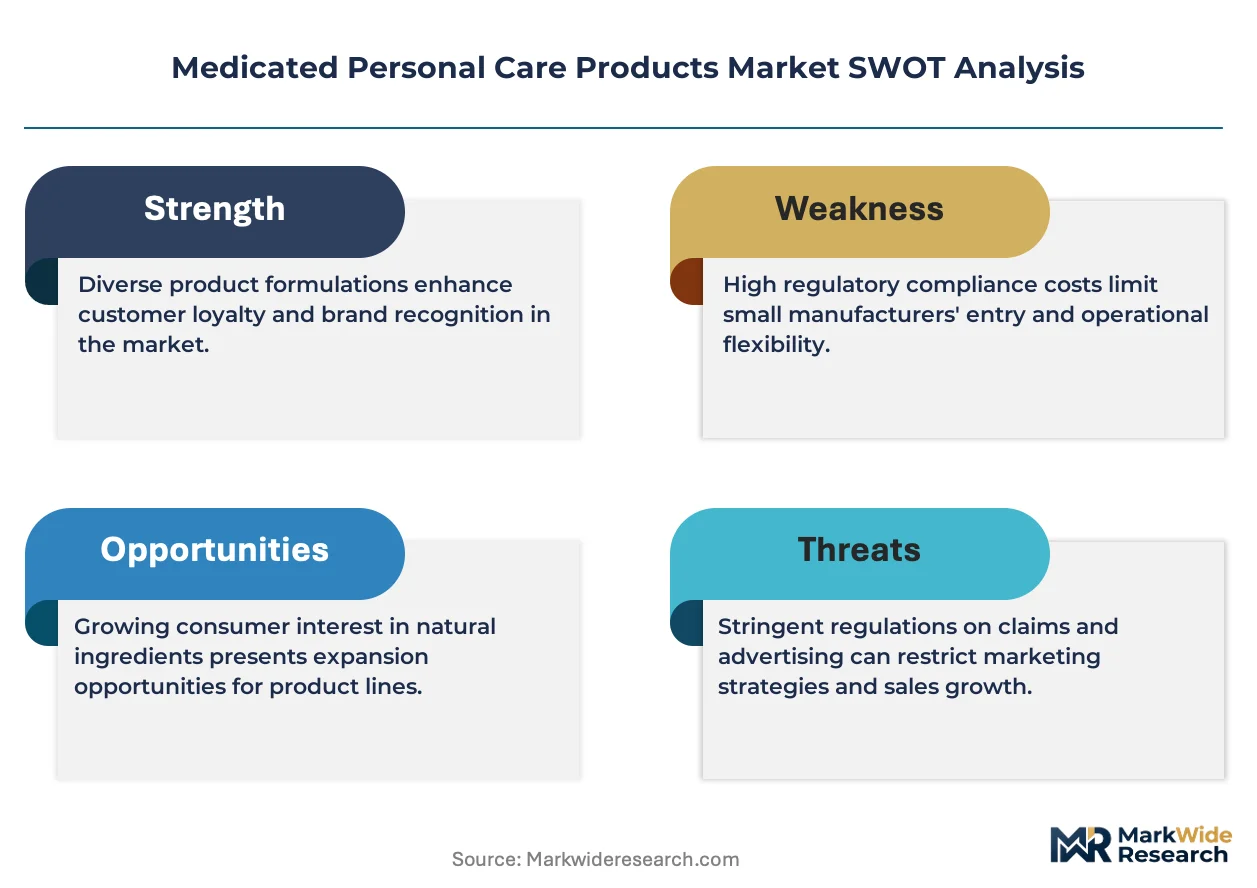
Regulatory classification ambiguity between cosmetics and drugs is forcing reformulation investments across the medicated personal care sector, as the FDA and EMA tighten borderline product scrutiny and disclosure mandates.
Growth Catalysts
- EMA Cosmetic-Therapeutic Borderline Clarity:The EMA's refined classification guidance is reducing market entry uncertainty for salicylic acid formulations in Germany and France, accelerating pharmacy channel expansion.
- Dermatology Clinic Dispensing:US and South Korean dermatology practices are building retail dispensing capabilities, creating direct-to-patient revenue streams for therapeutic skincare.
- Adult Acne Demand Convergence:Post-adolescent dermatological conditions are sustaining prescription-strength OTC demand in urban US and German markets.
Market Restraints
- Active Ingredient Cost Volatility:Benzoyl peroxide and hyaluronic acid supply concentrates among Chinese and Indian specialty chemical producers, exposing margins to input price swings.
- REACH Registration Burden:ECHA chemical registration requirements elevate European formulation transparency costs, particularly for novel delivery system ingredients.
- Regulatory Divergence Friction:Misaligned FDA-EMA classification thresholds force dual-track compliance investments for multinational product portfolios.
Strategic Opportunities
- South Korean Regulatory Tailwind:MFDS streamlined OTC approval pathways for medicated cosmetics are attracting formulation R&D investment from European and US manufacturers.
- Telehealth-Driven Channel Innovation:Digital dermatology platforms in the United States are creating subscription-based distribution for personalized therapeutic skincare regimens.
- Hyaluronic Acid-Niacinamide Convergence:Multi-active delivery systems combining these ingredients are opening anti-aging therapeutic positioning beyond traditional acne applications.
Industry Challenges
- Formulation Chemist Talent Scarcity:The intersection of pharmaceutical GMP and cosmetic sensory science requires hybrid expertise that outpaces current training pipeline output.
- FDA Monograph Compliance Timelines:OTC drug listing and facility registration processes create 12-18 month market entry delays for new benzoyl peroxide concentrations.
- Legacy ERP Integration Friction:Track-and-trace requirements for pharmaceutical-grade production clash with cosmetic industry batch record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medicated Personal Care Products Market |
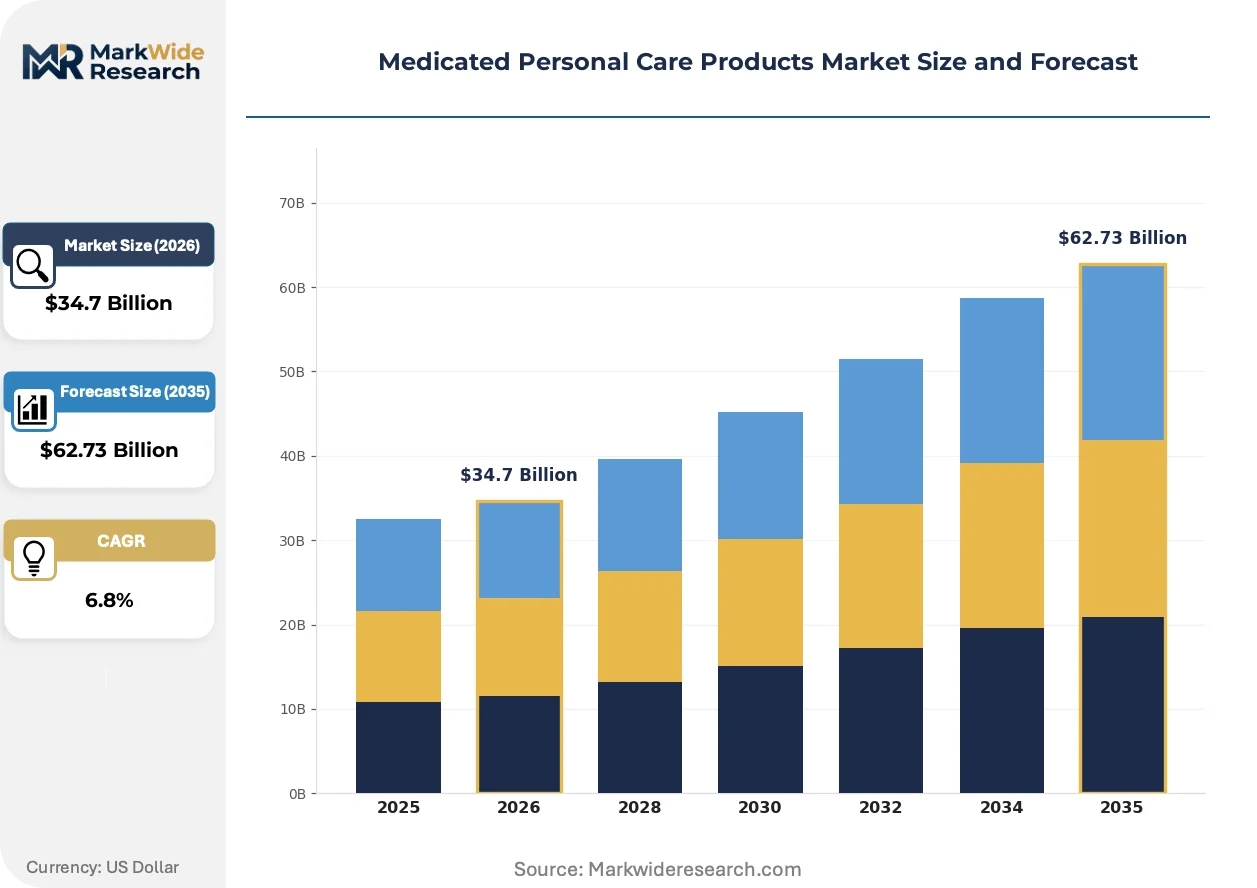
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Cleansers, Sunscreens, Shampoos Ingredient Type: Salicylic Acid, Benzoyl Peroxide, Hyaluronic Acid, Tea Tree Oil End User: Dermatologists, Pharmacists, Retail Consumers, Beauty Salons Application: Anti-Aging, Acne Treatment, Skin Hydration, Sun Protection |
| Companies Covered | Johnson & Johnson, Procter & Gamble, Bayer AG, Unilever, GlaxoSmithKline, Colgate-Palmolive, Reckitt Benckiser, Henkel AG, L'Oreal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medicated Personal Care Products Market Shifts & Advancements
Encapsulation technology and microbiome-targeted delivery systems are redrawing efficacy benchmarks in medicated personal care, compressing the gap between clinical outcomes and daily-use cosmetic experience.
Microencapsulation of benzoyl peroxide is decomposing the traditional stability-efficacy tradeoff that constrained formulation concentrations. Korean and German manufacturers are adopting lipid-shell delivery systems at accelerated rates. This technology is decomposing market segmentation between prescription and OTC strength categories by enabling higher active loads without irritation penalties.
California's state-level ingredient disclosure mandates are extending beyond federal FDA requirements, forcing national brands to adopt worst-case labeling standards. The industrial consequence is standardized transparency across US distribution regardless of destination state. Acne treatment lines targeting adolescent demographics face the steepest compliance cost escalation.
Subscription-based replenishment models are displacing pharmacy counter purchasing for chronic-condition skincare regimens. Direct-to-consumer channels in the United States and Germany are capturing recurring revenue from rosacea and eczema maintenance protocols. This shift concentrates customer lifetime value data with platform operators rather than retail pharmacists.
Medicated Personal Care Products Market Segmentation
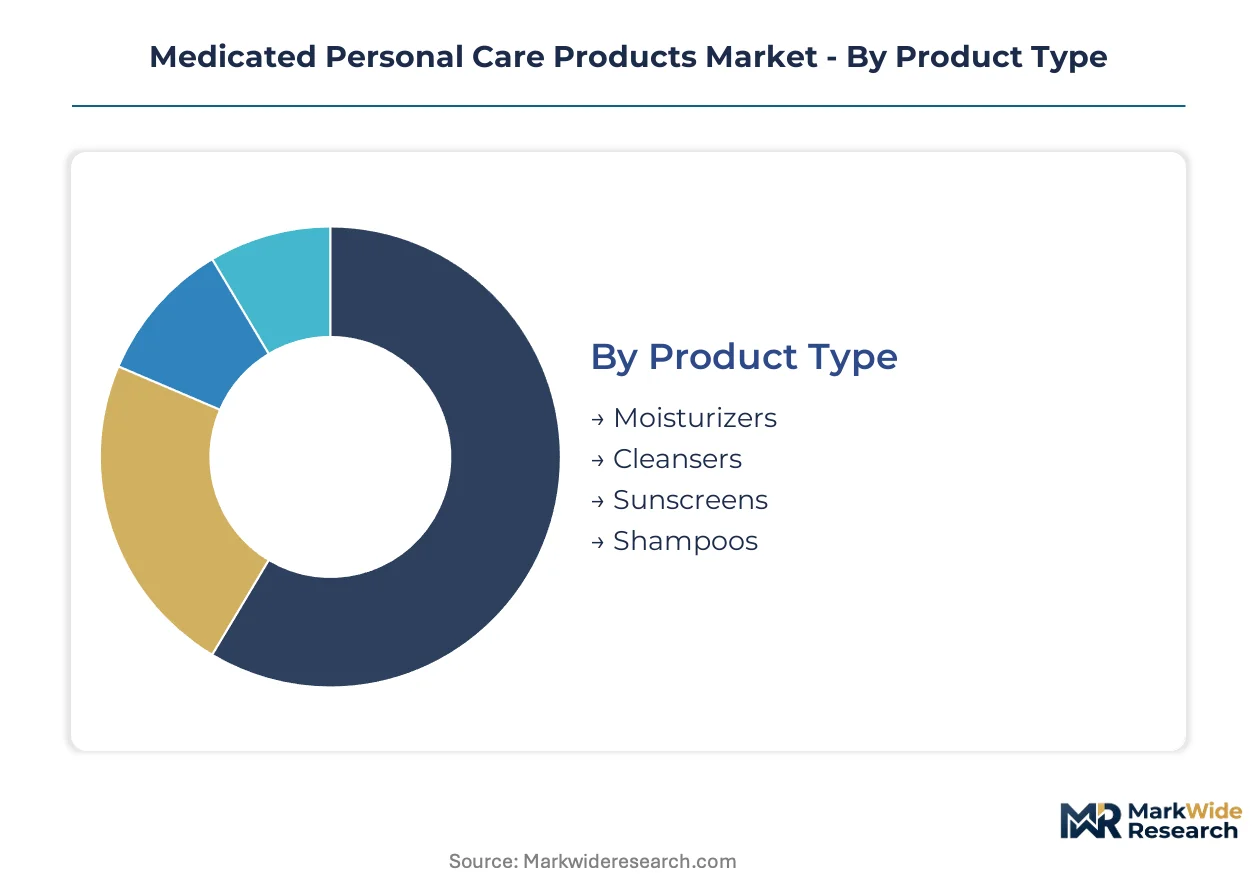
Medicated personal care segmentation reflects the tension between cosmetic formulation flexibility and pharmaceutical compliance requirements. Classification thresholds determine channel access, pricing architecture, and marketing claim boundaries across every segment dimension.
Product Type:
FDA monograph compliance and EMA borderline classifications fragment formulation strategies by delivery format, with stability requirements and shelf-life protocols varying substantially across topical categories.
- Moisturizers:Therapeutic moisturizers incorporate occlusive and humectant agents at concentrations requiring OTC drug listing in the United States. Demand concentrates in German pharmacy channels where dry skin conditions drive prescription-strength OTC adoption.
- Cleansers:Surfactant-based medicated cleansers deliver salicylic acid and benzoyl peroxide through rinse-off formats, with South Korean manufacturers leading encapsulation technology for irritation mitigation. Adult acne applications in US urban markets sustain premium positioning.
- Sunscreens:Photoprotective medicated formulations combine UV filters with anti-inflammatory actives, subject to FDA monograph and EMA cosmetic-therapeutic dual oversight.
- Shampoos:Anti-fungal and anti-dandruff shampoos leverage coal tar and pyrithione zinc at therapeutic concentrations, with pharmacy channel dominance in Germany and France.
Established volume favors moisturizers; emerging adoption favors cleansers.
Ingredient Type:
Active pharmaceutical ingredient sourcing geography and regulatory acceptance status determine margin structures and geographic rollout sequencing for formulation portfolios.
- Salicylic Acid:Beta-hydroxy acid at concentrations exceeding cosmetic thresholds commands broadest regulatory acceptance across FDA, EMA, and MFDS jurisdictions. German and US manufacturers prioritize this active for multi-market launch efficiency.
- Benzoyl Peroxide:Antimicrobial oxidizing agent requires stability engineering and microencapsulation investment to prevent degradation in cosmetic bases. Korean encapsulation specialists are capturing formulation partnerships.
- Hyaluronic Acid:Humectant polymer at medical-grade purity supports wound-healing claims and dermal filler adjacency, with Chinese fermentation supply concentrating input cost exposure.
- Tea Tree Oil:Natural-origin antimicrobial faces EMA allergen labeling requirements and California Proposition 65 disclosure mandates, limiting mass-market scalability.
Salicylic acid captures the broadest regulatory runway; hyaluronic acid is climbing the fastest on anti-aging therapeutic positioning.
End User:
Channel professionalization levels determine pricing architecture, with clinical credibility requirements escalating from retail self-selection through pharmacist consultation to dermatologist prescription authority.
- Dermatologists:Clinical dispensing of therapeutic skincare generates direct-to-patient revenue streams in US and South Korean practice models, with inventory investment shifting from retail pharmacists to clinic operators.
- Pharmacists:European pharmacy channel dominance in Germany and France sustains consultation-driven selection, though subscription models are displacing counter purchasing for chronic regimens.
- Retail Consumers:Self-directed purchasing concentrates in US mass-market and German drugstore channels, with telehealth platforms capturing customer data previously held by retail intermediaries.
- Beauty Salons:Aesthetic clinic adjacency supports premium professional-only lines, with regulatory ambiguity around scope-of-practice claims limiting geographic expansion.
Pharmacist channel retains the deepest chronic-condition loyalty; dermatologist dispensing is gaining share fastest on clinical credibility premiums.
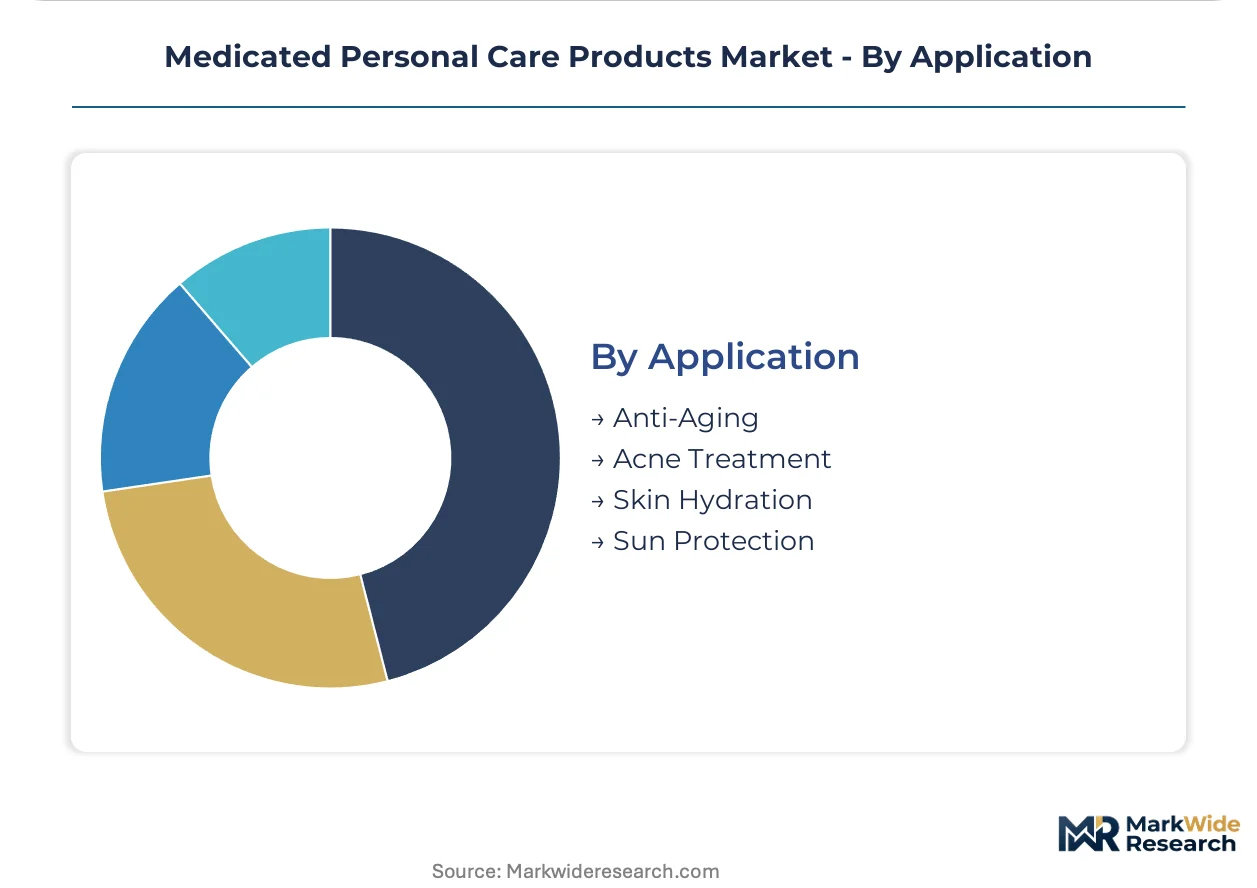
Application:
Condition severity and treatment duration determine subscription-model viability and lifetime value concentration, with chronic maintenance protocols outperforming acute intervention economics.
- Anti-Aging:Retinoid and peptide combinations at therapeutic concentrations target photoaging and wrinkle reduction, with South Korean MFDS streamlining approval pathways attracting R&D investment.
- Acne Treatment:Adolescent and adult-onset demand convergence sustains prescription-strength OTC volume in US and German urban markets, with benzoyl peroxide microencapsulation enabling higher active loads.
- Skin Hydration:Barrier repair formulations for eczema and rosacea maintenance generate recurring revenue through subscription replenishment in direct-to-consumer channels.
- Sun Protection:Photodamage prevention combines cosmetic elegance with therapeutic anti-inflammatory positioning, facing California disclosure mandate compliance cost escalation.
Acne treatment commands the steepest expansion trajectory; skin hydration delivers the most predictable recurring revenue profile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export medicated skincare formulations to South Korean distributors, establishing the primary transcontinental trade corridor in therapeutic cosmetics. This bilateral flow concentrates regulatory expertise and encapsulation technology transfer between two jurisdictions with stringent pharmaceutical-cosmetic borderline oversight.
United States
Dermatology clinic dispensing and telehealth subscription models drive demand concentration in California and New York. FDA monograph compliance timelines for benzoyl peroxide and salicylic acid products create 12-18 month market entry barriers. Boston and San Francisco anchor formulation R&D clusters where pharmaceutical GMP capabilities merge with cosmetic sensory science expertise.
Germany
Pharmacy channel consultation culture sustains prescription-strength OTC adoption for dry skin and eczema maintenance protocols. EMA borderline classification guidance reduces market entry uncertainty for salicylic acid formulations. The Rhine-Ruhr industrial corridor concentrates contract manufacturing capacity for lipid-shell microencapsulation systems serving French and Benelux distribution.
South Korea
MFDS streamlined OTC approval pathways attract European and US medicated cosmetic R&D investment. Adult acne demand convergence with adolescent segments sustains benzoyl peroxide microencapsulation adoption. Seoul Capital Area manufacturers lead lipid-shell delivery system production for export to German and US dermatology clinic networks.
France
ANSM allergen labeling requirements for tea tree oil and natural-origin antimicrobials limit mass-market scalability of therapeutic positioning. EMA cosmetic-therapeutic borderline scrutiny elevates formulation transparency costs for novel delivery ingredients. Lyon and Paris anchor pharmacy-centric distribution where consultation-driven selection resists subscription model displacement.
China
NMPA pharmaceutical-cosmetic classification thresholds force dual-track compliance for multinational portfolios seeking domestic market access. Hyaluronic acid fermentation supply concentrates in Shandong and Jiangsu provinces, exposing input cost volatility for medical-grade purity specifications. Yangtze River Delta contract manufacturers serve as formulation partners for Korean and German brand owners.
Medicated Personal Care Products Market Competitive Landscape
Listed leaders compete with private specialists across distribution channel access and regulatory compliance burden sharing. The vendor base stratifies between pharmaceutical heritage conglomerates, mass-market consumer goods houses, and pharmacy-channel specialists. Three archetypes dominate: drug-origin credibility anchors, scale-driven mass-market distributors, and therapeutic-category pure-plays. M&A activity concentrates on encapsulation technology acquisition and dermatology clinic network integration.
Within the pharmaceutical heritage tier, Johnson & Johnson and Bayer AG exemplify credibility anchors that leverage drug development expertise for therapeutic skincare positioning. Procter & Gamble occupies the mass-market vector where dermatologist-tested lines achieve scale through retail distribution density. These three entities represent divergent strategic bets on channel professionalization versus consumer self-selection.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Procter & Gamble |
| Bayer AG |
| Unilever |
| GlaxoSmithKline |
| Colgate-Palmolive |
| Reckitt Benckiser |
| Henkel AG |
| L'Oreal |
| Others |
Supply & Pricing Matrix
Contract manufacturing scale in the Rhine-Ruhr corridor and Seoul Capital Area determines unit economics for microencapsulated actives, concentrating supply-side leverage among Korean and German producers while establishing price floors for benzoyl peroxide and salicylic acid formulations.
Pricing Analysis
Legacy emulsion-based formulations trade at commodity margins against next-generation lipid-shell microencapsulated products commanding 40-60% premiums. Three-tier pricing structure across premium, standard, and economy levels reflects GMP certification grade and dermatologist endorsement density. Cost compression in standard-tier cleansers intensifies as Chinese contract manufacturers expand fermentation capacity for hyaluronic acid. Retail consumers in US mass-market channels exhibit highest price sensitivity; dermatology clinic dispensing captures lowest sensitivity through clinical credibility premiums.
Supply Chain Analysis
Strategic stockpiling of benzoyl peroxide and salicylic acid concentrates prevails among German and US formulators due to Chinese and Indian specialty chemical supply concentration. Active pharmaceutical ingredient sourcing draws from Shandong fermentation clusters for hyaluronic acid, Gujarat chemical corridors for benzoyl peroxide, and Korean biotech parks for encapsulation polymers. Single-source vulnerability in lipid-shell delivery system technology exposes margins to Korean supplier capacity constraints. Distribution runs through pharmacy wholesale networks in Germany, dermatology clinic direct accounts in the United States, and MFDS-licensed distributors in South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid formulation chemist expertise bridging pharmaceutical GMP and cosmetic sensory science represents the critical capability gap, with training pipeline output lagging demand from encapsulation technology adopters and regulatory compliance expansions.
For Market Incumbents: Consolidate encapsulation technology partnerships before Korean specialists impose exclusivity terms, and deepen backward integration into salicylic acid API production to offset Indian and Chinese input volatility. Threat substitution from microbiome-targeted delivery systems demands accelerated R&D in lipid-shell innovation. Channel control through dermatology clinic dispensing networks offers the strongest defensive lever against subscription-platform disintermediation. For New Entrants and Emerging Players: Anchor in South Korean MFDS streamlined approval pathways for medicated cosmetics, where European and US manufacturers are underrepresented relative to domestic incumbents. Adult acne maintenance regimens in German pharmacy channels present the most penetrable white-space, with telehealth subscription models offering direct-to-patient access without retail slotting fee barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors encapsulation specialists with GMP-certified manufacturing and established dermatology clinic relationships over pure-play cosmetic houses lacking pharmaceutical compliance infrastructure. Long-term viability hinges on regulatory divergence arbitrage capability across FDA, EMA, and MFDS jurisdictions. Acquisition targets should demonstrate dual-track compliance execution. The signal to watch is EMA borderline classification threshold tightening, which would accelerate consolidation among sub-scale European formulators unable to absorb transparency cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Acquisition | Lipid-shell delivery capability separates prescription-adjacent positioning from commodity OTC competition. |
| Dermatology Clinic Network Integration | Direct dispensing relationships capture patient lifetime value previously held by retail pharmacists. |
| MFDS Regulatory Pathway Investment | Streamlined South Korean OTC approvals accelerate market entry for novel therapeutic cosmetic formulations. |
| Backward Integration into API Production | In-house salicylic acid manufacturing insulates margins from Chinese and Indian supply volatility. |
| Telehealth Platform Partnership | Digital dermatology subscriptions displace pharmacy counter purchasing for chronic-condition regimens. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with formulation R&D directors, regulatory affairs leads at multinational consumer health divisions, pharmacy procurement managers in Germany and France, and dermatology clinic operators in the United States and South Korea; and secondary validation against FDA OTC monograph filings, EMA borderline classification guidance documents, MFDS approval registries, and customs trade data for active pharmaceutical ingredient flows. Bottom-up demand modeling across product type, ingredient concentration tier, and end-user channel triangulated against top-down market sizing from pharmaceutical and cosmetic industry associations.
Across the analysis window, value projections reflect segment-specific growth trajectories calibrated to regulatory approval timelines, encapsulation technology adoption curves, and channel shift dynamics. Segmentation dimensions modeled include product format stability requirements, active ingredient regulatory acceptance status, end-user professionalization level, and application condition chronicity. CAGRs derive from historical volume elasticities applied to projected regulatory pathway expansions and dermatology clinic dispensing penetration rates. Forecast inputs incorporate EMA borderline classification revision probabilities and MFDS streamlined pathway utilization rates.
Material uncertainties — FDA monograph compliance timeline extensions, EMA allergen labeling mandate expansions, and active ingredient supply disruptions from Chinese environmental enforcement actions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory divergence stability and encapsulation technology cost-down curves. Revision becomes warranted when EMA-FDA classification threshold misalignment exceeds current dual-track compliance burden thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Brazil Sustainable Personal Care Market
Beauty & Personal Care
False Eyelashes Market
Beauty & Personal Care
Makeup Setting Spray Market
Beauty & Personal Care
Facial Oil Market
Beauty & Personal Care
South America Hair Conditioner Market
Beauty & Personal Care
Beauty Tools Market
Beauty & Personal Care
Facial Cleansers and Toners Market
Beauty & Personal Care
Natural Deodorant Crystal Market
Beauty & Personal Care
South Korea Beauty Fridges Market
Beauty & Personal Care
Europe Cosmeceuticals Market
Beauty & Personal Care
Japan Beauty and Personal Care Products Market
Beauty & Personal Care
Bar Soap Market
Beauty & Personal Care
Global Hot Air Brushes Market
Beauty & Personal Care
LAMEA Hair Removal Wax Market
Beauty & Personal Care
Spray Tanning Market
Beauty & Personal Care
Brazil Beauty and Personal Care Products Market