
 Japan Beauty and Personal Care Products Market | 2026-2036
Japan Beauty and Personal Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Beauty and Personal Care Products Market Foresight
Department store buyer consolidation is realigning wholesale power toward a handful of national chains. Shiseido Co Ltd leverages its domestic manufacturing footprint to sustain pharmacy shelf dominance. Kao Corporation anchors volume through mass-market haircare and daily-use skincare lines. Kosé Corp competes in premium department store channels with specialized J-beauty formulations.
Beauty and personal care products encompass topical formulations for skin, hair, and body maintenance, typically manufactured through emulsification, fermentation, or extraction processes with pH-balanced active concentrations. These products serve consumer hygiene, aesthetic enhancement, and dermatological protection across retail and professional settings. Skincare commands the largest revenue pool among product types, reflecting Japan's aging demographic and preventive dermatology culture. Online retail represents the fastest-growing sales channel, though specialty stores retain margin concentration through personalized consultation services.
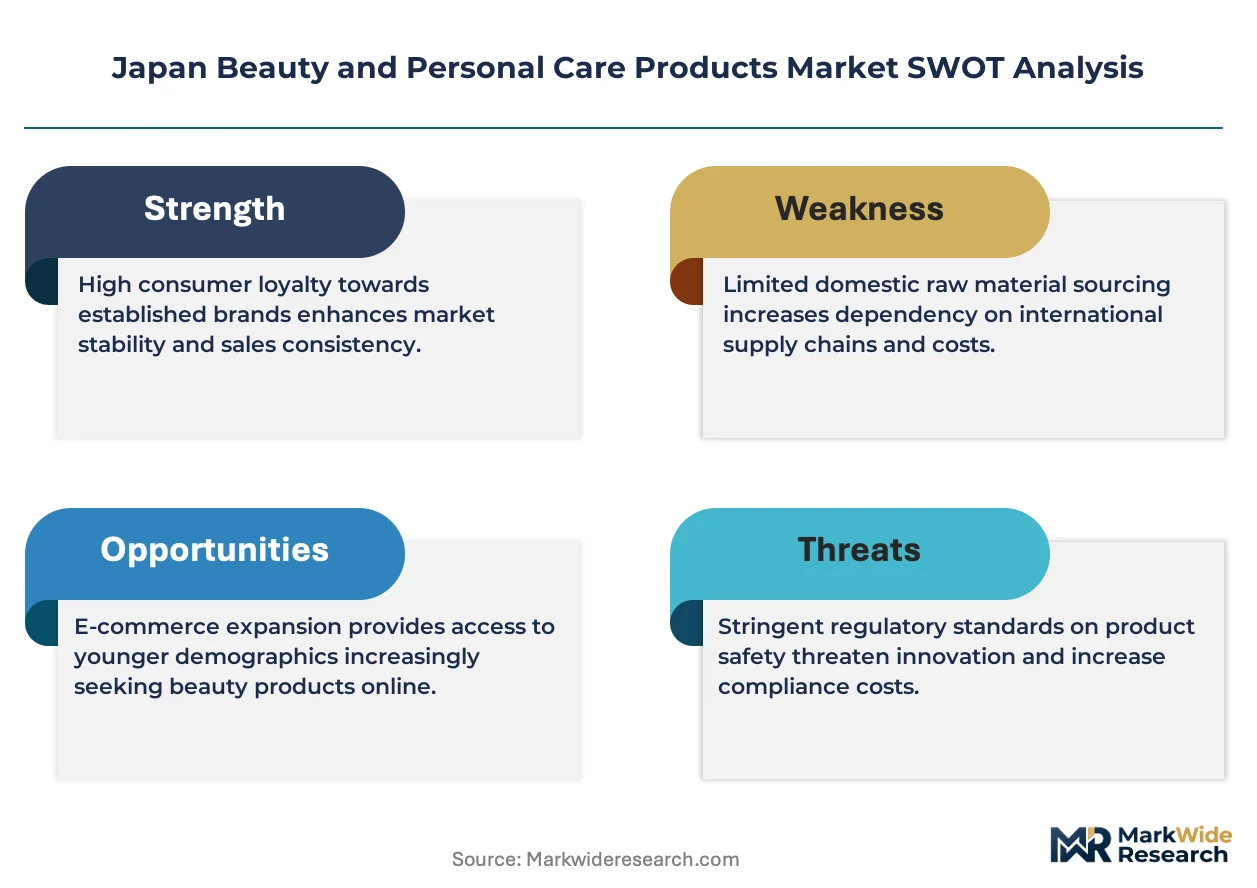
Japan's Ministry of Health, Labour and Welfare enforces the Pharmaceutical and Medical Device Act, which governs cosmetic safety standards and quasi-drug classifications. METI coordinates industry standards through JIS frameworks affecting packaging claims and sustainability metrics. PMDA oversight of functional ingredient approvals creates compliance barriers that favor established domestic laboratories with regulatory filing experience. Stakeholders must monitor evolving quasi-drug reclassification timelines and green packaging mandates to preserve market access and brand positioning.
Market Dynamics
Japan's Pharmaceutical and Medical Device Act reform is compressing formulation approval timelines while elevating quasi-drug documentation requirements, forcing domestic laboratories to accelerate regulatory filing capabilities or cede shelf space to established incumbents with PMDA rapport.
Growth Catalysts
- Preventive dermatology culture:Middle-aged consumers in Tokyo and Osaka metropolitan corridors are expanding premium skincare routines into daily preventive regimens, elevating average basket values in pharmacy and department store channels.
- Online retail infrastructure:E-commerce platforms are capturing consultative skincare transactions previously reserved for specialty stores, with logistics networks now supporting temperature-sensitive active ingredient delivery.
- METI green packaging mandates:Sustainability disclosure requirements under JIS frameworks are accelerating biodegradable material adoption among domestic manufacturers seeking regulatory preference in public procurement.
Market Restraints
- Functional ingredient approval friction:PMDA quasi-drug reclassification timelines extend 18-24 months for novel active compounds, freezing pipeline commercialization for mid-tier laboratories lacking regulatory filing experience.
- Department store buyer consolidation:Wholesale power concentrates among three national chains, compressing margin negotiations for specialty J-beauty brands dependent on premium retail presence.
- Synthetic preservative substitution pressure:Clean beauty positioning is displacing paraben-based formulations, requiring costly reformulation of legacy emulsion systems without equivalent shelf stability guarantees.
Strategic Opportunities
- Rural prefecture underpenetration:Tohoku and Shikoku regions exhibit skincare spending gaps versus Kanto benchmarks, presenting white-space opportunity for pharmacy chain expansion with localized marketing.
- Subscription replenishment models:Direct-to-consumer auto-replenishment platforms are capturing recurring revenue from aging consumers seeking convenience without consultation dependency.
- Fermentation-derived actives convergence:Biotechnology-processed ingredients from sake lees and rice bran are differentiating domestic formulations against imported competitors in Asian export markets.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in emulsion stability for humid climates is concentrating among retiring professionals, constraining new product development velocity.
- Legacy ERP integration:Batch traceability requirements under PMDA enforcement are forcing family-owned laboratories to replace paper-based manufacturing records with validated digital systems.
- Cross-border labeling complexity:Divergent quasi-drug definitions between Japan and export destinations are fragmenting packaging runs and elevating SKU proliferation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Beauty and Personal Care Products Market |
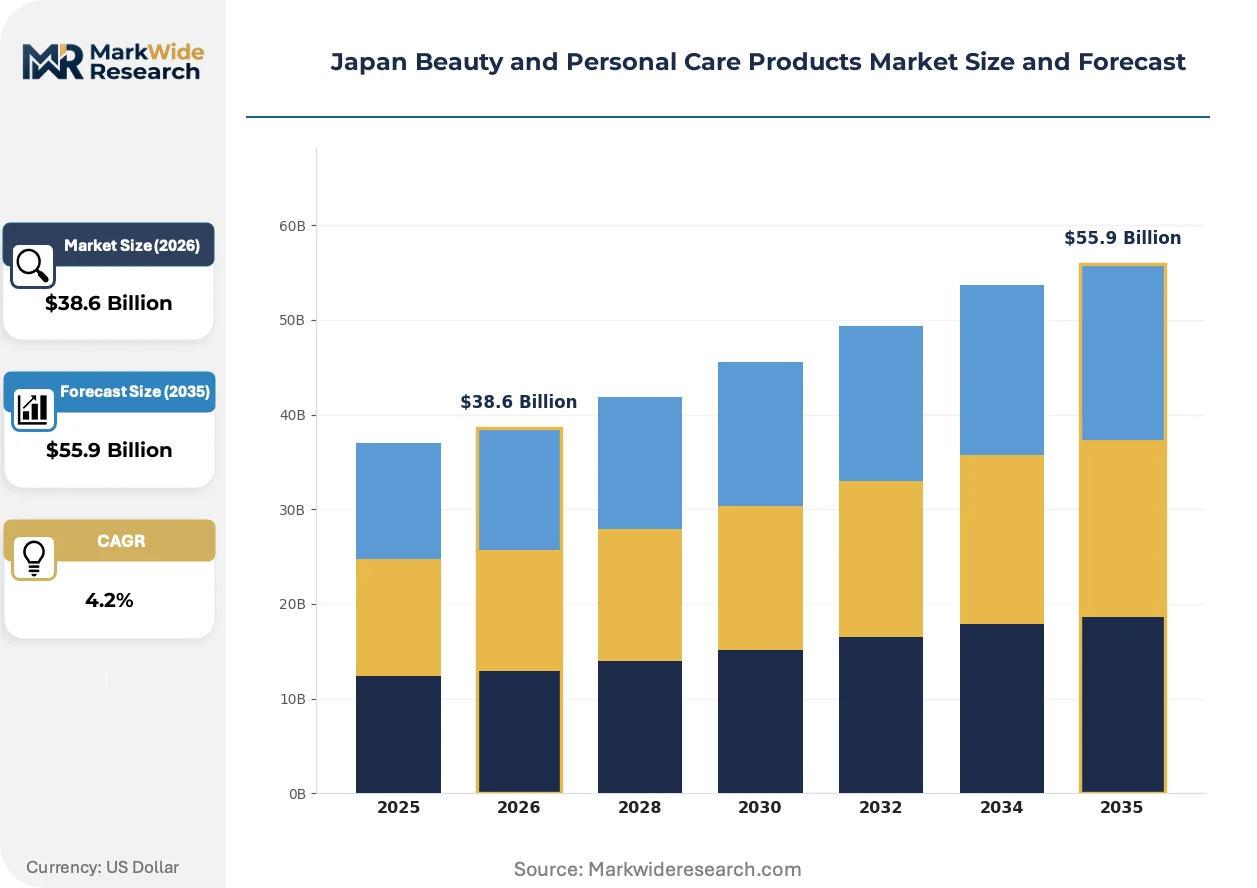
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $55.9 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance Consumer Age Group: Teenagers, Young Adults, Middle-aged, Seniors Sales Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies Brand Positioning: Luxury, Mass-market, Premium, Organic |
| Companies Covered | Pola Orbis Holdings Inc, L'Oréal Japan Ltd, Shiseido Co Ltd, Estée Lauder Group Cos KK, P&G Japan Ltd, Kao Corporation, Kanebo Cosmetics Inc, Chanel KK, Kosé Corp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Beauty and Personal Care Products Market Shifts & Advancements
Formulation science and distribution architecture are undergoing simultaneous recalibration as regulatory stringency intersects with digital channel maturation and shifting consumer consultation preferences.
Artificial intelligence-driven skin diagnostic tools are automating personalized regimen recommendations previously delivered by trained beauty consultants. Pharmacy chains in Tokyo prefecture are deploying these systems at scale, compressing the consultation-to-purchase cycle from fifteen minutes to under three minutes. The technology is automating inventory forecasting by linking diagnostic data to regional skin condition prevalence patterns.
PMDA's expanded quasi-drug classification criteria are tightening evidentiary standards for whitening and anti-aging claims. Domestic manufacturers must now submit clinical trial data for ingredients previously approved under abbreviated pathways. Premium department store channels are absorbing compliance costs through price tier elevation, while mass-market brands are retreating to basic moisturizing positioning.
Specialty store consultation services are unbundling from product transactions as consumers seek expertise without immediate purchase obligation. Independent beauty advisors in Osaka are monetizing knowledge through appointment-based fees rather than commission structures. This behavioral shift is most visible among consumers aged 45-60 who research extensively online before selective in-person validation.
Japan Beauty and Personal Care Products Market Segmentation
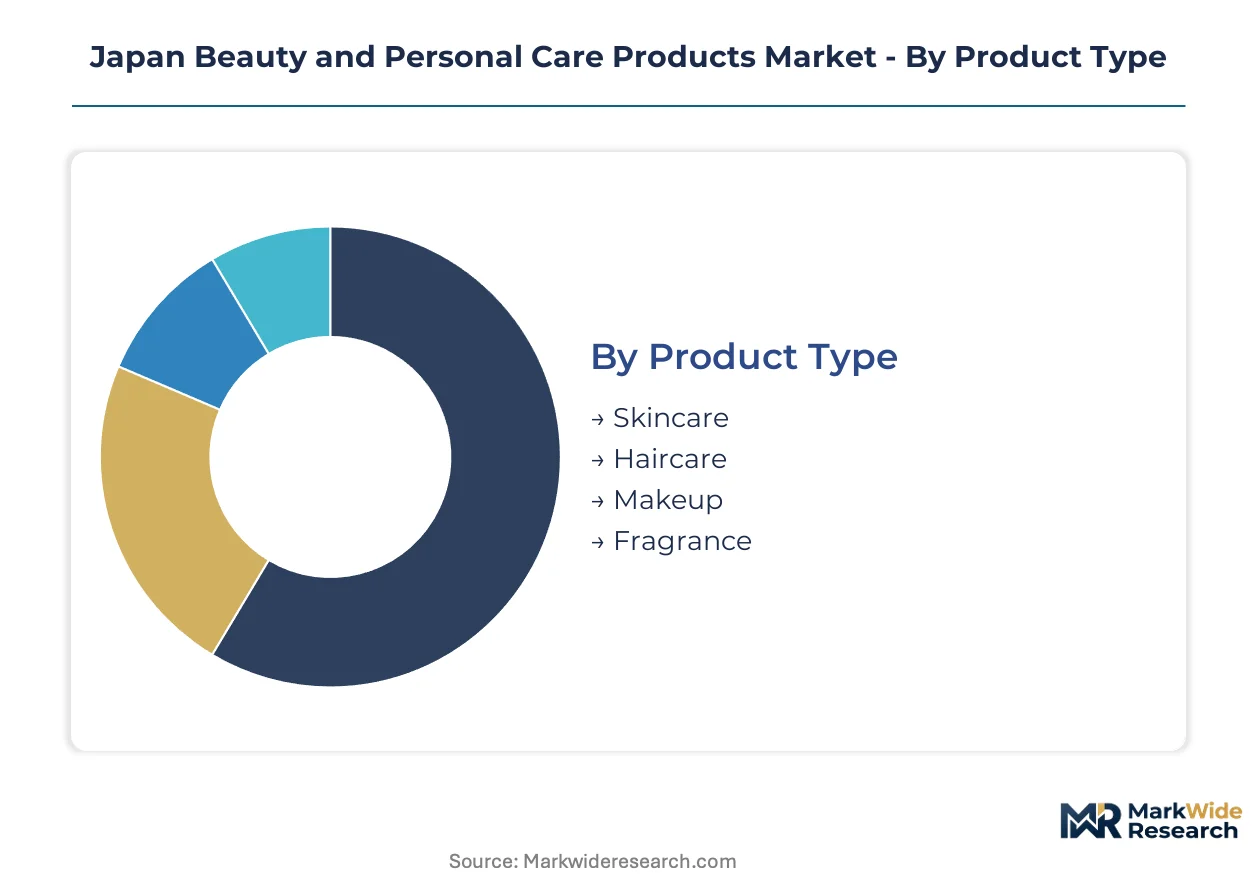
Segmentation in Japan's beauty market reveals how regulatory pressure and channel evolution fragment demand across distinct purchasing behaviors. PMDA quasi-drug classifications and METI sustainability mandates create divergent compliance burdens that reshape competitive positioning within each segment cluster.
Product Type:
Standalone formulations dominate pharmacy and department store shelves, while embedded multi-step systems integrate cleansing, treatment, and protection into unified regimen architectures.
- Skincare:Emulsion-based formulations with pH-balanced active concentrations serve preventive dermatology routines. Tokyo and Osaka metropolitan corridors concentrate demand among middle-aged consumers expanding daily regimens into premium tiers.
- Haircare:Mass-market shampoo and conditioner lines anchor volume through pharmacy chains, with specialized scalp treatment segments gaining traction among aging demographics seeking functional solutions beyond basic cleansing.
- Makeup:Color cosmetics face reformulation pressure as clean beauty mandates displace synthetic preservatives.
- Fragrance:Niche domestic houses compete against imported prestige brands in department store channels.
Volume placements concentrate in Skincare; the faster expansion belongs to specialized scalp treatment segments within Haircare.
Consumer Age Group:
Purchasing authority and consultation preferences diverge sharply across generational cohorts, with digital-native segments bypassing traditional specialty store channels entirely.
- Middle-aged:Consumers aged 45-60 command the largest premium skincare expenditure, driving pharmacy chain expansion and subscription auto-replenishment adoption. Preventive dermatology culture elevates basket values through multi-step regimen adherence.
- Seniors:Aging populations in rural prefectures seek functional formulations addressing thinning hair and age-related skin conditions, creating white-space opportunity for localized marketing in Tohoku and Shikoku regions.
- Young Adults:Digital-first research behaviors compress consultation-to-purchase cycles through AI-driven skin diagnostic tools deployed at scale in Tokyo prefecture.
- Teenagers:Entry-level price sensitivity concentrates demand in mass-market channels with influencer-driven product discovery.
Revenue concentration sits with Middle-aged consumers; steepest expansion trajectory belongs to Seniors as demographic aging accelerates.
Sales Channel:
Channel selection determines margin structure and regulatory exposure, with temperature-sensitive logistics now enabling active ingredient integrity across previously unsuitable distribution modes.
- Online Retail:E-commerce platforms capture consultative transactions previously reserved for specialty stores, with logistics networks supporting temperature-sensitive active ingredient delivery. Auto-replenishment models secure recurring revenue from aging consumers seeking convenience.
- Specialty Stores:Personalized consultation services retain margin concentration despite unbundling from immediate purchase obligation. Independent beauty advisors in Osaka monetize expertise through appointment-based fee structures.
- Pharmacies:Shelf dominance by domestic manufacturers with PMDA filing experience limits mid-tier laboratory access.
- Supermarkets:Mass-market haircare and daily-use skincare lines anchor volume through Kao Corporation's established distribution.
Transaction volume concentrates in Pharmacies; channel share is climbing fastest in Online Retail as consultation digitization matures.
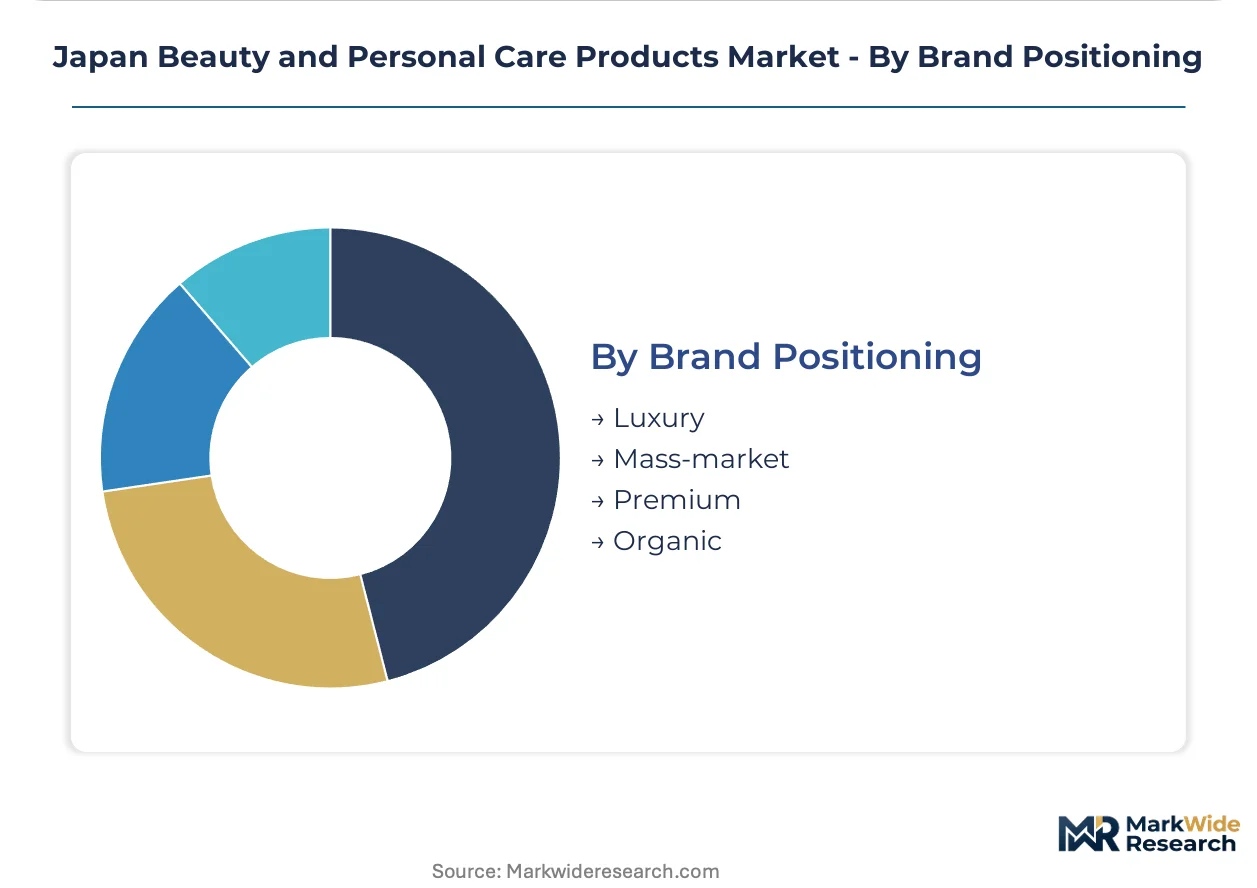
Brand Positioning:
Positioning tier determines regulatory compliance burden and formulation flexibility, with quasi-drug reclassification timelines creating divergent pipeline constraints across price bands.
- Premium:Department store channels absorb PMDA compliance costs through price tier elevation, with specialized J-beauty formulations from domestic laboratories differentiating against imported competitors. Clinical trial data requirements for whitening and anti-aging claims favor established incumbents.
- Mass-market:Volume anchoring through pharmacy chains requires efficient manufacturing scale and domestic production footprint. Brands retreat to basic moisturizing positioning as functional claim documentation burdens intensify.
- Luxury:Prestige positioning in consolidated national department store chains faces compressed margin negotiations.
- Organic:Clean beauty mandates drive paraben substitution without equivalent shelf stability guarantees.
Revenue concentration aligns with Premium positioning; share expansion is occurring fastest in Organic as METI green packaging mandates reshape procurement preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for beauty and personal care products concentrates in Japan's metropolitan corridors, with Tokyo and Osaka commanding disproportionate premium skincare expenditure. Rural prefectures exhibit significant underpenetration relative to urban benchmarks. Regulatory enforcement by METI and PMDA operates uniformly across all sub-regions, though compliance costs burden smaller laboratories in peripheral markets disproportionately.
Kanto/Tokyo
Tokyo prefecture drives the highest per-capita spending on preventive dermatology regimens among middle-aged consumers. METI's JIS sustainability frameworks receive strictest enforcement in this jurisdiction, accelerating biodegradable packaging adoption among manufacturers serving the capital corridor. Pharmacy chains deploy AI-driven skin diagnostic tools at scale throughout Shibuya and Ginza retail clusters, compressing consultation-to-purchase cycles.
Kansai/Osaka
Osaka's metropolitan corridor mirrors Tokyo's premium skincare demand intensity, with independent beauty advisors pioneering appointment-based consultation fees. PMDA quasi-drug documentation requirements elevate compliance burdens for domestic laboratories headquartered in this region. Department store buyer consolidation concentrates wholesale power among three national chains operating flagship locations in Osaka's central commercial districts.
Chubu/Nagoya
Nagoya anchors manufacturing capacity for domestic beauty brands with PMDA filing experience, leveraging proximity to pharmaceutical research clusters. The region's industrial base supports fermentation-derived active ingredient processing from sake lees and rice bran. Local laboratories face formulation chemist scarcity as specialized expertise in emulsion stability concentrates among retiring professionals.
Kyushu
Kyushu's aging demographic profile exceeds national averages, expanding demand for functional scalp treatment and age-related skin condition formulations. METI green packaging mandates reshape procurement preferences for manufacturers serving this market. Fukuoka's logistics infrastructure enables temperature-sensitive active ingredient distribution to peripheral islands.
Tohoku
Tohoku exhibits the largest skincare spending gap versus Kanto benchmarks, presenting white-space opportunity for pharmacy chain expansion. PMDA enforcement of batch traceability requirements forces family-owned laboratories to replace paper-based manufacturing records with validated digital systems. Localized marketing strategies remain underdeveloped compared to metropolitan corridors.
Japan Beauty and Personal Care Products Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital-native distribution and subscription replenishment models. The market structure consolidates around domestic incumbents with regulatory filing rapport and multinational subsidiaries leveraging global R&D pipelines. Three archetypes dominate: pharmaceutical-origin laboratories with quasi-drug expertise, diversified consumer goods conglomerates anchoring mass-market volume, and prestige houses defending department store positioning. Competitive moves concentrate on M&A absorption of mid-tier brands and backward integration into fermentation-derived active ingredient supply.
Among domestic-headquartered players, Shiseido Co Ltd, Kao Corporation, and Kosé Corp represent distinct strategic positions within the competitive architecture. Shiseido exemplifies the pharmaceutical-origin archetype with domestic manufacturing footprint sustaining pharmacy shelf dominance. Kao anchors the diversified conglomerate tier through mass-market haircare and daily-use skincare lines. Kosé occupies premium department store channels with specialized J-beauty formulations. These three entities collectively illustrate how regulatory filing experience, manufacturing scale, and channel positioning separate viable competitors from constrained aspirants.
| Leading Market Players |
|---|
| Pola Orbis Holdings Inc |
| L'Oréal Japan Ltd |
| Shiseido Co Ltd |
| Estée Lauder Group Cos KK |
| P&G Japan Ltd |
| Kao Corporation |
| Kanebo Cosmetics Inc |
| Chanel KK |
| Kosé Corp |
| Others |
Supply & Pricing Matrix
Department store buyer consolidation among three national chains is compressing wholesale margins for specialty J-beauty brands, forcing manufacturers to absorb PMDA compliance costs through tier elevation or retreat to mass-market positioning. This procurement power shift concentrates pricing leverage with consolidated retail gatekeepers while fragmenting supplier negotiation positions.
Pricing Analysis
Volume placements anchor mass-market pharmacy channels at compressed margins, while premium department store tiers capture value through clinical trial documentation and quasi-drug positioning. Price differentiation rests on PMDA filing experience and JIS sustainability certification tiers. Pricing pressure intensifies in mass-market segments as clean beauty mandates force costly paraben substitution without shelf stability equivalence. Young adult digital-first segments exhibit highest price sensitivity through influencer-driven discovery, while middle-aged preventive dermatology consumers show lowest elasticity for documented efficacy claims.
Supply Chain Analysis
Direct-to-pharmacy channels handle hyperscale distribution for Kao Corporation's daily-use lines, while specialty store networks manage temperature-sensitive active ingredient delivery for premium formulations. Manufacturing concentrates in Japan's Chubu region, with fermentation-derived inputs sourced domestically from sake lees and rice bran processing clusters. Raw material dependencies include specialized emulsion stabilizers, biodegradable packaging substrates, and biotechnology-processed actives. Single-source vulnerability concentrates in formulation chemist expertise for humid climate stability. Distribution runs through consolidated national department store chains and expanding e-commerce logistics networks with cold-chain capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemist scarcity constrains new product development velocity, propping pricing power for laboratories with retained expertise and PMDA rapport. This supply-constrained structure favors incumbents with regulatory filing capabilities and backward integration into fermentation-derived active ingredient supply.
For Market Incumbents: Extend regulatory filing capabilities through accelerated PMDA rapport development, securing quasi-drug pipeline priority against mid-tier laboratories facing 18-24 month approval freezes. Deepen backward integration into sake lees and rice bran fermentation processing to capture biotechnology-derived active ingredient margins. Counter subscription replenishment platform threats through direct-to-consumer auto-replenishment deployment targeting aging consumer convenience preferences. For New Entrants and Emerging Players: AI-driven skin diagnostic tools offer technology-first entry points into pharmacy channel digitization, bypassing incumbent consultation infrastructure. Target Tohoku and Shikoku rural prefectures exhibiting skincare spending gaps versus Kanto benchmarks, where localized marketing remains underdeveloped and pharmacy chain expansion presents white-space opportunity. Pursue subscription replenishment models capturing recurring revenue from senior demographics seeking convenience without consultation dependency. For Investors and Strategic Acquirers: The window for entry favors domestic laboratories with PMDA filing experience and fermentation-derived active ingredient capabilities, positioned for quasi-drug reclassification tailwinds. Long-term viability centers on regulatory compliance moats and biotechnology processing differentiation rather than brand equity alone. Monitor PMDA quasi-drug reclassification timeline acceleration as inflection signal for pipeline commercialization velocity and competitive consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Quasi-Drug Filing Acceleration | Compresses approval timelines for whitening and anti-aging claims, favoring incumbents with regulatory rapport. |
| Fermentation-Derived Active Integration | Biotechnology processing of sake lees and rice bran differentiates domestic formulations in Asian export markets. |
| Subscription Replenishment Platform Launch | Auto-replenishment models secure recurring revenue from aging consumers seeking consultation-independent convenience. |
| Rural Prefecture Pharmacy Expansion | Tohoku and Shikoku underpenetration offers white-space growth with localized marketing deployment. |
| AI Skin Diagnostic Tool Deployment | Automated consultation systems compress purchase cycles and enable inventory forecasting by regional skin condition patterns. |
Research Methodology
Independent corroboration across PMDA quasi-drug filing databases, METI JIS sustainability framework documentation, and pharmacy chain procurement records underwrites the qualitative findings. Primary interviews with brand managers at domestic manufacturers, category buyers at consolidated department store chains, regulatory affairs specialists, and formulation chemists combined with secondary validation from customs trade data, Nielsen retail audit records, and pharmaceutical industry association reports. Bottom-up SKU-level analysis triangulated against top-down market sizing from production and trade flows.
Comparable historical reference periods anchored the projection framework across the analysis window, with growth trajectories derived from segment-specific demand elasticity modeling and regulatory timeline assumptions. Segmentation dimensions included product type, consumer age cohort, sales channel architecture, and brand positioning tier. CAGRs reflect compounding assumptions around preventive dermatology culture penetration, e-commerce logistics maturation, and quasi-drug reclassification velocity. Forecast inputs incorporated PMDA approval pipeline data and METI green packaging mandate compliance cost estimates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under PMDA regulatory timeline acceleration or deceleration scenarios, department store buyer consolidation extending beyond three national chains, and formulation chemist retirement waves constraining new product development. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Europe and Asia Pacific Herbal Beauty Products Market
Beauty & Personal Care
India Hair Oil Market
Beauty & Personal Care
UK Vegan Cosmetics Market
Beauty & Personal Care
Spray Tanning Market
Beauty & Personal Care
Beeswax for Cosmetics Market
Beauty & Personal Care
Facial Wipes Market
Beauty & Personal Care
Deodorant & Anti-Perspirant Market
Beauty & Personal Care
Underarm Antiperspirant and Deodorant Market
Beauty & Personal Care
Loofah Bath Sponge Market
Beauty & Personal Care
Organic Liquid Soaps Market
Beauty & Personal Care
Middle East and Africa Hair Conditioner Market
Beauty & Personal Care
United States Beauty and Personal Care Products Market
Beauty & Personal Care
Nail Art Tools and Accessories Market
Beauty & Personal Care
Dry Shampoo Market
Beauty & Personal Care
Body Balm Market
Beauty & Personal Care
Eyelash Curler Market