
 Natural Deodorant Crystal Market | 2026-2036
Natural Deodorant Crystal Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Deodorant Crystal Market Insights
Clean-label formulation is narrowing the gap between conventional antiperspirant efficacy and natural deodorant performance. Thai Crystal Deodorant leverages its Bangkok manufacturing base to control raw alum supply from regional mines. Crystal Body Deodorant anchors North American shelf presence through pharmacy and natural grocery distribution. Salt of the Earth differentiates via B Corp certification and refillable packaging formats.
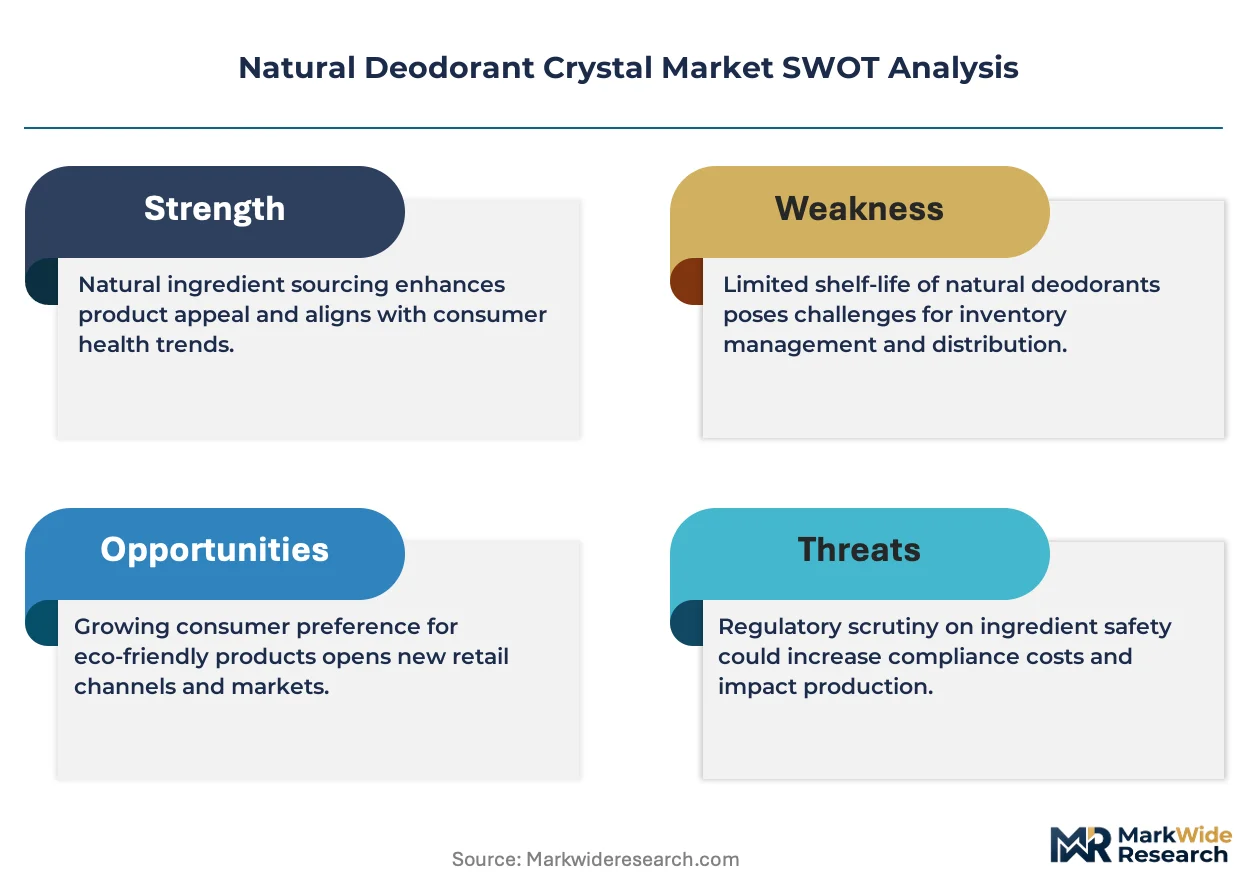
Natural deodorant crystals are solid antiperspirant alternatives composed primarily of potassium alum or ammonium alum, mineral salts that inhibit bacterial growth without blocking sweat ducts through aluminum chloride mechanisms. The potassium alum segment dominates current volume due to established supply chains from Thai and Chinese mines, while natural mineral stones represent the fastest-growing category as unprocessed, zero-waste formats gain traction among eco-conscious consumers. Application demand skews heavily toward personal care and organic cosmetics, where margin pools concentrate in premium positioning through specialty stores and online retail channels.
EU REACH and the EU Green Deal restrict synthetic aluminum chlorohydrate in cosmetic formulations, creating regulatory tailwinds for alum-based alternatives. The US FDA oversees antiperspirant-drug claims while allowing deodorant products to market under cosmetic regulations, creating a compliance bifurcation that shapes product labeling strategies. Stakeholders must monitor evolving definitions of natural claims across jurisdictions to avoid greenwashing litigation exposure.
Market Dynamics
EU REACH restrictions on synthetic aluminum chlorohydrate are compressing conventional antiperspirant formulations while expanding addressable demand for alum-based mineral alternatives across European pharmacy and specialty retail channels.
Growth Catalysts
- REACH compliance migration:ECHA's aluminum compound restrictions in cosmetic formulations are forcing brand owners to reformulate with potassium alum minerals. German pharmacist networks now stock alum stones as first-line recommendations.
- Zero-waste retail expansion:Refillable mineral stone formats are displacing single-use plastic packaging in UK and Scandinavian zero-waste stores. Unprocessed crystal stones eliminate synthetic binders entirely.
- Fitness culture normalization:Daily gym attendance patterns in urban centers are creating reapplication occasions that favor portable, non-staining crystal formats over roll-on liquids.
Market Restraints
- Raw alum supply concentration:Thai and Chinese mining operations control over 70% of cosmetic-grade potassium alum extraction, creating geographic vulnerability to export licensing changes.
- Efficacy perception gap:Consumer skepticism about sweat protection versus aluminum chlorohydrate antiperspirants limits trial conversion in humid climate markets.
- Input cost volatility:Energy-intensive alum refining processes expose margins to electricity price spikes in Southeast Asian manufacturing zones.
Strategic Opportunities
- Men's grooming underpenetration:Male deodorant users in France and Italy remain underindexed for natural crystal adoption compared to female-skewed clean beauty segments.
- EU Green Deal alignment:CSRD reporting requirements on packaging waste are incentivizing corporate procurement of refillable mineral formats for employee wellness programs.
- Direct-to-subscription models:Crystal stone replenishment cycles align with subscription box economics, bypassing slotting fee barriers in conventional mass retail.
Industry Challenges
- Natural claim standardization delays:Absence of harmonized definitions for mineral-derived versus synthetic-processed alum is creating litigation exposure across EU member state jurisdictions.
- Quality control skill scarcity:Analytical chemists capable of distinguishing cosmetic-grade from industrial-grade alum purity are concentrated in Bangkok and Guangzhou laboratory clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Deodorant Crystal Market |
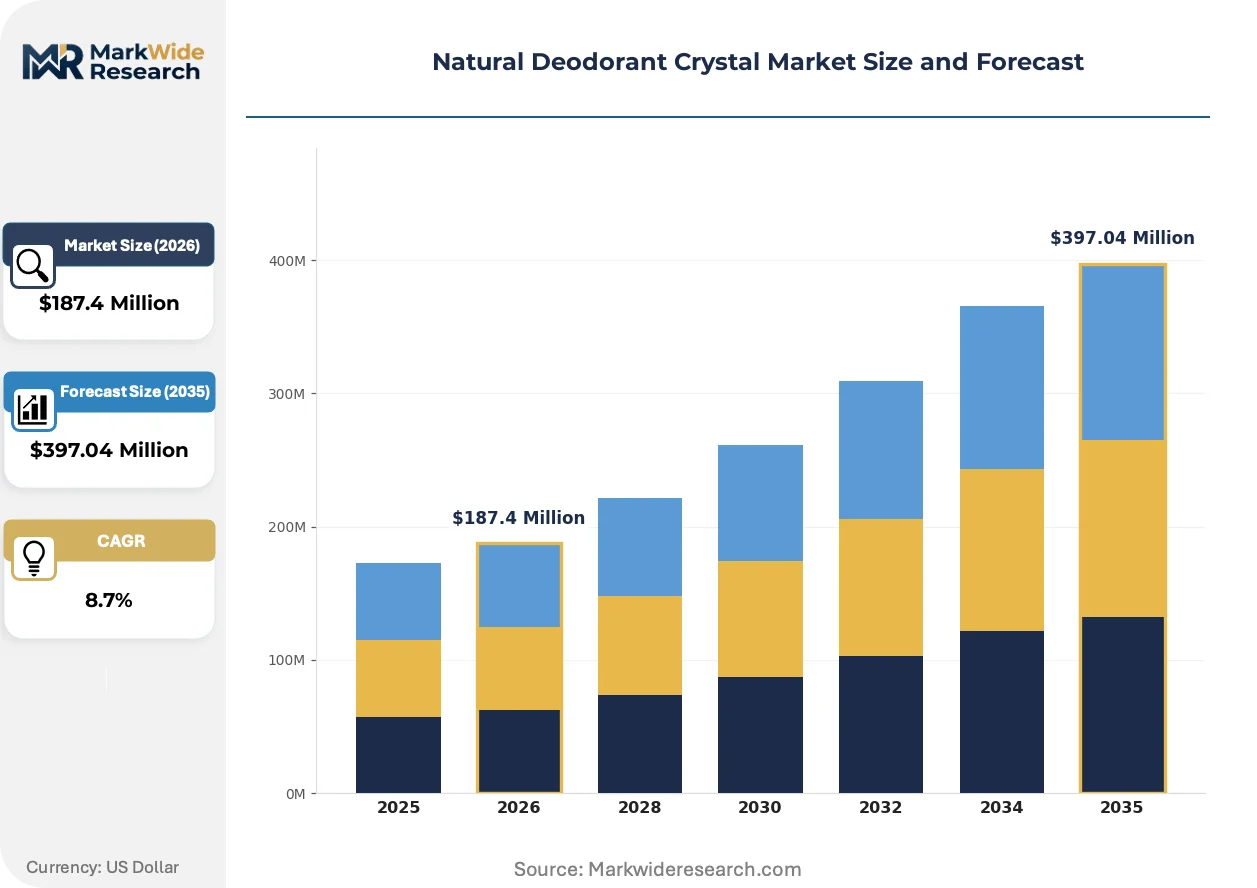
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pottassium Alum, Ammonium Alum, Potassium Magnesium Sulfate, Natural Mineral Stones Application: Personal Care, Sports & Recreation, Travel Essentials, Wellness Products, Organic Cosmetics End User: Women, Men, Teenagers, Fitness Enthusiasts, Eco-conscious Consumers Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Supermarkets, Direct Sales |
| Companies Covered | Thai Crystal Deodorant, Crystal Body Deodorant, Salt of the Earth, Lavilin, Naturally Fresh Deodorant Crystal, Deonat, PitRok, Alum Stone, Green Tidings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Deodorant Crystal Market Trends and Innovations
Formulation transparency and supply chain traceability are compressing competitive differentiation around mineral sourcing claims rather than functional performance metrics alone.
Blockchain-enabled provenance tracking is digitizing alum supply chain documentation from Thai mining operations through to finished goods labeling. Premium-positioned brands are adopting QR-linked extraction site verification to substantiate ethical sourcing claims. This technology is digitizing what had been paper-based chain-of-custody records, compressing audit timelines from months to real-time validation.
EU F-Gas Regulation phase-down schedules are indirectly pressuring cosmetic manufacturing energy profiles, accelerating adoption of solar-powered alum refining in Southeast Asian production facilities. German importers now require renewable energy certificates for contract manufacturing agreements. Crystal deodorant brands sourcing from Thai operations with captive solar arrays are securing preferential shelf placement in DM-drogerie markt and Rossmann chains.
Athleisure-inspired reapplication rituals are fragmenting deodorant usage occasions beyond morning application. Gym bag-sized crystal formats are displacing standard 120g household sizes in urban convenience retail. This behavioral shift concentrates in London, Berlin, and Amsterdam where boutique fitness membership density exceeds 25% of working-age populations.
Natural Deodorant Crystal Market Segmentation
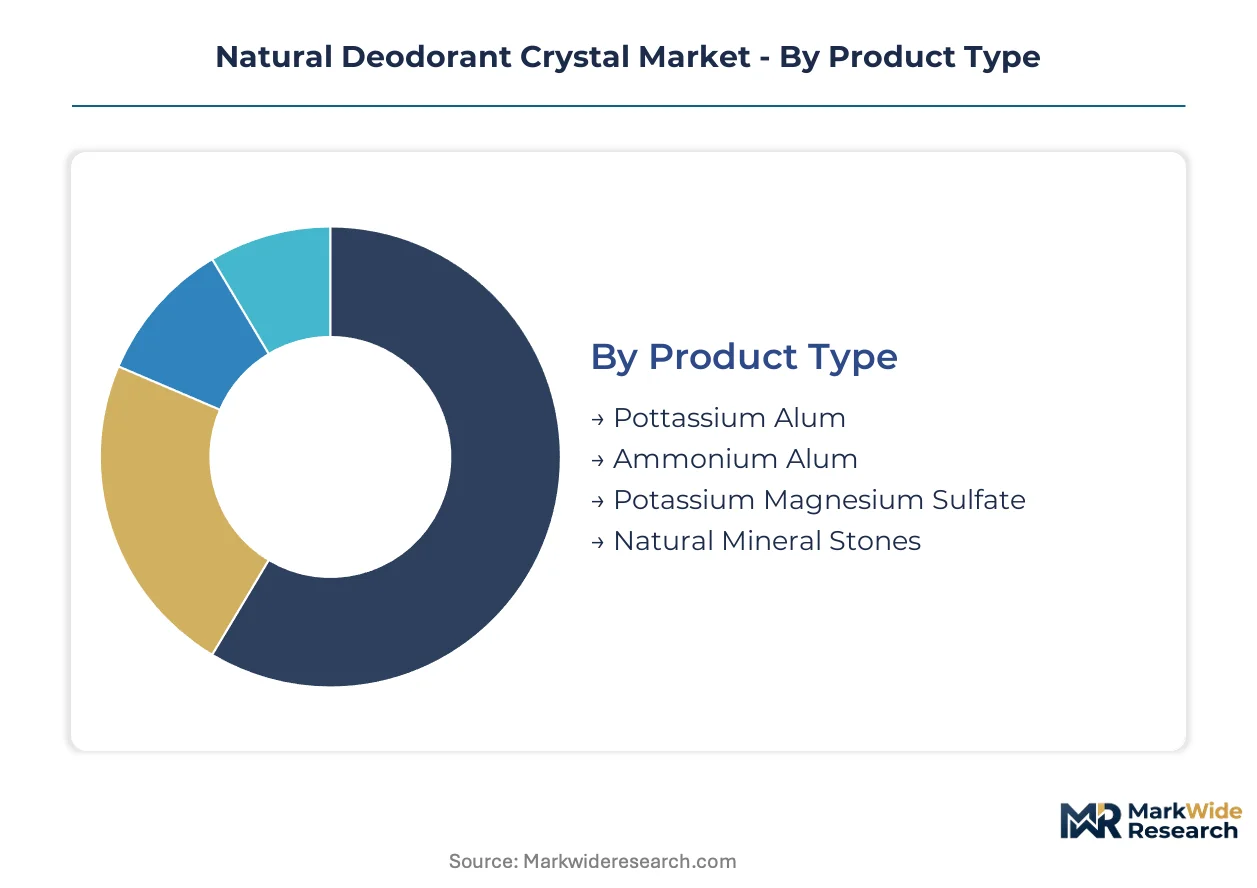
Segmentation in the natural deodorant crystal market exposes divergent margin structures across product chemistry, usage occasion, and channel economics. Understanding these splits reveals where formulation investments concentrate versus where volume scales fastest.
Product Type:
Cost tier stratification separates commodity mineral salts from premium-positioned unprocessed formats, with purity grades and processing intensity determining margin capture.
- Potassium Alum:The dominant mineral salt formulation, refined from bauxite-derived alumina through sulfuric acid neutralization. Demand concentrates in Germany and France where pharmacy chains stock potassium alum sticks as REACH-compliant alternatives to synthetic antiperspirants, though Thai supply concentration creates procurement vulnerability.
- Natural Mineral Stones:Unprocessed crystal chunks requiring zero synthetic binders or extrusion energy. The steepest expansion runs through UK and Scandinavian zero-waste retail where unprocessed stones command premium pricing through packaging elimination.
- Ammonium Alum:Alternative salt chemistry with higher water solubility, produced primarily in Chinese refining facilities for cost-sensitive export markets.
- Potassium Magnesium Sulfate:Niche double-salt formulation targeting sensitive-skin positioning in Japanese and South Korean cosmetic channels.
Potassium Alum commands the established base. The steepest expansion runs through Natural Mineral Stones.
Application:
Usage occasion fragmentation is splitting the market between daily hygiene rituals and situational reapplication needs, with fitness-adjacent occasions expanding fastest.
- Personal Care:Morning hygiene staple applications in bathroom vanity contexts, dominated by stick and roll-on formats. Volume concentrates in German DM-drogerie markt and Rossmann mass retail where pharmacist endorsement drives trial conversion.
- Sports & Recreation:Gym-bag portable formats sized for mid-workout reapplication. Demand clusters in London, Berlin, and Amsterdam where boutique fitness membership density exceeds 25% of working-age populations and non-staining crystal properties matter.
- Travel Essentials:TSA-compliant solid formats eliminating liquid restrictions, popular in airport convenience retail and subscription box curation.
- Wellness Products:Spa and holistic health channel positioning through ayurvedic and crystal healing retail networks.
- Organic Cosmetics:Certified clean beauty integration requiring COSMOS or ECOCERT validation for shelf placement in Sephora and Douglas premium doors.
Personal Care commands the established base. Sports & Recreation is climbing the fastest.
End User:
Customer type maturity varies sharply by gender and lifestyle affiliation, with male adoption lagging female clean beauty conversion.
- Women:Primary adopters through clean beauty and organic cosmetics channels, with concentrated purchasing in specialty retail and pharmacy environments.
- Fitness Enthusiasts:Behaviorally distinct segment normalizing multiple daily applications, receptive to portable formats and subscription replenishment models.
- Eco-conscious Consumers:Zero-waste motivated buyers prioritizing unprocessed stones and refillable packaging, concentrated in Scandinavian and UK urban centers.
- Men:Underpenetrated relative to female adoption, with French and Italian male deodorant users showing particular resistance to natural crystal trial.
- Teenagers:Parental purchase influence segment, sensitive to skin-irritation concerns and social media-driven clean ingredient awareness.
Women command the established base. Fitness Enthusiasts are gaining share fastest.
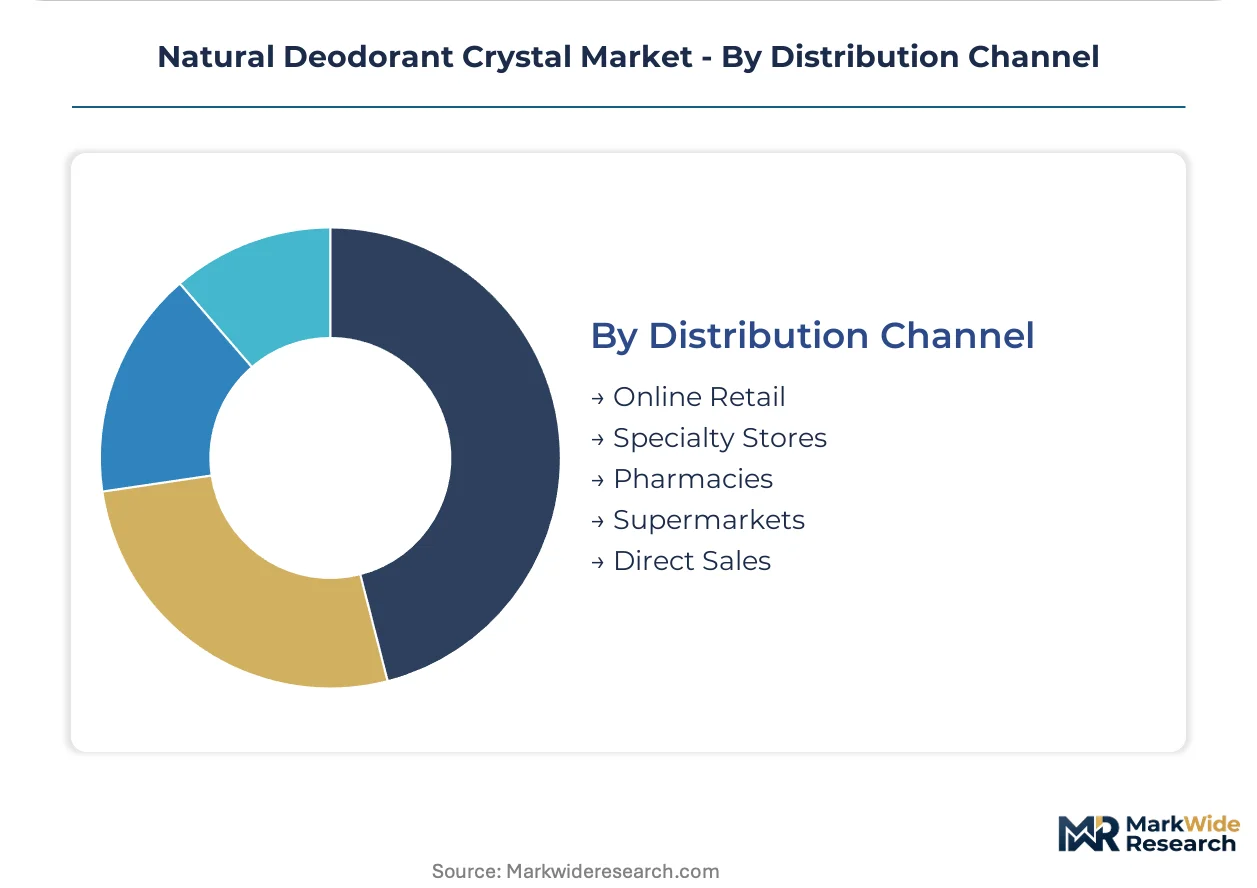
Distribution Channel:
Channel economics favor direct relationships where slotting fees and retail margin stacking compress profitability in conventional mass retail.
- Online Retail:DTC subscription models and Amazon marketplace presence, enabling replenishment cycle alignment and review-driven trial conversion without shelf-space competition.
- Specialty Stores:Zero-waste shops and clean beauty boutiques in UK and German cities, offering educational staff interaction for efficacy-skeptical first-time buyers.
- Pharmacies:German and French apothecary networks where trained staff recommend alum-based products as first-line natural alternatives, creating trusted endorsement.
- Supermarkets:Mass retail placement in DM-drogerie markt and similar chains, requiring renewable energy certificates from suppliers for contract manufacturing agreements.
- Direct Sales:Multi-level marketing and wellness practitioner networks, particularly active in ayurvedic and holistic health communities.
Pharmacies command the established base. Online Retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai mining operations export raw potassium alum to German pharmaceutical distributors and UK zero-waste retailers, creating a trade corridor that channels Southeast Asian mineral supply into European clean beauty demand.
Germany
Pharmacist endorsement of alum-based products drives concentrated adoption in DM-drogerie markt and Rossmann chains. ECHA's REACH restrictions on synthetic aluminum chlorohydrate position alum stones as first-line natural alternatives. Berlin and Hamburg anchor distribution infrastructure for pharmacy and specialty retail channels.
United Kingdom
Zero-waste retail expansion in London and Manchester prioritizes unprocessed mineral stones over packaged formats. The country's CSRD reporting requirements on packaging waste incentivize corporate procurement of refillable formats. Edinburgh and Glasgow cluster independent clean beauty boutiques with educational staff interaction.
France
Male deodorant users in Paris and Lyon show particular resistance to natural crystal trial compared to female-skewed adoption. ANSM cosmetic regulation enforces strict natural claim substantiation, creating compliance barriers for imported products. Marseille and Nice concentrate spa-channel distribution through ayurvedic retail networks.
Thailand
Bangkok-based manufacturing controls raw alum supply from regional mining operations for export to European and North American buyers. The country's national mining regulator oversees cosmetic-grade extraction licensing. Chiang Mai and Phuket host refining facilities with captive solar arrays securing preferential contract manufacturing agreements.
United States
FDA oversight of antiperspirant-drug claims creates compliance bifurcation that shapes product labeling strategies for cosmetic-positioned deodorants. California and New York cluster clean beauty specialty retail and direct-to-consumer subscription operations. Portland and Austin anchor zero-waste store expansion with unprocessed stone formats.
Natural Deodorant Crystal Market Competitive Landscape
On the supply side, the industry is fragmented across mineral extractors, contract refiners, and brand owners with limited vertical integration. Thai and Chinese mining operations control upstream alum supply while European and North American entities dominate downstream formulation and distribution. Three archetypes prevail: mining-integrated manufacturers, brand-focused marketers, and private-label suppliers. Capacity expansion in Southeast Asian solar-powered refining and strategic partnerships for blockchain provenance tracking represent dominant competitive moves.
Within the mining-integrated tier, Thai Crystal Deodorant leverages its Bangkok manufacturing base to control raw supply from regional mines. Crystal Body Deodorant anchors North American shelf presence through pharmacy and natural grocery distribution channels. Salt of the Earth occupies a position exemplifying B Corp certification and refillable packaging differentiation. These three entities represent distinct strategic postures: upstream supply control, established retail anchoring, and sustainability credentialing.
| Leading Market Players |
|---|
| Thai Crystal Deodorant |
| Crystal Body Deodorant |
| Salt of the Earth |
| Lavilin |
| Naturally Fresh Deodorant Crystal |
| Deonat |
| PitRok |
| Alum Stone |
| Green Tidings |
| Others |
Pricing and Supply Chain Analysis
Bangkok-to-Hamburg container freight corridors carry raw potassium alum from Thai mining operations to German pharmaceutical distributors, with freight cost volatility compressing margins for unprocessed mineral stone formats while amplifying price differentiation between solar-certified and conventional refining tiers.
Pricing Analysis
Current-generation potassium alum sticks command premium positioning against prior-generation ammonium alum imports and next-generation blockchain-verified mineral stones. Three-tier pricing structure across premium unprocessed stones, standard potassium alum sticks, and economy ammonium alum formats separates buyers by certification grade and renewable energy sourcing. Price differentiation hinges on ECOCERT validation and solar-powered refining credentials from Thai captive arrays. Pricing pressure stems from electricity cost spikes in Southeast Asian manufacturing zones. Eco-conscious consumers in Scandinavian zero-waste channels show lowest price sensitivity, while cost-sensitive export markets in Southern Europe exhibit highest elasticity.
Supply Chain Analysis
Extended payment terms from German pharmacy chains and DM-drogerie markt supply-chain finance facilities are restructuring working capital requirements for Bangkok-based refiners. Geographic supply concentration centers on Thailand, China, and Vietnam for cosmetic-grade potassium alum extraction. Raw material dependencies include bauxite-derived alumina, sulfuric acid for neutralization, and renewable energy certificates for contract eligibility. Single-source vulnerability to Thai export licensing changes creates structural risk exposure. Distribution runs through European pharmacy networks, UK zero-waste retail clusters, and North American direct-to-subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, where ECHA REACH compliance creates switching costs for brand owners locked into alum-based reformulation cycles.
For Market Incumbents: Build certification moats by securing COSMOS and ECOCERT validation ahead of EU natural claim standardization. Deepen backward integration into Thai solar-powered refining capacity to defend against energy cost volatility. Anchor pharmacy channel relationships through pharmacist training programs that reinforce first-line recommendation status against synthetic antiperspirant recovery.
For New Entrants and Emerging Players: French and Italian male deodorant segments offer underpenetrated white-space opportunity with half the adoption rate of female-skewed clean beauty channels. Target gym-bag portable formats for boutique fitness reapplication rituals in London and Berlin where membership density exceeds twenty-five percent of working-age populations. Pursue direct-to-subscription models bypassing slotting fee barriers in conventional mass retail.
For Investors and Strategic Acquirers: Mining-integrated brand owners with captive Thai supply and European pharmacy anchoring represent the most defensible acquisition archetype. Long-term viability rests on regulatory tailwinds persisting through EU Green Deal implementation and CSRD packaging waste reporting expansion. Monitor ECHA guidance on natural claim definitions as the critical inflection signal for litigation exposure and compliance cost restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Integration | QR-linked Thai extraction site verification substantiates ethical sourcing claims for DM-drogerie markt placement. |
| Solar-Powered Refining Expansion | Captive photovoltaic arrays in Chiang Mai secure renewable energy certificates required by German importers. |
| Men's Grooming Line Extension | Paris and Lyon male segments resist natural crystal trial, creating first-mover positioning opportunity. |
| Zero-Waste Format Introduction | Unprocessed mineral stones eliminate synthetic binders entirely for UK and Scandinavian retail channels. |
| Direct-to-Subscription Launch | Replenishment cycle alignment bypasses slotting fees and captures fitness enthusiast reapplication demand. |
Research Methodology
Cross-validation between primary interviews with Thai refinery operations managers, German pharmacy category buyers, UK zero-waste retail founders, and ECHA regulatory affairs specialists anchors the qualitative findings against secondary validation from REACH compliance databases, EU customs trade records, and SEC filings from listed personal care distributors. Bottom-up volume modeling from alum extraction licensing data triangulates against top-down market sizing from pharmacy and specialty retail channel audits.
Calibration against historical potassium alum trade flows and renewable energy certificate issuance patterns shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include mineral chemistry tier, application occasion, end-user lifestyle affiliation, and distribution channel economics. CAGRs derive from regression analysis of adoption curves in REACH-affected markets versus baseline geographies. Industry-specific forecast inputs incorporate boutique fitness membership density correlations and pharmacist endorsement conversion rates.
Practitioners should monitor ECHA natural claim guidance evolution, Thai export licensing policy shifts, and solar energy cost trajectories for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Herbal Beauty Products Market
Beauty & Personal Care
Vanity Mirror Market
Beauty & Personal Care
Anti-Acne Facial Serum Market
Beauty & Personal Care
Hair Removal Spray Market
Beauty & Personal Care
Nail Lamps Market
Beauty & Personal Care
Lip Care Market
Beauty & Personal Care
Europe Cosmetics Market
Beauty & Personal Care
Spray Tanning Market
Beauty & Personal Care
Brazil Sustainable Personal Care Market
Beauty & Personal Care
Hair Wig Market
Beauty & Personal Care
Bangladesh Shampoo Market
Beauty & Personal Care
Anti-Acne Cosmetics Market
Beauty & Personal Care
Hair and Nail Accessories Market
Beauty & Personal Care
Asia-Pacific Perms and Relaxants Market
Beauty & Personal Care
Kids Shampoo Market
Beauty & Personal Care
China Eyelash Serum Market