
 Emea Beauty Devices Market | 2026-2036
Emea Beauty Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Emea Beauty Devices Market Foresight
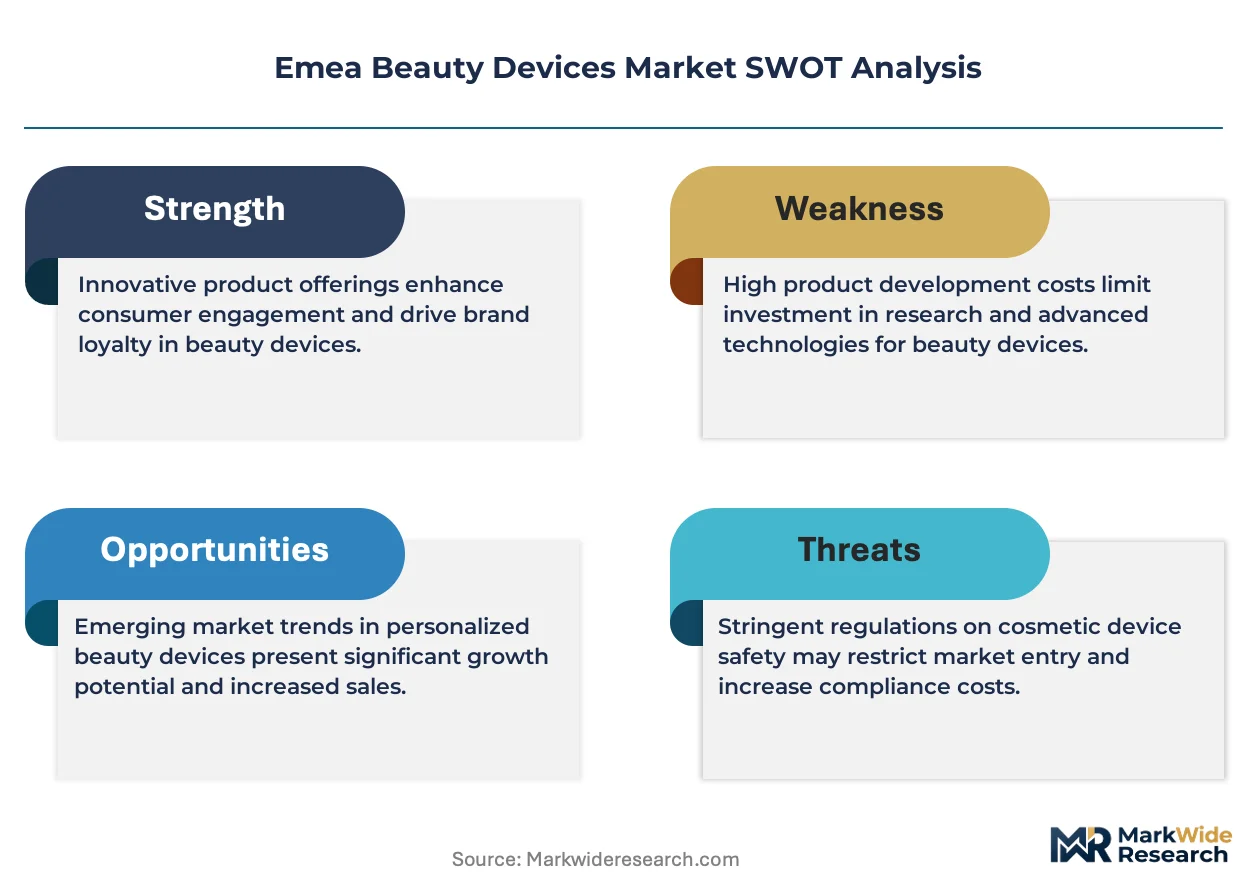
Multi-modal energy delivery is fragmenting the Emea beauty devices technology stack as manufacturers blend laser, radiofrequency, and LED into single platforms. L'Oréal Group leverages its dermatological research infrastructure to anchor premium device development in Paris and Milan. Koninklijke Philips N.V. competes through manufacturing scale across Eindhoven and Vienna production hubs. FOREO specializes in silicone-form factor facial cleansers, occupying a distinct mass-market tier with direct-to-consumer channel control.
Emea beauty devices encompass electrically powered instruments designed for non-invasive or minimally invasive cosmetic treatment of skin and hair, typically operating at wavelengths between 400 nm and 1064 nm or frequencies from 1 MHz to 40 MHz depending on modality. These devices serve commercial purposes across consumer home-use, professional salon, and clinical dermatology settings, with efficacy claims tied to collagen remodeling, melanin targeting, or follicular thermal damage. Hair removal devices and anti-aging devices represent the largest installed base segments, with hair removal systems sustaining mature replacement cycles in Mediterranean markets and anti-aging devices capturing expanding margin pools in Nordic premium channels. LED technology segments are growing fastest among energy-based categories, though radiofrequency retains higher average selling prices in dermatology clinic procurement.
The EU MDR and CE marking framework govern pre-market authorization and post-market surveillance for beauty devices claiming therapeutic effect across all EMEA member states. ECHA REACH restrictions on nickel and cobalt alloys in device housings shape material selection for handheld instrument manufacturers. Germany's BfArM and France's ANSM maintain national vigilance databases that track adverse events from laser and intense pulsed light systems. Stakeholders must monitor divergence between EU harmonized standards and emerging national digital health regulations in the Gulf states as Middle East distribution channels deepen.
Market Dynamics
EU MDR compliance deadlines are compressing go-to-market timelines for laser and radiofrequency equipment manufacturers, forcing portfolio rationalization across dermatology device suppliers. This regulatory pressure is concentrating procurement among CE-marked incumbents while marginalizing smaller players lacking notified body relationships.
Growth Catalysts
- EU MDR transition:Stricter pre-market conformity requirements for therapeutic claims are elevating barriers that favor established manufacturers with robust quality management systems and clinical evidence portfolios.
- Germany's medical-aesthetic channel:Premium salon chains and dermatology clinics in Munich and Hamburg are driving uptake of ultrasound-based skin rejuvenation systems through bundled service offerings.
- LED wavelength optimization:Advances in narrow-band photon delivery at 415 nm and 633 nm are expanding treatable indications beyond acne to include post-inflammatory hyperpigmentation and dermal repair.
Market Restraints
- ECHA REACH material restrictions:Nickel and cobalt alloy limitations in device housings are forcing redesign cycles for handheld instrument manufacturers, elevating unit costs and extending validation timelines.
- Notified body capacity:Concentration of EU MDR certification services among a shrinking pool of designated bodies is creating bottlenecks that delay market entry for novel energy-based platforms.
- Radiofrequency device substitution:Lower-cost microcurrent and electroporation alternatives are capturing price-sensitive segments in Mediterranean home-use markets, compressing margin pools for thermal modalities.
Strategic Opportunities
- Nordic premium channel expansion:Sweden and Denmark present underpenetrated demand for multi-modal platforms combining fractional laser with cooling-assisted radiofrequency in high-margin clinic settings.
- AI-integrated treatment planning:Convergence of machine vision with energy delivery parameters is enabling personalized dosage algorithms that differentiate professional-grade systems from consumer alternatives.
- Gulf state digital health alignment:Divergence between EU harmonized standards and emerging national regulations in Saudi Arabia and UAE creates first-mover advantage for manufacturers investing in dual-certification strategies.
Industry Challenges
- Clinical operator training deficits:Safe deployment of multi-energy platforms requires cross-functional expertise in laser physics and dermal anatomy that outpaces current vocational education output in Southern Europe.
- CE marking timeline compression:Extended clinical evaluation periods under MDR Article 61 are forcing capital-intensive evidence generation that strains mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emea Beauty Devices Market |
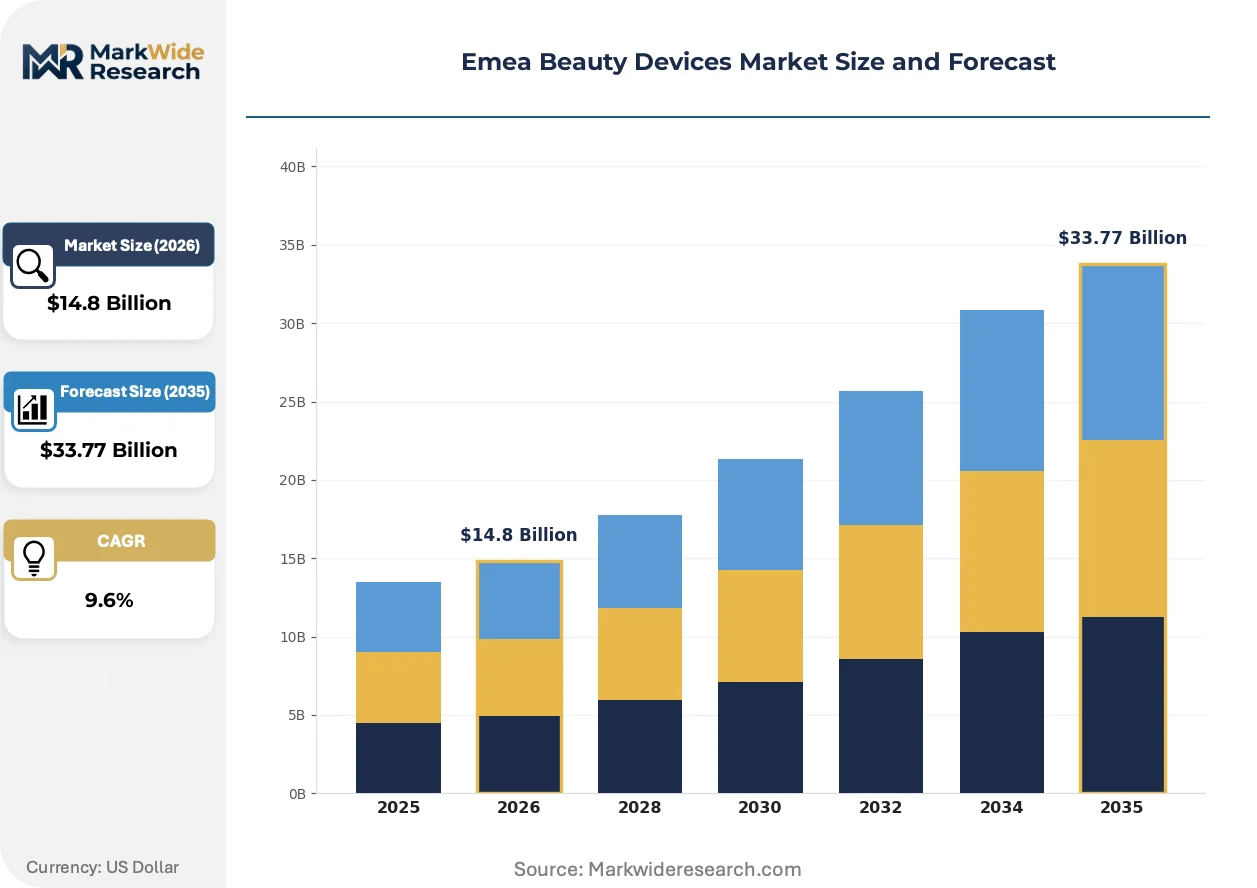
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $33.77 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Facial Cleanser, Hair Removal Device, Anti-Aging Device, Skin Rejuvenation Device Technology: Ultrasound, Laser, Radiofrequency, LED End User: Consumers, Salons, Dermatology Clinics, Spa Centers Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Department Stores |
| Companies Covered | Koninklijke Philips N.V., L’Oréal Group, Nu Skin Enterprises Inc., FOREO, Tria Beauty Inc., Termosalud, Tech4Beauty, Beurer GmbH, NuFACE, Others |
| Regions Covered | EMEA: Germany, UK, France, Saudi Arabia, UAE, South Africa, Russia, Italy, Rest of EMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emea Beauty Devices Market Shifts & Advancements
Digital twin architectures are virtualizing device calibration protocols and treatment simulation workflows across EMEA dermatology practices. This shift compresses training cycles while elevating outcome predictability for energy-based procedures.
Fractional laser systems with integrated cooling arrays are virtualizing the thermal management layer that previously required separate hardware modules. German dermatology clinics in Berlin and Düsseldorf are adopting these consolidated platforms to reduce footprint and streamline sterilization protocols. The technology is virtualizing capital allocation decisions by collapsing multiple single-modality purchases into single procurement events.
France's ANSM and Germany's BfArM are tightening adverse event reporting requirements for intense pulsed light systems through enhanced vigilance database integration. Device manufacturers must now submit real-world performance data quarterly rather than annually. Salon chains operating across the Benelux region are responding by consolidating supplier relationships toward vendors with established pharmacovigilance infrastructure.
Subscription-based device access is displacing outright purchase models among independent aesthetic practitioners in Spain and Italy. Equipment financiers are partnering with manufacturers to bundle consumables, maintenance, and software updates into per-treatment fees. This model is most visible in Barcelona and Milan where practitioner liquidity constraints intersect with high patient throughput expectations.
Emea Beauty Devices Market Segmentation
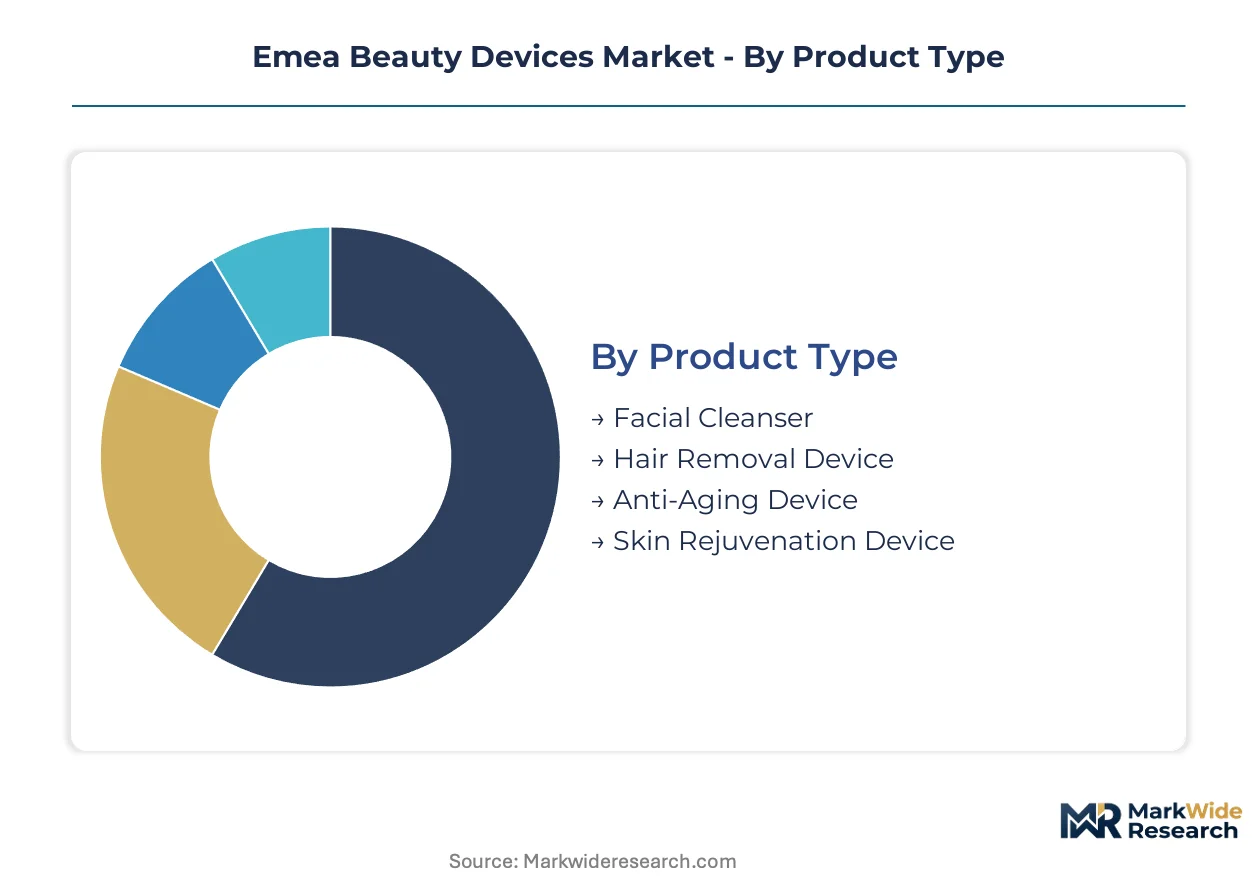
Segmentation reveals distinct margin architectures across EMEA beauty devices. Technology modality and end-user channel determine regulatory pathway complexity, while distribution strategy shapes working capital requirements and brand positioning latitude.
Product Type:
Application focus distinguishes device portfolios across consumer and professional tiers, with clinical efficacy claims driving material selection and certification intensity.
- Anti-Aging Device:Systems deploy radiofrequency and fractional laser modalities to stimulate collagen remodeling in dermal layers. Demand concentrates in German dermatology clinics and Nordic premium salon chains where bundled service packages justify capital outlay. EU MDR clinical evidence requirements favor established manufacturers with robust quality management systems.
- Hair Removal Device:Intense pulsed light and diode laser platforms target melanin in follicular structures across varying skin phototypes. Mediterranean markets sustain mature replacement cycles through consumer home-use adoption in Spain and Italy, though professional-grade systems retain pricing power in French medical-aesthetic practices.
- Facial Cleanser:Silicone-form factor sonic devices dominate mass-market penetration with direct-to-consumer channel control.
- Skin Rejuvenation Device:Multi-modal platforms combining ultrasound with LED wavelengths address post-inflammatory hyperpigmentation and textural irregularities.
Hair removal devices command the established base. The steepest expansion runs through anti-aging devices.
Technology:
Energy delivery mechanism determines regulatory classification, average selling price, and operator training requirements across EMEA jurisdictions.
- LED:Narrow-band photon delivery at 415 nm and 633 nm wavelengths addresses acne vulgaris and dermal repair with minimal thermal risk. French and German salon chains are expanding LED-only treatment menus to capture price-sensitive segments while avoiding laser operator certification requirements.
- Radiofrequency:Thermal energy delivery at 1-40 MHz frequencies achieves collagen contraction and neocollagenesis through controlled dermal heating. Dermatology clinics in Munich and Hamburg prioritize RF platforms for their superior margin profiles and established reimbursement pathways in Germany's medical-aesthetic channel.
- Laser:Coherent light emission across 400-1064 nm wavelengths enables precise melanin and hemoglobin targeting with adjustable pulse durations.
- Ultrasound:Microfocused and high-intensity focused ultrasound systems penetrate to SMAS layers for non-surgical lifting indications.
Radiofrequency commands the established base. LED is climbing the fastest through salon channel expansion.
End User:
Customer type dictates device specification, service bundling strategy, and post-sale support intensity across the value chain.
- Dermatology Clinics:Medical-grade platforms require CE marking under EU MDR with clinical evidence portfolios supporting therapeutic claims. German BfArM and French ANSM vigilance databases track adverse events, concentrating procurement toward vendors with established pharmacovigilance infrastructure.
- Consumers:Home-use devices operate at reduced energy densities with simplified user interfaces and enhanced safety interlocks. Mediterranean markets show particular price sensitivity, with Spanish and Italian consumers gravitating toward subscription-based access models that bundle consumables and software updates.
- Salons:Professional non-medical settings demand rapid treatment cycles and minimal operator training overhead.
- Spa Centers:Wellness-oriented environments prioritize sensory experience and multi-protocol flexibility over clinical outcomes.
Dermatology clinics command the established base. Consumer segments are gaining share fastest through direct-to-consumer channel maturation.
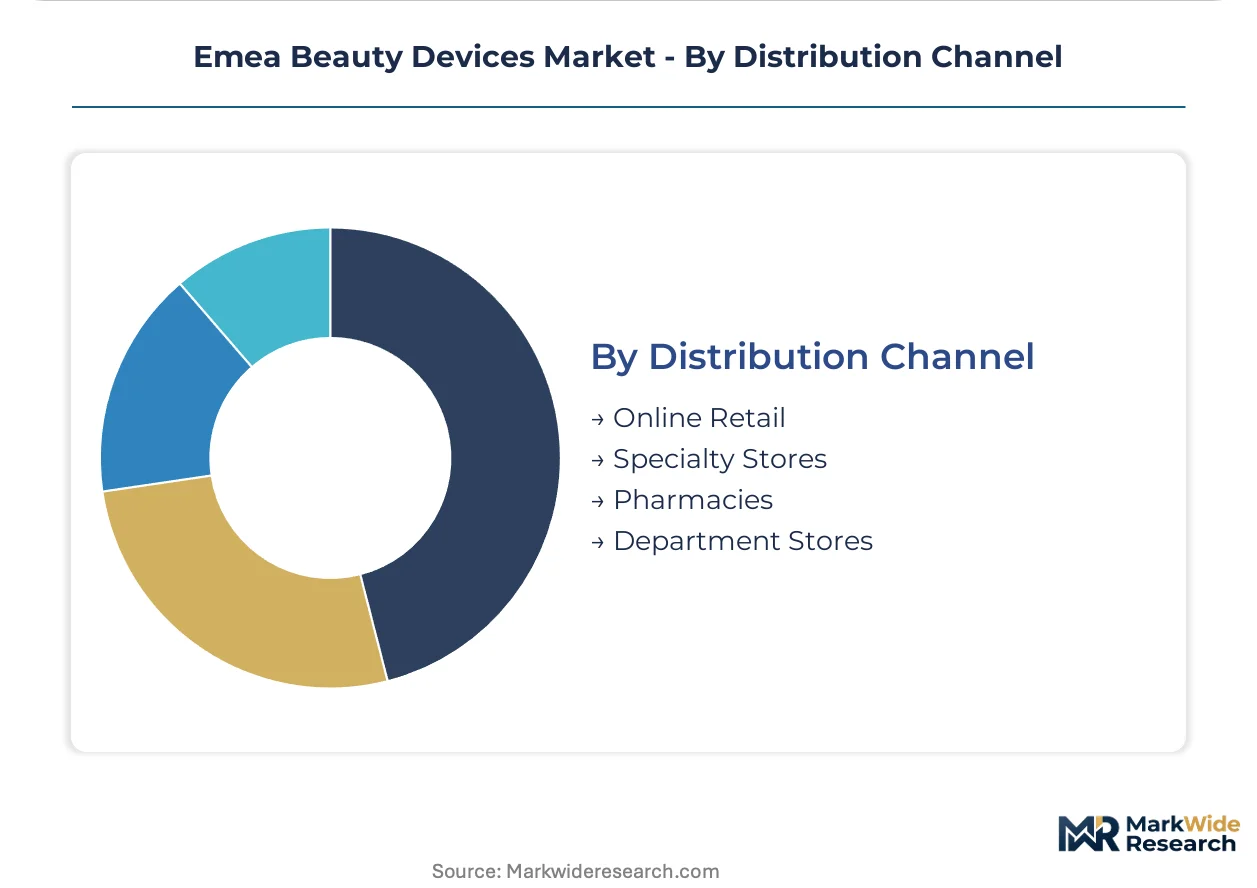
Distribution Channel:
Channel selection shapes margin retention, customer acquisition cost, and brand control across mass-market and premium tiers.
- Online Retail:Direct-to-consumer platforms enable margin capture and first-party data accumulation for algorithmic personalization. FOREO and comparable specialists leverage proprietary storefronts to bypass wholesale markups while maintaining pricing discipline across EMEA markets.
- Specialty Stores:Curated retail environments provide tactile evaluation and trained staff consultation for high-consideration purchases. Premium salon chains in Milan and Barcelona source professional-grade inventory through authorized distributors with certified technician training programs.
- Pharmacies:Regulated retail settings confer clinical credibility for devices with quasi-medical positioning.
- Department Stores:Flagship retail presence supports brand elevation and gift-market penetration.
Specialty stores command the established base. Online retail is expanding most quickly through platform logistics maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export ultrasound-based skin rejuvenation systems to dermatology clinics across the Nordics and Gulf states, establishing a trade corridor that channels premium device production toward high-margin medical-aesthetic markets.
Germany
Medical-aesthetic practices in Munich and Hamburg drive uptake of multi-modal platforms combining fractional laser with radiofrequency. BfArM maintains the national vigilance database tracking adverse events from intense pulsed light systems. Berlin and Düsseldorf dermatology clinics are consolidating supplier relationships toward vendors with established pharmacovigilance infrastructure.
France
Paris anchors premium device development through dermatological research infrastructure, while salon chains in Lyon and Marseille expand LED-only treatment menus. ANSM tightened quarterly adverse event reporting requirements for laser systems beyond annual submissions. The Île-de-France cluster concentrates CE-marked incumbents benefiting from robust quality management systems.
United Kingdom
London-based premium salon chains source professional-grade inventory through authorized distributors with certified technician training programs. The Medicines and Healthcare products Regulatory Agency enforces EU MDR-aligned conformity assessment for therapeutic claims. Manchester and Birmingham clinics are adopting subscription-based device access models bundling consumables and maintenance.
Italy
Milan practitioners drive subscription-based equipment financing bundling software updates into per-treatment fees. The Italian Ministry of Health oversees CE marking recognition under EU MDR transition timelines. Barcelona-to-Milan distribution corridors channel mass-market silicone-form factor devices toward Mediterranean price-sensitive segments.
United Arab Emirates
Dubai dermatology clinics present underpenetrated demand for cooling-assisted radiofrequency platforms in high-margin settings. MOHAP is developing digital health regulations that diverge from EU harmonized standards, creating dual-certification requirements. Abu Dhabi medical-aesthetic practices are consolidating procurement toward manufacturers investing in Gulf state regulatory alignment.
Emea Beauty Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tiers. The vendor base clusters around three archetypes: diversified beauty conglomerates leveraging dermatological research infrastructure, manufacturing-scale electronics specialists with production hub networks, and direct-to-consumer form-factor innovators. M&A activity concentrates portfolio rationalization among CE-marked incumbents, while strategic partnerships bundle equipment financing with consumables and maintenance services.
Among diversified beauty conglomerates, L'Oréal Group anchors premium device development through Paris and Milan research infrastructure. Koninklijke Philips N.V. occupies a position among manufacturing-scale specialists with production hub networks across Eindhoven and Vienna. FOREO exemplifies the direct-to-consumer archetype through proprietary storefront control and silicone-form factor specialization.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| L'Oréal Group |
| Nu Skin Enterprises Inc. |
| FOREO |
| Tria Beauty Inc. |
| Termosalud |
| Tech4Beauty |
| Beurer GmbH |
| NuFACE |
| Others |
Supply & Pricing Matrix
Overcapacity in Eindhoven and Vienna production hubs is compressing supplier margins while elevating procurement leverage for dermatology clinic chains and premium salon operators across Germany and France. This utilization dynamic feeds into pricing posture as manufacturers absorb ECHA REACH compliance costs to defend volume commitments against lower-cost microcurrent alternatives.
Pricing Analysis
Next-generation multi-modal platforms command substantial premiums over prior-generation single-energy systems and legacy diode laser units. Three-tier pricing structure across premium, standard, and economy levels stratifies by EU MDR certification grade and bundled after-sales service intensity. Pricing pressure stems from radiofrequency substitution by microcurrent alternatives in Mediterranean home-use markets. Consumers in Spain and Italy exhibit highest price sensitivity, while German dermatology clinics demonstrate lowest sensitivity due to established reimbursement pathways.
Supply Chain Analysis
Contract manufacturing concentration rests with Philips-scale electronics specialists operating Eindhoven and Vienna hubs alongside specialized EMS providers serving silicone-form factor innovators. Component sourcing draws from Germany for precision optics, China for LED arrays, and Switzerland for medical-grade sensors. Single-source vulnerability concentrates in EU MDR-notified body relationships. Distribution runs through authorized specialty distributors with certified technician training programs for professional tiers, while direct-to-consumer platforms capture mass-market volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance deadlines are compressing competitive timelines and elevating capital requirements, creating a high-growth disruption window for CE-marked incumbents with established clinical evidence portfolios.
For Market Incumbents: Pre-empt portfolio rationalization by consolidating notified body relationships before capacity bottlenecks intensify, and anchor backward integration into precision optics manufacturing to defend margin pools against microcurrent substitution in Mediterranean markets. For New Entrants and Emerging Players: Establish a beachhead in Nordic premium salon chains where cooling-assisted radiofrequency platforms remain underpenetrated, and leverage subscription-based equipment financing to bypass capital constraints among independent aesthetic practitioners in Barcelona and Milan. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer form-factor specialists with proprietary channel control and consumable bundling; long-term viability favors acquisition targets with established pharmacovigilance infrastructure and Gulf state regulatory alignment capabilities. Monitor quarterly adverse event reporting compliance as the signal for portfolio quality differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | CE marking under tightened Article 61 requirements elevates barriers for laser and radiofrequency platforms. |
| Multi-Modal Platform Launch | Integration of fractional laser with cooling-assisted radiofrequency consolidates procurement decisions in German clinics. |
| Direct-to-Consumer Channel Expansion | Proprietary storefronts enable margin capture and algorithmic personalization for silicone-form factor devices. |
| Gulf State Regulatory Alignment | Dual-certification strategies with MOHAP create first-mover advantage in Dubai and Abu Dhabi medical-aesthetic markets. |
| Subscription-Based Equipment Financing | Per-treatment fee models bundle consumables and software updates to address practitioner liquidity constraints in Southern Europe. |
Research Methodology
Initial hypotheses were tested against primary input from dermatology clinic operators, biomedical engineers, salon chain procurement directors, and notified body auditors and refined through secondary validation against EMA MDR guidance documents, BfArM vigilance database extracts, ANSM adverse event reports, and customs trade records for beauty device imports. Bottom-up installation base modeling and top-down market sizing triangulated volume estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation by technology modality, end-user channel, and distribution format. CAGRs were derived from installed base replacement cycles and premium channel expansion trajectories. Forecast inputs incorporated EU MDR transition timelines and ECHA REACH material restriction implementation phases.
Stress conditions across notified body capacity constraints, nickel alloy price volatility, and Gulf state regulatory divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding MDR compliance pacing and salon channel digitization. Quarterly review of BfArM and ANSM vigilance database trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Global Massage Oil Market
Beauty & Personal Care
Anti Stretch Mark Products Market
Beauty & Personal Care
Global Cosmetics Market
Beauty & Personal Care
Spain Dermocosmetics Market
Beauty & Personal Care
Beauty and Wellness Products Market
Beauty & Personal Care
Global Bath Bomb Market
Beauty & Personal Care
Home Use Anti-Aging Beauty Device Market
Beauty & Personal Care
South Korea Dermocosmetics Market
Beauty & Personal Care
Sunless Tanners Market
Beauty & Personal Care
Herbal Beauty Products Market
Beauty & Personal Care
China Eyelash Serum Market
Beauty & Personal Care
Brazil Beauty and Personal Care Products Market
Beauty & Personal Care
US Personal Care Products Market
Beauty & Personal Care
Middle East and Africa Hair Styling Products Market
Beauty & Personal Care
Facial Epilator Market
Beauty & Personal Care
Vanity Mirror Market