
 Bay Leaf Market | 2026-2036
Bay Leaf Market Size, Share, and Industry Trends Forecast 2026-2036
Bay Leaf Market Analysis
The gap between premium organic whole leaves and commodity-grade crushed material is consolidating into two distinct supply chains with diverging price floors and buyer expectations. McCormick & Company, Inc. leverages its retail distribution depth to anchor the branded spice shelf in North American supermarkets. Badia Spices competes on volume scale across Latin American and Caribbean ethnic grocery channels. Mountain Rose Herbs specializes in certified organic, whole-leaf formats targeting wellness-oriented direct-to-consumer buyers.
Bay leaf comprises the dried or fresh foliage of Laurus nobilis, an evergreen shrub native to the Mediterranean basin, typically harvested at 8–12 cm mature leaf length and air-dried to below 10% moisture for stable essential oil retention; its primary commercial purpose centers on slow-release aromatic flavoring in braised dishes, stocks, and preserved foods. Whole leaves retain the strongest essential oil concentration and command the highest per-kilogram margins within the product type dimension, while ground formats serve industrial food manufacturers seeking homogeneous batch dispersion. Within the application dimension, culinary use remains the mature revenue base, though medicinal and aromatherapy segments are attracting new supplier investment as functional botanicals gain traction in dietary supplements.
USDA organic certification and FDA food facility registration govern market access for imports entering the United States, while the EU's EFSA maximum residue limits and REACH chemical safety documentation shape compliance costs for Mediterranean exporters shipping into European food manufacturers. Turkey's national agricultural ministry and India's Spices Board both enforce export quality grading that directly determines lot eligibility for premium wholesale contracts. Stakeholders must monitor evolving organic equivalency agreements between major producing nations and destination markets, as these bilateral frameworks increasingly determine which suppliers retain tariff-advantaged access.
Market Dynamics
The bifurcation of organic whole-leaf supply chains from commodity crushed material is compressing middle-tier processors and forcing procurement teams to choose between traceability premiums and volume efficiency.
Growth Catalysts
- Clean-label mandates:North American food manufacturers under FDA facility registration requirements are reformulating with single-ingredient botanicals, pulling certified organic whole leaves into braised-sauce and stock applications.
- EU organic equivalency expansion:Bilateral recognition agreements between Turkey's national agricultural ministry and EFSA-aligned importers are reducing tariff friction for Aegean-region cooperatives.
- Sun-dried processing:Traditional air-drying below 10% moisture in Turkey's coastal zones preserves essential oil concentration that mechanical dehydration degrades, creating measurable quality premiums.
Market Restraints
- Input cost volatility:Labor-intensive hand-harvesting of mature 8–12 cm leaves faces seasonal wage pressure in Turkey's Aegean region, compressing margins for smallholder cooperatives.
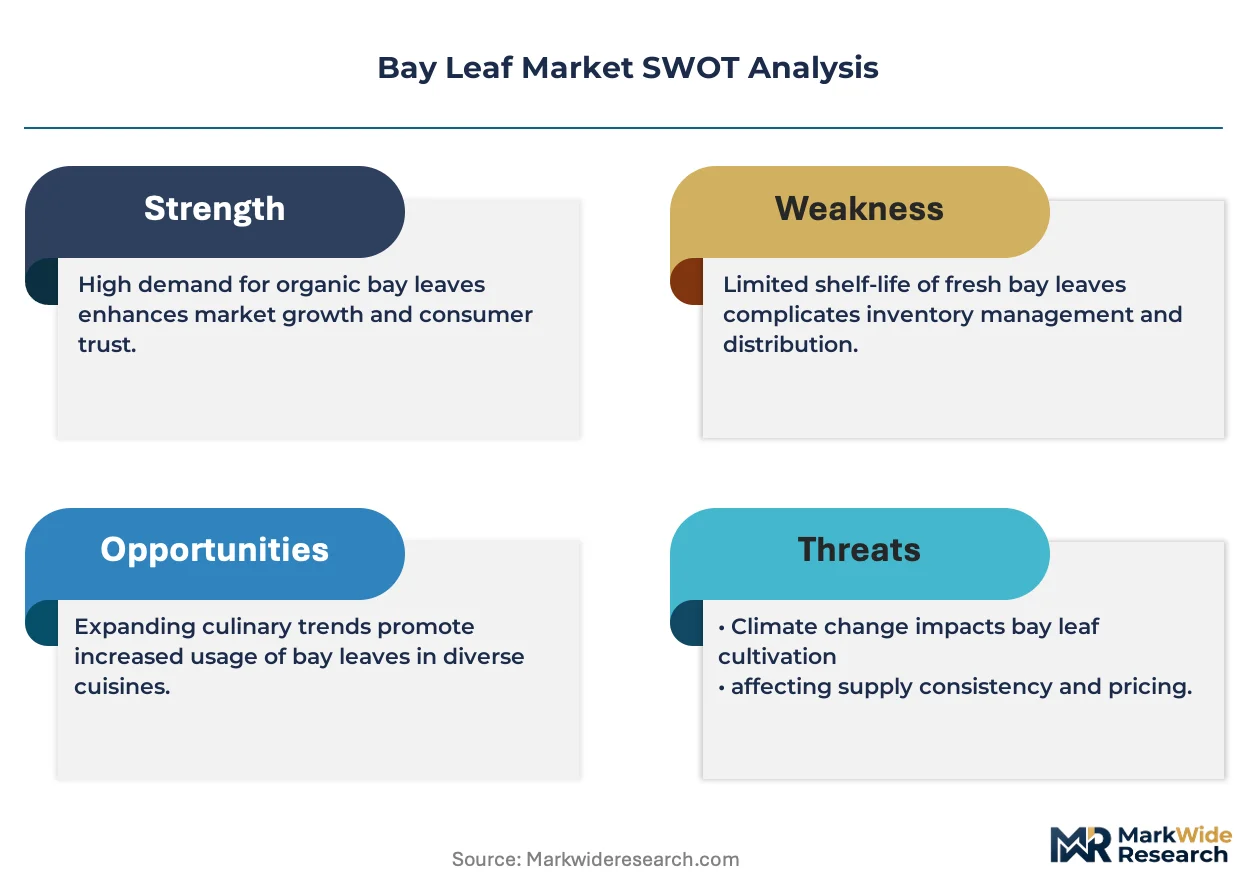
- Supply concentration risk:Premium-grade organic production clusters in Turkey's coastal provinces, exposing buyers to climate disruption and geopolitical friction in a single-source geography.
- Regulatory friction:REACH chemical safety documentation requirements for EU-bound shipments impose compliance costs that commodity-grade exporters cannot absorb, capping their market access.
Strategic Opportunities
- Underpenetrated wellness channels:Direct-to-consumer botanical retailers in Germany and France are building subscription models around certified organic whole-leaf formats for aromatherapy and dietary supplement applications.
- Functional ingredient pivot:Dietary supplement manufacturers are extracting bay leaf compounds for metabolic health positioning, creating demand for pharmaceutical-grade raw material specifications.
- Distribution innovation:Ethnic grocery consolidation across Latin American and Caribbean markets is opening shelf-space negotiations for branded whole-leaf formats previously confined to bulk spice trade.
Industry Challenges
- Certification timeline compression:USDA organic and EU organic equivalency audits require 18–36 month conversion periods for conventional orchards, stranding transitional inventory without premium pricing.
- Skill scarcity in quality grading:India's Spices Board export standards and Turkey's national grading protocols demand trained sensory evaluators that cooperatives struggle to retain against food-manufacturer recruitment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bay Leaf Market |
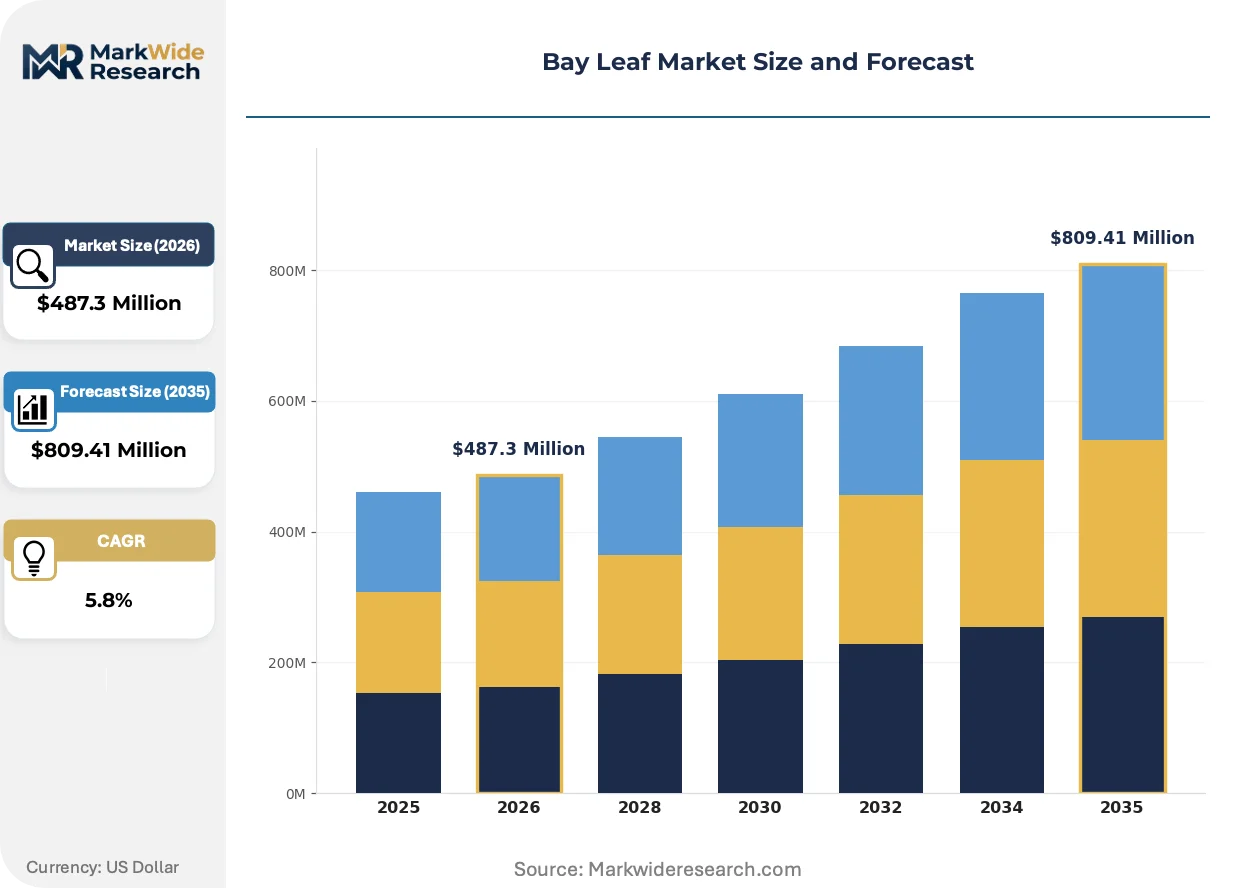
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Leaves, Crushed, Ground, Fresh End User: Households, Restaurants, Food Manufacturers, Exporters Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Application: Culinary, Medicinal, Cosmetic, Aromatherapy |
| Companies Covered | Badia Spices, Anatoli Spices, McCormick & Company, Inc., Pacific Spice Company, Inc., Gourmet Foods Inc., Spice World USA, Frontier Natural Products Co-op, Mountain Rose Herbs, Alpina Organic Bay Leaf Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bay Leaf Market Emerging Trajectories
Processing technology and procurement platforms are actively compressing the distance between Aegean-region harvest and North American formulation labs.
Near-infrared spectroscopy for essential oil validation is rewriting quality assurance protocols. Third-party certifiers in Turkey are deploying portable NIR units at cooperative collection points, enabling real-time cineole content verification before lot consolidation. This compresses rejection rates and accelerates payment cycles for smallholders.
EFSA's updated maximum residue limits for dried botanicals are tightening testing protocols. Exporters to European food manufacturers must now document multi-pesticide screens that previously applied only to fresh produce. Mediterranean suppliers are responding by segregating organic and conventional handling infrastructure to prevent cross-contamination.
Buyer concentration among North American clean-label formulators is shortening contract cycles. Food manufacturers that once committed to annual spice procurement are moving to quarterly reviews tied to batch-specific certificates of analysis. This behavioral shift is most visible in California and Pacific Northwest formulation hubs where R&D teams prioritize ingredient traceability for ESG disclosure requirements.
Bay Leaf Market Segmentation
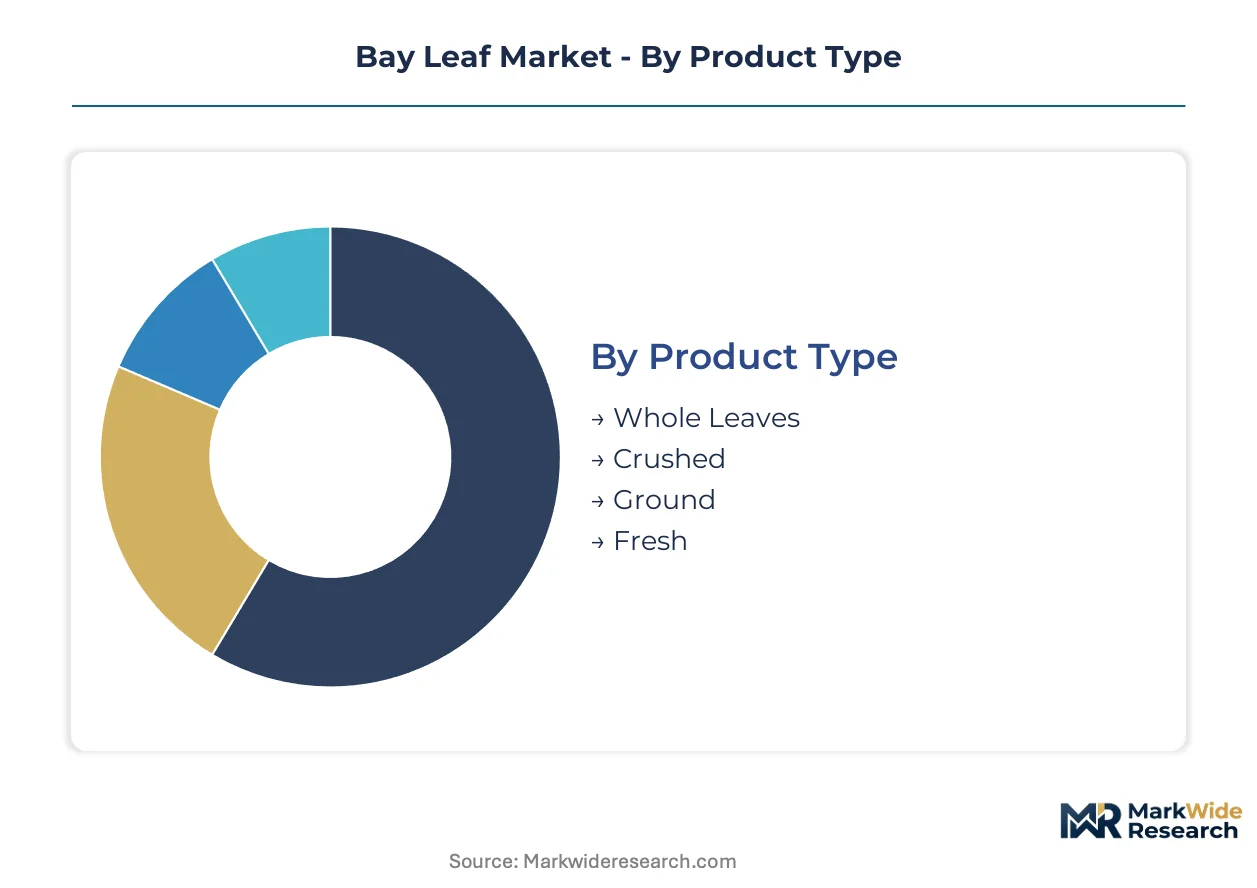
Bay leaf procurement patterns diverge sharply across format, buyer type, and sales channel. Each segmentation axis reveals distinct margin structures and compliance burdens that reshape supplier strategy.
Product Type:
Capital intensity concentrates in processing infrastructure for ground and crushed formats, while whole-leaf operations demand lighter equipment but heavier certification investment.
- Whole Leaves:Mature foliage at 8–12 cm length retains maximum essential oil concentration. Demand concentrates in North American clean-label formulation labs where McCormick and Mountain Rose Herbs specify organic-certified lots for braised-sauce applications. EFSA residue limits and USDA organic audits govern lot eligibility.
- Ground:Mechanical milling to homogeneous particle size serves industrial food manufacturers seeking batch dispersion consistency. Turkey's Aegean-region cooperatives face compressed margins as REACH documentation costs absorbable only by scaled processors.
- Crushed:Intermediate fragmentation targets ethnic grocery channels and mid-tier restaurant supply.
- Fresh:Refrigerated logistics limit geographic reach to proximate Mediterranean markets.
Most installed capacity flows through Ground. Expansion is steepest in Whole Leaves.
End User:
Buyer sophistication determines specification stringency and contract cycle length across household, commercial, and industrial channels.
- Food Manufacturers:FDA-registered facilities under clean-label mandates specify organic whole leaves with batch-specific certificates of analysis. Quarterly contract reviews tied to ESG disclosure requirements compress traditional annual procurement cycles in California and Pacific Northwest formulation hubs.
- Households:Direct-to-consumer subscription models in Germany and France build recurring revenue around certified organic formats for wellness applications.
- Restaurants:Ethnic grocery consolidation across Latin American and Caribbean markets opens branded shelf-space negotiations.
- Exporters:India's Spices Board and Turkey's national agricultural ministry grading protocols determine lot eligibility for premium wholesale contracts.
Volume concentrates with Food Manufacturers. Margin expansion is fastest in Households.
Distribution Channel:
Channel selection locks in traceability depth and working capital requirements for suppliers.
- Online Retail:Wellness-oriented platforms enable direct-to-consumer botanical sales with subscription mechanics. Germany and France lead channel development for aromatherapy and dietary supplement applications.
- Supermarkets:McCormick leverages retail distribution depth to anchor branded spice shelves across North American mass-market outlets.
- Specialty Stores:Ethnic grocery channels in Latin American and Caribbean markets stock whole-leaf formats previously confined to bulk trade.
- Wholesale:Consolidated procurement by industrial food manufacturers demands segregated organic handling infrastructure to prevent cross-contamination.
Revenue weight sits with Wholesale. Digital penetration is climbing fastest in Online Retail.
Application:
Functional positioning beyond traditional culinary use is attracting pharmaceutical-grade raw material investment.
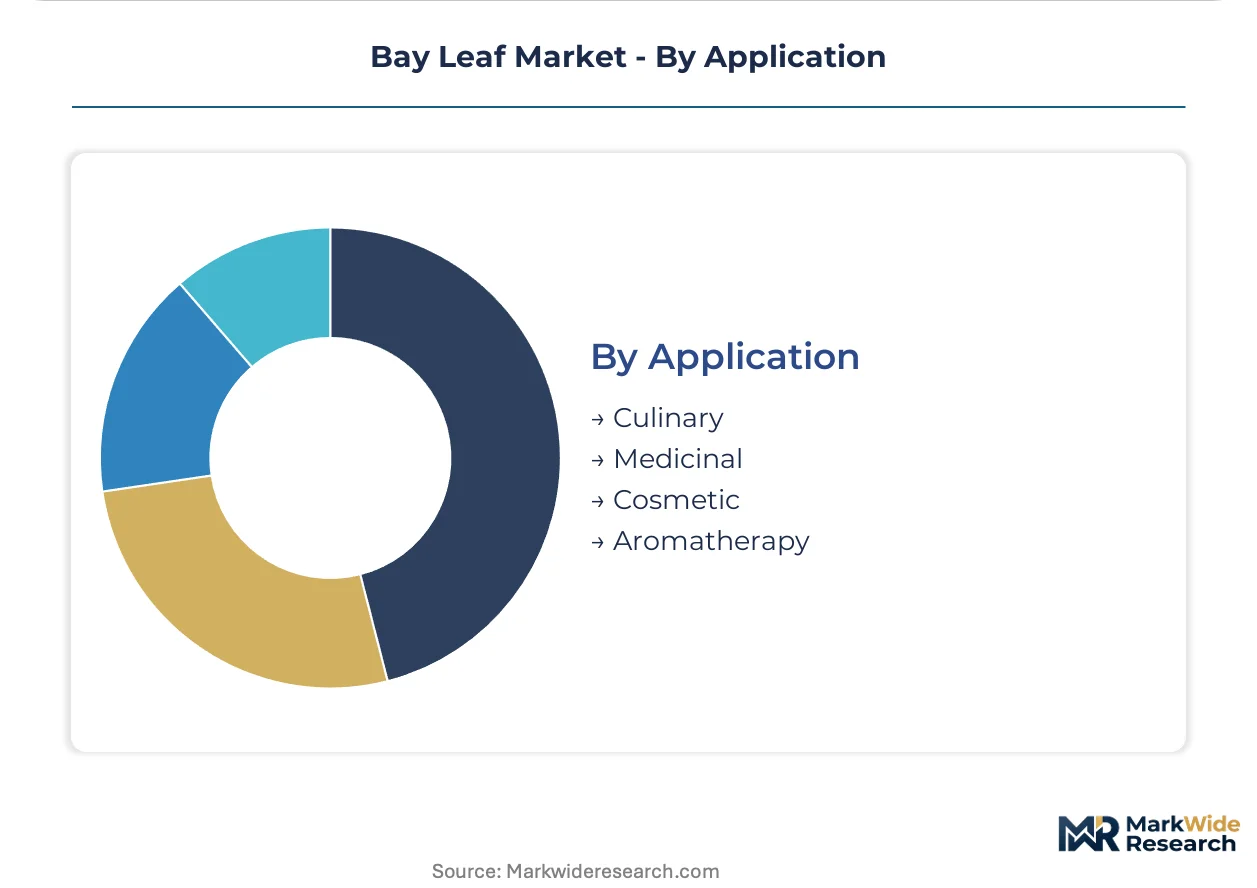
- Culinary:Slow-release aromatic flavoring in braised dishes, stocks, and preserved foods remains the mature revenue base. Turkey's sun-dried coastal production preserves essential oil concentration that mechanical dehydration degrades.
- Medicinal:Dietary supplement manufacturers extract bay leaf compounds for metabolic health positioning, creating demand for pharmaceutical-grade specifications.
- Aromatherapy:Direct-to-consumer botanical retailers build subscription models around certified organic whole-leaf formats.
- Cosmetic:Essential oil derivatives target personal care formulations with antimicrobial positioning.
Established volume flows through Culinary. New supplier investment is concentrating in Medicinal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkish agricultural cooperatives in the Aegean region anchor the skilled workforce for sun-dried bay leaf processing, with smallholder expertise in hand-harvesting mature foliage at 8–12 cm length concentrated along coastal provinces.
Turkey
Clean-label procurement from North American food manufacturers drives Aegean-region export volumes. The national agricultural ministry enforces quality grading protocols that determine premium wholesale contract eligibility. Izmir and Aydın provinces host the densest concentration of organic-certified sun-drying operations, where cooperatives maintain traditional air-drying infrastructure below 10% moisture targets.
United States
FDA-registered formulation labs in California and the Pacific Northwest specify organic whole leaves for braised-sauce applications. USDA organic certification governs import eligibility for Mediterranean suppliers. Sacramento Valley distribution hubs consolidate procurement for retail chains, with quarterly contract reviews tied to ESG disclosure requirements compressing traditional annual cycles.
Germany
Direct-to-consumer botanical subscription models in Berlin and Hamburg drive certified organic whole-leaf demand for wellness applications. EFSA maximum residue limits under REACH framework tighten testing protocols for dried botanical imports. Bavarian natural products distributors are building recurring revenue platforms around aromatherapy-grade specifications.
India
Export-oriented grading facilities in Kerala and Karnataka serve industrial food manufacturers seeking ground-format batch dispersion. The Spices Board enforces export quality standards that determine lot eligibility for premium contracts. Kochi processing clusters are investing in segregated organic handling infrastructure to prevent cross-contamination with conventional material.
France
Ethnic grocery consolidation in Paris and Marseille opens shelf-space negotiations for branded whole-leaf formats. EU organic equivalency agreements with Turkish exporters reduce tariff friction for Aegean-region cooperatives. Provence-Alpes-Côte d'Azur retail networks are expanding procurement of Mediterranean-origin botanicals for culinary and cosmetic applications.
Bay Leaf Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the bay leaf supply chain. The market structure bifurcates between vertically integrated processors with captive drying infrastructure and specialized traders sourcing through cooperative networks. Three archetypes dominate: multinational spice houses with retail distribution depth, regional ethnic grocery suppliers with volume scale, and certified organic specialists with direct-to-consumer channels. Competitive moves concentrate on backward integration into Aegean-region sourcing and portfolio diversification into pharmaceutical-grade raw material specifications.
Within the multinational spice house tier, McCormick & Company, Inc. and Badia Spices occupy positions representing divergent geographic emphases—North American mass-market retail versus Latin American and Caribbean ethnic channels. Mountain Rose Herbs exemplifies the certified organic specialist archetype, anchoring wellness-oriented direct-to-consumer positioning. These three entities collectively illustrate how distribution channel selection locks in divergent traceability investments and margin structures across the competitive landscape.
| Leading Market Players |
|---|
| Badia Spices |
| Anatoli Spices |
| McCormick & Company, Inc. |
| Pacific Spice Company, Inc. |
| Gourmet Foods Inc. |
| Spice World USA |
| Frontier Natural Products Co-op |
| Mountain Rose Herbs |
| Alpina Organic Bay Leaf Company |
| Others |
Supply Flow & Price Mechanics
Family-owned cooperatives in Turkey's Aegean region anchor both supply discipline and pricing power through traditional sun-drying expertise that scaled processors cannot replicate. Their control over certified organic whole-leaf production creates natural price floors that commodity-grade exporters struggle to undercut.
Pricing Analysis
The unbundled service model dominates, with whole-leaf formats commanding premiums for traceability while ground products compete on volume. Three-tier pricing structure across premium organic, certified conventional, and commodity grades reflects certification investment and essential oil concentration. Price differentiation rests on USDA organic tier and EFSA residue compliance, with REACH documentation costs intensifying compression at the commodity end. Household direct-to-consumer channels show lowest price sensitivity; industrial food manufacturers exhibit highest sensitivity as quarterly contract reviews squeeze supplier margins.
Supply Chain Analysis
Reverse-logistics flows are minimal given bay leaf's stable shelf life, though quality rejections at cooperative collection points create informal redistribution into lower-grade channels. Supply concentrates in Turkey, India, and Greece, with raw material flows drawing from Aegean-region smallholder orchards, Kerala processing clusters, and Mediterranean drying cooperatives. Single-source vulnerability in Turkey's coastal provinces exposes buyers to climate disruption. Distribution runs through consolidated wholesale procurement for industrial manufacturers, with online retail gaining share in wellness segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bay leaf market compounds steadily as clean-label mandates in North American and European food manufacturing create durable demand pull for certified organic supply.
For Market Incumbents: Deploy backward integration into Aegean-region cooperative networks to secure captive supply of premium organic whole leaves. McCormick and Mountain Rose Herbs should expand segregated handling infrastructure to prevent cross-contamination risks that EFSA tightening could exploit. Capacity addition in Izmir and Aydın provinces reinforces position against commodity-grade entrants facing REACH compliance barriers. For New Entrants and Emerging Players: The gap between premium organic and economy commodity tiers opens white space in mid-market certified conventional whole leaves for ethnic grocery channels. Target Latin American and Caribbean consolidation plays where Badia Spices lacks branded whole-leaf presence. A subscription-based direct-to-consumer model in German and French wellness markets offers fastest penetration with lowest capital intensity. For Investors and Strategic Acquirers: Valuations sit cheapest among Aegean-region cooperatives with organic certification but limited distribution reach. Long-term viability frames around 5-10 year organic equivalency agreement stability between Turkey and EU importers. Watch for bilateral trade friction signals as early inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aegean Sourcing | Captive supply from Izmir cooperatives secures organic whole-leaf traceability for ESG disclosure. |
| Segregated Organic Handling Infrastructure | Prevents cross-contamination risks that EFSA maximum residue limit enforcement could disqualify. |
| Direct-to-Consumer Subscription Launch | Berlin and Hamburg wellness platforms build recurring revenue around aromatherapy-grade specifications. |
| Near-Infrared Spectroscopy Deployment | Portable NIR units at Turkish cooperative collection points compress rejection rates and accelerate payment cycles. |
| Pharmaceutical-Grade Raw Material Pivot | Dietary supplement extraction demand for metabolic health compounds opens higher-margin specifications. |
Methodological Framework
Multiple input streams — primary stakeholder interviews, customs and trade databases, regulatory filing reviews, and agricultural ministry export records — were reconciled to build demand and supply estimates. Conversations with Turkish cooperative managers, Indian Spices Board officials, North American food manufacturer procurement leads, and German botanical retailers informed qualitative assessments. Secondary validation drew from FDA food facility registrations, USDA organic certification databases, EFSA guidance documents, and REACH compliance filings. Bottom-up lot-level production estimates from Aegean-region provinces were triangulated against top-down import value flows into US and EU markets.
Data-stream reconciliation anchored the analytical framework across product type, end user, distribution channel, and application dimensions, with organic certification status as a cross-cutting qualifier. CAGRs were derived from segment-level growth trajectory modeling rather than single-point extrapolation. Forecast inputs included bilateral organic equivalency agreement stability, clean-label formulation penetration in North American food manufacturing, and sun-dried processing capacity expansion in Turkey's coastal zones.
Caveats apply where EFSA residue limit revisions, Turkish-EU trade friction, or climate disruption in Aegean production zones could materially shift the outlook. Practitioners should monitor bilateral organic equivalency negotiations, REACH enforcement intensity, and cooperative labor cost inflation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Sriracha Market
Spices and Seasonings
Turmeric Oleoresin Market
Spices and Seasonings
Europe Seasoning and Spices Market
Spices and Seasonings
Low Sodium Sea Salt Market
Spices and Seasonings
Pink Himalayan Salt Market
Spices and Seasonings
Asafoetida Market
Spices and Seasonings
Herbs and Spices Market
Spices and Seasonings
Organic Saffron Market
Spices and Seasonings
Carthamus Yellow Market
Spices and Seasonings
Onion Oil Market
Spices and Seasonings
Cinnamon Market
Spices and Seasonings
Organic Spice Market
Spices and Seasonings
North America Seasonings Market
Spices and Seasonings
Paprika Color Market
Spices and Seasonings
Oregano Seasoning Market
Spices and Seasonings
Himalayan Salt Market