
 Himalayan Salt Market | 2026-2036
Himalayan Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Himalayan Salt Market Outlook
Multi-source procurement toward vertically integrated mine-to-retail operations is rebalancing supply reliability across the Himalayan salt value chain. The Spice Lab leverages direct Pakistani sourcing relationships to sustain consistent pink salt grades for North American foodservice channels. San Francisco Salt Co competes through specialty bath and spa product lines that command premium positioning in wellness retail. Morton Salt, Inc anchors industrial-grade distribution scale while navigating consumer segment expansion into gourmet culinary positioning.
Himalayan salt comprises halite deposits formed from ancient evaporated seabeds in the Salt Range of Pakistan, with trace mineral content including iron, magnesium, and potassium that produces its characteristic pink coloration. Granulated salt dominates volume throughput in food processing and table-use applications, while block salt for cooking surfaces and salt lamps for ambient air quality applications occupy higher-margin specialty niches. Bath salt formulations targeting cosmetic and therapeutic end uses represent the fastest-expanding application segment as wellness consumers prioritize magnesium absorption claims and spa-at-home rituals.
Pakistan's mining safety regulators and the FDA's food-contact substance standards both shape export market access requirements for Himalayan salt processors. The EU's REACH framework and FSSAI import certification protocols in India impose heavy-metal testing and origin documentation burdens that favor suppliers with laboratory verification capabilities. Stakeholders must monitor evolving organic and fair-trade certification standards that increasingly determine retail placement authority in premium natural-product channels.
Market Dynamics
Traceability mandates from the EU's REACH framework and India's FSSAI are compressing supplier margins while rewarding processors with captive laboratory verification capabilities, fundamentally restructuring competitive advantage around compliance infrastructure rather than raw material access alone.
Growth Catalysts
- Wellness ritual expansion:Spa-at-home bathing practices in Germany and Japan are accelerating bath salt formulations as magnesium absorption claims gain traction among premium consumers.
- REACH chemical safety protocols:Heavy-metal testing requirements are filtering out uncertified competitors and consolidating shelf space for verified Pakistani-origin suppliers in European natural-product retail.
- Air quality consciousness:Himalayan salt lamps are displacing synthetic ionizers in United States urban households seeking ambient purification without electronic components.
Market Restraints
- Pakistani mining concentration:Over 90% of authentic Himalayan salt originates from the Salt Range, creating geopolitical and logistics vulnerability for downstream processors.
- Input cost volatility:Manual extraction labor costs in Punjab Province fluctuate with seasonal migration patterns and safety regulation enforcement cycles.
- Substitution threat:Dead Sea salt and Epsom salt competitors are matching magnesium-content marketing claims at lower price points in cosmetic applications.
Strategic Opportunities
- Direct-to-consumer channel expansion:Subscription box services in the United States are bypassing traditional wholesale markups for certified culinary-grade product.
- Fair-trade certification tailwind:Evolving ethical sourcing standards in German and Japanese premium retail are creating placement advantages for mine-to-retail operators with documented labor practices.
- Cooking surface innovation:Salt block grilling accessories are penetrating outdoor culinary segments previously dominated by cast iron and ceramic alternatives.
Industry Challenges
- Laboratory certification timelines:FSSAI food-grade labeling and FDA food-contact substance approvals require 12-18 month validation cycles that strain working capital for mid-scale importers.
- Traceability system integration:Blockchain and RFID origin-tracking technologies demand capital deployment that legacy salt traders lack technical capacity to implement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Himalayan Salt Market |
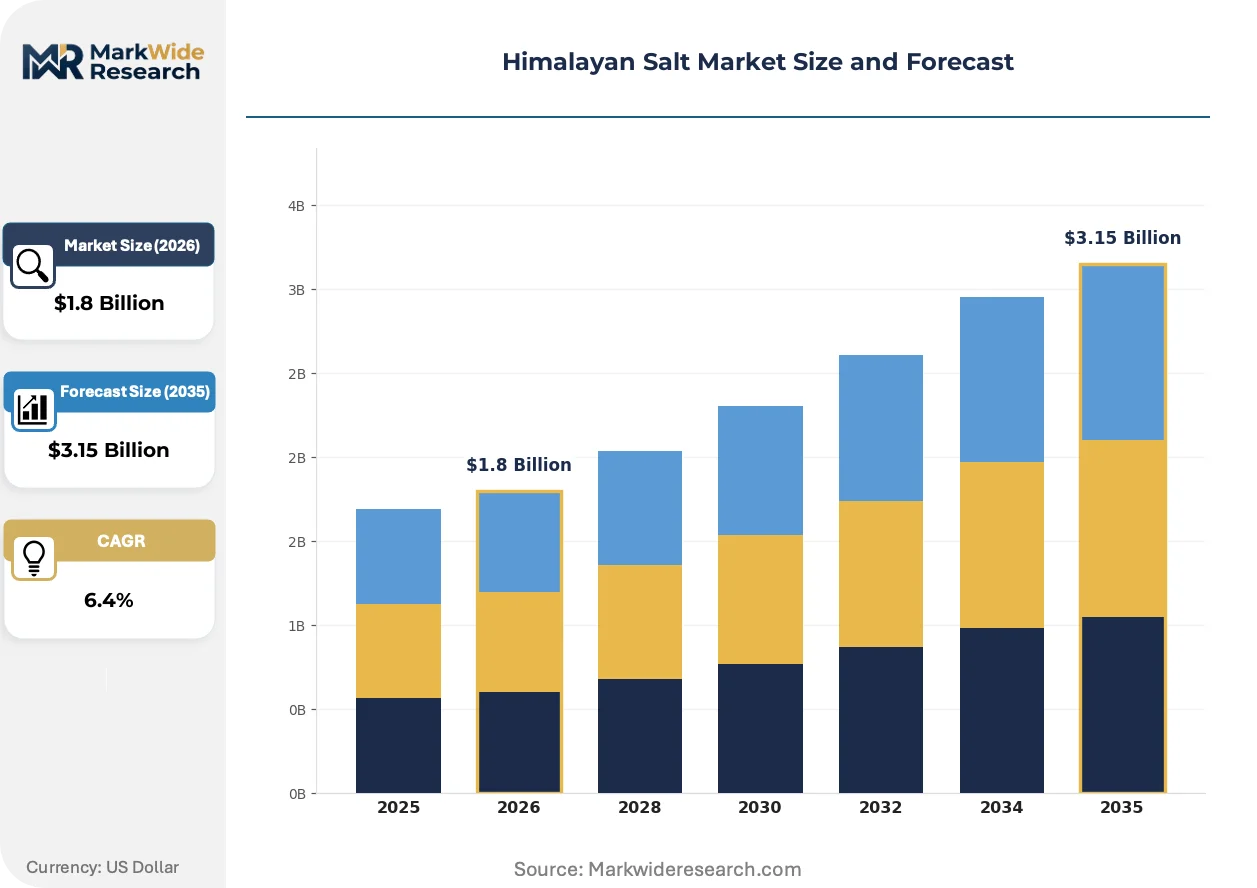
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granulated Salt, Block Salt, Salt Lamps, Bath Salt Application: Culinary, Industrial, Cosmetic, Nutritional End User: Restaurants, Retail, Health Stores, Households Distribution Channel: Online Retail, Supermarkets, Wholesalers, Specialty Stores |
| Companies Covered | The Spice Lab, Kutch Brine Chem Industries, San Francisco Salt Co, NutroActive Industries Pvt Ltd, Naturo Healthplus, Evolution Salt Co, Morton Salt, Inc, Saltan Ltd, Saltworks Technologies Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Himalayan Salt Market Strategic Shifts
Digital traceability infrastructure is converging with wellness marketing to reshape how Himalayan salt commands premium positioning, while regulatory fragmentation across import jurisdictions is forcing processors to build multi-standard compliance capabilities.
Near-infrared spectroscopy for mineral-content verification is converging with blockchain-based origin documentation to enable real-time authenticity confirmation. Premium retailers in Germany and Japan are adopting these dual-verification systems to defend margin positioning against commodity salt adulteration. This technology convergence is compressing the window for uncertified competitors to access shelf space in regulated channels.
The EU's REACH framework is tightening heavy-metal threshold requirements for cosmetic-grade salt imports, forcing Pakistani processors to invest in washing and laboratory infrastructure. Industrial consequence includes accelerated consolidation among exporters lacking capital for compliance upgrades. Bath salt formulations targeting therapeutic claims are most affected, with EU-bound shipments now requiring third-party arsenic and lead certification.
Certification-driven preference shifts are displacing price-based procurement in United States foodservice channels. Restaurant groups and meal-kit providers are now requiring FSSAI-equivalent documentation even for domestic distribution, replacing spot-market purchasing with contracted verified supply. This behavioral change is most visible in California and New York metropolitan clusters where liability-conscious operators dominate premium positioning.
Himalayan Salt Market Segmentation
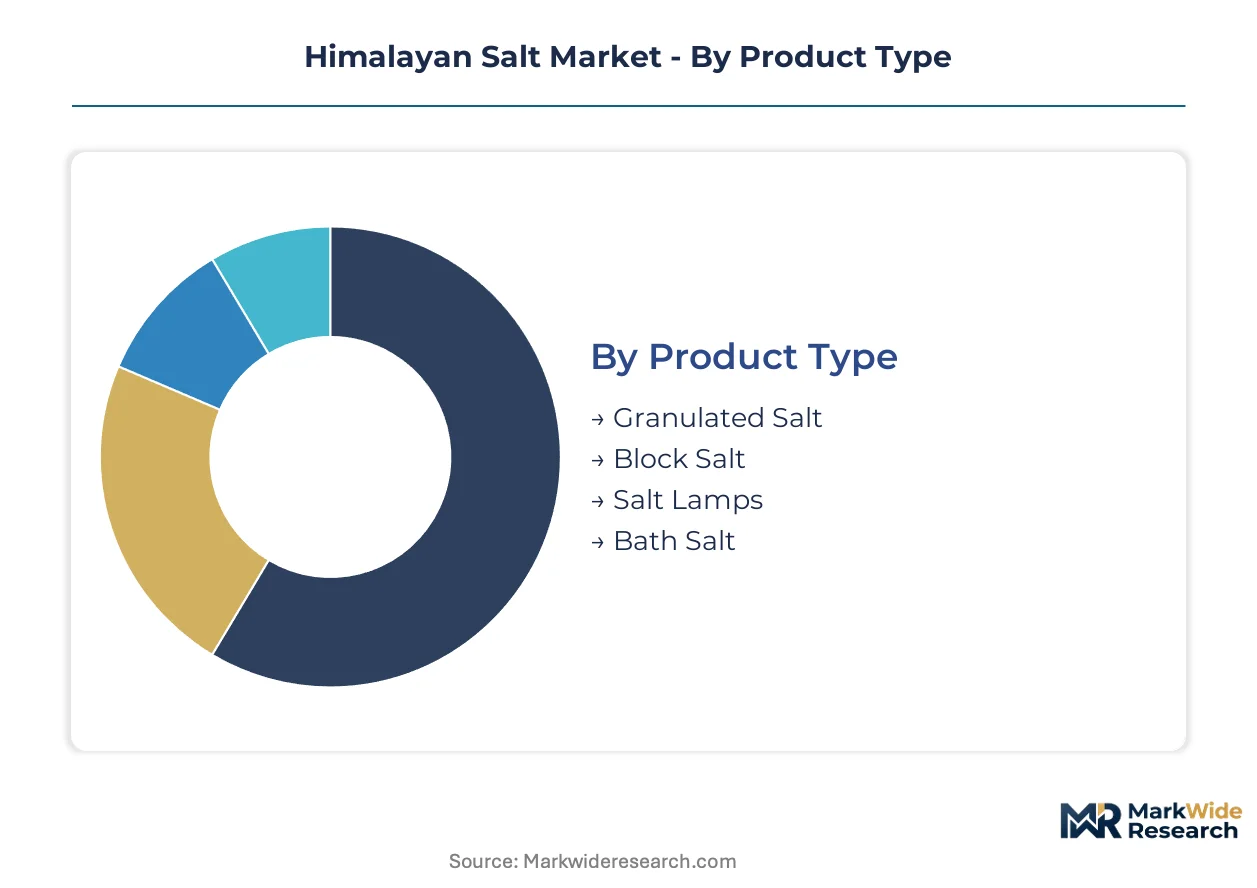
Himalayan salt processors configure production lines around mineral grade and crystalline structure, with capital deployment varying sharply across extraction, finishing, and certification stages. Segmentation discipline separates commodity throughput from premium positioning opportunities.
Product Type:
Granulated salt demands the heaviest capital commitment due to automated milling, sieving, and packaging infrastructure required for food-grade certification compliance.
- Granulated Salt:Fine-to-coarse crystalline particles processed for direct consumption and food manufacturing. Restaurants and meal-kit providers in the United States now mandate FSSAI-equivalent documentation even for domestic sourcing, replacing spot-market purchasing with contracted verified supply.
- Bath Salt:Coarse crystals and dissolvable formulations targeting magnesium absorption claims and spa-at-home rituals. German and Japanese wellness consumers are accelerating demand as therapeutic bathing practices displace synthetic alternatives.
- Block Salt:Solid slabs for cooking surfaces and serving presentations requiring minimal processing beyond cutting and surface finishing.
- Salt Lamps:Hollowed rock formations with internal lighting for ambient air quality applications, competing with electronic ionizers in urban United States households.
Granulated salt absorbs the bulk of installed capacity; bath salt is expanding most quickly.
Application:
Cosmetic applications command the widest margin dispersion due to therapeutic claim substantiation requirements and premium positioning in wellness retail channels.
- Culinary:Direct consumption and food preparation across household and commercial kitchens. REACH heavy-metal testing protocols in Europe are filtering uncertified competitors and consolidating shelf space for verified Pakistani-origin suppliers.
- Cosmetic:Bath formulations and topical preparations leveraging magnesium, potassium, and trace mineral content for skin therapy claims. EU-bound shipments now require third-party arsenic and lead certification under tightening REACH thresholds.
- Industrial:Non-food processing applications including water treatment and de-icing where mineral purity specifications are less stringent.
- Nutritional:Supplement and functional food ingredient uses requiring pharmaceutical-grade processing and documentation.
Culinary applications anchor volume throughput; cosmetic applications are climbing the fastest as wellness positioning commands premium pricing.
End User:
Health stores concentrate procurement authority for certified specialty grades, while restaurants drive standardization requirements across supply chains.
- Restaurants:Commercial foodservice operators requiring consistent granulation and documented origin for liability management. California and New York metropolitan clusters lead contracted verified supply adoption.
- Health Stores:Premium natural-product retailers in Germany and Japan prioritizing fair-trade certification and documented labor practices for placement authority.
- Retail:Mass-market grocery and general merchandise channels emphasizing price competitiveness over origin verification.
- Households:Direct consumers purchasing through subscription services and e-commerce platforms, bypassing traditional wholesale markups for certified culinary-grade product.
Restaurants absorb the bulk of food-grade volume; health stores are gaining share fastest as certification-driven preference shifts displace price-based procurement.
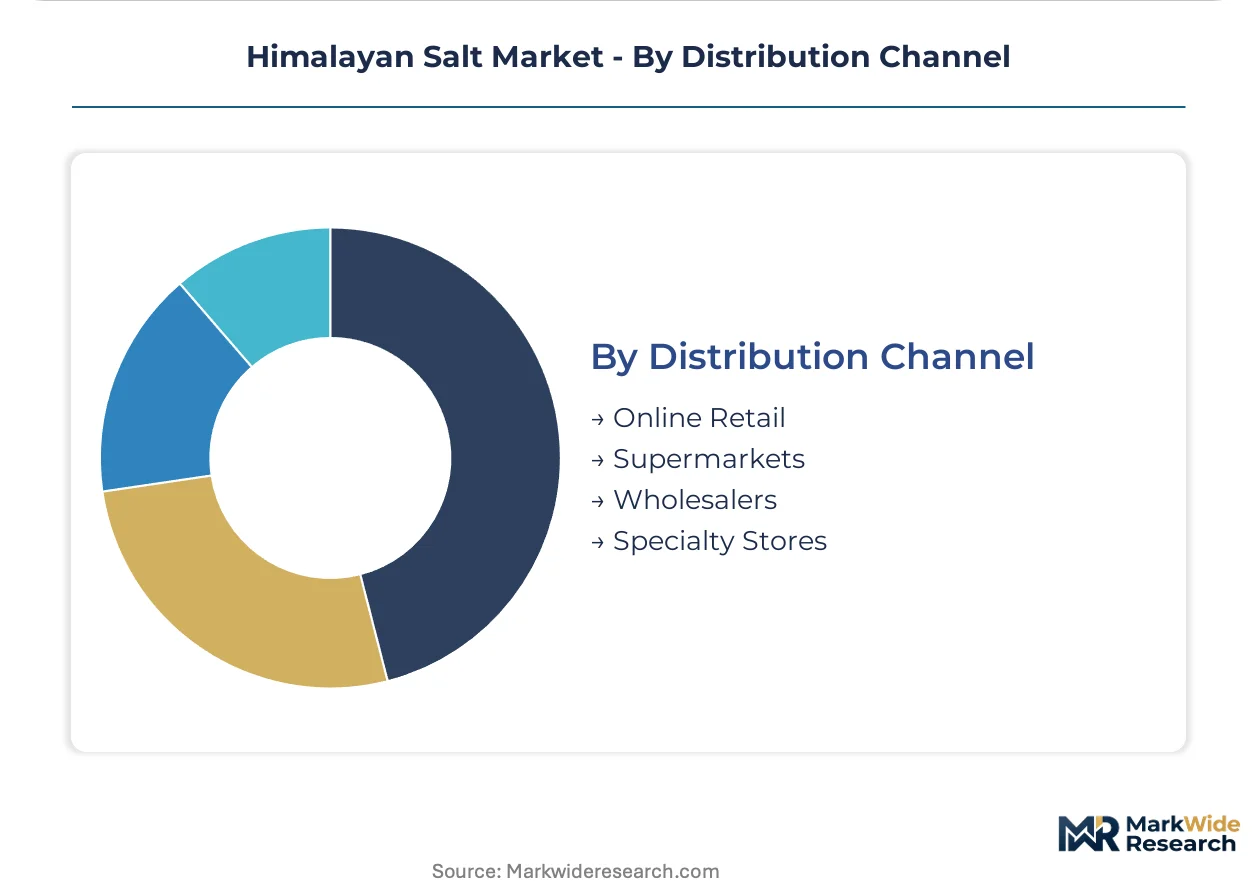
Distribution Channel:
Specialty stores require the deepest working capital commitment due to extended payment terms and inventory holding requirements for slow-turning premium SKUs.
- Specialty Stores:Premium natural-product and wellness retailers with certified product focus and educated consumer base. German and Japanese channels are adopting near-infrared spectroscopy and blockchain dual-verification systems to defend margin positioning against adulteration.
- Online Retail:Direct-to-consumer platforms and subscription box services enabling mine-to-retail operators to bypass wholesale markups and capture consumer data.
- Supermarkets:Mass-market grocery chains with private-label penetration and price-focused procurement, squeezing margins for non-differentiated product.
- Wholesalers:Traditional bulk distributors serving foodservice and industrial accounts with volume-based pricing and limited traceability documentation.
Supermarkets absorb the bulk of volume throughput; online retail is expanding most quickly as subscription models reshape procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Salt Range of Punjab Province anchors authentic Himalayan salt extraction, with downstream demand dispersing across wellness-focused consumer markets in North America, Europe, and Asia-Pacific.
United States
California and New York metropolitan clusters drive contracted verified supply adoption among liability-conscious restaurant groups and meal-kit providers. FDA food-contact substance standards shape import requirements, compressing margins for processors lacking laboratory verification capabilities. Subscription box services in these urban centers bypass traditional wholesale markups for certified culinary-grade product.
Germany
German wellness consumers accelerate bath salt formulations as spa-at-home rituals displace synthetic alternatives. ECHA REACH heavy-metal testing protocols filter uncertified competitors, consolidating shelf space for verified Pakistani-origin suppliers in natural-product retail. Berlin and Munich health stores prioritize fair-trade certification and documented labor practices for placement authority.
Japan
Japanese premium households source Himalayan salt for therapeutic bathing and ambient air quality applications. METI standards for cosmetic-grade imports impose documentation burdens that favor processors with captive laboratory infrastructure. Tokyo and Osaka specialty retailers adopt near-infrared spectroscopy and blockchain dual-verification systems to defend positioning against adulteration.
India
India's FSSAI food-grade labeling requirements tighten traceability standards for imported pink salt, rewarding domestic processors with verification capabilities. Mumbai and Delhi-NCR wellness retail channels expand shelf space for certified varieties targeting upper-middle-class households. BIS quality benchmarks increasingly determine procurement authority in premium natural-product segments.
United Kingdom
UK wellness retailers leverage direct Pakistani sourcing relationships to sustain consistent pink salt grades for foodservice and cosmetic channels. ECHA REACH chemical safety protocols align with post-Brexit retained EU law, maintaining heavy-metal testing requirements. London specialty stores and Manchester distribution hubs concentrate procurement authority for certified specialty grades.
Himalayan Salt Market Competitive Environment
Global majors compete with regional champions across certification infrastructure and mine-to-retail traceability. The vendor base stratifies between industrial-scale distributors, specialty wellness marketers, and vertically integrated Pakistani-origin processors. Three archetypes dominate: laboratory-verified exporters commanding European retail placement, direct-sourcing specialists capturing subscription channel economics, and diversified salt conglomerates leveraging industrial distribution scale for consumer segment expansion. Competitive moves center on compliance infrastructure investment and backward integration into captive Pakistani mining operations.
Among laboratory-verified exporters, Morton Salt, Inc and San Francisco Salt Co exemplify divergent scale positioning within North American channels. The Spice Lab anchors the direct-sourcing specialist archetype, representing mine-to-retail operators with documented Pakistani relationships. Kutch Brine Chem Industries occupies a position among India-based processors navigating FSSAI certification requirements for domestic and export markets.
| Leading Market Players |
|---|
| The Spice Lab |
| Kutch Brine Chem Industries |
| San Francisco Salt Co |
| NutroActive Industries Pvt Ltd |
| Naturo Healthplus |
| Evolution Salt Co |
| Morton Salt, Inc |
| Saltan Ltd |
| Saltworks Technologies Inc |
| Others |
Value Chain & Pricing Dynamics
Manual extraction labor costs in Punjab Province cascade through three distinct pricing tiers as seasonal migration patterns and safety enforcement cycles compress margins at the mine gate before certification premiums accrue downstream.
Pricing Analysis
Certification-bundling separates verified FSSAI and REACH-compliant product from uncertified commodity grades, with laboratory documentation and origin verification commanding substantial premiums in German and Japanese health stores. Three-tier pricing structure across certified premium, documented standard, and unverified economy levels reflects traceability investment recovery timelines. Pricing pressure stems from Dead Sea and Epsom salt competitors matching magnesium-content claims at lower price points. Mass-market retail channels exhibit highest price sensitivity, while specialty wellness retailers absorb certification premiums with limited volume elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Pakistan's Salt Range, where over 90% of authentic Himalayan salt originates from halite deposits formed from ancient evaporated seabeds. Raw material extraction draws from manual mining operations in Punjab Province, with finishing and packaging infrastructure concentrated in Karachi export zones. Tariff exposure and geopolitical logistics disruption constitute the dominant structural risk for downstream processors. Distribution runs through vertically integrated mine-to-retail operators and traditional wholesale importers serving foodservice and specialty retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Authentic Himalayan salt supply remains physically constrained to Pakistan's Salt Range deposits, with laboratory certification capacity acting as the binding bottleneck that sustains pricing premiums for verified exporters.
For Market Incumbents: Deepen captive laboratory infrastructure in Karachi and Lahore processing zones to compress FSSAI and REACH validation timelines from 18 months toward competitive 12-month cycles. Expand backward integration into documented fair-trade mining cooperatives in Punjab Province to defend placement authority against emerging ethical-sourcing specialists. Threat intensity concentrates in mid-scale importers lacking capital for blockchain traceability deployment. For New Entrants and Emerging Players: Subscription box services and direct-to-consumer wellness platforms represent the most penetrable route for certified culinary-grade product, bypassing wholesale markups and capturing consumer data in United States metropolitan clusters. Target California and New York household segments with spa-at-home bath salt formulations leveraging magnesium absorption marketing. Go-to-market execution hinges on near-infrared spectroscopy partnerships for real-time authenticity verification. For Investors and Strategic Acquirers: Accelerated consolidation among Pakistani exporters lacking REACH compliance upgrade capital is the leading indicator that laboratory-verified mid-scale processors will command acquisition premiums. Long-term viability across the analysis window favors operators with dual FSSAI-EU certification capabilities and documented mine-to-retail traceability. Watch for German health store chains adopting blockchain origin-tracking as the inflection signal for certification-driven preference shifts displacing price-based procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Certification Expansion | FSSAI and REACH compliance infrastructure filters uncertified competitors from European and Indian retail channels. |
| Blockchain Traceability Deployment | German and Japanese specialty retailers adopt dual-verification systems to defend margin positioning against adulteration. |
| Fair-Trade Sourcing Documentation | Berlin and Munich health stores prioritize documented labor practices for placement authority in premium natural-product segments. |
| Direct-to-Consumer Channel Buildout | Subscription services in California and New York bypass wholesale markups and capture consumer data for certified culinary-grade product. |
| Bath Salt Formulation Innovation | German wellness consumers accelerate spa-at-home rituals as therapeutic magnesium absorption claims displace synthetic alternatives. |
Study Parameters
Multi-period observation of FSSAI certification timelines, REACH heavy-metal testing protocols, and Pakistani mining safety enforcement cycles anchored the trend analysis, supplemented by interviews with mine operators in Punjab Province, export processors in Karachi, German health store category buyers, Japanese cosmetic-grade importers, and United States meal-kit procurement directors. Secondary validation drew from Pakistan's mining regulator disclosures, ECHA substance restriction updates, FDA food-contact substance guidance, and customs trade flow records. Bottom-up segment sizing and top-down macro constraint triangulation converged on volume and value estimates.
Segment-weighting across product type, application, end user, and distribution channel dimensions calibrated the analytical framework, with granulated salt, bath salt, block salt, and salt lamp categories receiving distinct growth trajectory assumptions. CAGRs were derived from mineral-grade demand elasticity, certification penetration curves, and wellness retail expansion rates across the projection horizon. Industry-specific forecast inputs included seasonal labor migration patterns in Punjab Province and evolving organic certification standards in premium natural-product channels.
The model holds under stable Pakistan-India geopolitical conditions and consistent REACH enforcement intensity; deviation in mining safety regulation stringency or ECHA heavy-metal threshold tightening would shift supply availability and pricing tier boundaries. Forecasts reflect documented assumptions about certification timeline compression and traceability technology adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Egypt Herbs and Spices Market
Spices and Seasonings
Turmeric Market
Spices and Seasonings
Organic Saffron Market
Spices and Seasonings
Boutique Salt Market
Spices and Seasonings
Organic Spices and Herbs Market
Spices and Seasonings
Organic Spice Market
Spices and Seasonings
North America Seasonings Market
Spices and Seasonings
Boswellia Extract Market
Spices and Seasonings
Bolivian Rose Salt Market
Spices and Seasonings
Thyme Extract Market
Spices and Seasonings
Habanero Salt Market
Spices and Seasonings
US Spice and Seasonings Market
Spices and Seasonings
Cardamom Market
Spices and Seasonings
Mint Oils Market
Spices and Seasonings
Savoury Seasoning Market
Spices and Seasonings
Europe Spice and Herb Extracts Market