
 Europe Seasoning and Spices Market | 2026-2036
Europe Seasoning and Spices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Seasoning and Spices Market Foresight
Clean-label extraction technology is fragmenting traditional supply chains for oleoresins and essential oils across European spice processing. McCormick & Company, Inc. leverages its R&D footprint in the Netherlands to develop reduced-sodium seasoning platforms. Kerry Group plc anchors industrial flavor systems for ready-meal manufacturers in Ireland and Britain. Fuchs Gruppe dominates private-label spice blending for German retail discounters.
Seasonings and spices comprise dried botanical materials—whole, ground, or extracted—that deliver flavor, color, aroma, or preservative function to food matrices, typically standardized for volatile oil content, moisture levels below 12%, and microbiological safety thresholds. Blends command the widest margin pools in food processing applications where formulation secrecy creates switching costs. Liquid extracts are displacing ground spices in beverage and sauce manufacturing due to superior solubility and batch consistency. Home cooking channels sustain volume throughput through supermarket and online distribution.
EFSA safety assessments govern maximum residue limits for ethylene oxide and other fumigants in imported spices, forcing suppliers toward steam-treated or irradiated alternatives. REACH registration requirements for solvent-based extraction processes elevate compliance costs for non-EU ingredient sources. ECHA substance evaluations on allergen labeling intensify traceability investments across the value chain. Stakeholders must calibrate sourcing strategies between cost-efficient bulk imports and regulatory-compliant processed ingredients.
Market Dynamics
EU Green Deal sustainability mandates and REACH chemical safety protocols are fragmenting traditional sourcing channels for imported spice raw materials, forcing processors toward steam-treated alternatives and irradiation facilities within European borders.
Growth Catalysts
- Clean-label procurement:Foodservice operators in Germany, France, and Italy are expanding purchases of additive-free spice blends for prepared meal lines, creating premium positioning for compliant suppliers.
- REACH solvent registration:Registration requirements for extraction processes are elevating compliance costs for non-EU sources, advantaging European processors with established ECHA dossiers.
- Mediterranean cuisine standardization:Eastern European processed meat manufacturers are adopting Mediterranean herb formulations, pulling volume through specialized blending facilities.
Market Restraints
- Ethylene oxide residue limits:EFSA maximum residue thresholds for fumigants in imported spices are rejecting substantial bulk shipments from traditional supply origins.
- Extraction solvent volatility:Petrochemical-derived solvents face escalating ECHA substance evaluation costs, compressing margins for oleoresin processors.
- Microbiological safety thresholds:Moisture content below 12% and volatile oil standardization require capital-intensive drying infrastructure that smaller importers cannot access.
Strategic Opportunities
- Eastern European meat processing:Poland and Romania present underpenetrated demand for standardized spice blends in sausage and cured meat production.
- Irradiation infrastructure gaps:Countries lacking commercial irradiation facilities must import pre-treated materials, creating toll-processing opportunities for Dutch and Belgian operators.
- CSRD supply chain disclosure:Corporate Sustainability Reporting Directive mandates are forcing food manufacturers to document spice provenance, rewarding processors with traceable farmgate relationships.
Industry Challenges
- Allergen traceability systems:ECHA substance evaluations on sesame and celery labeling require lot-level tracking from raw material through blended finished goods.
- Volatile oil assay standardization:Gas chromatography capacity constraints at third-party laboratories are extending batch release timelines for essential oil verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Seasoning and Spices Market |
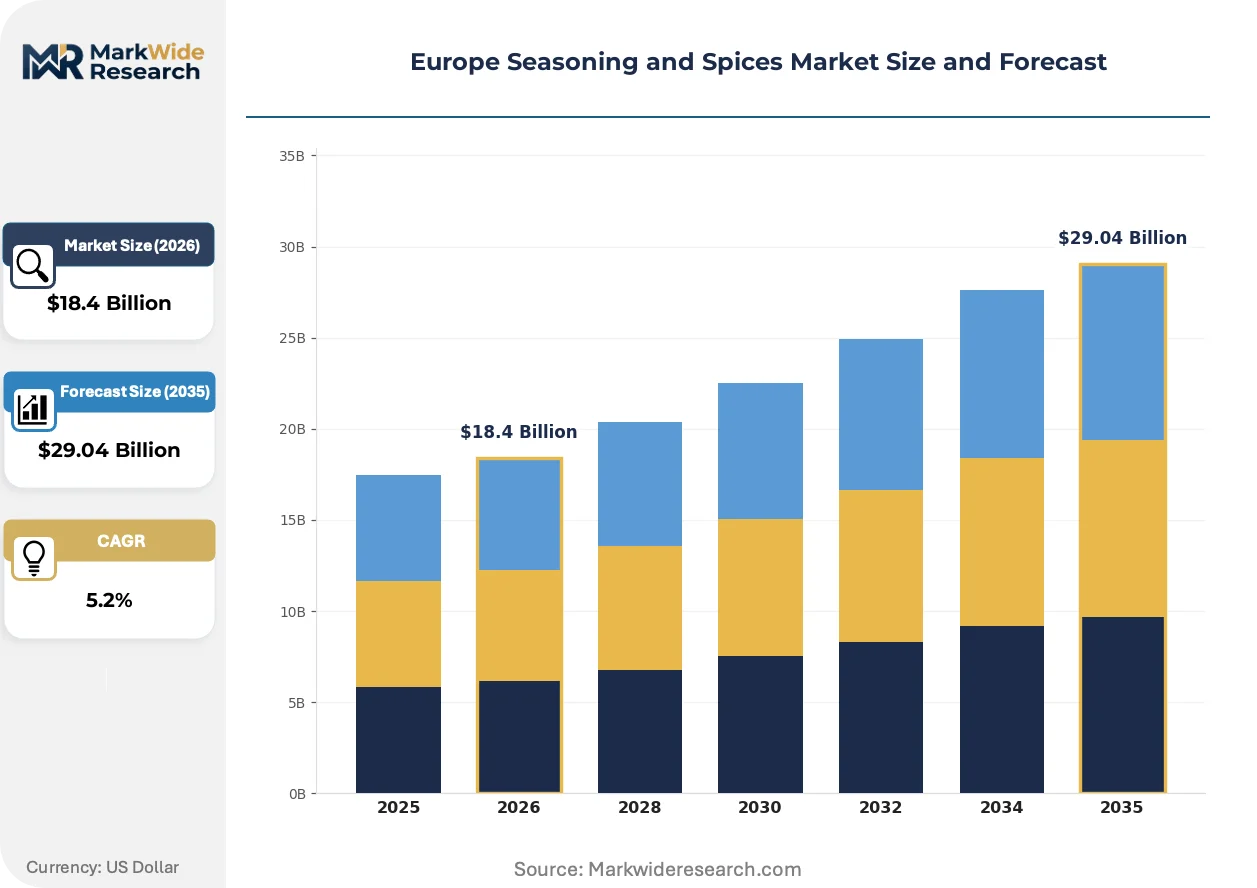
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $29.04 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbs, Seasonings, Blends, Spices Form: Whole, Ground, Liquid, Paste Application: Food Processing, Home Cooking, Foodservice, Snacks Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | McCormick & Company, Inc., Kerry Group plc, Olam International, Döhler GmbH, Associated British Foods plc, Fuchs Gruppe, Euroma B.V., Prymat Group, Nedspice Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Seasoning and Spices Market Shifts & Advancements
Clean-label extraction technology and regulatory disclosure mandates are compressing traditional supply chain tiers, concentrating value capture among processors with in-house analytical capabilities and documented sustainability credentials.
Supercritical CO2 extraction systems are migrating from beverage flavor applications into spice oleoresin production. Ready-meal manufacturers in Ireland and Britain are specifying these extracts for batch consistency. The technology is migrating from premium positioning toward mid-tier sauce and soup applications, eroding price premiums for conventional solvent extraction.
REACH registration requirements for solvent-based processes are elevating compliance costs for imported raw materials. Non-EU suppliers without ECHA dossiers face market exclusion. Food processors in Germany and the Netherlands are responding by qualifying European extraction facilities with existing substance registrations.
Home cooking channels are sustaining volume throughput through supermarket and online distribution. Traditional wholesale spice merchants are losing share to direct-processor relationships and private-label retail contracts. This pattern is most visible in German discount retail, where Fuchs Gruppe and similar blenders supply standardized formulations under retailer brands.
Europe Seasoning and Spices Market Segmentation
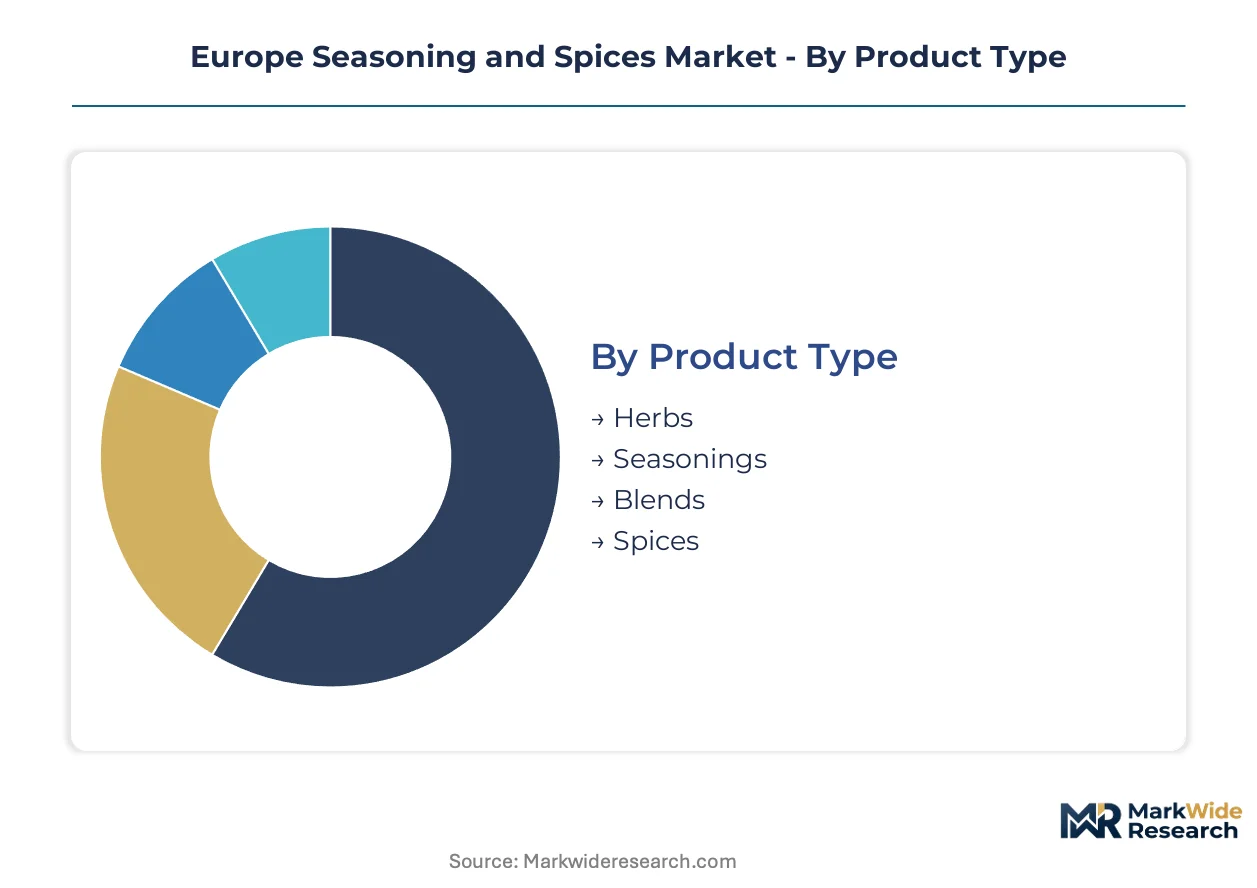
Segmentation in the Europe seasoning and spices market reveals how regulatory pressure and end-use requirements fragment procurement strategies. Food manufacturers prioritize standardized volatile oil content and microbiological safety thresholds, while retail channels drive differentiation through format convenience and clean-label positioning.
Product Type:
After-sales service intensity varies sharply across product categories, with extraction-based segments requiring technical support for assay standardization and regulatory documentation that whole-spice suppliers rarely provide.
- Blends:Proprietary formulations combining multiple spices and herbs with standardized flavor profiles and moisture content below 12%. German and French foodservice operators are expanding procurement of additive-free blends for prepared meal lines as clean-label mandates intensify. Blends command the widest margin pools where formulation secrecy creates switching costs for food processors.
- Spices:Dried botanical materials delivering pungency, color, or preservative function, typically evaluated for volatile oil content and ethylene oxide residue compliance. EFSA maximum residue limits are rejecting substantial bulk shipments from traditional supply origins, forcing importers toward steam-treated alternatives.
- Herbs:Aromatic leaf materials standardized for essential oil composition and microbiological thresholds.
- Seasonings:Salt-based matrices incorporating flavoring agents for industrial food processing applications.
Blends hold the largest share; momentum sits with spice segments qualifying for irradiation treatment to meet EFSA safety thresholds.
Form:
Cost tier differentiation separates capital-intensive extraction infrastructure from commodity grinding operations, with mid-tier processors struggling to bridge the compliance gap.
- Liquid:Solvent or supercritical CO2 extracts delivering superior solubility and batch consistency for beverage and sauce manufacturing. Ready-meal manufacturers in Ireland and Britain are specifying these extracts as REACH registration requirements elevate compliance costs for imported raw materials.
- Ground:Milled particles with standardized particle size distribution for uniform dispersion in food matrices. Eastern European processed meat manufacturers in Poland and Romania are adopting Mediterranean herb formulations, pulling volume through specialized grinding and blending facilities.
- Whole:Intact botanical materials requiring downstream processing by food manufacturers or foodservice operators.
- Paste:Wet-ground preparations with preservative systems for industrial sauce and marinade applications.
Ground form dominates volume throughput; liquid extracts are climbing the fastest as supercritical CO2 technology migrates from premium positioning toward mid-tier applications.
Application:
Customer type fragmentation concentrates procurement power among industrial food processors with dedicated quality assurance teams, while home cooking channels sustain volume through fragmented retail distribution.
- Food Processing:Industrial-scale ingredient procurement for ready-meals, sauces, and processed meats requiring documented traceability and allergen controls. Kerry Group plc anchors flavor systems for manufacturers in Ireland and Britain, leveraging established ECHA dossiers for solvent-based extraction processes.
- Foodservice:Bulk supply to restaurants, catering operations, and institutional kitchens with specification flexibility. German, French, and Italian operators are expanding purchases of clean-label spice blends as EU Green Deal sustainability mandates reshape sourcing requirements.
- Home Cooking:Retail-packaged products distributed through supermarkets and online channels.
- Snacks:Seasoning coatings for savory snack applications with flavor intensity and adhesion requirements.
Food processing commands the largest revenue pool; foodservice is gaining share fastest as clean-label procurement expands across Mediterranean cuisine applications.
Distribution Channel:
Supply concentration in Dutch and Belgian irradiation infrastructure creates geographic dependency for pre-treated materials, disadvantaging distributors without toll-processing relationships.
- Supermarkets:Mass-market retail dominating home cooking volume through private-label contracts. Fuchs Gruppe supplies standardized formulations under German discount retailer brands, consolidating procurement relationships that bypass traditional wholesale merchants.
- Wholesale:Bulk supply to food manufacturers and foodservice operators with specification negotiation and technical service support. Countries lacking commercial irradiation facilities must import pre-treated materials, creating toll-processing opportunities for Dutch and Belgian operators.
- Online:Direct-to-consumer and B2B platforms with expanded assortment and traceability documentation.
- Specialty Stores:Premium and ethnic-focused retail with curated provenance and origin storytelling.
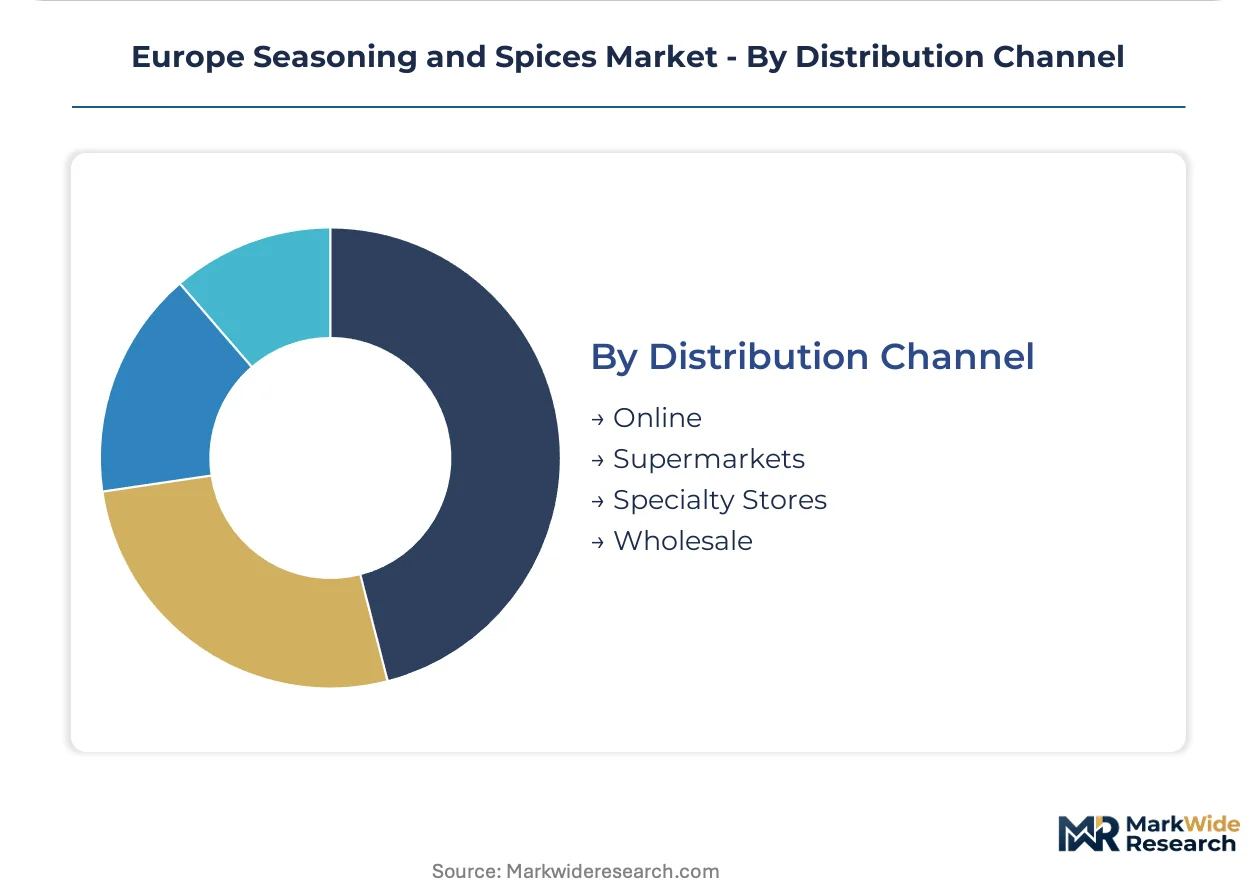
Supermarkets hold the largest share; online channels show steepest expansion trajectory as CSRD supply chain disclosure mandates reward processors with documented farmgate relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian spice exports flow predominantly into Dutch and Belgian processing hubs, where irradiation infrastructure transforms raw botanicals into EFSA-compliant ingredients for onward distribution across the continent.
Germany
Discount retail chains drive procurement volume for private-label spice blends. REACH registration requirements for solvent-based extraction processes elevate compliance costs for non-EU sources, advantaging domestic processors. Fuchs Gruppe anchors industrial blending operations in Lower Saxony, supplying standardized formulations that bypass traditional wholesale channels.
Netherlands
Rotterdam and Amsterdam harbor zones concentrate import processing for steam-treated and irradiated spices. McCormick & Company leverages its R&D footprint near Utrecht to develop reduced-sodium seasoning platforms for foodservice clients. The country's commercial irradiation infrastructure creates toll-processing opportunities for materials rejected at other EU entry points.
France
Mediterranean cuisine applications pull demand for herb formulations through specialized blending facilities near Lyon and Marseille. ANSM allergen labeling protocols intensify traceability investments across the value chain. Foodservice operators in Paris and Lyon are expanding purchases of clean-label spice blends as EU Green Deal mandates reshape sourcing requirements.
Italy
Prepared meal manufacturers in Lombardy and Emilia-Romagna standardize procurement around volatile oil content specifications. EFSA maximum residue limits for ethylene oxide are rejecting substantial bulk shipments from traditional supply origins. Processing clusters near Milan are qualifying European extraction facilities with established ECHA dossiers.
Poland
Processed meat manufacturers in Warsaw and Krakow present underpenetrated demand for standardized spice blends in sausage production. CSRD supply chain disclosure mandates force food manufacturers to document spice provenance. The country's lack of commercial irradiation facilities necessitates import of pre-treated materials from Dutch processors.
Europe Seasoning and Spices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. The vendor base separates into retail-private-label suppliers, industrial flavor-system providers, and commodity trading houses. Three archetypes dominate: integrated processors with in-house extraction capabilities, toll-processing operators leveraging regulatory infrastructure, and blenders serving discount retail channels. Competitive moves concentrate on backward integration into sourcing relationships and qualification of alternative treatment technologies.
Among US-based multinationals, McCormick & Company, Inc. and Kerry Group plc occupy positions representing divergent strategic vectors—one anchored in consumer-branded retail presence, the other in industrial flavor-system supply. Fuchs Gruppe exemplifies the private-label archetype dominating German discount retail consolidation. These three entities represent the structural tension between brand equity, industrial scale, and retail channel control that defines competitive positioning.
| Leading Market Players |
|---|
| McCormick & Company, Inc. |
| Kerry Group plc |
| Olam International |
| Döhler GmbH |
| Associated British Foods plc |
| Fuchs Gruppe |
| Euroma B.V. |
| Prymat Group |
| Nedspice Group |
| Others |
Supply & Pricing Matrix
Rotterdam harbor zones anchor European spice import processing, where irradiation and steam-treatment capacity constraints translate directly into toll-processing premiums for EFSA-compliant materials. Dutch and Belgian operators capture margin from food manufacturers facing rejected shipments at alternative entry points.
Pricing Analysis
Supercritical CO2 extraction technology commands premium positioning against conventional solvent-based processes, while commodity grinding operations compete on volume scale. Three-tier pricing structure across premium extracts, standard oleoresins, and economy ground spices reflects compliance burden differentiation. Cost compression in solvent-extracted tiers intensifies as REACH registration requirements elevate European processor advantages. Private-label retail channels exhibit highest price sensitivity; industrial food processors prioritize batch consistency over unit cost.
Supply Chain Analysis
REACH chemical safety protocols and EU Green Deal sustainability mandates restrict raw material flows from non-EU sources lacking ECHA dossiers. Supply concentrates in India, Vietnam, and Indonesia for raw botanicals, with Dutch and Belgian hubs handling transformation into compliant ingredients. The chain draws from petrochemical-derived solvents, steam-treatment infrastructure, and irradiation facilities. Single-source vulnerability concentrates in Rotterdam-Amsterdam processing clusters. Distribution runs through direct-processor relationships and private-label retail contracts that displace traditional wholesale merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label extraction technology and CSRD supply chain disclosure mandates are disrupting procurement patterns, creating asymmetric advantage for processors with documented sustainability credentials and in-house analytical capabilities.
For Market Incumbents: Insulate market position by deepening backward integration into traceable farmgate sourcing relationships across Mediterranean herb origins. Expand captive irradiation capacity in Dutch and Belgian hubs to capture toll-processing revenue from importers lacking treatment infrastructure. EFSA ethylene oxide enforcement and REACH solvent registration costs threaten non-compliant suppliers. For New Entrants and Emerging Players: Mid-tier sauce and soup manufacturers in Eastern Europe represent the most penetrable entry point for supercritical CO2 extracts migrating from premium positioning. Polish and Romanian processed meat facilities lack standardized spice blend suppliers with ECHA-compliant extraction capabilities. Lead with technical service support for volatile oil assay standardization and regulatory documentation. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because compliance infrastructure creates durable moats against commodity traders lacking ECHA dossiers and irradiation access. Target processors with established European extraction facilities and documented farmgate traceability systems. Watch for CSRD disclosure mandate acceleration as inflection signal for traceability-premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sourcing | Captures margin from Indian and Vietnamese farmgate relationships while satisfying CSRD provenance requirements. |
| Irradiation Infrastructure Expansion | Dutch and Belgian operators toll-process materials rejected at ports lacking commercial treatment capacity. |
| Supercritical CO2 Technology Migration | Mid-tier sauce manufacturers in Ireland and Britain specify these extracts for superior batch consistency. |
| Clean-Label Blend Formulation | German discount retailers source additive-free private-label platforms from Fuchs Gruppe and similar processors. |
| ECHA Dossier Qualification | European extraction facilities with REACH registrations exclude non-EU competitors from industrial supply contracts. |
Research Methodology
A spread of perspectives from procurement directors at ready-meal manufacturers, quality assurance leads at spice processors, regulatory affairs specialists at extraction facilities, and category buyers at German discount retailers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through EFSA safety assessments, ECHA substance registrations, EU Green Deal policy documents, and customs trade data. Bottom-up volume modeling triangulated against top-down market sizing across product type, form, application, and distribution channel dimensions.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation by product type, form, application, and distribution channel. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points including REACH enforcement acceleration and CSRD disclosure phase-ins. Industry-specific inputs incorporated volatile oil standardization requirements, ethylene oxide residue limit compliance rates, and irradiation infrastructure capacity utilization.
Practitioners should monitor EFSA enforcement intensity, REACH registration cost escalation, and CSRD disclosure timeline acceleration for early signals of forecast deviation. Material shifts in regulatory enforcement patterns or alternative treatment technology cost curves would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Achiote Powder Market
Spices and Seasonings
Myrrh Gum Market
Spices and Seasonings
Himalayan Salt Market
Spices and Seasonings
Bolivian Rose Salt Market
Spices and Seasonings
Spice Oils and Oleoresins Market
Spices and Seasonings
Cardamom Oil Market
Spices and Seasonings
All-Purpose Seasoning Market
Spices and Seasonings
Hot Pot Seasoning Market
Spices and Seasonings
Plastic Spice Jars Market
Spices and Seasonings
Global Spices and Stimulants Market
Spices and Seasonings
Herbs and Spices Market
Spices and Seasonings
Habanero Salt Market
Spices and Seasonings
Ginger Market
Spices and Seasonings
US Gourmet Salt Market
Spices and Seasonings
Africa Seasoning and Spices Market
Spices and Seasonings
Garlic Oleoresin Market